
 Electric and Hybrid Vehicles Driveline Market | 2026-2036
Electric and Hybrid Vehicles Driveline Market Size, Share, and Industry Trends Forecast 2026-2036
Electric and Hybrid Vehicles Driveline Market Analysis
Project finance tied to battery supply chain offtake agreements is fragmenting capital requirements for driveline manufacturing scale-up. Robert Bosch GmbH leverages its integrated power electronics and motor manufacturing footprint to sustain cost competitiveness across European OEM programs. GKN Automotive anchors its position through dedicated eDrive systems engineering for premium passenger car architectures. BorgWarner Inc competes by extending its transmission expertise into integrated electric axle modules for North American truck platforms.
An electric and hybrid vehicles driveline comprises the integrated mechanical and electrical subsystems that transmit torque from electric motors, combustion engines, or combined power sources to vehicle wheels, typically operating at voltages between 400V and 800V with multi-speed or single-speed reduction gearboxes. Its primary purpose is to optimize energy conversion efficiency, recuperate braking energy, and manage torque vectoring across diverse driving cycles. Battery Electric Vehicle drivelines command the dominant share of current component value as OEMs eliminate mechanical complexity in favor of direct-drive and coaxial motor-gearbox units. Plug-in Hybrid Electric Vehicle architectures retain transmission complexity and represent concentrated margin pools for suppliers mastering clutch-integrated e-motor packaging. Regenerative Braking System technology differentiation separates premium tier suppliers from commodity motor providers in commercial vehicle applications.
The EPA tailpipe emission standards and NHTSA fuel economy regulations in the United States mandate fleet-average CO2 reductions that force OEMs toward electrified driveline sourcing. EMA and EU Green Deal carbon border adjustments shape component qualification requirements for European market access, while China's MIIT enforces GB standards for electric powertrain efficiency and safety testing. Stakeholders must monitor how divergent regional certification timelines for solid-state battery integration reshape driveline thermal management and voltage architecture roadmaps.
Market Dynamics
Powertrain electrification mandates from China's MIIT and the EU Green Deal are compressing supplier qualification timelines while fragmenting capital deployment across battery supply chain offtake structures.
Growth Catalysts
- Fleet electrification mandates:Logistics operators in Germany and the United States are scaling electrified driveline procurement under tightening CO2 fleet standards. Urban transit networks accelerate deployment of integrated electric axle modules for medium-duty commercial vehicles.
- GB standards enforcement:China's MIIT powertrain efficiency testing protocols are forcing domestic OEMs to source higher-voltage driveline architectures. Local manufacturing capacity expansion for 800V systems concentrates in Jiangsu and Guangdong provinces.
- Charging infrastructure buildout:Public fast-charging station deployment across Norway, the Netherlands, and California reduces range anxiety for battery electric vehicle adopters. Direct-drive motor-gearbox unit demand strengthens in markets with dense DC fast-charging corridors.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium processing capacity concentrates in China's Inner Mongolia and Jiangxi provinces. Western driveline manufacturers face input cost volatility and geopolitical offtake risk for permanent magnet motors.
- Copper winding cost exposure:Electric motor stator production depends on LME copper price fluctuations. Suppliers without long-term cathode supply contracts absorb margin compression during commodity spikes.
- Legacy transmission asset stranding:Plug-in hybrid architectures retain multi-speed gearbox complexity that delays full electrification. European suppliers with sunk investment in precision gear manufacturing face demand bifurcation.
Strategic Opportunities
- Commercial vehicle electrification white space:Heavy-duty truck driveline penetration remains below passenger car levels in the United States. Integrated electric axle modules for Class 8 trucks represent uncaptured margin pools.
- Solid-state battery convergence:Next-generation cell chemistry eliminates thermal runaway risks and enables simplified driveline cooling architectures. Suppliers mastering 800V silicon carbide power electronics position for platform standardization.
- EU Green Deal carbon border adjustments:EMA component qualification requirements for European market access favor suppliers with verified low-carbon manufacturing. Battery supply chain traceability certification becomes a competitive differentiator.
Industry Challenges
- Power electronics talent scarcity:Silicon carbide inverter design and thermal management engineering expertise concentrates in automotive Tier 1 suppliers and semiconductor firms. OEMs face recruitment competition for embedded software engineers with motor control algorithm experience.
- Multi-voltage platform certification:Simultaneous 400V and 800V architecture validation stretches engineering resources. Suppliers must maintain parallel testing protocols while awaiting solid-state battery integration timelines.
- Legacy supplier integration friction:Traditional transmission manufacturers lack electric motor winding and power electronics assembly capabilities. Joint venture structures with battery cell producers create governance complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric and Hybrid Vehicles Driveline Market |
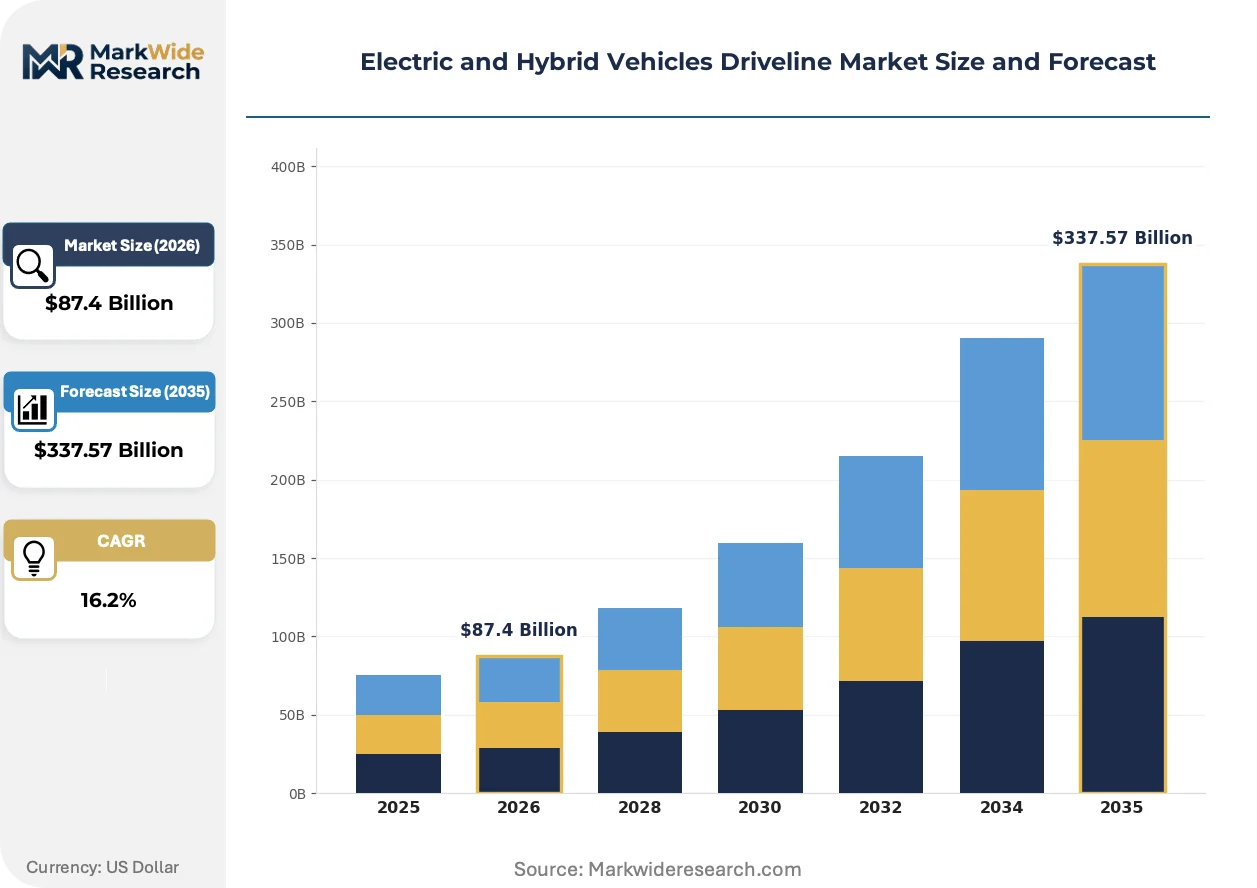
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $337.57 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Electric Vehicle, Plug-in Hybrid Electric Vehicle, Fuel Cell Electric Vehicle, Mild Hybrid Electric Vehicle Technology: Electric Motor, Internal Combustion Engine, Regenerative Braking System, Transmission End User: OEMs, Fleet Operators, Dealerships, Aftermarket Providers Application: Passenger Cars, Commercial Vehicles, Two-Wheelers, Three-Wheelers |
| Companies Covered | Robert Bosch GmbH, GKN Automotive, Schaeffler AG, BorgWarner Inc, ZF Friedrichshafen AG, Continental AG, Denso Corporation, Magna International Inc, Hitachi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric and Hybrid Vehicles Driveline Market Emerging Trajectories
Silicon carbide power semiconductors and coaxial motor-gearbox architectures are compressing driveline package sizes while elevating thermal management requirements across passenger and commercial vehicle platforms.
Silicon carbide MOSFETs replace silicon IGBTs in 800V inverter designs, cutting switching losses by half and enabling higher power density. European premium OEMs are adopting these devices for performance electric vehicles with sustained high-speed capability. The technology is hybridizing cost structures as suppliers balance SiC wafer premiums against copper and cooling system savings.
The EU Green Deal's tightening CO2 fleet standards force powertrain electrification roadmaps that eliminate internal combustion engine variants by 2035. OEMs are consolidating supplier bases to reduce qualification overhead for integrated driveline modules. North American truck manufacturers face compressed development cycles to meet EPA tailpipe standards while maintaining towing capacity ratings.
Fleet operators now specify total cost of ownership contracts that bundle driveline hardware with predictive maintenance software and energy management services. Traditional component sales models face displacement by performance-guaranteed service agreements. German logistics providers lead this transition, demanding brake energy recuperation guarantees and uptime commitments from electric axle suppliers.
Electric and Hybrid Vehicles Driveline Market Segmentation
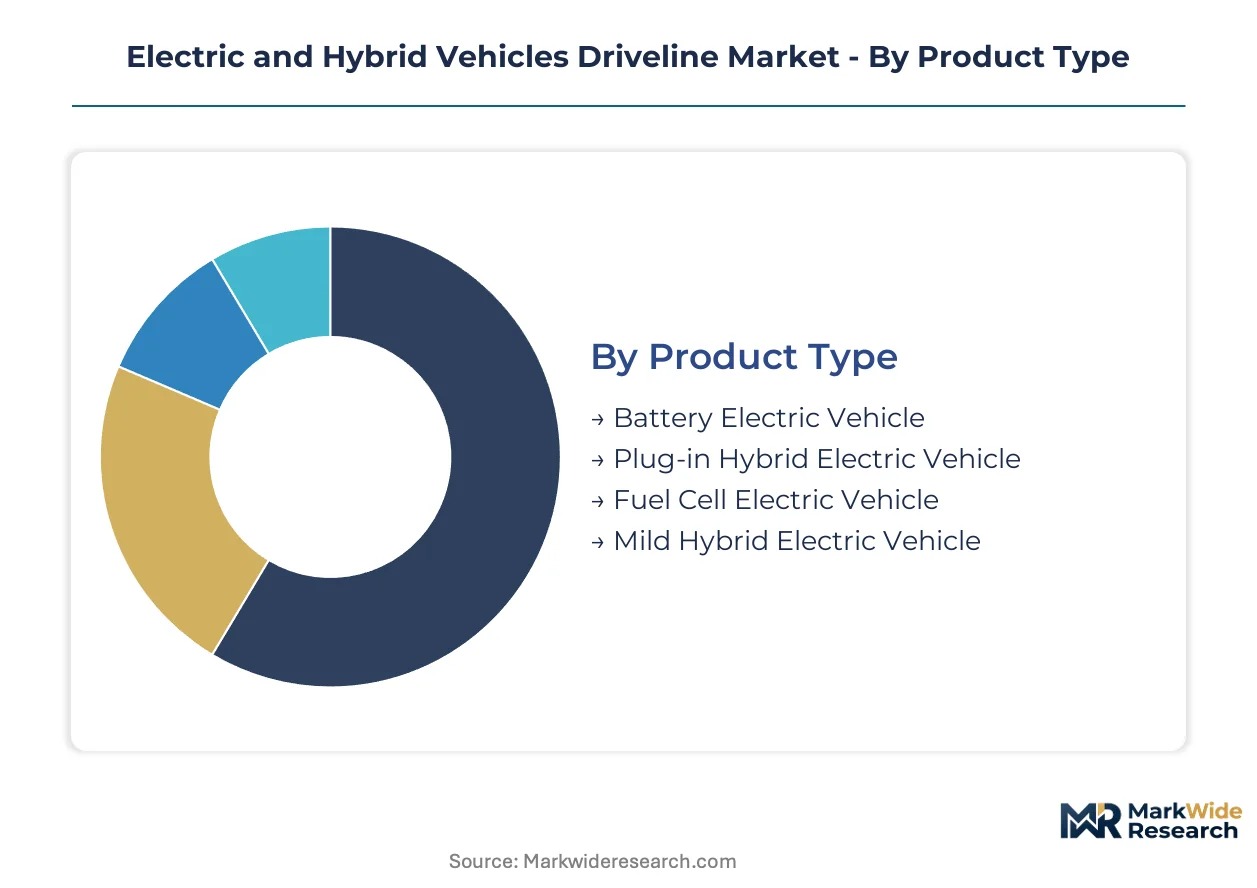
Driveline procurement patterns diverge sharply across electrification intensity, with battery electric architectures commanding premium engineering resources while hybrid systems retain transitional complexity. Fleet operators and OEMs source distinct performance specifications, forcing suppliers to maintain parallel qualification tracks across voltage classes and duty cycles.
Product Type:
Cost tier stratification separates full electrification platforms from transitional hybrid architectures, with capital deployment intensity scaling directly with battery integration depth.
- Battery Electric Vehicle:Direct-drive and coaxial motor-gearbox units eliminate mechanical transmission complexity entirely. Demand concentrates in China, Germany, and California where charging infrastructure density and local manufacturing capacity for 800V systems have achieved scale. Chinese OEMs source these architectures aggressively under MIIT dual carbon enforcement timelines.
- Plug-in Hybrid Electric Vehicle:Clutch-integrated e-motor packaging retains multi-speed transmission hardware alongside electric powertrains. European premium passenger programs represent concentrated margin pools as suppliers master torque-fill algorithms and thermal management for blended operation modes under EU Green Deal fleet standards.
- Fuel Cell Electric Vehicle:Hydrogen fuel cell stacks paired with buffer batteries and electric traction motors serve heavy-duty commercial corridors in South Korea and Japan.
- Mild Hybrid Electric Vehicle:Belt-integrated starter-generator systems provide limited torque assist without plug-in capability, dominating cost-sensitive entry segments.
Battery Electric Vehicle commands the established base. The steepest expansion runs through Plug-in Hybrid Electric Vehicle as European OEMs bridge compliance gaps.
Technology:
Application-specific performance requirements dictate technology selection, with thermal management and energy recuperation capabilities separating premium tier suppliers from commodity providers.
- Electric Motor:Permanent magnet synchronous and induction motor designs operate at 400V to 800V with power densities exceeding 4 kW/kg. Demand clusters in Jiangsu province manufacturing corridors and Bavarian automotive clusters where silicon carbide inverter integration enables sustained high-speed operation.
- Regenerative Braking System:Brake-by-wire architectures with torque blending algorithms maximize energy recuperation across diverse driving cycles. German logistics fleets now specify guaranteed brake energy recovery rates in procurement contracts, elevating this technology to competitive differentiator status for commercial vehicle suppliers.
- Internal Combustion Engine:Downsized turbocharged engines serve range-extender functions in plug-in hybrid architectures.
- Transmission:Multi-speed reduction gearboxes persist in hybrid applications where mechanical torque multiplication complements electric motor characteristics.
Electric Motor anchors current component value. Regenerative Braking System is climbing the fastest as fleet operators mandate performance-guaranteed energy recovery.
End User:
Customer type determines contract structure, with volume procurement shifting from component sales toward total cost of ownership agreements bundled with predictive maintenance.
- OEMs:Integrated driveline module sourcing with platform-standardization requirements and multi-year qualification timelines. German and US passenger car manufacturers consolidate supplier bases to reduce validation overhead for 800V architectures.
- Fleet Operators:Logistics providers in Germany and California specify uptime commitments and energy management services alongside hardware procurement. Direct-drive electric axle demand strengthens as operators electrify medium-duty urban delivery routes under tightening municipal emissions zones.
- Dealerships:Limited aftermarket conversion and retrofit programming for existing vehicle populations.
- Aftermarket Providers:Replacement motor and inverter servicing for out-of-warranty electric vehicle populations.
OEMs retain the dominant procurement volume. Fleet Operators are expanding most quickly as total cost of ownership contracting displaces traditional component sales.
Application:
Volume scale and duty cycle severity create divergent engineering priorities across passenger convenience and commercial durability requirements.
- Passenger Cars:Coaxial motor-gearbox units prioritize packaging density and NVH performance for premium European and Chinese electric vehicle platforms. Single-speed reduction architectures dominate as sustained high-speed capability requirements favor silicon carbide power electronics over mechanical complexity.
- Commercial Vehicles:Integrated electric axle modules for Class 4-8 trucks demand reinforced housings and thermal management for gradeability and towing capacity. North American truck manufacturers face compressed EPA tailpipe compliance timelines while maintaining payload ratings, creating white space for suppliers mastering heavy-duty torque vectoring.
- Two-Wheelers:Hub motor and mid-drive configurations serve urban mobility markets in India and Southeast Asia.
- Three-Wheelers:Low-speed electric drivelines dominate last-mile delivery and passenger transport in dense South Asian urban corridors.
Passenger Cars represent the established revenue base. Commercial Vehicles show the steepest expansion trajectory as electrification penetrates heavy-duty segments previously resistant to battery integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT dual carbon enforcement in China and EU Green Deal fleet standards are compressing supplier timelines while fragmenting capital deployment across battery supply chain structures.
China
Domestic OEMs source 800V driveline architectures aggressively under GB standards enforcement. MIIT powertrain efficiency testing protocols concentrate manufacturing capacity expansion in Jiangsu and Guangdong provinces where local suppliers achieve scale for silicon carbide inverter integration.
Germany
Premium passenger programs drive clutch-integrated e-motor packaging demand under tightening EU CO2 fleet standards. EMA component qualification requirements favor suppliers with verified low-carbon manufacturing in Bavarian automotive clusters where precision gear expertise meets electric motor winding capabilities.
United States
EPA tailpipe standards and NHTSA fuel economy regulations force OEMs toward electrified driveline sourcing for Class 4-8 trucks. California fleet operators specify uptime commitments and energy management services alongside hardware procurement for medium-duty urban delivery electrification.
South Korea
Hydrogen fuel cell stacks paired with buffer batteries serve heavy-duty commercial corridors under METI-influenced technology roadmaps. Busan-Ulsan manufacturing belts concentrate integrated electric axle production for export-oriented commercial vehicle platforms.
Japan
Automotive Tier 1 suppliers anchor silicon carbide inverter design expertise under JIS standards harmonization. Kanto region engineering centers face recruitment competition for embedded software engineers with motor control algorithm experience across 400V and 800V architectures.
Electric and Hybrid Vehicles Driveline Market Vendor Landscape
On the supply side, the industry is consolidating around integrated power electronics and motor manufacturing capabilities. Tier 1 automotive suppliers with transmission heritage compete against dedicated eDrive specialists for platform-standardization contracts. Three archetypes dominate: diversified industrial conglomerates with powertrain heritage, pure-play electric driveline engineering firms, and semiconductor-forward technology integrators. Strategic moves concentrate on joint venture structures with battery cell producers and backward integration into rare earth magnet supply chains.
Within the diversified industrial tier, Robert Bosch GmbH and ZF Friedrichshafen AG occupy positions exemplifying integrated power electronics manufacturing footprints. GKN Automotive represents the dedicated eDrive specialist archetype through its systems engineering focus. BorgWarner Inc anchors the transmission heritage vector extending expertise into electric axle modules. These three names illustrate how competitive positioning fragments across manufacturing scale, engineering specialization, and legacy powertrain integration capabilities.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| GKN Automotive |
| Schaeffler AG |
| BorgWarner Inc |
| ZF Friedrichshafen AG |
| Continental AG |
| Denso Corporation |
| Magna International Inc |
| Hitachi |
| Others |
Supply Flow & Price Mechanics
Jiangsu province's silicon carbide inverter manufacturing clusters concentrate 800V driveline component capacity, translating upstream scarcity into pricing power for qualified suppliers serving European and North American OEM programs. GB standards enforcement by China's MIIT accelerates local procurement premiums while rare earth magnet supply concentration in Inner Mongolia injects volatility into permanent magnet motor cost structures.
Pricing Analysis
Certification level (CE marking under EU Green Deal carbon border adjustments) creates the primary spread between premium and commodity tiers. Three-tier pricing structure across premium, standard, and economy levels reflects GB standards compliance depth and silicon carbide versus silicon IGBT inverter architectures. Cost compression in standard-tier electric motor stators is intensifying because LME copper price volatility squeezes suppliers without long-term cathode contracts. Fleet operators exhibit the lowest price sensitivity due to total cost of ownership contracting, while aftermarket providers face margin pressure from warranty-captive service networks.
Supply Chain Analysis
Export-control restrictions on silicon carbide wafer fabrication equipment limit capacity expansion outside established manufacturing corridors. Component supply concentrates in China, Germany, and Japan where precision gear expertise intersects with power electronics assembly. Rare earth magnet processing draws from Inner Mongolia and Jiangxi provinces, while copper winding supply rests on Chilean and Peruvian mining output. Single-source vulnerability in neodymium processing creates structural risk. Distribution runs through Tier 1 supplier integration with OEM platform engineering teams rather than merchant spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric and hybrid vehicles driveline demand is recovering from cyclical lows as fleet electrification mandates compress replacement cycles and force accelerated procurement timelines. EPA tailpipe standards and EU CO2 fleet standards under the EU Green Deal constitute the primary cyclical driver resetting OEM sourcing volumes.
For Market Incumbents: Harden qualification timelines for 800V architectures to defend against semiconductor-forward technology integrators capturing platform-standardization contracts. Deepen backward integration into rare earth magnet supply chains to offset Inner Mongolia processing concentration. Prioritize silicon carbide inverter thermal management R&D to maintain differentiation as commodity motor providers close performance gaps. For New Entrants and Emerging Players: Class 8 heavy-duty truck electrification in the United States represents the most penetrable white space, with integrated electric axle modules for North American platforms commanding premium engineering margins. Target commercial vehicle fleet operators with performance-guaranteed service agreements bundling predictive maintenance software. Pursue joint venture structures with battery cell producers to secure qualification pathways for OEM platform integration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors dedicated eDrive specialists with systems engineering capabilities over diversified industrial conglomerates with legacy transmission heritage. Long-term viability hinges on mastering 800V silicon carbide power electronics and solid-state battery thermal management convergence. Acquisition target archetype: Tier 1 suppliers with verified low-carbon manufacturing under EMA component qualification requirements. The signal to monitor is solid-state battery integration timelines reshaping driveline cooling architecture roadmaps.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures cell offtake for 800V driveline platform standardization under MIIT dual carbon timelines. |
| Silicon Carbide Power Electronics Investment | Enables higher power density inverters for sustained high-speed European premium passenger programs. |
| Geographic Manufacturing Footprint | Establishes Jiangsu and Guangdong capacity to serve Chinese OEM GB standards compliance requirements. |
| Charging Infrastructure Partnership | Reduces range anxiety for battery electric vehicle adopters in California and German logistics corridors. |
| Platform Standardization | Consolidates supplier bases to reduce validation overhead for 800V architectures under EPA tailpipe mandates. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with Tier 1 supplier procurement managers, OEM platform engineers, fleet operator logistics directors, and aftermarket service heads. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings from automotive suppliers, and EPA tailpipe standard regulatory filings. Bottom-up segment sizing triangulated against top-down market envelope checks to ensure consistency across the analysis window.
Calibration against historical production volumes and announced OEM platform launches anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include propulsion architecture, vehicle class, content per vehicle, and regional production cluster. CAGRs were derived from slope analysis of technology adoption curves and regulatory compliance deadline clustering. Forecast inputs incorporated silicon carbide inverter penetration rates and solid-state battery integration timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by semiconductor-forward technology integrators or battery cell producers would shift outcomes beyond modeled ranges. Material shifts in rare earth magnet export restrictions or solid-state battery commercialization timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Global Hybrid Vehicle Transmission Market
Hybrid Vehicles
North America Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hybrid Electric Self-Driving Car Market
Hybrid Vehicles
High-Voltage Hybrid Vehicle Market
Hybrid Vehicles
Germany Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Mild Hybrid Vehicles Market
Hybrid Vehicles
India Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Electric Vehicle Market
Hybrid Vehicles
Hybrid Train Market
Hybrid Vehicles
United Arab Emirates Hybrid and Electric Vehicles Market
Hybrid Vehicles
Smart Hybrid Vehicle Market
Hybrid Vehicles
Asia-Pacific Mild-Hybrid Vehicles Market
Hybrid Vehicles
North America Micro Hybrid Vehicles Market
Hybrid Vehicles
Hypercar Market
Hybrid Vehicles
Global Hybrid-Electric Vehicle Insulation Market
Hybrid Vehicles
Hybrid Powertrain Systems Market