
 India Automotive Glass Fiber Composites Market | 2026-2036
India Automotive Glass Fiber Composites Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive Glass Fiber Composites Market Foresight
Modular component bundling is consolidating procurement patterns across Indian automotive supply chains. Owens Corning leverages its fiber formulation expertise to anchor high-performance reinforcement supply to tier-1 suppliers. BASF India Ltd. competes through localized resin compounding operations that sustain just-in-time delivery commitments to Chennai and Pune manufacturing clusters.
India automotive glass fiber composites combine E-glass or S-glass reinforcement with thermoset matrices such as epoxy, polyester, or vinyl ester, achieving specific tensile strength above 300 MPa and density below 2.0 g/cm³ for weight-critical structural applications. These materials primarily serve vehicle lightweighting mandates while maintaining crash integrity and corrosion resistance. Body panels dominate current volume absorption given their scale in passenger car and commercial vehicle programs, while electric vehicle battery enclosures represent the fastest-expanding application segment as OEMs seek mass reduction for range optimization. The RTM manufacturing technique captures expanding share where dimensional precision and surface finish requirements tighten.
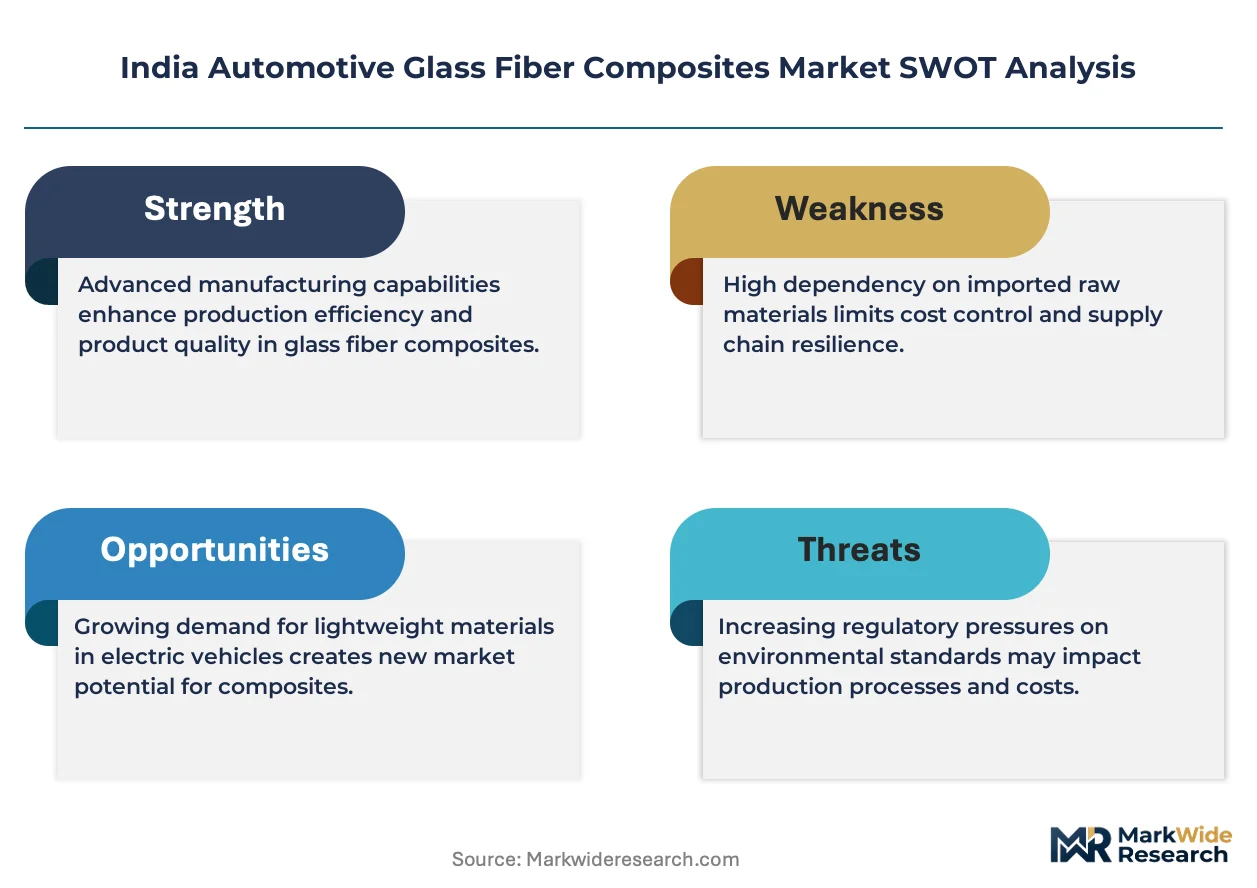
BIS certification protocols and ARAI homologation standards govern material qualification and crash-performance validation for automotive composites sold in India. The PLI scheme for automobile and auto component manufacturing intensifies capital flows toward domestic fiber and resin production, tightening import dependency. OEMs and tier-1 suppliers must monitor evolving FAME subsidy structures and state-level EV policies that directly alter composite content specifications across vehicle platforms.
Market Dynamics
The PLI scheme for automobile and auto component manufacturing is redirecting capital toward domestic fiber and resin production, tightening import dependency while OEMs scramble to localize supply chains ahead of subsidy compliance deadlines.
Growth Catalysts
- FAME subsidy structures:State-level EV policies in Maharashtra and Karnataka directly alter composite content specifications, mandating lighter battery enclosures to maximize electric range eligibility.
- RTM manufacturing technique:Resin transfer molding captures expanding share where dimensional precision and surface finish requirements tighten for passenger car body panels.
- Tamil Nadu assembly corridors:Electric vehicle manufacturers in this state are scaling orders for lightweight structural components, creating concentrated demand pull for glass fiber reinforced polymers.
Market Restraints
- Epoxy resin price volatility:Petrochemical feedstock fluctuations transmit directly to thermoset matrix costs, compressing tier-1 supplier margins on fixed-price OEM contracts.
- S-glass fiber import concentration:High-performance reinforcement grades remain concentrated in Chinese and European supply bases, exposing Indian compounders to currency and logistics risk.
- ARAI homologation timeline:Extended crash-performance validation cycles for new composite formulations delay platform integration by 18-24 months versus metallic alternatives.
Strategic Opportunities
- Haryana commercial vehicle clusters:Underpenetrated heavy truck cab and cargo body applications offer volume expansion as Bharat Stage VI emission norms intensify weight reduction mandates.
- Battery enclosure convergence:Integration of thermal runaway protection with structural load-bearing functions creates specification white space for multifunctional composite designs.
- DGFT import substitution incentives:Localized E-glass fiber production under phased manufacturing programs reduces landed cost disadvantage against Asian competitors.
Industry Challenges
- Tooling capex intensity:RTM and compression mold fabrication for complex automotive geometries requires specialized equipment investments that strain mid-tier supplier balance sheets.
- BIS certification backlog:Material qualification queue delays at Bureau of Indian Standards testing facilities extend time-to-revenue for new compound formulations.
- Polymer-matrix recycling infrastructure:End-of-life thermoset composite recovery capabilities remain underdeveloped, creating compliance exposure under extended producer responsibility frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive Glass Fiber Composites Market |
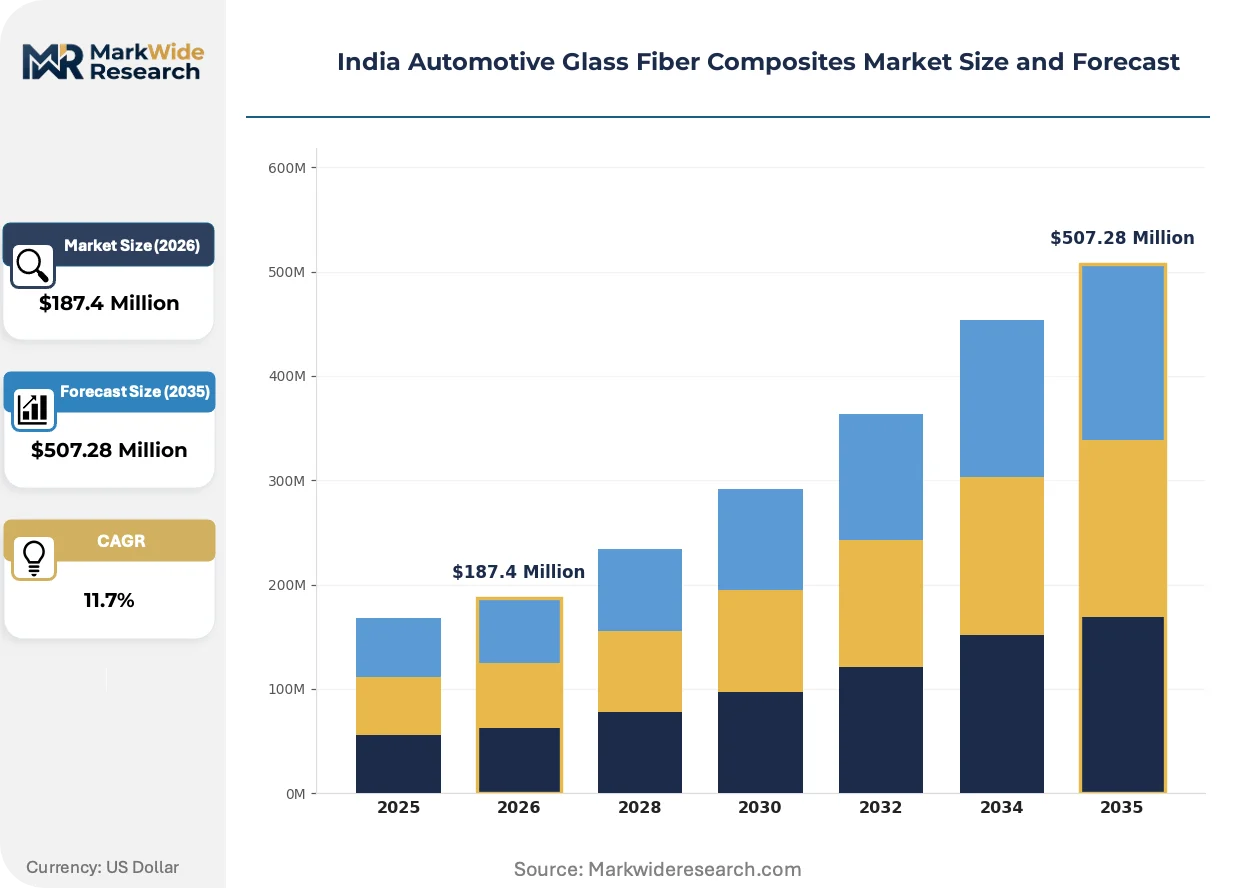
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Body Panels, Roof Liners, Door Trims, Bumpers Application: Passenger Cars, Commercial Vehicles, Electric Vehicles, Specialty Vehicles Manufacturing Technique: Hand Lay-Up, Spray-Up, Pultrusion, RTM End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | SAERTEX GmbH & Co.KG, BASF India Ltd., Owens Corning, U.P. Twiga Fiber Glass Ltd, Saint-Gobain India Private Limited, Solvay Group, Veplas Group, Goa Glass Fibre Limited, 3B (Braj Binani Group), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive Glass Fiber Composites Market Shifts & Advancements
Automation of manufacturing processes and tightening crash-test protocols are compressing development cycles while reshaping competitive requirements for Indian automotive composite suppliers.
Automated fiber placement systems are automating preform construction for complex battery enclosure geometries. Tier-1 suppliers in Pune and Chennai manufacturing clusters are adopting robotic layup cells to reduce cycle time variation. The technology is automating quality consistency thresholds that manual processes cannot sustain at production volumes above 50,000 units annually.
BIS certification protocols governing material qualification were tightened in coordination with Automotive Research Association of India crash-performance validation standards. The regulatory revision mandates dynamic impact testing at velocities previously reserved for metallic structures. Passenger car OEMs in Gujarat and Maharashtra assembly corridors are responding by qualifying hybrid glass-carbon reinforcement schedules.
Modular component bundling is consolidating procurement patterns across Indian automotive supply chains. Tier-1 suppliers now contract for integrated body panel and structural reinforcement packages rather than discrete material shipments. The behavioral shift is most visible in Karnataka, where electric vehicle platforms specify subsystem-level composite content guarantees from single-source integrators.
India Automotive Glass Fiber Composites Market Segmentation
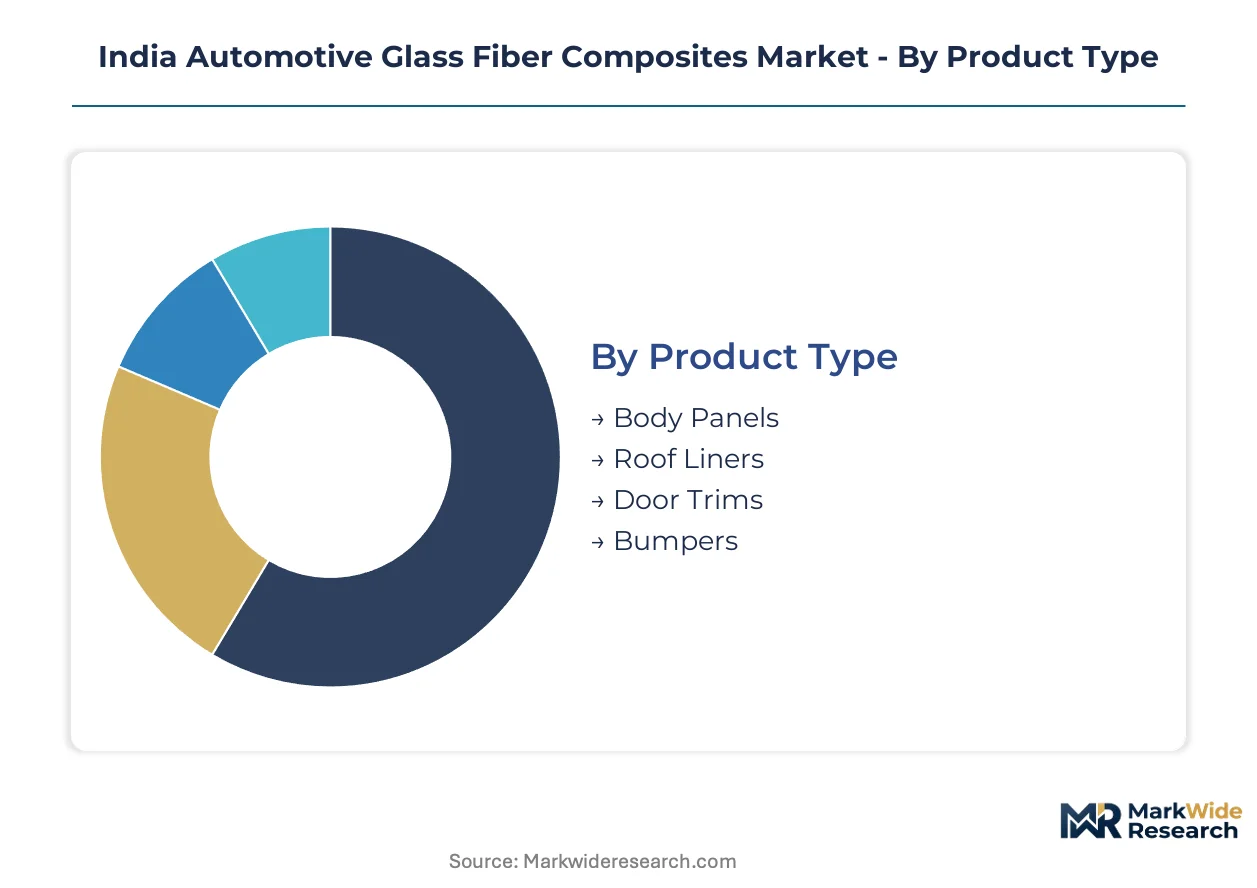
Glass fiber composite specifications vary sharply across automotive subsystems in India. Material selection hinges on surface finish requirements, structural load paths, and the manufacturing scale of each vehicle platform.
Product Type:
Surface finish tolerances and structural complexity determine which product category commands procurement priority from Maharashtra and Karnataka assembly corridors.
- Body Panels:These components combine E-glass reinforcement with polyester or vinyl ester matrices to achieve Class A surface finish for exterior visibility. Demand concentrates around passenger car hoods and trunk lids where weight reduction targets meet aesthetic requirements. OEMs in Gujarat specify these for mid-size sedan programs seeking fuel efficiency compliance.
- Roof Liners:Headliner substrates utilize chopped strand mat construction with polyurethane foam cores for acoustic dampening. Tamil Nadu electric vehicle manufacturers specify these for panoramic roof architectures where mass reduction must coexist with head impact protection. The segment climbs fastest as cabin refinement expectations rise across premium vehicle tiers.
- Door Trims:Interior panels integrate glass fiber with thermoplastic backers for impact resistance and tactile quality.
- Bumpers:Energy-absorbing cores use long-fiber reinforced compounds meeting pedestrian safety protocols.
Volume sits with body panels; growth tilts toward roof liners.
Application:
Vehicle electrification intensity and emission compliance deadlines reshape composite content specifications across platform categories.
- Passenger Cars:Body-in-white applications and closure panels absorb the majority of current glass fiber volume. Haryana and Pune manufacturing clusters specify hybrid reinforcement schedules for B-pillar reinforcements where side-impact ratings determine model viability. BIS crash-test protocols drive material thickness and fiber orientation requirements.
- Electric Vehicles:Battery enclosure structures represent the steepest expansion trajectory as OEMs seek mass reduction for range optimization. Karnataka and Tamil Nadu assembly plants specify fire-retardant epoxy formulations meeting thermal runaway containment standards. The PLI scheme for auto manufacturing accelerates localized supply chain development for these safety-critical components.
- Commercial Vehicles:Cab structures and cargo bodies offer underpenetrated volume potential as Bharat Stage VI norms intensify weight reduction mandates.
- Specialty Vehicles:Defense and agricultural equipment utilize heavy-tow rovings for impact resistance in severe service environments.
Passenger cars anchor current procurement; electric vehicles are gaining share fastest.
Manufacturing Technique:
Production volume thresholds and dimensional precision requirements dictate process selection across supplier tiers.
- RTM:Resin transfer molding captures expanding share where dimensional tolerance below 0.5mm and painted surface quality are mandatory. Tier-1 suppliers in Chennai deploy closed-mold automation for battery enclosure lids requiring seal integrity against water and dust ingress. The technique sustains cycle times compatible with 50,000-unit annual platforms.
- Hand Lay-Up:Open-mold fabrication persists for low-volume specialty vehicle components and prototype development. Maharashtra suppliers retain this capability for commercial vehicle aftermarket repair panels where tooling investment recovery is uncertain. Labor intensity limits scalability beyond 10,000-unit programs.
- Spray-Up:Chopped roving deposition suits thick-section cargo body panels where surface finish is secondary to impact absorption.
- Pultrusion:Continuous profile manufacture serves bumper beams and structural rails requiring consistent cross-sectional properties.
Hand lay-up retains volume in aftermarket channels; RTM expands most quickly in OEM supply.
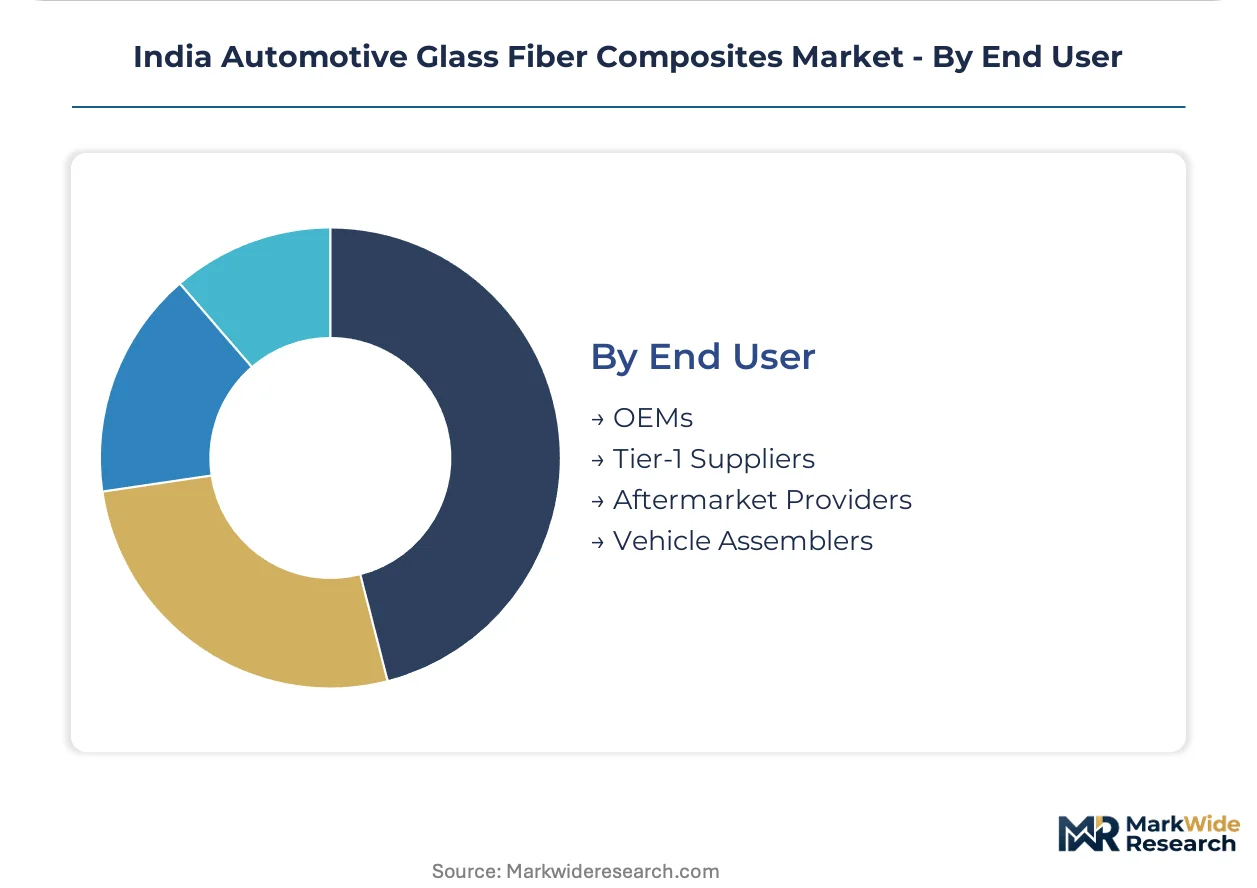
End User:
Supply chain position and technical integration responsibility determine composite procurement authority.
- OEMs:Direct material specification authority concentrates with Maruti Suzuki, Tata Motors, and Mahindra for proprietary body architectures. These manufacturers set fiber grade, resin system, and surface finish standards that cascade through supply contracts. In-house composite competence remains limited to pilot programs and racing applications.
- Tier-1 Suppliers:Motherson, Bharat Forge, and similar integrators consolidate procurement for subsystem-level content packages. These firms operate compounding and molding facilities in Pune, Chennai, and Manesar to satisfy just-in-time delivery commitments. Their technical staff mediate between OEM design studios and raw material vendors.
- Vehicle Assemblers:Contract manufacturers and joint venture partners execute build-to-print programs with limited material discretion.
- Aftermarket Providers:Independent distributors serve collision repair and customization segments with hand-laminated panels.
Tier-1 suppliers capture procurement volume; OEMs are tightening specification control fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Tamil Nadu concentrate glass fiber composite demand through tax incentives and plug-and-play infrastructure for electric vehicle component manufacturing.
Gujarat
Electric vehicle battery enclosure programs and passenger car lightweighting mandates drive composite procurement from Sanand and Halol assembly corridors. The state electronics policy and Gujarat Industrial Development Corporation infrastructure subsidies accelerate resin compounding facility establishment. Ahmedabad-based tier-1 suppliers coordinate just-in-time delivery to Tata Motors and MG Motor India plants.
Tamil Nadu
Two-wheeler and electric vehicle OEMs scale orders for structural reinforcement components from Sriperumbudur and Oragadam manufacturing belts. The Tamil Nadu Electric Vehicle Policy offers capital subsidies up to twenty percent for composite component suppliers meeting localization thresholds. Chennai clusters host automated RTM production lines serving Hyundai and Ola Electric platforms.
Maharashtra
Passenger car body panel specifications and commercial vehicle cab structures absorb the majority of glass fiber volume from Pune and Chakan industrial zones. The Maharashtra Electric Vehicle Policy mandates domestic value addition requirements that favor localized fiber reinforcement supply chains. Pimpri-Chinchwad suppliers integrate with Mahindra and Bajaj Auto assembly operations.
Haryana
Commercial vehicle manufacturers seek mass reduction solutions for Bharat Stage VI compliance across Gurugram and Manesar production hubs. The Haryana Enterprises Promotion Policy targets automotive component investments through land allotment preferences and stamp duty exemptions. Faridabad-based fabricators supply Maruti Suzuki and Hero MotoCorp with structural composite assemblies.
Karnataka
Electric vehicle startups and premium passenger car OEMs specify fire-retardant epoxy formulations for battery enclosures from Bengaluru and Hosur manufacturing corridors. The Karnataka Electric Vehicle and Energy Storage Policy provides reimbursement on state goods and services tax for composite component investments. Nelamangala suppliers coordinate with Ather Energy and Volvo Car India platforms.
India Automotive Glass Fiber Composites Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across raw material supply and component fabrication tiers. Market structure tilts toward consolidation at the fiber and resin production level, with fragmentation persisting among mid-tier molding specialists. Three archetypes dominate: multinational chemical conglomerates with localized compounding operations, domestic fiber manufacturers leveraging import substitution incentives, and tier-1 automotive suppliers integrating backward into composite fabrication. Capacity expansion and strategic technology licensing represent the primary competitive moves as firms position for PLI scheme compliance deadlines.
Among multinational material suppliers, Owens Corning and BASF India Ltd. anchor the high-performance reinforcement and resin compounding segments respectively. SAERTEX GmbH & Co.KG exemplifies the specialized technical textile archetype, while U.P. Twiga Fiber Glass Ltd. and Goa Glass Fibre Limited represent domestic manufacturing positions within the supply base. Saint-Gobain India Private Limited occupies a diversified industrial materials position spanning multiple automotive substrate applications.
| Leading Market Players |
|---|
| SAERTEX GmbH & Co.KG |
| BASF India Ltd. |
| Owens Corning |
| U.P. Twiga Fiber Glass Ltd |
| Saint-Gobain India Private Limited |
| Solvay Group |
| Veplas Group |
| Goa Glass Fibre Limited |
| 3B (Braj Binani Group) |
| Others |
Supply & Pricing Matrix
Epoxy resin price indices on the Indian commodity exchanges cascade through thermoset matrix formulations into tiered procurement contracts across OEM and tier-1 supplier tiers. Petrochemical feedstock volatility compresses margin structures at the compounding stage, forcing price renegotiation clauses into annual offtake agreements with Maharashtra and Tamil Nadu assembly plants.
Pricing Analysis
Cost-down pressure on E-glass fiber grades accelerates because Chinese import competition intensifies under DGFT duty restructuring. Three-tier pricing structure across premium S-glass, standard E-glass, and economy chopped strand mat levels separates qualification-intensive battery enclosure applications from commercial vehicle aftermarket panels. OEM direct contracts exhibit lowest price sensitivity given PLI scheme compliance deadlines; mid-tier molders face acute margin compression on fixed-price heritage programs.
Supply Chain Analysis
Dual-sourcing mandates from Maruti Suzuki and Tata Motors require tier-1 suppliers to qualify fiber reinforcement from both domestic and Chinese origins. Geographic supply concentration centers on China for high-performance S-glass rovings, India for localized E-glass mat production, and Germany for specialized epoxy resin formulations. Raw material dependencies rest on petrochemical-derived epoxy hardeners, borosilicate glass batch for fiber drawing, and aluminum oxide precursors for S-glass chemistry. Single-source vulnerability persists in aerospace-grade fiber imports. Distribution runs through just-in-time hub arrangements at Pune, Chennai, and Manesar manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India automotive glass fiber composites market is consolidating around PLI scheme compliance capabilities, with capital intensity and ARAI homologation timelines forcing sub-scale compounders toward exit or acquisition.
For Market Incumbents: Deepen backward integration into resin compounding at Gujarat and Tamil Nadu special economic zones to defend margin structures against epoxy price volatility. Anchor supply contracts through BIS certification pre-qualification investments that extend ARAI validation timelines for challenger formulations. Prioritize RTM automation capex in Chennai clusters to sustain cycle time advantages over hand-lay-up competitors. For New Entrants and Emerging Players: The PLI scheme for automobile and auto component manufacturing in India opens a window for localized fiber production investments targeting battery enclosure specifications. Penetrate the underdeveloped Haryana commercial vehicle cab segment where Bharat Stage VI weight mandates outpace incumbent capacity expansion. Lead with fire-retardant epoxy formulation partnerships rather than commodity E-glass supply to bypass entrenched pricing tiers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier molders with ARAI-validated product libraries in Maharashtra and Karnataka corridors. Long-term viability hinges on electric vehicle platform penetration rates and thermal runaway protection specification convergence. Watch FAME subsidy renewal negotiations as the inflection signal for battery enclosure content acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Localized epoxy formulation at Pune facilities reduces landed cost exposure to petrochemical volatility. |
| ARAI Homologation Pre-Investment | Early crash-test validation commitment locks out challengers on 18-24 month platform integration cycles. |
| RTM Production Line Automation | Robotic layup cells at Chennai tier-1 suppliers sustain quality thresholds above 50,000-unit annual volumes. |
| Battery Enclosure Thermal Management Partnership | Fire-retardant epoxy co-development with Karnataka EV platforms captures specification-setting authority. |
| Gujarat Special Economic Zone Capacity Expansion | GIDC infrastructure subsidies compress breakeven timelines for domestic fiber drawing operations. |
Research Methodology
Multi-period observation of vehicle production registrations, PLI scheme disbursement filings, and BIS certification queues anchored the trend analysis, supplemented by interviews with tier-1 supplier procurement directors, OEM platform engineers, resin compounding plant managers, and ARAI homologation officers. Secondary validation drew from Directorate General of Foreign Trade import statistics, Automotive Research Association of India technical bulletins, state industrial development corporation investment databases, and vehicle segment-wise production data. Bottom-up fiber and resin volume estimates were triangulated against top-down composite content per vehicle assumptions across passenger car, electric vehicle, and commercial vehicle platforms.
Input-output matrices modeled resin consumption against fiber reinforcement tonnage, segmented by manufacturing technique intensity, application structural criticality, and end-user supply chain position. CAGRs were derived from elasticity-adjusted demand projections tied to FAME subsidy penetration scenarios and Bharat Stage VI compliance deadlines. Forecast inputs incorporated electric vehicle battery enclosure specification evolution and RTM automation adoption curves across Tamil Nadu and Maharashtra supplier clusters.
The model assumes a particular technology adoption path; alternative pathways for thermoplastic composite displacement of thermoset systems would alter the outlook. Forecasts reflect material qualification timeline assumptions and PLI scheme continuity parameters. Deviation in FAME subsidy structure or BIS certification backlog severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Carbon Fiber Market
Automotive Components
Asia Pacific Automotive Actuators Market
Automotive Components
Automotive Straps Market
Automotive Components
Alloys for Automotive Market
Automotive Components
Automotive Radiator Fan Market
Automotive Components
Automotive Grade Modules Market
Automotive Components
Automotive Exhaust Manifolds Market
Automotive Components
Off-Highway Actuators Market
Automotive Components
Automotive Engine Encapsulation Market
Automotive Components
Automotive Millimeter Wave Compatible Emblem Market
Automotive Components
Russia Automotive Pneumatic Actuators Market
Automotive Components
Automotive Front-End Module (FEM) Market
Automotive Components
Auto Fender Market
Automotive Components
Global Automotive HUD Market
Automotive Components
South Korea Automotive Sunroof Market
Automotive Components
Global Automotive Cigarette Lighters Market