
 Asia Pacific Automotive AHSS Market | 2026-2036
Asia Pacific Automotive AHSS Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Automotive AHSS Market Outlook
Market Context
The tier-1 supplier channel is narrowing as steelmakers build direct OEM relationships. ArcelorMittal SA leverages its integrated global R&D network to sustain technology leadership in hot-stamped solutions. POSCO anchors Korean supply through captive production lines serving Hyundai-Kia platforms. Tata Steel Limited competes on cost-optimized cold-rolled grades for mass-market Indian OEMs.
Technical and Segment Dynamics
Automotive advanced high-strength steel encompasses alloy formulations exceeding 500 MPa tensile strength, produced through controlled thermomechanical processing or direct quenching to achieve crash-energy absorption with reduced gauge thickness. Hot stamped grades dominate structural applications where extreme strength-to-weight ratios justify capital-intensive press-hardening lines, while dual phase material grades capture expanding share in chassis components due to superior formability versus martensitic alternatives. Body structure applications command the deepest margin pools as OEMs consolidate platforms around standardized AHSS-intensive architectures.
Regulatory Environment
India's BIS certification and PLI scheme for specialty steel, China's GB standards administered by SAMR, and Japan's METI fuel-efficiency mandates collectively tighten material performance thresholds. These frameworks compel mills to document carbon intensity and recyclability credentials alongside mechanical properties. Stakeholders must track how India's phased emission norms and China's dual carbon goals redirect procurement toward EAF-produced AHSS grades.
Market Dynamics
India's PLI scheme for specialty steel is compressing supplier margins while forcing domestic capacity expansion, as OEMs requalify local mills for platform-critical structural grades previously sourced from Korean and Japanese integrated producers.
Growth Catalysts
- Crashworthiness mandates:India's BIS certification protocols for passenger vehicle safety are compelling OEMs to adopt hot-stamped boron steel in A-pillar and roof-rail assemblies, displacing conventional high-strength grades below 980 MPa tensile strength.
- Platform electrification:Battery electric vehicle architectures require AHSS-intensive battery enclosures and crash structures to offset pack mass, with Korean and Chinese OEMs specifying martensitic grades for underfloor protection.
- Western India manufacturing corridor:Concentrated capacity in Pune, Chennai, and Gujarat clusters enables just-in-time delivery to Maruti Suzuki, Tata Motors, and Hyundai Motor India assembly plants, reducing logistics costs for coil-to-blank supply chains.
Market Restraints
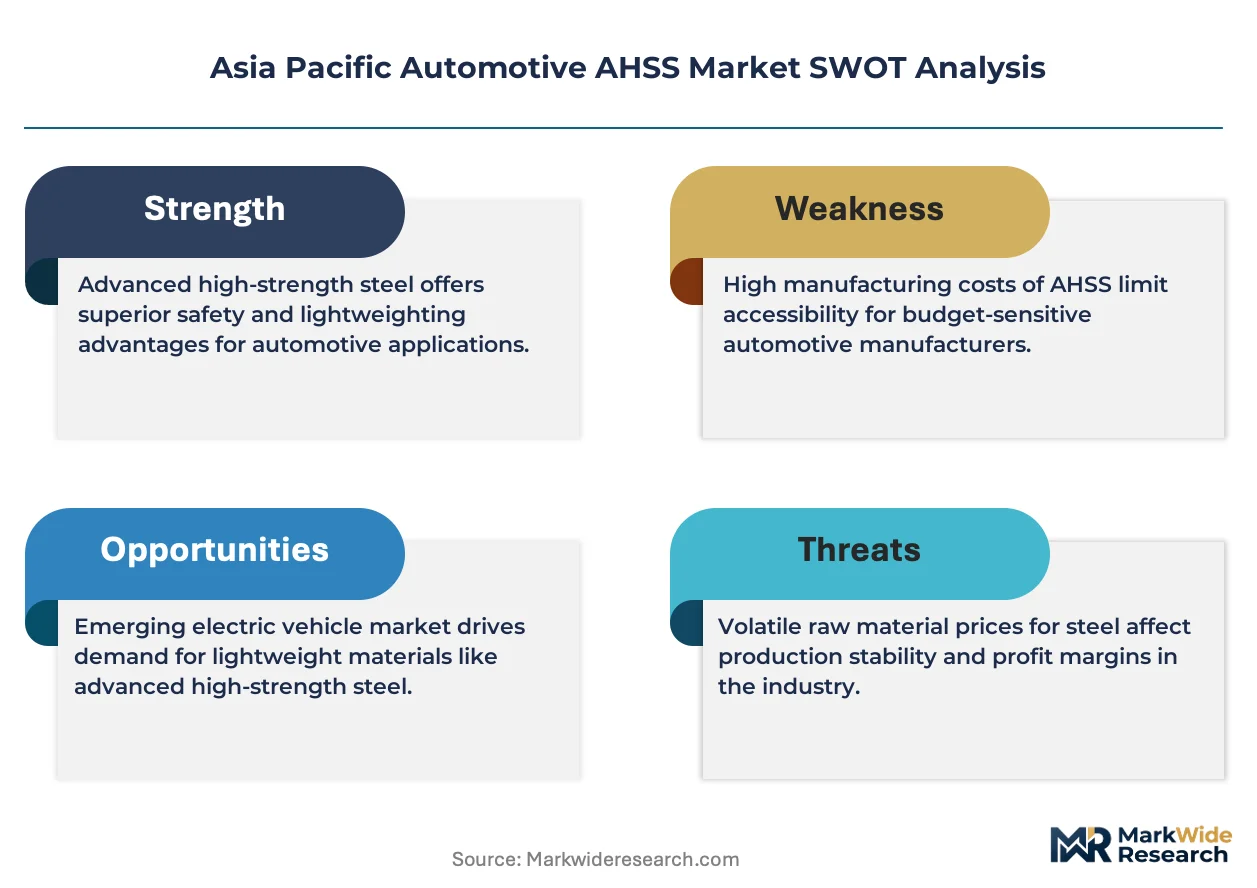
- Nickel and molybdenum price volatility:Alloy surcharges on dual-phase and TRIP grades fluctuate with London Metal Exchange pricing, compressing mill margins and forcing quarterly contract renegotiations with tier-1 stampers.
- Korean supply concentration:POSCO and Hyundai Steel control over sixty percent of regional hot-rolled coil capacity for automotive grades, creating single-source risk for Japanese and Southeast Asian OEMs without captive steelmaking.
- Aluminum substitution in closures:Hood and door outer panels increasingly specify 5000-series and 6000-series aluminum sheet for mass reduction, displacing cold-rolled AHSS in non-structural applications above 1.2 mm gauge.
Strategic Opportunities
- Vietnam and Indonesia passenger vehicle buildout:Emerging assembly capacity for Toyota, Honda, and VinFast creates first-mover advantage for mills establishing local slitting and blanking operations ahead of ASEAN trade integration.
- Third-generation AHSS for chassis:Quench-and-partitioning and medium-manganese formulations enable 1200 MPa strength with 20% elongation, opening control arm and subframe applications previously reserved for forged aluminum.
- China's dual carbon goals:MEE enforcement of carbon intensity disclosure favors EAF-produced AHSS with scrap-based feedstock, rewarding mills with vertical integration into ferrous scrap processing and renewable-powered melting capacity.
Industry Challenges
- Hot-stamping die engineering talent scarcity:Tooling design for press-hardening lines requires specialized knowledge of thermal cycle management and coating systems, with fewer than 200 qualified engineers across India and Southeast Asia.
- Multi-material joining certification:OEM weld qualification protocols for AHSS-to-aluminum and AHSS-to-carbon fiber adhesive bonding extend platform development cycles by 8-14 months, delaying model launches.
- Scrap sorting and segregation infrastructure:Downcycling of post-consumer automotive steel into construction grades destroys alloy value, requiring investment in automated shredding and sensor-based separation to close AHSS recycling loops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Automotive AHSS Market |
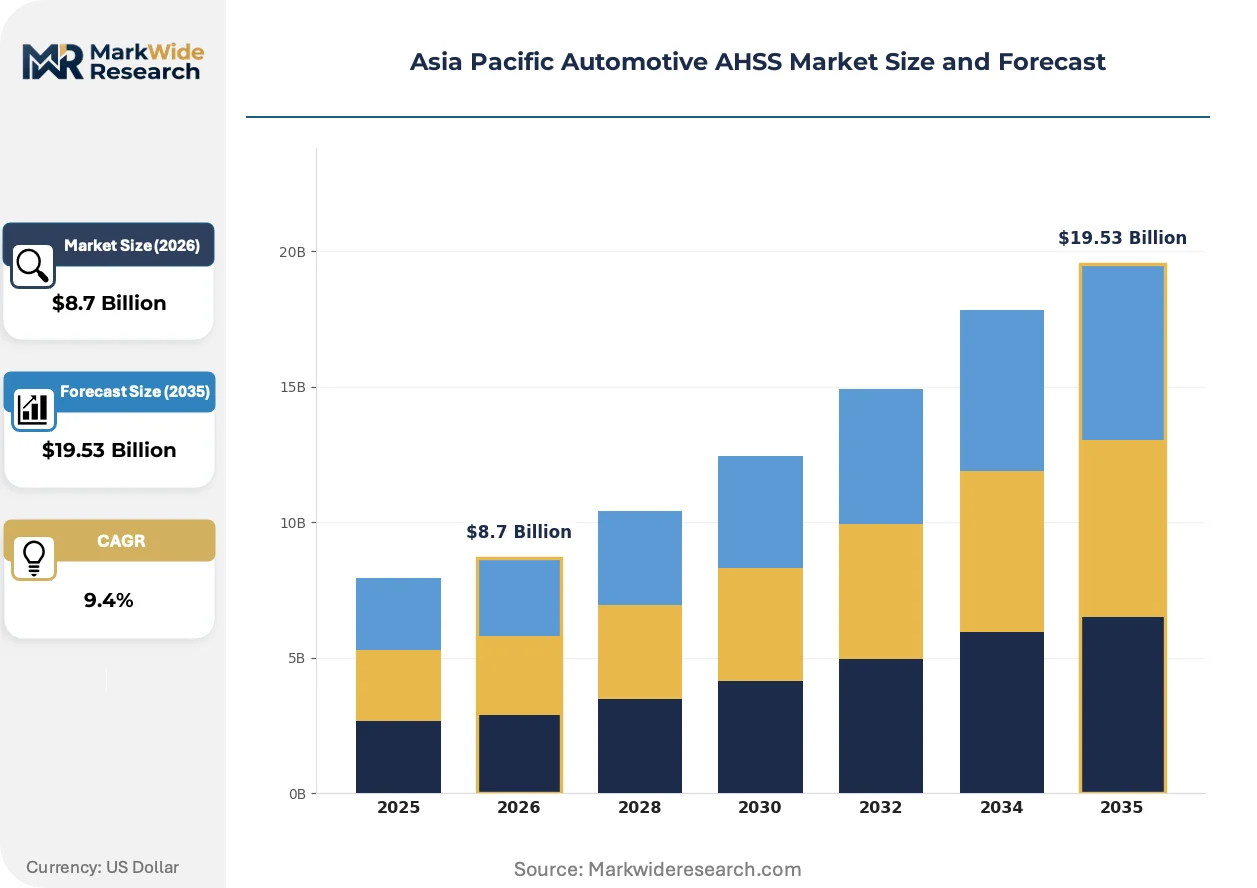
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Stamped, Cold Rolled, Formable, Ultra High Strength Application: Body Structure, Chassis, Suspension, Panels End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Material Grade: Dual Phase, Trip Steel, Quenching, Others |
| Companies Covered | ArcelorMittal SA, China Baowu Steel Group Corp, POSCO, Tata Steel Limited, SSAB AB, ThyssenKrupp AG, Kobe Steel Ltd, Baoshan Iron & Steel Co Ltd, Nippon Steel Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Automotive AHSS Market Strategic Shifts
Material-process integration is collapsing the traditional boundary between steelmaking and component forming, as mills invest in downstream blanking, laser-welded tailored blanks, and predictive alloy design.
Press-hardening technology is hybridizing with in-die tempering and partial austenitization to produce gradient-strength components from single blanks. Hyundai-Kia and Great Wall Motor are qualifying these process variants for B-pillar reinforcements that reduce piece counts and assembly steps. The convergence is compressing lead times for complex structural parts while raising capital barriers for stampers without thermal processing expertise.
China's GB standards administered by SAMR are tightening permissible variance in tensile strength and elongation for automotive structural grades, forcing mills to retool finishing lines with inline X-ray fluorescence and automated surface inspection. The regulatory compression is disqualifying second-tier producers from platform supply to BYD, NIO, and Xpeng, consolidating procurement around integrated steelmakers with metallurgical R&D capabilities.
Buyer concentration among electric vehicle pure-plays is rewiring procurement terms toward performance-guaranteed supply contracts with indexed alloy surcharges. NIO and Li Auto now specify mechanical property bands rather than discrete grade designations, transferring metallurgical risk to mills. The behavioral shift is most pronounced in China's Yangtze River Delta, where Tesla Shanghai, NIO, and Volkswagen Anhui anchor demand for customized AHSS chemistries with 48-hour mill-to-stamping-plant delivery windows.
Asia Pacific Automotive AHSS Market Segmentation
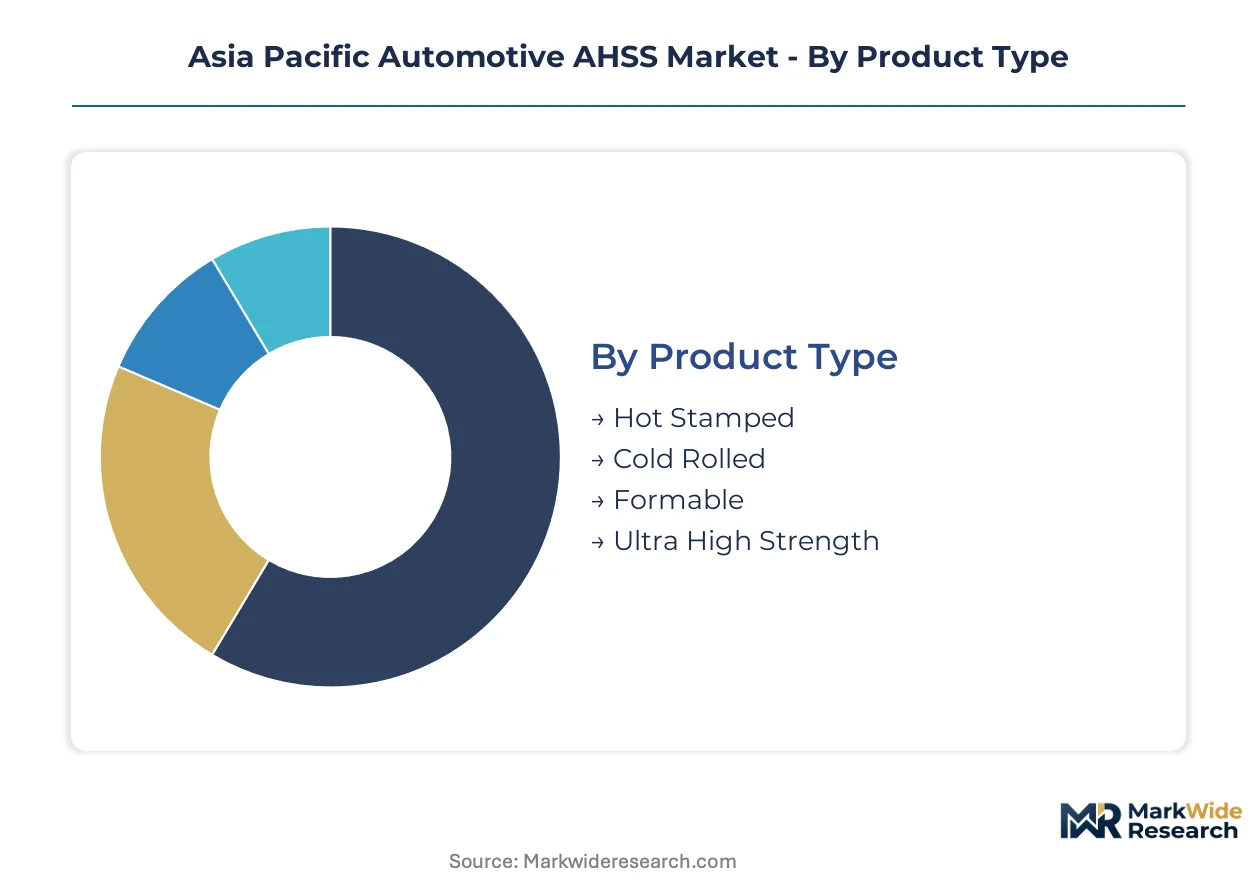
Automotive advanced high-strength steel procurement in Asia Pacific follows distinct technical and commercial fault lines. Product type determines capital intensity and margin structure, while application segments dictate alloy specification and certification requirements.
Product Type:
Cost tier separates these categories, with capital equipment requirements and energy intensity driving pricing stratification across the supply base.
- Hot Stamped:Boron-alloyed grades undergo austenitization at 900°C followed by die quenching to achieve 1500 MPa tensile strength. Maruti Suzuki and Hyundai Motor India specify these for A-pillar and roof-rail assemblies under BIS crashworthiness protocols, displacing conventional high-strength alternatives below 980 MPa.
- Cold Rolled:Annealed dual-phase and complex-phase grades deliver 600-980 MPa strength through continuous annealing lines without press-hardening infrastructure. Tata Motors sources these for mass-market platforms in Pune and Gujarat clusters where gauge reduction must balance cost against formability.
- Formable:Retained austenite TRIP grades achieve 30% elongation at 780 MPa, serving deep-drawn structural components.
- Ultra High Strength:Martensitic grades exceeding 1200 MPa target battery enclosure reinforcements for electric vehicle platforms.
Hot Stamped holds installed capacity. Ultra High Strength is rotating up the share rankings.
Application:
Volume concentration tracks platform architecture decisions, with crash structure standardization creating procurement scale effects.
- Body Structure:Platform-critical pillars, rails, and crossmembers absorb collision energy while enabling cabin integrity. BYD and NIO in China's Yangtze River Delta specify gradient-strength hot-stamped assemblies that reduce piece counts and welding operations.
- Chassis:Subframes and control arms demand third-generation quench-and-partitioning grades delivering 1200 MPa strength with 20% elongation. Korean OEMs are qualifying these for forged aluminum substitution in rear suspension modules.
- Suspension:Coil spring seats and knuckle reinforcements specify medium-manganese formulations.
- Panels:Closure outers face aluminum displacement pressure above 1.2 mm gauge, constraining AHSS specification to structural reinforcements.
Body Structure commands procurement volume. Chassis is climbing the fastest as aluminum substitution economics shift.
End User:
Customer type determines contract structure, with captive steel relationships versus merchant market exposure creating divergent procurement behaviors.
- OEMs:Direct mill relationships are consolidating as ArcelorMittal and POSCO qualify proprietary grades for platform supply. Tesla Shanghai and Li Auto now specify mechanical property bands rather than discrete designations, transferring metallurgical risk upstream.
- Tier-1 Suppliers:Stamping specialists like Gestamp and Benteler manage coil-to-blank logistics for just-in-time delivery to assembly plants in India's western corridor.
- Vehicle Assemblers:Contract manufacturers in Vietnam and Indonesia source standardized grades through regional distributors.
- Aftermarket Providers:Collision repair networks consume cut-to-length blanks for structural replacement parts.
OEMs hold direct qualification authority. Tier-1 Suppliers is gaining share as platform complexity rises.
Material Grade:
Maturity curves separate established formulations from emerging chemistries, with R&D investment intensity determining competitive access.
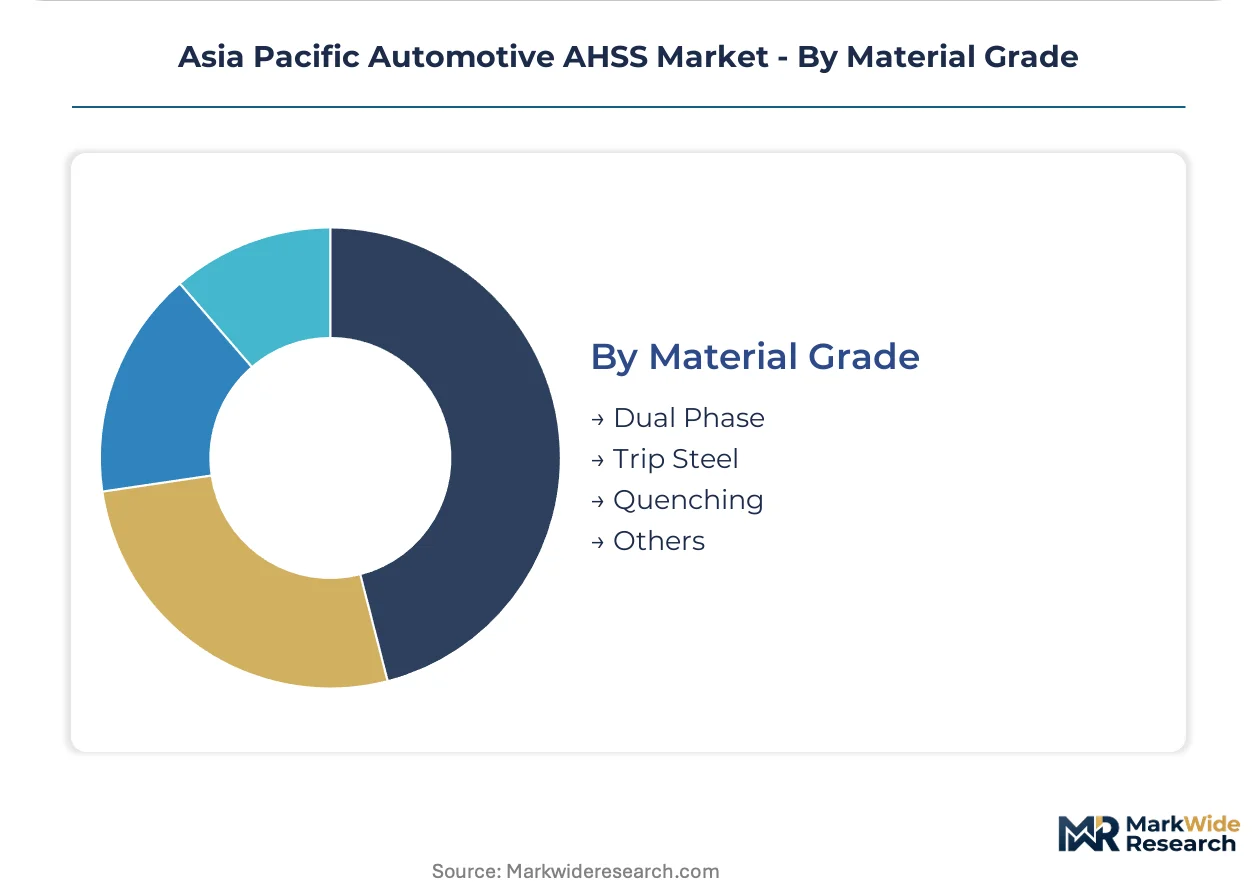
- Dual Phase:Ferrite-martensite microstructures deliver superior formability versus martensitic alternatives, capturing chassis component share where elongation requirements exceed 15%. GB standards administered by SAMR are tightening tensile variance tolerances, disqualifying second-tier producers from BYD and NIO supply.
- Trip Steel:Transformation-induced plasticity grades retain austenite through silicon and aluminum alloying, enabling complex geometries in suspension brackets.
- Quenching:Direct-quenched martensitic grades target battery underfloor protection for electric vehicle architectures.
- Others:Medium-manganese and quench-and-partitioning formulations represent next-generation development pipelines.
Dual Phase holds production scale. Quenching is expanding most quickly on electrification demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Korean mills command pricing power over Japanese and Southeast Asian buyers, while Indian producers absorb margin compression from domestic PLI scheme obligations. This asymmetry reshapes procurement flows across the region's automotive corridors.
China
BYD and NIO in the Yangtze River Delta specify gradient-strength hot-stamped assemblies that reduce welding operations. SAMR-administered GB standards tighten tensile variance tolerances, disqualifying second-tier producers from platform supply. Tesla Shanghai anchors demand with 48-hour mill-to-stamping-plant delivery windows.
India
Maruti Suzuki and Tata Motors source cost-optimized cold-rolled grades for mass-market platforms. BIS certification protocols for passenger vehicle safety compel hot-stamped boron steel adoption in A-pillar assemblies. The western manufacturing corridor spanning Pune, Chennai, and Gujarat enables just-in-time coil-to-blank supply chains.
Japan
Domestic OEMs qualify third-generation quench-and-partitioning grades for chassis applications previously reserved for forged aluminum. METI fuel-efficiency mandates tighten material performance thresholds for structural components. Kansai and Nagoya industrial zones concentrate stamping capacity for Toyota and Honda platforms.
South Korea
Hyundai-Kia platforms drive captive production line investment for hot-rolled coil supply. POSCO anchors regional supply through integrated mill relationships with domestic OEMs. The Busan-Ulsan corridor houses press-hardening infrastructure serving battery electric vehicle architectures.
Vietnam
Emerging assembly capacity for Toyota, Honda, and VinFast creates first-mover opportunity for mills establishing local slitting operations. ASEAN trade integration accelerates regional procurement consolidation. Northern industrial zones near Hanoi attract blanking facility investment ahead of duty-free access expansion.
Asia Pacific Automotive AHSS Market Competitive Environment
Integrated global steelmakers and regional captive producers split the market between technology-licensed solutions and cost-optimized local supply. The structure concentrates procurement authority around mills with metallurgical R&D capabilities and inline quality certification. Two archetypes dominate: technology leaders leveraging hot-stamp process integration, and scale-driven regional suppliers capturing government-incentivized domestic share. Competitive moves center on direct OEM qualification partnerships and downstream blanking capacity expansion.
Within the technology-leader tier, ArcelorMittal SA and POSCO exemplify integrated global networks sustaining R&D leadership in press-hardening solutions. Tata Steel Limited occupies a position among cost-optimized regional suppliers competing for mass-market Indian OEM procurement under PLI scheme requirements. These three anchors represent divergent strategic paths: proprietary grade development versus government-aligned capacity expansion.
| Leading Market Players |
|---|
| ArcelorMittal SA |
| China Baowu Steel Group Corp |
| POSCO |
| Tata Steel Limited |
| SSAB AB |
| ThyssenKrupp AG |
| Kobe Steel Ltd |
| Baoshan Iron & Steel Co Ltd |
| Nippon Steel Corporation |
| Others |
Value Chain & Pricing Dynamics
The Busan-Ulsan corridor in South Korea concentrates press-hardening infrastructure and captive hot-rolled coil capacity, giving POSCO and Hyundai Steel substantial leverage over Japanese and Southeast Asian OEMs in quarterly contract negotiations for boron-alloyed grades.
Pricing Analysis
The customization-premium spread between configured-to-order gradient-strength hot-stamped assemblies and standard cold-rolled dual-phase grades runs wide. Contract-based long-term offtake dominates procurement, with price differentiation driven by certification level under BIS and GB standards plus volume scale. Cost compression in cold-rolled tiers is intensifying because Indian PLI scheme obligations force domestic mills to absorb margin compression. Mass-market Indian OEMs exhibit highest price sensitivity; Chinese EV pure-plays like NIO and Li Auto show lowest sensitivity due to performance-guaranteed supply contracts with indexed alloy surcharges.
Supply Chain Analysis
Tariff exposure between South Korea and Japan dominates supply chain risk calculations for mills serving cross-border OEM platforms. Geographic supply concentrates in South Korea, India, and China. Raw material dependencies draw from nickel, molybdenum, and ferrous scrap feedstock. Single-source vulnerability persists where POSCO and Hyundai Steel control over sixty percent of regional hot-rolled coil capacity. Distribution runs through direct mill-to-OEM relationships and tier-1 stamper coil-to-blank logistics for just-in-time delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform electrification across Asia Pacific is collapsing the traditional steelmaking-stamping boundary into integrated material-process ecosystems, with OEMs now specifying mechanical property bands rather than discrete grades.
For Market Incumbents: Insulate proprietary grade portfolios by deepening captive R&D relationships with Hyundai-Kia and BYD for battery enclosure specifications. Secure backward integration into ferrous scrap processing to meet China's MEE carbon intensity disclosure requirements. Lock in tier-1 stamper partnerships along India's western corridor before PLI scheme obligations force requalification of local mills. For New Entrants and Emerging Players: Vietnam and Indonesia passenger vehicle buildout represents the most penetrable entry point, with Toyota and VinFast assembly capacity creating demand ahead of ASEAN trade integration. Third-generation quench-and-partitioning grades for chassis applications offer technical differentiation against forged aluminum. Establish local slitting and blanking operations with 48-hour delivery windows to mirror Tesla Shanghai procurement terms. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated steelmakers seeking to divest non-core automotive divisions amid carbon transition pressures. Long-term viability hinges on EAF-produced AHSS with renewable-powered melting capacity and inline X-ray fluorescence certification. Watch for MEE enforcement tightening disqualifying second-tier producers from NIO and BYD supply as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Direct OEM Qualification Partnership | ArcelorMittal and POSCO sustain technology leadership through proprietary hot-stamp grade development with platform engineers. |
| Downstream Blanking Capacity Expansion | Local slitting operations in Vietnam and Indonesia capture ASEAN trade integration benefits ahead of competitors. |
| EAF Production Transition | Scrap-based feedstock with renewable melting meets China's dual carbon goals and MEE carbon intensity disclosure. |
| Gradient-Strength Process Integration | In-die tempering and partial austenitization reduce piece counts for Hyundai-Kia B-pillar reinforcements. |
| Automated Scrap Sorting Infrastructure | Sensor-based separation closes AHSS recycling loops and preserves alloy value for closed-loop steelmaking. |
Study Parameters
Cross-validation between primary interviews with OEM platform engineers, tier-1 supplier procurement leads, and steel mill technical directors anchors the qualitative findings. Secondary validation draws from BIS certification records, SAMR GB standard filings, vehicle production databases, and customs trade data for alloy surcharge indices. Bottom-up coil consumption estimates by automotive platform and top-down regional steel demand triangulation bound the market sizing.
Calibration against historical platform standardization cycles and electrification content-per-vehicle trajectories shapes the analytical framework. Segmentation dimensions span product type, application, end user, and material grade across the projection horizon. CAGRs derive from slope-consistent growth rate analysis applied to OEM platform rollout schedules and PLI scheme capacity addition timelines. Forecast inputs include battery electric vehicle architecture penetration and crashworthiness mandate implementation phasing.
Macroeconomic conditions sit as an overlay; deviation in nickel and molybdenum LME pricing, PLI scheme disbursement timing, or ASEAN trade integration pace would shift the trajectory. Forecasts reflect documented assumptions about platform electrification rates and regulatory enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Instrument Cluster Market
Automotive Components
Beryllium Copper for Automobile Market
Automotive Components
Automotive Millimeter Wave Compatible Emblem Market
Automotive Components
Automotive Catalyst Market
Automotive Components
Automotive Polycarbonate Glazing Market
Automotive Components
Automotive Exhaust Components Aftermarket Market
Automotive Components
Casted Automotive Components Market
Automotive Components
Automotive Gudgeon Pin Market
Automotive Components
Automotive Lightweighting Market
Automotive Components
Global Automotive Plastic Compounding Market
Automotive Components
Automotive Headlight Bulb Market
Automotive Components
Automotive Fender Market
Automotive Components
United States Automotive Pneumatic Actuators Market
Automotive Components
Global Flexible Shaft Couplings Market
Automotive Components
Asia-Pacific Automotive Composites Market
Automotive Components
Automotive Metal Stamping Market