
 Asia-Pacific Automotive Composites Market | 2026-2036
Asia-Pacific Automotive Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Automotive Composites Market Outlook
China's Jiangsu and Zhejiang provinces is narrowing the cost gap between glass fiber and carbon fiber automotive components through scaled prepreg manufacturing. Toray Industries leverages its integrated carbon fiber-to-composite supply chain to dominate high-performance structural applications. BASF sustains technology leadership in polyurethane matrix systems for interior components. Mitsubishi Chemical Group Corporation anchors regional supply through its phenolic resin and carbon fiber precursor operations across Japanese and Thai facilities.
Asia-Pacific automotive composites encompass fiber-reinforced polymer materials engineered for specific strength-to-weight ratios exceeding 150 MPa/(g/cm³), manufactured through resin transfer molding or compression molding processes to replace stamped steel and aluminum in vehicle architectures. Their primary purpose centers on mass reduction for fuel efficiency compliance and electric vehicle range extension without sacrificing crashworthiness. Carbon fiber commands premium positioning in structural parts and exterior components where performance thresholds justify material costs, while glass fiber occupies volume applications in interior components and non-structural exterior panels. Prepreg manufacturing stages attract specialized investment from Japanese suppliers, whereas compression molding scales more readily for Chinese OEM in-house production.
China's MIIT enforces GB standards for passenger vehicle corporate average fuel consumption that directly mandate lightweighting material adoption, while Japan's METI administers JIS standards governing carbon fiber quality grades for automotive structural certification. India's BIS is developing localized composite testing protocols under CEA technical committees to reduce import dependency for electric vehicle platforms. Stakeholders must monitor divergence between Chinese domestic content requirements and Japanese material certification reciprocity as supply chain regionalization intensifies.
Market Dynamics
China's dual carbon goals and Japan's tightening fuel economy standards are forcing simultaneous lightweighting acceleration across electric vehicle and internal combustion platforms, compressing material qualification timelines and reshaping supplier-OEM relationships across the region.
Growth Catalysts
- MIIT Corporate Average Fuel Consumption mandates:China's GB standards enforce lightweighting material adoption, directly pulling carbon fiber and glass fiber composites into passenger vehicle architectures as steel substitution becomes compliance-critical.
- Electric vehicle range extension imperatives:Battery electric vehicle manufacturers in the Yangtze River Delta cluster prioritize mass reduction to offset battery weight, concentrating demand for structural composite solutions.
- Prepreg manufacturing scale economies:Japanese suppliers' automated fiber placement capabilities are narrowing cost differentials between carbon fiber and conventional materials, expanding addressable applications.
Market Restraints
- Acrylonitrile precursor supply concentration:Carbon fiber production depends on petrochemical feedstock vulnerable to price volatility, with regional precursor manufacturing concentrated among limited Japanese and Korean suppliers.
- JIS certification reciprocity gaps:Japanese material quality standards lack mutual recognition with Chinese GB testing protocols, creating friction for cross-border component sourcing.
- Aluminum intensive vehicle architectures:Mature aluminum stamping supply chains and established recycling infrastructure present substitution competition for non-structural automotive panels.
Strategic Opportunities
- India BIS composite protocol development:Localization of electric vehicle testing standards under CEA technical committees opens import substitution opportunities for domestic manufacturing.
- Thailand automotive export hub positioning:Japanese supplier facility expansion into ASEAN manufacturing corridors creates regional composite fabrication capacity for right-hand-drive export markets.
- Thermoplastic resin transfer molding convergence:Cycle time compression from thermoplastic matrix adoption enables high-volume exterior panel applications previously reserved for thermoset systems.
Industry Challenges
- Automated fiber placement technician scarcity:Prepreg layup and resin transfer molding operations require specialized workforce development programs that lag behind facility expansion timelines.
- Crashworthiness certification duration:Structural composite homologation for passenger safety cell applications demands extended dynamic testing protocols that delay platform launches.
- Multi-material joining complexity:Dissimilar material interfaces between carbon fiber composites and aluminum or steel substructures require adhesive and mechanical fastening engineering that complicates assembly line integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Automotive Composites Market |
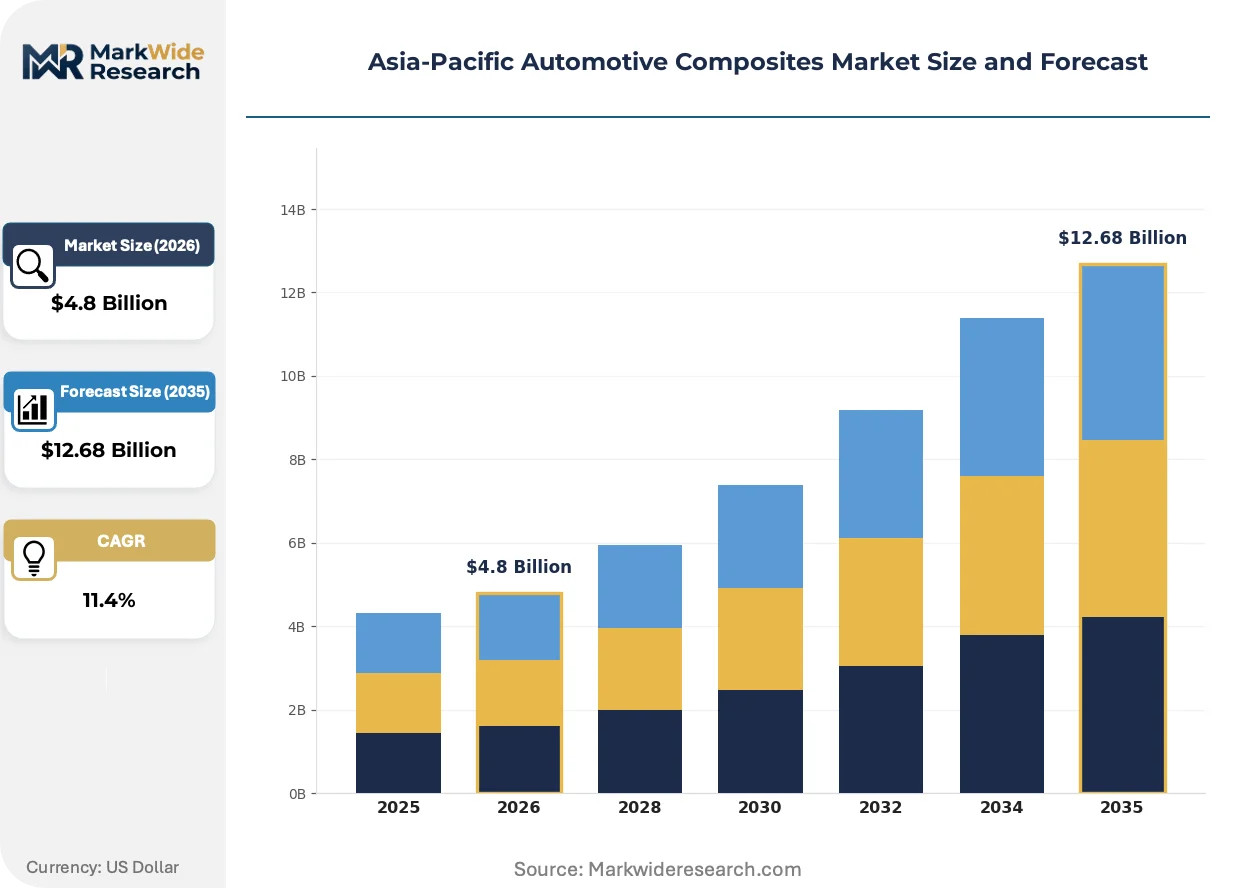
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
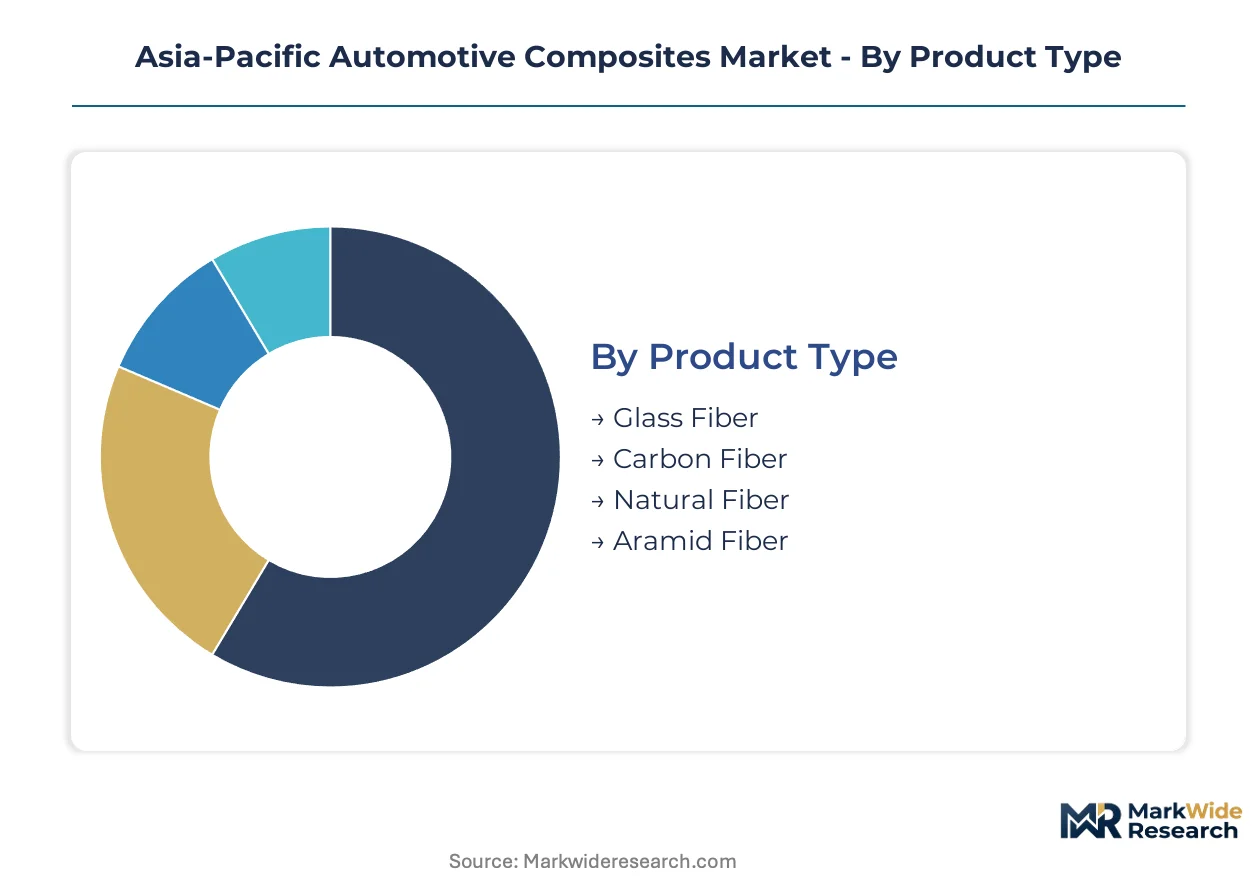
| Segmentation | Product Type: Glass Fiber, Carbon Fiber, Natural Fiber, Aramid Fiber Application: Interior Components, Exterior Components, Structural Parts, Engine Components Manufacturing Stage: Prepregs, Resin Transfer Molding, Compression Molding, Pultrusion End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | BASF, Mitsubishi Chemical Group Corporation, Toray Industries, Gurit, 3B-Fibreglass, Teijin Limited, SGL Carbon, Hexcel Corporation, Solvay, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Automotive Composites Market Strategic Shifts
Material-process convergence and regulatory compression are actively restructuring how automotive composites move from raw fiber to finished vehicle component, with implications for supplier power and OEM insourcing decisions.
Recycled carbon fiber reclaimed from aerospace and industrial waste streams is collapsing the feedstock cost structure for non-structural automotive applications. Tier-1 suppliers in Jiangsu province are integrating pyrolysis-based reclamation into prepreg manufacturing, enabling price positioning that competes with virgin glass fiber in interior trim and underbody panels. This secondary fiber supply is compressing the premium positioning that virgin carbon fiber previously commanded in volume automotive segments.
METI's revised JIS standards for automotive structural carbon fiber quality grades are tightening tensile strength and modulus consistency requirements. Japanese OEMs must recertify existing composite suppliers against accelerated thermal cycling and moisture ingress protocols, diverting engineering resources from new platform development. The certification burden falls heaviest on exterior body panel applications where surface quality and dimensional stability must satisfy Class A finish standards.
Consolidated procurement by Chinese battery electric vehicle platforms is compressing supplier margins and compressing development cycle timelines. NIO, BYD, and XPeng are mandating simultaneous engineering and manufacturing responsibility from composite tier-1s, eliminating traditional tier-2 material supply relationships. This buyer concentration is visible most acutely in the Yangtze River Delta, where co-located fabrication facilities enable just-in-sequence delivery directly to vehicle assembly lines.
Asia-Pacific Automotive Composites Market Segmentation
Segmentation in Asia-Pacific automotive composites reveals how material selection, manufacturing investment, and supply chain position stratify across the region's divergent regulatory and production environments. Understanding these divisions exposes where margin concentrates and which technology transitions reshape competitive advantage.
Product Type:
Mature glass fiber applications coexist with emerging carbon fiber scale economies as Chinese OEMs compress cost differentials through vertical manufacturing integration.
- Glass Fiber:E-glass and S-glass formulations dominate non-structural interior panels and underbody shields where cost thresholds override performance premiums. MIIT fuel consumption mandates pull glass fiber into hood and decklid applications across BYD and Geely platforms in the Yangtze River Delta.
- Carbon Fiber:T700 and T800 grade PAN-based precursors from Toray and Mitsubishi Chemical supply structural passenger cell components and exterior Class A panels. Japanese JIS certification requirements constrain sourcing flexibility for Chinese battery electric vehicle platforms seeking crashworthiness qualification.
- Natural Fiber:Flax and hemp fiber compounds from Indian suppliers serve interior trim applications with lower thermal stability requirements.
- Aramid Fiber:Para-aramid reinforcements occupy niche ballistic and high-temperature engine compartment shields.
Glass fiber retains volume leadership; carbon fiber holds the steepest expansion curve as prepreg manufacturing scales in Jiangsu province.
Application:
Application segmentation tracks the tension between visible surface quality demands and hidden structural performance requirements across vehicle architectures.
- Interior Components:Door panels, instrument carriers, and seat structures utilize glass fiber-polypropylene compounds for acoustic damping and mass reduction. NIO and XPeng specify recycled carbon fiber content in premium cabin trim to satisfy ESG reporting requirements.
- Structural Parts:B-pillars, floor pans, and front-end carriers require carbon fiber epoxy prepregs with tensile strength exceeding 1500 MPa. METI's revised JIS standards extend certification timelines for these safety-critical applications.
- Exterior Components:Fenders, roofs, and liftgates balance surface finish against impact resistance.
- Engine Components:Underhood heat shields and intake manifolds demand phenolic matrix systems.
Interior components command shipment volume; structural parts capture the highest value per kilogram.
Manufacturing Stage:
Manufacturing stage selection determines capital intensity, cycle time, and which supplier tier controls the value chain.
- Prepregs:Automated fiber placement of resin-impregnated carbon fiber tapes enables complex geometries with void content below 2%. Japanese equipment suppliers dominate this precision manufacturing tier, constraining Chinese OEM attempts at backward integration.
- Compression Molding:Sheet molding compound and bulk molding compound processes serve high-volume exterior panels with sub-3-minute cycle times. SAIC and GAC operate captive compression facilities in Guangdong province to bypass tier-1 margin capture.
- Resin Transfer Molding:Closed-mold infusion suits medium-volume structural components.
- Pultrusion:Continuous profile extraction produces bumper beams and running boards.
Compression molding scales fastest; prepreg manufacturing retains the tightest supply concentration.
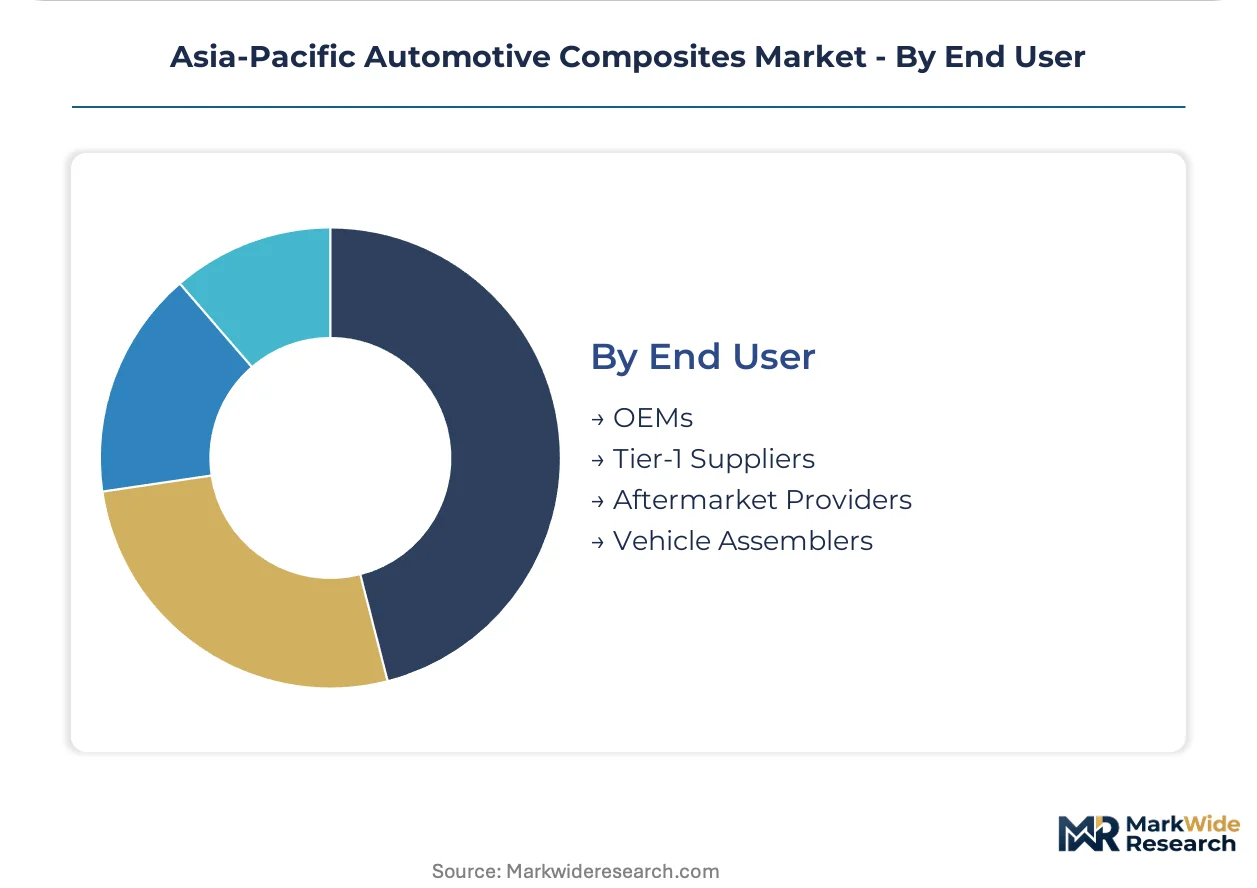
End User:
End user segmentation exposes how procurement centralization and technical capability requirements fragment the supplier landscape.
- OEMs:BYD, NIO, and Toyota specify composite architectures at platform conception, mandating simultaneous engineering participation from material suppliers. Direct OEM contracts eliminate traditional tier-1 intermediaries for structural applications in China's battery electric vehicle segment.
- Tier-1 Suppliers:Bosch, Denso, and Chinese counterparts like CATL's composite division manage subsystem integration and just-in-sequence delivery. These suppliers absorb JIS and GB certification burdens on behalf of vehicle assemblers.
- Vehicle Assemblers:Contract manufacturers in Thailand and Indonesia source composite components for export-market assembly.
- Aftermarket Providers:Performance tuning and collision repair channels serve niche carbon fiber replacement demand.
OEMs consolidate structural procurement; tier-1 suppliers defend position in interior and non-structural exterior supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB standards for corporate average fuel consumption anchor composite demand across the region, with Chinese battery electric vehicle platforms pulling material adoption faster than Japanese regulatory timelines permit.
China
BYD and NIO compress supplier qualification cycles through co-located fabrication in the Yangtze River Delta. The dual carbon goals mandate lightweighting adoption across passenger vehicle architectures. Jiangsu province hosts prepreg manufacturing scale-ups that narrow carbon fiber cost differentials against glass fiber.
Japan
Toyota and Honda extend JIS certification requirements for structural carbon fiber applications. METI's revised quality standards tighten tensile consistency thresholds for safety-critical components. Nagoya's Chubu region concentrates Toray Industries' integrated carbon fiber-to-composite supply chain operations.
India
Tata Motors and Mahindra & Mahindra localize electric vehicle platforms under BIS protocol development. CEA technical committees advance composite testing standards to reduce import dependency. Maharashtra's Pune-Nashik automotive corridor attracts tier-1 supplier facility announcements for domestic content compliance.
South Korea
Hyundai Motor Group accelerates carbon fiber adoption in dedicated electric vehicle architectures. MFDS alignment with international material certification protocols streamlines cross-border sourcing. Gyeonggi Province's battery electric vehicle cluster concentrates composite subsystem procurement for export-market production.
Thailand
Japanese supplier expansion targets right-hand-drive export markets across ASEAN. Board of Investment incentives for electric vehicle component manufacturing attract resin transfer molding capacity. Rayong's Eastern Economic Corridor hosts Mitsubishi Chemical Group phenolic resin operations serving regional automotive fabrication.
Asia-Pacific Automotive Composites Market Competitive Environment
Integrated petrochemical conglomerates and specialized carbon fiber manufacturers split the market through divergent approaches to feedstock control and application engineering. Market structure tilts toward consolidation at the precursor and prepreg tiers, with fragmentation penetrating compression molding and finished component supply. Three archetypes dominate: backward-integrated chemical majors commanding matrix resin supply, Japanese fiber specialists controlling PAN precursor and tow conversion, and Chinese OEM captive operations absorbing tier-1 margin capture. Competitive moves concentrate on simultaneous engineering contracts with battery electric vehicle platforms and JIS-GB dual certification investments.
Among the integrated chemical majors, BASF anchors polyurethane matrix systems for interior component applications. Toray Industries and Mitsubishi Chemical Group Corporation occupy positions spanning PAN precursor through prepreg manufacturing, exemplifying the fiber-to-composite archetype that Japanese suppliers have refined across automotive certification cycles. These three entities represent distinct competitive vectors: European matrix technology leadership, Japanese vertical fiber integration, and regional supply chain anchoring across Thai and Japanese facilities.
| Leading Market Players |
|---|
| BASF |
| Mitsubishi Chemical Group Corporation |
| Toray Industries |
| Gurit |
| 3B-Fibreglass |
| Teijin Limited |
| SGL Carbon |
| Hexcel Corporation |
| Solvay |
| Others |
Value Chain & Pricing Dynamics
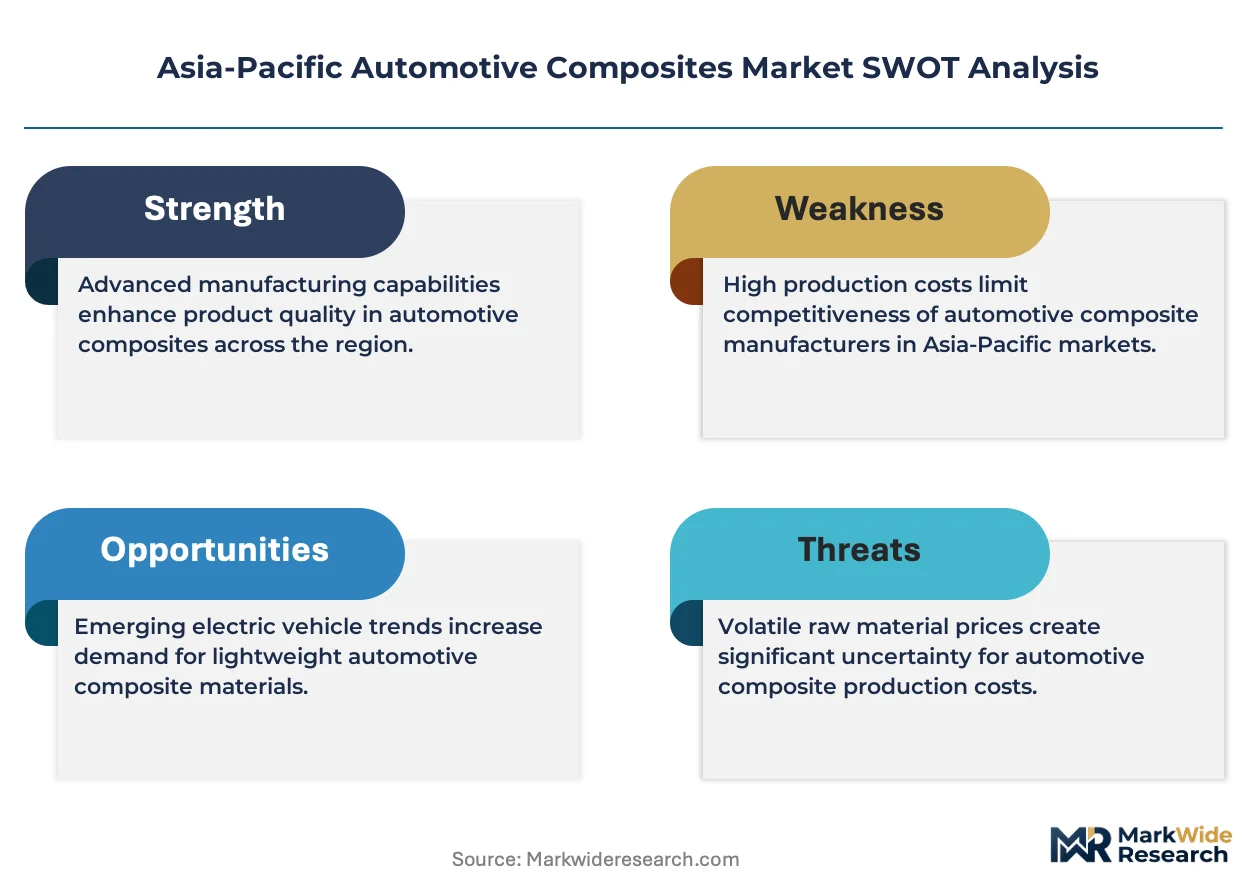
Acrylonitrile precursor supply concentration among Japanese and Korean petrochemical suppliers determines both the premium spread for T800-grade carbon fiber and the regional clustering of prepreg manufacturing capacity. MIIT's domestic content requirements for battery electric vehicle platforms amplify this dependency, compressing margins for Chinese OEMs while reinforcing Toray Industries' pricing power across structural applications.
Pricing Analysis
Jiangsu province carbon fiber pricing runs 15-20% below Nagoya basin equivalents for comparable T700 grades, though JIS certification premiums for structural applications erase much of this spread. Three-tier pricing structure across JIS-certified structural, GB-compliant non-structural, and uncertified industrial grades reflects divergent qualification burdens. Cost compression in compression-molded glass fiber components is intensifying because SAIC and GAC captive facilities bypass tier-1 margin capture. Tier-1 suppliers absorb the highest price sensitivity as OEM direct procurement consolidates.
Supply Chain Analysis
Japan's export control regime on carbon fiber precursor manufacturing technology limits Chinese backward integration into PAN tow production. Geographic supply concentration centers on Japan for T800-grade precursor, South Korea for acrylonitrile feedstock, and China for compression molding compounds. Raw material dependencies span petrochemical-derived acrylonitrile, epoxy resin systems from BASF's regional operations, and phenolic precursors from Mitsubishi Chemical's Thai facilities. Single-source vulnerability sits with Toray's dominance in aerospace-grade tow conversion. Distribution runs through just-in-sequence delivery to Yangtze River Delta assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite component lifecycle services—including crash damage assessment certification and recycled fiber reclamation—expand faster than virgin material supply as ESG reporting mandates penetrate OEM procurement criteria.
For Market Incumbents: Entrench JIS-GB dual certification capabilities as Chinese battery electric vehicle platforms accelerate qualification timelines. Secure long-term acrylonitrile offtake agreements before Korean petrochemical suppliers redirect feedstock toward carbon fiber precursor expansion. Backward integration into pyrolysis-based recycled carbon fiber processing defends margin position against glass fiber substitution in interior applications. For New Entrants and Emerging Players: India's Maharashtra corridor offers the most penetrable entry point as BIS protocol development lags behind electric vehicle platform localization. Target natural fiber compounding for interior trim applications where thermal stability requirements remain below carbon fiber thresholds. Pursue joint development contracts with Tata Motors and Mahindra & Mahindra under domestic content compliance timelines. For Investors and Strategic Acquirers: METI's revised JIS standards reshape the acquisition landscape toward suppliers with existing automotive structural certification rather than aerospace conversion candidates. Long-term viability favors integrated fiber-to-composite operations with established OEM simultaneous engineering relationships. Watch for MIIT domestic content threshold announcements as the inflection signal for Chinese supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| JIS-GB Dual Certification Investment | Unlocks cross-border component sourcing for NIO and Toyota platform engineering. |
| Recycled Carbon Fiber Capacity Buildout | Captures ESG-driven procurement mandates from BYD and XPeng sustainability targets. |
| Prepreg Manufacturing Joint Venture | Addresses technician scarcity constraining Toray's automated fiber placement expansion. |
| Thailand Export Hub Positioning | Serves right-hand-drive ASEAN markets through Board of Investment incentive corridors. |
| Thermoplastic Resin Transfer Molding Scale-Up | Enables sub-3-minute cycle times for high-volume exterior panel applications. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of MIIT vehicle production databases, Japanese automotive supplier association technical filings, and customs records for carbon fiber precursor trade flows. Primary interviews spanned OEM platform engineers at BYD and Toyota, tier-1 procurement directors at Bosch and Denso, and resin system technical leads at BASF and Mitsubishi Chemical. Secondary validation drew from JIS standard revision documentation, BIS committee meeting minutes, and Yangtze River Delta industrial cluster investment filings. Bottom-up segment sizing triangulates against top-down vehicle production forecasts.
Forecast inputs span vehicle class segmentation across battery electric and internal combustion platforms, propulsion architecture content-per-vehicle modeling, and regional production cluster capacity utilization rates. Segmentation dimensions include fiber type, manufacturing process, application tier, and end-user procurement structure. CAGRs derive from regression analysis against historical lightweighting material adoption curves, adjusted for regulatory mandate acceleration effects. Industry-specific inputs incorporate MIIT corporate average fuel consumption trajectory assumptions and METI certification timeline compression scenarios.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Chinese state-backed petrochemical conglomerates would shift outcomes. Material shifts in JIS-GB mutual recognition protocols or acrylonitrile feedstock supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Interior Plastic Components Market
Automotive Components
Global Automotive Gearbox Market
Automotive Components
Automotive Regenerative Braking System Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
Asia-Pacific Automotive Upholstery Market
Automotive Components
Germany Automotive Carbon Fiber Composites Market
Automotive Components
Australia Automotive Glass Fiber Composites Market
Automotive Components
Argentina Automotive Electric Actuators Market
Automotive Components
Automotive Silencer Market
Automotive Components
Automobile Accessories Market
Automotive Components
Automotive Resonator Market
Automotive Components
Europe Automotive Pneumatic Actuators Market
Automotive Components
North America Automotive Hydraulic Actuators Market
Automotive Components
Global Automotive Window Regulator Market
Automotive Components
Automotive Pedals Market
Automotive Components
GCC Automotive Lubrication Services Market