
 Europe Train Battery Market | 2026-2036
Europe Train Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Train Battery Market Analytics
Electrification engineering talent scarcity is reorganizing supplier priorities across the European rail battery supply chain. Siemens Mobility leverages its integrated traction and battery platform to dominate German and Austrian procurement cycles. Saft Groupe S.A. anchors the French market through its lithium-ion cell production facility in Bordeaux, supplying Alstom's Coradia Continental platform. HOPPECKE Batterien GmbH & Co. KG competes in the lead-acid retrofit segment for older regional fleets across Central Europe.
Europe train batteries are rechargeable electrochemical storage systems engineered for rolling stock traction and auxiliary power, typically employing lithium iron phosphate or nickel manganese cobalt chemistries with operating temperatures between minus twenty and plus fifty degrees Celsius and cycle lives exceeding four thousand charge events at eighty percent depth of discharge. Lithium-ion chemistry leads value creation given its energy density advantage in high-speed and urban transit applications where weight reduction directly improves acceleration and braking energy recovery. Lead-acid retains position in freight train starter and backup systems where capital constraints outweigh efficiency premiums. Passenger trains represent the fastest-growing application dimension as operators replace diesel multiple units on branch lines lacking overhead catenary infrastructure.
The EU Green Deal's Transport Decarbonisation Package, the European Railway Agency's TSIs for rolling stock interoperability, and Germany's Federal Railway Authority homologation requirements collectively mandate zero-emission propulsion for new procurements by specified deadlines. ECHA's REACH restrictions on nickel and cobalt processing are reshaping cell chemistry roadmaps toward sodium-ion and LFP alternatives. Stakeholders must monitor how France's SNCF and Italy's Trenitalia translate national hydrogen strategies into battery-electric versus fuel-cell procurement splits for regional corridors.
Market Dynamics
Deutsche Bahn's procurement templates are forcing a supplier consolidation wave across Central European rail networks, as national operators abandon fragmented diesel retrofit suppliers in favor of integrated traction-battery platforms that satisfy EU Green Deal mandates.
Growth Catalysts
- EU Green Deal Transport Decarbonisation Package:Mandates zero-emission propulsion for new rolling stock procurements, compelling operators to accelerate battery-electric multiple unit adoption on non-electrified branch lines.
- Lithium iron phosphate chemistry:Offers superior thermal stability and cycle life exceeding four thousand charge events, making it the default choice for high-frequency regional passenger services.
- German Federal Railway Authority homologation:Creates certification pathways that neighboring Austrian and Swiss networks adopt without redundant testing, compressing time-to-market for validated battery systems.
Market Restraints
- Cobalt and nickel supply concentration:ECHA REACH restrictions on raw material processing force cell manufacturers toward sodium-ion alternatives with lower energy density, trading performance for compliance.
- Lead-acid installed base:Freight operators with capital constraints resist full fleet electrification, extending replacement cycles and fragmenting demand between chemistry types.
- Catenary infrastructure lock-in:Existing electrified corridors absorb maintenance budgets, starving battery-electric pilot programs of operational funding in Southern European networks.
Strategic Opportunities
- Polish and Romanian regional networks:Underpenetrated markets with extensive non-electrified track mileage offer first-mover advantages for battery-electric multiple unit suppliers establishing local service partnerships.
- Braking energy recovery systems:Integration with smart grid infrastructure enables revenue-generating frequency regulation services, transforming trains from cost centers to grid assets.
- French hydrogen-battery hybrid corridors:SNCF's national strategy creates demand for dual-mode platforms that switch between fuel-cell and battery propulsion, requiring specialized high-voltage storage architectures.
Industry Challenges
- Electrification engineering talent scarcity:Traction power specialists command premium compensation, forcing suppliers to poach from automotive battery divisions and delay project timelines.
- European Railway Agency TSI certification:Interoperability testing for cross-border rolling stock adds eighteen to twenty-four months to product development cycles, compressing contract award windows.
- Legacy fleet integration complexity:Retrofitting thirty-year-old diesel multiple units with battery-electric powertrains requires custom mechanical adapters that erode supplier margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Train Battery Market |
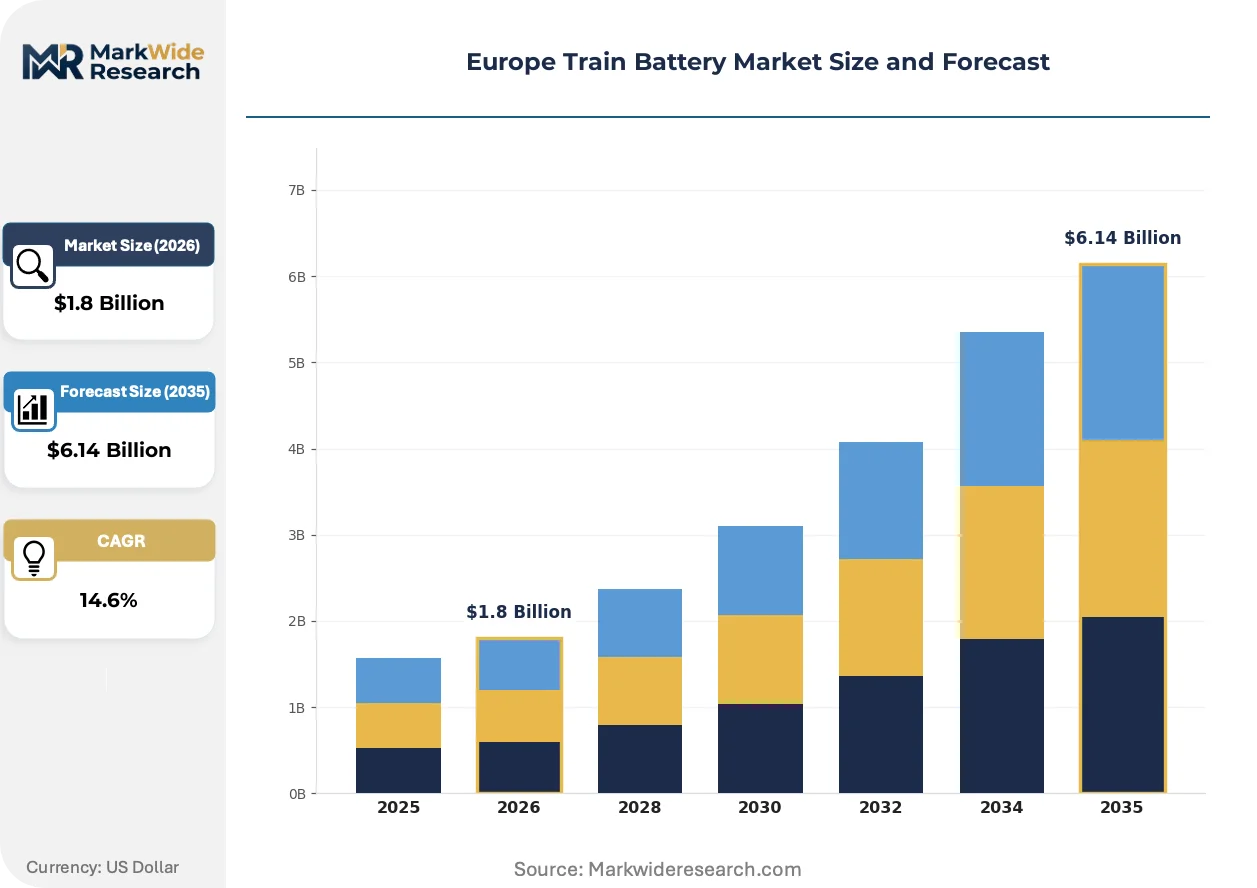
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Sodium-ion Application: Passenger Trains, Freight Trains, High-speed Trains, Urban Transit Power Capacity: 100 kWh, 200 kWh, 300 kWh, 500 kWh End User: Rail Operators, Government Agencies, Private Companies, Municipalities |
| Companies Covered | Siemens Mobility, Alstom, Saft Groupe S.A., HOPPECKE Batterien GmbH & Co. KG, GS Yuasa International Ltd., Hitachi Rail Limited, EnerSys, Power & Industrial Battery Systems GmbH, Leclanché SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Train Battery Market Evolving Landscape
Battery management system intelligence is becoming the primary competitive differentiator as operators demand predictive maintenance capabilities that minimize service disruptions on high-availability regional corridors.
Sodium-ion cell chemistry is displacing nickel manganese cobalt formulations in temperature-sensitive applications, with Scandinavian operators piloting cold-weather platforms that maintain discharge performance below minus twenty degrees Celsius without thermal management overhead, compressing total cost of ownership calculations for Arctic route electrification.
ECHA's evolving REACH restrictions on critical mineral processing are forcing manufacturers to redesign supply chains around LFP and sodium-ion alternatives, with the French market most affected due to its reliance on Bordeaux-based cobalt-dependent cell production, prompting Alstom to qualify alternative chemistries for its Coradia Continental platform.
Outcome-based availability contracts are replacing traditional equipment purchase models, with German regional transport authorities now specifying guaranteed service kilometers rather than battery specifications, shifting technical risk to suppliers and rewarding predictive maintenance capabilities over raw energy density metrics.
Europe Train Battery Market Segmentation
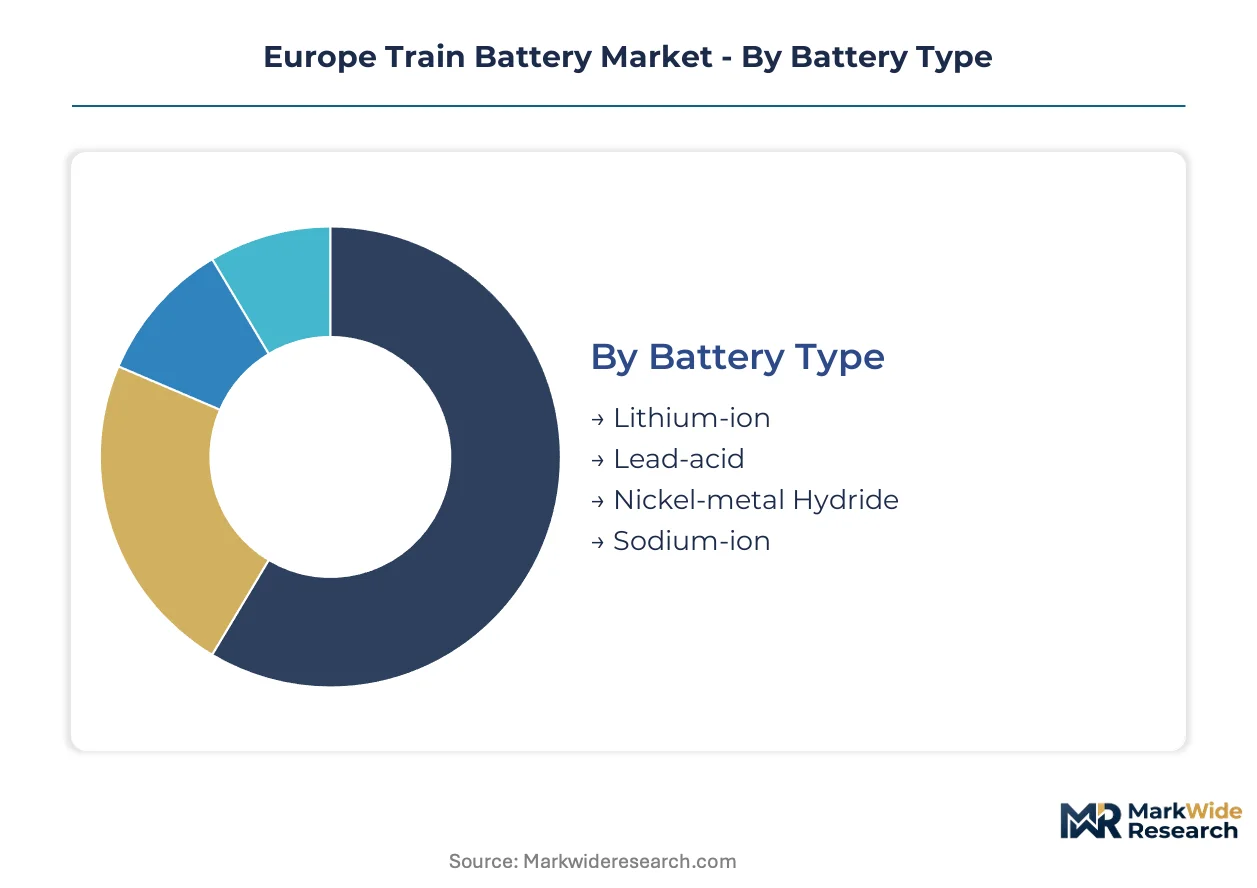
Europe's train battery market fragments across chemistry types, power ratings, and procurement channels that each carry distinct margin structures and certification burdens. Suppliers must align R&D roadmaps with how Deutsche Bahn, SNCF, and Trenitalia weight energy density against thermal stability in their tender specifications.
Battery Type:
Lithium iron phosphate and sodium-ion variants are capturing margin pools as ECHA REACH restrictions erode nickel-cobalt economics, while lead-acid defends residual value in cost-constrained freight retrofits.
- Lithium-ion:Dominant chemistry employing lithium iron phosphate and nickel manganese cobalt formulations with energy densities between 150-250 Wh/kg. German and Austrian regional networks concentrate procurement here for battery-electric multiple units on non-electrified branch lines, driven by EU Green Deal zero-emission mandates and four-thousand-plus cycle life requirements.
- Lead-acid:Mature technology with lower capital cost but energy density below 50 Wh/kg and cycle life under one thousand events. Freight operators in Poland and Romania retain this chemistry for starter and backup systems where electrification budgets remain constrained by diesel fuel price volatility.
- Nickel-metal Hydride:Intermediate chemistry with moderate energy density and reduced cobalt dependency compared to NMC variants. Japanese-derived traction platforms in limited European deployment utilize this technology where thermal management infrastructure is pre-installed.
- Sodium-ion:Emerging chemistry eliminating critical mineral supply risks with discharge stability below minus twenty degrees Celsius. Scandinavian operators are piloting this technology for Arctic route electrification where thermal management overhead compression drives total cost of ownership calculations.
Lead-acid holds installed capacity in Central European freight depots. Sodium-ion is rotating up the share rankings as French and Nordic networks qualify alternatives to Bordeaux-dependent cobalt supply chains.
Application:
Passenger rail electrification absorbs the majority of engineering talent and certification investment, while freight applications remain fragmented by capital availability across national rail networks.
- Passenger Trains:Battery-electric multiple units replacing diesel fleets on regional branch lines lacking catenary infrastructure. Germany's Federal Railway Authority homologation creates certification pathways that Austrian and Swiss networks adopt without redundant testing, compressing supplier time-to-market.
- Freight Trains:Limited electrification due to capital constraints and route unpredictability. Polish and Romanian freight operators prioritize lead-acid starter systems over full battery-electric conversion, extending diesel dependency on non-electrified corridors.
- High-speed Trains:Auxiliary power and emergency traction applications where weight reduction improves acceleration profiles. Trenitalia and SNCF specifications drive demand for high-voltage architectures with rapid charge acceptance.
- Urban Transit:Metro and tram systems with frequent stop-start cycles maximizing regenerative braking energy recovery. Battery management system intelligence becomes critical differentiator as operators specify predictive maintenance capabilities.
Passenger trains command premium pricing for integrated traction-battery platforms. Urban transit is climbing fastest as municipal operators accelerate zero-emission fleet conversions ahead of national rail timelines.
Power Capacity:
Higher capacity tiers concentrate value creation where range anxiety and route flexibility determine procurement outcomes, while entry-level ratings serve retrofit applications with mechanical integration constraints.
- 500 kWh:Extended-range configurations enabling battery-electric multiple units to traverse hundred-kilometer non-electrified corridors without infrastructure investment. Deutsche Bahn's pilot programs establish procurement templates for cross-border regional services.
- 300 kWh:Balanced specification for medium-density regional routes with intermittent charging opportunities. French Coradia Continental platforms utilize this capacity tier for hybrid hydrogen-battery corridors where mode switching demands flexible storage architecture.
- 200 kWh:Compact systems for urban transit and shuttle services with high-frequency charging infrastructure. Municipal operators in mid-sized German cities specify this rating for tram and light-rail electrification.
- 100 kWh:Entry-level capacity for auxiliary power and emergency traction in legacy fleet retrofits. Lead-acid replacement cycles in Central European freight depots concentrate demand here despite limited electrification scope.
300 kWh ratings anchor current procurement volumes. 500 kWh configurations are gaining share fastest as network planners design battery-electric services around infrastructure-minimal deployment models.
End User:
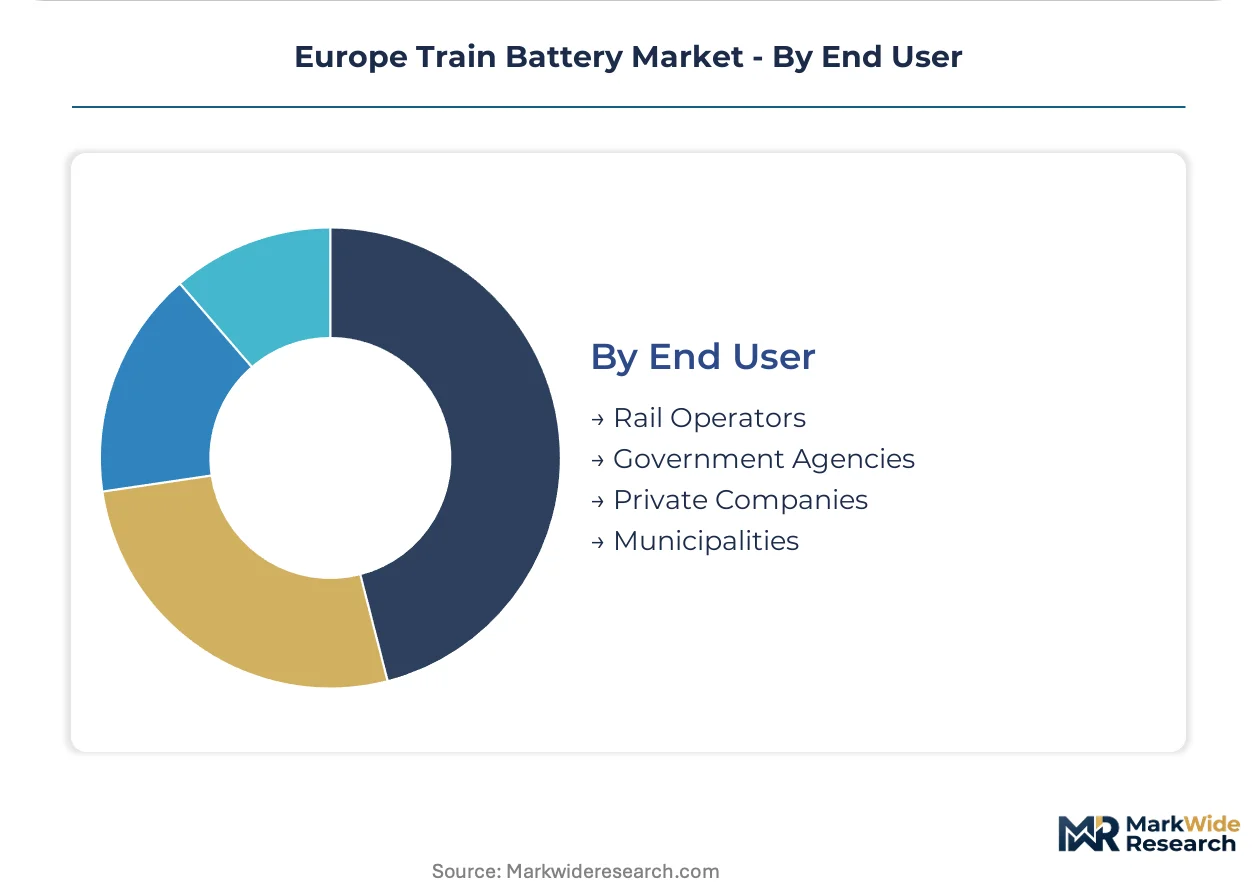
Rail operators and government agencies control procurement through outcome-based availability contracts that shift technical risk to suppliers, while private companies and municipalities operate on shorter capital cycles with distinct certification tolerances.
- Rail Operators:Deutsche Bahn, SNCF, Trenitalia, and ÖBB dominate volume through framework agreements specifying guaranteed service kilometers rather than battery specifications. Predictive maintenance capabilities determine supplier selection over raw energy density metrics.
- Government Agencies:Federal and state transport authorities in Germany, France, and Italy allocate Green Deal implementation budgets toward zero-emission fleet procurement. Tender designs favor integrated traction-battery platforms that satisfy interoperability requirements.
- Private Companies:Industrial rail operators and mining logistics firms with captive networks. Capital constraints and route specificity limit battery-electric adoption to pilot demonstrations with short payback horizons.
- Municipalities:Urban transit authorities in mid-sized cities accelerating tram and metro electrification. Shorter procurement cycles and localized service partnerships create entry points for specialized suppliers.
Rail operators hold installed capacity through multi-year framework agreements. Municipalities are climbing fastest as urban decarbonization timelines compress procurement windows for specialized urban transit configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German procurement templates command premium pricing for integrated traction-battery platforms, while Polish and Romanian freight operators defer electrification investments due to capital constraints and diesel price volatility.
Germany
Deutsche Bahn's battery-electric multiple unit pilots on non-electrified branch lines create procurement templates that Austrian and Swiss networks adopt without redundant homologation testing. The Federal Railway Authority certification pathways compress supplier time-to-market across Central Europe. Siemens Mobility anchors production in Munich and Nuremberg, supplying integrated platforms that satisfy EU Green Deal zero-emission mandates.
France
SNCF's national hydrogen-battery hybrid strategy generates demand for dual-mode platforms requiring specialized high-voltage storage architectures on regional corridors. ECHA REACH restrictions on cobalt processing force Alstom to qualify alternative chemistries for its Coradia Continental platform. Saft Groupe S.A. maintains cell production in Bordeaux despite supply chain redesign pressures toward LFP and sodium-ion alternatives.
Austria
ÖBB leverages German Federal Railway Authority homologation reciprocity to accelerate battery-electric fleet procurement without duplicative certification cycles. The Alpine network's tunnel-intensive routes favor thermal-stable lithium iron phosphate chemistries with extended cycle life. Graz and Linz serve as maintenance hubs for cross-border regional services connecting Bavaria and Northern Italy.
Poland
PKP Cargo and regional operators prioritize lead-acid starter systems over full battery-electric conversion due to capital constraints and route unpredictability on non-electrified corridors. EU cohesion fund allocations for transport decarbonization remain absorbed by catenary infrastructure maintenance. The Silesian industrial cluster around Katowice concentrates pilot demonstrations with short payback horizons for captive mining logistics networks.
Scandinavia
Swedish and Norwegian operators pilot sodium-ion platforms for Arctic route electrification where discharge stability below minus twenty degrees Celsius eliminates thermal management overhead. SJ and Vy specify cold-weather performance metrics that reshape supplier chemistry roadmaps away from nickel manganese cobalt formulations. Stockholm and Oslo municipal transit authorities accelerate urban zero-emission timelines ahead of national rail procurement schedules.
Europe Train Battery Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European rail battery supply chain. Integrated traction-battery platforms dominate German and Austrian procurement cycles, while chemistry specialists and legacy lead-acid suppliers fragment demand in cost-constrained Central European markets. Three archetypes define competitive positioning: diversified industrial conglomerates with rail divisions, dedicated battery manufacturers with rail-specific certifications, and regional specialists serving retrofit applications. Consolidation pressures favor integrated platform providers, while ECHA regulatory shifts reward chemistry-agnostic suppliers with flexible cell sourcing.
Among Germany-based industrial conglomerates, Siemens Mobility exemplifies the integrated platform archetype that captures premium procurement cycles through combined traction and battery system offerings. Saft Groupe S.A. and HOPPECKE Batterien GmbH & Co. KG occupy distinct positioning tiers—Saft anchoring French lithium-ion cell production despite cobalt dependency pressures, HOPPECKE defending residual value in Central European lead-acid retrofit segments where capital constraints prolong replacement cycles. These three entities represent the structural segmentation between technology-forward electrification and cost-optimized legacy fleet maintenance.
| Leading Market Players |
|---|
| Siemens Mobility |
| Alstom |
| Saft Groupe S.A. |
| HOPPECKE Batterien GmbH & Co. KG |
| GS Yuasa International Ltd. |
| Hitachi Rail Limited |
| EnerSys |
| Power & Industrial Battery Systems GmbH |
| Leclanché SA |
| Others |
Value Network & Pricing Analysis
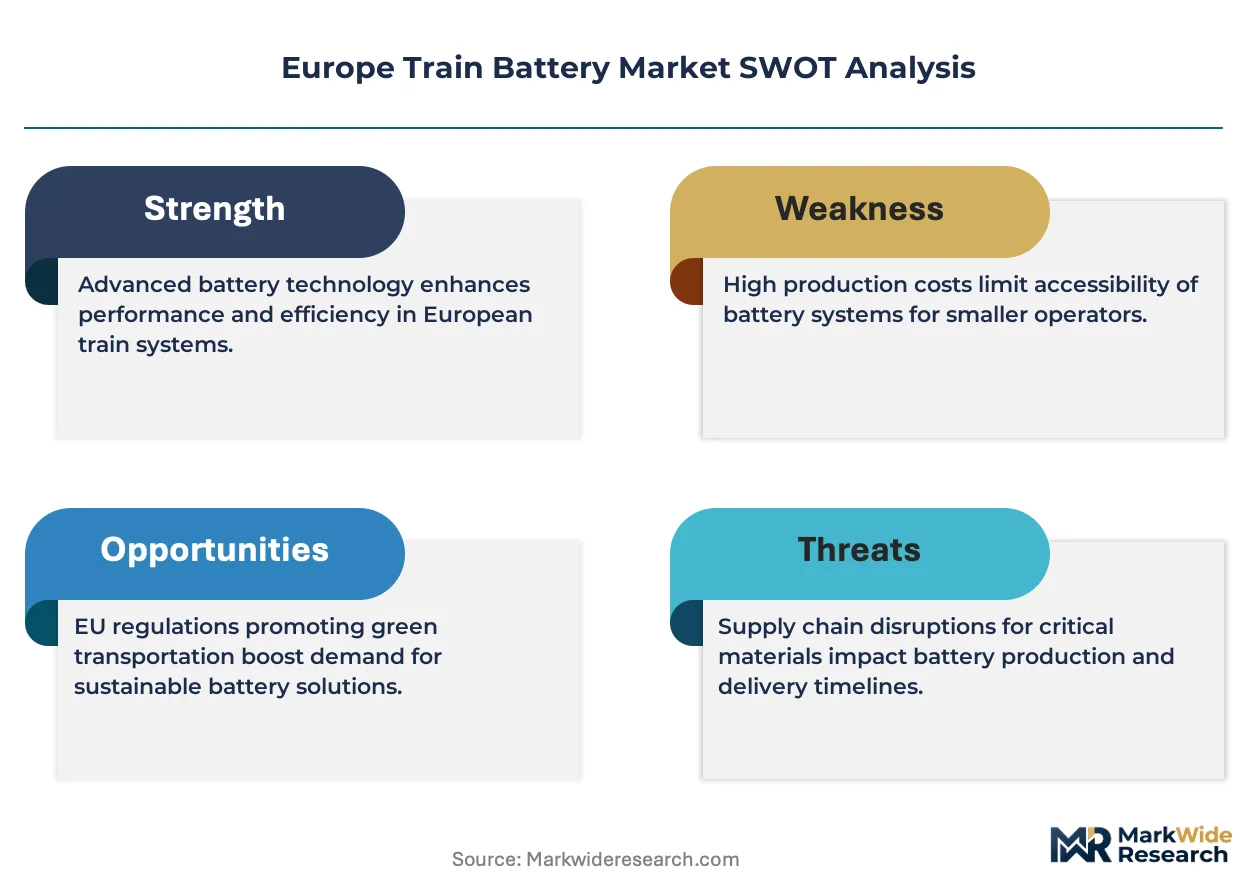
Ninety-day cathode precursor lead times from South Korean refiners concentrate pricing power among integrated cell manufacturers, while German rail operators exploit outcome-based contracting to compress supplier margins on non-specification components. This inventory-to-pricing nexus forces chemistry specialists toward captive mining partnerships or LFP pivot strategies to defend margin structures.
Pricing Analysis
German-Austrian procurement corridors command fifteen to twenty percent premiums over Polish-Romanian freight retrofit markets, reflecting homologation reciprocity value and predictive maintenance bundling. Three-tier pricing structure across integrated traction-battery platforms, standalone energy storage systems, and lead-acid replacement cells stratifies the market. Cost compression in the lead-acid tier intensifies because ECHA REACH compliance redirects R&D budgets toward sodium-ion qualification. Municipal transit authorities exhibit highest price sensitivity due to compressed capital cycles, while Deutsche Bahn framework agreements prioritize availability guarantees over unit economics.
Supply Chain Analysis
Eighteen-month qualification cycles for railway-specific cell formats tether inventory planning to long-term offtake commitments with limited spot market flexibility. Cathode active material production concentrates in South Korea, Japan, and China, with European coating and pack assembly anchoring final integration in Germany and France. The supply chain draws from lithium carbonate, nickel sulfate, and cobalt hydroxide feedstocks, with ECHA processing restrictions elevating LFP precursor demand. Single-source vulnerability around high-purity electrolyte formulations creates disruption risk for high-voltage architectures. Distribution runs through OEM direct contracts for integrated platforms and specialized distributors for retrofit lead-acid segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting toward interoperability-driven winner-take-most dynamics, as German Federal Railway Authority certification reciprocity creates ecosystem lock-in across Central European networks.
For Market Incumbents: Consolidate traction-battery integration capabilities through backward integration into cell qualification laboratories, eliminating third-party certification delays that erode framework agreement margins. Acquire sodium-ion pilot production capacity ahead of ECHA cobalt restriction enforcement. Defend against chemistry-agnostic entrants by embedding predictive maintenance algorithms into battery management system firmware, creating switching costs for operators specifying outcome-based availability contracts. For New Entrants and Emerging Players: Anchor in Polish and Romanian regional network electrification, where EU cohesion fund absorption by catenary maintenance starves battery-electric programs of incumbent attention. Target 200 kWh urban transit configurations for mid-sized German municipalities accelerating zero-emission timelines ahead of national rail procurement schedules. Pursue local service partnership models that compress response times below integrated platform providers' centralized maintenance structures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sodium-ion qualification and Arctic-route thermal management R&D, favoring scaled chemistry specialists over niche retrofit suppliers. Five-to-ten year viability hinges on positioning for EU Green Deal implementation budget allocation shifts from hydrogen corridors toward battery-electric branch line deployment. Acquisition target archetype: chemistry-agnostic cell assemblers with existing EBA/ERA certification pathways and underutilized European production capacity. Signal to monitor: SNCF hydrogen-battery hybrid procurement splits as indicator of dual-mode platform demand elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Traction-Battery Platform Standardization | Deutsche Bahn procurement templates compress supplier qualification cycles across Austrian and Swiss networks. |
| Sodium-Ion Chemistry Qualification | ECHA REACH restrictions on cobalt processing force redesign of French-dependent Bordeaux supply chains. |
| Outcome-Based Availability Contracting | German regional transport authorities now specify guaranteed service kilometers, shifting technical risk to suppliers. |
| Braking Energy Recovery Grid Integration | Smart grid frequency regulation services transform trains from cost centers to revenue-generating grid assets. |
| Local Service Partnership Establishment | Polish and Romanian regional networks offer first-mover advantages for specialized maintenance coverage. |
Research Methodology
A spread of perspectives from Deutsche Bahn procurement officers, Alstom platform engineers, Saft cell manufacturing directors, ECHA regulatory affairs specialists, and Polish regional operator fleet managers converged on the working assumptions driving chemistry roadmap shifts. Primary field engagement combined structured interviews with secondary validation through EU Transport Decarbonisation Package filings, ERA TSI certification databases, national railway authority procurement registers, and ECHA REACH restriction evolution tracking. Bottom-up cell demand modeling triangulated against top-down Green Deal implementation budget allocation analysis.
Segmentation dimensions modeled span battery chemistry type, power capacity tier, application category, and end-user procurement channel across the projection horizon. CAGRs derived from volume-weighted averaging of operator fleet replacement schedules and supplier production capacity expansion announcements. Industry-specific forecast inputs incorporated German Federal Railway Authority homologation reciprocity adoption curves and Scandinavian cold-weather platform pilot results.
Material uncertainties — ECHA cobalt restriction enforcement timing, EU cohesion fund reallocation toward battery-electric corridors, sodium-ion cycle life validation in high-frequency regional service — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding interoperability certification pathway harmonization and operator capital cycle recovery post-pandemic. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Battery Recycling
Automobile Storage Battery Market
Transportation Battery Recycling
Transportation Battery Market
Transportation Battery Recycling
Asia-Pacific Transportation Battery Recycling Market
Transportation Battery Recycling
South Korea Transportation Battery Recycling Market
Transportation Battery Recycling
Transportation Battery Recycling Market
Transportation Battery Recycling
China Transportation Battery Recycling Market
Transportation Battery Recycling
Automotive Battery Recycling Market
Transportation Battery Recycling
Automotive Energy Recovery System Market
Transportation Battery Recycling
EV Battery Recycling Services Market
Transportation Battery Recycling
Two-Wheeler Battery Market
Transportation Battery Recycling
Europe Automotive Start-Stop Battery Market
Transportation Battery Recycling
ASEAN Electric Vehicle Battery Anode Market