
 Automotive Polycarbonate Glazing Market | 2026-2036
Automotive Polycarbonate Glazing Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Polycarbonate Glazing Market Intelligence
The push for lighter, more fuel-efficient vehicles under frameworks like the EU Green Deal is pivoting automotive design towards polycarbonate glazing. SABIC leverages its extensive polymer science portfolio to offer specialized grades for complex window shapes. Covestro AG competes on the basis of advanced coating technologies that improve scratch and UV resistance. Teijin Limited specializes in high-performance materials for panoramic sunroof applications.
Automotive polycarbonate glazing refers to the use of thermoplastic polymers, specifically polycarbonate, as a substitute for traditional silicate glass in vehicle windows and roofs. This material offers up to 50% weight savings and 250 times the impact resistance of glass, enhancing both fuel efficiency and occupant safety. While passenger vehicles remain the largest application, adoption in electric vehicles is growing most rapidly. Sunroofs and moonroofs represent a high-value product segment, often utilizing advanced injection molding techniques for complex geometries.
Global vehicle safety standards, enforced by bodies like the US NHTSA and through UNECE regulations, mandate specific optical clarity and abrasion resistance for glazing. Concurrently, environmental regulations from the EPA and China's MEE indirectly promote polycarbonate by incentivizing vehicle weight reduction to meet emissions targets. Material suppliers must therefore balance the engineering challenge of durability with the commercial imperative of lightweighting for future vehicle platforms.
Market Dynamics
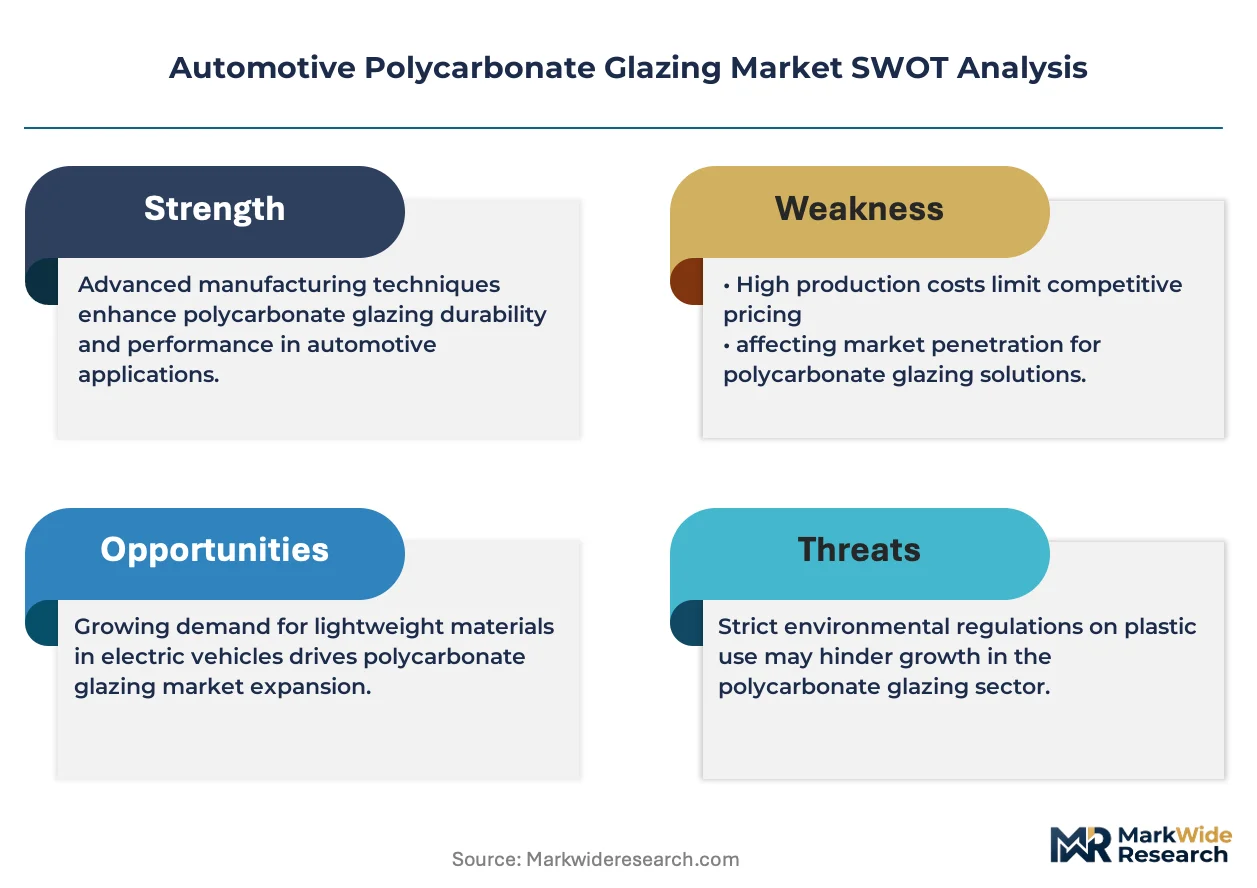
The imperative for vehicle lightweighting, driven by stringent CO2 emissions regulations and the need to extend electric vehicle range, is the central force shaping the automotive polycarbonate glazing market. This pressure compels automakers to seek alternatives to traditional glass, accelerating material substitution.
Growth Catalysts
- EV Battery Range Extension:The adoption of electric vehicles is a primary catalyst, as weight reduction directly correlates to longer battery range. Polycarbonate's ability to save up to 50% in weight compared to glass makes it critical for optimizing EV performance and addressing consumer range anxiety.
- EU Emission Standards:Regulatory frameworks, particularly the European Union's stringent CO2 emission targets for new vehicles, incentivize automakers to adopt lightweighting technologies. Polycarbonate glazing offers a direct path to reducing overall vehicle mass, helping manufacturers meet fleet-wide compliance goals and avoid penalties.
- Design Freedom for Aerodynamics:The material allows for complex, three-dimensional shapes and curves that are difficult or impossible to achieve with glass. This design flexibility enables more aerodynamic vehicle profiles, which further improves fuel and energy efficiency for both internal combustion and electric vehicles.
Market Restraints
- Higher Material Cost:The upfront cost of optical-grade polycarbonate resin and the associated specialized coatings is significantly higher than that of automotive-grade silicate glass. This cost differential remains a primary barrier to mass adoption, especially in economy and mid-range vehicle segments.
- Durability and Abrasion Resistance:Without advanced hard-coating technologies, polycarbonate is susceptible to scratching and degradation from UV radiation. Meeting the rigorous abrasion resistance and optical clarity standards mandated by bodies like the UNECE requires sophisticated, costly coating processes.
- Complex Manufacturing Processes:Producing large, optically clear polycarbonate parts like windshields and panoramic roofs requires substantial capital investment in large-tonnage injection molding machines, cleanroom environments, and precision coating lines. This manufacturing complexity limits the number of qualified suppliers.
Strategic Opportunities
- Smart Glazing Integration:There is a significant opportunity in integrating polycarbonate with smart technologies like Suspended Particle Devices (SPD) or electrochromics. This enables dynamic tinting for sunroofs and side windows, enhancing passenger comfort and reducing HVAC energy consumption.
- Advanced Driver-Assistance Systems (ADAS):Polycarbonate's formability allows for the seamless integration of sensors, cameras, and LiDAR units directly into glazing components. This supports the development of more sophisticated and aesthetically integrated ADAS and autonomous driving systems.
- Expansion in Commercial Vehicles:The commercial truck and bus segment is an underpenetrated market. Lightweighting in these heavy vehicles offers substantial fuel savings over their operational lifetime, presenting a strong value proposition for fleet operators looking to reduce total cost of ownership.
Industry Challenges
- Recycling and End-of-Life Management:Establishing a scalable and cost-effective recycling infrastructure for coated polycarbonate automotive parts is a significant challenge. Developing circular economy pathways is crucial for long-term sustainability and meeting future regulations like the EU's End-of-Life Vehicles Directive.
- Thermal Expansion Mismatch:Polycarbonate has a different coefficient of thermal expansion than the metal and composite materials used in a vehicle's body. Managing this mismatch requires specialized adhesives and mounting systems to prevent stress, leaks, and noise over the vehicle's lifespan.
- Long-Term Weatherability Testing:Validating the long-term performance of new coating formulations against decades of real-world exposure to UV radiation, humidity, and temperature extremes is a time-consuming and complex process. Shortening these validation cycles without compromising reliability is a key operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Polycarbonate Glazing Market |
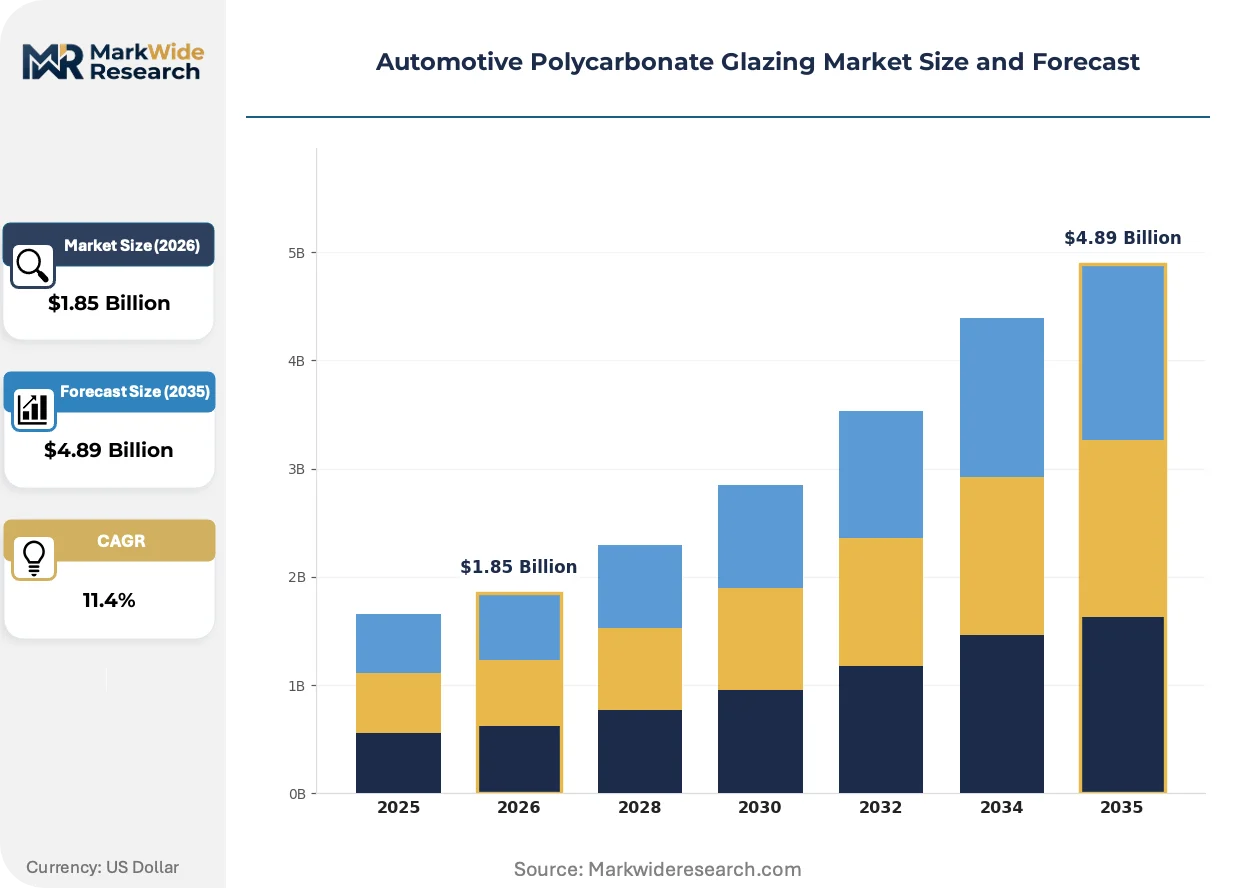
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Windows, Sunroofs, Moonroofs, Rear Glass End User: Original Equipment Manufacturers, Aftermarket Suppliers, Tier-1 Suppliers, Vehicle Assemblers Application: Passenger Vehicles, Light Commercial Vehicles, Heavy Commercial Vehicles, Electric Vehicles Technology: Injection Molding, Thermoforming, Co-Extrusion, Laser Etching |
| Companies Covered | Mitsubishi Chemical Group, Chi Mei Corporation, Covestro AG, LG Chem, Idemitsu Kosan Co., Ltd., SABIC, Trinseo S.A., AGC Inc., Teijin Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Polycarbonate Glazing Market Strategic Shifts & Innovations
Material science advancements are focused on enhancing polycarbonate's inherent properties to meet automotive-grade durability requirements. Innovations in coating chemistry and injection molding are enabling functional integration, turning windows from passive components into active parts of the vehicle's electronic and structural systems.
Multi-shot injection molding allows for the creation of single, integrated glazing modules that incorporate features like lighting, aerodynamic elements, and mounting points. Automakers in the premium EV sector are adopting this to create distinctive design signatures for panoramic roofs and rear quarter windows. This capability is decentralizing component production away from multiple suppliers and consolidating it within the specialized Tier 1 glazing manufacturing process.
The US EPA's stringent Corporate Average Fuel Economy (CAFE) standards directly incentivize vehicle mass reduction as a primary compliance strategy. This regulatory pressure forces automakers to evaluate and adopt lightweight materials across all vehicle systems, including glazing. The light truck and SUV segments, which face the biggest challenges in meeting efficiency targets, are most affected and are seeing accelerated evaluation of polycarbonate for large surfaces like backlights and sunroofs.
Automaker design priorities are shifting to specify glazing based on its ability to enable unique, aerodynamic forms that contribute to brand identity. This alters the procurement dynamic from a simple cost-per-part comparison to a total system value calculation, where glazing is a key enabler of efficiency and design. This trend is most visible in the competitive luxury EV markets of Germany and China, where styling is a critical differentiator.
Automotive Polycarbonate Glazing Market Segmentation
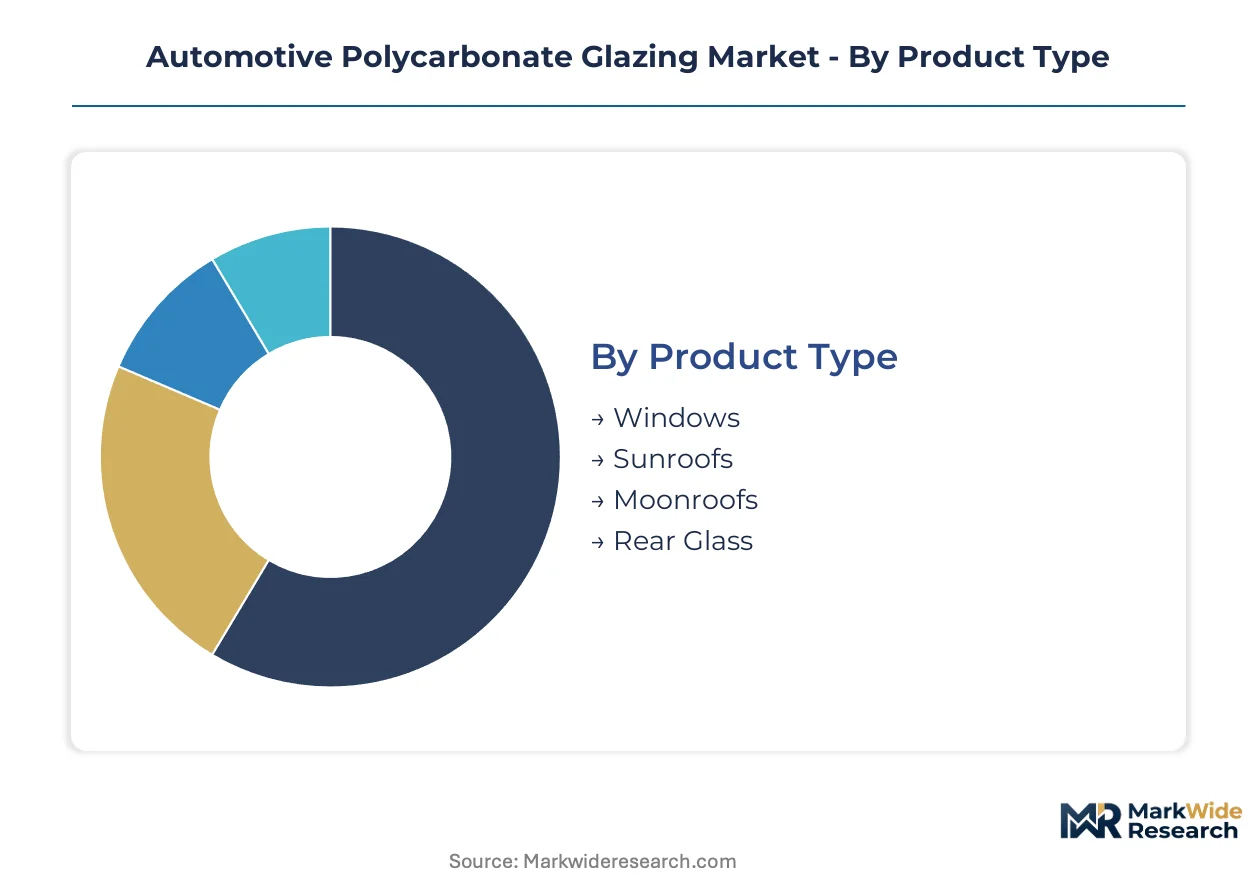
The automotive polycarbonate glazing market is analyzed through distinct segments, reflecting how material advancements and manufacturing processes are driving product evolution and market penetration. Understanding these categorizations is critical for assessing material substitution trends and identifying high-growth niches within the broader automotive industry.
Product Type:
The market's product segmentation highlights the ongoing upgrade and replacement cycle from traditional glass to advanced polycarbonate solutions across various vehicle components.
- Sunroofs:This high-value product segment utilizes advanced injection molding for complex geometries, enabling distinctive design signatures in premium electric vehicles. Demand for panoramic sunroofs is particularly strong in competitive luxury EV markets like Germany and China.
- Moonroofs:Often employing multi-shot injection molding, moonroofs integrate lighting and aerodynamic elements, enhancing both aesthetic appeal and vehicle efficiency. Their adoption in premium EV sectors creates unique design opportunities.
- Windows:Polycarbonate windows, including side and rear applications, offer up to 50% weight savings over silicate glass, directly contributing to fuel efficiency and extended EV battery range. Regulatory pressures from the EU's CO2 emission targets incentivize this material substitution.
- Rear Glass:Lightweight polycarbonate rear glass contributes to overall vehicle mass reduction, helping automakers meet stringent efficiency standards like the US EPA's CAFE regulations.
Volume placements concentrate in Windows; the faster expansion belongs to Sunroofs.
End User:
This segmentation categorizes the market by the type of customer procuring polycarbonate glazing, illustrating the diverse procurement patterns across the automotive supply chain.
- Original Equipment Manufacturers:OEMs directly integrate polycarbonate glazing into new vehicle designs, driven by requirements for lightweighting, design flexibility, and regulatory compliance. Their demand is concentrated in premium and electric vehicle platforms.
- Tier-1 Suppliers:These suppliers manufacture and assemble complete glazing modules, often incorporating advanced coatings and smart technologies, before delivering them to OEMs. They play a crucial role in developing integrated solutions for ADAS and complex roof systems.
- Aftermarket Suppliers:This segment provides replacement polycarbonate glazing products for repairs or upgrades, focusing on durability and ease of installation. Their market is smaller but critical for vehicle longevity.
- Vehicle Assemblers:Assemblers integrate components from various suppliers, including glazing, into the final vehicle. Their focus is on efficient assembly processes and quality control for completed vehicles.
Demand for advanced polycarbonate solutions primarily originates from Original Equipment Manufacturers, while Tier-1 Suppliers are gaining share through integrated module offerings.
Application:
The application segment delineates where polycarbonate glazing is being deployed, revealing the specific vehicle types driving market growth and material innovation.
- Passenger Vehicles:This segment represents the largest application area, with polycarbonate glazing used for weight reduction and design freedom in various car models. Stringent CO2 emission targets in Europe incentivize its use.
- Electric Vehicles:Polycarbonate adoption in EVs is expanding most quickly, as weight reduction is critical for extending battery range and addressing consumer range anxiety. This application leverages the material's lightweight properties to optimize performance.
- Light Commercial Vehicles:Lightweighting in LCVs offers significant fuel savings over their operational lifetime, presenting a strong value proposition for fleet operators. This segment is an underpenetrated market for polycarbonate glazing.
- Heavy Commercial Vehicles:The HCV segment benefits from polycarbonate glazing through enhanced fuel efficiency and improved occupant safety due to the material's high impact resistance.
The largest volume of polycarbonate glazing is found in Passenger Vehicles, whereas Electric Vehicles exhibit the steepest expansion trajectory.
Technology:
This segment categorizes the market by the manufacturing processes used to produce polycarbonate glazing, highlighting the technical expertise required for high-performance components.
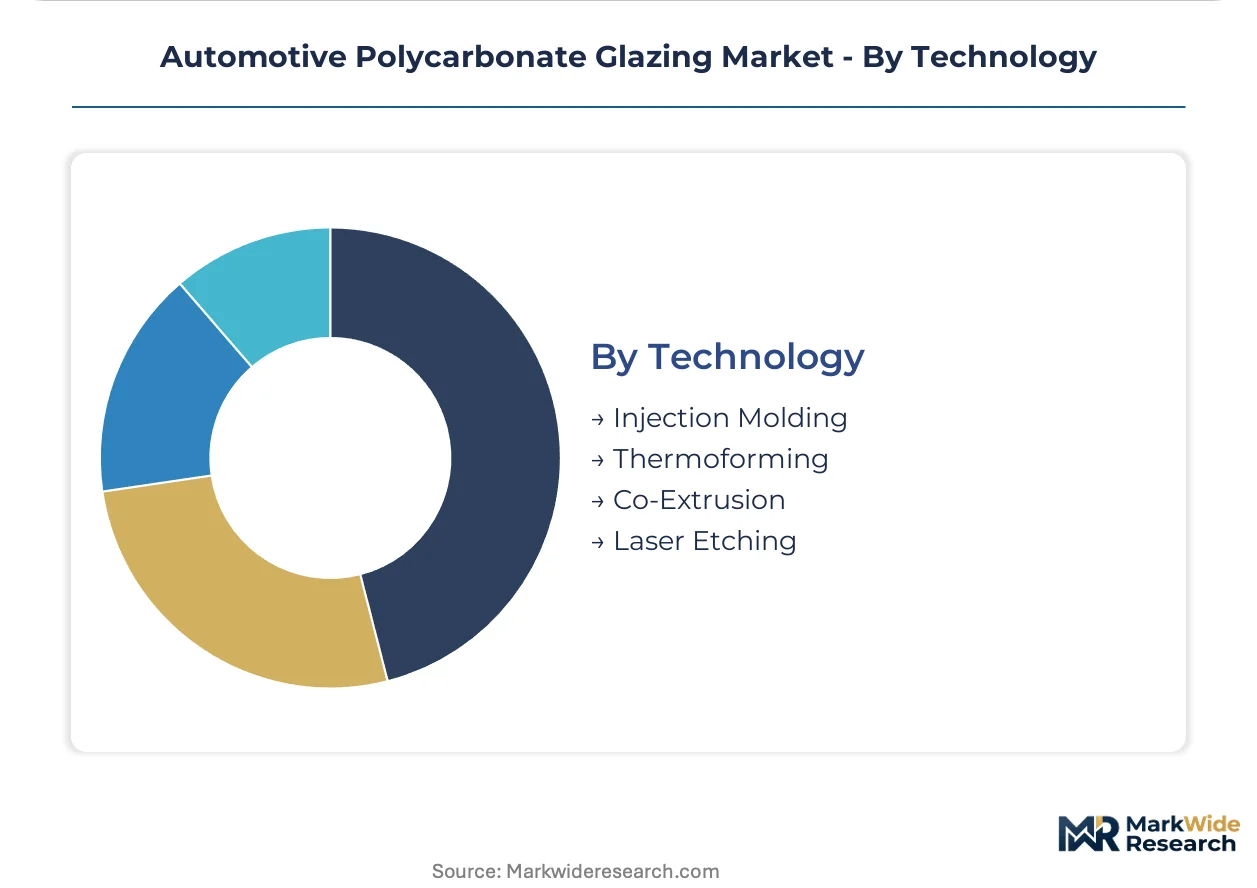
- Injection Molding:This process is vital for creating large, optically clear polycarbonate parts with complex, three-dimensional shapes, enabling aerodynamic vehicle profiles. It requires substantial capital investment and cleanroom environments.
- Thermoforming:Thermoforming offers flexibility for producing various polycarbonate glazing components, particularly for parts with less intricate geometries than those made by injection molding. This method is cost-effective for medium-volume production runs.
- Co-Extrusion:This technology allows for the creation of multi-layered polycarbonate structures, often integrating different material properties like UV protection or scratch resistance into a single sheet. Co-extrusion enhances the material's durability.
- Laser Etching:Laser etching is used for precise marking, patterning, or functional integration within polycarbonate glazing, such as creating anti-glare surfaces or integrating sensor pathways.
Injection Molding represents the most critical manufacturing method for complex polycarbonate glazing, while Thermoforming offers a balanced approach for various component needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive polycarbonate glazing market exhibits a clear divide between manufacturing concentration and widespread consumption. Production capabilities for advanced materials and complex molding often reside in specific industrial clusters. Demand for lightweight vehicles spans major automotive markets worldwide.
China
China's vast automotive manufacturing base drives significant demand for polycarbonate glazing, especially in its rapidly expanding electric vehicle segment. The country's MEE environmental regulations and dual carbon goals incentivize vehicle lightweighting. Key suppliers and advanced molding facilities are concentrating within the Yangtze River Delta region.
Germany
European demand for advanced polycarbonate glazing is heavily influenced by Germany's premium automotive sector and its focus on innovative design. The EU Green Deal and strict CO2 emission targets compel German automakers to adopt lightweight materials. Research and development for specialized coatings thrive in clusters like Bavaria and Baden-Württemberg.
United States
The United States market sees polycarbonate glazing adoption driven by the need for weight reduction in its large light truck and SUV segments. The US EPA's stringent CAFE standards incentivize automakers to reduce vehicle mass for compliance. Automotive suppliers in Michigan are evaluating polycarbonate for large surfaces like backlights and panoramic roofs.
Japan
Japanese automakers are pursuing polycarbonate glazing for its high-performance properties, enhancing both vehicle safety and efficiency in compact EV designs. METI's industrial policies support the development of advanced materials, while JIS standards ensure component quality. Material science companies and Tier-1 suppliers in the Kanto region are innovating specialized grades.
South Korea
South Korea's rapid expansion in electric vehicle production fuels strong demand for lightweight polycarbonate glazing, particularly for aesthetic integration. Government incentives for EV manufacturing and national quality certifications promote the adoption of innovative materials. Leading automotive and chemical companies in the Seoul Capital Area are developing integrated glazing modules.
Automotive Polycarbonate Glazing Market Key Industry Players
The competitive structure tilts toward specialized material science companies providing advanced polycarbonate resins and sophisticated coating solutions. This market features a mix of large chemical conglomerates and focused polymer innovators. Companies are engaging in strategic partnerships with automotive Tier-1 suppliers to co-develop integrated glazing modules. Key competitive moves include continuous investment in R&D for enhanced durability and expanding production capacity for complex injection molded parts.
Within the specialized material supplier archetype, SABIC and Covestro AG exemplify companies leveraging extensive polymer science portfolios and advanced coating technologies. SABIC, a global chemical leader, represents a broad material solutions provider for complex automotive designs. Germany-based Covestro AG anchors its position through innovation in advanced coating technologies that enhance scratch and UV resistance for glazing applications. Teijin Limited, a Japan-based high-performance materials company, sits within the segment focused on specialized applications like panoramic sunroofs. These entities are pivotal in developing the next generation of automotive-grade polycarbonate solutions.
| Leading Market Players |
|---|
| Mitsubishi Chemical Group |
| Chi Mei Corporation |
| Covestro AG |
| LG Chem |
| Idemitsu Kosan Co., Ltd. |
| SABIC |
| Trinseo S.A. |
| AGC Inc. |
| Teijin Limited |
| Others |
Cost & Logistics Intelligence
Sovereign-backed chemical producers and large multinational conglomerates dictate the supply and pricing dynamics for automotive polycarbonate glazing. Their substantial capital investments in R&D and specialized manufacturing processes shape market access and cost structures.
Pricing Analysis
Cost-down pressure on material suppliers accelerates as automakers balance lightweighting benefits against higher polycarbonate material costs. Pricing primarily operates on a contract-based long-term offtake model, often incorporating value-based elements for specialized solutions. Price differentiation stems from advanced coating technologies and the complexity of injection molded geometries. Economy and mid-range vehicle segments exhibit the highest price sensitivity, whereas premium electric vehicle manufacturers prioritize performance over upfront cost.
Supply Chain Analysis
Regional distribution centers support a hub-and-spoke model for specialized polycarbonate components, delivering directly to automotive assembly plants. Geographic supply concentration for advanced resins and coatings centers in China, Germany, and Japan. The supply chain relies on high-purity polycarbonate resin and specialized coating chemicals. A significant structural risk involves capacity constraints for specialized production, given the capital-intensive nature of large-tonnage injection molding and cleanroom environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is poised for consolidation, as stringent global safety and quality standards, coupled with high capital investment requirements, pressure smaller, less specialized players. Only firms with advanced R&D and manufacturing capabilities can meet the evolving demands of automakers.
For Market Incumbents: Deepen strategic partnerships with Tier-1 suppliers for integrated module development. Invest continuously in advanced coating technologies to enhance scratch and UV resistance, addressing durability concerns. This counters material cost sensitivity from mass-market OEMs. Expand R&D in multi-shot injection molding for complex geometries.
For New Entrants and Emerging Players: Specialized coating service providers can target Light Commercial Vehicles, emphasizing lifetime fuel savings through lightweighting. Focus on niche performance vehicle applications where design flexibility and impact resistance command a premium. Offer value-added coating services meeting specific regional safety standards. Develop cost-effective thermoforming solutions for less intricate geometries.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized material science companies in Germany and Japan with proprietary coating or complex injection molding expertise. This market offers strong long-term viability, driven by sustained EV growth and regulatory lightweighting mandates. Target firms with proven R&D pipelines. The signal to watch is scalable recycling infrastructure for automotive polycarbonate parts.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Advanced Coating Production | Enhances durability against abrasion and UV degradation, meeting stringent UNECE regulations for optical clarity. |
| Invest in Multi-Shot Injection Molding | Enables complex geometries and functional integration, supporting distinctive designs in premium EV models. |
| Develop Circular Economy Pathways | Addresses end-of-life management challenges and aligns with future EU End-of-Life Vehicles Directive mandates. |
| Form EV Platform Co-Development Partnerships | Integrates polycarbonate glazing early into new electric vehicle designs, optimizing battery range and aerodynamics. |
| Target Heavy Commercial Vehicle Segment | Unlocks substantial fuel savings for fleet operators, reducing total cost of ownership over vehicle lifespans. |
Research Approach
Multi-period observation of vehicle production volumes and material adoption rates anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary interviews included OEM platform engineers, Tier-1 supplier procurement leads, and R&D directors at material science companies. Secondary validation drew from vehicle production databases, customs/trade data, and SEC 10-K filings. This approach ensured bottom-up market sizing and top-down validation.
Segment-weighting across product type, end user, application, and technology dimensions informed the market projections across the analysis window. The analytical framework modeled polycarbonate content per vehicle, considering various vehicle classes and propulsion architectures. Compound annual growth rates were derived from historical adoption trends and projected electric vehicle penetration rates. Regulatory compliance targets, such as EU CO2 and US CAFE standards, served as key forecast inputs.
Several conditions sit outside the modeled scope, including geopolitical trade tensions and unforeseen breakthroughs in competing glazing materials. Forecasts reflect assumptions regarding raw material price stability and sustained regulatory pressure for lightweighting. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Metal Casting Market
Automotive Components
Japan Automotive Electric Actuators Market
Automotive Components
Global Automotive Bumpers Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Automotive Buffers Market
Automotive Components
Automotive Radiator Grille Market
Automotive Components
China Automotive Actuators Market
Automotive Components
Automotive Connecting Rod Market
Automotive Components
Automotive Carbon Fiber Market
Automotive Components
Automotive Metal Timing Chain Market
Automotive Components
Automotive Chromium Market
Automotive Components
MEMS Automobile Sensors Market
Automotive Components
Saudi Arabia Automotive Actuators Market
Automotive Components
Automotive Brake Pads Market
Automotive Components
North America Heat Shrink Tubing for Automotive Market
Automotive Components
Automotive Lightweighting Market