
 India Two-Wheelers Rental Market | 2026-2036
India Two-Wheelers Rental Market Size, Share, and Industry Trends Forecast 2026-2036
India Two-Wheelers Rental Market Foresight
Electric vehicle certification tiers is collapsing the cost barrier between ICE and battery-operated rental fleets. Vogo dominates the dockless scooter segment through dense station networks across Bengaluru and Hyderabad. Bounce anchors its position with in-house battery-swapping infrastructure that reduces downtime for commuter rentals. Royal Brothers differentiates through premium motorcycle touring packages targeting leisure travelers in Kerala and Goa.
India two-wheelers rental constitutes a mobility service where operators provide short-to-medium term access to motorized two-wheelers against periodic fees, typically incorporating GPS tracking, digital keyless entry, and maintenance-inclusive pricing. The service addresses urban congestion gaps where public transit coverage remains incomplete and car ownership costs prove prohibitive for younger demographics. Daily and monthly rental formats capture the highest transaction volumes as commuters seek predictable transport budgets without asset ownership burdens. Electric bike categories within vehicle type segmentation attract disproportionate operator investment due to lower per-kilometer running costs and favorable state-level EV policies.
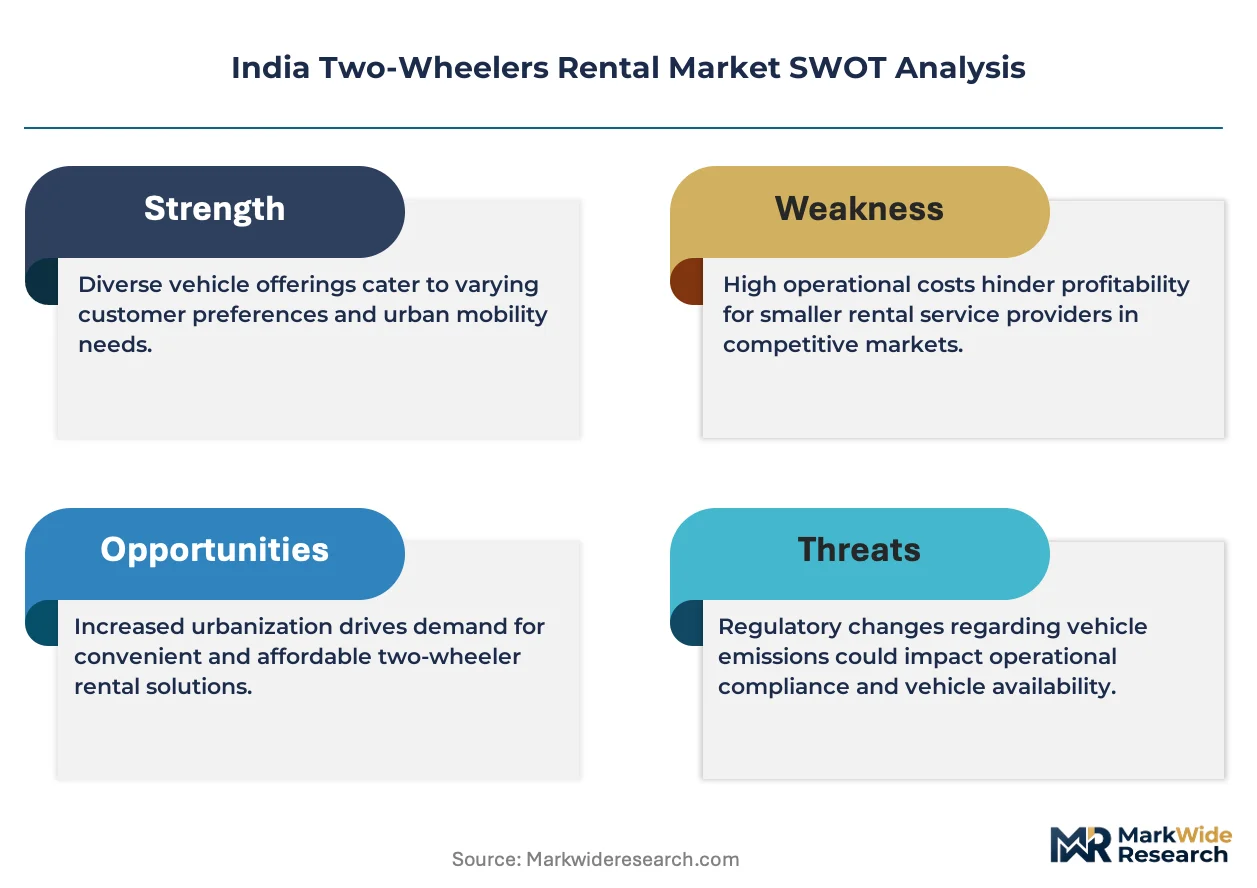
BIS standards for lithium-ion battery safety, CEA guidelines for charging infrastructure deployment, and state-level EV policies framed by Karnataka and Tamil Nadu regulators collectively shape fleet composition and capital expenditure planning. CDSCO oversight on imported battery components adds compliance layers that favor domestic assembly partnerships. Stakeholders must track how state transport department rulings on commercial registration for electric fleets evolve, as these determinations will dictate geographic rollout sequencing and tariff competitiveness against incumbent ICE alternatives.
Market Dynamics
PLI scheme incentives for electric vehicles are compressing the total cost of ownership gap between ICE and battery-powered rental fleets, forcing operators to restructure procurement priorities and station deployment sequencing.
Growth Catalysts
- State-level EV policies:Karnataka and Tamil Nadu subsidies for commercial electric fleet registration reduce upfront capital barriers for rental operators expanding beyond Bengaluru.
- Last-mile delivery demand:E-commerce logistics networks in Mumbai and Hyderabad generate predictable daily utilization rates that stabilize revenue per asset.
- Battery-swapping infrastructure:Standardized interchange stations eliminate charging downtime for commuter-focused operators, improving asset turnover ratios.
Market Restraints
- Lithium-ion import dependence:CDSCO oversight on battery cell imports creates procurement delays and working capital pressure for fleet operators.
- CEA charging guidelines:Grid-connection compliance requirements for high-capacity charging hubs slow station rollout in dense urban zones.
- ICE residual value risk:Accelerating electric adoption erodes secondary market liquidity for petrol scooter fleets, trapping capital in depreciating assets.
Strategic Opportunities
- Kerala leisure touring:Premium motorcycle rental packages targeting tourism corridors along coastal highways command pricing premiums above commuter segments.
- Inter-city electric corridors:Battery-swapping networks along Bengaluru-Chennai highway routes enable one-way rental products currently absent from operator portfolios.
- BIS safety certification:Tiered battery standards create differentiation pathways for operators investing in higher-grade thermal management systems.
Industry Challenges
- Commercial registration bottlenecks:State transport department rulings on electric fleet classification create permit uncertainty that delays station launches.
- Technician training gaps:High-voltage system diagnostics and battery management calibration require specialized labor pools that rental operators must build internally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Two-Wheelers Rental Market |
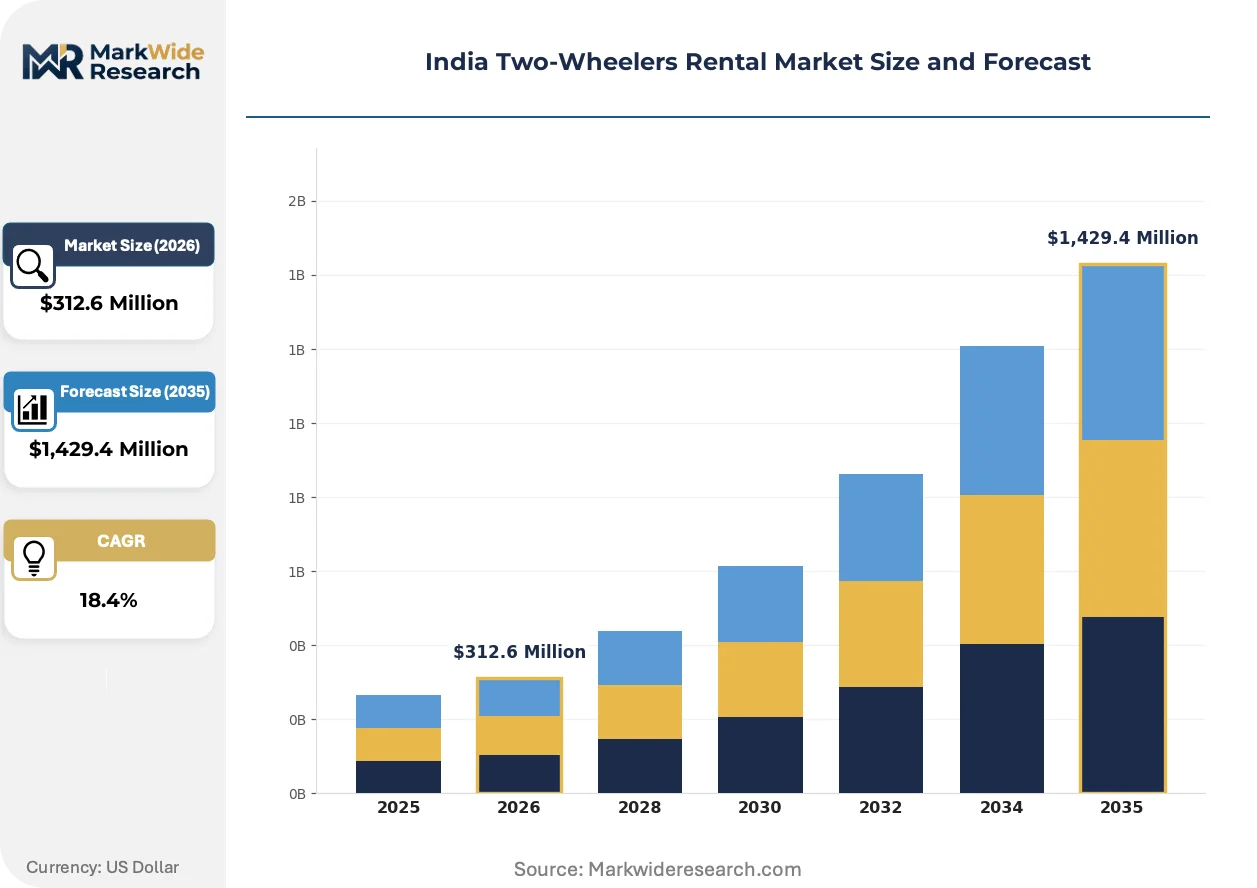
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $1,429.4 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hourly Rental, Daily Rental, Weekly Rental, Monthly Rental Vehicle Type: Scooter, Motorcycle, Moped, Electric Bike End User: Tourists, Commuters, Students, Professionals Payment Method: Cash, Credit Card, Mobile Wallet, Bank Transfer |
| Companies Covered | Wheelstreet, ONN Bikes Rental, Vogo, Fae Bikes, WickedRide Adventure Services, Bounce, Drivezy, Royal Brothers, Yulu, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Two-Wheelers Rental Market Shifts & Advancements
Digital keyless entry systems and integrated GPS telemetry are redefining asset security and utilization tracking, while regulatory pressure on emissions accelerates powertrain substitution across metropolitan rental networks.
IoT-enabled telematics platforms are displacing manual check-in processes and paper-based damage documentation at rental stations. Fleet operators deploy these systems to capture real-time riding behavior data that feeds dynamic pricing algorithms and preventive maintenance scheduling. The displacement of human-staffed pickup counters reduces station operating costs and enables 24-hour unmanned access models in residential neighborhoods.
CEA guidelines for charging infrastructure deployment mandate standardized connector specifications and grid-impact assessments for stations above 50 kW capacity. These requirements favor larger operators with dedicated compliance teams over fragmented station owners. Tier-1 cities including Mumbai and Delhi see accelerated consolidation as smaller players exit rather than absorb certification costs.
Subscription-based monthly rental contracts are replacing daily walk-in transactions among gig economy workers seeking transport budget predictability. Platform aggregators disintermediate direct operator relationships by bundling insurance, maintenance, and battery-swap access into flat-rate packages. This shift concentrates transaction volume in southern Indian metropolitan clusters where two-wheeler dependency already exceeds public transit coverage.
India Two-Wheelers Rental Market Segmentation
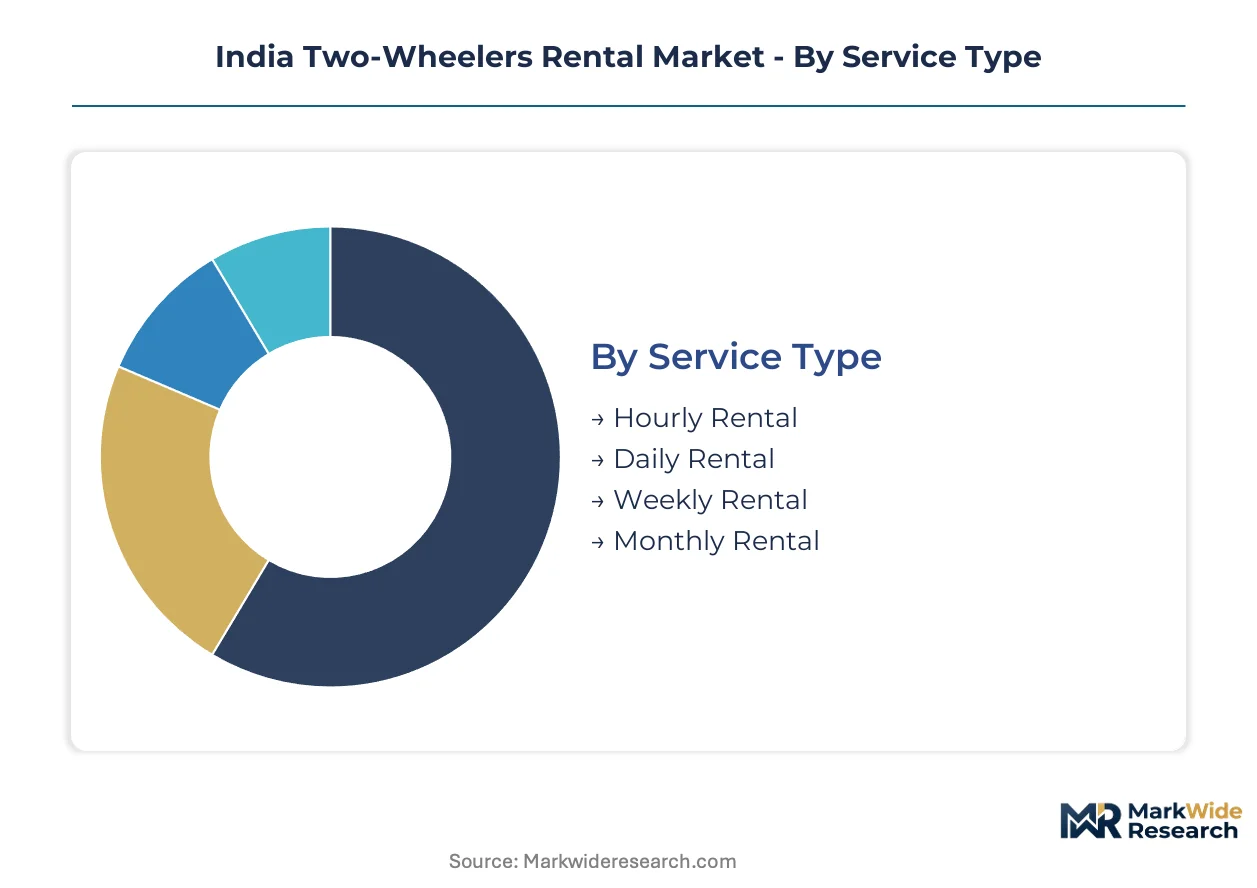
Segmentation in the India two-wheelers rental market reveals how distinct user behaviors and asset configurations create differentiated margin pools. Operators calibrate fleet composition and pricing architecture around these divides to optimize utilization rates and customer lifetime value.
Service Type:
Margin pools concentrate in longer-duration contracts where customer acquisition costs amortize across extended rental periods and asset turnover predictability improves.
- Hourly Rental:Micro-duration access for spontaneous urban trips, typically booked through mobile apps with GPS-enabled unlock. Demand clusters around metro station catchments in Bengaluru and Hyderabad where first-mile connectivity gaps persist.
- Daily Rental:Twenty-four-hour blocks dominate transaction volumes among gig workers and delivery fleets seeking flexible asset access without ownership burdens. Revenue per asset stabilizes through predictable utilization patterns in Mumbai's e-commerce logistics corridors.
- Weekly Rental:Seven-day packages target short-term visitors and temporary workers with bundled maintenance and insurance. This format captures pricing premiums above daily rates while reducing customer churn frequency.
- Monthly Rental:Extended contracts generate the highest per-customer lifetime value through subscription pricing that locks in transport budgets for commuters and professionals. Operators prioritize these arrangements for working capital predictability.
The dominant share belongs to Daily Rental, while Monthly Rental is closing the gap fastest through subscription bundling by platform aggregators.
Vehicle Type:
Technology choices here trace directly to state-level EV policy incentives and the total cost of ownership calculus facing fleet procurement teams.
- Scooter:Automatic transmission units with step-through frames dominate urban commuter rentals for their maneuverability in dense traffic. Karnataka's commercial EV registration subsidies accelerate electric scooter deployment across Bengaluru station networks.
- Motorcycle:Manual transmission models with higher displacement serve touring segments along Kerala and Goa coastal highways where premium pricing applies. Royal Brothers anchors positioning in this category through specialized leisure packages.
- Moped:Low-power two-stroke and electric variants address price-sensitive student segments in university towns. These assets carry lower acquisition costs but generate thinner margins per kilometer.
- Electric Bike:Battery-powered categories attract disproportionate operator investment due to lower per-kilometer running costs and PLI scheme incentives compressing procurement premiums against ICE alternatives. BIS lithium-ion safety certification tiers create differentiation pathways for thermal management investments.
Scooter retains the largest fleet share, though Electric Bike is expanding most quickly as PLI subsidies restructure procurement priorities.
End User:
Customer archetypes determine station location strategy, pricing elasticity, and the appropriate balance between manned counters and unmanned digital access.
- Tourists:Leisure travelers seeking experiential mobility along coastal corridors and heritage circuits. Kerala and Goa operators command pricing premiums through curated touring packages with insurance and route guidance bundled.
- Commuters:Daily wage workers and salaried employees requiring predictable transport budgets for workplace access. Subscription monthly contracts displace walk-in transactions among this segment as gig economy participation expands.
- Students:University populations in southern metropolitan clusters with high two-wheeler dependency but constrained purchasing power. Price sensitivity here drives demand for moped categories and weekly rental formats.
- Professionals:White-collar workers seeking flexible mobility without ownership hassles in cities with incomplete public transit coverage. This segment shows highest adoption of keyless entry and app-based booking systems.
Commuters constitute the largest addressable base, while Tourists deliver the steepest per-transaction margins.
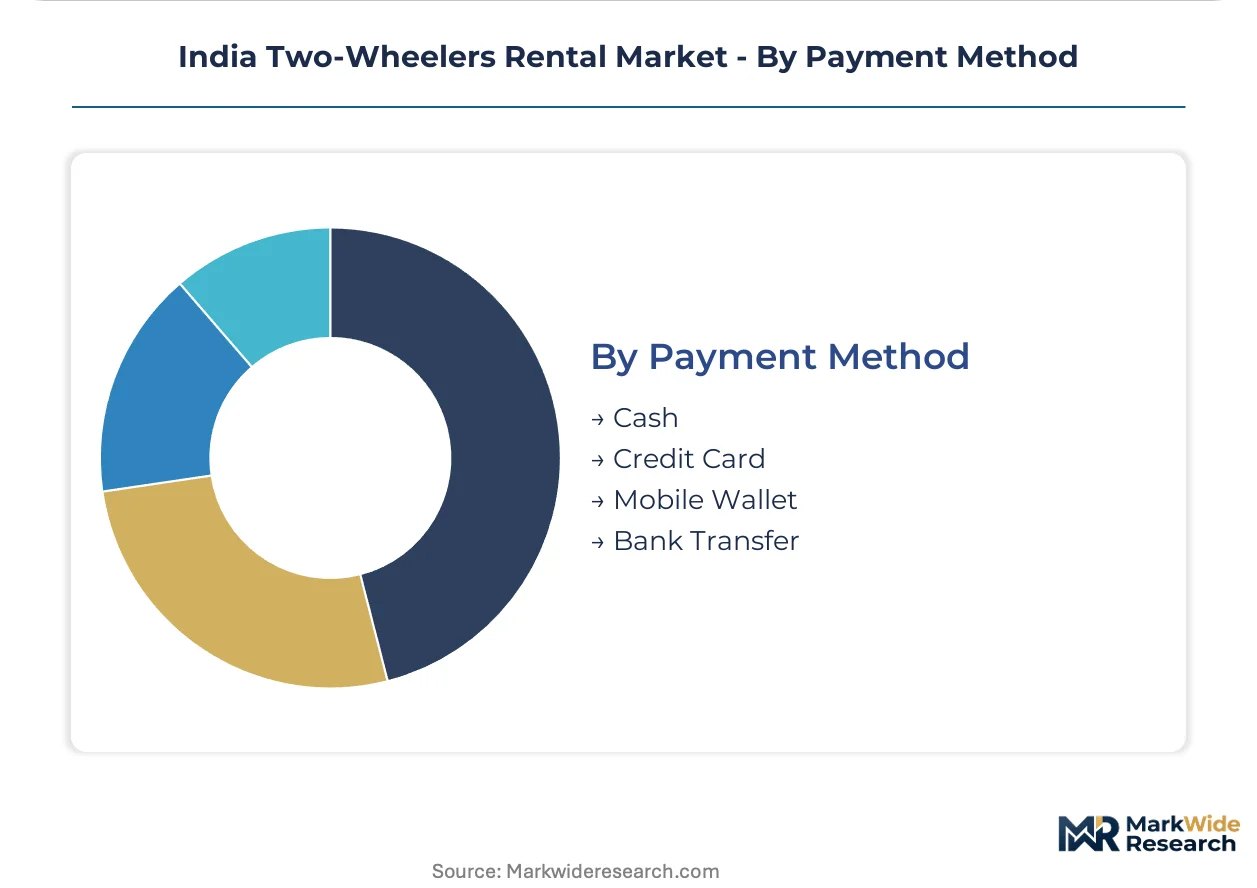
Payment Method:
Digital infrastructure maturity and regulatory frameworks for financial inclusion shape how rental transactions clear and working capital cycles operate.
- Cash:Physical currency persists at manned station counters serving older demographics and unbanked populations. This format elevates reconciliation costs and security risks for operators.
- Credit Card:Card-present and tokenized transactions dominate premium motorcycle rentals and international tourist bookings. RBI payment aggregator guidelines govern how platforms handle card data.
- Mobile Wallet:UPI-linked digital wallets have displaced cash for daily and hourly rentals in tier-1 cities. TRAI digital payment infrastructure supports real-time settlement that improves operator cash conversion cycles.
- Bank Transfer:Net banking and NEFT arrangements apply primarily to monthly subscription contracts and corporate fleet arrangements. These methods introduce settlement delays that operators offset through deposit requirements.
Mobile Wallet has captured the dominant transaction share, with Credit Card retaining importance in premium leisure segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Indian states. Karnataka and Tamil Nadu commuters absorb premium pricing for electric fleets where subsidies offset costs. Northern and central states exhibit steeper elasticity, with demand clustering around entry-level petrol scooters and weekly rental formats.
Karnataka
Bengaluru's tech workforce generates sustained demand for subscription-based electric scooter access. The state's EV policy offers commercial registration subsidies that compress procurement premiums for rental operators. Dense station networks in Koramangala and Whitefield corridors enable unmanned 24-hour access models.
Maharashtra
Mumbai's e-commerce logistics corridors drive predictable daily utilization for delivery fleet rentals. Maharashtra's transport department rulings on electric commercial permits remain pending, creating station rollout delays. Thane and Navi Mumbai sub-markets show concentration of battery-swapping infrastructure investments.
Tamil Nadu
Chennai's manufacturing workforce favors monthly rental contracts for workplace commuting. State-level EV incentives from Tamil Nadu's industrial policy accelerate electric two-wheeler procurement by fleet operators. Ambattur and Guindy industrial zones host emerging station clusters serving factory shift workers.
Telangana
Hyderabad's pharmaceutical and IT corridors generate dual demand streams for commuter and professional segments. Telangana's EV policy framework lags southern neighbors, preserving ICE fleet dominance. Gachibowli and HITEC City sub-markets concentrate dockless scooter deployments.
Kerala
Tourism corridors along coastal highways command the steepest pricing premiums for premium motorcycle rentals. The state's absence of specific commercial EV subsidies leaves procurement decisions to operator economics. Kochi and Thiruvananthapuram anchor leisure-focused station networks targeting experiential mobility.
India Two-Wheelers Rental Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the rental ecosystem. The market exhibits tiered consolidation with dockless platform operators, fleet-leasing specialists, and premium leisure providers occupying distinct competitive spaces. Three archetypes dominate: asset-heavy station network operators, asset-light platform aggregators, and experience-focused touring specialists. Competitive moves concentrate on battery-swapping infrastructure partnerships and subscription bundling to lock in commuter cohorts.
Among dockless scooter specialists, Vogo and Bounce occupy positions exemplifying station density strategies versus in-house infrastructure control. Royal Brothers anchors the premium leisure archetype through coastal tourism corridor concentration. These three represent divergent strategic postures on asset ownership, technology integration, and customer segmentation.
| Leading Market Players |
|---|
| Wheelstreet |
| ONN Bikes Rental |
| Vogo |
| Fae Bikes |
| WickedRide Adventure Services |
| Bounce |
| Drivezy |
| Royal Brothers |
| Yulu |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day lithium-ion battery import lead times compress working capital cycles and concentrate pricing power among operators with domestic assembly partnerships. This inventory constraint shapes how fleet procurement teams balance PLI scheme incentives against CDSCO compliance delays.
Pricing Analysis
After-sales maintenance bundling drives lifetime value in subscription monthly contracts. Three-tier pricing structure across premium touring, standard commuter, and economy delivery tiers segments buyer archetypes. Cost compression in economy delivery tiers intensifies because gig workers absorb zero premium for brand. Tourists show least price sensitivity.
Supply Chain Analysis
Inventory lead times stretch across sixty-to-ninety-day bands for lithium-ion cells sourced from China, South Korea, and Japan. Domestic assembly partnerships rest on BIS-certified battery management systems and CEA-compliant charging hardware. Single-source vulnerability concentrates in imported thermal management components. Distribution runs through station network operators with captive maintenance crews.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's two-wheeler rental market functions as a defensive-moat business where station density creates network effects that lock in commuter routes and deter replication.
For Market Incumbents: Compound station density in Bengaluru and Hyderabad corridors before battery-swapping standardization freezes competitive positions. Acquire distressed ICE fleet operators to convert their permit holdings into electric registrations. Vertical integration into in-house technician training pools addresses the high-voltage diagnostic labor shortage threatening uptime ratios.
For New Entrants and Emerging Players: Inter-city one-way rental gaps along Bengaluru-Chennai highway routes offer uncontested white space. Kerala's coastal touring corridors support premium motorcycle positioning with pricing power absent from saturated commuter markets. Partner with hospitality aggregators for bundled experiential mobility packages.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive groups with under-monetized electric two-wheeler fleets. Five-to-ten-year viability hinges on PLI scheme extension timelines and state-level EV policy durability. Watch Karnataka transport department rulings on commercial registration classification as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Swapping Infrastructure Partnership | Standardized interchange stations eliminate charging downtime and improve asset turnover ratios. |
| Subscription Bundling Platform | Aggregated insurance-maintenance-swap access locks in gig worker commuter cohorts. |
| Domestic Assembly Partnership | CDSCO-compliant battery pack production reduces import lead times and working capital pressure. |
| Premium Touring Package Development | Curated coastal corridor experiences in Kerala and Goa command pricing premiums above urban rentals. |
| Technician Training Academy | In-house high-voltage diagnostics capability addresses labor scarcity threatening fleet uptime. |
Research Methodology
A standing panel of fleet operations directors, state transport department officials, battery procurement managers, and platform engineering leads provided ongoing calibration across primary interview cycles. Secondary validation drew from CEA charging infrastructure filings, BIS certification registries, state EV policy documents, and RBI payment aggregator disclosures. Bottom-up station deployment modeling and top-down metropolitan mobility demand estimates were triangulated.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include service duration tier, vehicle propulsion architecture, end-user archetype, payment method, and regional regulatory cluster. CAGRs were derived from utilization rate assumptions and fleet expansion trajectories. PLI scheme incentive schedules and state-level subsidy durability informed electric fleet penetration curves.
Forecasts assume regulatory continuity in Karnataka, Tamil Nadu, and Maharashtra EV policy regimes; material subsidy withdrawal or commercial registration reclassification would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Indonesia Car Rental Market
Transportation Services
Airport Handling Service Market
Transportation Services
United Kingdom Car Rental Market
Transportation Services
Aerial Lift Rental Services Market
Transportation Services
Truck Rental Market
Transportation Services
Asia Pacific Tourism Vehicle Rental Market
Transportation Services
Drayage Services Market
Transportation Services
Europe Vehicle Rental Market
Transportation Services
Car Rental Service Market
Transportation Services
Vehicle Management System Market
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
Asia-Pacific Rickshaw Ride Hailing Service Market
Transportation Services
Vietnam Car Rental Market
Transportation Services
Multispace Parking Meter Market
Transportation Services
Taxi and Ride-Hailing Services Market
Transportation Services
Bike and Scooter Rental Market