
 Automotive Grade Modules Market | 2026-2036
Automotive Grade Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Grade Modules Market Insights
AEC-Q100 qualification is redrawing competitive boundaries across the Automotive Grade Modules Market. Infineon Technologies leverages captive silicon carbide foundry capacity to anchor supply security for European OEM programs. STMicroelectronics competes through integrated module-software stacks that sustain design-win momentum in electrified powertrain applications.
Automotive grade modules comprise ruggedized electronic assemblies engineered to operate across temperature ranges from minus 40 degrees Celsius to 150 degrees Celsius while resisting vibration, moisture, and electromagnetic interference in vehicle environments. These modules integrate power semiconductors, sensors, microcontrollers, and communication interfaces into sealed packages that manage energy conversion, signal processing, and data transmission for critical vehicle functions. Power modules currently dominate value capture given their central role in inverter and DC-DC converter architectures for electrified vehicles, while sensor modules represent the fastest-expanding category as ADAS penetration deepens across vehicle segments. Control modules retain mature margin profiles in internal combustion powertrain applications even as communication modules gain traction with vehicle-to-everything protocol standardization.
FDA oversight of automotive health-monitoring interfaces, EPA tailpipe and efficiency mandates, and NHTSA functional-safety requirements collectively elevate module validation burdens and extend development cycles. EMA-equivalent standards in European markets and China's GB/T automotive electronics specifications add further compliance layers for multinational suppliers. Stakeholders must monitor evolving semiconductor export controls and carbon-border adjustment mechanisms that threaten to fragment module sourcing strategies across major automotive manufacturing regions.
Market Dynamics
Silicon carbide substrate qualification is compressing supplier timelines as OEMs dual-source AEC-Q100-certified power modules for next-generation inverter platforms. Tier-1 suppliers now demand captive foundry relationships to secure die supply through 2030.
Growth Catalysts
- EPA Efficiency Mandates:Corporate Average Fuel Economy standards are forcing electrified powertrain architectures that consume three times more power modules per vehicle than conventional internal combustion platforms.
- Silicon Carbide Trench Designs:Next-generation MOSFET geometries are cutting switching losses by half, enabling smaller thermal management systems and extending electric vehicle range.
- China Manufacturing Clusters:Shenzhen and Shanghai automotive electronics corridors are concentrating module assembly capacity within four hours of major vehicle assembly plants.
Market Restraints
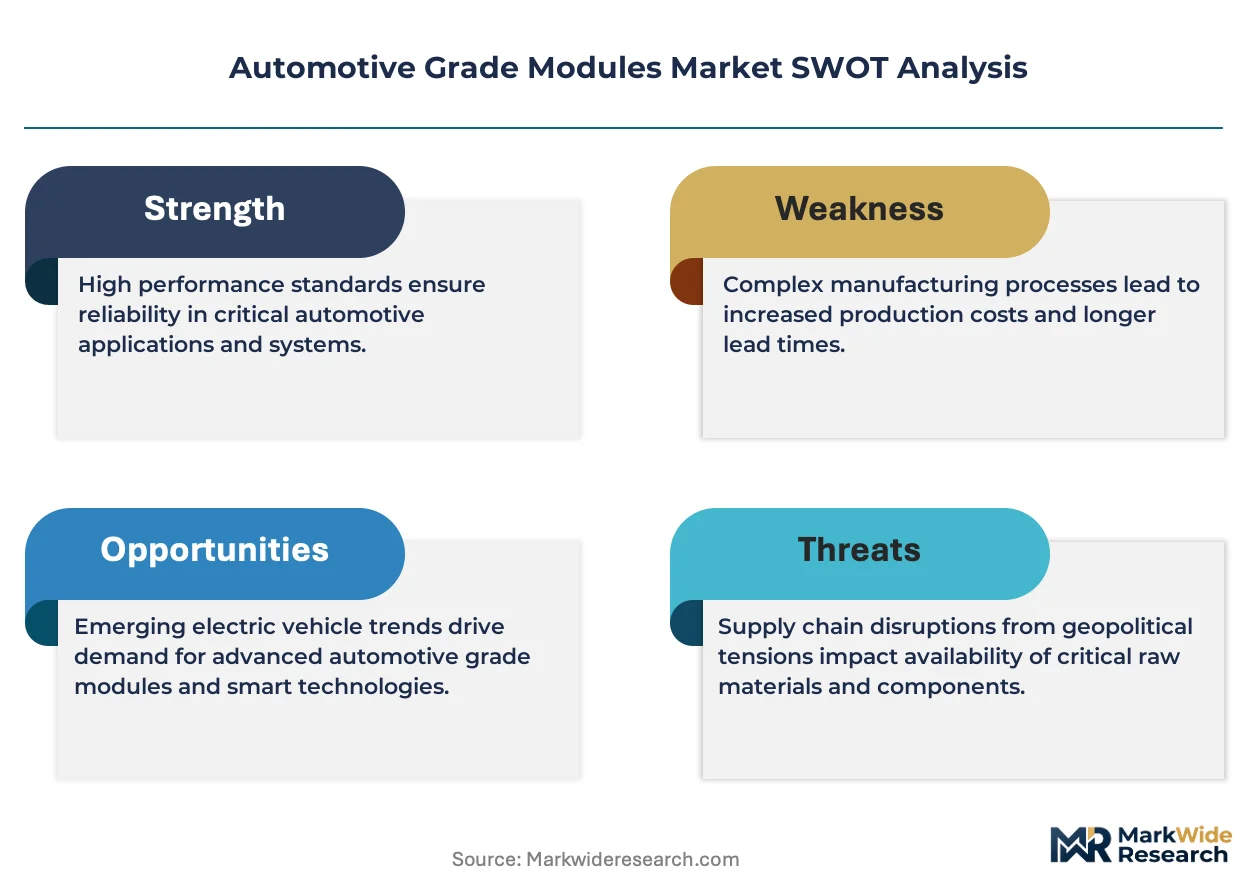
- Silicon Carbide Wafer Supply:Six-inch substrate availability remains bottlenecked by limited crystal growth furnace capacity, concentrating supply among three merchant vendors.
- AEC-Q100 Validation Burden:Extended temperature cycling and humidity testing add eighteen months to new product introduction timelines, freezing out capital-constrained entrants.
- Copper and Epoxy Resin Volatility:Lead frame materials and encapsulation compounds account for thirty percent of module bill-of-materials cost exposure to commodity swings.
Strategic Opportunities
- India Automotive Electronics:PLI scheme incentives for advanced automotive component manufacturing are attracting module packaging investments near Chennai and Pune assembly corridors.
- Vehicle-to-Everything Protocol Standardization:DSRC and C-V2X communication modules represent greenfield demand as regulatory mandates for connected vehicle infrastructure take hold.
- Health Monitoring Integration:FDA-cleared biometric sensors are merging with automotive grade modules to enable driver fatigue detection and emergency response systems.
Industry Challenges
- Functional Safety Engineering Talent:ISO 26262-certified hardware architects command premium compensation, constraining program staffing for mid-tier suppliers.
- Legacy Powertrain Module Obsolescence:Internal combustion control module portfolios require sustained engineering support despite declining volumes, fragmenting R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Grade Modules Market |
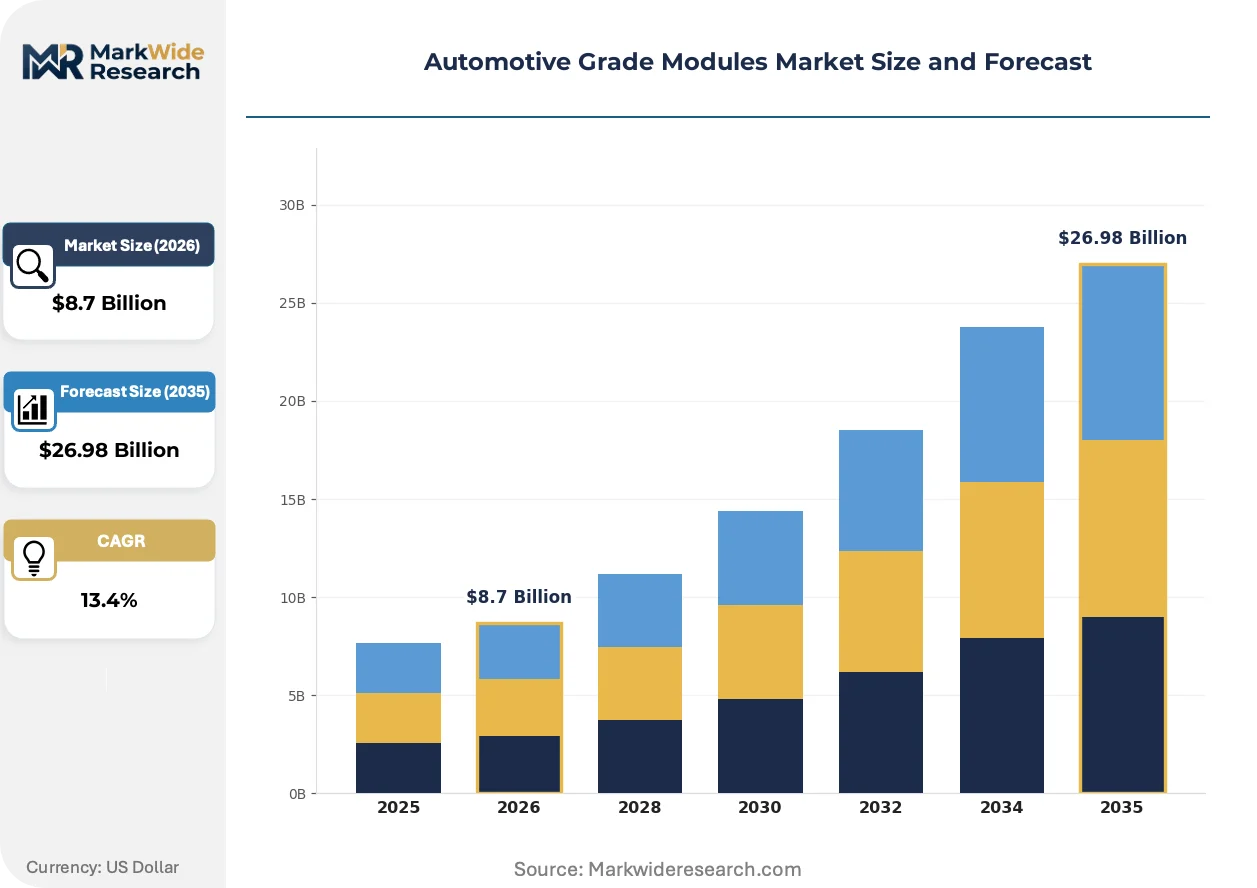
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Modules, Sensor Modules, Control Modules, Communication Modules Technology: Embedded Systems, Wireless Communication, Diagnostics, Connectivity End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Safety Systems, Infotainment, Powertrain Control, Driver Assistance |
| Companies Covered | onsemi, Mitsubishi Electric, Infineon Technologies, Magna International, Denso Corporation, STMicroelectronics, ROHM Semiconductor, Valeo, Wolfspeed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Grade Modules Market Trends and Innovations
Module architectures are bifurcating between discrete component integration and system-in-package consolidation, with thermal co-design emerging as the critical discipline separating qualified suppliers from design-win losers.
Silicon carbide power modules are supplanting silicon IGBTs in 800-volt electric vehicle platforms. Premium OEMs in Germany and South Korea have committed to full SiC inverter deployments by 2027. This transition is compressing silicon foundry utilization rates while expanding ceramic substrate and silver sintering equipment demand.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant monitoring module adoption. Automotive HVAC systems must now integrate pressure and temperature sensors with predictive leak detection algorithms. European Tier-1 climate system suppliers are redesigning module form factors to accommodate these additional sensing channels.
Fleet operators are consolidating module procurement through direct OEM partnerships rather than aftermarket distributors. Commercial vehicle electrification programs in California and the Netherlands are bypassing traditional component wholesalers to secure volume pricing and dedicated engineering support. This channel compression is forcing module vendors to build captive service organizations.
Automotive Grade Modules Market Segmentation
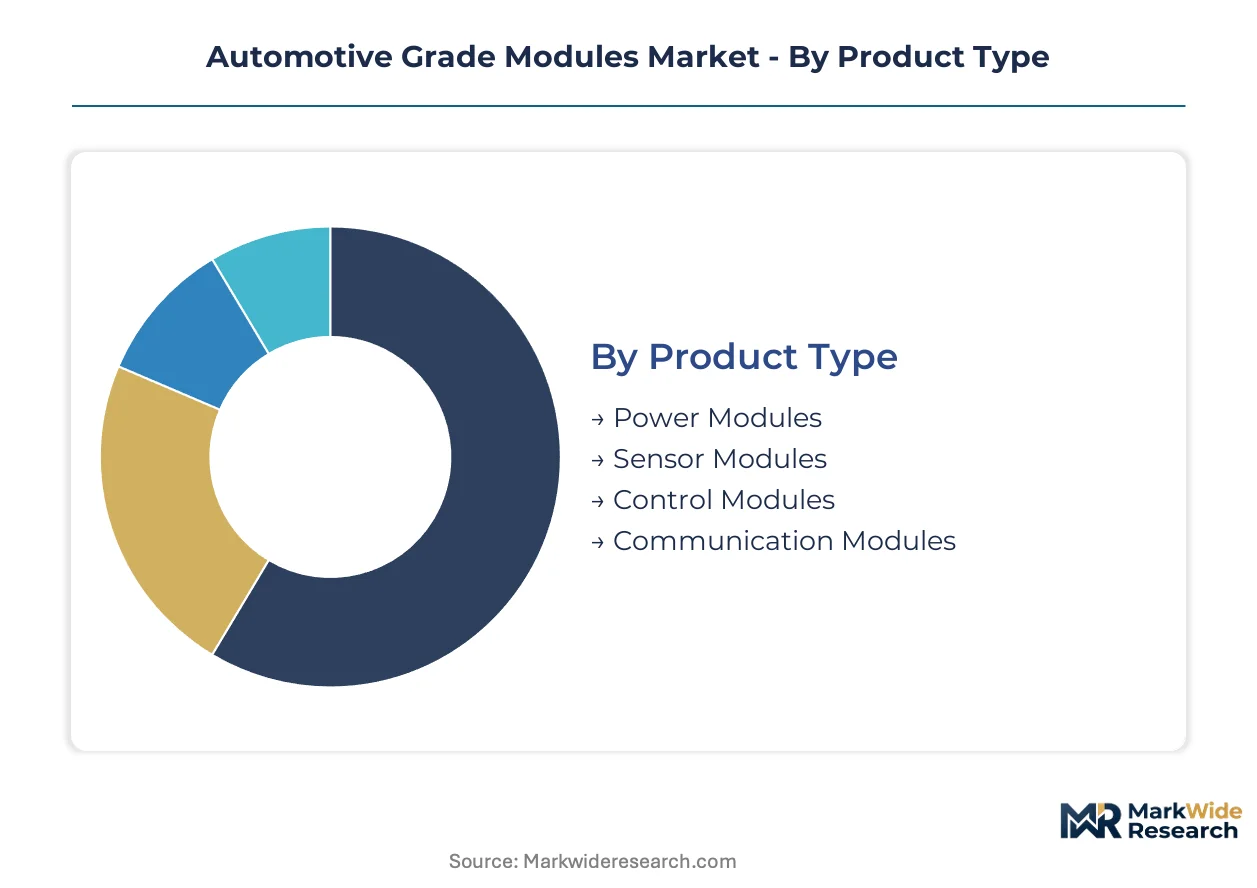
Automotive grade modules segment along functional, technological, and supply chain dimensions that determine qualification requirements and margin capture. Each category reflects distinct regulatory pressures and customer engineering specifications that shape vendor selection criteria.
Product Type:
AEC-Q100 temperature grade requirements and ISO 26262 functional safety ratings create divergent validation burdens across module categories.
- Power Modules:These assemblies integrate silicon carbide or silicon IGBTs with gate drivers and thermal management substrates for inverter and DC-DC conversion. German and South Korean OEMs are specifying full SiC architectures for 800-volt platforms, compressing supplier qualification timelines. Power modules handle the majority of throughput; sensor modules are the fastest mover on share.
- Sensor Modules:Pressure, temperature, position, and current sensing elements packaged with signal conditioning ASICs and automotive-grade connectors. EPA-mandated refrigerant monitoring and NHTSA crash detection requirements are expanding sensor channel counts per vehicle. Shenzhen assembly corridors are concentrating capacitive and MEMS sensor module capacity near electric vehicle final assembly plants.
- Control Modules:Microcontroller-based units executing real-time powertrain, chassis, and body electronics algorithms. These retain mature margin profiles in internal combustion applications even as electrification shifts engineering resources toward power electronics.
- Communication Modules:Transceiver assemblies enabling CAN-FD, Ethernet, and vehicle-to-everything protocols. DSRC and C-V2X standardization in the United States and European Union is creating greenfield demand for connected infrastructure compatibility.
Power modules command the highest unit values; sensor modules are expanding most quickly across vehicle platforms.
Technology:
Cost tier differentiation separates premium certified stacks from commodity connectivity implementations.
- Embedded Systems:Real-time operating systems running on automotive-grade microcontrollers with deterministic latency guarantees. These dominate safety-critical applications where ISO 26262 ASIL-D ratings are mandatory.
- Wireless Communication:Cellular V2X, Wi-Fi, Bluetooth, and UWB modules enabling over-the-air updates and keyless entry. China MIIT spectrum allocations and FCC Part 90 rulings are accelerating 5G automotive module adoption.
- Diagnostics:On-board monitoring systems detecting fault conditions and predicting component degradation. Commercial fleet operators in California are mandating predictive maintenance interfaces for electric vehicle warranty compliance.
- Connectivity:Wired backbone technologies including Automotive Ethernet and CAN-FD physical layers. Infineon and NXP are integrating MAC-PHY combinations to reduce module count and harness complexity.
Embedded systems anchor safety-critical revenue; wireless communication is gaining share fastest as connected vehicle mandates proliferate.
End User:
Customer type determines procurement volume scale and engineering support intensity.
- OEMs:Vehicle manufacturers specifying module architectures and qualifying suppliers through program-specific validation gates. Direct OEM partnerships are consolidating procurement for commercial electrification programs, bypassing traditional distribution channels.
- Tier-1 Suppliers:System integrators combining modules into subassemblies for powertrain, chassis, and climate systems. These demand captive foundry relationships to secure die supply through decade-long platform lifecycles.
- Aftermarket Providers:Distributors and remanufacturers serving vehicle service and retrofit markets. Channel compression is squeezing margins as fleet operators consolidate procurement through OEM direct agreements.
- Vehicle Assemblers:Contract manufacturers performing final module integration and calibration. These concentrate near assembly corridors in Chennai, Pune, and Mexico to minimize logistics costs.
Tier-1 suppliers dominate module volume; OEM direct procurement is climbing the fastest as electrification programs consolidate supply relationships.
Application:
Application maturity separates legacy internal combustion control from emerging electrified and automated functions.
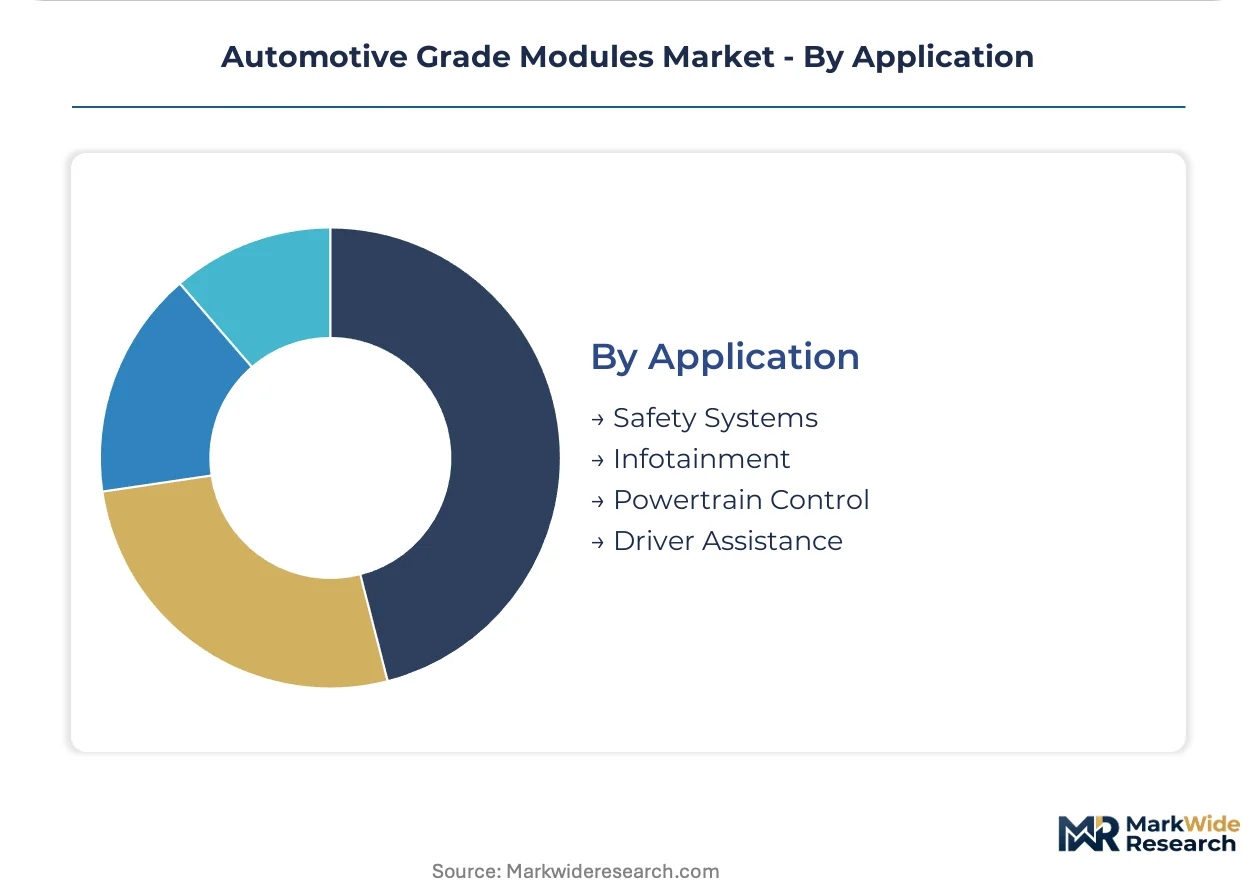
- Safety Systems:Airbag deployment, anti-lock braking, and tire pressure monitoring modules requiring ASIL-D functional safety ratings. NHTSA FMVSS mandates and EU General Safety Regulation requirements are standardizing sensor fusion architectures.
- Infotainment:Display drivers, audio processing, and connectivity hubs with consumer-grade user experience expectations. These modules face shorter development cycles and lower temperature grade requirements than powertrain applications.
- Powertrain Control:Engine management, transmission control, and thermal management modules. Electrification is bifurcating this category between declining internal combustion controllers and expanding battery management systems.
- Driver Assistance:Camera, radar, and lidar processing modules enabling automated lane keeping and emergency braking. China GB/T and EU NCAP test protocols are mandating ADAS feature inclusion across vehicle segments.
Powertrain control handles established volume; driver assistance is on the steepest expansion trajectory as regulatory mandates deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA tailpipe mandates and national electrification incentives are concentrating module demand in automotive manufacturing corridors across five countries. OEMs and Tier-1 suppliers are co-locating assembly capacity within four-hour logistics radii of vehicle final assembly plants.
China
Shenzhen and Shanghai electronics corridors host the densest concentration of power module packaging capacity worldwide. MIIT dual carbon goals and GB/T automotive electronics specifications are accelerating domestic qualification of silicon carbide substrates. BYD and NIO final assembly plants in Hefei and Xi'an are pulling module suppliers inland from coastal export zones.
Germany
Premium OEM commitments to 800-volt SiC architectures by 2027 are compressing supplier validation timelines. EU F-Gas Regulation phase-down schedules mandate refrigerant monitoring modules in HVAC systems. Bavaria and Baden-Württemberg host captive foundry relationships between Infineon, Bosch, and Mercedes-Benz powertrain programs.
United States
NHTSA functional-safety requirements and California Air Resources Board mandates are elevating module validation burdens for electrified commercial fleets. Detroit and Austin assembly corridors are attracting packaging investments from Tier-1 suppliers seeking proximity to Ford, GM, and Tesla programs. Direct OEM procurement is bypassing traditional aftermarket distribution channels.
Japan
METI carbon neutrality roadmaps are driving hybrid and battery-electric powertrain module demand. Toyota and Honda electrification programs in Aichi and Saitama prefectures are sustaining control module engineering resources. Denso and Mitsubishi Electric maintain integrated module-software stacks for domestic OEM design wins.
South Korea
Hyundai-Kia electrification platforms are specifying full SiC inverter deployments by 2026. MFDS-equivalent automotive electronics standards and KBA import requirements shape module qualification protocols. Busan-Ulsan manufacturing clusters concentrate power semiconductor packaging capacity within two hours of Asan and Gwangju vehicle plants.
Automotive Grade Modules Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and captive foundry access. The vendor base concentrates among semiconductor incumbents with AEC-Q100 certification infrastructure and Tier-1 system integrators with decade-long OEM relationships. Three archetypes dominate: integrated device manufacturers with captive silicon carbide capacity, fabless module specialists relying on merchant foundry supply, and diversified automotive suppliers bundling modules into subsystem assemblies. Competitive moves center on backward integration into substrate supply and geographic co-location with OEM final assembly corridors.
Within the integrated device manufacturer tier, Infineon Technologies and STMicroelectronics exemplify the foundry-capability archetype. Wolfspeed represents the pure-play silicon carbide substrate specialist position. Among diversified automotive suppliers, Denso Corporation and Magna International occupy positions spanning module packaging through full subsystem integration. ROHM Semiconductor and onsemi sit within the fabless-module-specialist cluster despite varying degrees of captive fabrication. Mitsubishi Electric and Valeo represent the Japanese and European Tier-1 system integrator archetypes respectively, each bundling module supply into climate and powertrain subassemblies.
| Leading Market Players |
|---|
| onsemi |
| Mitsubishi Electric |
| Infineon Technologies |
| Magna International |
| Denso Corporation |
| STMicroelectronics |
| ROHM Semiconductor |
| Valeo |
| Wolfspeed |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Tier-1 suppliers and silicon carbide substrate vendors lock in both die supply access and price visibility across the Automotive Grade Modules Market, insulating qualified suppliers from spot-market volatility while freezing out capital-constrained entrants lacking AEC-Q100 certification infrastructure.
Pricing Analysis
Certification level creates the primary spread between qualified and commodity-grade module suppliers. AEC-Q100 Grade 0 components command premium positioning against Grade 2 alternatives, with ISO 26262 ASIL-D ratings adding further differentiation. Cost compression in silicon IGBT modules is intensifying because OEMs are dual-sourcing SiC architectures, while Tier-1 suppliers show least price sensitivity due to captive foundry relationships securing decade-long platform supply.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for ceramic substrate and silver sintering equipment shipments. Manufacturing gravity centers on China, Germany, and the United States, with module assembly drawing from silicon carbide wafers, copper lead frames, and epoxy resin encapsulation compounds. Single-source vulnerability concentrates in six-inch SiC substrate supply among three merchant vendors. Distribution runs through direct OEM partnerships bypassing traditional aftermarket wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward OEMs and Tier-1 suppliers as fleet operators consolidate procurement through direct partnerships, fragmenting volume access for mid-tier module vendors unable to secure captive foundry relationships.
For Market Incumbents: Consolidate backward integration into silicon carbide substrate supply and expand AEC-Q100 certification infrastructure to defend against fabless specialists gaining design-win momentum. Lock in capacity reservations with crystal growth furnace vendors before merchant supply tightens further. Prioritize co-location with Shenzhen and Shanghai assembly corridors to compress logistics radii. For New Entrants and Emerging Players: Lead with India PLI scheme incentives for module packaging investments near Chennai and Pune, where domestic OEM electrification programs lack qualified local suppliers. Target health monitoring integration as the most penetrable application, merging FDA-cleared biometric sensors with automotive grade modules for driver fatigue detection systems. Pursue DSRC and C-V2X communication modules as greenfield demand emerges from connected vehicle mandates. For Investors and Strategic Acquirers: Fabless module specialists with AEC-Q100 certification infrastructure and established Tier-1 relationships represent the highest-conviction acquisition archetype for long-term viability across the electrification transition. Watch silicon carbide trench design adoption rates as the inflection indicator separating design-win momentum from portfolio obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Capacity Expansion | Captive substrate supply secures die availability for 800-volt OEM programs. |
| AEC-Q100 Certification Infrastructure Investment | Extended temperature cycling capabilities freeze out capital-constrained competitors. |
| Geographic Co-location with Assembly Corridors | Four-hour logistics radii to Shenzhen and Shanghai plants reduce delivery costs. |
| Integrated Module-Software Stack Development | Deterministic latency guarantees sustain design-win momentum in powertrain applications. |
| Vehicle-to-Everything Protocol Standardization | DSRC and C-V2X compatibility opens greenfield demand from NHTSA mandates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade data, and patent disclosures through structured interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and semiconductor foundry operations managers. Bottom-up module shipment estimates triangulate against top-down vehicle production projections from registration databases and IHS Markit assembly data.
Segmentation dimensions modeled span powertrain architecture, functional safety rating, substrate technology, and regional manufacturing cluster across the projection horizon. CAGRs derive from unit-volume buildups by vehicle class and content-per-vehicle assumptions, with silicon carbide adoption curves and EPA efficiency mandate compliance timelines as key forecast inputs.
Forecasts assume regulatory continuity in EPA tailpipe standards, EU F-Gas phase-down schedules, and China MIIT dual carbon goals; material policy shifts would require re-modeling. Semiconductor export control expansions, carbon-border adjustment mechanisms, and AEC-Q100 specification revisions represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Door Module Market
Automotive Components
Argentina Automotive Electric Actuators Market
Automotive Components
Global Automotive HUD Market
Automotive Components
Automotive Engine Encapsulation Market
Automotive Components
Automotive Polymer Composites Market
Automotive Components
France Automotive Electric Actuators Market
Automotive Components
Europe Automotive Heat Exchanger Market
Automotive Components
Japan Automotive Composites Market
Automotive Components
Global Cylinder Deactivation System Market
Automotive Components
Automotive Carbon Thermoplastic Market
Automotive Components
North America Heat Shrink Tubing for Automotive Market
Automotive Components
Intelligent Torque Controlled Coupling (ITCC) Market
Automotive Components
Turkey Automotive Plastic Compounding Market
Automotive Components
Automotive Exhaust Emission Control Device Market
Automotive Components
Global Automotive Window Regulator Market
Automotive Components
Automotive Spray Guns Market