
 Vehicle Control Unit (VCU) Market | 2026-2036
Vehicle Control Unit (VCU) Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Control Unit (VCU) Market Analytics
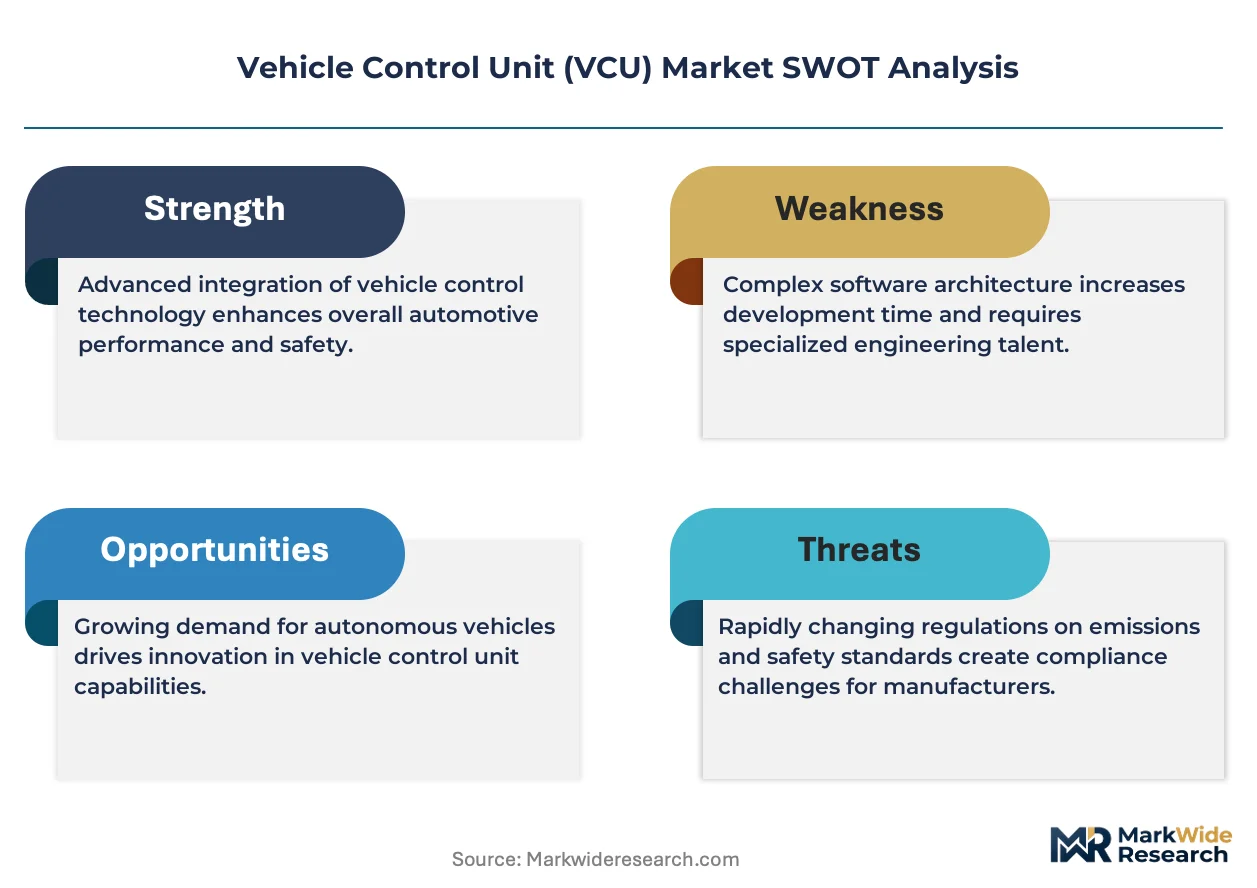
EU Green Deal vehicle emission mandates are broadening the cost-of-entry calculus for VCU suppliers seeking European homologation. Continental AG leverages its systems integration depth to anchor powertrain control contracts with German OEMs. Bosch competes through manufacturing scale across its semiconductor and mechatronics divisions. Texas Instruments sustains R&D intensity in automotive-grade microcontrollers for real-time chassis processing.
A Vehicle Control Unit is an embedded electronic controller that manages power distribution, torque coordination, and subsystem communication across automotive networks, typically operating on 12V or 48V architectures with CAN, LIN, or Ethernet protocol stacks. Its primary commercial purpose is to unify previously discrete control modules into a centralized computing layer that reduces wiring complexity and enables over-the-air software updates. The ECU product type still occupies the largest installed base, though Ethernet-based communication is displacing CAN in premium architectures where bandwidth for sensor fusion and autonomous functions has become critical. OEM end users dominate procurement volumes, but Tier-1 Suppliers control the design-in process and capture disproportionate margin pools through firmware ownership.
FCC certification requirements govern wireless-enabled VCUs in the United States, while EMA and EU Green Deal frameworks shape emission-linked software validation across Europe. NHTSA safety standards in the US and CE marking obligations in Europe collectively raise compliance spend for entrants lacking established regulatory affairs teams. Stakeholders must decide whether to build in-house homologation capabilities or absorb the margin compression from outsourcing certification to specialized consultancies.
Market Dynamics
Centralized powertrain computing architectures are compressing supplier margins as OEMs consolidate previously discrete ECU functions into unified domain controllers, forcing firmware specialists to defend value through software ownership rather than hardware volume.
Growth Catalysts
- Battery-electric commercial vehicle fleets:Fleet operators in Germany's logistics corridors are procuring integrated powertrain controllers that unify motor control, battery management, and thermal systems into single compute layers.
- EU Green Deal emission mandates:Homologation requirements for software verification are tightening validation protocols, creating pull for suppliers with established regulatory affairs capabilities.
- Ethernet protocol migration:Premium vehicle architectures are replacing CAN bus with Ethernet stacks to accommodate sensor fusion bandwidth demands for autonomous functions.
Market Restraints
- Automotive-grade semiconductor supply concentration:Foundry capacity for AEC-Q100 qualified microcontrollers remains concentrated among Taiwan-based suppliers, exposing procurement timelines to geographic concentration risk.
- Functional safety certification costs:ISO 26262 ASIL-D compliance requires specialized engineering talent and extended validation cycles that compress margins for mid-tier suppliers.
- 48V architecture transition friction:Legacy 12V supply chains and tooling investments create stranded asset risk for suppliers without dual-voltage platform capabilities.
Strategic Opportunities
- Over-the-air update infrastructure:Firmware monetization through subscription-based feature activation creates recurring revenue streams beyond initial hardware sales.
- Commercial vehicle electrification in India:PLI scheme incentives for domestic manufacturing are attracting controller suppliers to establish local engineering centers around Pune and Chennai.
- Chassis-suspension integration:Convergence of torque vectoring and active damping control into unified chassis domain controllers opens white space beyond powertrain applications.
Industry Challenges
- Embedded cybersecurity expertise scarcity:ISO/SAE 21434 compliance requires automotive engineers with cryptographic protocol and intrusion detection capabilities that remain scarce in traditional ECU development teams.
- Legacy CAN network integration complexity:Mixed-architecture vehicles require protocol translation layers that increase software validation burden and defect surface area.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Control Unit (VCU) Market |
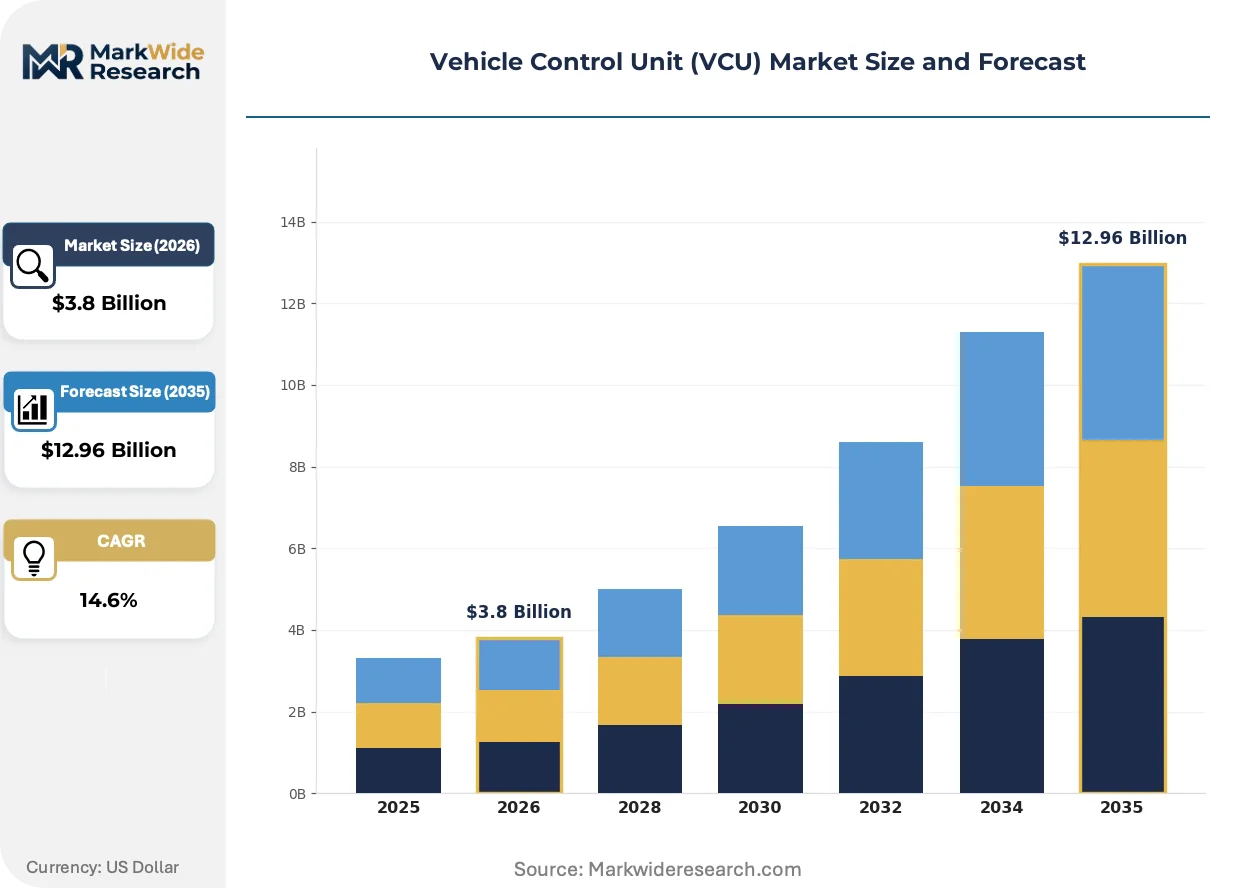
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ECU, BCM, TCU, ABS Module Technology: CAN, LIN, FlexRay, Ethernet End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Powertrain, Chassis Control, Safety Systems, Infotainment |
| Companies Covered | Texas Instruments, ZF Friedrichshafen AG, Continental AG, Marelli, Denso Corporation, Bosch, Mitsubishi Electric Corporation, Hirain Technologies, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Control Unit (VCU) Market Evolving Landscape
Software-defined vehicle architectures are reconfiguring competitive boundaries between semiconductor suppliers, Tier-1 integrators, and OEM captive engineering organizations. Three forces are compressing traditional value chains.
Domain controller consolidation is decentralizing function-specific ECU procurement decisions from individual engineering groups into centralized platform teams. German OEMs are migrating body, chassis, and powertrain control into zonal compute nodes. This compression is eliminating standalone module suppliers that lack systems integration depth.
REACH substance restrictions and EU Green Deal lifecycle assessment requirements are mandating material traceability through semiconductor supply chains. Component suppliers must document conflict mineral status and carbon intensity for homologation eligibility. Battery-electric vehicle platforms face the strictest documentation burdens, with German regulators leading enforcement stringency.
Fleet procurement teams are consolidating supplier relationships around full-stack powertrain control rather than discrete module sourcing. Commercial vehicle operators in Stuttgart's logistics basin are awarding multi-year contracts to integrators owning both hardware and firmware IP. This concentration is visible across Germany's automotive engineering corridor, where Tier-1 suppliers with captive semiconductor partnerships capture disproportionate contract value.
Vehicle Control Unit (VCU) Market Segmentation
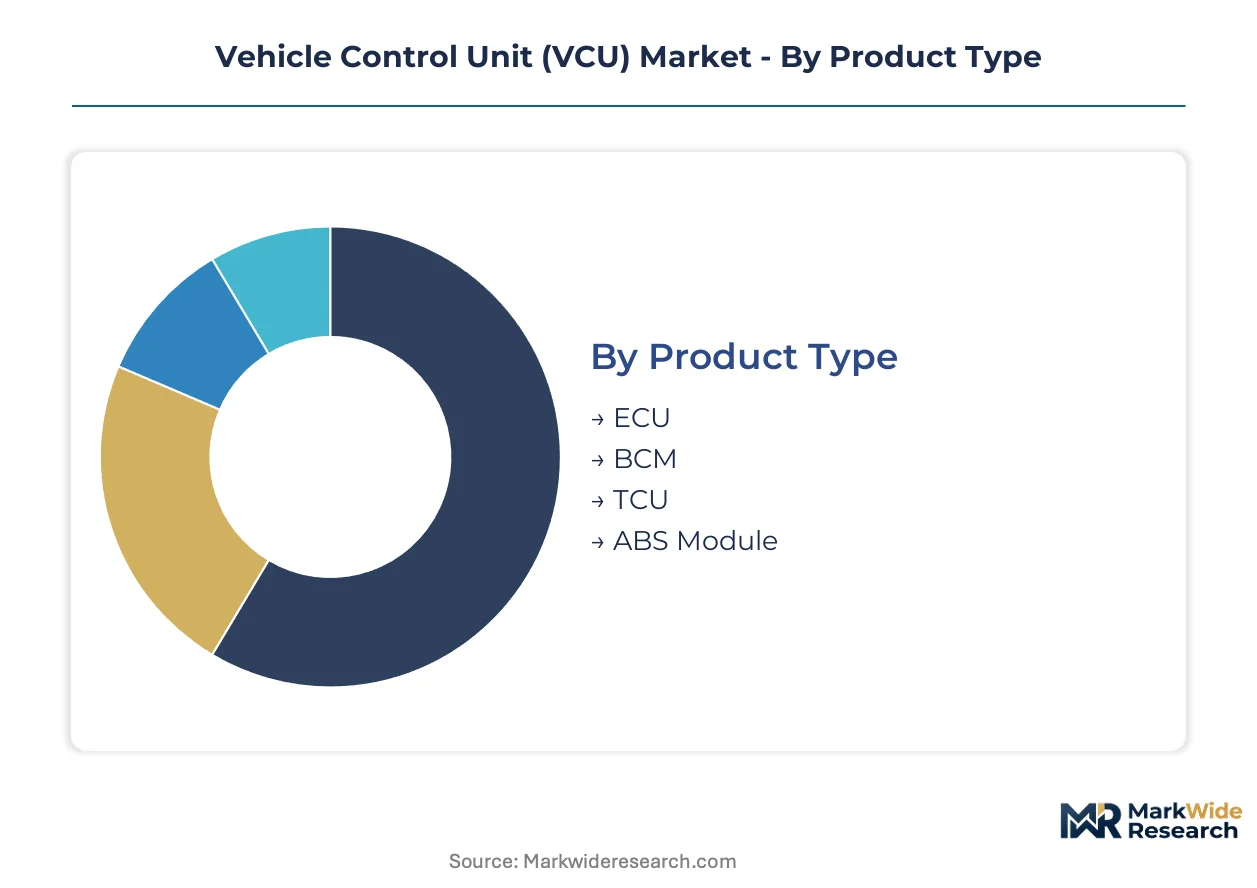
VCU procurement patterns diverge sharply across product architectures, communication protocols, and buyer types. Understanding these fault lines exposes where margin pools concentrate and which technology transitions threaten incumbent positioning.
Product Type:
Hardware differentiation separates suppliers with firmware ownership from commodity module assemblers.
- ECU:Embedded controllers manage engine timing, fuel injection, and emissions compliance through real-time signal processing. German OEMs in Stuttgart's engineering corridor source ECUs with integrated homologation documentation for EU Green Deal validation.
- BCM:Body control modules coordinate lighting, climate, and access systems across 12V and 48V architectures. Fleet operators in commercial vehicle electrification programs demand BCMs with over-the-air update capability to reduce warranty exposure.
- TCU:Transmission control units optimize gear selection and torque delivery for hybrid powertrains.
- ABS Module:Anti-lock braking controllers integrate with ESC systems for stability management.
ECU leads volumes today; BCM is gaining share fastest.
Technology:
Protocol selection locks buyers into specific semiconductor ecosystems and validation cost structures.
- CAN:Controller Area Network dominates legacy vehicle architectures with proven reliability for powertrain and chassis signaling. Tier-1 suppliers in Germany's automotive corridor maintain CAN engineering teams for backward compatibility with 12V platforms.
- Ethernet:Automotive Ethernet delivers the bandwidth density required for camera fusion and LiDAR processing in automated driving stacks. Premium German OEMs specify Ethernet backbone architectures for next-generation domain controllers.
- LIN:Low-cost single-wire protocol serves door modules and seat controls where data rates remain minimal.
- FlexRay:Deterministic high-speed bus supports brake-by-wire and steer-by-wire safety systems.
CAN retains the largest installed base; Ethernet is climbing the fastest.
End User:
Procurement authority determines who captures firmware IP value versus hardware margin.
- OEMs:Vehicle manufacturers with captive software engineering increasingly specify open controller architectures to retain update authority. German OEM platform teams consolidate VCU sourcing decisions away from individual vehicle lines.
- Tier-1 Suppliers:Systems integrators with semiconductor partnerships control design-in processes and firmware ownership. Continental AG and Bosch anchor powertrain control contracts through manufacturing scale across mechatronics divisions.
- Aftermarket Providers:Independent distributors serve repair networks with replacement modules requiring reverse engineering of proprietary calibration data.
- Vehicle Assemblers:Contract manufacturers without full R&D capabilities rely on turnkey controller supply from integrated Tier-1 partners.
Tier-1 Suppliers dominate contract value today; OEMs are consolidating procurement authority fastest.
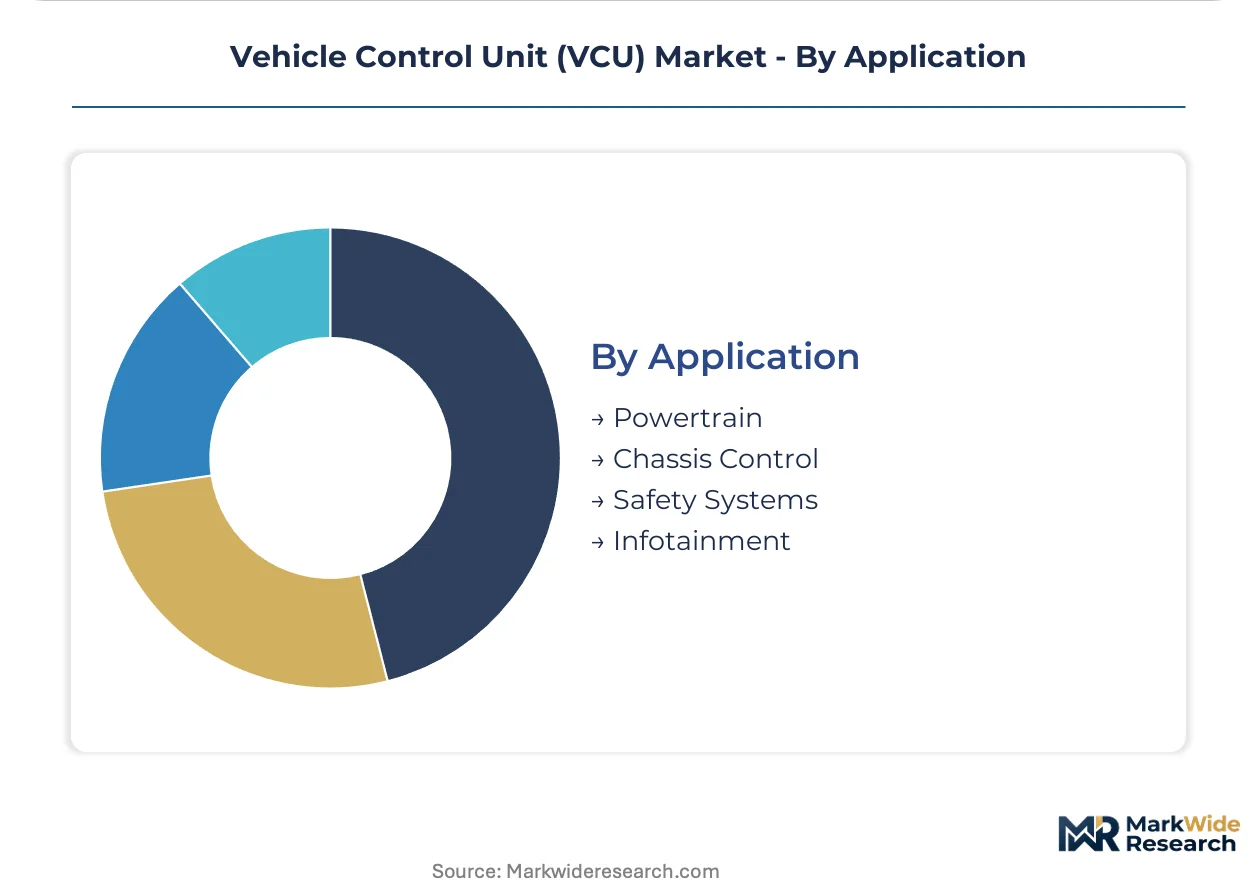
Application:
Functional domain determines safety integrity level requirements and validation timeline exposure.
- Powertrain:Motor control, battery management, and thermal coordination demand ASIL-D functional safety certification. Battery-electric commercial fleets in Germany's logistics corridors procure integrated powertrain controllers unifying previously discrete modules.
- Safety Systems:Airbag deployment, collision avoidance, and emergency braking require deterministic response latency. NHTSA safety standards and CE marking obligations raise compliance spend for safety-critical controller development.
- Chassis Control:Active suspension, torque vectoring, and steer-by-wire systems converge into unified domain controllers.
- Infotainment:Cabin connectivity and display processing operate at lower safety grades but face FCC certification for wireless-enabled modules.
Powertrain leads revenue concentration today; Safety Systems face the steepest certification cost escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive electronics engineering talent concentrates in Germany's Stuttgart-Munich corridor, Taiwan's semiconductor foundry clusters, and Detroit's legacy powertrain engineering base. These workforce pools anchor VCU design, validation, and manufacturing capacity across three continents.
Germany
Battery-electric commercial fleets in Baden-Württemberg and Bavaria procure integrated powertrain controllers from Tier-1 suppliers with captive firmware IP. KBA enforces EU Green Deal software verification protocols that lengthen homologation timelines for entrants lacking established regulatory affairs teams. Stuttgart's engineering corridor hosts concentrated procurement decisions from German OEM platform teams consolidating previously discrete ECU functions.
United States
Detroit's automotive engineering base supports powertrain controller development for hybrid and electric truck platforms serving domestic fleet operators. NHTSA safety standards and FCC certification requirements for wireless-enabled modules raise compliance spend for suppliers without in-house homologation capabilities. Michigan's automotive supplier network maintains CAN protocol engineering teams for backward compatibility with legacy 12V platforms.
China
Domestic EV manufacturers in the Yangtze River Delta and Pearl River Delta scale procurement of domain controllers unifying motor control and battery management functions. MIIT oversees GB standards compliance for automotive-grade microcontrollers used in safety-critical applications. Shanghai's electronics manufacturing corridor concentrates foundry relationships for AEC-Q100 qualified semiconductors.
Japan
Hybrid powertrain specialists in Nagoya's Chubu region and Tokyo's Kanto corridor develop transmission control units for dual-motor architectures. METI coordinates national semiconductor supply resilience initiatives affecting automotive microcontroller procurement timelines. Toyota City's supplier ecosystem anchors concentrated TCU engineering for domestic OEM captive programs.
India
Commercial vehicle electrification programs in Maharashtra and Tamil Nadu attract controller suppliers establishing local engineering centers. PLI scheme incentives for domestic manufacturing reduce landed cost for integrated powertrain modules serving fleet operators. Pune's automotive supplier cluster hosts emerging firmware development capabilities for chassis-suspension integration applications.
Vehicle Control Unit (VCU) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered supplier structure. The vendor base organizes around three strategic archetypes: semiconductor suppliers with automotive-grade microcontroller portfolios, Tier-1 systems integrators owning firmware IP and manufacturing scale, and captive OEM engineering organizations retaining architecture authority. Dominant competitive moves include strategic partnerships between semiconductor foundries and module integrators, plus backward integration by Tier-1 suppliers into AEC-Q100 qualified component sourcing.
Among diversified technology conglomerates, Texas Instruments and STMicroelectronics represent the semiconductor-centric archetype with automotive microcontroller development intensity. Continental AG and Bosch exemplify the integrated Tier-1 systems supplier model, anchoring powertrain control contracts through combined hardware manufacturing and firmware ownership. These four entities occupy positions spanning the value chain from silicon to module assembly.
| Leading Market Players |
|---|
| Texas Instruments |
| ZF Friedrichshafen AG |
| Continental AG |
| Marelli |
| Denso Corporation |
| Bosch |
| Mitsubishi Electric Corporation |
| Hirain Technologies |
| STMicroelectronics |
| Others |
Value Network & Pricing Analysis
Automotive-grade firmware engineering talent clustering in Germany's Stuttgart-Munich corridor compresses labor-cost differentials between premium ASIL-D certified modules and standard-grade controllers, widening pricing-tier spreads as Tier-1 suppliers defend margin through firmware ownership rather than hardware volume.
Pricing Analysis
Bundled hardware-firmware contracts dominate premium procurement, while unbundled module sourcing persists in aftermarket channels. Pricing stratifies across ASIL-D safety-certified, ASIL-B functional, and economy-grade tiers based on validation depth and semiconductor content. Cost compression in mid-tier ECUs is intensifying because OEMs consolidate discrete modules into domain controllers. Fleet operators in commercial vehicle electrification programs exhibit highest price sensitivity; German OEM captive engineering organizations show lowest sensitivity where firmware IP ownership is at stake.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated powertrain controllers, while Tier-1 integrators feed aftermarket distributors with replacement modules. Foundry capacity for AEC-Q100 qualified microcontrollers concentrates in Taiwan, South Korea, and the United States. The supply chain draws from automotive-grade silicon wafers, rare-earth magnet materials for motor control integration, and specialized laminates for high-voltage isolation. Single-source vulnerability around Taiwan-based foundry exposure creates procurement timeline risk for suppliers without qualified secondary sources. Distribution runs through consolidated Tier-1 integrators capturing firmware value, with direct OEM relationships commanding preferred allocation during capacity constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Vehicle Control Unit procurement rests on software-defined vehicle architectures shifting value capture from hardware volume toward firmware monetization and over-the-air update infrastructure.
For Market Incumbents: Hedge against domain controller consolidation by anchoring powertrain control contracts through captive semiconductor partnerships and ASIL-D certification depth. Tier-1 suppliers with established KBA regulatory affairs capabilities capture disproportionate contract value as EU Green Deal software verification timelines lengthen. Capacity addition in India's PLI scheme corridors around Pune and Chennai reduces landed cost exposure for commercial vehicle electrification programs. For New Entrants and Emerging Players: Cloud-based calibration platforms offer a lower-friction entry path than hardware manufacturing, enabling firmware specialists to bypass foundry capacity constraints and anchor design-in relationships through software value. Chassis-suspension integration applications present the most penetrable white space beyond saturated powertrain controller procurement. Target commercial vehicle fleet operators in Germany's logistics corridors with subscription-based feature activation models that decouple revenue from hardware shipment cycles. For Investors and Strategic Acquirers: Semiconductor suppliers with automotive microcontroller portfolios are the most active acquirer in this space, seeking to capture downstream module value through backward integration into firmware development. Long-term viability over the next decade hinges on software ownership depth rather than manufacturing scale alone. Watch Ethernet protocol migration rates in premium German OEM architectures as the inflection signal separating winners from commodity hardware assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Captures recurring firmware revenue beyond initial hardware sales through over-the-air update infrastructure. |
| Battery Supply Agreement | Secures preferred allocation of AEC-Q100 qualified microcontrollers from Taiwan-based foundry partners. |
| Platform Standardization | Reduces validation burden across 12V and 48V architectures for German OEM consolidated procurement teams. |
| Geographic Manufacturing Footprint | Positions suppliers for PLI scheme incentives in India's Maharashtra and Tamil Nadu corridors. |
| Charging Infrastructure Partnership | Opens fleet procurement relationships with commercial vehicle operators in Stuttgart's logistics basin. |
Research Methodology
Direct dialogue with OEM platform engineers, Tier-1 supplier procurement leads, semiconductor foundry planning officers, and aftermarket distributor operations heads grounded qualitative assessment of procurement authority shifts and firmware value capture. Secondary validation drew from vehicle production databases, IHS Markit registration data, KBA homologation filings, and SEC disclosures from automotive electronics suppliers. Bottom-up unit economics triangulated against top-down OEM procurement budget estimates across the analysis window.
Segment-level outputs reflect modeled propagation of battery-electric commercial vehicle fleet expansion, EU Green Deal software verification timeline compression, and Ethernet protocol migration rates in premium architectures. CAGRs derived from regression against historical content-per-vehicle trajectories and projected domain controller consolidation patterns. Forecast inputs included semiconductor foundry capacity expansion announcements, PLI scheme incentive disbursement schedules, and ASIL-D certification pipeline visibility.
The model assumes a particular technology adoption path; alternative pathways for zonal E/E architecture migration would alter the outlook if OEMs accelerate central compute consolidation beyond projected timelines. Forecasts reflect documented assumptions around foundry yield improvements and regulatory enforcement stringency trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Two-Wheeler Connectivity Systems Market
Automotive Electronics & Wiring
Mexico Automotive Camera Market
Automotive Electronics & Wiring
Asia-Pacific Automotive Smart Key Market
Automotive Electronics & Wiring
Automotive Head-Up Display (HUD) and Instrument Cluster Market
Automotive Electronics & Wiring
Automotive Wireless Module Market
Automotive Electronics & Wiring
Automotive Data Cables Market
Automotive Electronics & Wiring
Automotive Ultrasonic Sensors Market
Automotive Electronics & Wiring
UAE Automotive Sensors Market
Automotive Electronics & Wiring
Automotive AR HUD Market
Automotive Electronics & Wiring
Australia Automotive Camera Market
Automotive Electronics & Wiring
Automotive Speedometer Cable Market
Automotive Electronics & Wiring
Brake Cables Market
Automotive Electronics & Wiring
Passenger Vehicle Dashboard Camera Market
Automotive Electronics & Wiring
Vehicle Intercom System Market
Automotive Electronics & Wiring
Automotive Steer-By-Wire System (Sbw) Market
Automotive Electronics & Wiring
India ECU Market