
 Plastic Fuel Tanks Market | 2026-2036
Plastic Fuel Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Fuel Tanks Market Insights
Market Context with Strategic Players
Polymer engineering talent is rotating from traditional blow-molding toward multilayer coextrusion expertise as OEMs demand barrier-enhanced tanks. Plastic Omnium leverages vertical integration across resin compounding and tank assembly to sustain cost leadership in Europe. Kautex Textron anchors North American supply through dedicated HDPE production lines serving Detroit automakers. Yachiyo Industry dominates Asian sourcing with Japan-centered manufacturing that navigates just-in-time delivery requirements.
Technical Definition and Structural Segments
Plastic fuel tanks are blow-molded or rotationally molded polymer reservoirs engineered to store gasoline, diesel, or alternative fuels in vehicles and equipment, typically constructed from high-density polyethylene with ethylene-vinyl alcohol barrier layers to meet permeation limits below 0.5 grams per square meter per day. The primary purpose is to reduce vehicle weight by 30-50% versus stamped steel while maintaining crash integrity and emissions compliance. HDPE-based inboard automotive installations occupy the largest value pool given passenger vehicle production scale, while portable tanks for marine and outdoor power equipment represent the fastest-expanding segment driven by recreational boating demand. Nylon and polypropylene formulations are gaining share in hybrid vehicle applications where higher temperature resistance offsets material cost premiums.
Regulatory Frame and Forward-Looking Close
EPA fuel permeation regulations under 40 CFR Part 1060, EU F-Gas Regulation, and China's GB standards enforced by SAMR collectively mandate multilayer barrier construction and evaporative emission controls that elevate technical entry barriers. NHTSA crashworthiness requirements and ECE R34 harmonization further shape tank geometry, mounting, and flame-retardant specifications across export markets. Stakeholders must monitor how California Air Resources Board zero-emission vehicle mandates and Euro 7 tailpipe standards redirect tank demand toward range-extender hybrids versus full battery platforms.
Market Dynamics
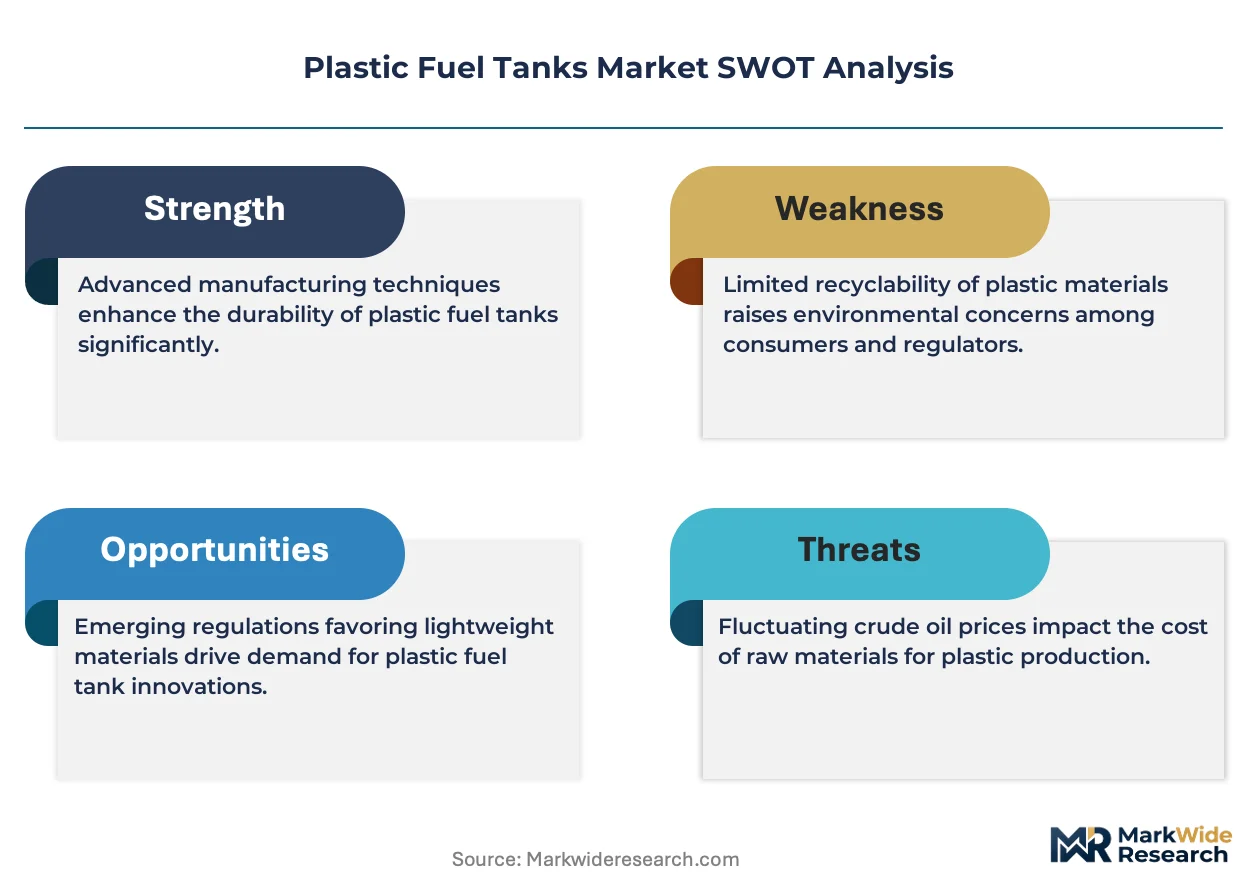
Automotive OEMs are consolidating tank sourcing around multilayer coextrusion capacity as EPA and EU permeation standards harden, forcing resin suppliers and molders to synchronize barrier-layer investments with vehicle platform cycles.
Growth Catalysts
- EPA 40 CFR Part 1060:Federal permeation limits below 0.5 grams per square meter per day mandate six-layer HDPE/EVOH construction, locking in polymer tank demand for gasoline-powered light trucks and passenger vehicles.
- Hybrid powertrain thermal loads:Range-extender and plug-in hybrid architectures require fuel tanks withstanding 80-90°C operating temperatures, accelerating nylon and polypropylene formulations in electrified platforms.
- Marine recreational equipment:Portable blow-molded tanks for outboard motors and personal watercraft are capturing volume as coastal tourism rebounds and boat ownership expands in Florida, Queensland, and the Mediterranean basin.
Market Restraints
- Ethylene feedstock volatility:HDPE resin costs fluctuate with naphtha and natural gas liquids pricing, compressing converter margins when crude benchmarks spike above refinery crack spread equilibrium.
- Barrier-layer supply concentration:EVOH copolymer production concentrates in Japan and Belgium, exposing tank manufacturers to freight cost surges and currency hedging complexity.
- Full battery electric substitution:BEV platforms eliminate fuel tanks entirely, threatening long-term demand in passenger segments where range and charging infrastructure achieve parity with liquid fuels.
Strategic Opportunities
- India two-wheeler and three-wheeler conversion:Compressed natural gas and ethanol-blend fuel systems in Mumbai, Delhi, and Bangalore present first-mover openings for localized blow-molding capacity serving Bajaj Auto and TVS Motor.
- EU Green Deal sustainable feedstocks:Bio-based HDPE and chemically recycled barrier resins qualify for green procurement preferences in German and French OEM supply contracts.
- Smart tank telemetry integration:Level sensors and leak-detection electronics are converging with molded polymer reservoirs, creating aftermarket retrofit demand for connected fleet management.
Industry Challenges
- Multilayer coextrusion technician scarcity:Blow-molding operators with barrier-layer die tuning expertise command wage premiums in Michigan, Baden-Württemberg, and Guangdong, constraining capacity expansion timelines.
- Homologation testing backlog:ECE R34 crashworthiness certification and EPA evaporative emission validation queues extend 14-18 months, delaying new tank program launches for redesigned vehicle architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Fuel Tanks Market |
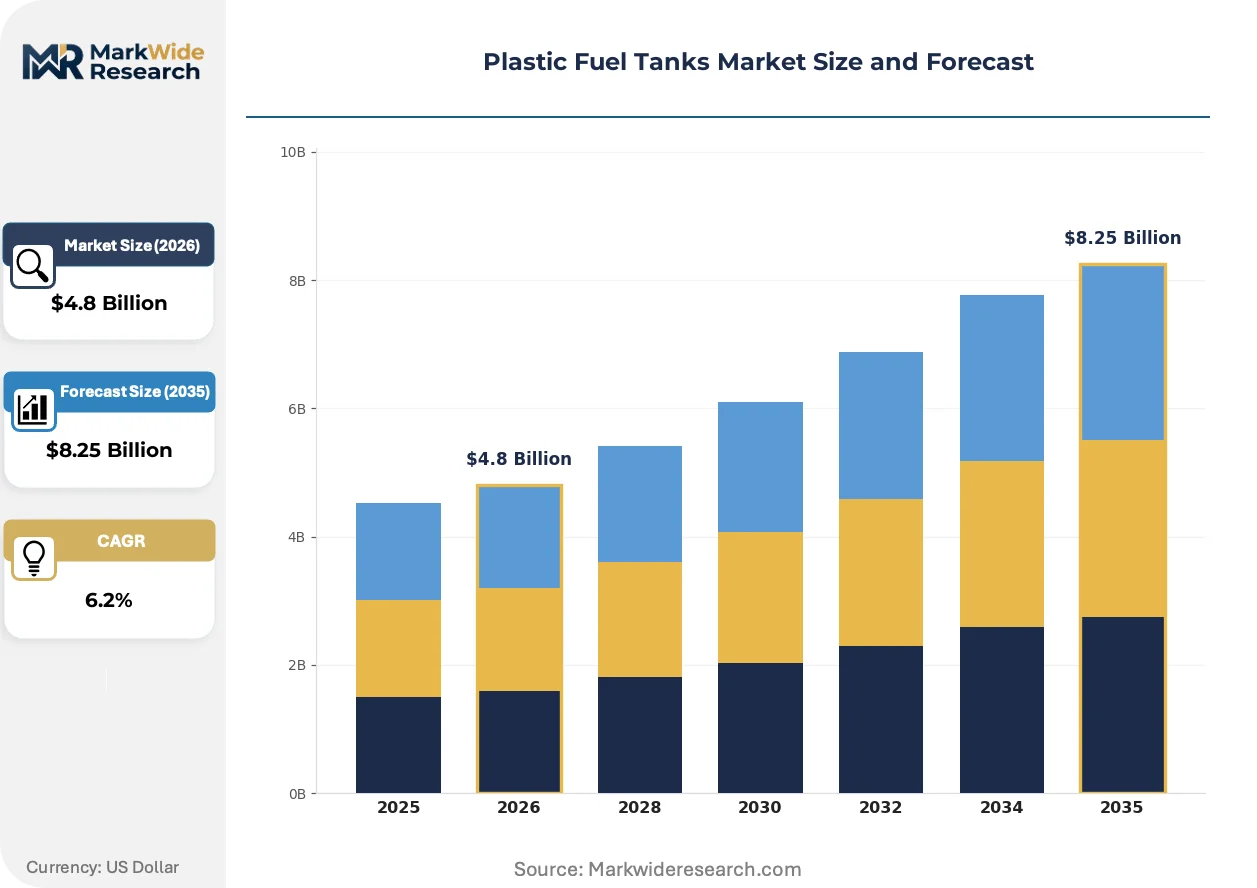
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inboard, Outboard, Portable, Stationary End User: Automotive, Marine, Agricultural, Industrial Material: Polyethylene, Polypropylene, Nylon, PVC Installation Type: Above Ground, Underground, Mobile, Fixed |
| Companies Covered | Plastic Omnium, TI Fluid Systems, Kautex Textron, Yachiyo Industry, Magna International, YAPP Automotive, Unipres, Hanon Systems, Fuel Total Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Fuel Tanks Market Trends and Innovations
Material science and manufacturing process control are converging to produce thinner, lighter barrier structures without permeation performance degradation, reshaping competitive advantage around resin formulation precision rather than molding scale alone.
Sequential coextrusion with nanoclay-modified EVOH is miniaturizing barrier layer thickness from 2 millimeters to sub-millimeter specifications while maintaining hydrocarbon containment. Tier 1 suppliers serving Detroit and Stuttgart are adopting these structures for 2027 platform launches. This compression is enabling tank weight reductions of 15-20% beyond baseline HDPE advantages, shifting specification battles toward resin compound intellectual property.
REACH SVHC candidate list expansion is restricting certain plasticizers and flame retardants historically used in tank mounting hardware and grommet seals. Compounders in Rotterdam and Antwerp are reformulating masterbatches to exclude restricted substances ahead of 2026 sunset dates. European passenger vehicle programs face the tightest compliance windows, with German OEMs accelerating supplier qualification audits.
Fleet operators and leasing companies are unbundling tank replacement cycles from vehicle depreciation schedules, creating independent aftermarket demand for certified remanufactured units. Distributors in Texas, São Paulo, and Jakarta are building regional refurbishment centers to capture this disintermediated volume. The shift is most pronounced in commercial light truck segments where 150,000-mile tank replacement intervals now trigger standalone procurement events.
Plastic Fuel Tanks Market Segmentation
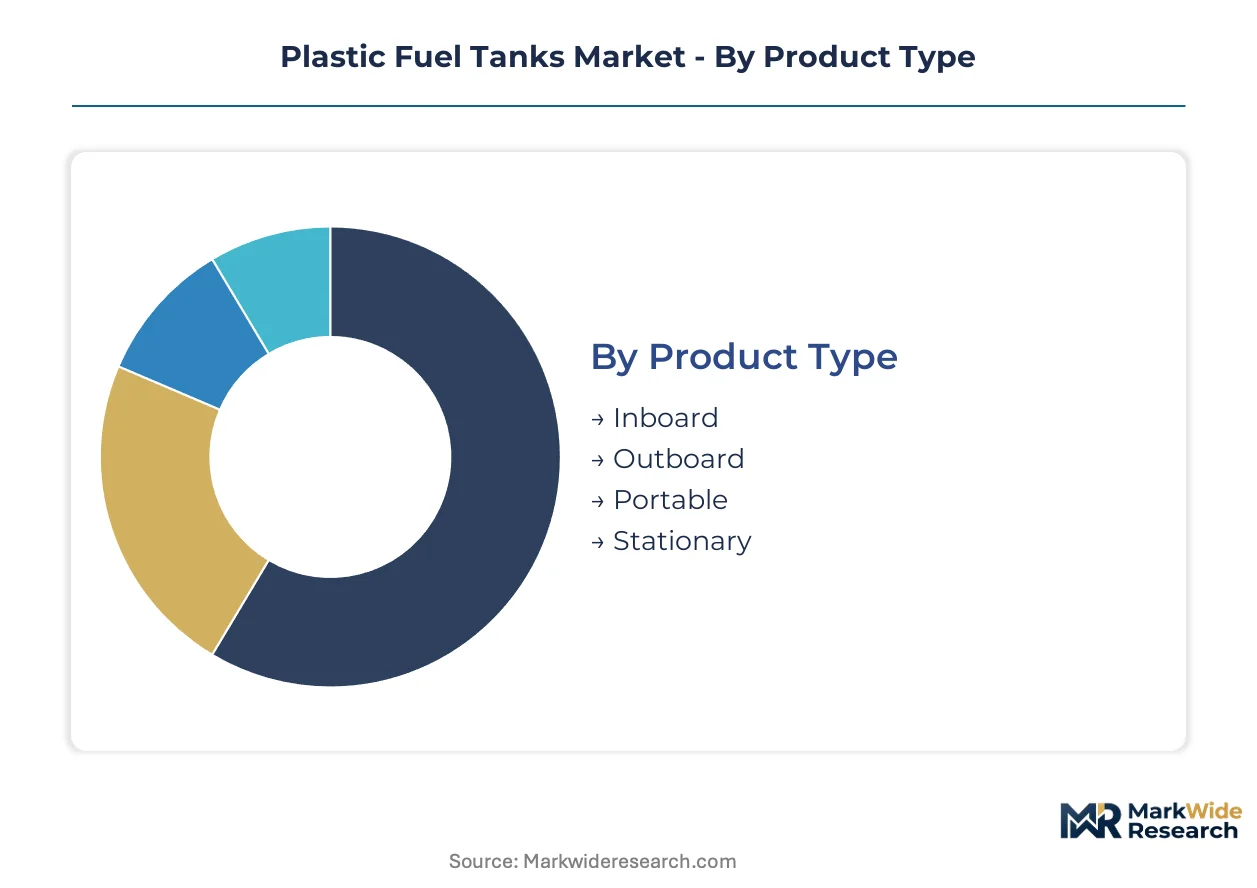
Segmentation in plastic fuel tanks determines which manufacturing footprints and certification pathways suppliers must maintain. Channel economics diverge sharply between automotive OEM direct supply and aftermarket distribution, shaping where converters invest coextrusion capacity versus blow-molding assets.
Product Type:
Inboard systems flow through Tier 1 automotive supply chains with long-term platform contracts, while portable and outboard variants reach end-users through marine distributors and outdoor power equipment retailers with seasonal demand patterns.
- Inboard:Multilayer HDPE/EVOH constructions dominate passenger vehicle and commercial truck applications, with six-layer coextrusion now standard for EPA permeation compliance. Demand concentrates in Michigan and Baden-Württemberg where Detroit and Stuttgart OEMs anchor high-volume programs.
- Portable:Blow-molded single-wall or dual-layer tanks serve recreational boating and outdoor power equipment, prioritizing weight reduction and UV stability over barrier performance. Florida, Queensland, and Mediterranean coastal markets drive replacement cycles as boat ownership expands.
- Outboard:Compact fuel systems integrate directly with marine engine packages, requiring saltwater corrosion resistance and vibration tolerance. Japanese outboard manufacturers in Shizuoka prefecture specify these for global distribution.
- Stationary:Large-capacity above-ground and underground installations serve agricultural and industrial bulk storage, emphasizing structural ribbing and chemical compatibility over permeation limits.
Inboard systems dominate installed base across vehicle parc volume. Portable tanks are where expansion concentrates as coastal tourism rebounds.
End User:
Cost tier segmentation separates specification-grade automotive programs from price-sensitive agricultural replacement markets, with marine and industrial occupying intermediate positions on technical compliance and margin structure.
- Automotive:OEM direct supply demands full PPAP validation, ECE R34 homologation, and zero-defect quality protocols for gasoline, diesel, and hybrid applications. German, Chinese, and US passenger vehicle production runs determine global volume allocation.
- Marine:Outboard motor manufacturers and boat builders require EPA and CARB evaporative emission certification alongside ABYC safety standards. Florida and Mediterranean basin distributors stock seasonal inventory ahead of spring launch cycles.
- Agricultural:Tractor and combine harvester producers prioritize diesel compatibility and field durability over permeation minutiae, with replacement demand cycling through Deere and CNH dealer networks.
- Industrial:Generator set and material handling equipment manufacturers specify tanks for stationary and mobile applications, with forklift producers in South Carolina and Bavaria driving niche volume.
Automotive commands the highest specification tier and captive supply relationships. Marine is climbing the fastest on post-pandemic recreational investment.
Material:
Volume concentration in polyethylene reflects automotive scale economics, while material substitution patterns track thermal load requirements and regulatory pressure on barrier performance.
- Polyethylene:HDPE remains the baseline substrate for blow-molded tanks, with density grades and UV stabilizer packages differentiated by application. Automotive programs in Germany and the United States consume the majority of barrier-enhanced HDPE compound production.
- Nylon:PA6 and PA66 formulations penetrate hybrid vehicle architectures where 80-90°C operating temperatures exceed HDPE thermal limits. Japanese and Korean OEM electrification roadmaps are accelerating qualification timelines.
- Polypropylene:PP homopolymer and copolymer grades compete in cost-sensitive portable tanks and select industrial applications, with lower density offering incremental weight savings.
- PVC:Limited to stationary agricultural and industrial bulk storage where chemical resistance and weldability outweigh permeation concerns, with restricted automotive adoption due to thermal and emission constraints.
Polyethylene anchors production scale across all major manufacturing regions. Nylon is gaining share fastest where powertrain electrification elevates thermal specifications.
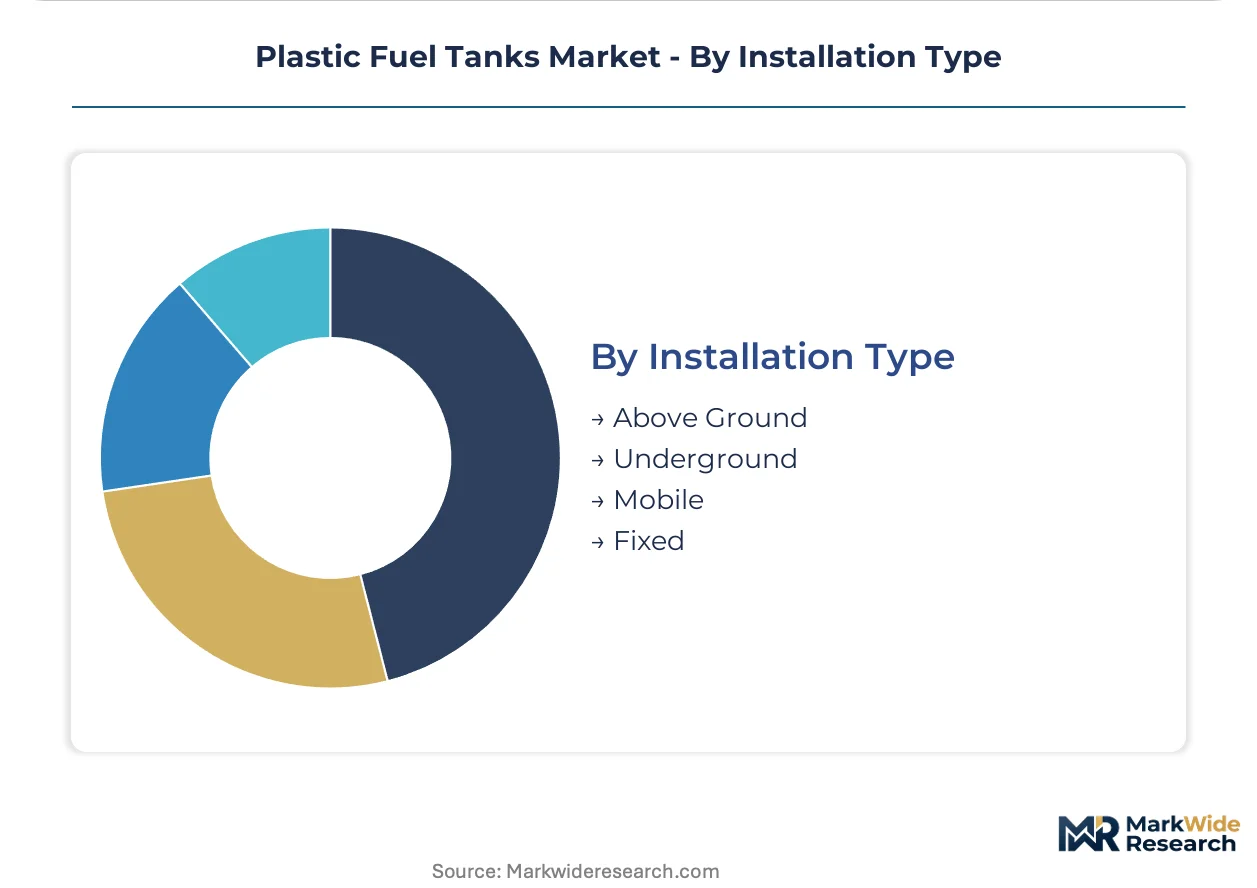
Installation Type:
Customer type segmentation distinguishes OEM-integrated mobile systems from aftermarket infrastructure projects, with diverging sales cycles and technical support requirements.
- Above Ground:Agricultural and industrial bulk tanks emphasize forklift accessibility and spill containment integration, with Texas and São Paulo distribution centers stocking standardized capacities.
- Underground:Stationary installations for retail fueling and fleet depots demand corrosion-resistant jackets and leak detection systems, with US EPA UST regulations and EU ATEX directives governing construction.
- Mobile:Vehicle-integrated tanks span automotive, marine, and portable equipment applications, with just-in-time delivery requirements constraining supplier geography to final assembly plant proximity.
- Fixed:Permanent industrial generator and heating oil installations prioritize seismic anchoring and fire-rated barriers, with Japanese building codes and German DIN standards shaping regional specifications.
Mobile systems dominate unit volume through automotive and equipment OEM integration. Underground installations are where specification value concentrates on compliance complexity and project scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese supply chains where barrier-layer coextrusion expertise commands premiums, while Chinese converters compete on scale economics for standard HDPE volumes. This asymmetry shapes where multilayer technology investments flow versus where commodity blow-molding capacity expands.
United States
Detroit automakers anchor HDPE tank demand through light truck and SUV production platforms. EPA 40 CFR Part 1060 permeation limits enforce six-layer EVOH construction for gasoline applications. Michigan-based Tier 1 suppliers operate dedicated coextrusion lines within 50 miles of final assembly plants to meet just-in-time delivery windows.
Germany
Stuttgart and Munich OEMs specify the highest barrier-performance tiers for premium passenger vehicle segments. EU F-Gas Regulation and REACH SVHC restrictions accelerate reformulation of masterbatches for mounting hardware. Baden-Württemberg compounders are qualifying bio-based HDPE feedstocks ahead of 2026 Green Deal procurement deadlines.
China
Domestic passenger vehicle production in Shanghai and Guangzhou drives polyethylene tank consumption at unmatched scale. SAMR-enforced GB standards on evaporative emissions align technical specifications with EPA and EU benchmarks. Yangtze River Delta molders are expanding capacity for hybrid vehicle applications where thermal loads favor nylon formulations.
Japan
Shizuoka-based outboard motor manufacturers specify compact fuel systems for global marine distribution. METI industrial standards shape flame-retardant and vibration-resistance requirements. Kanto region suppliers concentrate EVOH barrier-layer expertise that serves both domestic OEMs and export markets across Southeast Asia.
India
Two-wheeler and three-wheeler conversion to CNG and ethanol blends in Mumbai and Delhi creates localized blow-molding demand. BIS certification requirements for automotive fuel systems elevate technical entry barriers. Pune and Chennai manufacturing clusters are attracting first-mover investments from global Tier 1 suppliers seeking proximity to Bajaj Auto and TVS Motor assembly lines.
Plastic Fuel Tanks Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with barrier-layer coextrusion specialists commanding specification premiums while high-volume HDPE molders compete on resin throughput and logistics integration. The market structures around three tiers: integrated automotive suppliers with captive resin compounding, independent blow-molding specialists serving aftermarket and portable segments, and regional fabricators focused on single-layer agricultural and industrial tanks. Dominant competitive moves include backward integration into EVOH barrier resin supply and geographic co-location with OEM final assembly plants to compress delivery lead times.
Within the integrated automotive supplier tier, Plastic Omnium and Kautex Textron exemplify archetypes that combine resin formulation control with platform-level OEM relationships. Yachiyo Industry occupies a position representing Japanese-centered manufacturing expertise serving just-in-time delivery requirements across Asian markets. These three entities anchor the competitive landscape without exhausting its diversity, as independent specialists and regional fabricators continue to capture volume in portable, marine, and agricultural applications where specification complexity remains lower.
| Leading Market Players |
|---|
| Plastic Omnium |
| TI Fluid Systems |
| Kautex Textron |
| Yachiyo Industry |
| Magna International |
| YAPP Automotive |
| Unipres |
| Hanon Systems |
| Fuel Total Systems |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at six-layer coextrusion lines in Michigan and Baden-Württemberg shapes both supply concentration and price floors for barrier-enhanced tanks, compressing margins for converters without backward integration into EVOH resin supply.
Pricing Analysis
Configured-to-order six-layer HDPE/EVOH constructions command 40-60% premiums over standard single-wall portable tanks. Price differentiation hinges on EPA 40 CFR Part 1060 certification tier and volume scale, with automotive OEM direct contracts anchoring the premium band. Cost compression in standard HDPE blow-molding is intensifying because Chinese converters are expanding commodity capacity. Aftermarket agricultural buyers exhibit highest price sensitivity, while Stuttgart and Detroit OEMs prioritize zero-defect quality protocols over unit cost.
Supply Chain Analysis
Just-in-time inventory requirements constrain Tier 1 suppliers to locate within 50 miles of final assembly plants, compressing lead times to 4-6 hours for sequenced delivery. Geographic supply concentration centers on Germany, China, and the United States for multilayer automotive tanks, with Japan and Belgium anchoring EVOH barrier-layer production. Raw material dependencies draw from ethylene feedstocks, EVOH copolymers, and nanoclay modifiers. Single-source vulnerability in Japanese EVOH supply exposes converters to freight cost surges. Distribution runs through captive OEM supply chains for automotive, marine distributors for portable segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities are opening as powertrain electrification splinters demand across thermal-grade materials, creating specialist niches for nylon and polypropylene formulations alongside incumbent HDPE scale players.
For Market Incumbents: Secure barrier-layer resin supply through backward integration or long-term offtake agreements with Kuraray and Nippon Gohsei to defend against EVOH supply shocks. Add coextrusion capacity in the Yangtze River Delta to capture hybrid vehicle thermal-grade demand before qualification windows close. Full battery electric substitution represents the existential threat requiring range-extender hybrid platform capture as counterweight. For New Entrants and Emerging Players: Differentiate on bio-based HDPE feedstock certification to qualify for EU Green Deal procurement preferences in German and French OEM supply contracts. Target India's two-wheeler CNG conversion market in Pune and Chennai where BIS certification barriers are surmountable for localized blow-molding investments. Lead with smart tank telemetry integration as aftermarket retrofit value proposition for connected fleet operators. For Investors and Strategic Acquirers: Independent blow-molding specialists with marine and portable equipment certification offer acquisition targets at favorable multiples before coastal tourism rebound fully prices in. Long-term viability hinges on material science IP position rather than molding scale alone. Watch California Air Resources Board zero-emission vehicle mandate acceleration as inflection signal for range-extender hybrid tank demand versus full battery platform extinction.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier-Layer Backward Integration | Captive EVOH supply from Kuraray insulates Kautex Textron from freight volatility. |
| Bio-Based HDPE Qualification | Braskem renewable feedstock certification unlocks BMW and Mercedes procurement preferences. |
| Smart Tank Telemetry Integration | Level sensor convergence with molded reservoirs creates aftermarket retrofit demand. |
| India Localized Capacity Buildout | Pune blow-molding proximity to Bajaj Auto captures CNG conversion volume. |
| Nylon Formulation R&D Investment | PA66 thermal-grade development qualifies suppliers for Hyundai-Kia hybrid platforms. |
Research Methodology
Desk research of EPA certification databases, vehicle production registries, and customs trade data preceded structured interviews with Tier 1 supplier procurement directors, OEM platform engineers, blow-molding plant managers, and marine equipment distributors. Primary fieldwork across Michigan, Baden-Württemberg, and Guangdong validated secondary estimates. Bottom-up tank unit projections and top-down automotive production triangulation anchored value estimates.
Variance decomposition across material grade, end-use segment, vehicle propulsion architecture, and regional production cluster shaped the analytical framework. CAGRs were derived from segment-level volume buildups and price trajectory assumptions. Hybrid powertrain thermal load specifications and EPA permeation standard enforcement timelines served as industry-specific forecast inputs across the projection horizon.
Material uncertainties — ethylene feedstock volatility, BEV adoption pace, and EVOH supply disruption — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and OEM platform cycle continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Plastics Market
Automotive Parts
Automotive Composite Leaf Springs Market
Automotive Parts
Automotive Radiator Hose Market
Automotive Parts
Bumper Beam Market
Automotive Parts
Norway Automotive Engine Oils Market
Automotive Parts
Automotive Paint Robots Market
Automotive Parts
Latin America Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Fastener Market
Automotive Parts
Global Automotive Flywheel Market
Automotive Parts
Automotive Cooling Fan Market
Automotive Parts
Electric Power Steering System (EPS) Market
Automotive Parts
Automotive Crankshaft Materials Market
Automotive Parts
US Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Fuel Accumulator Market
Automotive Parts
Diesel Oxidation Catalyst Market
Automotive Parts
Automotive Steering System Market