
 Russia Automotive Actuators Market | 2026-2036
Russia Automotive Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Automotive Actuators Market Analytics
The Russia automotive actuators landscape is restructuring around a widening gap between premium precision systems and commodity-grade mechanical units. Continental AG leverages its integrated electronics-actuator platforms to dominate higher-margin chassis applications. Robert Bosch GmbH sustains broad coverage across powertrain and safety segments through extensive localized engineering support. Marelli Holdings Co., Ltd specializes in compact electric actuator designs for interior climate and seating modules, occupying a distinct tier below the full-system integrators.
Russia automotive actuators are electromechanical, hydraulic, pneumatic, or mechanical devices that convert control signals into precise physical motion, typically operating at voltage ranges from 12V to 48V in passenger and commercial vehicles, with response times measured in milliseconds for safety-critical functions. Their primary purpose is to execute commanded adjustments in engine management, braking, steering, and occupant comfort systems with repeatable accuracy under thermal and vibrational stress. Electric actuators lead the product type landscape due to compatibility with electrified powertrains and simplified control architectures, while hydraulic actuators retain structural share in heavy-duty chassis applications where force density requirements exceed electric alternatives. Among end users, OEMs and Tier-1 Suppliers capture the dominant procurement volume, though aftermarket providers are gaining relevance as Russia's vehicle parc ages and replacement cycles compress.
Russia's TR CU 018/2011 technical regulation on wheeled vehicle safety, administered by Rosstandart, shapes actuator demand by mandating electromagnetic compatibility and environmental durability testing that favors suppliers with certified laboratory networks. The EAEU's common conformity assessment framework further conditions market access, requiring component-level documentation that smaller importers struggle to assemble. Stakeholders must monitor how Russia's evolving localization requirements under industrial policy decrees reshape supplier qualification criteria and sourcing geography.
Market Dynamics
Russia's automotive actuators sector is restructuring around electrification-driven powertrain complexity and the enforcement of TR CU 018/2011 certification standards, which compress supplier margins while elevating technical barriers for new entrants.
Growth Catalysts
- Passenger vehicle electrification:Battery-electric and hybrid powertrains require expanded actuator deployment for thermal management, battery contactors, and regenerative braking systems, creating incremental demand across Moscow's manufacturing corridor.
- TR CU 018/2011 enforcement:Rosstandart's mandatory electromagnetic compatibility and environmental durability testing favors suppliers with certified laboratory networks, consolidating procurement toward pre-qualified Tier-1 integrators.
- Climate control module sophistication:Multi-zone HVAC systems in premium vehicles deploy compact electric actuators for flap positioning and vent modulation, extending actuator counts per vehicle.
Market Restraints
- Semiconductor input volatility:Actuator control electronics depend on automotive-grade microcontrollers and power MOSFETs subject to allocation constraints and price instability, compressing gross margins for electromechanical actuator producers.
- Supply concentration in Germany and China:Precision motor and sensor subcomponents flow through a narrow supplier base concentrated in Baden-Württemberg manufacturing clusters and Shenzhen electronics corridors, exposing Russian assemblers to transit disruption risk.
- Hydraulic actuator displacement ceiling:Electric alternatives face force-density limitations in heavy-duty commercial chassis applications above 16-tonne gross vehicle weight, preserving hydraulic incumbent positions in long-haul trucking.
Strategic Opportunities
- Kaluga and Tatarstan supplier zones:Industrial policy decrees incentivize component localization through preferential tariff treatment and subsidized industrial park occupancy, creating greenfield actuator assembly opportunities for qualified investors.
- Aftermarket channel expansion:Russia's aging vehicle parc, concentrated in 2012-2018 production vintages, compresses replacement cycles for door lock, headlamp leveling, and throttle body actuators, elevating independent service channel relevance.
- Smart actuator convergence:Integration of position sensing, local processing, and LIN/CAN communication into single electromechanical units enables predictive maintenance data streams and reduces wiring harness complexity for OEMs.
Industry Challenges
- Embedded software certification timelines:Functional safety validation under ISO 26262 for safety-critical brake and steering actuators extends development cycles and requires specialized verification engineering capacity scarce in the Russian labor market.
- Legacy powertrain integration friction:Electrified actuator architectures must maintain backward compatibility with internal combustion vehicle platforms still dominating Russian production volumes, forcing dual-design engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Automotive Actuators Market |
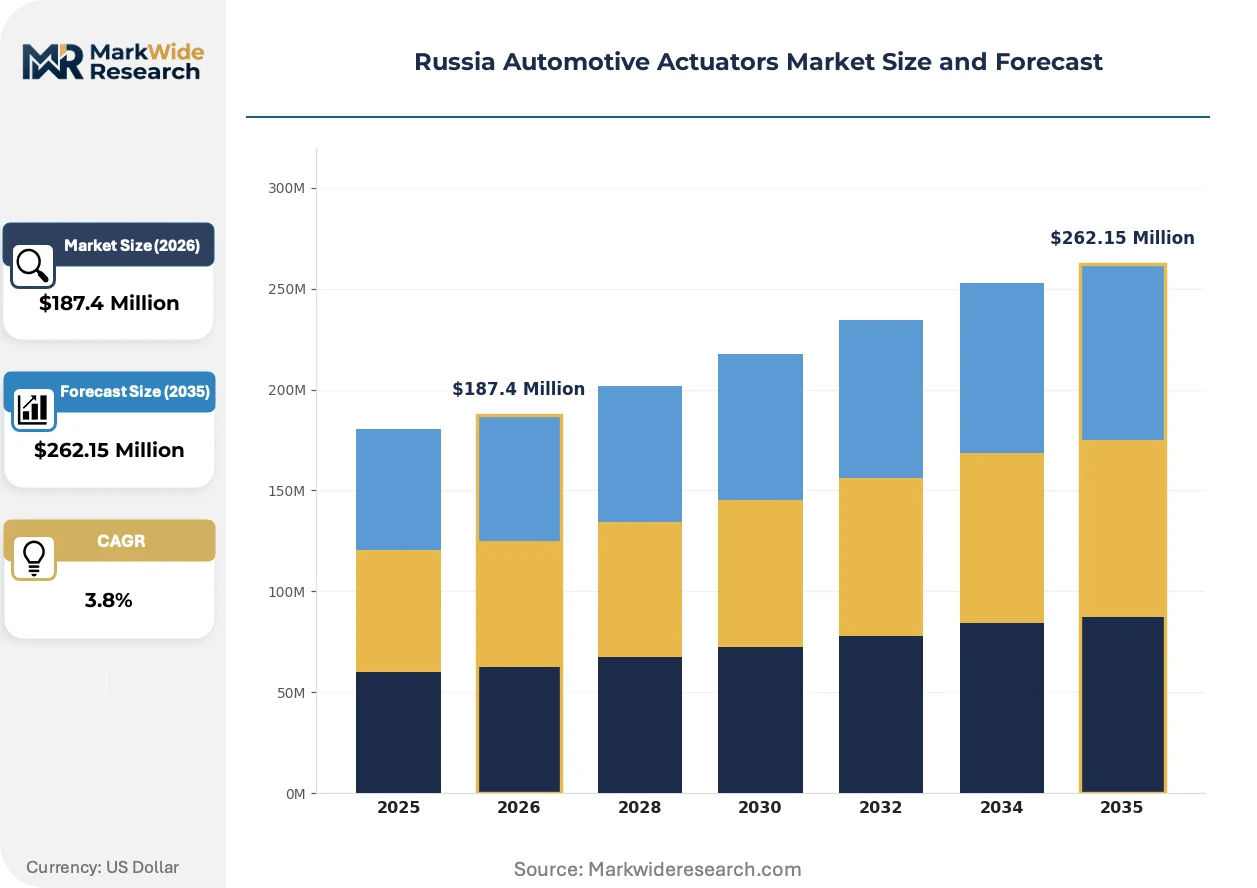
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Actuators, Hydraulic Actuators, Pneumatic Actuators, Mechanical Actuators End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Powertrain, Chassis, Interior, Safety Systems Technology: Positioning Technology, Control Technology, Feedback Systems, Communication Protocols |
| Companies Covered | Denso Corporation, Robert Bosch GmbH, Continental AG, Nidec Corporation, Hitachi Ltd, Mitsubishi Electric Corporation, ZF Friedrichshafen AG, HELLA GmbH & Co. KGaA, Marelli Holdings Co., Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Automotive Actuators Market Evolving Landscape
Electrification and localized intelligence are reshaping actuator architecture, compressing the traditional separation between mechanical motion and electronic control while forcing suppliers to absorb software development burdens previously borne by vehicle manufacturers.
Smart actuators with integrated position sensing and edge computing capability are decentralizing control authority away from centralized body control modules. Tier-1 suppliers in St. Petersburg's electronics corridor are adopting these units for seat adjustment and mirror positioning applications. This shift reduces wiring harness mass and enables closed-loop calibration without manufacturer-specific programming tools.
Rosstandart's phased implementation of updated electromagnetic compatibility test protocols under TR CU 018/2011 is accelerating laboratory certification investments. Domestic actuator producers must demonstrate immunity to conducted and radiated disturbances across expanded frequency ranges. The chassis and safety actuator segments face the steepest compliance cost escalation, prompting consolidation among smaller electromagnetic component suppliers.
Fleet operators and leasing companies are compressing specification cycles by demanding modular actuator platforms compatible across multiple vehicle generations. This procurement pattern favors suppliers offering standardized mechanical interfaces with configurable electronic personalities. The commercial vehicle segment around Nizhny Novgorod exhibits the most pronounced preference for interchangeable actuator families that reduce spare parts inventory carrying costs.
Russia Automotive Actuators Market Segmentation
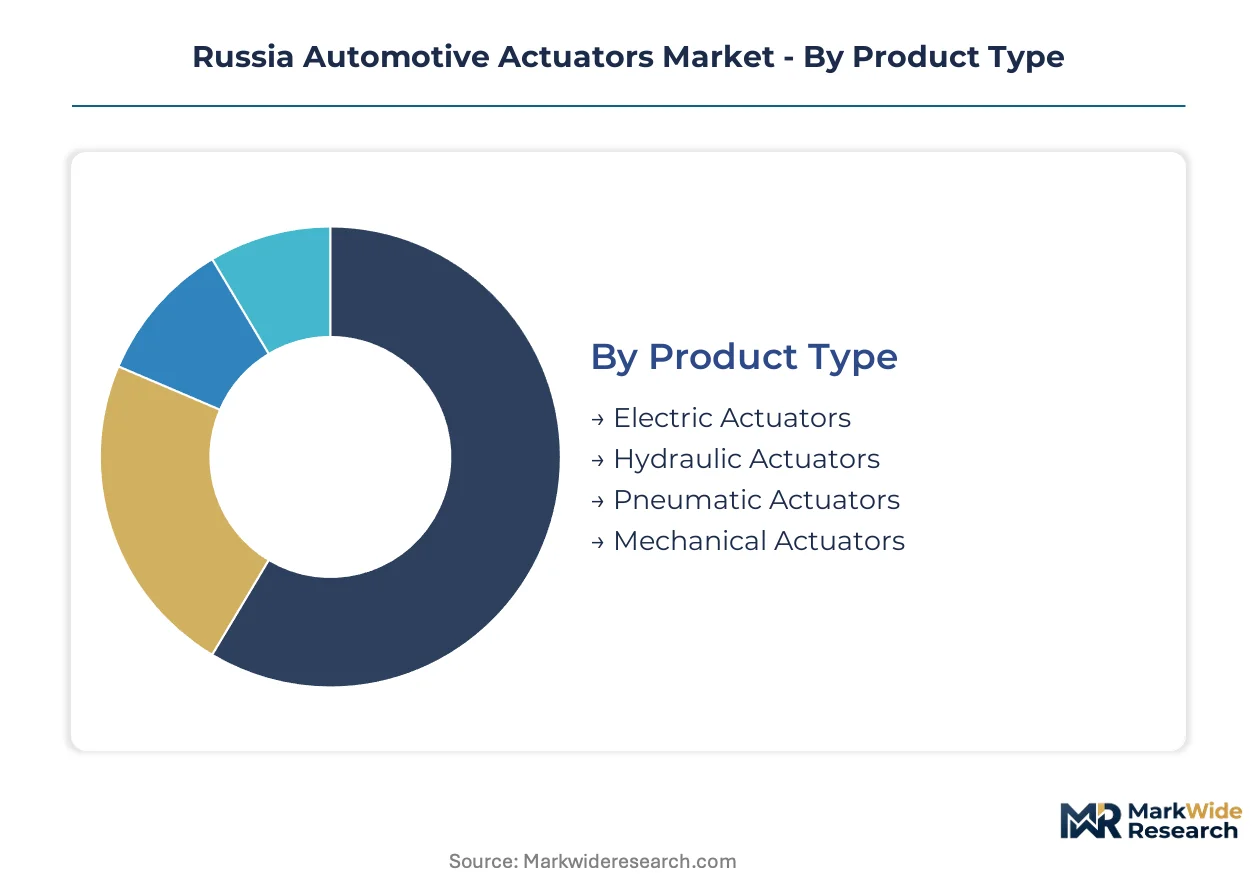
Segmentation in Russia's automotive actuators market reveals how TR CU 018/2011 certification requirements concentrate procurement toward specific product architectures and customer tiers. Suppliers must align their technical portfolios with the electromagnetic compatibility and durability standards that Rosstandart enforces across each segment boundary.
Product Type:
TR CU 018/2011 mandates distinct certification pathways for each actuator technology, with electric variants facing the most stringent electromagnetic compatibility testing while hydraulic units confront environmental durability protocols.
- Electric Actuators:These 12V-48V electromechanical units convert electrical signals into precise linear or rotary motion through brushless DC motors and lead-screw mechanisms. Moscow's passenger vehicle electrification corridor drives concentrated demand for thermal management and battery contactor actuators, though semiconductor input volatility constrains margin expansion for producers.
- Hydraulic Actuators:Fluid-power systems utilizing pressurized oil to generate high force density for chassis and heavy-duty applications. St. Petersburg's commercial vehicle supplier base sustains procurement for 16-tonne-plus gross vehicle weight platforms where electric alternatives lack sufficient torque output.
- Pneumatic Actuators:Compressed-air systems deployed primarily in braking assistance and suspension leveling for heavy trucks operating across Russia's road infrastructure.
- Mechanical Actuators:Cable and linkage-based motion transfer mechanisms retaining cost-sensitive positions in entry-level vehicle interior adjustments.
Electric Actuators sits at the top of the volume ranking, with Pneumatic Actuators climbing the fastest as fleet operators seek simplified maintenance architectures.
End User:
Cost tier differentiation separates procurement patterns, with premium specification actuators flowing through integrated Tier-1 channels while commodity units serve price-sensitive aftermarket channels.
- OEMs:Original equipment manufacturers in Moscow's manufacturing cluster specify actuators during platform development, absorbing full TR CU 018/2011 certification costs into vehicle homologation budgets.
- Tier-1 Suppliers:Full-system integrators such as chassis module and powertrain assembly specialists consolidate component procurement and manage regulatory documentation on behalf of vehicle manufacturers.
- Aftermarket Providers:Independent distributors and service chains targeting Russia's aging 2012-2018 vehicle parc with replacement door lock, headlamp leveling, and throttle body actuators.
- Vehicle Assemblers:Contract manufacturing operations in Kaluga and Tatarstan industrial zones sourcing actuators under localization decree incentives.
Tier-1 Suppliers commands the dominant procurement volume, with Aftermarket Providers expanding most quickly as replacement cycles compress.
Application:
Application scope determines margin structure, with safety-critical and chassis functions commanding premium pricing against interior comfort modules.
- Powertrain:Engine management actuators for throttle control, turbocharger wastegate positioning, and transmission shift mechanisms. Kaluga's engine manufacturing cluster generates concentrated demand as electrified architectures require expanded thermal management actuator deployment.
- Chassis:Suspension leveling, active damping, and steer-by-wire systems where ISO 26262 functional safety validation extends development timelines and elevates engineering costs.
- Interior:Seat adjustment, HVAC flap positioning, and mirror folding actuators with shorter specification cycles and modular platform compatibility requirements.
- Safety Systems:Brake-by-wire and autonomous emergency braking actuators facing the steepest Rosstandart electromagnetic immunity test protocol escalation.
Powertrain holds the largest volume position, with Safety Systems gaining share fastest as autonomous driving feature penetration advances.
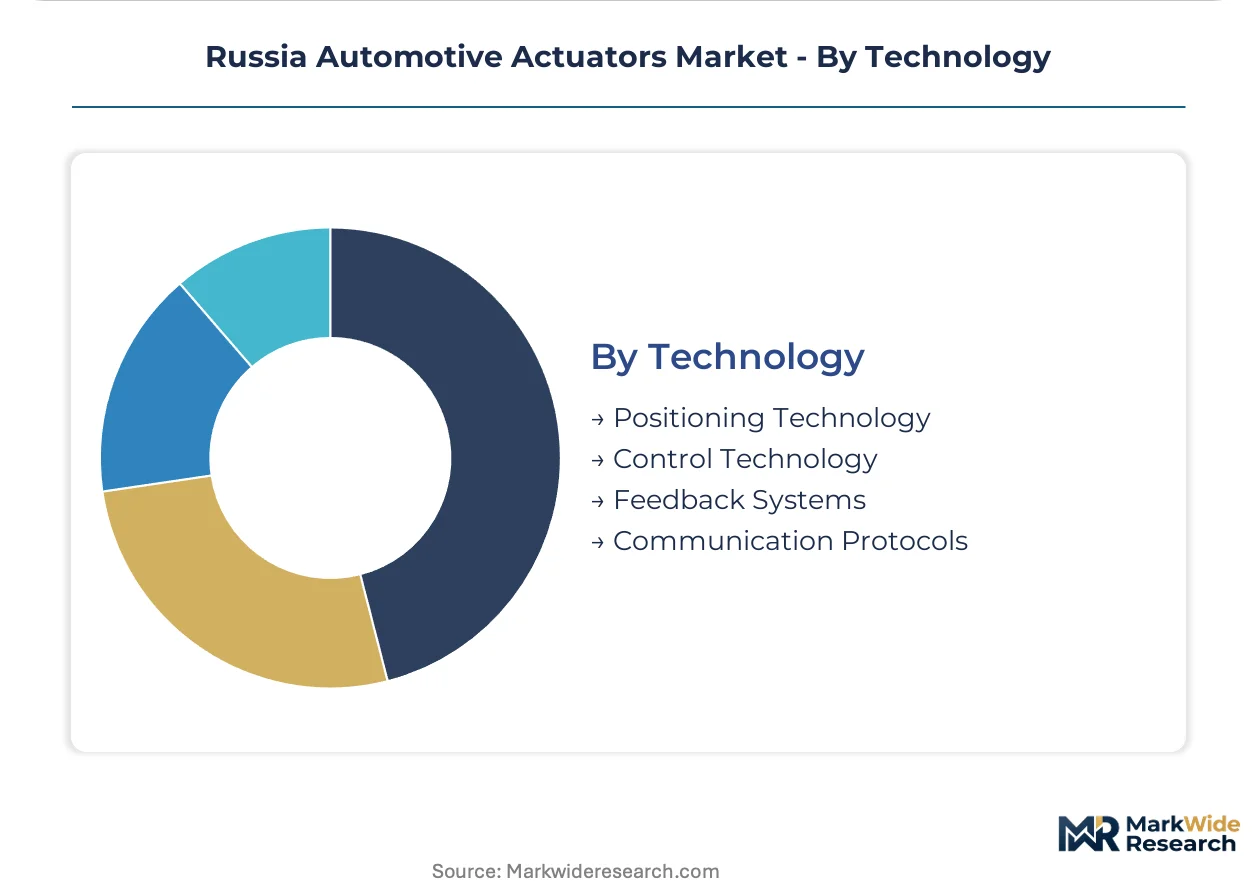
Technology:
Technology architecture maturity separates established positioning and control layers from emerging feedback and communication integration.
- Positioning Technology:Hall-effect sensors, potentiometers, and optical encoders delivering closed-loop position verification for safety-critical functions.
- Control Technology:Embedded microcontrollers and motor driver integrated circuits executing PID algorithms for motion profiling.
- Feedback Systems:Integrated torque and current sensing enabling predictive maintenance data streams and stall detection.
- Communication Protocols:LIN and CAN bus interfaces decentralizing control authority from centralized body modules toward smart actuator edge computing.
Control Technology maintains the highest deployment volume, with Communication Protocols showing the steepest expansion trajectory as wiring harness simplification drives OEM preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent concentrates in Moscow's automotive corridor and St. Petersburg's electronics manufacturing belt, anchoring Russia's actuator production capacity. Regional demand patterns diverge sharply between electrified passenger vehicle clusters and heavy-duty commercial vehicle zones.
Central Federal District
Moscow's manufacturing corridor drives premium electric actuator procurement for battery thermal management and powertrain electrification. Rosstandart's TR CU 018/2011 certification enforcement channels procurement toward pre-qualified Tier-1 integrators with certified laboratory networks. Kaluga's industrial park hosts foreign component assembly operations benefiting from localization decree incentives.
Northwestern Federal District
St. Petersburg's supplier base sustains hydraulic actuator demand for heavy commercial chassis above 16-tonne gross vehicle weight. The region's electronics manufacturing heritage supports smart actuator development with integrated LIN/CAN communication protocols. Local engineering capacity concentrates on chassis and safety system validation under ISO 26262 functional safety standards.
Volga Federal District
Nizhny Novgorod's commercial vehicle assembly operations generate fleet procurement of modular actuator platforms compatible across multiple vehicle generations. Industrial policy decrees incentivize component localization through preferential tariff treatment. The region's automotive heritage supports aftermarket channel expansion for aging 2012-2018 vehicle parc replacement cycles.
Southern Federal District
Rostov-on-Don's transport logistics hub creates aftermarket demand for door lock, headlamp leveling, and throttle body actuators serving Russia's aging vehicle fleet. Regional distributors consolidate procurement from Moscow-based Tier-1 suppliers. Climate control module sophistication drives compact electric actuator deployment in premium vehicle segments.
Volga Federal District — Tatarstan
Kazan and Naberezhnye Chelny's industrial zones attract greenfield actuator assembly investments under subsidized industrial park occupancy schemes. The region's polymer and materials processing capacity supports actuator housing and gear train component manufacturing. Localization requirements reshape supplier qualification criteria toward domestic value-added thresholds.
Russia Automotive Actuators Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Russia's automotive actuators sector, with integrated system houses holding structural advantages in certification-intensive safety applications. The market structure tilts toward consolidation as TR CU 018/2011 electromagnetic compatibility testing eliminates smaller electromagnetic component suppliers. Three archetypes dominate: full-system integrators managing regulatory documentation on behalf of OEMs; component specialists supplying compact electric designs for interior modules; and diversified industrial conglomerates leveraging cross-sector manufacturing scale. Competitive moves center on laboratory certification investments and localization partnerships in Kaluga and Tatarstan industrial zones.
Within the full-system integrator tier, Continental AG and Robert Bosch GmbH occupy positions defined by integrated electronics-actuator platforms and localized engineering support coverage. Marelli Holdings Co., Ltd. exemplifies the compact electric actuator specialist archetype, concentrating on interior climate and seating modules beneath the full-system integrator tier. These three entities anchor the competitive structure through distinct technical positioning and customer tier alignment.
| Leading Market Players |
|---|
| Denso Corporation |
| Robert Bosch GmbH |
| Continental AG |
| Nidec Corporation |
| Hitachi Ltd |
| Mitsubishi Electric Corporation |
| ZF Friedrichshafen AG |
| HELLA GmbH & Co. KGaA |
| Marelli Holdings Co., Ltd |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between TR CU 018/2011-compliant precision systems and uncertified commodity units manifests in divergent pricing architectures and sourcing geographies across Russia's automotive actuators sector. Premium electric actuators for chassis and safety applications command substantial markups through bundled engineering support and regulatory documentation, while commodity mechanical units flow through price-transparent aftermarket channels with minimal value-added services.
Pricing Analysis
Bundled certification and engineering services versus unbundled component-only transactions defines the dominant pricing split in Russia's actuator market. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels separates procurement channels, with TR CU 018/2011 electromagnetic compatibility validation serving as the primary price differentiation driver alongside localized technical support availability. Cost compression in economy-tier mechanical actuators is intensifying because aftermarket distributors consolidate purchasing power, while OEM procurement of safety-critical units exhibits lowest price sensitivity due to homologation risk exposure.
Supply Chain Analysis
Direct-to-OEM channels handle high-volume platform contracts, while specialized distributors serve fragmented aftermarket demand across Russia's federal districts. Precision motor and sensor subcomponents draw from manufacturing clusters in Germany, China, and South Korea, with semiconductor-dependent control electronics resting on concentrated foundry capacity in Taiwan and mainland China. Single-source vulnerability in automotive-grade microcontroller supply creates structural exposure to allocation constraints. Distribution runs through Tier-1 system integrators managing regulatory documentation on behalf of vehicle manufacturers in Moscow and St. Petersburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's automotive actuators market functions as a stable compounder, with vehicle electrification and regulatory compliance mandates generating persistent demand for certified precision components across the projection horizon.
For Market Incumbents: To counter semiconductor input volatility and margin compression in electromechanical actuator lines, prioritize backward integration into motor and gear train manufacturing through partnerships in Tatarstan's subsidized industrial zones. Expand certified laboratory networks to capture TR CU 018/2011 documentation revenue streams from smaller competitors lacking compliance infrastructure. For New Entrants and Emerging Players: The premium-to-economy price gap in interior comfort actuators offers accessible entry points beneath Continental AG and Robert Bosch GmbH's full-system integration tier. Target aftermarket channel expansion for 2012-2018 vehicle parc replacement cycles, particularly door lock and headlamp leveling applications where certification requirements remain minimal. Pursue white-label manufacturing partnerships with St. Petersburg electronics houses to bypass capital-intensive laboratory investments. For Investors and Strategic Acquirers: Consolidation pressure builds where TR CU 018/2011 certification costs eliminate sub-scale electromagnetic component suppliers unable to fund expanded immunity testing protocols. Long-term viability favors asset-light designers with established OEM relationships over capital-heavy producers exposed to raw material volatility. Monitor Rosstandart's phased implementation of updated electromagnetic compatibility test protocols as the critical inflection signal for laboratory capacity valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Localization Partnership in Kaluga Industrial Zone | Preferential tariff treatment under industrial policy decrees reduces landed cost for German and Japanese component suppliers. |
| Smart Actuator Platform Development | Integration of LIN/CAN communication protocols enables predictive maintenance data streams for Moscow-based fleet operators. |
| Certified Laboratory Network Expansion | Rosstandart's TR CU 018/2011 electromagnetic immunity requirements create recurring revenue from regulatory documentation services. |
| Aftermarket Channel Distributor Acquisition | Rostov-on-Don's logistics hub consolidates procurement for aging 2012-2018 vehicle parc replacement cycles. |
| Polymer Housing Manufacturing Joint Venture | Tatarstan's materials processing capacity supports actuator gear train component localization under domestic value-added thresholds. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and Rosstandart certification specialists with secondary validation against vehicle production databases, EAEU customs records, and industrial policy decree filings. Bottom-up actuator shipment estimates triangulated against top-down vehicle assembly projections across Moscow, St. Petersburg, Kaluga, and Tatarstan production clusters.
Segment-weighting approaches distributed volume and value estimates across electric, hydraulic, pneumatic, and mechanical product types, further disaggregated by powertrain, chassis, interior, and safety system applications. CAGRs were derived from regression analysis of historical production correlations with vehicle assembly trends, incorporating electrification penetration assumptions and TR CU 018/2011 compliance cost trajectories across the analysis window. Propulsion architecture transitions and content-per-vehicle expansion for thermal management served as primary forecast inputs.
Caveats apply where semiconductor allocation constraints, transit disruption through Baltic corridor logistics, or Rosstandart regulatory enforcement intensity could materially shift the outlook. Forecasts reflect documented assumptions regarding electrification pace and localization decree implementation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Nigeria Automotive Engine Oils Market
Automotive Parts
Automotive Differential Housing Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
Mexico Automotive Air Filters Market
Automotive Parts
Germany Automotive Parts Zinc Die Casting Market
Automotive Parts
Cheetah Friction Reduction Technologies Market
Automotive Parts
France Automotive Parts Magnesium Die Casting Market
Automotive Parts
Engine Oil Market
Automotive Parts
Mexico Automotive Parts Zinc Die Casting Market
Automotive Parts
Camshaft Lifters Market
Automotive Parts
Europe Industrial Roller Chain Drive Market
Automotive Parts
South Africa Automotive Lubricants Market
Automotive Parts
US Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive AHSS Market
Automotive Parts
Argentina Passenger Vehicles Lubricants Market
Automotive Parts
Australia Automotive Parts Magnesium Die Casting Market