
 Global Automotive Engine Belt and Hose Market | 2026-2036
Global Automotive Engine Belt and Hose Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Engine Belt and Hose Market Foresight
Commercial fleet operators are unwinding their historical preference for low-cost aftermarket belts toward OEM-specification timing and serpentine systems. Gates Corporation leverages its captive compound development to sustain margin leadership in reinforced EPDM formulations. Continental AG anchors European supply through integrated hose extrusion and crimping operations. Yokohama Rubber Co Ltd competes aggressively in Asia-Pacific via specialized fluoroelastomer fuel hose production for turbocharged engines.
Automotive engine belts and hoses are elastomeric power transmission and fluid conveyance components, typically fabricated from ethylene propylene diene monomer or hydrogenated nitrile butadiene rubber with aramid or polyester tensile reinforcement, designed to operate across temperature ranges from minus forty to one hundred fifty degrees Celsius while resisting ozone, coolant, and hydrocarbon exposure. Their primary purpose is to synchronize crankshaft and camshaft rotation, drive accessory systems, and circulate coolant, fuel, and vacuum within internal combustion propulsion systems. Serpentine belt demand leads volume as multi-rib designs consolidate former V-belt and separate accessory belt architectures across passenger and commercial vehicle platforms. Thermoplastic elastomer formulations represent the fastest-expanding material category by growth rate, displacing conventional chloroprene in select heater and vacuum hose applications where weight reduction targets dominate OEM specifications. Timing belts command premium positioning due to molded tooth precision requirements and the catastrophic failure cost profile associated with interference engine designs.
EPA tailpipe standards and NHTSA fuel economy mandates in the United States compel OEMs to specify extended-life belt and hose systems that withstand elevated underhood thermal loads from downsized turbocharged powertrains. EMA and REACH frameworks in Europe restrict phthalate plasticizers and short-chain chlorinated paraffins in rubber compounding, forcing reformulation investments across the supplier base. China's MIIT and GB standards enforce localization ratios and material traceability for engine ancillary components. Stakeholders must monitor how electrification transition timelines alter belt and hose content per vehicle, particularly the elimination of serpentine architectures in dedicated battery electric platforms and the emergence of thermal management hose demand in coolant circuit-intensive hybrid designs.
Market Dynamics
The electrification transition is bifurcating demand trajectories: dedicated battery electric platforms eliminate serpentine belt architectures entirely, while hybrid powertrains intensify thermal management hose specifications through more complex coolant circuits. This structural divergence forces suppliers to simultaneously manage content erosion and specification escalation across overlapping customer bases.
Growth Catalysts
- EPA emissions enforcement:Commercial fleet operators in the United States face intensified durability requirements, accelerating procurement of EPDM-based coolant hoses rated for extended service intervals under elevated thermal loads.
- BIS quality mandates:India's Bureau of Indian Standards mandates localized testing protocols for engine ancillary components, creating captive demand for domestic belt and hose manufacturing capacity.
- PLI scheme for auto components:India's production-linked incentive framework subsidizes capital equipment for rubber compounding and extrusion, attracting greenfield investments in timing belt and reinforced hose production.
Market Restraints
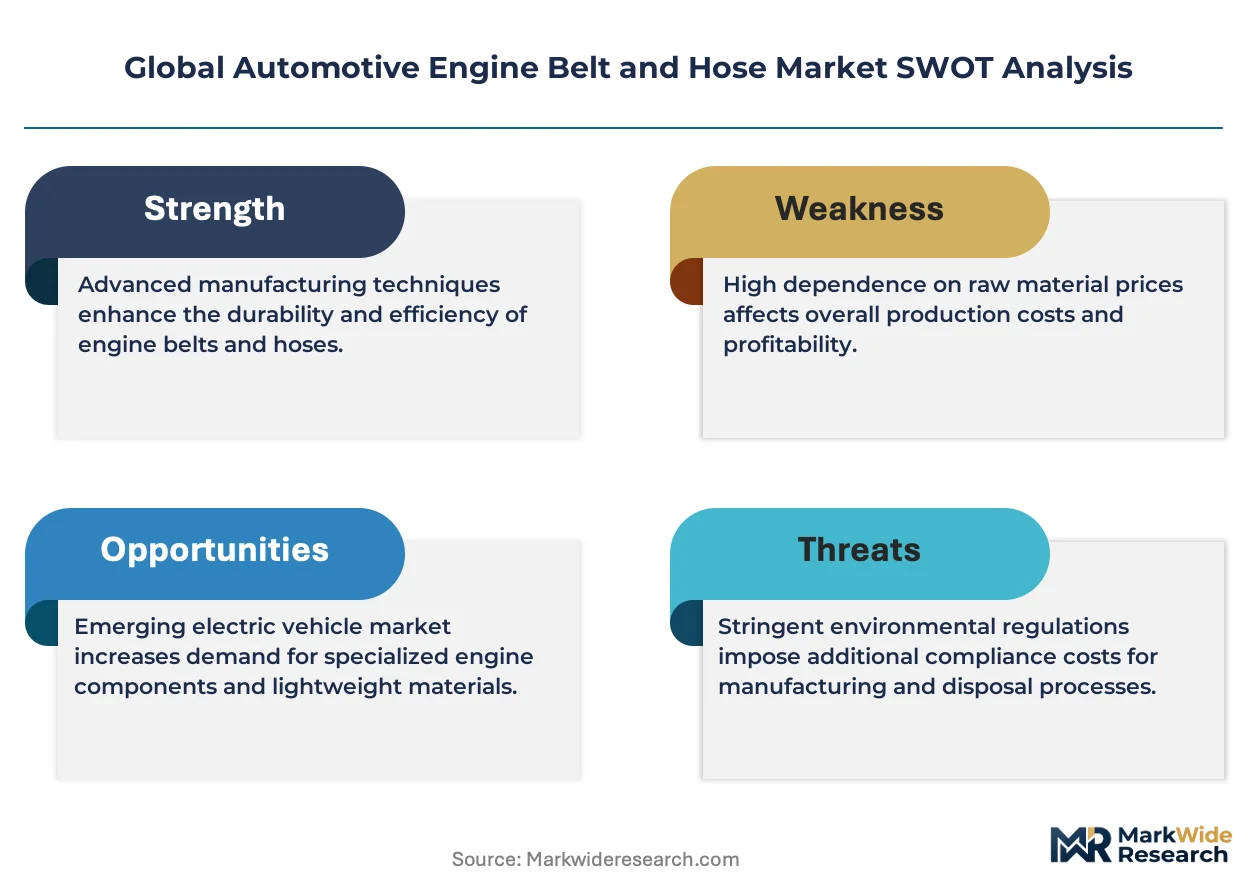
- Raw material volatility:EPDM polymer and aramid fiber prices fluctuate with ethylene-propylene feedstock markets, compressing compounder margins during crude oil price spikes.
- REACH chemical restrictions:ECHA regulations on phthalate plasticizers and short-chain chlorinated paraffins force costly reformulation of legacy rubber compounds without immediate price recovery mechanisms.
- Platform-specific demand collapse:Dedicated battery electric vehicle architectures eliminate serpentine belt content entirely, stranding capacity investments tied to internal combustion accessory drive systems.
Strategic Opportunities
- Hybrid thermal management expansion:Coolant circuit-intensive hybrid designs require specialized hose architectures for battery pack conditioning, creating specification premiums above conventional internal combustion applications.
- Thermoplastic elastomer displacement:TPV and TPE compounds penetrate heater and vacuum hose segments where OEM weight reduction targets override historical chloroprene specifications.
- Fluoroelastomer fuel hose specialization:Turbocharged direct-injection gasoline engines operating at higher fuel pressures demand FKM-lined hoses resistant to aromatic hydrocarbon permeation.
Industry Challenges
- Compound formulation expertise scarcity:Hydrogenated nitrile butadiene rubber compounding for high-temperature timing belt applications requires specialized polymer science capabilities concentrated among legacy suppliers.
- Multi-standard certification timelines:Simultaneous compliance with EPA durability protocols, EMA chemical restrictions, and MIIT localization ratios extends product qualification cycles by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Engine Belt and Hose Market |
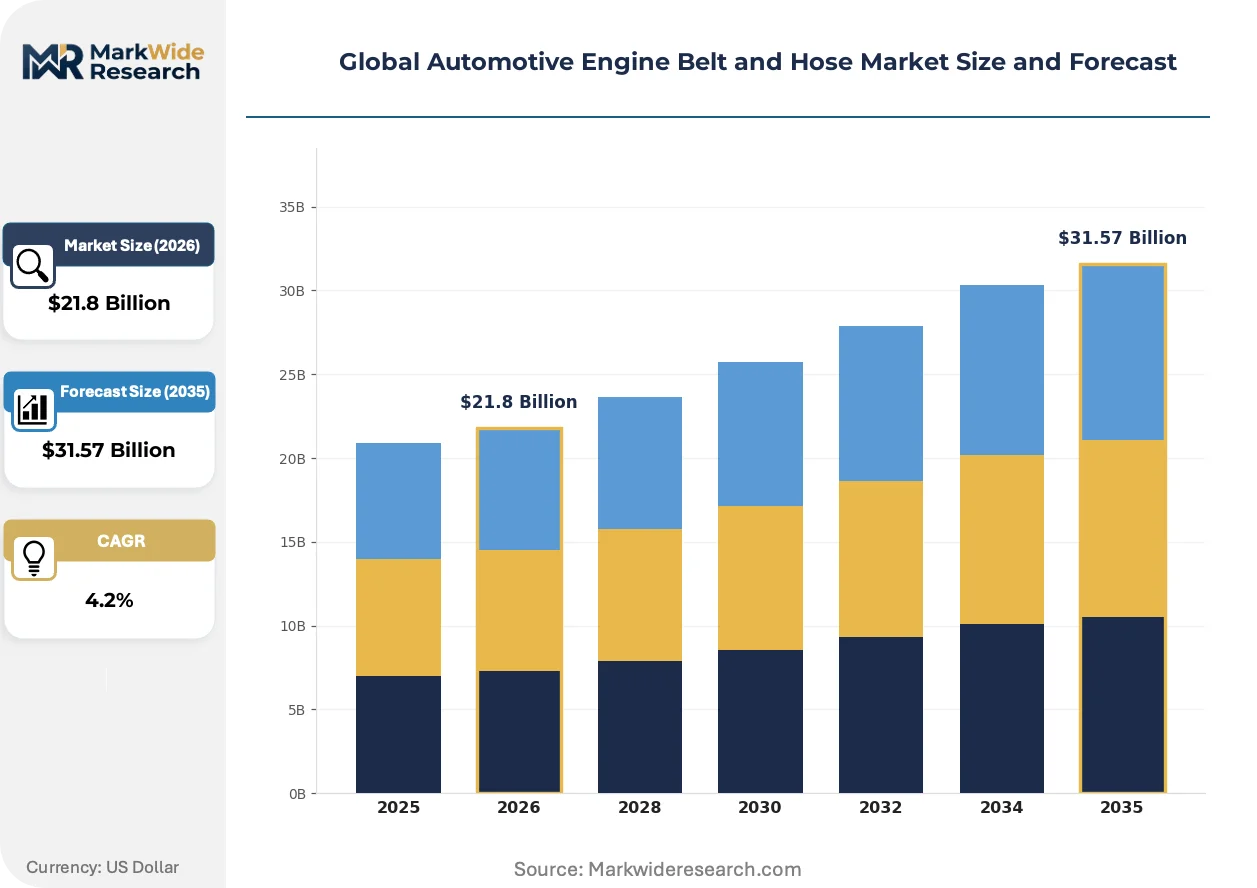
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $31.57 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Timing Belts, Serpentine Belts, Radiator Hoses, Heater Hoses, Fuel Hoses, Vacuum Hoses Material: Rubber, Reinforced Rubber, Silicone, Neoprene, EPDM, Thermoplastic Elastomers Application: Passenger Vehicles, Commercial Vehicles, Off-Highway Vehicles, Industrial Equipment, Marine Engines, Agricultural Machinery End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Component Manufacturers |
| Companies Covered | Yokohama Rubber Co Ltd, Gates Corporation, Sumitomo Riko Co Ltd, Schaeffler AG, Hutchinson SA, Continental AG, Toyoda Gosei Co Ltd, Nichirin Co Ltd, Dayco IP Holdings LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Engine Belt and Hose Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are converging to reshape compound selection criteria, while procurement centralization among commercial fleet operators restructures channel economics. Three developments dominate this transformation.
Aramid-reinforced hydrogenated nitrile butadiene rubber timing belts are displacing conventional chloroprene constructions in interference engine applications where tooth precision and heat resistance determine failure cost profiles. OEM specification engineers now mandate molded tooth profiles with sub-millimeter pitch accuracy for downsized turbocharged powertrains. This displacement is compressing aftermarket demand for legacy replacement intervals as extended-life compounds stretch service windows.
REACH Annex XVII restrictions on short-chain chlorinated paraffins are forcing rubber compounders to eliminate established plasticizer systems from coolant hose formulations. ECHA enforcement timelines compress reformulation investment decisions into eighteen-month windows. European suppliers with captive polymer development capabilities are capturing specification share from import-dependent competitors facing certification gaps.
Commercial vehicle fleet operators are consolidating aftermarket procurement through direct supplier contracts, bypassing traditional distributor networks for high-volume timing and serpentine belt categories. This channel compression concentrates price negotiation leverage among operators with thousand-vehicle maintenance schedules. The United States exhibits the most visible procurement centralization, where EPA enforcement transparency enables predictive replacement budgeting at fleet scale.
Global Automotive Engine Belt and Hose Market Segmentation
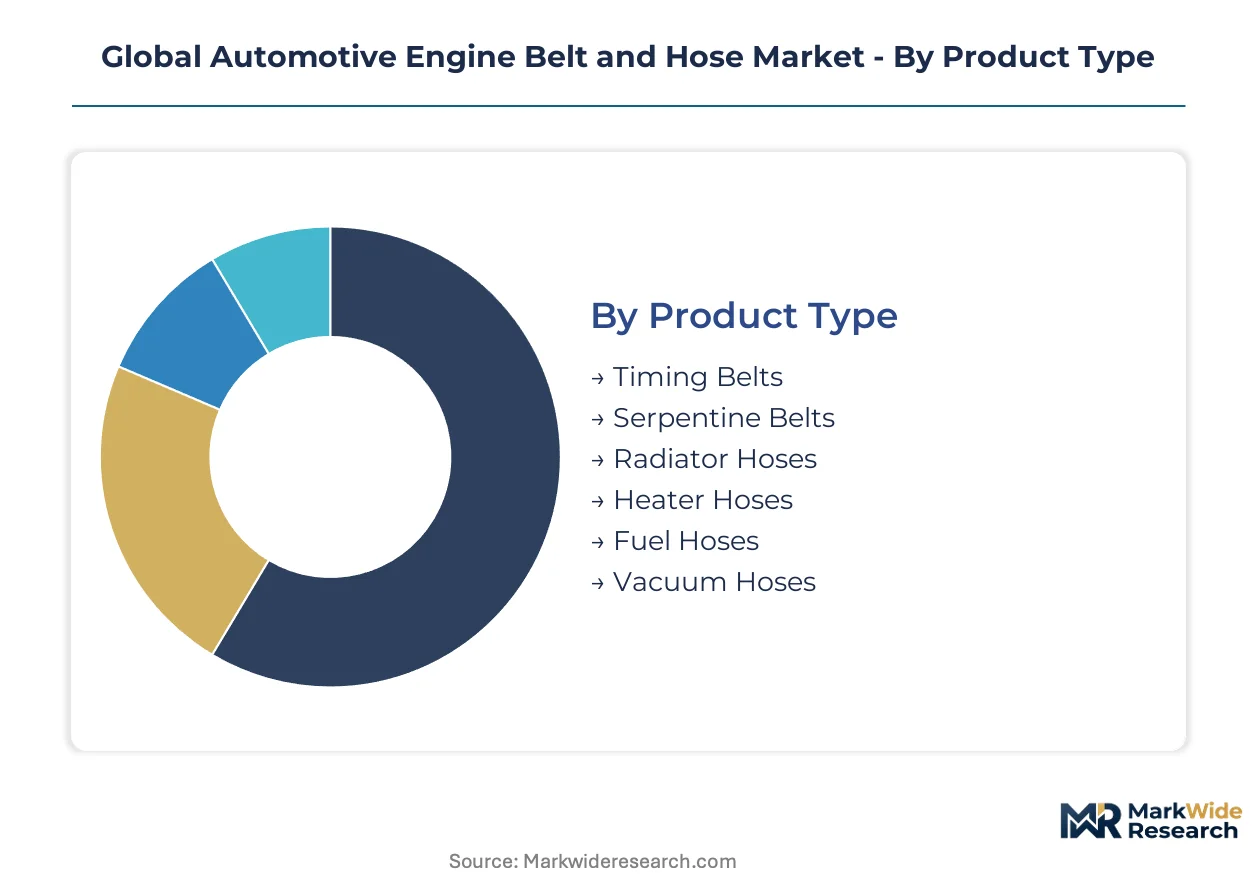
Segmentation in the automotive engine belt and hose market reveals how specification premiums concentrate around thermal load tolerance and interference engine architectures. Material chemistry and reinforcement topology determine which suppliers capture OEM qualification versus aftermarket volume.
Product Type:
Margin pools concentrate in synchronous power transmission components where tooth precision failures carry catastrophic engine damage costs.
- Timing Belts:Aramid-reinforced hydrogenated nitrile butadiene rubber constructions with molded tooth profiles deliver sub-millimeter pitch accuracy for interference engine synchronization. Demand clusters around downsized turbocharged powertrains in Germany and Japan where OEMs specify extended-life compounds to stretch service intervals.
- Serpentine Belts:Multi-rib EPDM constructions consolidate former V-belt and separate accessory belt architectures into single-drive systems. Fleet operators in the United States are unwinding low-cost aftermarket preferences toward OEM-specification systems as EPA durability enforcement intensifies.
- Radiator Hoses:Reinforced EPDM formulations circulate coolant across minus forty to one hundred fifty degrees Celsius operating ranges.
- Heater Hoses:Smaller-diameter coolant lines route to HVAC cores with reduced pressure specifications.
- Fuel Hoses:FKM-lined constructions resist aromatic hydrocarbon permeation in turbocharged direct-injection gasoline applications.
- Vacuum Hoses:Thermoplastic elastomer displacements target weight reduction in auxiliary system routing.
The dominant share belongs to Serpentine Belts, while Timing Belts command the steepest specification premiums per unit.
Material:
Compound selection tracks regulatory chemistry restrictions and thermal load escalation from downsized powertrains.
- Rubber:Conventional chloroprene and natural rubber compounds face displacement as REACH Annex XVII restrictions eliminate established plasticizer systems.
- Reinforced Rubber:Aramid or polyester tensile reinforcement layers extend fatigue life under cyclic loading.
- Silicone:High-temperature stability suits turbocharger intercooler and EGR circuit applications.
- Neoprene:Legacy chloroprene formulations retreat to cost-sensitive aftermarket replacement intervals.
- EPDM:Ethylene propylene diene monomer dominates coolant hose specifications with ozone resistance and thermal aging stability. Commercial vehicle procurement in India concentrates here as BIS quality mandates and PLI scheme subsidies accelerate localized compounding capacity.
- Thermoplastic Elastomers:TPV and TPE compounds expand fastest in heater and vacuum hose segments where OEM weight reduction targets override historical specifications.
EPDM holds the largest installed base, though Thermoplastic Elastomers are climbing the fastest as lightweighting mandates propagate across passenger vehicle platforms.
Application:
Vehicle architecture determines thermal circuit complexity and belt drive elimination risk through electrification transition timelines.
- Passenger Vehicles:Downsized turbocharged gasoline engines intensify hose specification requirements while serpentine belt content faces erosion in dedicated battery electric platforms.
- Commercial Vehicles:Fleet-scale procurement centralization in the United States drives EPDM coolant hose volume as EPA enforcement transparency enables predictive replacement budgeting.
- Off-Highway Vehicles:Construction and mining equipment demand reinforced constructions for contaminated operating environments.
- Industrial Equipment:Stationary engine applications specify longer replacement intervals than automotive counterparts.
- Marine Engines:Saltwater exposure mandates specialized ozone and corrosion-resistant formulations.
- Agricultural Machinery:Seasonal operating patterns concentrate demand in pre-planting maintenance windows.
Passenger Vehicles generate the highest absolute volume, while Commercial Vehicles exhibit the most visible procurement consolidation toward direct supplier contracts.
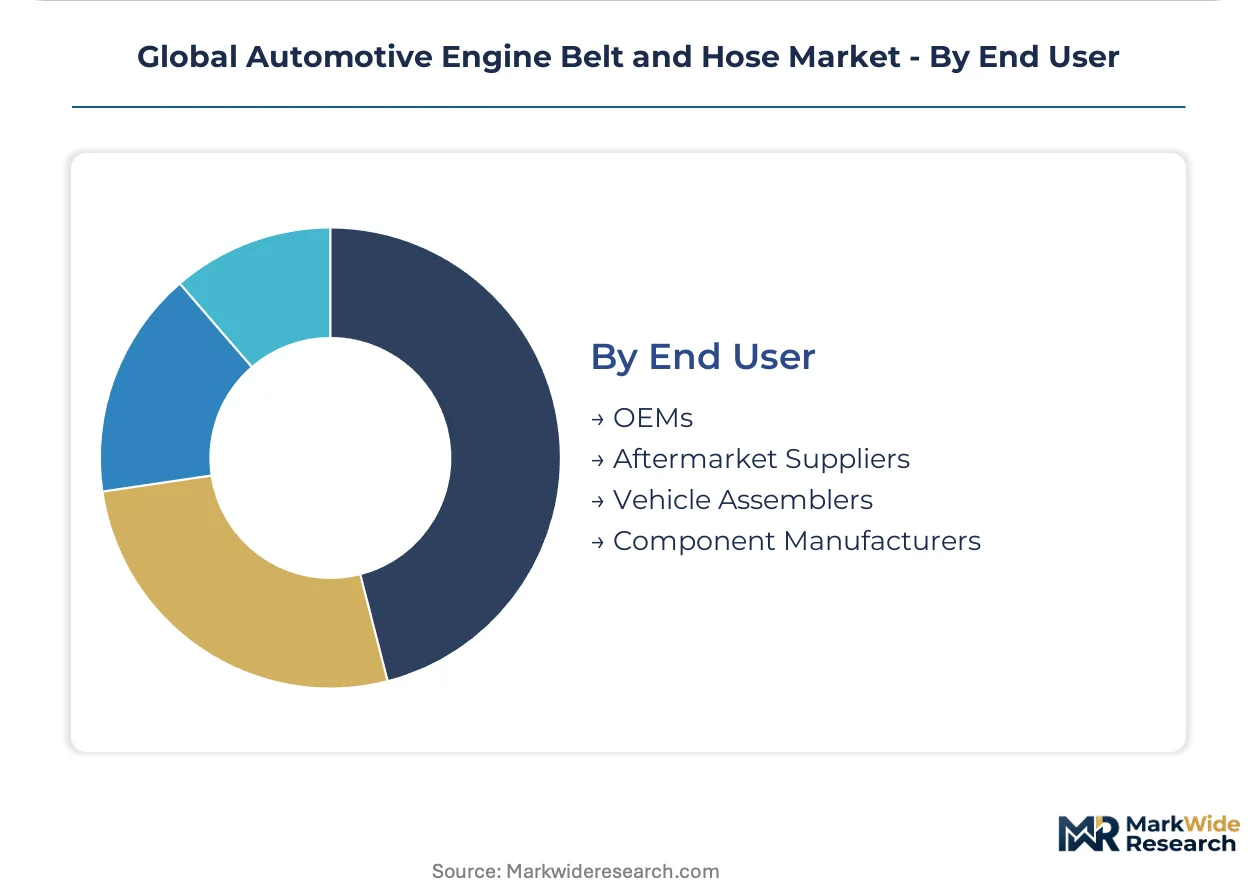
End User:
Channel structure bifurcates between specification-setting OEMs and price-sensitive aftermarket distributors.
- OEMs:Platform engineers mandate compound specifications that withstand elevated underhood thermal loads from downsized turbocharged powertrains. NHTSA fuel economy mandates in the United States compel extended-life system designs.
- Aftermarket Suppliers:Distributor networks face compression as commercial fleet operators consolidate procurement through direct supplier contracts for high-volume timing and serpentine categories.
- Vehicle Assemblers:Final assembly plants specify just-in-time delivery of belt and hose kits matched to engine build sequences.
- Component Manufacturers:Tier suppliers with captive polymer development capabilities capture specification share from import-dependent competitors facing REACH certification gaps.
OEMs control specification premiums, though Aftermarket Suppliers still process the highest transaction frequency across replacement intervals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European supply chain throughput for EPDM compound imports serving German automotive belt and hose fabrication. This infrastructure position concentrates specification-setting power among OEMs operating along the Rhine-Ruhr corridor.
United States
Commercial fleet operators with thousand-vehicle maintenance schedules are consolidating aftermarket procurement through direct supplier contracts. EPA emissions enforcement transparency enables predictive replacement budgeting at national scale. Detroit-Warren-Dearborn anchors domestic manufacturing for reinforced EPDM coolant hoses rated under elevated thermal loads.
Germany
OEM specification engineers mandate molded tooth profiles with sub-millimeter pitch accuracy for downsized turbocharged powertrains. ECHA REACH Annex XVII restrictions on short-chain chlorinated paraffins compress reformulation investment decisions into eighteen-month compliance windows. Stuttgart and Munich house captive polymer development capabilities capturing specification share from import-dependent competitors.
China
MIIT localization ratios and GB standards enforce material traceability requirements for engine ancillary components. Domestic suppliers are scaling hydrogenated nitrile butadiene rubber compounding capacity for high-temperature timing belt applications. Shanghai and Guangzhou clusters concentrate thermoplastic elastomer displacement activity targeting OEM weight reduction specifications.
India
BIS quality mandates for engine ancillary components create captive demand for localized belt and hose testing protocols. The PLI scheme for auto components subsidizes capital equipment for rubber compounding and extrusion operations. Pune and Chennai greenfield investments are accelerating timing belt and reinforced hose production capacity.
Japan
Specialized fluoroelastomer fuel hose production serves turbocharged direct-injection gasoline engines operating at higher fuel pressures. METI industrial standards coordinate with OEM specification requirements for extended-life compound formulations. Yokohama and Nagoya industrial zones concentrate precision molding capabilities for interference engine synchronization components.
Global Automotive Engine Belt and Hose Market Competitive Landscape
Listed leaders compete with private specialists across compound development capabilities and regional certification coverage. The vendor base separates into consolidated multi-national compounders with captive polymer science operations, mid-scale regional fabricators serving single-country qualification requirements, and specialized elastomer developers focused on fluoroelastomer or thermoplastic formulations. Three strategic archetypes dominate: integrated rubber compounders controlling upstream EPDM polymer supply, precision molding specialists capturing timing belt specification premiums, and diversified automotive suppliers leveraging existing OEM relationships for hose kit bundling. Capacity expansion and backward integration into aramid fiber sourcing represent the dominant competitive moves across tiers.
Within the integrated compounder tier, Gates Corporation and Continental AG exemplify archetypes of margin leadership through captive formulation development and integrated hose extrusion operations respectively. Yokohama Rubber Co Ltd occupies a specialist position representing fluoroelastomer fuel hose expertise concentrated in Asia-Pacific turbocharged engine applications. These three entities anchor competitive positioning across the specification-premium spectrum without exhaustive market share claims.
| Leading Market Players |
|---|
| Yokohama Rubber Co Ltd |
| Gates Corporation |
| Sumitomo Riko Co Ltd |
| Schaeffler AG |
| Hutchinson SA |
| Continental AG |
| Toyoda Gosei Co Ltd |
| Nichirin Co Ltd |
| Dayco IP Holdings LLC |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day compound formulation lead times concentrate pricing power among EPDM suppliers with captive polymer development capabilities, while inventory cycles at just-in-time vehicle assemblers amplify volatility transmission from ethylene-propylene feedstock markets into tier-one procurement negotiations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale. OEM-specification aramid-reinforced timing belts with sub-millimeter pitch accuracy command substantial premiums over aftermarket chloroprene replacements. Cost compression in standard-tier serpentine belts is intensifying because commercial fleet operators consolidate thousand-vehicle procurement schedules. Aftermarket distributors exhibit highest price sensitivity, while OEM platform engineers prioritize thermal load tolerance over unit cost.
Supply Chain Analysis
Germany and Japan anchor precision molding capabilities for interference engine synchronization components, while China and India scale EPDM compounding capacity for localized coolant hose production. The supply chain draws from aramid fiber producers in the United States, EPDM polymer manufacturers in the Netherlands and Saudi Arabia, and fluoroelastomer specialists in Japan. Single-source vulnerability concentrates in hydrogenated nitrile butadiene rubber compounding expertise for extended-life timing belt formulations. Distribution runs through direct supplier contracts with commercial fleet operators, bypassing traditional aftermarket distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated commercial fleet operators with predictive replacement budgeting capabilities, fragmenting traditional aftermarket distributor influence across high-volume belt and hose categories.
For Market Incumbents: Shield specification premiums by deepening backward integration into aramid fiber sourcing and accelerating REACH-compliant compound reformulation ahead of ECHA enforcement windows. Threats from thermoplastic elastomer displacement in heater and vacuum hose segments demand preemptive R&D investment in TPV extrusion capabilities. Channel control through direct fleet contracts represents the critical defensive lever against distributor network erosion. For New Entrants and Emerging Players: Differentiate on localized EPDM compounding for India's PLI-subsidized capacity expansion, where BIS quality mandates create specification entry barriers for import-dependent competitors. The most penetrable white space sits in hybrid thermal management hose architectures for battery pack conditioning circuits. A go-to-market angle anchored in MIIT localization ratio compliance for Chinese OEM supply chains bypasses entrenched European compounder relationships. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because electrification transition timelines will strand serpentine belt capacity while rewarding thermal management specialization. Acquisition targets should exhibit captive polymer science capabilities and multi-regional certification coverage. The signal to watch is hybrid powertrain penetration rates in passenger vehicle platforms, which dictate coolant circuit complexity and hose specification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aramid Fiber Sourcing | Captive reinforcement supply secures margin control against DuPont and Teijin price volatility. |
| REACH-Compliant Compound Reformulation | ECHA Annex XVII alignment captures specification share from phthalate-dependent import competitors. |
| Direct Fleet Procurement Contracts | Bypassing distributor networks concentrates pricing leverage with thousand-vehicle maintenance operators. |
| Hybrid Thermal Management Hose Development | Battery pack conditioning specifications command premiums above conventional internal combustion applications. |
| PLI-Aligned Greenfield Capacity in India | BIS-mandated localized testing protocols create captive demand for domestic extrusion and compounding assets. |
Research Methodology
The analysis maps EPDM coolant hose, aramid-reinforced timing belt, and fluoroelastomer fuel hose sub-sectors, each validated through OEM platform engineers, Tier 1 supplier procurement leads, commercial fleet maintenance directors, and aftermarket distributor operations heads. Primary interview findings triangulated against customs trade data, vehicle production databases, SEC 10-K filings from listed compounders, and IHS Markit registration data. Bottom-up unit volume estimates and top-down value reconciliation ensured cross-validation across modeling approaches.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include propulsion architecture, material chemistry tier, thermal load specification, and regional production cluster. CAGRs derived from fitted growth curves applied to baseline volumetrics, with electrification transition timelines and EPA enforcement intensity as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EPA emissions enforcement, ECHA REACH restrictions, and MIIT localization ratios; material policy shifts would require re-modeling. Specific risks include faster-than-anticipated battery electric vehicle adoption collapsing serpentine belt demand, and EPDM feedstock price spikes compressing compounder margins. Recalibration cycles align with material shifts in hybrid powertrain penetration and regional PLI scheme modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Transmission System Market
Powertrain
Gear Reduction Starter Market
Powertrain
India Automotive Engine Oils Market
Powertrain
Automotive Fan Clutch Market
Powertrain
Engine Tuner Market
Powertrain
Global Automotive Torque Vectoring Market
Powertrain
Industrial Diesel Turbocharger Market
Powertrain
Automotive TCU Market
Powertrain
Axle Shaft Market
Powertrain
Transmission Fluids Market
Powertrain
North America Torque Vectoring Market
Powertrain
Global Industrial Turbocharger Market
Powertrain
Middle East and Africa Internal Combustion Engines Market
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
Power Steering Filter Market
Powertrain
Drive Shaft Market