
 China Passenger Vehicles Lubricants Market | 2026-2036
China Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
China Passenger Vehicles Lubricants Market Outlook
Asset-light leasing arrangements for lubricant blending facilities are reconfiguring competitive entry barriers for domestic challengers. China National Petroleum Corporation leverages captive refinery access to anchor supply security across northern provinces. Jiangsu Lopal Tech Co Ltd specializes in synthetic formulations for high-compression gasoline direct injection engines. BP PLC (Castrol) navigates premium positioning through workshop channel partnerships in tier-one cities.
China passenger vehicles lubricants encompass refined petroleum-based and synthetic fluid formulations engineered to reduce friction, dissipate heat, and prevent wear in powertrain assemblies operating across temperature ranges from minus forty to one hundred fifty degrees Celsius. Their primary commercial purpose is extending engine and transmission service life while maintaining fuel efficiency certification thresholds. Engine oils command the dominant margin pool due to higher formulation complexity and shorter drain intervals, while transmission fluids represent the fastest-growing category as dual-clutch and continuously variable transmissions proliferate in domestic vehicle production. Workshop distribution channels capture the highest value per liter through bundled service contracts, whereas online sales expand fastest among private vehicle owners in lower-tier cities seeking price transparency.
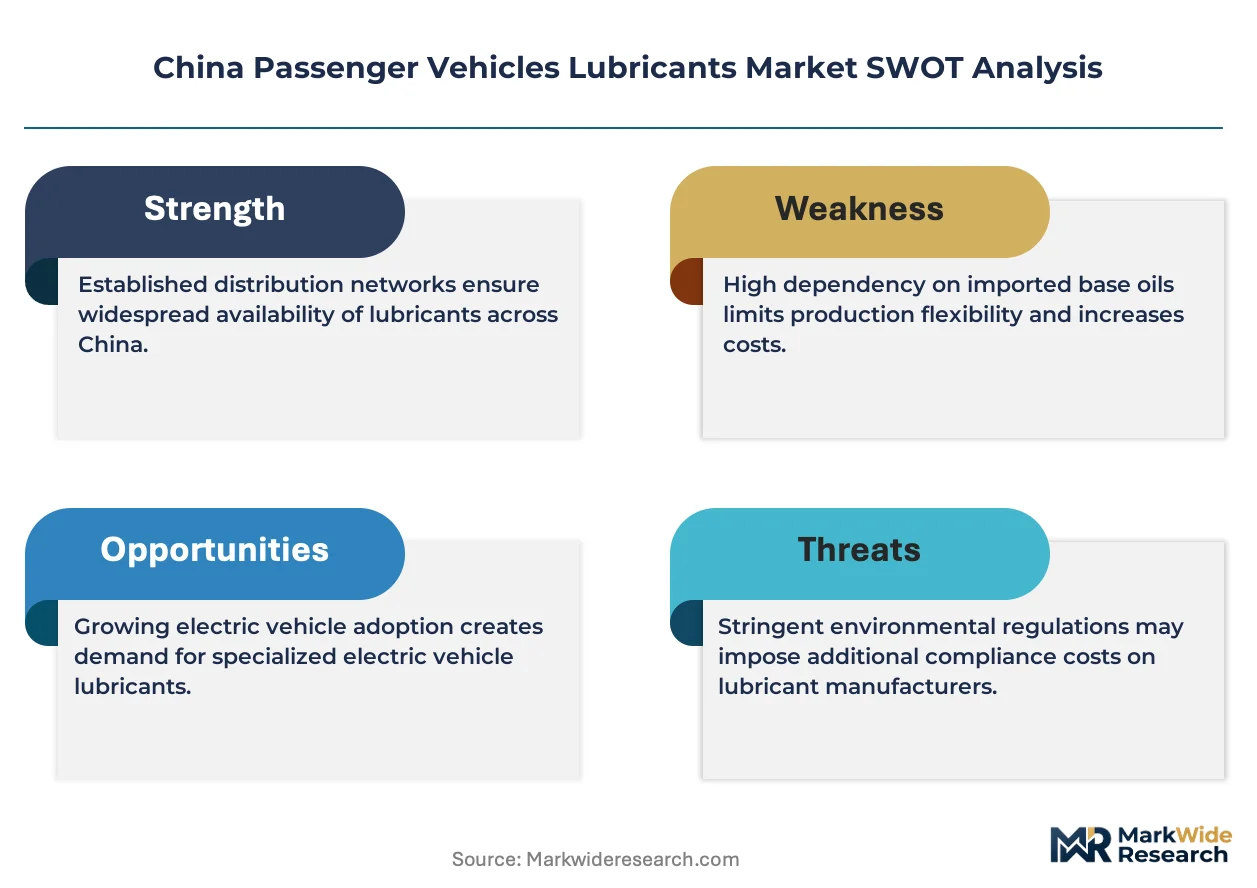
MIIT fuel consumption regulations and China's evolving GB standards for passenger car engine oils jointly elevate low-viscosity synthetic demand while phasing out obsolete mineral formulations. SAMR market surveillance protocols enforce labeling accuracy and performance claims verification, tightening market access for uncertified imports. Stakeholders must monitor alignment between provincial new energy vehicle mandates and lubricant portfolio transitions as hybrid powertrains reshape volume requirements.
Market Dynamics
MIIT fuel consumption regulations and tightening GB standards for passenger car engine oils are compressing formulation cycles while elevating synthetic blend requirements across domestic production lines.
Growth Catalysts
- Dual-clutch transmission proliferation:Domestic automakers are expanding dual-clutch and continuously variable transmission production, multiplying specialized fluid demand per vehicle.
- GB 11122-2019 upgrade cycle:Mandatory performance tier upgrades are phasing out obsolete mineral formulations and forcing portfolio refresh across licensed blenders.
- Yangtze River Delta manufacturing concentration:Shanghai-centered automotive clusters generate dense lubricant offtake from captive fleet operators and OEM assembly plants.
Market Restraints
- Group II/III base oil import dependence:Domestic refiners lack sufficient hydrocracking capacity, exposing blenders to Singapore and South Korean supply volatility.
- MEE environmental compliance escalation:Wastewater discharge and VOC emission standards are raising blending facility retrofit costs without offsetting price recovery mechanisms.
- Hybrid powertrain volume erosion:Extended drain intervals and reduced thermal loading on hybrid engines compress per-vehicle lubricant consumption versus conventional powertrains.
Strategic Opportunities
- Western province fleet penetration:Chongqing and Chengdu logistics corridors remain underserved by synthetic formulation specialists relative to coastal density.
- SAMR-certified import channel development:Accelerated registration pathways for API SP/ILSAC GF-6 compliant products create first-mover positioning in premium synthetic tiers.
- Workshop bundling digitization:Tier-two city independent garages are adopting fluid-plus-service subscription platforms, opening direct-to-installer bypass of traditional distributor layers.
Industry Challenges
- Additive package chemist scarcity:Formulation expertise for high-ash, low-SAPS gasoline direct injection compatibility concentrates among senior technologists at state-owned research institutes.
- GB standard alignment lag:Blend certification timelines frequently misalign with OEM factory fill qualification windows, freezing contract awards.
- Cross-border e-commerce labeling enforcement:SAMR surveillance protocols are intercepting non-compliant imports, creating inventory seizure risk for gray-channel operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Passenger Vehicles Lubricants Market |
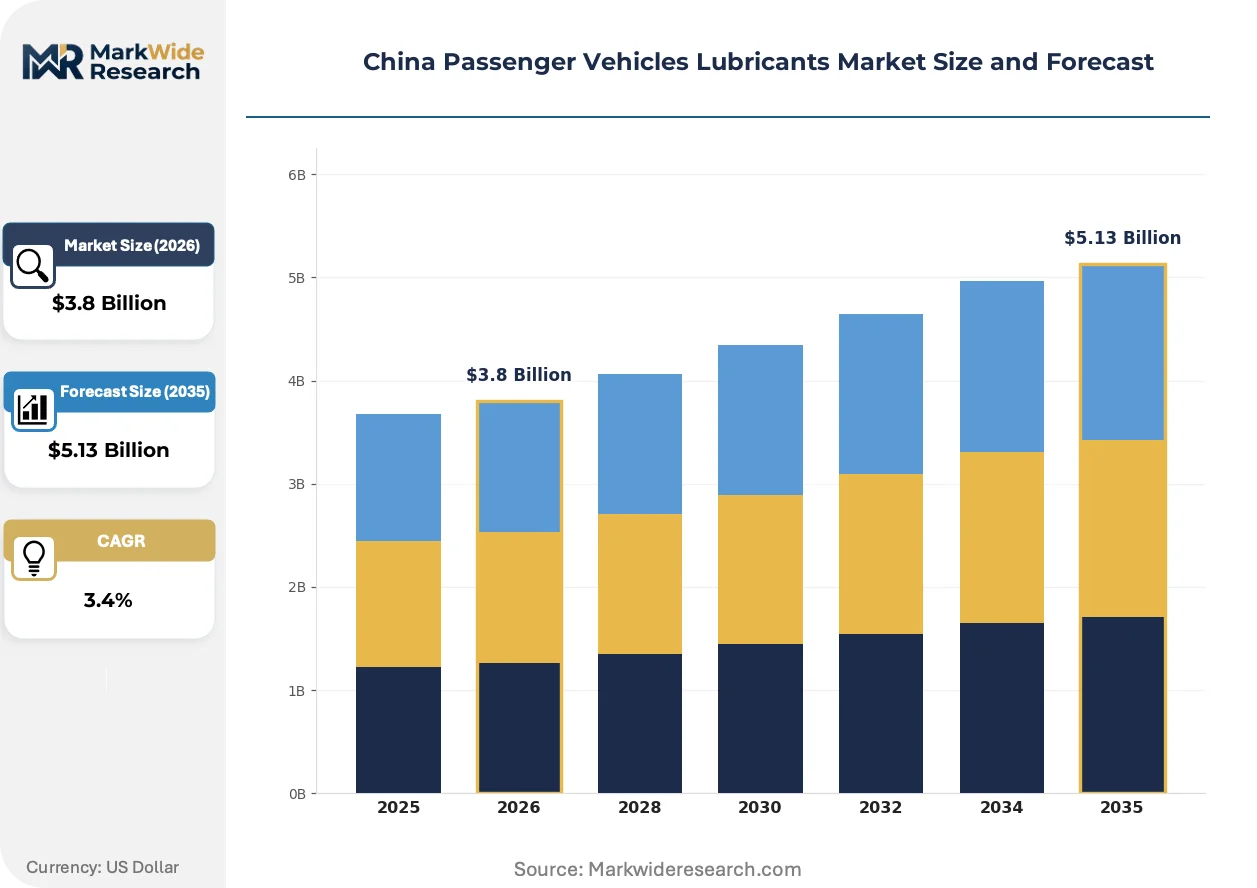
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.13 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oils, Transmission Fluids, Greases, Brake Fluids Application: Passenger Cars, SUVs, Light Trucks, Crossovers Distribution Channel: Retail Stores, Online Sales, Service Stations, Workshops End User: Private Vehicle Owners, Fleet Operators, Rental Companies, Automotive Garages |
| Companies Covered | China National Petroleum Corporation, China Petroleum & Chemical Corporation, BP PLC (Castrol), ExxonMobil Corporation, Royal Dutch Shell Plc, Chevron Corporation, TotalEnergies, Jiangsu Lopal Tech Co Ltd, Qingdao COPTON Technology Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Passenger Vehicles Lubricants Market Strategic Shifts
Synthetic base stock substitution and regulatory performance tier escalation are compressing mineral oil viability while expanding formulation complexity requirements across the value chain.
Polyalphaolefin and ester-based synthetic blends are virtualizing Group I mineral oil positions in high-temperature, high-shear gasoline direct injection applications. Domestic OEMs are accelerating factory fill adoption of 0W-20 and 0W-16 grades to meet corporate average fuel consumption targets. This viscosity grade compression is virtualizing legacy 5W-30 and 10W-40 volume positions in new vehicle segments.
MIIT's corporate average fuel consumption mandate and evolving China 6 emission standards are jointly enforcing low-viscosity synthetic adoption across passenger car engine oil categories. Blenders must now certify formulations against both fuel economy retention and aftertreatment compatibility requirements. Northern provinces face accelerated compliance timelines versus southern manufacturing zones.
Independent workshop chains in tier-two and tier-three cities are consolidating procurement through vertical platform aggregators, disintermediating traditional regional distributors. These platforms bundle fluid supply with technician training and warranty administration, capturing service contract value previously fragmented across multiple supplier relationships. Hebei and Shandong provinces exhibit the fastest platform penetration rates among private vehicle service channels.
China Passenger Vehicles Lubricants Market Segmentation
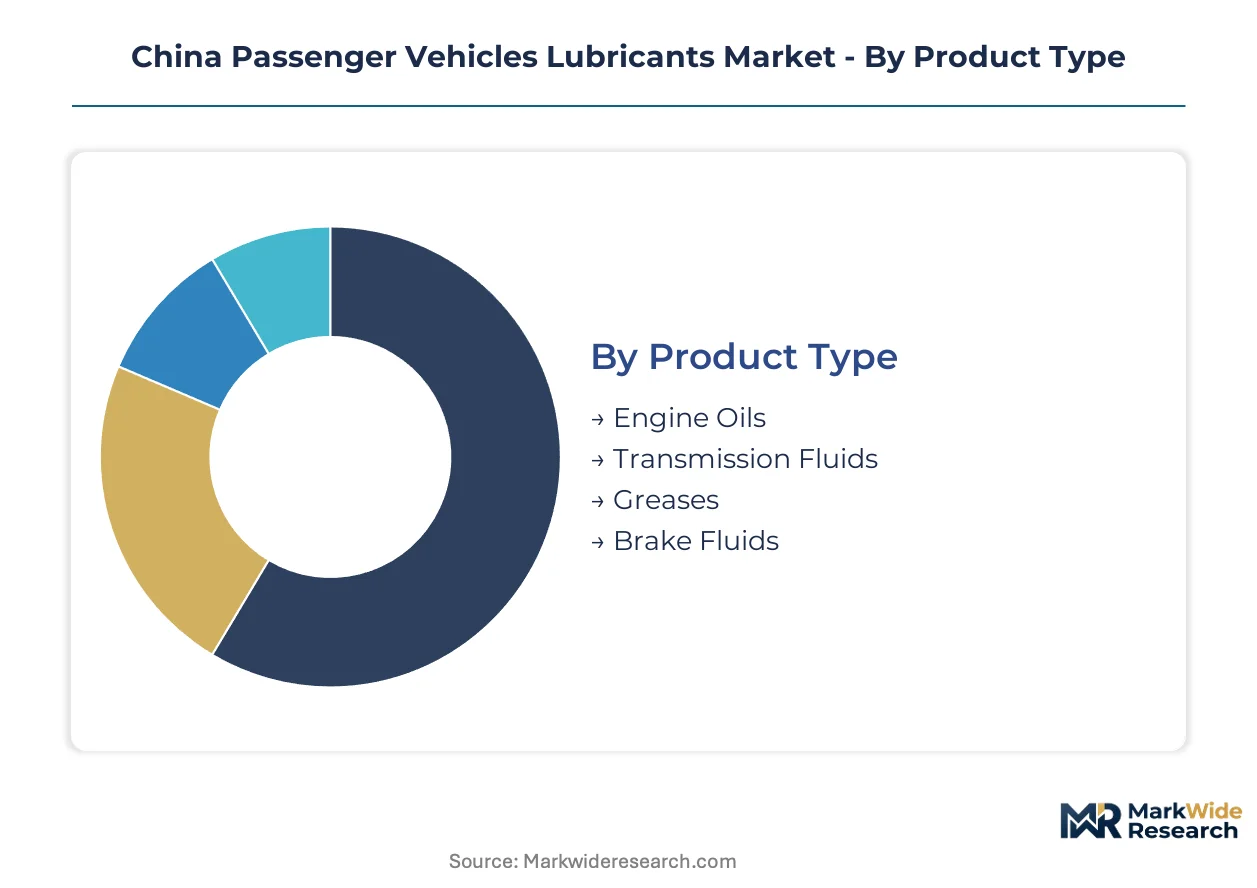
China's passenger vehicle lubricant demand fragments across formulation chemistry, vehicle architecture, and procurement channel economics. Segment boundaries are blurring as OEM factory fill specifications migrate downstream and workshop consolidation reshapes aftermarket access.
Product Type:
Formulation chemistry determines margin structure and technical certification burden across the value chain.
- Engine Oils:Refined petroleum and synthetic blends dominate volume, with viscosity grades compressing toward 0W-20 and 0W-16 under MIIT fuel consumption mandates. Yangtze River Delta OEM assembly plants concentrate factory fill procurement for gasoline direct injection powertrains.
- Transmission Fluids:Specialized formulations for dual-clutch and continuously variable transmissions command premium positioning as domestic automakers expand automated gearbox production. Fluid complexity multiplies per vehicle versus conventional automatic transmissions.
- Greases:Lithium and polyurea-thickened formulations serve chassis and wheel bearing applications with longer service intervals.
- Brake Fluids:Glycol-ether and silicone-based specifications maintain steady replacement demand through mandatory safety inspection protocols.
Engine oils hold installed capacity. Transmission fluids are rotating up the share rankings.
Application:
Vehicle architecture shapes thermal loading patterns and drain interval economics.
- Passenger Cars:Sedan segments drive standardized 5W-30 and 0W-20 volume positions, with fleet operators in Shanghai and Guangzhou optimizing procurement around extended drain synthetic programs.
- SUVs:Higher displacement powertrains and all-wheel-drive differentials expand multi-fluid requirements per vehicle, concentrating demand in northern provinces where cold-start protection specifications tighten.
- Light Trucks:Commercial-adjacent utilization patterns compress drain intervals versus passenger applications, sustaining conventional mineral blend positions in cost-sensitive segments.
- Crossovers:Unibody construction with car-derived powertrains replicate passenger car fluid specifications at scaled production volumes.
SUVs command the steepest expansion trajectory. Passenger cars retain volume leadership.
Distribution Channel:
Channel economics separate bundled service value from commodity fluid transactions.
- Retail Stores:Hypermarket and automotive specialty chains serve DIY maintenance segments with price-transparent 4-liter packaging, losing share to digital alternatives in tier-three cities.
- Online Sales:E-commerce platforms capture fastest growth among private owners seeking specification verification and bulk pricing, with SAMR-certified listings filtering gray-market imports.
- Service Stations:CNPC and Sinopec captive networks anchor quick-lube volume in highway corridor locations, bundling fluid with standardized inspection protocols.
- Workshops:Independent garages and OEM-authorized service centers extract highest value per liter through technician-installed programs with warranty backing, consolidating procurement through vertical platform aggregators in Hebei and Shandong.
Workshops hold installed capacity. Online sales are rotating up the share rankings.
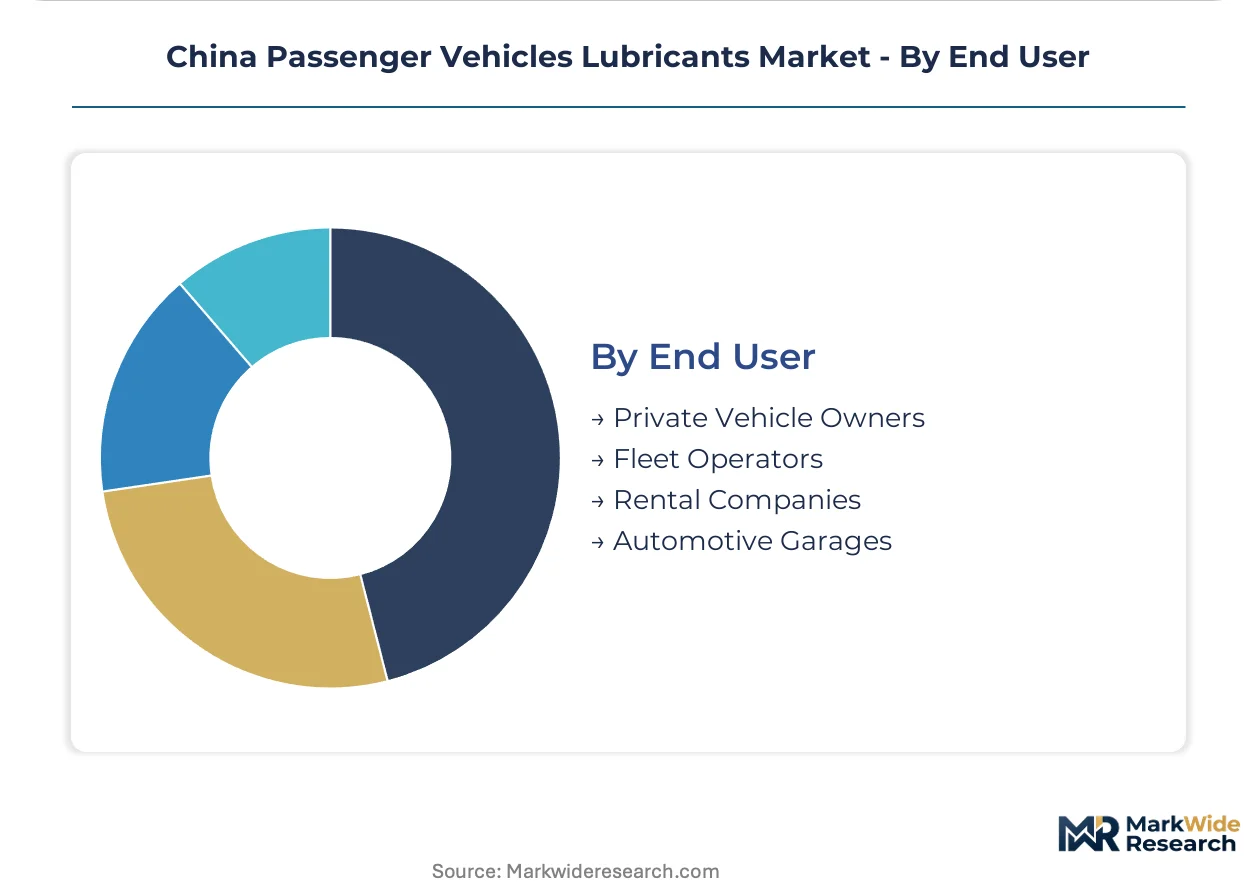
End User:
Customer type determines specification authority and procurement scale.
- Private Vehicle Owners:Individual consumers prioritize price transparency and brand recognition, migrating toward platform-verified synthetic products as GB standard awareness spreads.
- Fleet Operators:Logistics and ride-hailing fleets centralize lubricant procurement through annual contracts, negotiating volume discounts against documented drain interval compliance.
- Rental Companies:Vehicle turnover cycles compress maintenance windows, favoring quick-service channel relationships over specification optimization.
- Automotive Garages:Independent repair businesses consolidate fluid purchasing through subscription platforms that bundle supply with technical training and warranty administration.
Fleet operators hold installed capacity. Automotive garages are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT fuel consumption mandates and tightening GB standards are redistributing lubricant demand across China's provincial manufacturing clusters, with synthetic formulation requirements escalating fastest in coastal automotive corridors.
Yangtze River Delta
Shanghai-centered OEM assembly plants and captive fleet operators concentrate factory fill procurement for gasoline direct injection powertrains. SAMR market surveillance protocols enforce labeling accuracy across Jiangsu and Zhejiang blending facilities. The Suzhou-Nantong manufacturing corridor generates dense offtake as domestic automakers expand dual-clutch transmission production.
Pearl River Delta
Guangzhou and Shenzhen logistics fleets centralize lubricant procurement through annual contracts negotiating volume discounts against drain interval compliance. MEE environmental compliance escalation raises wastewater discharge standards for blending facilities in Dongguan and Foshan. Independent workshop chains in Guangdong consolidate procurement through vertical platform aggregators.
Beijing-Tianjin-Hebei
State-owned refinery networks anchor supply security across northern provinces through captive base oil access. Northern provinces face accelerated compliance timelines for China 6 emission standards versus southern manufacturing zones. Tianjin port logistics corridors expose blenders to Singapore and South Korean Group II/III base oil import volatility.
Sichuan-Chongqing
Western logistics corridors remain underserved by synthetic formulation specialists relative to coastal density. Provincial new energy vehicle mandates reshape lubricant portfolio transitions as hybrid powertrains compress per-vehicle consumption. Chongqing automotive clusters generate growing demand for high-compression gasoline direct injection compatible formulations.
Shandong Peninsula
Independent garages in tier-two cities adopt fluid-plus-service subscription platforms fastest among private vehicle service channels. Hebei and Shandong provinces exhibit the fastest platform penetration rates for workshop bundling digitization. Qingdao blending facilities face rising retrofit costs from MEE VOC emission standards without offsetting price recovery mechanisms.
China Passenger Vehicles Lubricants Market Competitive Environment
On the supply side, the industry is consolidating around state-owned refinery-integrated blenders and multinational premium specialists, with mid-tier domestic challengers squeezed between captive supply security and formulation complexity barriers. Three strategic archetypes dominate: state-owned enterprises leveraging vertical refinery integration, multinational lubricant majors navigating premium positioning through workshop partnerships, and domestic synthetic specialists targeting high-compression engine compatibility. Competitive moves center on GB standard certification acceleration and workshop channel digitization to bypass traditional distributor layers.
Among state-owned integrated operators, China National Petroleum Corporation and China Petroleum & Chemical Corporation anchor supply security across northern and coastal provinces through captive refinery access. BP PLC (Castrol) exemplifies the multinational premium archetype, occupying positions in tier-one city workshop channels. Jiangsu Lopal Tech Co Ltd represents domestic synthetic formulation specialists targeting technical certification for advanced powertrain architectures.
| Leading Market Players |
|---|
| China National Petroleum Corporation |
| China Petroleum & Chemical Corporation |
| BP PLC (Castrol) |
| ExxonMobil Corporation |
| Royal Dutch Shell Plc |
| Chevron Corporation |
| TotalEnergies |
| Jiangsu Lopal Tech Co Ltd |
| Qingdao COPTON Technology Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Shandong's independent blending facilities is compressing margin recovery across mid-tier suppliers while forcing synthetic specialists toward premium certification tiers. This utilization imbalance simultaneously elevates pricing power for GB-certified producers and erodes spot-market leverage for mineral-formulation operators.
Pricing Analysis
Performance tier certification creates the primary spread between factory-fill contracts and aftermarket spot transactions. Three-tier pricing structure across premium synthetic, mid-grade blend, and economy mineral levels stratifies around GB 11122-2019 compliance status and OEM qualification windows. Price erosion runs through economy mineral tiers as MIIT fuel consumption mandates accelerate low-viscosity substitution. Fleet operators exhibit highest price sensitivity due to annual contract renegotiation cycles, while OEM technical service centers absorb premium positioning through bundled warranty programs.
Supply Chain Analysis
Group II/III base oil feedstock draws from Singapore, South Korea, and Middle Eastern hydrocracking complexes, with domestic hydrocracker capacity lagging synthetic blend demand. Additive packages hinge on Lubrizol, Infineum, and Afton import channels for high-ash low-SAPS gasoline direct injection compatibility. Single-source vulnerability concentrates in Singapore Strait logistics corridors exposed to maritime chokepoint risk. Distribution runs through CNPC/Sinopec captive terminal networks in northern provinces, with independent blenders relying on third-party tank farm access in Yangtze River Delta clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise for high-compression gasoline direct injection engines concentrates among senior technologists at state-owned research institutes, creating bottlenecks for portfolio refresh timelines. This capability scarcity elevates acquisition premiums for certified technical teams and compresses windows for independent certification.
For Market Incumbents: Build captive refinery integration moats through backward control over Group II/III base oil hydrocracking capacity in northern provinces. Secure OEM factory-fill qualification windows ahead of GB standard upgrade cycles to freeze contract awards. Defend against synthetic specialists by accelerating low-viscosity 0W-16 certification pipelines. For New Entrants and Emerging Players: Build out western province distribution infrastructure in Chongqing-Chengdu logistics corridors underserved by synthetic formulation density. Target tier-two city independent garage subscription platforms in Hebei and Shandong exhibiting fastest platform penetration. Penetrate through SAMR-certified import channel development for API SP/ILSAC GF-6 compliant products. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across wastewater discharge and VOC emission retrofit compliance as MEE standards tighten. Long-term viability favors blenders with captive terminal access and vertical additive package integration. Target acquisition archetype: mid-cap synthetic specialists with GB-certified technical teams and underutilized blending capacity. Signal to monitor: provincial new energy vehicle mandate acceleration compressing hybrid powertrain lubricant consumption assumptions.| Strategic Initiative | Industry Significance |
|---|---|
| GB Standard Certification Acceleration | MIIT fuel consumption mandates compress formulation cycles, forcing portfolio refresh ahead of OEM qualification windows. |
| Backward Integration into Base Oil Hydrocracking | Domestic Group II/III capacity deficits expose blenders to Singapore and South Korean supply volatility. |
| Workshop Channel Digitization | Tier-two city garage subscription platforms in Hebei and Shandong disintermediate traditional distributor layers. |
| Synthetic Formulation Specialist Acquisition | High-ash low-SAPS gasoline direct injection expertise concentrates among senior technologists at state-owned institutes. |
| Western Province Distribution Expansion | Chongqing and Chengdu logistics corridors remain underserved relative to Yangtze River Delta synthetic density. |
Study Parameters
Initial hypotheses were tested against primary input from lubricant blending plant managers, OEM technical service engineers, aftermarket distributor procurement leads, and fleet operator maintenance directors, then refined against secondary validation. Trade data from China Customs, MIIT fuel consumption compliance filings, SAMR certification registries, and provincial environmental disclosure reports anchored supply-side quantification. Bottom-up volume builds from individual blending facility capacity utilization triangulated against top-down demand estimates derived from vehicle production and parc data.
Demand-supply balance modeling across the projection horizon segmented by formulation chemistry, vehicle architecture, and procurement channel economics. Analytical framework incorporated viscosity grade compression trajectories, drain interval elasticity, and hybrid powertrain penetration assumptions. CAGRs were derived from segment-level volume builds calibrated to OEM factory-fill contract awards and aftermarket channel growth rates. Forecast inputs included MIIT corporate average fuel consumption mandate compliance timelines and provincial new energy vehicle adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by state-owned refiners or accelerated SAMR enforcement against gray-channel imports would shift outcomes. Cross-checking against CNPC and Sinopec annual production disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
HCV Brake Components Market
Automotive Parts
France Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
Industrial V Belt Market
Automotive Parts
Auxiliary Oil Cooler Market
Automotive Parts
Windshield Washer Fluid Market
Automotive Parts
Gearshift Sleeves Market
Automotive Parts
Australia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Engine Bearings Market
Automotive Parts
Global Automotive Dynamic Chassis Control System Market
Automotive Parts
Global Automotive Parts Remanufacturing Market
Automotive Parts
Power Liftgate Market
Automotive Parts
Colombia Commercial Vehicles Lubricants Market
Automotive Parts
Europe Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Engine Oil Coolant Market
Automotive Parts
Global All Wheel Drive Market