
 Vehicle Jump Starter Market | 2026-2036
Vehicle Jump Starter Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Jump Starter Market Analytics
Automotive parts stores is reconfiguring shelf space toward lithium-ion jump starters as consumer preference shifts away from traditional lead-acid units. NOCO Company leverages its proprietary Boost technology to anchor premium positioning in specialty retail channels. Clore Automotive sustains dominance in heavy-duty segments through captive supply of professional-grade charging systems. Stanley Black & Decker competes across mass-market tiers by extending its brand architecture into portable power categories.
A vehicle jump starter is a self-contained portable power device delivering high-amperage current to restart disabled internal combustion engines or supplement depleted electric vehicle 12V auxiliary systems, typically incorporating lithium iron phosphate or lead-acid cells rated between 400 and 4000 peak amps. Its primary commercial purpose centers on eliminating dependency on second-vehicle assistance or tow services during battery failure events. Lithium-ion technology leads unit economics through superior energy density and reduced weight profiles, while portable form factors capture the fastest expansion as glove-box-compatible designs penetrate personal vehicle segments. Heavy-duty configurations retain margin concentration in commercial fleet and emergency services channels where duty-cycle reliability commands pricing premiums.
The US NHTSA and EPA shape product compliance through battery transport safety and hazardous material handling standards, while the EU REACH and RoHS frameworks restrict heavy metal content in imported power cells. China's SAMR enforces GB standards on lithium battery safety that govern export eligibility for Shenzhen DBPower Technology and comparable manufacturers. Stakeholders must monitor divergence between regional certification regimes as dual carbon goals in Asia and circular economy mandates in Europe recalibrate supply chain qualification requirements.
Market Dynamics
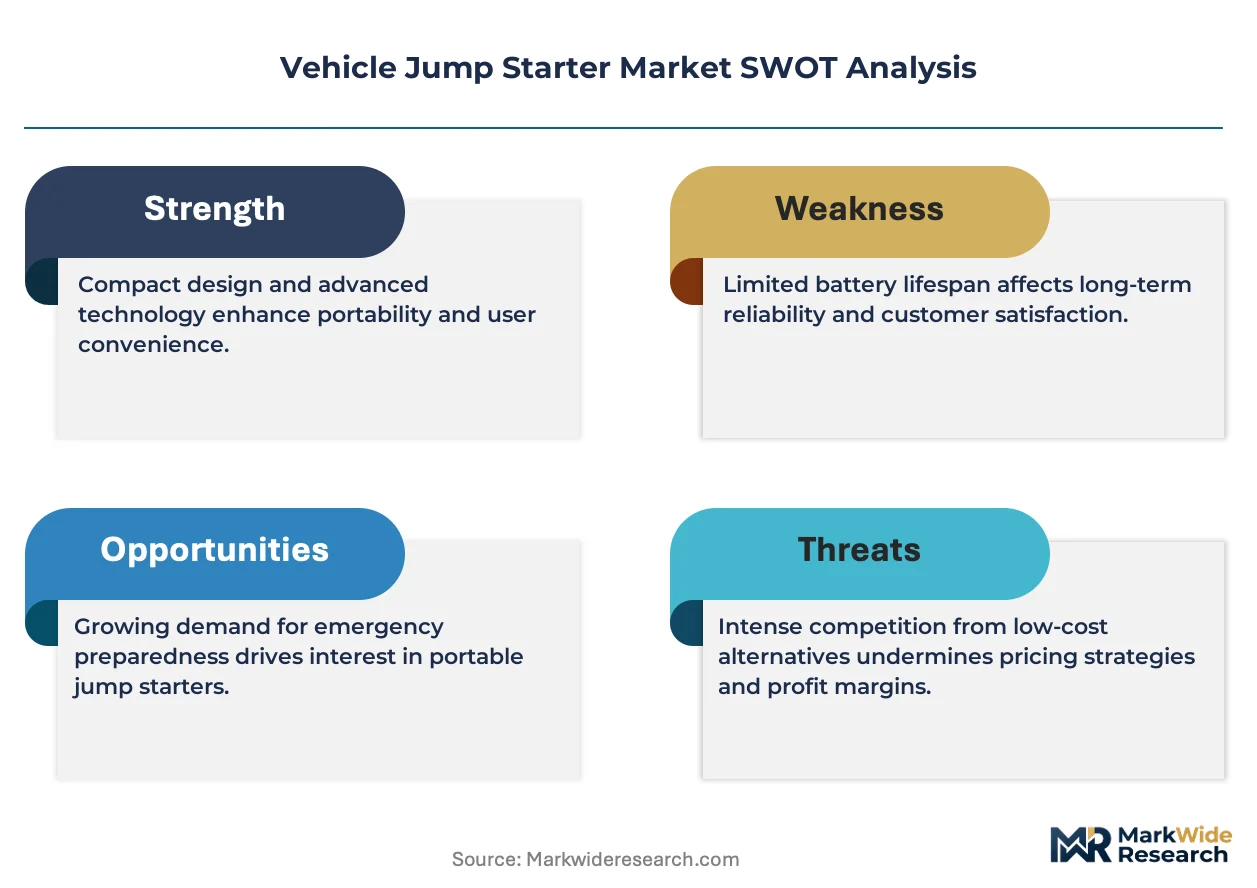
Commercial fleet electrification is compressing replacement cycles for roadside assistance equipment pools, forcing lithium-ion jump starters into service rotations historically dominated by lead-acid units. Procurement managers at logistics operators now mandate multi-function portability as a baseline specification, reshaping supplier qualification criteria across North America and Asia-Pacific distribution channels.
Growth Catalysts
- Lithium iron phosphate chemistry:Superior thermal stability and cycle life are displacing legacy lead-acid configurations in professional-grade units, particularly within emergency services vehicle fleets.
- China's dual carbon goals:Domestic manufacturers accelerate export-oriented production of compact multi-function designs as SAMR enforces stricter GB standards on lithium battery safety certification.
- Roadside assistance electrification:Motor clubs and commercial fleet operators expand equipment modernization programs to service hybrid and electric vehicle auxiliary systems.
Market Restraints
- Lithium carbonate price volatility:Raw material input costs for cathode production create margin compression for mid-tier manufacturers without captive supply arrangements.
- Shenzhen production concentration:Heavy reliance on Guangdong Province contract manufacturers exposes supply continuity risks from localized energy rationing or logistics disruptions.
- EU REACH substance restrictions:RoHS compliance costs for heavy metal content in power cells create non-tariff barriers for Asian exporters targeting European aftermarket channels.
Strategic Opportunities
- India aftermarket penetration:Underdeveloped organized retail for automotive electronics creates first-mover advantage for brands establishing distributor networks in tier-two cities.
- Camping and outdoor recreation:Convergence of jump starter functionality with portable power station features opens consumer segments beyond traditional automotive applications.
- US IRA clean vehicle incentives:Tax credit structures for commercial fleet electrification indirectly accelerate auxiliary equipment upgrade cycles.
Industry Challenges
- UN 38.3 lithium transport certification:Extended testing timelines for air freight eligibility delay product launches and constrain inventory positioning for cross-border e-commerce.
- Embedded software integration:Smart battery management systems requiring firmware development and cybersecurity protocols strain engineering capacity at traditional hardware-focused manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Jump Starter Market |
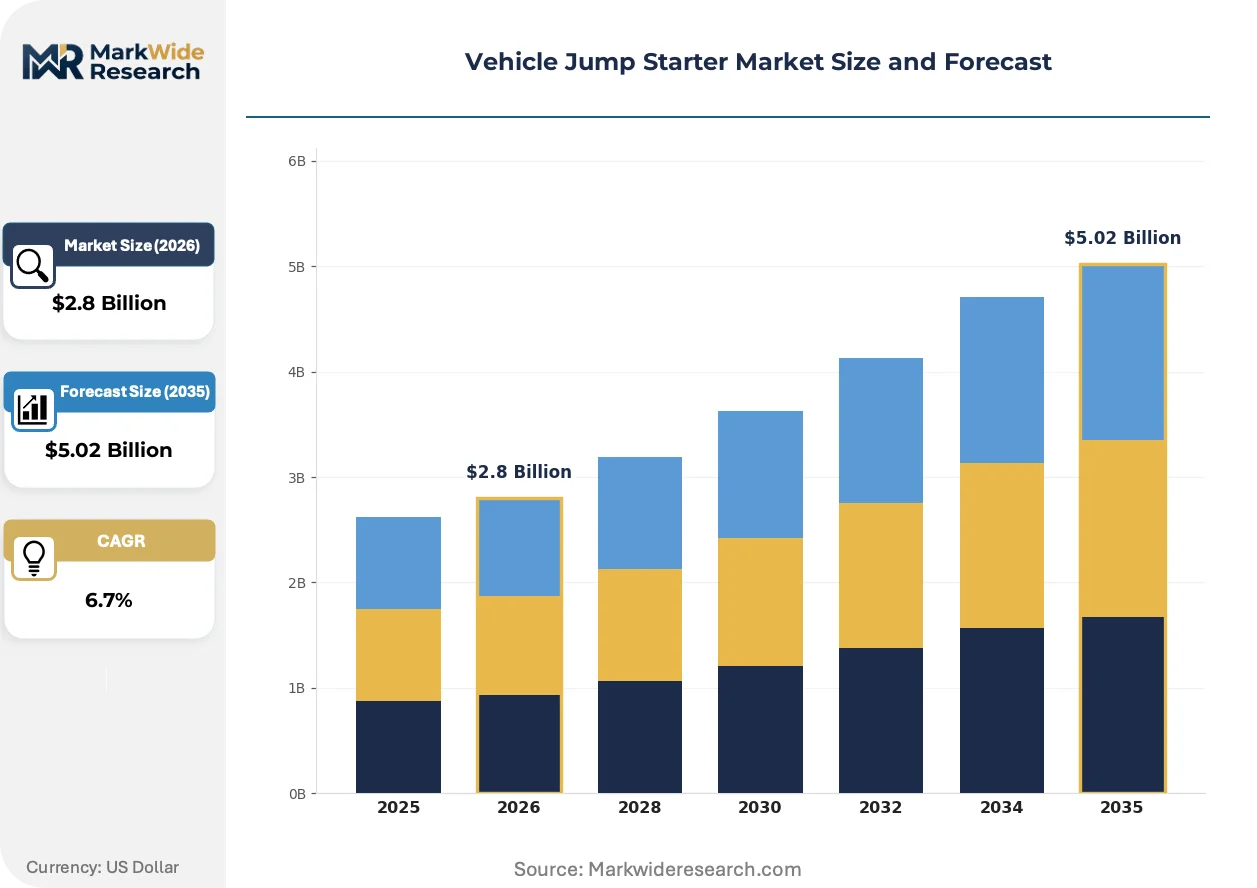
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Jump Starter with Air Compressor, Heavy-Duty, Multi-Function Technology: Lithium-Ion, Lead Acid, Smart Charging, Compact End User: Personal Vehicles, Commercial Fleets, Emergency Services, Rental Companies Distribution Channel: Online Retail, Automotive Parts Stores, Wholesale Distributors, Specialty Retailers |
| Companies Covered | NOCO Company, Clore Automotive, Stanley Black & Decker, Schumacher Electric Corporation, Anker Innovations, Energizer Holdings, CTEK Sweden AB, Antigravity Batteries LLC, Shenzhen DBPower Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Jump Starter Market Evolving Landscape
Product architecture is bifurcating between ultra-compact consumer units and ruggedized commercial systems, with feature convergence around USB-C power delivery and wireless charging pads becoming standard expectations rather than premium differentiators.
Gallium nitride (GaN) power electronics are rendering obsolete conventional silicon-based charging circuits in premium jump starter designs. Automotive aftermarket retailers report accelerating shelf space reallocation toward GaN-equipped models. The technology's thermal efficiency and volume reduction are compressing form factor constraints that previously limited glove-box compatibility.
NHTSA's tightening safety standards for battery-powered emergency devices are mandating enhanced short-circuit protection and thermal runaway containment in units sold through US commercial channels. Manufacturers must redesign housing architectures and add redundant fail-safe circuitry. Heavy-duty fleet procurement specifications now require third-party validation against updated FMVSS testing protocols.
Fleet maintenance departments are consolidating vendor relationships and demanding outcome-based service agreements that bundle equipment replacement with roadside response coverage. Traditional distributor networks face disintermediation as direct manufacturer partnerships with national motor clubs capture volume concentration. This pattern is most visible in Germany and the United Kingdom where commercial fleet management has centralized under large leasing operators.
Vehicle Jump Starter Market Segmentation
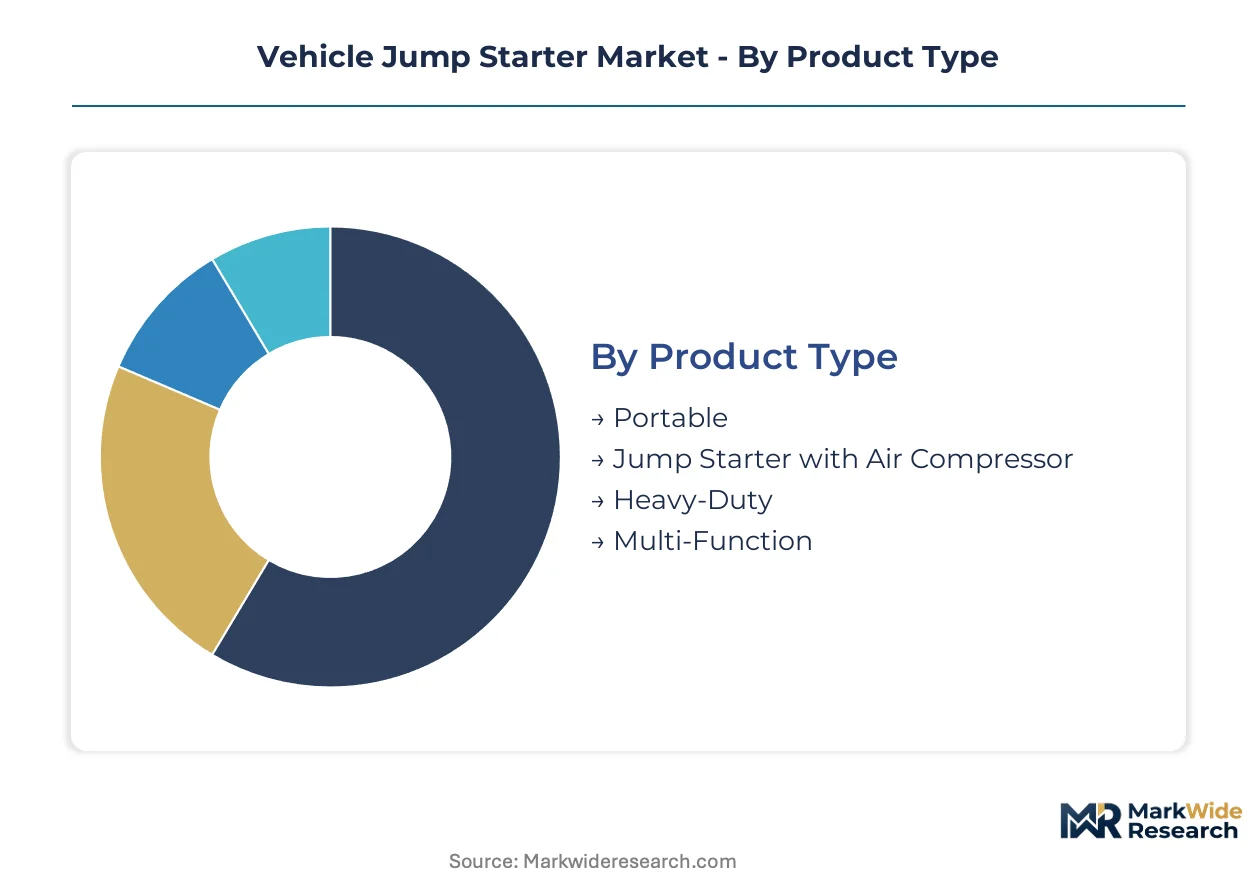
Vehicle jump starter procurement patterns diverge sharply across use cases, with fleet operators prioritizing duty-cycle reliability while consumers favor glove-box portability. Segment boundaries are blurring as multi-function designs absorb air compression and power delivery capabilities.
Product Type:
Mature configurations anchor commercial procurement, while emerging hybrid formats capture consumer attention through feature convergence.
- Portable:Compact lithium iron phosphate units rated 400-1500 peak amps dominate personal vehicle segments. Shenzhen manufacturers scale production of credit-card-thin designs for North American e-commerce channels where glove-box compatibility commands premium positioning.
- Jump Starter with Air Compressor:Integrated tire inflation functionality addresses roadside assistance use cases. Fleet operators in Germany and the United Kingdom specify these units for light commercial vehicles where space constraints prohibit separate equipment.
- Heavy-Duty:Professional-grade systems rated above 3000 peak amps service commercial trucking and mining equipment.
- Multi-Function:USB-C power delivery and wireless charging pads expand utility beyond engine starting.
Portable units retain volume leadership; multi-function designs hold the steepest expansion curve.
Technology:
Cost tiers separate established electrochemistry from emerging semiconductor integration.
- Lithium-Ion:Lithium iron phosphate cathodes deliver superior thermal stability and 2000+ cycle life. NHTSA certification requirements for battery transport safety are compressing supplier qualification timelines for units entering US commercial channels.
- Lead Acid:Legacy flooded and AGM configurations persist in price-sensitive aftermarket segments. India's tier-two cities still absorb these units through unorganized retail where distributor networks remain underdeveloped.
- Smart Charging:Microprocessor-controlled voltage regulation prevents overcharge damage.
- Compact:Gallium nitride power electronics enable 60% volume reduction versus silicon-based predecessors.
Lithium-ion retains volume leadership; compact designs gain share fastest.
End User:
Application intensity dictates durability specifications and procurement contract structures.
- Personal Vehicles:Consumer purchases favor sub-2-pound units with intuitive safety clamps. Amazon and direct-to-consumer channels capture volume as automotive parts stores reconfigure shelf space.
- Commercial Fleets:Logistics operators mandate UN 38.3 transport certification and outcome-based service agreements. National motor clubs in Germany consolidate vendor relationships under centralized leasing operators.
- Emergency Services:Fire departments and police fleets require FMVSS-validated thermal runaway containment.
- Rental Companies:Airport and urban fleet operators specify standardized units for customer self-service.
Commercial fleets retain volume leadership; emergency services hold the steepest expansion curve.
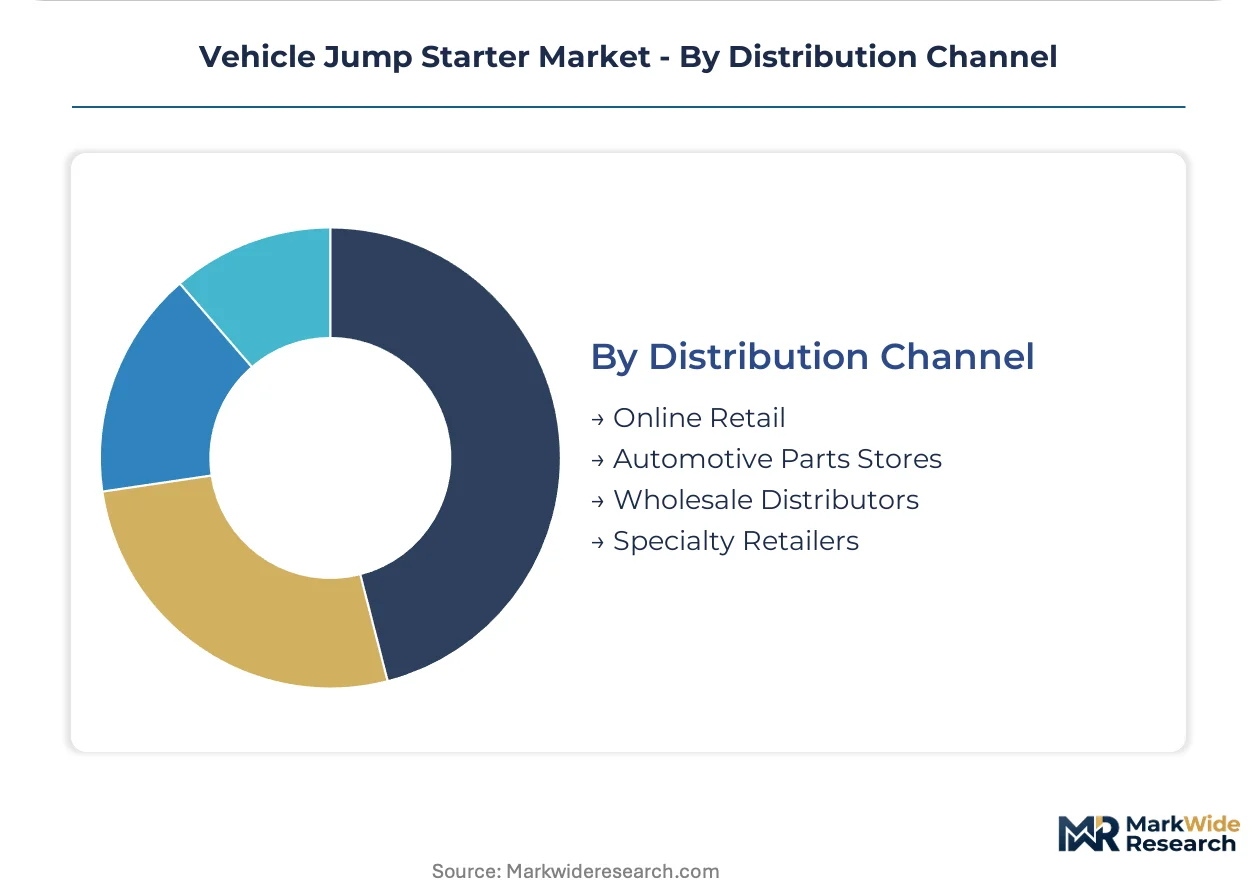
Distribution Channel:
Customer type determines channel preference, with procurement centralization favoring direct manufacturer relationships.
- Online Retail:Amazon and Alibaba platforms aggregate consumer demand with review-driven discovery. Cross-border e-commerce faces UN 38.3 testing timeline constraints that delay inventory positioning.
- Automotive Parts Stores:NAPA and O'Reilly Auto Parts reallocate shelf space toward lithium-ion and GaN-equipped models. Clore Automotive sustains presence through professional-grade charging system displays.
- Wholesale Distributors:Regional warehousing networks service independent repair shops and smaller fleet operators.
- Specialty Retailers:Camping and outdoor recreation channels expand addressable market beyond automotive applications.
Automotive parts stores retain volume leadership; specialty retailers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shenzhen anchors Asia-Pacific supply chain connectivity for lithium battery exports, while the Port of Long Beach handles inbound containerized electronics for North American distribution networks.
United States
Commercial fleet electrification compresses equipment replacement cycles at logistics operators. NHTSA tightens certification requirements for battery-powered emergency devices through updated FMVSS testing protocols. Los Angeles-area distributors reconfigure warehousing networks to accommodate lithium-ion transport restrictions.
Germany
Centralized fleet leasing operators consolidate vendor relationships under outcome-based service agreements. KBA enforces type approval standards for automotive auxiliary equipment entering commercial channels. Stuttgart's automotive supplier cluster integrates jump starter procurement into broader vehicle service contracts.
China
Domestic manufacturers scale production of compact multi-function units for export markets. SAMR enforces GB standards on lithium battery safety that govern export eligibility. Shenzhen's Pearl River Delta electronics corridor concentrates contract manufacturing capacity for global brands.
India
Underdeveloped organized retail in tier-two cities creates first-mover advantage for distributor network establishment. BIS certification requirements for imported electronics create compliance barriers for unqualified suppliers. Maharashtra's Pune-Nashik industrial belt absorbs initial professional-grade unit deployments.
Japan
Emergency services vehicle fleets specify thermal-stable lithium iron phosphate configurations. METI promotes domestic battery safety standards aligned with UN 38.3 transport protocols. Osaka-Kobe manufacturing corridor supplies precision battery management components to regional assemblers.
Vehicle Jump Starter Market Competitive Landscape
On the supply side, the industry is fragmented across three distinct capability tiers. Tier-one incumbents leverage captive charging system technology and established fleet service relationships. Tier-two specialists concentrate on compact lithium-ion form factors for consumer channels. Tier-three contract manufacturers in Guangdong Province supply private-label programs for mass-market retailers. Dominant competitive moves include portfolio diversification into portable power stations and strategic partnerships with national motor clubs.
Within the premium-tier segment, NOCO Company and Clore Automotive exemplify divergent specialization strategies. NOCO Company represents the technology-anchored archetype with proprietary boost circuitry integration. Clore Automotive occupies the professional-grade systems position through heavy-duty charging equipment heritage. Shenzhen DBPower Technology anchors the export-oriented manufacturing tier, supplying compact multi-function designs for cross-border e-commerce channels.
| Leading Market Players |
|---|
| NOCO Company |
| Clore Automotive |
| Stanley Black & Decker |
| Schumacher Electric Corporation |
| Anker Innovations |
| Energizer Holdings |
| CTEK Sweden AB |
| Antigravity Batteries LLC |
| Shenzhen DBPower Technology |
| Others |
Value Network & Pricing Analysis
Lithium carbonate price volatility determines both pricing tier spreads and supply chain shape, forcing mid-tier manufacturers toward captive supply arrangements while premium brands absorb margin compression through feature bundling. This feedstock instability compresses procurement timelines across Guangdong Province contract manufacturers and accelerates backward integration strategies among volume leaders.
Pricing Analysis
Volume-discount tiering structures separate professional-grade fleet procurement from personal vehicle retail channels, with UN 38.3 certification and GaN power electronics commanding premium positioning. Three-tier pricing structure across premium, standard, and economy levels reflects duty-cycle reliability ratings and after-sales service bundling. Pricing pressure stems from raw material input costs, particularly cathode production expenses. Fleet operators exhibit lowest price sensitivity due to outcome-based service agreements, while e-commerce consumers drive economy-tier competition.
Supply Chain Analysis
Upstream feedstock concentration in Chile, Australia, and Argentina's lithium triangle anchors cathode material flows to Shenzhen and Dongguan assembly corridors. Cell production draws from South Korean and Japanese separator technology, with power management semiconductors sourced from Taiwan and Germany. Single-source vulnerability concentrates in Guangdong Province contract manufacturing, where localized energy rationing disrupts export schedules. Distribution runs through Los Angeles-area warehousing for North American aftermarket channels and Rotterdam hub facilities for European fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where NHTSA certification requirements and UN 38.3 transport protocols create sticky supplier relationships that resist price-based displacement.
For Market Incumbents: Entrench position through captive supply of lithium iron phosphate cells and exclusive service agreements with national motor clubs. Expand certification investment in FMVSS-validated thermal runaway containment to defend against emerging GaN-equipped challengers. Deepen backward integration into battery management system firmware development. For New Entrants and Emerging Players: India's tier-two cities with underdeveloped organized retail represent the most penetrable entry point for professional-grade unit distribution. Camping and outdoor recreation channels in North America offer white-space positioning beyond traditional automotive applications. Pursue direct-to-consumer launch with review-optimized Amazon storefronts to bypass established automotive parts store gatekeepers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with captive cell supply and multi-region certification portfolios. Long-term viability hinges on lithium chemistry expertise and firmware development capacity. Monitor UN 38.3 testing timeline extensions as an inflection indicator for inventory positioning advantages.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Power Electronics Integration | Enables 60% volume reduction for glove-box-compatible designs competing through NOCO's Boost technology positioning. |
| Multi-Function Feature Convergence | Absorbs air compression and USB-C power delivery to capture camping channel expansion beyond automotive applications. |
| Outcome-Based Service Agreements | Bundles equipment replacement with roadside response coverage to lock in German and UK fleet leasing operator relationships. |
| Regulatory Certification Investment | Secures NHTSA FMVSS validation and UN 38.3 air freight eligibility for cross-border e-commerce inventory positioning. |
| Backward Integration into Cell Supply | Captures lithium iron phosphate production margin and insulates against carbonate price volatility through Shenzhen manufacturing partnerships. |
Research Methodology
A standing panel of fleet procurement managers, automotive aftermarket distributors, lithium battery safety engineers, and roadside assistance program directors provided ongoing calibration across primary interview cycles. Secondary validation drew from NHTSA FMVSS testing protocol filings, SAMR GB standard enforcement records, UN 38.3 transport certification databases, and customs trade data for lithium battery exports. Bottom-up unit shipment estimates triangulated against top-down value projections.
Scenario-bracketing anchored projections across conservative, baseline, and aggressive lithium carbonate price trajectories throughout the forecast period. Segmentation dimensions modeled include product type, electrochemistry, end-user intensity, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to fleet electrification adoption patterns and consumer channel shift velocities. Industry-specific inputs incorporated roadside assistance equipment replacement cycles and GaN semiconductor penetration rates.
Practitioners should monitor lithium carbonate spot price movements and NHTSA certification backlog durations for early signals requiring forecast revision. Cross-checking against IHS Markit vehicle production data and commercial fleet registration trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Smoke Spill Motor Market
Automotive Parts
Automotive Belts Market
Automotive Parts
Europe Roll Forming Body in White Market
Automotive Parts
Electric Power Steering Market
Automotive Parts
Asia-Pacific Electric Power Steering Market
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
Tire Mold Market
Automotive Parts
Automotive Cylinder Head Gasket Market
Automotive Parts
Latin America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Brass Synchronizer Ring Market
Automotive Parts
South Korea Passenger Vehicles Lubricants Market
Automotive Parts
Industrial V Belt Market
Automotive Parts
Mexico Automotive Air Filters Market
Automotive Parts
Global Automotive Nitrous Oxide System Market
Automotive Parts
Global Climate Control System for Commercial Vehicle Market
Automotive Parts
Motorcycle Aluminum Casting Market