
 Driving Helmet Market | 2026-2036
Driving Helmet Market Size, Share, and Industry Trends Forecast 2026-2036
Driving Helmet Market Analysis
Software-defined ventilation and connected safety diagnostics bundled through subscription tiers is realigning how manufacturers monetize head protection. Arai Helmet Ltd. leverages its handmade shell construction to sustain premium positioning across professional racing circuits. Bell Helmets anchors its competitive stance through deep control over North American distribution channels for competitive and commuter segments. Shoei Co., Ltd. differentiates via proprietary AIM+ composite shell technology that extends its reputation for impact dispersion among safety-conscious riders.
A driving helmet is a form-fitted protective headgear engineered from layered composites—typically polycarbonate, fiberglass, carbon fiber, or Kevlar—with EPS impact liners and retention systems designed to absorb kinetic energy during collision events. Full-face configurations dominate the premium tier due to superior chin-bar protection, while carbon fiber material grades command the highest margin pools by balancing mass reduction against structural rigidity. Modular designs are gaining share among commuters seeking versatility between open-face convenience and closed-circuit protection. ECE and Snell safety ratings function as gatekeeping standards that stratify pricing and channel access across retail and direct-to-consumer platforms.
DOT certification administered by the NHTSA governs minimum legal sale in the United States, while ECE R22.06 enforced by European type-approval bodies is raising bar for rotational-impact testing and visor optical clarity. India's BIS certification mandate under the Central Motor Vehicles Rules is compelling domestic and import brands to localize testing infrastructure for market entry. Stakeholders must monitor how divergent safety-rating stringency across these jurisdictions reshapes R&D allocation and manufacturing footprint decisions.
Market Dynamics
ECE R22.06 mandates are compressing product development cycles as manufacturers redesign shell geometries and visor assemblies to satisfy rotational-impact testing protocols. This regulatory tightening is simultaneously elevating R&D expenditure and creating tiered market stratification between certified and non-compliant inventory.
Growth Catalysts
- Professional Racing Circuits:Motorsport participation in India and Southeast Asia is expanding the addressable base for premium full-face configurations. Track-day licensing requirements in these markets mandate Snell or ECE-rated equipment.
- ECE R22.06 Implementation:European type-approval bodies are enforcing stricter impact-absorption standards that compel manufacturers to upgrade EPS liner densities and shell composite formulations.
- Carbon Fiber Material Grades:Advances in prepreg layup automation are reducing unit costs for aerospace-grade carbon fiber, enabling broader adoption in mid-tier helmet segments previously constrained to fiberglass.
Market Restraints
- Raw Material Concentration:Toray Industries and Hexcel Corporation control over 70% of global aerospace carbon fiber supply, creating input cost volatility for premium shell manufacturers.
- Certification Timeline Friction:ECE R22.06 testing protocols extend type-approval cycles by 8-14 months, freezing working capital in pre-certified inventory.
- Modular Design Trade-offs:Hinge mechanisms in flip-up configurations introduce structural failure points that limit Snell certification eligibility, constraining premium positioning.
Strategic Opportunities
- Software-Defined Ventilation:Integration of MEMS airflow sensors with smartphone telemetry is automating climate control adjustments based on rider biometric data.
- Subscription Diagnostics:Connected safety platforms offering crash-detection alerts and maintenance scheduling are creating recurring revenue streams beyond hardware margins.
- India BIS Localization:Central Motor Vehicles Rules mandate domestic testing infrastructure, favoring early entrants establishing captive certification laboratories in Pune and Chennai.
Industry Challenges
- Composite Engineering Talent Scarcity:Specialized knowledge in AIM+ and proprietary shell layup techniques concentrates within Japanese and Italian manufacturing clusters, limiting geographic diversification.
- Multi-Certification Inventory Complexity:Parallel DOT, ECE, and BIS compliance requirements force SKU proliferation that strains distribution logistics and forecasting accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Driving Helmet Market |
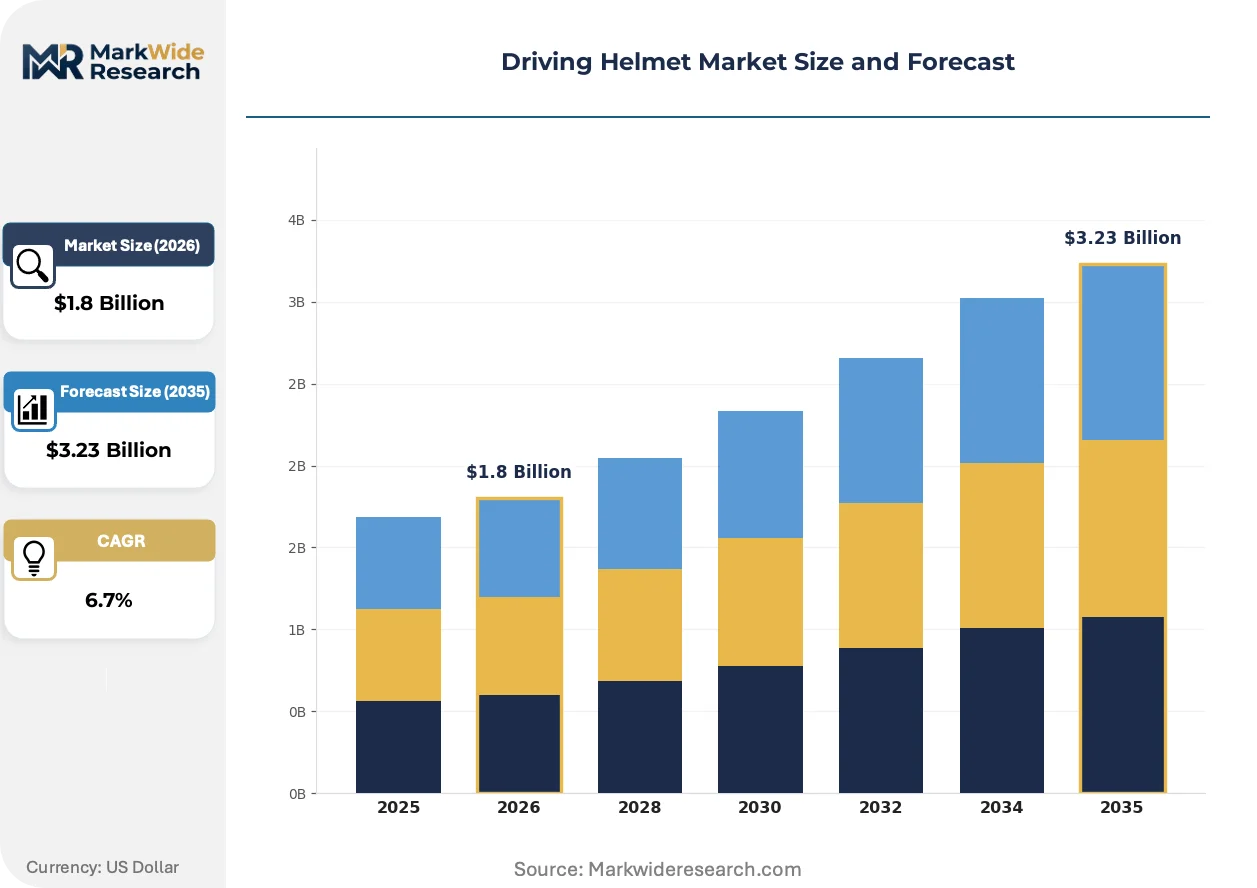
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full-Face, Open-Face, Modular, Half-Helmet Material: Polycarbonate, Fiberglass, Carbon Fiber, Kevlar Safety Rating: DOT, ECE, Snell, FIM End User: Professional Racers, Commuters, Recreational Riders, Off-Road Enthusiasts |
| Companies Covered | Arai Helmet Ltd., Bell Helmets, Shoei Co., Ltd., HJC Helmets, Schuberth GmbH, AGV, Shark Helmets, Nolan Helmets, LS2 Helmets, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Driving Helmet Market Emerging Trajectories
Connected helmet architectures are displacing passive protection as the primary value proposition, with manufacturers bundling hardware, software, and services into integrated safety ecosystems. This convergence is redrawing competitive boundaries between traditional gear producers and consumer electronics suppliers.
Sensor-integrated impact detection is automating emergency response protocols through accelerometer-gyroscope fusion that distinguishes crash events from routine riding vibrations. Professional racing teams are piloting real-time telemetry feeds to pit crews, compressing medical response windows during on-track incidents. The technology is automating liability documentation for insurance carriers, creating secondary revenue channels through data licensing arrangements.
ECE R22.06 mandates from European type-approval bodies are mandating rotational-impact testing through oblique anvil strikes that simulate angular acceleration trauma. Manufacturers must redesign internal liner geometries and add low-friction slip-plane layers to achieve compliance. Full-face configurations face the steepest redesign burden, while open-face and modular designs confront certification eligibility constraints under the revised protocol.
Direct-to-consumer channel expansion is fragmenting traditional powersports retail relationships as digitally native brands capture younger rider demographics through social media engagement and virtual fitment tools. Specialty retailers in Germany and the United Kingdom are responding with experiential showroom investments that emphasize professional fitting services and track-day event sponsorships. India exhibits the most pronounced channel tension, where urban commuters research online but purchase through local dealers seeking post-sale adjustment support.
Driving Helmet Market Segmentation
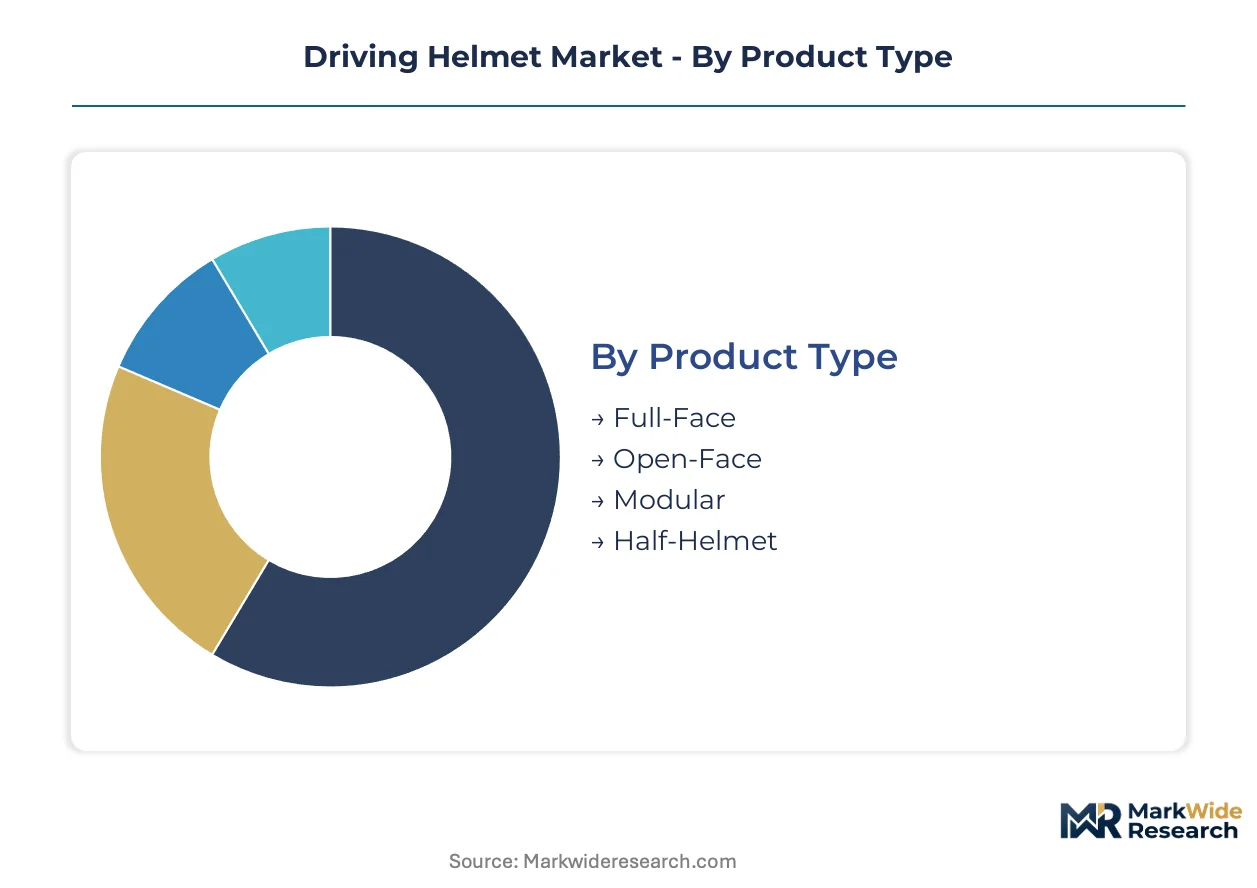
Helmet manufacturers allocate composite engineering capacity and certification testing resources unevenly across segment boundaries. Supply concentration in shell fabrication and liner molding creates divergent margin profiles that reshape portfolio prioritization decisions.
Product Type:
Shell fabrication capacity concentrates in full-face configurations where chin-bar integration demands unified molding processes rather than modular assembly.
- Full-Face:Enclosed chin-bar architecture integrates visor mechanism and ventilation ducts into a single structural unit. Professional racing circuits in India and Southeast Asia mandate this configuration for track-day licensing, compressing approval timelines for certified suppliers.
- Modular:Flip-up hinge mechanisms enable transitions between open-face convenience and closed-circuit protection. Hinge engineering introduces failure points that exclude most designs from Snell certification eligibility, constraining premium channel placement.
- Open-Face:Three-quarter coverage shell omits chin protection for urban maneuverability. European commuters favor this format for scooter mobility in dense traffic corridors.
- Half-Helmet:Minimal coverage design prioritizes mass reduction and thermal comfort. Regulatory acceptance varies sharply by jurisdiction, limiting cross-border inventory fungibility.
Full-face configurations absorb the bulk of installed capacity; modular designs are expanding most quickly among commuters seeking versatility trade-offs.
Material:
Raw material procurement patterns stratify manufacturing footprints between commodity thermoplastics and aerospace-grade composites.
- Carbon Fiber:Pre-impregnated layup construction delivers superior strength-to-weight ratios through unidirectional fiber alignment. Toray Industries and Hexcel Corporation supply over 70% of aerospace-grade feedstock, creating input cost volatility for premium shell producers.
- Fiberglass:Woven glass fiber mats saturated with thermoset resins balance impact absorption against unit economics. Indian manufacturers leverage this grade for BIS certification compliance under Central Motor Vehicles Rules mandates.
- Polycarbonate:Injection-molded thermoplastic shells enable high-volume production with consistent wall thickness. Mass-market commuter helmets dominate this tier.
- Kevlar:Aramid fiber reinforcement enhances puncture resistance in high-impact zones. Limited adoption reflects processing complexity and material cost premiums relative to carbon alternatives.
Carbon fiber commands the steepest margin premiums; fiberglass is climbing the fastest as Indian localization requirements reshape sourcing strategies.
Safety Rating:
Certification stringency tiers function as gatekeeping mechanisms that determine retail channel access and pricing authority.
- ECE:European type-approval protocol R22.06 mandates rotational-impact testing through oblique anvil strikes. Manufacturers redesign shell geometries and add slip-plane layers to achieve compliance, extending development cycles.
- Snell:Independent foundation protocol imposes impact-energy thresholds exceeding regulatory minimums. Professional racing teams and track-day organizers specify this rating for liability mitigation.
- DOT:NHTSA-administered baseline standard governs minimum legal sale in the United States. Self-certification structure permits faster market entry but carries lower retail price realization.
- FIM:International Motorcycling Federation protocol governs homologation for world championship competition. Limited production runs and specialized testing restrict this tier to factory racing programs.
ECE-rated inventory absorbs the bulk of certification laboratory capacity; FIM is gaining share fastest among factory racing suppliers.
End User:
Customer archetypes distribute across sharply divergent performance requirements and replacement cadences.
- Professional Racers:FIM-homologated equipment with integrated telemetry compatibility. Motorsport participation expansion in India and Southeast Asia is widening the addressable base for premium configurations.
- Commuters:Daily-use helmets prioritizing ventilation efficiency and optical clarity. Modular designs are displacing open-face preferences in European urban markets.
- Recreational Riders:Weekend touring and leisure motorcycling with moderate mileage accumulation. Replacement cycles stretch 3-5 years versus annual refresh rates for competitive users.
- Off-Road Enthusiasts:Motocross and enduro disciplines demanding peak ventilation and goggle integration. Peak visor architecture and extended chin bars distinguish this specification.
Professional racers concentrate the highest per-unit expenditure; commuters represent the steepest expansion trajectory in absolute volume terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pune anchors helmet manufacturing expansion in India, where BIS certification laboratories cluster along the Mumbai-Pune industrial corridor. This concentration reflects regulatory localization mandates and proximity to Maharashtra's motorsport circuits.
United States
Track-day licensing growth in California and Florida drives Snell-certified equipment procurement. NHTSA administers DOT baseline standards through self-certification structures that accelerate market entry. Bell Helmets maintains headquarters and distribution control in California's powersports retail corridor.
Germany
ECE R22.06 enforcement by KBA tightens rotational-impact testing protocols for visor and shell assemblies. Schuberth GmbH operates manufacturing in Magdeburg, where automated prepreg layup systems serve European premium segments.
India
Two-wheeler ownership expansion in Maharashtra and Tamil Nadu widens addressable demand for BIS-certified head protection. Central Motor Vehicles Rules mandate domestic testing infrastructure, compelling import brands to establish captive laboratories in Pune and Chennai. Royal Enfield's racing program in Coimbatore accelerates professional-tier equipment adoption.
Japan
AIM+ composite shell expertise concentrates in Tokyo and Osaka manufacturing clusters. METI oversees industrial standards coordination for export-oriented producers. Shoei Co., Ltd. maintains proprietary layup facilities in Iwate Prefecture, supplying FIM-homologated equipment to factory racing programs.
Italy
AGV and Nolan Helmets anchor carbon fiber helmet production in Veneto and Lombardy regions. ECE type-approval bodies in Milan enforce revised impact-absorption standards. The Modena motorsport corridor drives professional racer equipment specifications across European circuits.
Driving Helmet Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across certification-tier stratification. Integrated manufacturers controlling shell fabrication and liner molding dominate premium ECE and Snell segments, while brand licensors relying on contract foundries populate mass-market polycarbonate tiers. Three archetypes define competitive positioning: proprietary composite specialists, distribution-anchored heritage brands, and digitally native direct-to-consumer entrants. Consolidation pressure manifests through certification laboratory acquisitions and exclusive racing sponsorship contracts.
Among Japanese composite specialists, Arai Helmet Ltd. and Shoei Co., Ltd. exemplify proprietary shell-technology differentiation. Schuberth GmbH represents German engineering-focused automation in European markets. Bell Helmets occupies a position as a North American distribution-anchored heritage brand with deep retail channel control.
| Leading Market Players |
|---|
| Arai Helmet Ltd. |
| Bell Helmets |
| Shoei Co., Ltd. |
| HJC Helmets |
| Schuberth GmbH |
| AGV |
| Shark Helmets |
| Nolan Helmets |
| LS2 Helmets |
| Others |
Supply Flow & Price Mechanics
Composite engineering talent concentration in Japan and Italy feeds labor-cost differentials that widen pricing-tier spreads between handmade shell construction and mass-market thermoplastic molding. ECE R22.06 certification complexity further stratifies margin pools as manufacturers absorb extended testing timelines into premium positioning.
Pricing Analysis
Safety-outcome pricing anchors valuation to crash-test performance rather than material cost alone. Three-tier pricing structure across premium, standard, and economy levels separates FIM-homologated racing equipment from ECE-certified commuter gear and DOT-baseline mass-market units. Price differentiation hinges on certification grade and shell composite sophistication. Cost compression in polycarbonate commuter tiers is intensifying because Indian BIS localization mandates force import brands to absorb captive laboratory overhead. Commuter segments exhibit highest price sensitivity; professional racing teams demonstrate lowest sensitivity due to liability-driven specification requirements.
Supply Chain Analysis
Dual-sourcing requirements from major OEMs mandate multi-supplier qualification for aerospace-grade carbon fiber feedstock. Manufacturing gravity centers on Japan, Italy, and India, with shell fabrication drawing from Toray Industries prepreg and Hexcel Corporation unidirectional fiber. Raw material dependencies rest on epoxy resin systems, EPS liner foam, and visor polycarbonate. Single-source vulnerability concentrates in aerospace carbon fiber supply where two producers dominate. Distribution runs through powersports retail chains in North America, specialized fitting showrooms in Germany and the United Kingdom, and local dealer networks in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The driving helmet sector sits in a technology-transition phase where connected safety platforms displace passive protection as the primary value proposition. Sensor-integrated telemetry and subscription diagnostics are supplanting legacy hardware-only business models.
For Market Incumbents: Deepen proprietary composite shell expertise through captive engineering retention in Iwate and Veneto manufacturing clusters. Accelerate software-defined ventilation R&D to defend against consumer electronics entrants. ECE R22.06 compliance investment serves as the priority lever to lock out uncertified competitors from European premium channels.
For New Entrants and Emerging Players: Launch via direct-to-consumer digital channels targeting Indian urban commuters who research online but seek post-sale fitting support. White-space concentration sits in mid-tier carbon fiber segments where prepreg automation cost reductions enable margin capture previously reserved for fiberglass. Connected safety subscription bundles offer the most penetrable revenue architecture.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists with captive certification laboratory infrastructure. Long-term viability hinges on regulatory compliance capability rather than brand heritage alone. Watch BIS laboratory acquisition activity in Pune and Chennai as the inflection signal for India market access consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Laboratory Acquisition | Captive BIS testing infrastructure in Pune accelerates India market entry for import brands. |
| Connected Safety Platform Launch | Crash-detection telemetry bundled with hardware creates recurring revenue beyond unit sales. |
| Carbon Fiber Prepreg Partnership | Long-term supply agreements with Toray Industries reduce input cost volatility for premium shells. |
| Direct-to-Consumer Channel Expansion | Virtual fitment tools capture younger rider demographics outside traditional powersports retail. |
| Software-Defined Ventilation Integration | MEMS airflow sensors automate climate control based on rider biometric data. |
Methodological Framework
Independent corroboration across helmet manufacturing executives, motorsport team equipment managers, and BIS certification laboratory directors underwrites the qualitative findings. Primary fieldwork incorporated structured interviews with composite engineering leads at shell fabrication facilities, procurement officers at carbon fiber suppliers, and channel heads at European specialty retailers. Secondary validation drew from ECE type-approval filings, NHTSA DOT certification databases, Central Motor Vehicles Rules documentation, and customs trade records. Bottom-up demand modeling triangulated against top-down market sizing across product type, material grade, safety rating tier, and end-user segment.
Comparable-period anchoring aligned the projection horizon against historical certification cycle lengths and replacement cadence patterns in professional racing versus commuter segments. The analytical framework modeled volume and value trajectories across full-face, modular, open-face, and half-helmet configurations; carbon fiber, fiberglass, polycarbonate, and Kevlar material grades; ECE, Snell, DOT, and FIM safety ratings; and professional racer, commuter, recreational rider, and off-road enthusiast end-user archetypes. CAGRs were derived from segmented growth rate reconciliation. Forecast inputs incorporated ECE R22.06 implementation timelines, Indian two-wheeler ownership expansion curves, and prepreg automation cost reduction slopes.
The model assumes a particular technology adoption path; alternative pathways for connected helmet architectures would alter the outlook. Forecasts reflect assumptions regarding regulatory enforcement consistency, raw material supply continuity, and motorsport participation growth in India and Southeast Asia. Deviation in BIS certification laboratory capacity expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Airbag Control Unit Sensor Market
Automotive Safety and Security Systems
Global Automotive Lidar Sensor Market
Automotive Safety and Security Systems
Motorcycle Stability Control Market
Automotive Safety and Security Systems
Asia Pacific Airbag Systems Market
Automotive Safety and Security Systems
Automotive Crash Barriers Market
Automotive Safety and Security Systems
Stolen Vehicle Recovery (SVR) Tracking Service Market
Automotive Safety and Security Systems
Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Driver State Monitoring Systems Market
Automotive Safety and Security Systems
Front Collision Warning Market
Automotive Safety and Security Systems
ICE Start and Stop System Market
Automotive Safety and Security Systems
Automotive Smart Security Device Market
Automotive Safety and Security Systems
Automotive Brake Actuation Systems Market
Automotive Safety and Security Systems
Automatic Emergency Braking Market
Automotive Safety and Security Systems
Automotive Start-Stop System Market
Automotive Safety and Security Systems
China Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automotive Radar Market