
 Needle Roller Bearings Market | 2026-2036
Needle Roller Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Needle Roller Bearings Market Analysis
Aftermarket predictive maintenance subscriptions is decoupling hardware sales from pure unit economics in the bearing sector. SKF leverages digital vibration-monitoring services to extend customer lifetime value beyond initial product shipment. Schaeffler Group anchors its European position through captive remanufacturing networks that recover used needle roller assemblies. NSK Ltd. competes on ceramic-hybrid needle roller variants for electric vehicle reduction gearboxes.
Needle roller bearings are rolling-element bearings with slender cylindrical rollers whose length-to-diameter ratio exceeds three to one, typically manufactured from through-hardened chromium steel with raceway surface finishes below 0.2 micrometers Ra to withstand oscillating loads in constrained radial envelopes. Their primary purpose is to support high radial loads within minimal axial cross-sections where conventional ball or tapered roller geometries cannot fit. Automotive transmissions represents the most mature application segment, with established OEM qualification cycles and price transparency compressing margins for standard catalogue items. Robotics applications generate the fastest structural expansion, as collaborative arm joints and precision reducers demand caged needle roller configurations with sub-micron positional repeatability. Industrial machinery retains the deepest margin pools, particularly in replacement cycles for machine tool spindles and printing press cylinders where downtime costs override component price sensitivity.
EPA emissions thresholds in the United States and NHTSA fuel-economy mandates push automotive suppliers toward lighter, lower-friction needle roller designs in transmission and engine auxiliary systems. EMA and REACH in Europe enforce restricted substance limits on lubricant additives and bearing steel alloying elements, raising compliance costs for non-integrated suppliers. ISO 492 and JIS B 1514 dimensional tolerances govern international interchangeability, yet regional certification preferences still fragment procurement specifications. Stakeholders must monitor ceramic material qualification progress and lubricant compatibility testing protocols as electrified powertrains eliminate conventional engine-oil splash environments.
Market Dynamics
Electric drivetrain architectures are eliminating conventional engine-oil splash environments that historically lubricated needle roller bearings in transmission housings, forcing material scientists to redesign cage geometries and surface coatings for dry-running or grease-limited conditions.
Growth Catalysts
- EMA and REACH substance restrictions:European material standards for bearing steels and lubricant additives are accelerating R&D investment in compliant alloy formulations and synthetic base stocks that outperform legacy mineral oils.
- Robotics precision reducers:Collaborative arm joints demand caged needle roller configurations with sub-micron positional repeatability, creating specification premiums unavailable in automotive transmission commodity tiers.
- German manufacturing clusters:Precision OEM supply chains co-located with bearing producers in Stuttgart and Schweinfurt compress logistics costs and qualification timelines for high-volume transmission programs.
Market Restraints
- Chromium steel input volatility:Through-hardened bearing steel alloys face price swings tied to ferrochrome supply from South African smelters, squeezing margin predictability for mid-tier catalogue producers.
- Substitution by ceramic hybrids:Silicon nitride rolling elements in electric vehicle reduction gearboxes displace conventional steel needles in high-speed, low-lubrication regimes above fifteen thousand RPM.
- REACH compliance friction:Non-integrated suppliers lacking in-house metallurgical laboratories face eighteen-month certification delays for new alloy compositions containing restricted hexavalent chromium alternatives.
Strategic Opportunities
- Japan automotive electrification:METI carbon-neutrality roadmaps are mandating domestic EV production scale-up, opening qualification windows for needle roller variants engineered for e-axle differentials and reduction stages.
- Predictive maintenance subscriptions:Vibration-monitoring digital services bundled with hardware shipments extend customer lifetime value beyond initial bearing replacement cycles in industrial machinery accounts.
- China machine tool retrofit:Aging spindle installations in Shenzhen and Suzhou manufacturing corridors require precision replacement bearings where downtime costs override component price sensitivity.
Industry Challenges
- Surface finish metrology talent:Sub-0.2 micrometer Ra raceway specifications demand operators trained in white-light interferometry and atomic force microscopy, skills concentrated in German and Japanese technical institutes.
- ISO 492 certification timelines:International dimensional tolerance verification requires inter-laboratory comparison studies that extend product launch schedules by eight to fourteen months for new needle roller geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Needle Roller Bearings Market |
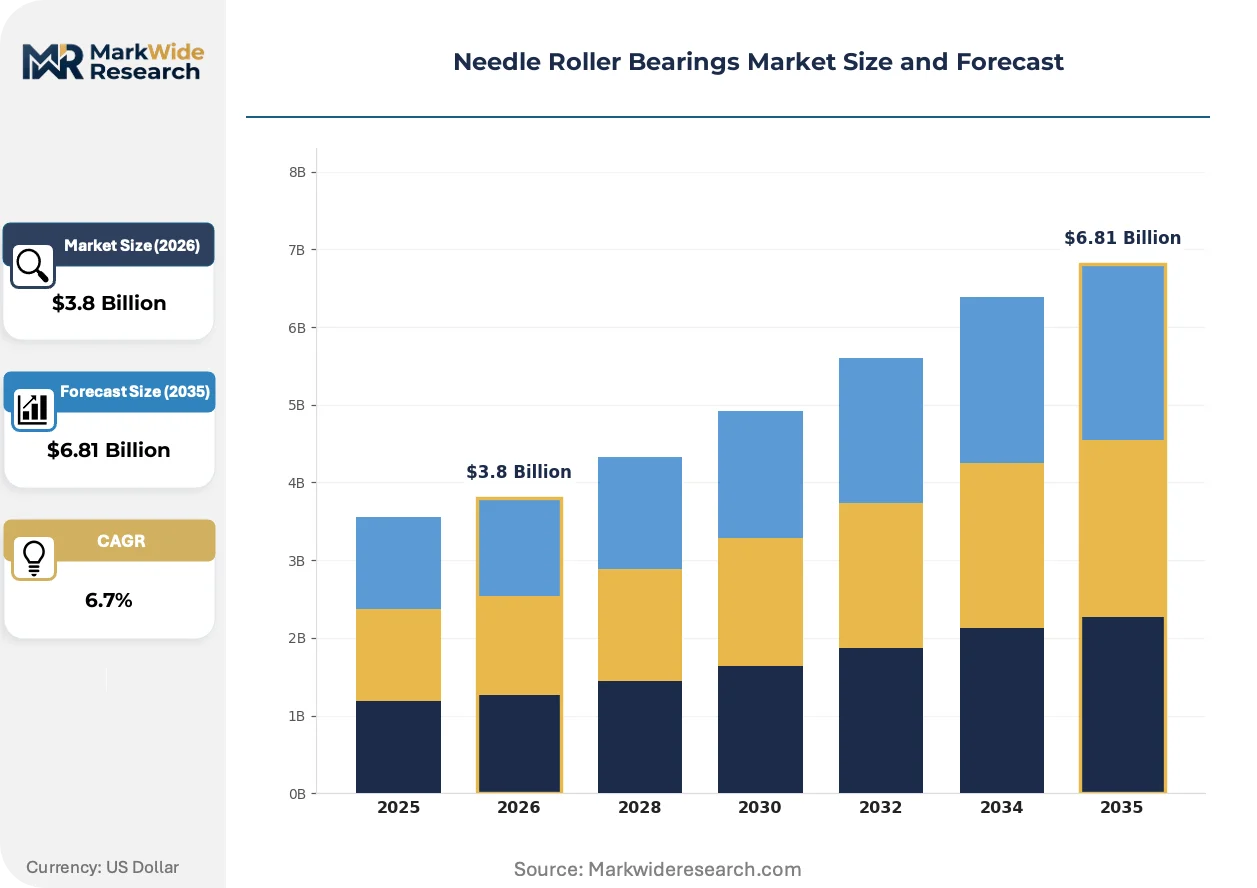
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Needle Roller, Cage, Retainer, Separator Industry Vertical: Aerospace, Automotive, Industrial Machinery, Consumer Electronics Mounting Style: Grease Lubricated, Oil Lubricated, Seal Type, Open Type Application: Automotive Transmissions, Robotics, Marine Equipment, Agricultural Equipment |
| Companies Covered | SKF, IKO International, Inc., NSK Ltd., RBC Bearings Incorporated, JTEKT Corporation, NTN Corporation, Timken, Zhejiang Waxing Electromechanical Co., Ltd., Schaeffler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Needle Roller Bearings Market Emerging Trajectories
Ceramic-hybrid material systems, predictive digital services, and consolidated procurement specifications are restructuring how needle roller bearings are engineered, sold, and replaced across automotive and industrial verticals.
Silicon nitride ceramic rolling elements deliver density advantages forty percent below steel equivalents, enabling higher speed limits in electric vehicle reduction gearboxes where centrifugal loading previously constrained steel needle performance. Tier-one drivetrain suppliers in Japan and Germany are qualifying these hybrids for production volumes scheduled across the coming decade. This ceramic migration is converging with advanced polyetheretherketone cage designs that eliminate metal-to-metal contact in dry-running conditions.
EPA emissions thresholds and NHTSA fuel-economy mandates in the United States are pressuring automotive suppliers toward lighter, lower-friction needle roller configurations in transmission and engine auxiliary systems. Lubricant formulators must validate additive packages against new thermal profiles while maintaining compatibility with existing seal elastomers. Powertrain engineering teams in Detroit and Tennessee are responding by specifying ion-plated coatings that reduce boundary friction coefficients below 0.05 in stop-start urban cycles.
Industrial machinery buyers are unbundling hardware procurement from aftermarket service contracts, negotiating vibration-monitoring subscriptions that predict bearing failure before unplanned downtime occurs. SKF and Schaeffler digital platforms are displacing traditional distributor relationships in German automotive supplier parks and Japanese precision manufacturing corridors. This service-model pivot is most visible in printing press and machine tool accounts where single-shift downtime exceeds component replacement costs by orders of magnitude.
Needle Roller Bearings Market Segmentation
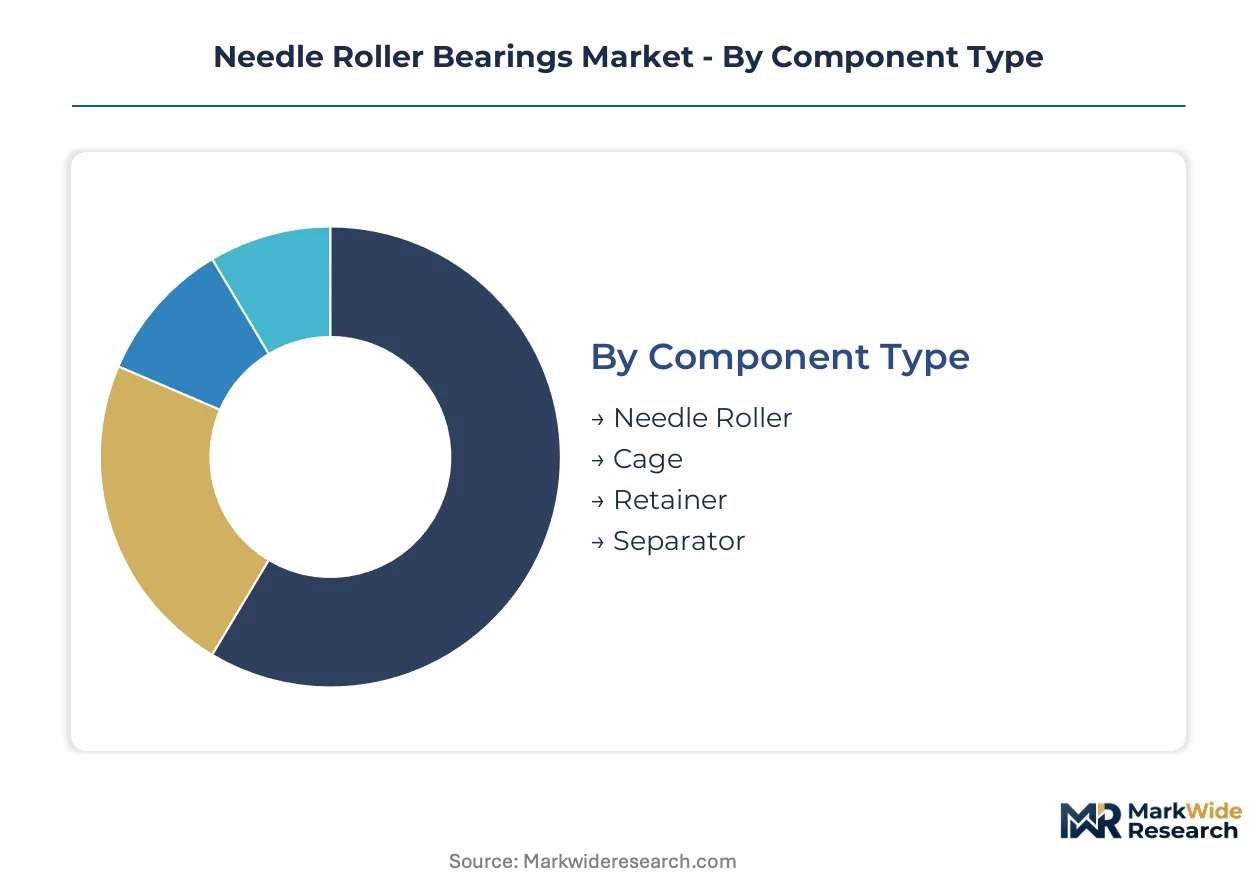
Needle roller bearing procurement splits sharply between specification-driven OEM transmission programs and price-sensitive industrial replacement cycles. Component geometry, lubrication architecture, and end-use duty cycles each create distinct margin tiers that suppliers must navigate simultaneously.
Component Type:
Buyers in this category differentiate by assembly complexity tolerance and maintenance access constraints.
- Needle Roller:Through-hardened chromium steel cylinders with length-to-diameter ratios exceeding three-to-one, precision-ground to sub-0.2 micrometer Ra surface finishes. Demand concentrates in Stuttgart and Schweinfurt manufacturing corridors where German automotive OEMs specify these for high-volume transmission programs under REACH-compliant material certifications.
- Cage:Polyetheretherketone and steel ribbon configurations that maintain roller spacing under oscillating loads. Robotics manufacturers in Japan prioritize caged assemblies for collaborative arm joints requiring sub-micron positional repeatability, paying specification premiums unavailable in commodity automotive tiers.
- Retainer:Stamped steel or brass stampings for low-speed industrial applications.
- Separator:Discrete spacer elements used in custom heavy-duty assemblies.
Volume sits with Needle Roller; growth tilts toward Cage.
Industry Vertical:
Margin durability varies dramatically by end-use downtime costs and qualification cycle length.
- Automotive:Transmission and e-axle applications dominate unit economics, with EPA emissions thresholds and NHTSA fuel-economy mandates pressuring suppliers toward lighter, lower-friction designs. Detroit and Tennessee engineering teams specify ion-plated coatings for stop-start urban cycle performance.
- Industrial Machinery:Machine tool spindles and printing press cylinders generate the deepest margin pools. Shenzhen and Suzhou manufacturing corridors drive replacement demand where single-shift downtime costs override component price sensitivity.
- Aerospace:Flight-critical bearing assemblies with extended qualification protocols.
- Consumer Electronics:Miniature configurations for precision motion systems.
Automotive captures current volume; Industrial Machinery offers the steepest expansion trajectory.
Mounting Style:
Lubrication environment determines material compatibility requirements and service interval economics.
- Grease Lubricated:Sealed-for-life configurations eliminating maintenance access in compact gearboxes. Electric drivetrain architectures are eliminating conventional engine-oil splash environments, forcing redesigns for dry-running or grease-limited conditions in Japanese and German EV reduction stages.
- Oil Lubricated:Circulating systems for high-speed continuous duty in legacy transmission housings.
- Seal Type:Elastomer-protected assemblies for contaminated environments.
- Open Type:Unsealed configurations for accessible maintenance points in industrial settings.
Grease Lubricated dominates new design wins; Oil Lubricated retains installed base replacement volume.
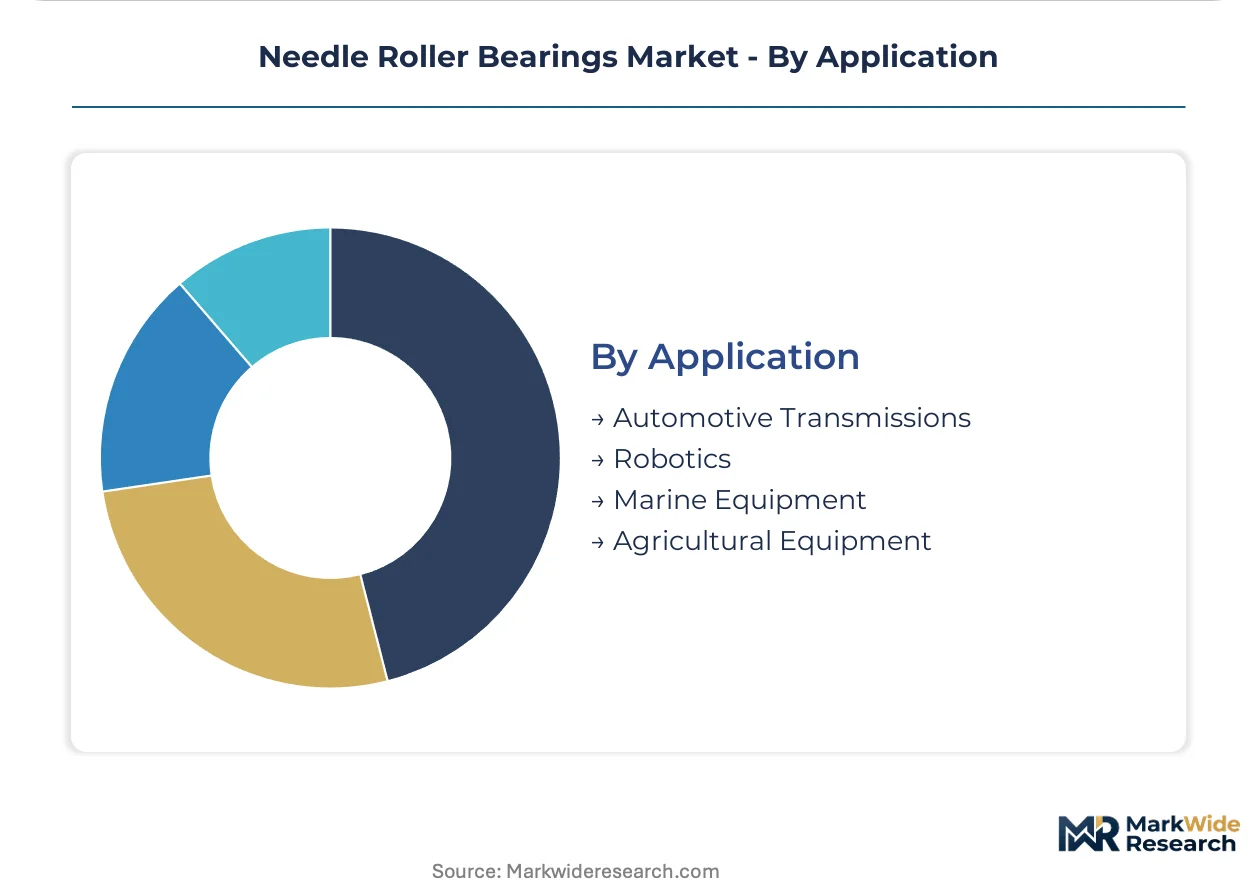
Application:
Load characteristics and motion profiles dictate cage geometry and surface coating specifications.
- Automotive Transmissions:The most mature segment with established OEM qualification cycles compressing margins for standard catalogue items. EMA and REACH substance restrictions accelerate R&D investment in compliant alloy formulations for European supply chains.
- Robotics:Collaborative arm joints and precision reducers demand caged configurations with sub-micron positional repeatability, generating specification premiums unavailable in automotive commodity tiers.
- Marine Equipment:Corrosion-resistant coatings for saltwater exposure environments.
- Agricultural Equipment:Contamination-tolerant designs for high-dust field operations.
Automotive Transmissions anchors current revenue; Robotics is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany produces precision bearing clusters that supply automotive OEMs across Europe, while Japan and China absorb the majority of Asian demand for industrial machinery and robotics applications. Consumption patterns diverge sharply between mature replacement cycles in Western Europe and capacity expansion in Chinese manufacturing corridors.
Germany
Stuttgart and Schweinfurt manufacturing corridors anchor European needle roller bearing production for transmission programs. ECHA REACH substance restrictions enforce compliant alloy formulations for bearing steels and lubricant additives. Baden-Württemberg precision engineering clusters co-locate with captive remanufacturing networks that recover used assemblies.
Japan
METI carbon-neutrality roadmaps mandate domestic EV production scale-up, opening qualification windows for e-axle differential bearings. JIS B 1514 dimensional tolerances govern international interchangeability for precision reducers in collaborative robotics. Nagoya and Osaka industrial belts concentrate ceramic-hybrid development for high-speed reduction gearboxes.
China
Shenzhen and Suzhou manufacturing corridors drive replacement demand for aging machine tool spindles where downtime costs override component price sensitivity. MIIT industrial upgrading policies accelerate precision bearing localization in automotive supply chains. Yangtze River Delta clusters absorb capacity expansion for grease-limited EV transmission designs.
United States
EPA emissions thresholds and NHTSA fuel-economy mandates pressure Detroit and Tennessee engineering teams toward lighter, lower-friction transmission configurations. Ion-plated coating specifications reduce boundary friction coefficients in stop-start urban cycles. Midwest automotive supplier parks integrate predictive vibration-monitoring services from bearing vendors.
Needle Roller Bearings Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a tiered supplier base where integrated metallurgical laboratories separate premium-tier qualification capabilities from catalogue commodity producers. European and Japanese incumbents anchor the consolidated upper tier through captive remanufacturing networks and ceramic-hybrid R&D pipelines. Mid-tier specialists compete on regional logistics proximity to automotive OEM parks. Dominant competitive moves include backward integration into bearing steel alloying and predictive digital service bundling that extends customer lifetime value beyond hardware shipment.
Within the integrated European tier, Schaeffler Group and SKF occupy positions defined by remanufacturing network scale and vibration-monitoring platform deployment. NSK Ltd. exemplifies the Japanese ceramic-hybrid specialist archetype focused on electric drivetrain qualification cycles. Zhejiang Waxing Electromechanical Co., Ltd. represents Chinese capacity expansion into precision bearing localization for domestic automotive programs.
| Leading Market Players |
|---|
| SKF |
| IKO International, Inc. |
| NSK Ltd. |
| RBC Bearings Incorporated |
| JTEKT Corporation |
| NTN Corporation |
| Timken |
| Zhejiang Waxing Electromechanical Co., Ltd. |
| Schaeffler Group |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in German and Japanese manufacturing clusters anchor supply discipline through captive metallurgical laboratories, translating REACH-compliant alloy investments into pricing premiums that catalogue commodity producers cannot match. This ownership pattern concentrates pricing power among integrated incumbents while squeezing margin predictability for distributors dependent on spot-market ferrochrome exposure.
Pricing Analysis
Margin tightening in automotive transmission tiers reflects established OEM qualification cycles compressing returns on standard needle roller geometries. Three-tier pricing structure across premium, standard, and economy levels separates ceramic-hybrid variants for electric vehicle reduction gearboxes from chromium steel catalogue items. Price differentiation rests on ISO 492 certification grade and volume scale commitments. Industrial machinery buyers exhibit lowest price sensitivity where single-shift downtime costs override component replacement economics.
Supply Chain Analysis
MIIT domestic-content mandates in China are reshaping sourcing patterns for precision bearing localization in Yangtze River Delta automotive corridors. Supply concentrates in Germany, Japan, and China where precision manufacturing clusters co-locate with OEM engineering teams. Raw material dependencies include ferrochrome from South African smelters, through-hardened chromium steel alloys, and polyetheretherketone cage resins. Single-source vulnerability around ceramic powder suppliers in Nagoya industrial belts threatens hybrid bearing expansion. Distribution runs through captive remanufacturing networks and vibration-monitoring platform subscriptions extending customer lifetime value.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The needle roller bearings market functions as a consolidation play where REACH certification delays and ceramic-hybrid R&D capital requirements force weaker catalogue producers toward exit or acquisition. EMA substance restrictions and METI electrification roadmaps accelerate this thinning.
For Market Incumbents: Anchor European market position through backward integration into bearing steel alloying and expansion of captive remanufacturing networks recovering used assemblies from Stuttgart automotive supplier parks. Ceramic-hybrid qualification pipelines for Japanese e-axle programs represent the critical defensive lever against silicon nitride substitution in high-speed reduction gearboxes above fifteen thousand RPM. For New Entrants and Emerging Players: Ceramic-hybrid manufacturing partnerships with Nagoya industrial belt powder metallurgists offer the most penetrable wedge into premium automotive tiers where NSK Ltd. and Schaeffler Group currently dominate qualification cycles. Target Shenzhen and Suzhou machine tool retrofit corridors for grease-limited replacement bearings where downtime cost sensitivity overrides incumbent brand loyalty. Go-to-market execution should bundle predictive vibration-monitoring subscriptions mimicking SKF digital platform economics. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier catalogue producers in Chinese manufacturing corridors facing MIIT localization pressure without captive metallurgical laboratory capabilities. Long-term viability hinges on five-to-ten year electrification transition windows where ceramic-hybrid penetration determines survival. The signal to watch is JIS B 1514 certification timeline compression for new alloy compositions containing restricted hexavalent chromium alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-Hybrid R&D Pipeline | Silicon nitride rolling elements displace steel needles in Japanese EV reduction stages. |
| Captive Remanufacturing Network | Schaeffler Group recovers used assemblies across Baden-Württemberg precision clusters. |
| Predictive Maintenance Platform | SKF vibration-monitoring subscriptions displace traditional distributor relationships. |
| REACH-Compliant Alloy Investment | ECHA restrictions force eighteen-month certification delays for non-integrated suppliers. |
| Machine Tool Retrofit Channel | Shenzhen spindle replacement demand overrides component price sensitivity. |
Methodological Framework
Independent corroboration across primary interviews with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket service heads, and plant maintenance directors underwrites the qualitative findings. Secondary validation draws from customs/trade data, SEC 10-K filings, IHS Markit vehicle production databases, and JIS B 1514 dimensional tolerance specifications. Bottom-up demand modeling across automotive transmission, robotics precision reducer, and machine tool spindle segments triangulates against top-down industry aggregation.
Rate-of-change decomposition across the projection horizon segments volume and value outputs by component type, industry vertical, mounting style, and application duty cycle. CAGRs derive from regression analysis against electric drivetrain penetration curves and industrial machinery replacement cycle timing. Forecast inputs include ferrochrome price volatility indices and METI carbon-neutrality roadmap implementation pacing.
Several conditions sit outside the modeled scope, including unannounced regulatory revisions to REACH substance restrictions, breakthrough ceramic material formulations, and geopolitical disruptions to South African ferrochrome supply. Forecasts reflect documented assumptions about electrification transition speed and robotics adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Power Window Regulator Market
Automotive Parts
Windshield Washer Fluid Market
Automotive Parts
Automotive Coolant Aftermarket Market
Automotive Parts
Russia Passenger Vehicles Lubricants Market
Automotive Parts
Europe Automotive Engine Oils Market
Automotive Parts
Automotive Bellows Market
Automotive Parts
Thailand Automotive Lubricants Market
Automotive Parts
Uae Commercial Vehicles Lubricants Market
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
Aluminum Parts Gravity Die Casting Market
Automotive Parts
Germany Automotive Parts Aluminium Die Casting Market
Automotive Parts
North America Automotive Actuators Market
Automotive Parts
Plastic Fuel Tanks Market
Automotive Parts
Canada Automotive Pneumatic Actuators Market
Automotive Parts
Automotive Engine Cooling System Market
Automotive Parts
Europe Automotive Parts Zinc Die Casting Market