
 Motorcycle Battery Chargers Market | 2026-2036
Motorcycle Battery Chargers Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Battery Chargers Market Insights
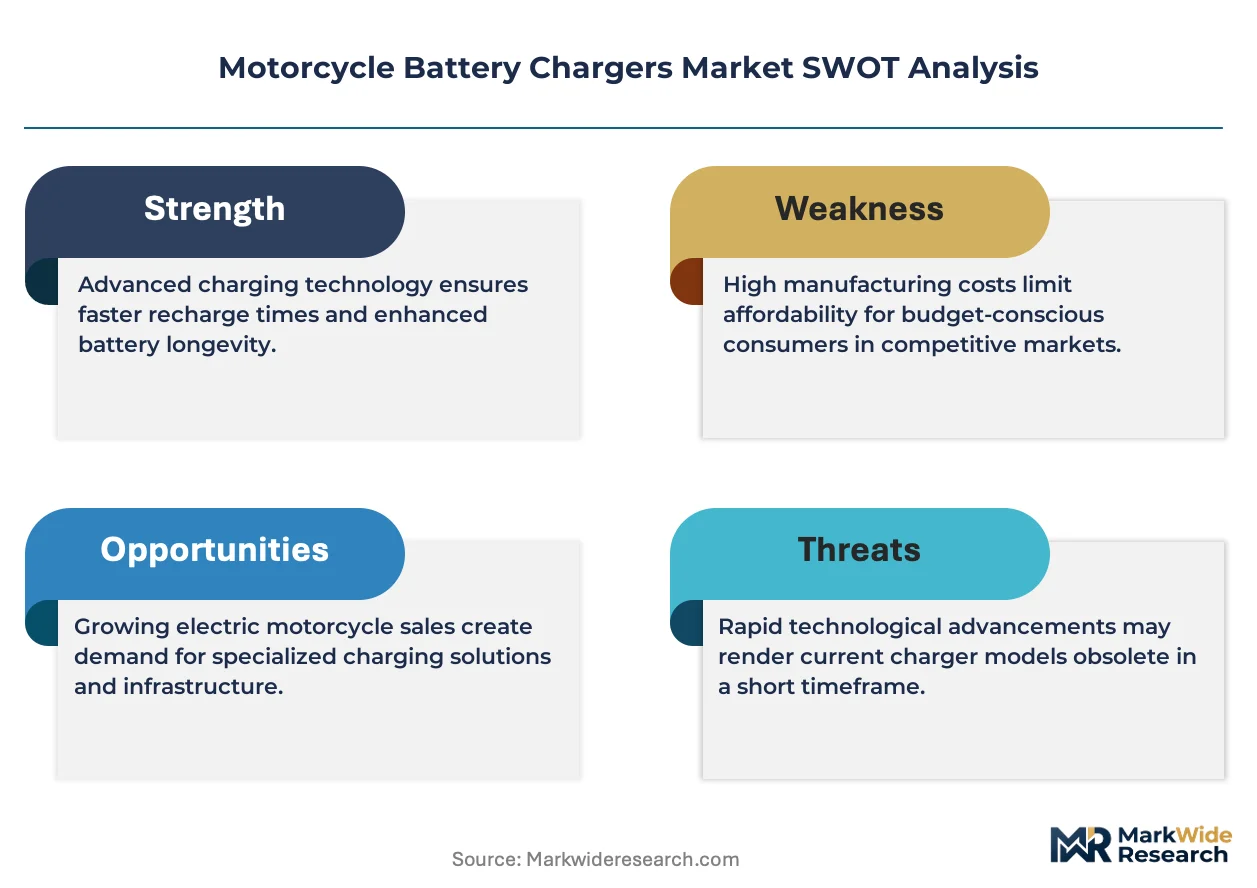
Smart charger certification tiers is bifurcating the competitive landscape into premium and value segments. CTEK leverages its Scandinavian engineering heritage to sustain premium positioning across European markets. Battery Tender anchors the North American aftermarket through deep channel control in specialty retail. Guangzhou Yunyang Electronic Technology competes on manufacturing scale, dominating cost-sensitive export channels.
Motorcycle battery chargers are electromechanical devices designed to restore and maintain charge in motorcycle power cells, typically operating between 6V and 12V with output currents ranging from 0.75A to 10A depending on battery chemistry and capacity; their primary purpose is to prevent sulfation in lead-acid units and to manage cell balancing in lithium-ion packs during storage or seasonal downtime. Smart chargers lead product type segmentation due to integrated microprocessor control and multi-stage charging algorithms that extend battery service life. Inductive charging technology represents the fastest-growing segment as OEMs explore cable-free integration for electric motorcycles, though contact charging retains the dominant installed base across internal combustion engine models.
The US Consumer Product Safety Commission and Underwriters Laboratories enforce electrical safety standards that shape charger design requirements for thermal protection and spark resistance, while the EU F-Gas Regulation and REACH compliance frameworks influence material selection and manufacturing location decisions for brands serving European riders. China's GB standards and SAMR quality certification requirements create parallel compliance obligations for manufacturers sourcing components from or selling into that market. Stakeholders must monitor how divergent lithium-ion battery management protocols across OEM platforms reshape charger compatibility requirements and aftermarket replacement cycles.
Market Dynamics
The motorcycle battery charger market is restructuring around lithium-ion battery chemistry migration, which demands fundamentally different charging protocols, voltage precision, and thermal management than legacy lead-acid systems.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases are accelerating OEM redesign of charger thermal systems toward solid-state cooling architectures.
- Electric motorcycle platforms:Zero Motorcycles and Energica are driving inductive charging integration that requires compatible aftermarket infrastructure.
- Storage sulfation prevention:Seasonal riders in Germany and Japan are adopting smart maintainers to preserve battery health during extended downtime.
Market Restraints
- Copper and semiconductor input costs:Volatility in power management IC pricing compresses margin on entry-level charger SKUs.
- Component concentration in Guangdong Province:Single-region sourcing of switch-mode power supplies creates vulnerability to logistics disruptions.
- Patent thickets around lithium balancing algorithms:IP fragmentation across cell management system vendors slows new entrant certification.
Strategic Opportunities
- India two-wheeler electrification:The PLI scheme for advanced chemistry cell manufacturing is creating parallel demand for compatible charging infrastructure.
- Direct-to-rider e-commerce:Amazon and RevZilla are displacing traditional distributor networks for accessory-grade chargers.
- GB standard harmonization:China's SAMR certification alignment with IEC 60335-2-29 is reducing retesting burden for export-oriented manufacturers.
Industry Challenges
- Firmware engineering talent scarcity:Shortage of embedded systems developers with battery algorithm experience delays smart charger development cycles.
- Multi-protocol certification backlog:Divergent OEM battery management interfaces require redundant validation testing for universal charger claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Battery Chargers Market |
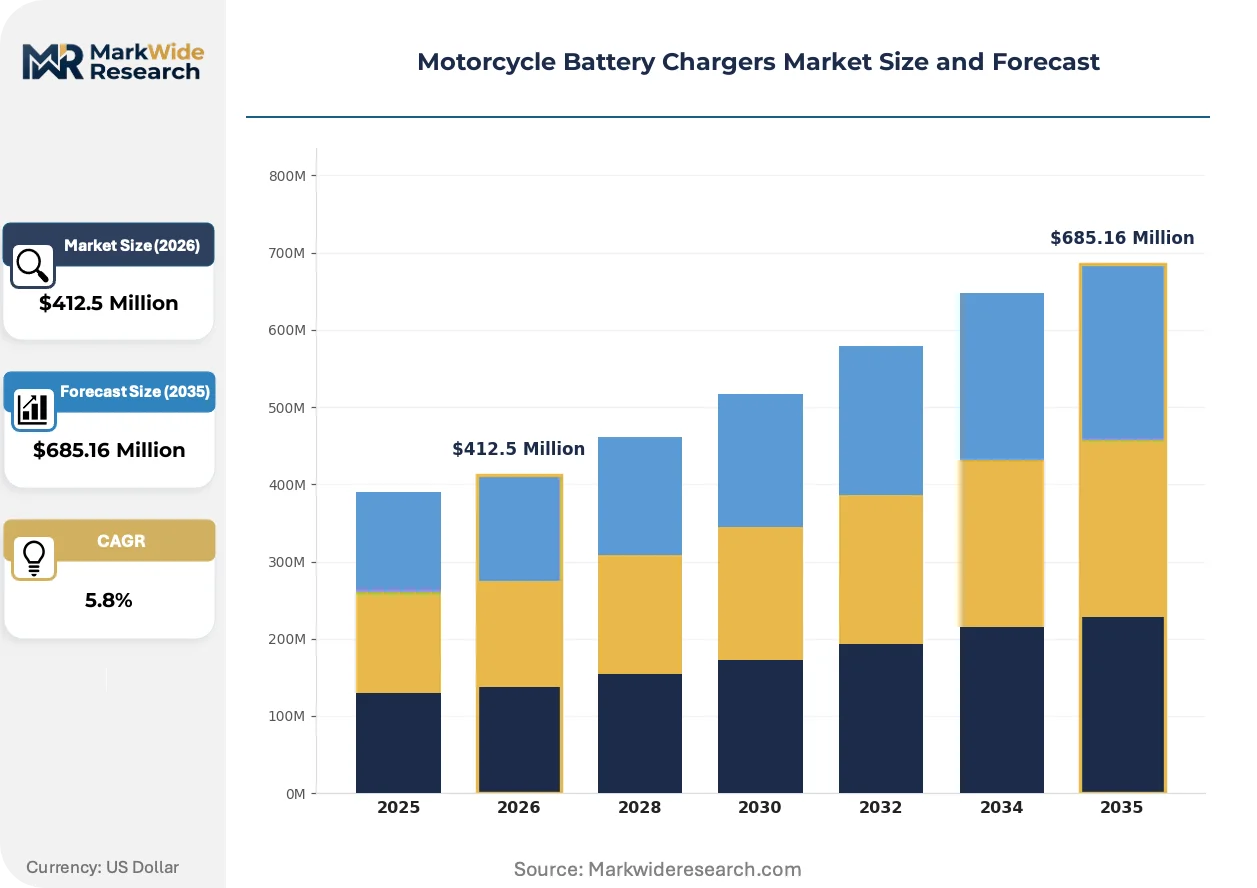
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Chargers, Lead-Acid Chargers, Lithium-Ion Chargers, Universal Chargers End User: Individual Riders, Dealerships, Repair Shops, Fleet Operators Technology: Contact Charging, Inductive Charging, Solar Charging, Fast Charging Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Automotive Stores |
| Companies Covered | NOCO, Battery Tender, CTEK, Schumacher, OptiMate, Guangzhou Yunyang Electronic Technology, MOTOPOWER, Oxford, KACEPAR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Battery Chargers Market Trends and Innovations
Gallium nitride power semiconductors and software-defined charging profiles are compressing device footprints while expanding compatibility across battery chemistries. These shifts are redrawing competitive boundaries between hardware specialists and platform-agnostic software vendors.
GaN transistor technology is replacing silicon MOSFETs in AC-DC conversion stages, cutting heat dissipation requirements by two-thirds. Aftermarket suppliers in Taiwan and South Korea are adopting these components fastest, targeting touring riders with glove-compact form factors. The resulting architecture is miniaturizing charger enclosures to sub-200-gram weights without sacrificing output current.
REACH substance restrictions on cadmium and hexavalent chromium are forcing redesign of connector plating and PCB finishes for European market access. Manufacturers are shifting to tin-bismuth alloys and immersion silver surface treatments. This regulatory pressure is most acute for value-segment brands dependent on cost-minimized electroplating.
Rider preference for subscription-connected maintenance is displacing standalone charger purchases. Harley-Davidson's H-D Connect and BMW Motorrad's Connected app are bundling battery monitoring with dealer service scheduling. This behavioral pivot is most visible in the United States, where dealer loyalty programs now incorporate charger provisioning as a retention tool.
Motorcycle Battery Chargers Market Segmentation
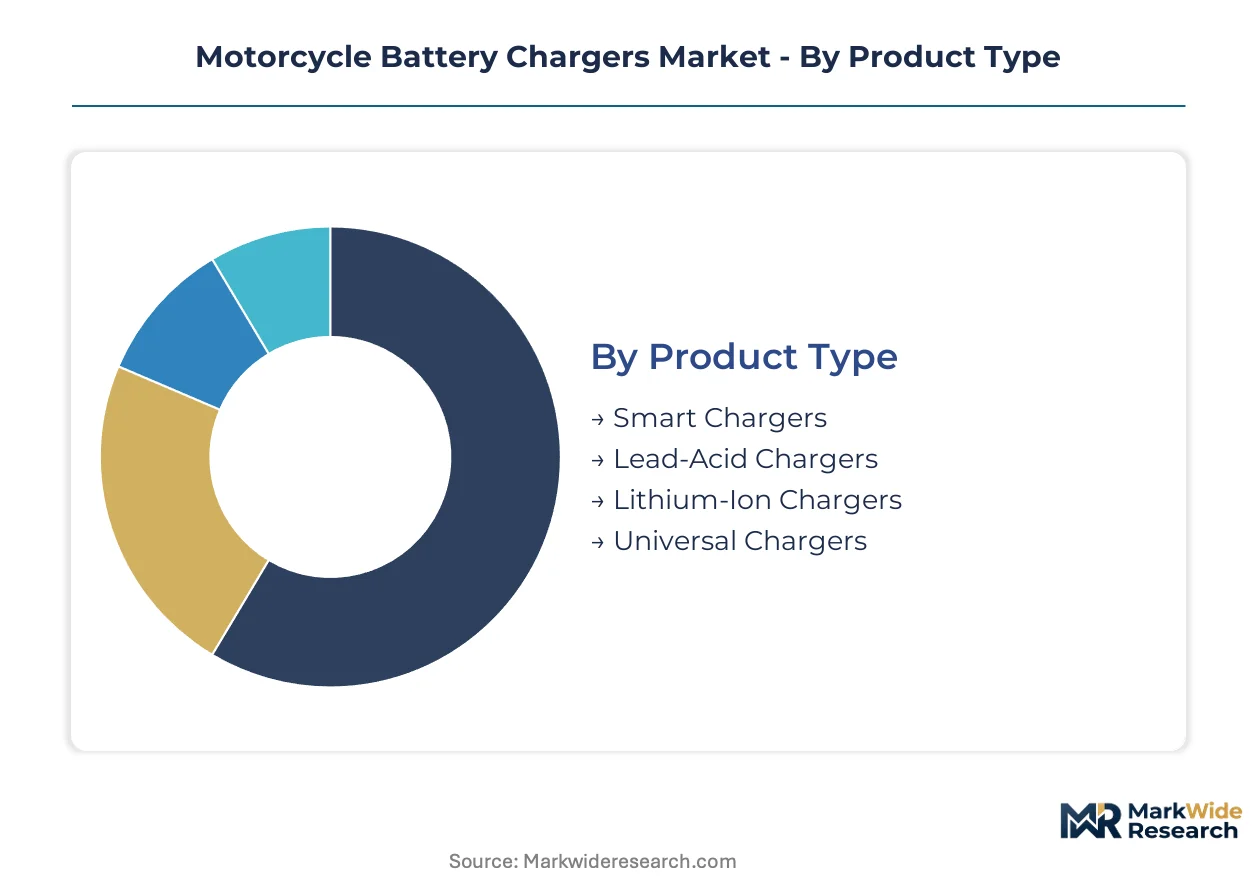
Segmentation in motorcycle battery chargers reflects divergent technical requirements across battery chemistries and sharply different procurement behaviors between retail riders and institutional fleets. Understanding these splits enables suppliers to align firmware capabilities, channel investments, and pricing architectures with actual purchase patterns rather than assumed uniformity.
Product Type:
Domestic demand concentrates on smart chargers in Germany and Japan where seasonal storage drives premium maintainer adoption, while export manufacturing from Guangdong Province dominates basic lead-acid units for emerging markets.
- Smart Chargers:Microprocessor-controlled units execute multi-stage charging algorithms with voltage precision to 0.1V, preventing sulfation in lead-acid packs and managing cell balancing in lithium-ion configurations. German and Japanese individual riders deploy these for winter storage protection, driving replacement cycles tied to battery warranty periods. Smart chargers command the established base.
- Lithium-Ion Chargers:These systems incorporate battery management system communication protocols and thermal runaway protection circuits mandatory for newer electric motorcycle platforms. Demand clusters around Zero Motorcycles and Energica service networks in California and Italy where OEM-specific firmware compatibility determines aftermarket viability. The steepest expansion runs through lithium-ion chargers.
- Lead-Acid Chargers:Conventional transformer-based or switch-mode designs serve legacy internal combustion engine motorcycles across South Asia and Latin America where cost sensitivity dominates procurement.
- Universal Chargers:Multi-chemistry units with automatic voltage detection and manual override switches target touring riders carrying single devices for mixed fleet maintenance.
Smart chargers anchor current revenue. Lithium-ion variants are gaining share fastest as OEM electrification accelerates.
End User:
Volume flows through fragmented individual rider purchases, while margin concentrates in fleet operator contracts with standardized specification and centralized procurement.
- Individual Riders:Enthusiast owners in the United States and Germany purchase maintainers through Amazon and RevZilla for seasonal storage, prioritizing plug-and-play simplicity and Bluetooth connectivity for mobile monitoring. This segment dominates unit volume through replacement-driven purchase patterns.
- Fleet Operators:Motorcycle rental chains and police departments in France and Spain issue tenders requiring IP65 enclosure ratings, multi-year warranty terms, and bulk firmware update capabilities. Procurement centralization extracts price concessions but locks in multi-year supply agreements. Fleet procurement is displacing traditional distributor networks.
- Dealerships:Authorized service centers bundle chargers with new motorcycle sales and maintenance packages, particularly for BMW Motorrad and Harley-Davidson loyalty programs.
- Repair Shops:Independent mechanics in Italy and Brazil stock entry-level units for emergency charging services, prioritizing durability and rapid turnaround over advanced features.
Individual riders generate the volume base. Fleet operators deliver the margin expansion trajectory.
Technology:
Cost structures separate mature contact charging from capital-intensive inductive systems, with solar variants occupying a narrow outdoor-specialist niche.
- Contact Charging:Cable-connected conductive systems using SAE J1287 or DIN connectors retain the dominant installed base across internal combustion engine motorcycles. Taiwanese and South Korean manufacturers leverage GaN transistor adoption to compress form factors below 200 grams for touring applications. Contact charging commands the established base.
- Inductive Charging:Wireless power transfer coils integrated into motorcycle frames and parking pads eliminate connector wear while enabling automated charging for electric motorcycle fleets. Zero Motorcycles and Energica are driving pilot deployments in California and Italy, though infrastructure costs constrain aftermarket adoption. The steepest expansion runs through inductive charging.
- Solar Charging:Photovoltaic panel-integrated maintainers target off-grid riders in Australia and rural United States with trickle-charge capabilities for extended parking without grid access.
- Fast Charging:High-current DC systems deliver 80% state-of-charge in under 30 minutes for commercial fleet turnaround, requiring active cooling and substantial electrical infrastructure.
Contact charging retains the volume base. Inductive systems are climbing the fastest as OEM integration deepens.
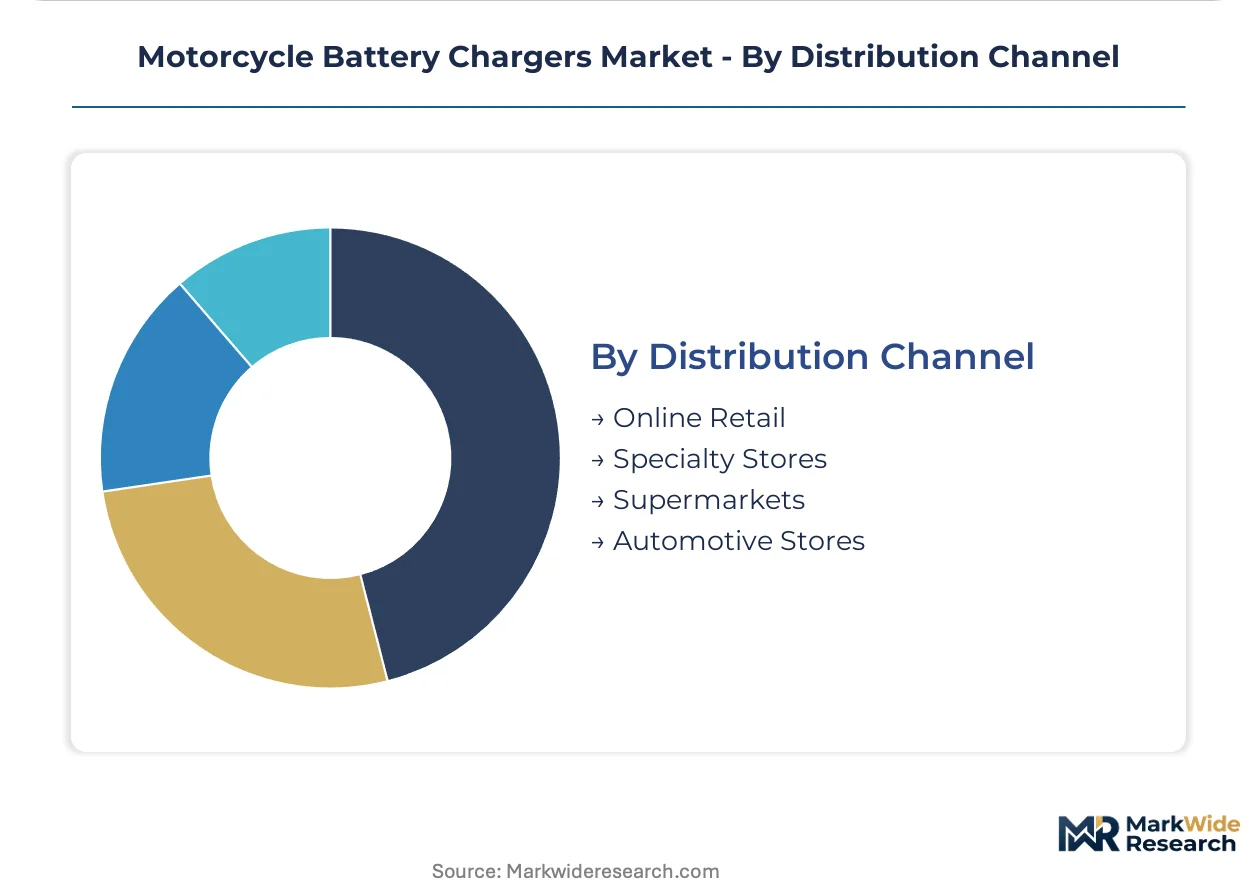
Distribution Channel:
Channel control bifurcates between e-commerce disintermediation in North America and specialty retail persistence in European markets with hands-on specification requirements.
- Online Retail:Amazon, RevZilla, and direct-to-consumer brand sites capture growing share of replacement charger purchases in the United States and United Kingdom, displacing traditional distributor markups. Search-optimized listings and review aggregation drive selection behavior among individual riders. Online retail commands the established base.
- Specialty Stores:Motorcycle accessory retailers in Germany and France provide technical consultation and compatibility verification that complex lithium-ion charger purchases demand. Staff expertise justifies price premiums and reduces return rates. The steepest expansion runs through specialty stores.
- Automotive Stores:Generalist auto parts chains in the United States and Canada stock basic maintainers alongside car battery chargers, capturing impulse purchases from multi-vehicle owners.
- Supermarkets:Mass merchants in Brazil and India distribute entry-level units as seasonal promotional items, prioritizing price point over feature differentiation.
Online retail dominates volume capture. Specialty stores are gaining share fastest as lithium-ion complexity demands technical guidance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Individual riders in Germany and Japan absorb premium pricing for smart maintainers, while emerging market buyers in Brazil and India prioritize entry-level lead-acid units.
United States
Seasonal storage patterns in northern states drive replacement cycles for battery maintainers. The US Consumer Product Safety Commission enforces thermal protection standards that shape charger enclosure designs. Milwaukee and Chicago host distributor networks that channel products through Amazon and RevZilla into enthusiast hands.
Germany
Winter downtime exceeding five months sustains demand for precision voltage maintenance. The KBA enforces strict electromagnetic compatibility requirements for aftermarket electrical accessories. Stuttgart and Munich anchor specialty retail clusters where technical consultation justifies price premiums.
Japan
Aging rider demographics favor automated charging solutions requiring minimal intervention. METI certification protocols for lithium-ion battery management systems create compliance barriers for foreign suppliers. Nagoya and Osaka concentrate manufacturing of compact switch-mode power supplies for regional OEMs.
China
Domestic two-wheeler electrification expands addressable market for lithium-compatible infrastructure. SAMR certification alignment with IEC standards is reducing retesting burdens for export-oriented manufacturers. Guangdong Province hosts concentrated component sourcing for switch-mode power supplies serving global assembly.
India
Two-wheeler fleet operators in commercial delivery segments drive bulk procurement of universal chargers. The PLI scheme for advanced chemistry cell manufacturing is creating parallel demand for compatible charging infrastructure. Tamil Nadu and Maharashtra are emerging as assembly locations for cost-optimized maintainer production.
Motorcycle Battery Chargers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the motorcycle battery charger market. The vendor base organizes into three tiers: premium engineering houses with certification depth, volume manufacturers leveraging Guangdong component clusters, and specialty fabricators serving regional aftermarket channels. Scandinavian and North American brands occupy the premium tier through firmware sophistication. Chinese manufacturers anchor the value segment via scale economics. Dominant competitive moves include portfolio diversification across battery chemistries and geographic expansion through e-commerce channel capture.
Within the premium engineering tier, CTEK and Battery Tender exemplify divergent geographic anchoring strategies. CTEK represents European certification-led positioning, while Battery Tender occupies a position as the North American aftermarket standard. Guangzhou Yunyang Electronic Technology sits within the scale-driven export archetype, leveraging proximity to Guangdong component clusters for cost-sensitive channel supply.
| Leading Market Players |
|---|
| NOCO |
| Battery Tender |
| CTEK |
| Schumacher |
| OptiMate |
| Guangzhou Yunyang Electronic Technology |
| MOTOPOWER |
| Oxford |
| KACEPAR |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride transistor substitution for silicon MOSFETs is redrawing component sourcing maps from Taiwan and South Korea toward mainland China packaging facilities while compressing premium-tier pricing spreads against standard units by two-thirds through reduced thermal management overhead.
Pricing Analysis
After-sales firmware update subscriptions and extended warranty bundling now generate lifetime value multiples exceeding initial hardware margins across premium charger tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth—UL/CE dual-marked units command substantial premiums over single-certified alternatives in cross-border channels. Cost compression in entry-level SKUs is intensifying because power management IC spot volatility erodes already-thin assembler margins. Fleet operators in France and Spain exhibit lowest price sensitivity due to centralized procurement and multi-year service agreements, while individual riders in Brazil and India gravitate toward economy-tier lead-acid units with minimal feature differentiation.
Supply Chain Analysis
Shenzhen port congestion and customs processing variability constitute the primary logistics chokepoint for Guangdong-sourced switch-mode power supplies feeding global assembly lines. Manufacturing gravity centers on China, Taiwan, and Vietnam for PCB fabrication and final enclosure assembly, with South Korea anchoring GaN wafer supply. Copper windings, ferrite cores, and battery management ICs constitute critical input dependencies. Single-region concentration in Guangdong Province creates tariff exposure vulnerability as trade policy shifts. Distribution runs through Amazon and RevZilla direct-to-rider platforms in North America, while European specialty retail retains technical consultation layers that slow channel disintermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded systems engineering talent with battery algorithm experience represents the binding constraint on smart charger development velocity, compressing product refresh cycles and amplifying first-mover advantages for firms with captive firmware capabilities.
For Market Incumbents: Shield premium positioning through accelerated certification investment in lithium-ion balancing protocols ahead of fragmented OEM standard convergence. Deepen backward integration into GaN transistor sourcing to offset power semiconductor cost volatility. Lock in multi-year fleet operator contracts in France and Spain before channel disintermediation accelerates. For New Entrants and Emerging Players: Differentiate on India two-wheeler electrification infrastructure compatibility, where PLI scheme incentives are creating parallel demand for cost-optimized lithium-compatible chargers. Target repair shop channels in Italy and Brazil with durable entry-level units emphasizing rapid turnaround over connectivity features. Pursue white-label supply agreements with emerging electric motorcycle OEMs seeking bundled charging solutions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed automotive aftermarket platforms seeking charger category adjacencies. Five-to-ten-year viability hinges on lithium-ion chemistry migration pace and universal protocol standardization outcomes. Monitor firmware engineering hiring velocity at tier-one suppliers as inflection indicator for development cycle competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Transistor Integration | Taiwanese and South Korean component adoption enables sub-200-gram touring-grade form factors. |
| Lithium-Ion Protocol Certification | UL and CE dual-marking unlocks fleet operator procurement in Germany and France. |
| Direct-to-Rider E-Commerce Buildout | Amazon and RevZilla channel capture displaces traditional distributor markups in North America. |
| Inductive Charging Infrastructure Partnership | Zero Motorcycles and Energica pilot deployments in California anchor aftermarket compatibility roadmaps. |
| Firmware Subscription Monetization | Harley-Davidson H-D Connect bundling shifts revenue from hardware to recurring service retention. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with product managers at CTEK and Battery Tender, procurement leads at French and Spanish fleet operators, embedded systems engineers at Taiwanese GaN component suppliers, and channel partners at Amazon and RevZilla. Secondary validation drew from US Consumer Product Safety Commission enforcement databases, EU F-Gas Regulation implementation notices, SAMR certification registries, SEC 10-K filings from listed automotive aftermarket suppliers, and customs trade data for Guangdong Province switch-mode power supply exports. Bottom-up unit shipment estimates by chemistry type and voltage tier were triangulated against top-down aftermarket accessory spending projections.
Across the analysis window, volume and value outputs reflect segmentation modeling across battery chemistry, charger intelligence tier, end-user procurement behavior, and geographic regulatory cluster. CAGRs were derived from fitted trend extrapolation with scenario-weighted adjustments for lithium-ion platform penetration and inductive charging infrastructure buildout rates. Industry-specific forecast inputs incorporated electric motorcycle production schedules from Zero Motorcycles and Energica, seasonal storage duration patterns in Germany and Japan, and REACH substance restriction implementation timelines affecting connector plating specifications.
Material uncertainties—lithium-ion battery management protocol fragmentation, copper and semiconductor input cost volatility, and logistics disruption recurrence—sit outside the modeled envelope. Forecasts reflect documented assumptions regarding OEM electrification pacing and aftermarket channel migration trajectories. Practitioners should keep alternative scenarios live as EU F-Gas Regulation thermal system redesign requirements and India PLI scheme infrastructure deployment timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
China Automotive Parts Aluminum Die Casting Market
Automotive Parts
Norway Automotive Engine Oils Market
Automotive Parts
Light Vehicle Exhaust and Emissions Systems Market
Automotive Parts
Automotive Suspension System Market
Automotive Parts
Power Liftgate Market
Automotive Parts
Racing Motor Bike Seat Unit Market
Automotive Parts
Global Intelligent All-Wheel Drive System Market
Automotive Parts
Automotive Coolant Aftermarket Market
Automotive Parts
Europe Commercial Vehicles Lubricants Market
Automotive Parts
Mechanical Performance Tuning Components Market
Automotive Parts
Global Bevel Gearbox Market
Automotive Parts
Automotive Valve Stem Seal Market
Automotive Parts
Center and Drag Link Market
Automotive Parts
US Automotive Parts Magnesium Die Casting Market
Automotive Parts
Electric Parking Brake Market
Automotive Parts
Automotive Oil Seals Market