
 Automotive Hydraulic Filters Market | 2026-2036
Automotive Hydraulic Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Hydraulic Filters Market Analysis
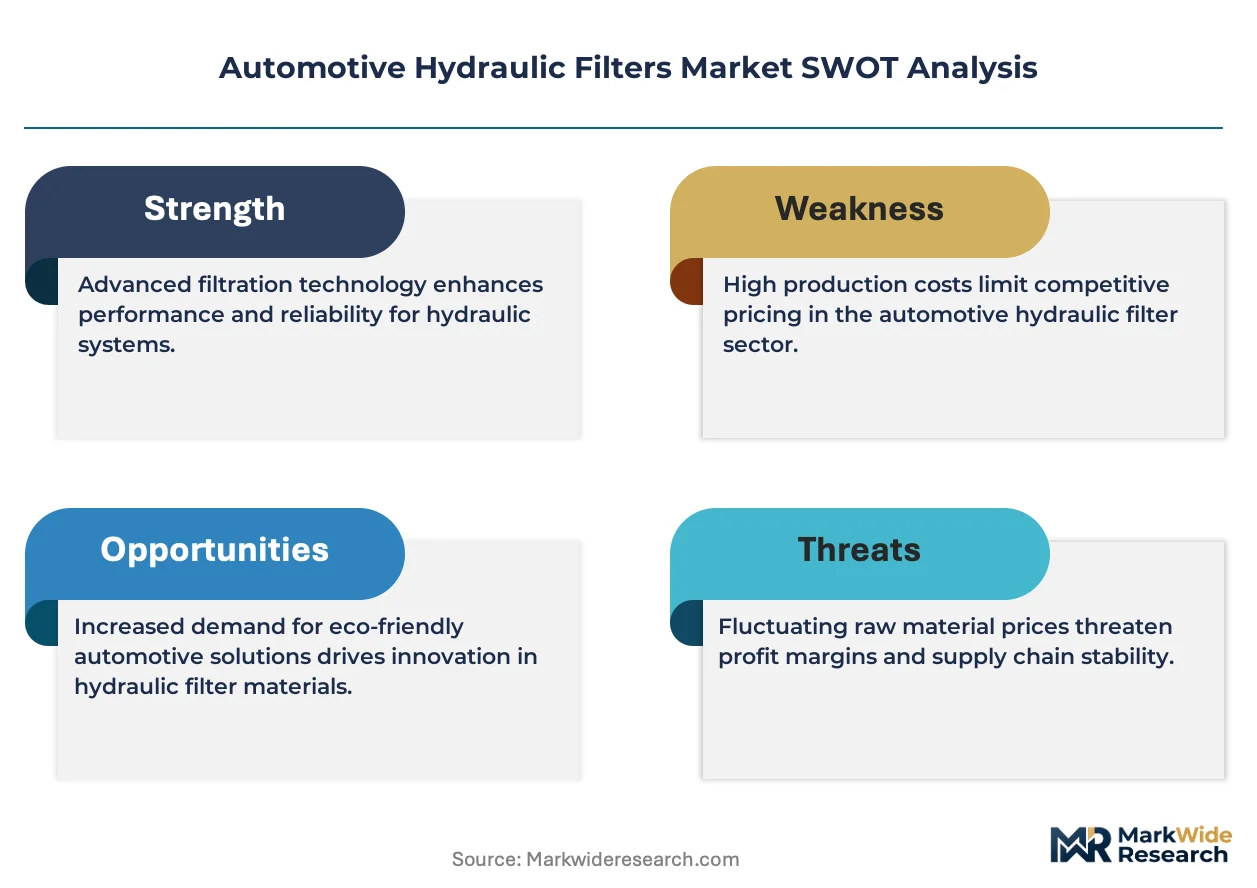
High-efficiency beta-rated filtration is rotating through automotive hydraulic circuits as electrified steering and braking architectures demand tighter particle control. Mann+Hummel leverages its captive media development to supply OEMs with multi-layer synthetic elements. Donaldson Company anchors North American aftermarket distribution through its extensive dealer network. Robert Bosch GmbH competes on integrated sensor-filter modules that monitor clogging in real time.
Automotive hydraulic filters are pressure-rated fluid conditioning devices, typically constructed from pleated synthetic media bonded to metal support cores, designed to remove abrasive particulates from transmission, steering, and braking fluid circuits. Beta ratios of 200 or higher at specified micron ratings define performance tiers for critical applications. Inline filters and pressure filters command premium positioning as electrified chassis systems proliferate, while return filters and suction filters retain volume dominance in conventional powertrain segments. Polyester and fiberglass media are displacing cellulose in severe-duty construction equipment and agricultural machinery applications where thermal cycling accelerates degradation.
EPA, EMA, and China's MEE enforce divergent fluid cleanliness protocols that force suppliers to maintain parallel certification tracks for cross-border sales. ISO 4406 cleanliness codes and SAE J1165 test methods establish the technical baseline for filter validation across jurisdictions. Stakeholders must weigh regional regulatory divergence against platform standardization economics when situating R&D and manufacturing footprints.
Market Dynamics
Electrified chassis architectures are compressing hydraulic filter specifications toward beta-rated precision while fragmenting volume demand across powertrain types. Tier 1 suppliers now engineer parallel filtration portfolios for conventional internal combustion, hybrid, and full-electric platforms.
Growth Catalysts
- EPA Tier 3 and Euro 6d fluid cleanliness mandates:Emission benchmarks now require sub-10-micron filtration in transmission and steering circuits, forcing OEMs to upgrade from cellulose to synthetic media across vehicle classes.
- Electric power steering (EPS) hydraulic assist:Hybrid and full-electric architectures retain hydraulic backup systems that demand compact, high-pressure inline filters with real-time clogging sensors.
- China's MEE enforcement of GB standards:Domestic automakers in Shanghai and Guangdong provinces are localizing precision filter procurement to meet import-substitution targets in the NEV supply chain.
Market Restraints
- Cellulose media price volatility:Pulp feedstock costs fluctuate with forestry harvest cycles in Nordic and Canadian supply regions, squeezing margin on economy-tier aftermarket filters.
- Glass microfiber supply concentration:High-efficiency synthetic media production clusters in Germany and Japan, exposing filter assemblers to single-source risk for beta-200+ rated elements.
- SAE J1165 test protocol complexity:Multi-cycle validation requirements extend new product qualification timelines, delaying platform launches for Tier 2 suppliers lacking captive test facilities.
Strategic Opportunities
- India's PLI scheme for auto components:Filter manufacturers establishing Tamil Nadu and Maharashtra facilities gain 4-6% cost advantage on exported precision elements to ASEAN markets.
- Integrated sensor-filter modules:Convergence of MEMS pressure sensors with multi-layer synthetic elements enables predictive maintenance contracts for fleet operators managing Class 8 trucks.
- Remanufactured hydraulic assemblies:Circular economy mandates in the EU Green Deal create aftermarket demand for reconditioned filters with verified cleanliness codes in German and French commercial vehicle sectors.
Industry Challenges
- Cross-contamination control in multi-platform plants:Suppliers producing both conventional and electrified filtration must segregate ISO 4406 Class 18/16/13 cleanroom zones from standard assembly lines.
- Legacy powertrain inventory absorption:Return and suction filter volumes for internal combustion architectures face demand cliff risks as OEMs accelerate platform consolidation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Hydraulic Filters Market |
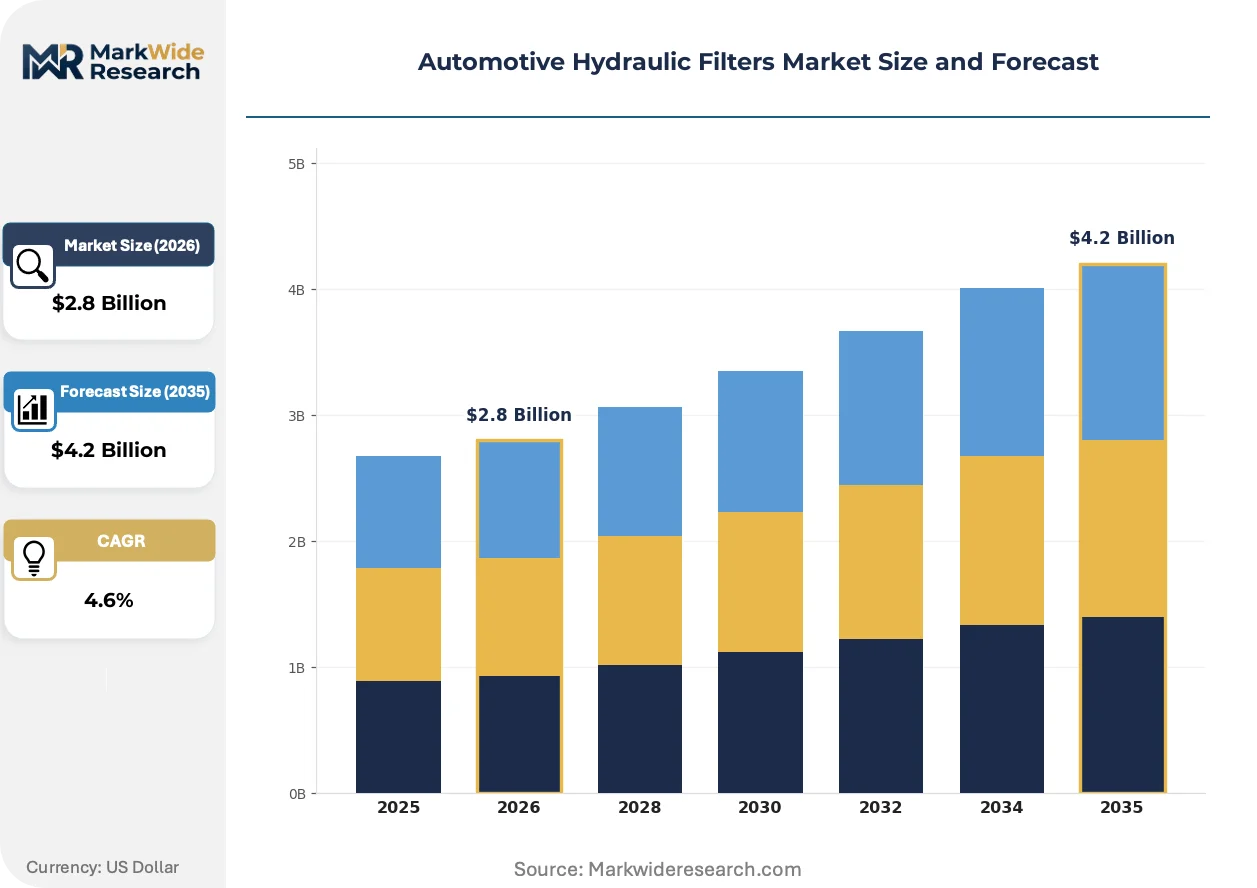
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inline Filters, Return Filters, Pressure Filters, Suction Filters End User: Original Equipment Manufacturers, Aftermarket Providers, Repair Shops, Fleet Operators Application: Construction Equipment, Agricultural Machinery, Trucks, Passenger Vehicles Material: Stainless Steel, Polyester, Polypropylene, Fiberglass |
| Companies Covered | Mann+Hummel, MAHLE GmbH, Donaldson Company, Parker Hannifin, Robert Bosch GmbH, Atmus Filtration Technologies, Freudenberg, HYDAC Technology, Schaeffler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Hydraulic Filters Market Emerging Trajectories
Synthetic media chemistry and embedded diagnostics are fragmenting the competitive landscape into precision-tier specialists and volume commodity producers. Technical differentiation now hinges on real-time contamination monitoring rather than passive filtration efficiency alone.
Nanofiber surface layers bonded to polyester support substrates are bifurcating the performance hierarchy between severe-duty construction equipment and standard passenger vehicle applications. Mining and agricultural OEMs in Australia and Brazil specify these elements for 1000-hour service intervals, while economy passenger filters compress toward 15,000-kilometer change cycles. This divergence is concentrating R&D investment in North American and German specialty media houses.
REACH restrictions on perfluorinated compounds are compelling filter manufacturers to reformulate water-repellent coatings on synthetic media. The industrial consequence is a 12-18 month qualification gap as suppliers validate fluorine-free alternatives against SAE J1165 multi-pass test protocols. German KBA type-approval timelines have extended correspondingly, most affecting hydraulic steering filters in premium passenger vehicle segments.
Fleet procurement teams now specify outcome-based fluid cleanliness guarantees rather than component-level filter purchases. Commercial vehicle leasing companies in the United States negotiate contracts where suppliers assume contamination-related warranty risk. This transfer of technical accountability is compressing the independent aftermarket channel and favoring direct OEM-supplier relationships in long-haul trucking.
Automotive Hydraulic Filters Market Segmentation
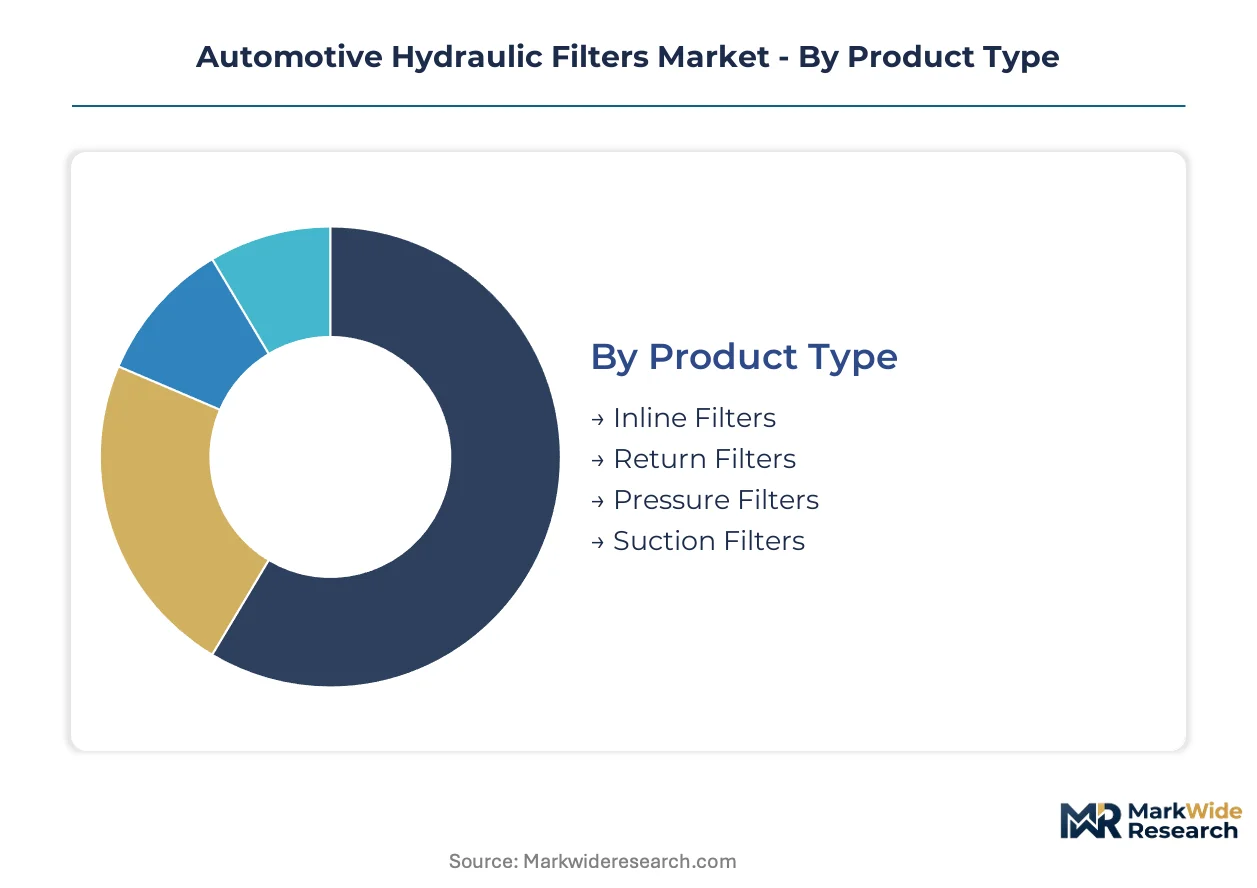
Electrified chassis architectures are fragmenting demand across conventional and precision filtration tiers. Suppliers must engineer parallel portfolios where beta-rated synthetic elements command premium positioning while cellulose-based return filters absorb volume in legacy powertrains. Segmentation discipline determines which R&D investments align with platform consolidation timelines.
Product Type:
Inline filters face acute substitution pressure from integrated sensor-filter modules as electrified steering and braking systems demand real-time clogging diagnostics.
- Inline Filters:Compact high-pressure elements with beta-200+ ratings serve electric power steering backup circuits and brake-by-wire hydraulic assist. Demand concentrates in German and Chinese passenger vehicle assembly where EPS penetration exceeds conventional architectures.
- Pressure Filters:Heavy-duty cylindrical housings with pleated synthetic media protect transmission circuits in Class 8 trucks and mining equipment. Australian and Brazilian fleet operators specify 1000-hour service intervals, driving specification toward nanofiber surface layers.
- Return Filters:Low-pressure elements with cellulose or blended media condition fluid returning to reservoir tanks in conventional automatic transmissions.
- Suction Filters:Wire-mesh or pleated elements mounted at pump inlets prevent large particulate ingress in agricultural hydraulic systems.
Return filters anchor the volume base while inline filters gain share at the steepest rate.
End User:
Cost tier stratification separates captive OEM supply from price-sensitive aftermarket channels, with fleet procurement rewriting contract structures.
- Original Equipment Manufacturers:Tier 1 suppliers negotiate multi-year platform contracts specifying ISO 4406 cleanliness codes and SAE J1165 validation. German and US automakers require integrated sensor-filter modules with predictive maintenance capability.
- Fleet Operators:Commercial vehicle leasing companies in the United States now demand outcome-based fluid cleanliness guarantees where suppliers assume contamination-related warranty risk. This compresses independent aftermarket margins.
- Aftermarket Providers:Distributors stock economy-tier cellulose filters for legacy powertrain service intervals in price-sensitive channels.
- Repair Shops:Independent service centers source branded replacement elements through regional distribution networks.
OEM contracts deliver the highest margin per unit while fleet operators expand most quickly as outcome-based procurement spreads.
Application:
Volume concentration in passenger vehicles masks the technology divergence where severe-duty equipment drives synthetic media innovation.
- Passenger Vehicles:Conventional automatic transmissions and hydraulic power steering systems consume return and suction filters in high volumes. Electrification is compressing this segment as electric power steering eliminates hydraulic circuits.
- Construction Equipment:Excavators and loaders subject hydraulic fluid to thermal cycling and contamination loads that degrade cellulose media. OEMs in Japan and Germany specify fiberglass-reinforced polyester for extended service intervals.
- Agricultural Machinery:Tractors and harvesters operate in dust-intensive environments where suction filters protect pump inlets from abrasive ingress.
- Trucks:Long-haul Class 8 vehicles combine high-pressure transmission filtration with steering circuit conditioning across million-mile duty cycles.
Passenger vehicles retain volume dominance while construction equipment climbs the fastest as severe-duty specifications proliferate.
Material:
Supply concentration in German and Japanese glass microfiber production creates single-source exposure for beta-200+ rated elements.
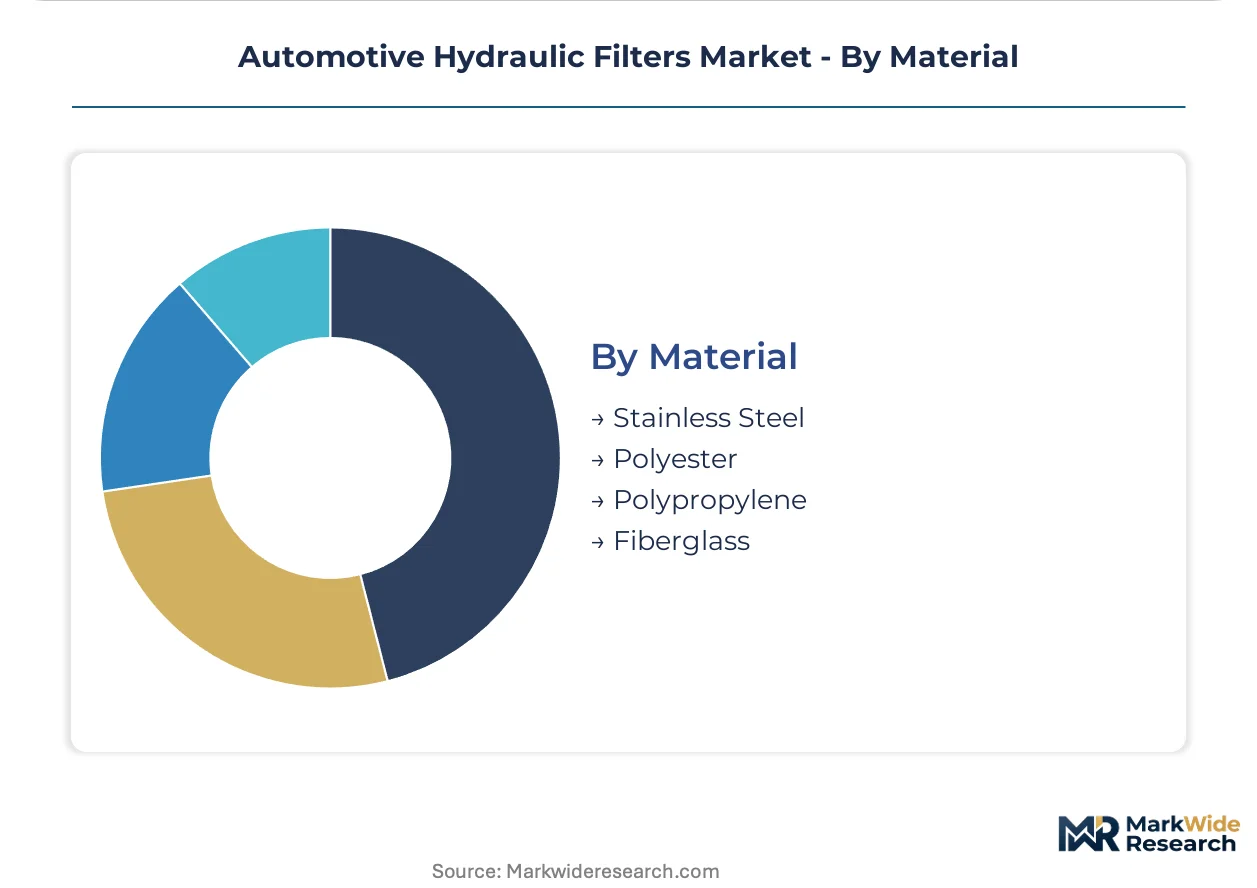
- Fiberglass:Borosilicate microfiber layers achieve sub-10-micron absolute ratings required by EPA Tier 3 and Euro 6d fluid cleanliness mandates. Production clusters in Germany and Japan expose filter assemblers to geographic concentration risk.
- Polyester:Melt-blown synthetic substrates bonded to nanofiber surface layers serve severe-duty construction and agricultural applications. REACH restrictions on perfluorinated compounds are forcing 12-18 month requalification timelines for water-repellent coatings.
- Stainless Steel:Woven wire mesh provides reusable suction filtration in mining equipment where washability extends element life.
- Polypropylene:Melt-blown depth media offers economy-tier filtration in temperature-stable passenger vehicle applications.
Cellulose remnants in economy tiers still anchor volume while synthetic media displaces share across all premium specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Filter trade flows tilt toward manufacturing clusters that serve electrified powertrain demand. China, Germany, and the United States absorb dominant precision output shares. Export-import balances favor media-rich economies over assembly-only jurisdictions.
China
Domestic automakers in Shanghai and Guangdong provinces localize precision filter procurement for NEV supply chains. MEE enforces GB fluid cleanliness standards that match EPA Tier 3 stringency. Tianjin and Suzhou industrial zones concentrate beta-rated synthetic element production for hybrid steering systems.
Germany
KBA type-approval timelines for hydraulic steering filters extend 12-18 months under REACH reformulation mandates. OEMs in Stuttgart and Munich specify integrated sensor-filter modules with real-time clogging diagnostics. Baden-Württemberg hosts glass microfiber production clusters supplying beta-200+ rated media across Europe.
United States
Commercial vehicle leasing companies in Michigan and Ohio negotiate outcome-based fluid cleanliness contracts. EPA Tier 3 mandates sub-10-micron filtration in transmission circuits. Detroit-area Tier 1 suppliers engineer parallel portfolios for conventional and electrified platforms.
Japan
METI coordinates domestic filter validation against SAE J1165 protocols shared with US and European regulators. Construction equipment OEMs in Aichi and Osaka prefectures specify fiberglass-reinforced polyester for 1000-hour service intervals. Chubu region concentrates severe-duty media development for mining and agricultural exports.
India
PLI scheme incentives draw filter manufacturers to Tamil Nadu and Maharashtra facilities serving ASEAN export markets. Domestic automakers absorb cost advantages of 4-6% on precision elements. Pune and Chennai industrial corridors expand cleanroom capacity for ISO 4406 Class 18/16/13 assembly zones.
Automotive Hydraulic Filters Market Vendor Landscape
Concentration sits with diversified filtration conglomerates and precision-tier specialists. The vendor base spans three structural tiers: captive media developers, integrated sensor-filter module producers, and regional aftermarket distributors. Strategic moves cluster around backward integration into synthetic media production and predictive maintenance capability acquisition. Partnerships between filter assemblers and MEMS sensor suppliers accelerate module convergence timelines.
Within the diversified conglomerate tier, Mann+Hummel and MAHLE GmbH exemplify European-origin manufacturers with captive media development capabilities. Donaldson Company occupies a position among North American fabricators with extensive distribution infrastructure. Robert Bosch GmbH represents the integrated systems archetype, anchoring sensor-filter module development for real-time diagnostics applications.
| Leading Market Players |
|---|
| Mann+Hummel |
| MAHLE GmbH |
| Donaldson Company |
| Parker Hannifin |
| Robert Bosch GmbH |
| Atmus Filtration Technologies |
| Freudenberg |
| HYDAC Technology |
| Schaeffler |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at German and Japanese glass microfiber plants shapes both supply concentration and price floors for beta-200+ rated elements. OEM procurement teams leverage multi-year platform contracts to compress margins on synthetic media while cellulose-based aftermarket filters face pulp feedstock volatility from Nordic forestry cycles.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on ISO 4406 cleanliness certification grade and volume scale commitments in platform contracts. Cost compression in the economy tier is intensifying because pulp feedstock volatility squeezes cellulose filter margins. Fleet operators show least price sensitivity where outcome-based fluid cleanliness guarantees transfer warranty risk to suppliers, while independent aftermarket distributors remain most exposed to spot-price cellulose media.
Supply Chain Analysis
Germany and Japan anchor high-efficiency synthetic media production for beta-200+ rated elements. Borosilicate glass microfiber, melt-blown polyester substrates, and nanofiber surface layers constitute critical input dependencies. Single-source vulnerability concentrates in Chubu and Baden-Württemberg media clusters where REACH reformulation mandates extend qualification timelines. Distribution runs through captive OEM supply chains for precision-tier modules and regional dealer networks for aftermarket volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance service contracts for fleet operators expand faster than hardware unit sales, creating recurring revenue layers that outpace filter element replacement cycles. This service-attach dynamic rewards suppliers who bundle real-time diagnostics with fluid cleanliness outcome guarantees.
For Market Incumbents: Fortify backward integration into synthetic media production to offset glass microfiber supply concentration risk in Germany and Japan. Deepen captive cleanroom capacity for ISO 4406 Class 18/16/13 assembly zones in Tamil Nadu and Maharashtra to capture PLI scheme advantages. Defend against integrated sensor-filter module specialists by accelerating MEMS partnership timelines for real-time clogging diagnostics.
For New Entrants and Emerging Players: SAE J1165 test protocol fast-tracks offer entry pathways for Tier 2 suppliers lacking captive validation facilities. Target India's PLI scheme jurisdictions where 4-6% cost advantages on precision elements enable ASEAN export competitiveness. Pursue remanufactured hydraulic assembly certifications under EU Green Deal circular economy mandates as the most penetrable aftermarket white space.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated sensor-filter module producers with predictive maintenance software stacks. Long-term viability hinges on electrified chassis penetration rates where hydraulic backup systems retain filter demand. Watch fleet procurement contract structures as the inflection signal—outcome-based fluid cleanliness guarantees indicate supplier consolidation toward direct OEM relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Media | Captive borosilicate microfiber production mitigates single-source exposure in German and Japanese supply clusters. |
| Integrated Sensor-Filter Module Development | MEMS pressure sensor convergence enables predictive maintenance contracts with US commercial vehicle leasing companies. |
| PLI Scheme Manufacturing Footprint | Tamil Nadu and Maharashtra facilities capture 4-6% cost advantages for ASEAN precision element exports. |
| REACH-Compliant Coating Reformulation | Fluorine-free water-repellent validation closes 12-18 month German KBA type-approval gaps. |
| Remanufactured Assembly Certification | EU Green Deal circular economy mandates create verified cleanliness code demand in German and French commercial vehicle sectors. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with Tier 1 supplier procurement teams, OEM platform engineers, aftermarket distribution heads, and fleet maintenance directors. Secondary validation drew from vehicle production databases, IHS Markit registration data, EPA Tier 3 regulatory filings, and SAE J1165 test protocol documentation. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation by propulsion architecture, filter product type, material grade tier, end-user channel, and regional production cluster. CAGRs were derived from platform penetration curves for electrified steering and braking systems, cross-referenced with fluid cleanliness mandate enforcement timelines. Forecast inputs incorporated OEM platform consolidation schedules and cellulose pulp feedstock cycle assumptions.
Decision-makers should treat outputs as directional under stable regulatory enforcement and platform electrification cadence; material deviation in EPA or MEE stringency would warrant model refresh. Recalibration cycles align with shifts in REACH reformulation timelines and fleet procurement contract structure adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Battery Jump Starters Market
Automotive Parts
Philippines Passenger Vehicles Lubricants Market
Automotive Parts
Motorcycle Battery Chargers Market
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
Australia Automotive Airfilters Market
Automotive Parts
Automotive Hinges Market
Automotive Parts
Electric Vehicle Aluminum Electric Drive Parts Market
Automotive Parts
Mexico Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Belts Market
Automotive Parts
Resin Silencer Market
Automotive Parts
Auto Parts Manufacturing Market
Automotive Parts
Indonesia Commercial Vehicles Lubricants Market
Automotive Parts
Argentina Commercial Vehicles Lubricants Market
Automotive Parts
Automatic Bus Door System Market
Automotive Parts
Automotive Engine Oil Coolers Market
Automotive Parts
Automotive Pinion Gear Market