
 Automotive Transaxle Market | 2026-2036
Automotive Transaxle Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Transaxle Market Analysis
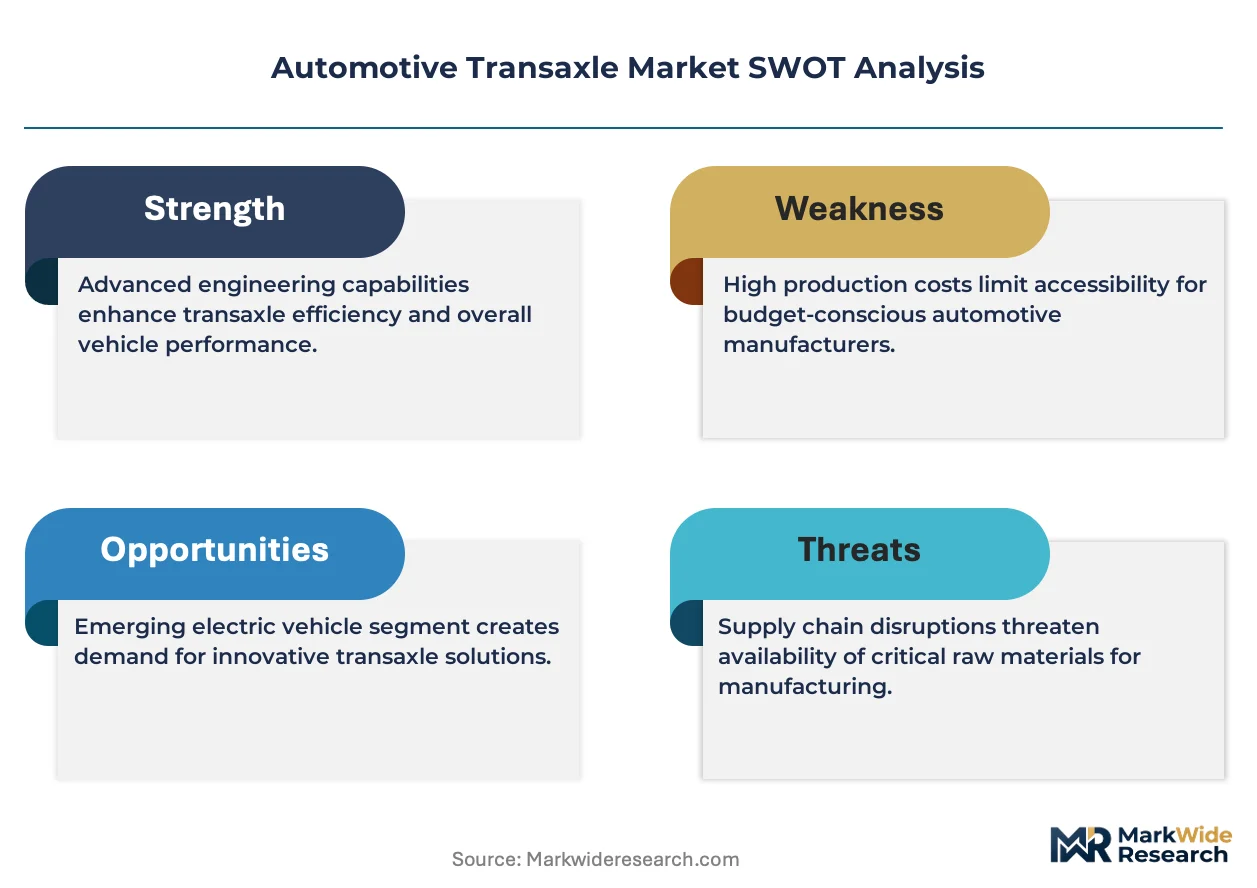
Asset-light leasing models for powertrain manufacturing equipment is fragmenting competitive entry barriers across the supplier base. ZF Friedrichshafen leverages captive tooling networks to sustain high-volume automatic transaxle output. Aisin anchors its position through deep hybrid integration expertise. BorgWarner competes on electrified transaxle architectures for battery-electric platforms.
An automotive transaxle combines the transmission, differential, and final drive into a single integrated housing, typically manufactured through precision gear hobbing, heat-treated alloy steel shafts, and aluminum die-cast casings to deliver torque vectoring and speed reduction directly to the driven axle. The assembly serves as the primary torque management and power distribution mechanism in front-wheel-drive, rear-wheel-drive, and all-wheel-drive vehicle configurations. Automatic transaxle systems command the largest installed base among product type segments, while dual-clutch transaxles capture expanding share in performance-oriented applications. Aluminum-intensive material formulations dominate OEM sourcing for weight-driven efficiency compliance, though composite reinforcement is gaining traction in hybrid electric technology variants where thermal management demands intensify.
NHTSA fuel economy standards and EPA emissions mandates in the United States compel OEMs to specify transaxles with reduced friction losses and expanded ratio spread. The EU Green Deal and REACH material compliance frameworks in Europe restrict certain alloying elements while incentivizing recyclable aluminum content in powertrain castings. Stakeholders must monitor how battery-electric platform standardization alters transaxle specification authority between vehicle assemblers and Tier-1 suppliers.
Market Dynamics
Platform electrification is compressing transaxle design cycles as OEMs abandon multi-speed architectures for single-speed reduction units, forcing suppliers to retool capacity toward integrated e-axle modules.
Growth Catalysts
- China EV platform scaling:Domestic OEMs in China are mandating dedicated skateboard architectures that embed transaxle functions within compact e-axle housings, accelerating specification shifts toward integrated suppliers.
- EU Green Deal material incentives:The framework's recyclability mandates favor aluminum-intensive transaxle castings, pulling foundry investment toward closed-loop production systems.
- Dual-clutch efficiency gains:Heat-treated alloy gearsets in performance applications deliver friction reductions that satisfy NHTSA fuel economy thresholds for light truck segments.
Market Restraints
- Rare earth magnet cost volatility:Permanent magnet materials for integrated e-axle motors face price swings tied to Chinese export quotas, squeezing margin predictability for mid-volume suppliers.
- Heat treatment capacity concentration:Precision gear hardening services cluster in Germany and Japan, creating single-source vulnerability for European and North American transaxle assemblers.
- BEV range anxiety substitution:Extended-range electric vehicles with simplified direct-drive layouts bypass multi-speed transaxles entirely in urban delivery segments.
Strategic Opportunities
- India commercial EV retrofit:State-level electric bus mandates in Maharashtra and Karnataka create aftermarket demand for bolt-on transaxle replacement kits in legacy chassis.
- Cell-to-chassis convergence:Battery pack structural integration with floor pans is freeing transaxle packaging volume for torque-vectoring differentials in premium AWD platforms.
- US IRA production credits:The Inflation Reduction Act's domestic content thresholds incentivize reshoring of aluminum die-casting operations for North American EV supply chains.
Industry Challenges
- Mechatronics skill scarcity:The fusion of gear mechanics with motor control software demands calibration engineers fluent in both domains, a combination rare in traditional powertrain workforces.
- Multi-homologation burden:Transaxle variants must simultaneously satisfy NHTSA FMVSS, ECE R100, and UN R85 protocols, extending validation timelines for global platform suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Transaxle Market |
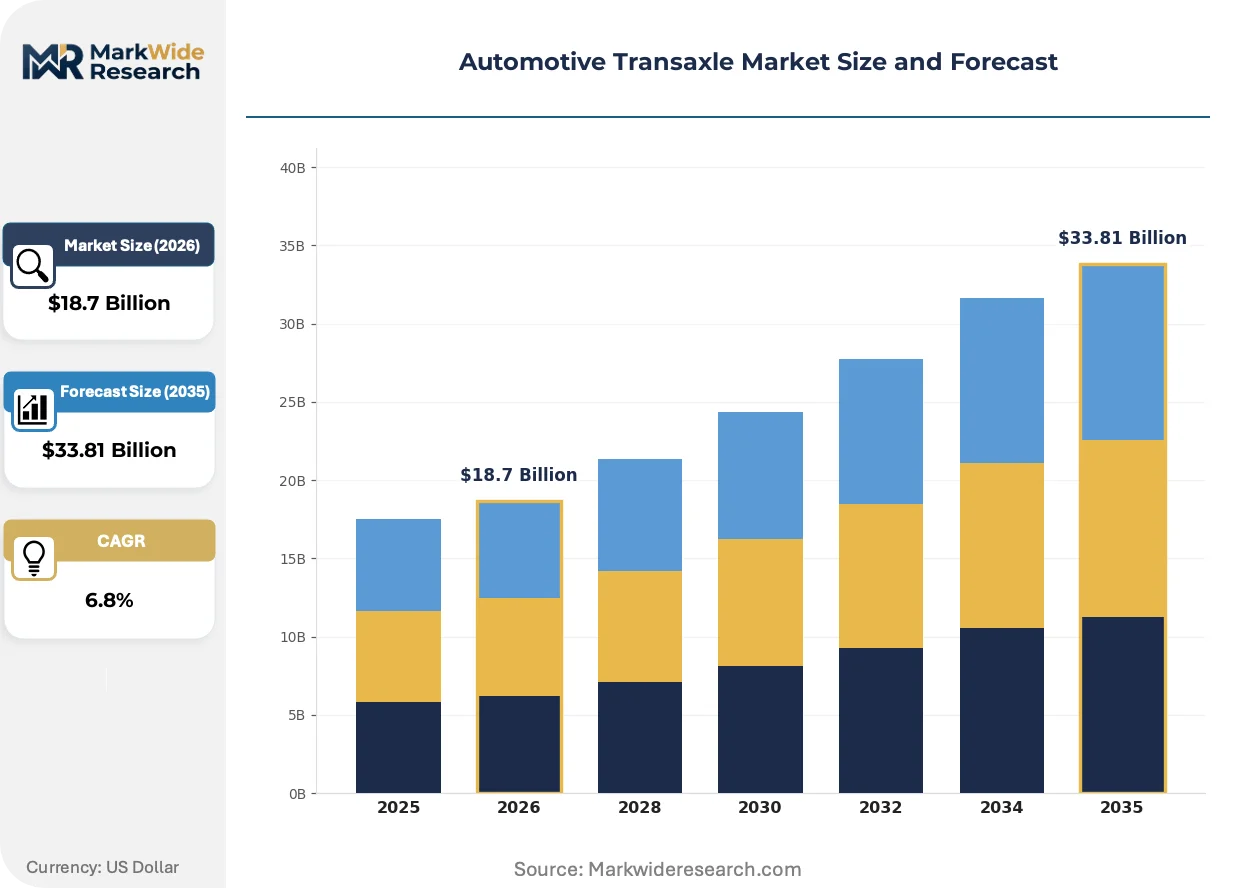
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Transaxle, Automatic Transaxle, Continuously Variable Transaxle, Dual-Clutch Transaxle End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Material: Aluminum, Steel, Composite, Magnesium Technology: Hybrid Electric, Fuel Cell, Gasoline, Diesel |
| Companies Covered | Hyundai Transys, Schaeffler, Aisin, Allison Transmission, JATCO, ZF Friedrichshafen, BorgWarner, Eaton, Magna International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Transaxle Market Emerging Trajectories
Electrification is collapsing the boundary between transmission and axle functions, compelling suppliers to master thermal-fluid dynamics and power electronics alongside mechanical gearing.
Additive manufacturing of conformal cooling channels within aluminum transaxle housings is rendering obsolete conventional straight-drilled oil galleries that struggle to manage heat flux in high-torque e-axle applications. Tier-1 suppliers serving German premium OEMs are adopting laser powder bed fusion for prototype iterations, compressing thermal validation cycles from months to weeks. The structural consequence is rendering obsolete legacy sand-cast housing designs that cannot accommodate complex internal geometries.
REACH Annex XVII restrictions on lead-containing alloys are forcing reformulation of bearing cages and synchronizer hubs across European supply chains. The ECHA framework's sunset dates for specific substance categories are accelerating migration to engineered polymer alternatives in friction-critical components. Heat-stabilized polyamide grades now dominate synchronizer applications in dual-clutch transaxles bound for EU markets.
Fleet operators are consolidating powertrain procurement through direct Tier-1 relationships, bypassing traditional vehicle assembler specification authority in electric commercial vehicle segments. Logistics operators with thousand-unit order scales now negotiate e-axle module pricing directly with BorgWarner and ZF, disintermediating OEM parts organizations. This pattern concentrates most visibly in North American last-mile delivery electrification programs where uptime guarantees override brand loyalty.
Automotive Transaxle Market Segmentation
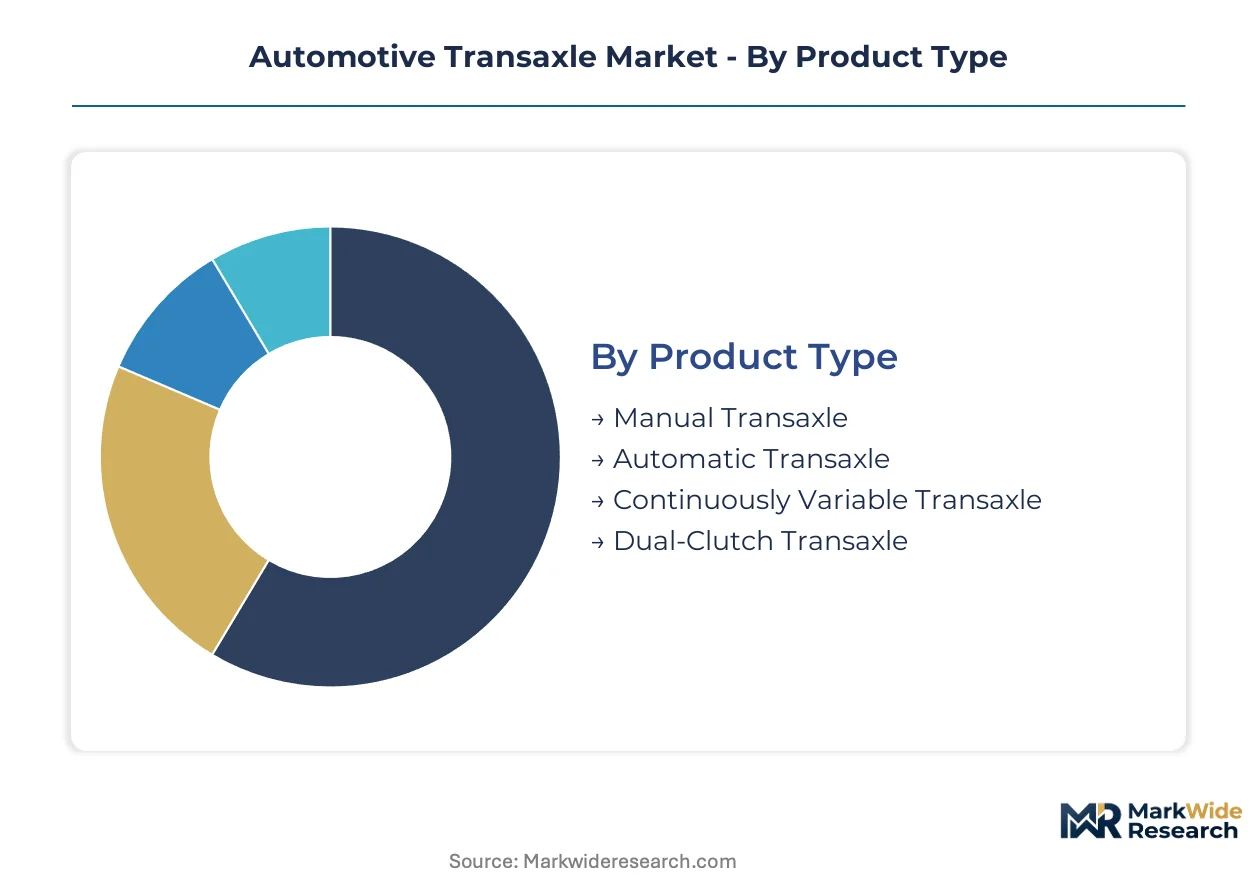
Transaxle segmentation reveals how electrification is fragmenting legacy architectures while concentrating procurement authority among new stakeholder types. Understanding these divides exposes where design cycles compress and where margin pools are migrating across the value chain.
Product Type:
Automatic and dual-clutch systems turn over fastest as OEMs chase efficiency mandates, while manual architectures face extended replacement cycles in cost-sensitive fleet segments.
- Automatic Transaxle:Torque converter architectures with planetary gearsets dominate light truck and SUV applications across North American OEM portfolios. Demand clusters with Detroit Three assemblers seeking NHTSA compliance through expanded ratio spreads and reduced parasitic losses.
- Dual-Clutch Transaxle:Wet-clutch and dry-clutch variants deliver sub-100-millisecond shifts for performance-oriented platforms. European premium OEMs in Germany and Italy specify these systems most intensively, driven by EU fleet CO2 targets that reward friction efficiency.
- Manual Transaxle:Synchronized constant-mesh designs persist in emerging-market compact vehicles and enthusiast sports cars.
- Continuously Variable Transaxle:Pulley-and-belt systems with steel push belts serve Japanese OEM hybrid strategies.
Automatic transaxles dominate installed base. Dual-clutch configurations are where expansion concentrates.
End User:
Procurement authority is shifting from vehicle assemblers toward direct Tier-1 relationships as fleet operators consolidate powertrain purchasing.
- OEMs:Original equipment manufacturers specify transaxle architectures during platform definition, retaining authority over gear ratio selection and thermal management requirements. Their sourcing decisions cascade through supplier tiers, with German and Japanese OEMs maintaining the most stringent validation protocols.
- Tier-1 Suppliers:Integrated module producers like ZF and Aisin now negotiate directly with logistics fleets for e-axle volumes, bypassing traditional OEM parts organizations. This disintermediation concentrates in North American last-mile electrification where uptime guarantees override assembler brand loyalty.
- Vehicle Assemblers:Contract manufacturers and regional assembly plants execute build-to-print contracts with limited design influence.
- Aftermarket Providers:Independent distributors and remanufacturers serve replacement demand in legacy internal-combustion fleets.
OEMs retain specification authority for new platforms. Tier-1 suppliers are capturing the steepest expansion trajectory through direct fleet relationships.
Material:
Cost tiers separate aluminum-intensive designs from steel legacy architectures, with magnesium and composites occupying narrow premium niches.
- Aluminum:Die-cast A380 and Silafont-36 alloys dominate housing production, driven by EU Green Deal recyclability mandates and NHTSA fuel economy weight reduction requirements. Foundry investment is concentrating in closed-loop production systems serving German and Chinese supply chains.
- Steel:Heat-treated alloy shafts and gearsets remain indispensable for torque transmission despite housing material shifts. Japanese and German heat treatment capacity constrains global supply, creating single-source vulnerability for precision-hardened components.
- Composite:Glass-fiber and carbon-fiber reinforced polymers penetrate hybrid electric variants where thermal isolation benefits outweigh cost premiums.
- Magnesium:AZ91D castings serve ultra-lightweight applications in limited European premium volumes.
Aluminum dominates installed base. Steel maintains irreplaceable positions in torque-critical subsystems.
Technology:
Application type determines thermal management intensity and integration complexity, with hybrid and fuel cell platforms imposing the most severe engineering constraints.
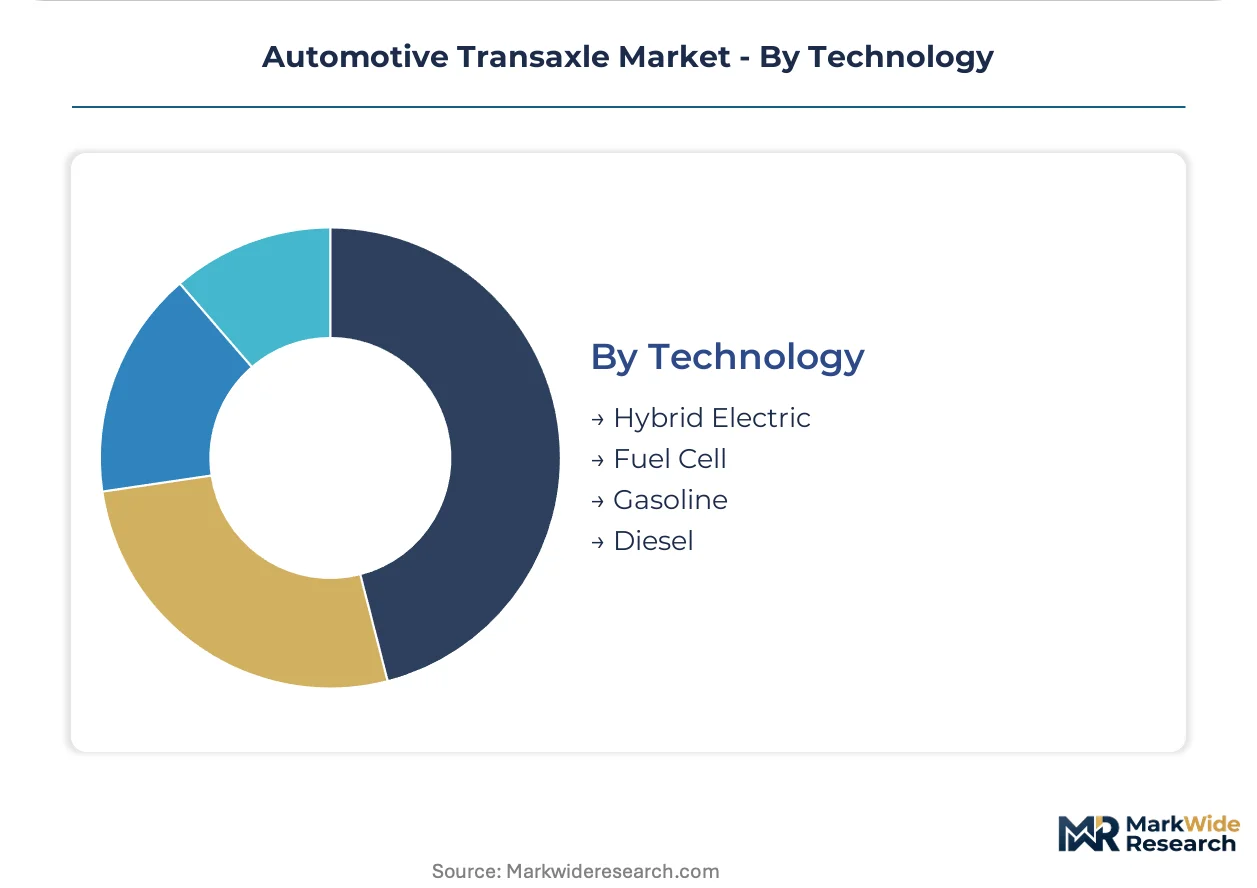
- Hybrid Electric:Power-split and P2 architectures demand transaxles that blend mechanical torque with electric motor output through planetary carriers and clutch packs. Japanese and Chinese OEMs specify these systems most aggressively as bridge technologies during full electrification transitions.
- Gasoline:Turbocharged direct-injection engines paired with multi-speed automatics persist in North American light truck segments where towing capacity requirements resist electrification timelines.
- Fuel Cell:Proton-exchange membrane vehicles require specialized reduction gearsets matched to high-revving fuel cell stack output characteristics.
- Diesel:Compression-ignition transaxle demand contracts in European passenger markets but sustains in Indian and Southeast Asian commercial vehicle segments.
Gasoline systems dominate installed base. Hybrid electric configurations are gaining share fastest as regulatory deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Inflation Reduction Act's domestic content thresholds are reshaping North American supply chains while Chinese EV platform mandates accelerate specification shifts toward integrated e-axle suppliers.
United States
Detroit Three assemblers specify expanded-ratio automatic transaxles to satisfy NHTSA fuel economy thresholds for light truck segments. The IRA's production credits incentivize reshoring of aluminum die-casting operations. Foundry investment clusters in Michigan and Ohio as Tier-1 suppliers establish closed-loop production systems for EV supply chains.
Germany
Premium OEMs in Bavaria and Baden-Württemberg mandate wet-clutch dual-clutch systems to meet EU fleet CO2 targets through friction efficiency gains. ECHA REACH Annex XVII restrictions on lead-containing alloys force bearing cage reformulation across supplier tiers. Heat treatment capacity concentrates in Stuttgart and Munich, creating single-source vulnerability for precision-hardened gear components.
China
Domestic OEMs mandate dedicated skateboard architectures that embed transaxle functions within compact e-axle housings. MIIT dual carbon goals accelerate full electrification timelines beyond bridge hybrid phases. Manufacturing gravity centers on Yangtze River Delta foundries serving BYD and NIO platform scaling.
Japan
Power-split hybrid architectures sustain transaxle demand as bridge technologies during electrification transitions. METI technology roadmaps prioritize thermal management integration in next-generation e-axle modules. Supplier engineering concentrates in Aichi Prefecture around Toyota and Honda platform development centers.
India
State-level electric bus mandates in Maharashtra and Karnataka create aftermarket demand for bolt-on transaxle replacement kits in legacy commercial chassis. The PLI scheme for automotive components attracts foundry investment toward aluminum-intensive housing production. Manufacturing clusters in Tamil Nadu and Gujarat serve domestic OEM scaling and export programs.
Automotive Transaxle Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The vendor base organizes around three strategic archetypes: integrated module producers capturing direct fleet relationships, precision gear specialists anchoring heat-treatment-dependent supply chains, and aluminum foundry operators controlling housing cost structures. Dominant competitive moves include capacity retooling toward e-axle architectures and backward integration into permanent magnet motor assembly.
Among German-based integrated module producers, ZF Friedrichshafen and Schaeffler exemplify the channel-control archetype through captive tooling networks and direct OEM specification authority. Aisin represents the hybrid integration specialist tier, anchoring power-split architecture expertise across Japanese and Chinese OEM portfolios. These three companies occupy positions that define competitive intensity for precision-hardened components and aluminum-intensive housing supply.
| Leading Market Players |
|---|
| Hyundai Transys |
| Schaeffler |
| Aisin |
| Allison Transmission |
| JATCO |
| ZF Friedrichshafen |
| BorgWarner |
| Eaton |
| Magna International |
| Others |
Supply Flow & Price Mechanics
Heat treatment capacity underutilization in European precision gear facilities is compressing margin structures for mid-volume transaxle assemblers while simultaneously incentivizing foundry consolidation in aluminum housing supply. This utilization asymmetry between heat-treated steel components and die-cast aluminum enclosures creates divergent pricing power across supplier tiers, with housing producers capturing volume discounts that gear specialists cannot match.
Pricing Analysis
Certification level across NHTSA FMVSS, ECE R100, and UN R85 protocols creates the primary spread between premium validated units and economy-tier unhomologated alternatives. Pricing stratifies across OEM-specified, Tier-1 fleet-direct, and aftermarket remanufactured tiers, with fleet operators commanding steepest discounts through thousand-unit order scales. Cost compression in aluminum die-casting is intensifying because Chinese Yangtze River Delta foundries are expanding closed-loop production capacity. OEM platform engineers exhibit lowest price sensitivity due to thermal management performance guarantees, while aftermarket distributors face margin erosion from remanufactured import competition.
Supply Chain Analysis
Contract manufacturing concentration among ZF Friedrichshafen, Aisin, and Magna International controls approximately two-thirds of integrated e-axle module capacity across Germany, China, and Mexico. Raw material flows draw from heat-treated alloy steel shaft production in Germany and Japan, permanent magnet materials subject to Chinese export quotas, and A380 aluminum ingot sourcing from domestic smelters. Single-source vulnerability concentrates in precision gear hardening services clustered around Stuttgart and Nagoya. Distribution runs through captive OEM supply agreements for new platforms, direct Tier-1 negotiation for fleet electrification programs, and independent aftermarket channels for legacy internal-combustion replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform electrification represents a substitution defense imperative for incumbent mechanical powertrain suppliers, as single-speed e-axle architectures displace multi-speed transaxle demand in battery-electric vehicle scaling. The collapse of gear-count specifications threatens traditional competitive moats anchored in ratio-spread engineering.
For Market Incumbents: Pre-empt margin erosion in automatic transaxle segments by accelerating backward integration into permanent magnet motor assembly and thermal-fluid dynamics software stacks. Capture direct fleet relationships in North American last-mile electrification before logistics operators consolidate procurement authority entirely around uptime-guarantee contracts. Prioritize heat treatment capacity expansion in lower-cost manufacturing clusters to offset German and Japanese single-source vulnerability.
For New Entrants and Emerging Players: Mid-market commercial EV retrofit opportunities in Indian state bus mandates represent the most penetrable entry point, with Maharashtra and Karnataka procurement programs lacking established supplier relationships. Bolt-on transaxle replacement kits for legacy chassis require minimal platform engineering integration compared to clean-sheet e-axle development. Pursue direct state-transport-department certification pathways that bypass OEM specification gatekeeping entirely.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated module producers with captive fleet-maintenance contracts spanning battery-electric commercial vehicle deployments. Long-term viability in this market hinges on thermal management software differentiation rather than mechanical gearing heritage alone. Monitor cell-to-chassis architecture adoption rates as the critical signal for whether torque-vectoring differential premiumization sustains or collapses.
| Strategic Initiative | Industry Significance |
|---|---|
| E-Axle Platform Standardization | Reduces engineering validation burden across BYD and NIO skateboard architectures. |
| Permanent Magnet Supply Agreement | Secures rare earth magnet volumes ahead of Chinese export quota volatility. |
| Additive Manufacturing Adoption | Enables conformal cooling channels that sand-cast housings cannot accommodate. |
| Direct Fleet Relationship Establishment | Bypasses OEM parts organizations in North American last-mile electrification. |
| Closed-Loop Foundry Investment | Satisfies EU Green Deal recyclability mandates for aluminum-intensive castings. |
Methodological Framework
The analysis maps automatic, dual-clutch, manual, and continuously variable transaxle architectures alongside integrated e-axle modules, each validated through Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and fleet maintenance operators. Primary fieldwork combined with secondary validation from NHTSA fuel economy filings, EPA emissions compliance databases, EU Green Deal implementation reports, and MIIT dual carbon policy documents anchored segmentation boundaries. Bottom-up production volume estimates triangulated against top-down OEM platform allocation data.
Assumptions held battery-electric vehicle penetration timelines and rare earth magnet price trajectories as fixed boundary conditions while varying thermal management intensity requirements and fleet electrification procurement consolidation rates. Segmentation dimensions modeled include propulsion architecture, vehicle class, material formulation, and regional regulatory cluster. CAGRs derived from production volume elasticity to platform scaling announcements and foundry capacity expansion disclosures. Industry-specific forecast inputs incorporated heat treatment capacity utilization rates and aluminum die-casting investment pipelines.
Practitioners should monitor MIIT dual carbon acceleration signals and IRA domestic content threshold adjustments for early revision triggers to electrification timelines. Forecasts reflect these documented assumptions regarding platform standardization and supplier consolidation trajectories. Quarterly review of permanent magnet export quota announcements and EU REACH Annex XVII substance restriction updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
China Automotive Actuators Market
Automotive Components
Automotive Polymer Composites Market
Automotive Components
Automotive Solar Control Glass Market
Automotive Components
Australia Automotive Composites Market
Automotive Components
Electric Vehicle Fluid Lubricants Market
Automotive Components
Automotive Subframe Market
Automotive Components
Automotive Camshaft Phase Variator Market
Automotive Components
India Automotive Glass Fiber Composites Market
Automotive Components
Automotive Door Module Market
Automotive Components
Automotive Filters Market
Automotive Components
Global Automatic Lubrication System Market
Automotive Components
Automotive Differential Market
Automotive Components
Germany Automotive Composites Market
Automotive Components
Global Automotive Condenser Market
Automotive Components
Automotive Carbon Brake Rotor Market
Automotive Components
India Automotive Heat Exchanger Market