
 Automotive Distributor O Ring Market | 2026-2036
Automotive Distributor O Ring Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Distributor O Ring Market Outlook
Southeast Asia is fragmenting as low-cost molding capacity expands across Thailand, Vietnam, and Indonesia. Freudenberg Sealing Technologies leverages its captive compound development to supply heat-resistant grades for hybrid distributor modules. Trelleborg AB anchors its position through precision extrusion capabilities that serve European premium OEMs. SKF competes by extending its bearing-channel relationships into adjacent sealing procurement decisions.
An automotive distributor O ring is a toroidal elastomeric seal installed at the interface of a distributor housing and engine block to prevent vacuum, oil, and coolant leakage under cyclic thermal and pressure loads; manufacturers typically mold these components from fluorocarbon or silicone compounds rated for continuous operation above 150°C and intermittent exposure to aromatic hydrocarbons. Standard O Rings occupy the volume base due to interchangeability across legacy internal combustion platforms, while Customized O Rings capture margin pools as electrified architectures demand non-standard groove geometries and multi-material bonding. Specialty O Rings represent the fastest-growing material category as perfluoroelastomer formulations penetrate high-voltage coolant circuits in battery thermal management systems.
EPA regulations under the Clean Air Act and NHTSA Corporate Average Fuel Economy standards enforce evaporative emission limits that directly tighten allowable permeation rates for fuel-system seals, including distributor interfaces. The EU F-Gas Regulation and REACH restrictions on perfluorinated substances are reshaping compound formulation roadmaps for suppliers serving European OEMs. Stakeholders must monitor how refrigerant transitions under EPA SNAP rules and MEE dual-carbon enforcement in China redefine material qualification timelines for air-conditioning and thermal management seals.
Market Dynamics
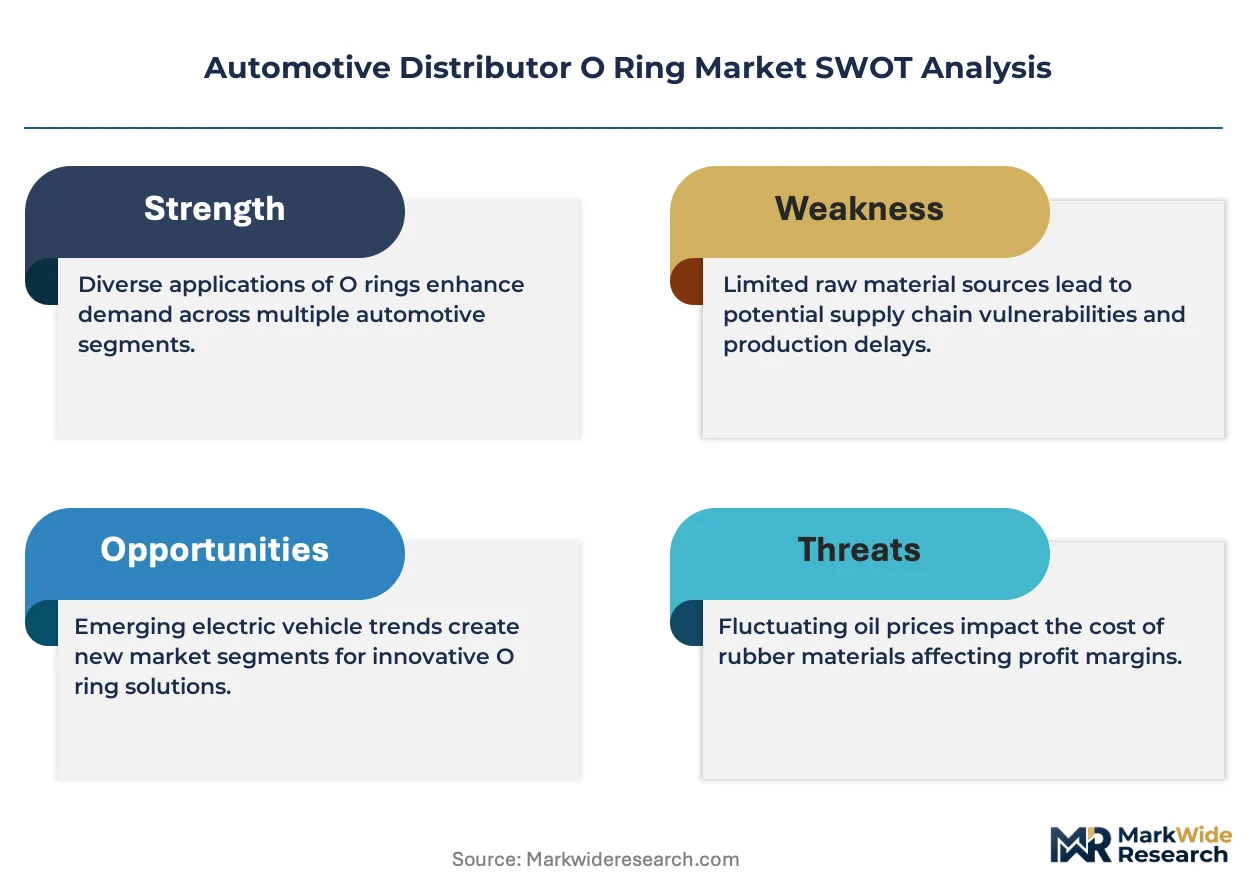
Thermal management complexity in battery electric vehicles is forcing compound qualification cycles to compress from 18 months to under 12 months, reshaping how sealing suppliers allocate R&D resources and validate material portfolios.
Growth Catalysts
- EPA evaporative emission thresholds:Tightened permeation limits under Clean Air Act amendments are accelerating fluorocarbon O ring replacement cycles in fuel distributor assemblies across US light-duty fleets.
- China MEE dual-carbon enforcement:Domestic automakers in Shanghai and Shenzhen are localizing sealing procurement to meet carbon intensity benchmarks in thermal management supply chains.
- Perfluoroelastomer thermal stability:Specialty compounds rated above 200°C continuous operation are penetrating high-voltage coolant circuits as battery pack energy densities climb.
Market Restraints
- Fluoropolymer feedstock volatility:Hexafluoropropylene and vinylidene fluoride monomer prices swing with refrigerant phase-down schedules, compressing compounder margins unpredictably.
- Thai molding capacity concentration:Low-cost extrusion and compression molding clusters around Bangkok and Rayong are absorbing regional volume, pressuring European and Japanese suppliers on price.
- REACH perfluorinated substance restrictions:ECHA proposals to limit PFAS in automotive applications are forcing reformulation roadmaps that extend qualification timelines by 8-14 months.
Strategic Opportunities
- Indonesian EV component localization:Government mandates for 40% domestic content in electric powertrains by 2027 are opening captive demand for locally molded sealing solutions.
- Multi-material bonding architectures:Hybrid metal-elastomer distributor modules requiring co-molded seals are creating margin pools above standard O ring replacement business.
- EU F-Gas refrigerant transition:R-1234yf adoption timelines are accelerating demand for low-permeation seals in thermal expansion valve and distributor interfaces.
Industry Challenges
- Compound formulation chemist scarcity:Expertise in perfluoroelastomer curing systems and metal adhesion promoters is concentrating at a handful of European and Japanese suppliers, constraining expansion.
- Legacy groove geometry incompatibility:Electrified architectures with non-standard housing interfaces require custom seal designs that cannot leverage existing tooling from internal combustion platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Distributor O Ring Market |
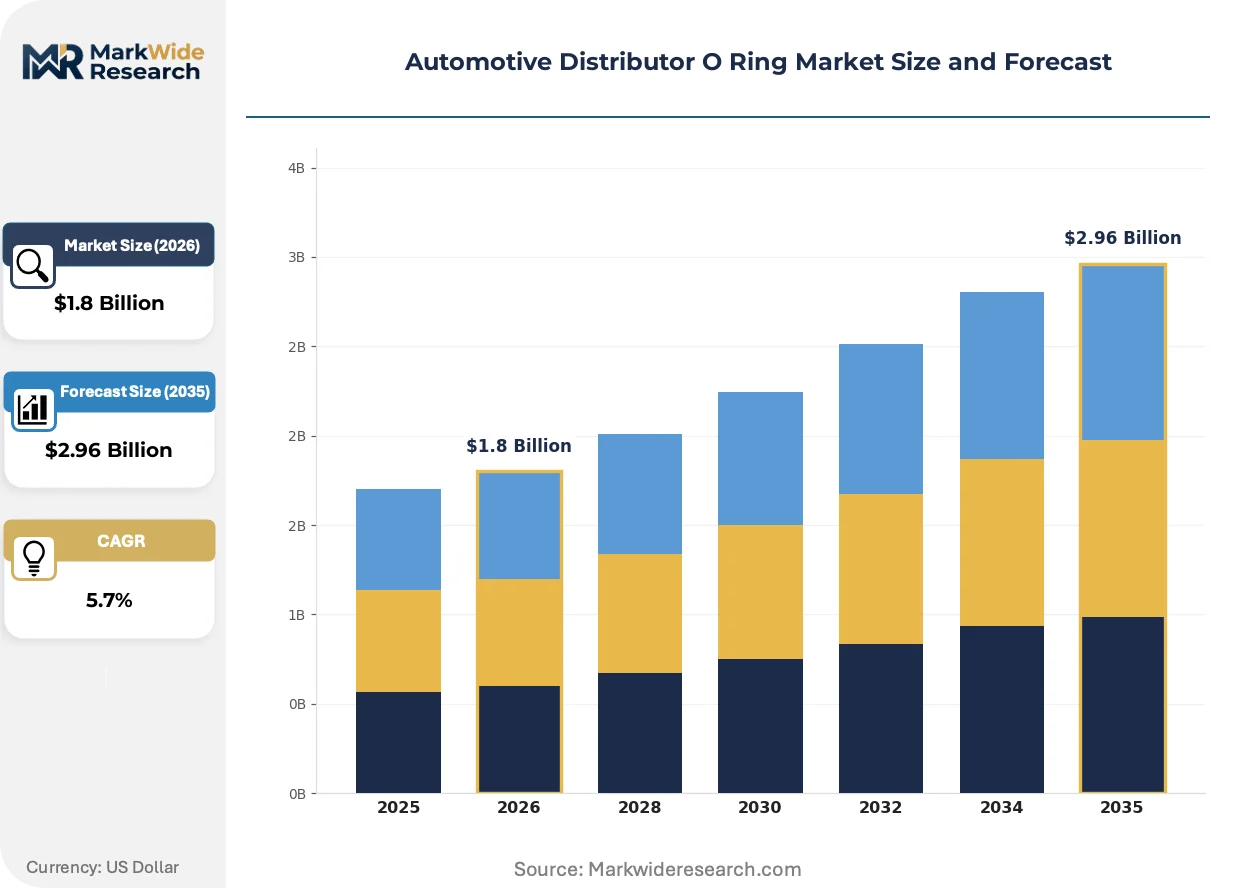
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard O Rings, Customized O Rings, Specialty O Rings, Metric O Rings Material: EPDM, Nitrile Rubber, Neoprene, Silicone End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships Application: Fuel Systems, Hydraulic Systems, Air Conditioning, Engine Components |
| Companies Covered | Freudenberg Sealing Technologies, Parker Hannifin, Trelleborg AB, MAHLE GmbH, NOK Corporation, Marco Rubber & Plastics, LLC, Apple Rubber Products, Inc, Precision Associates, Inc, SKF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Distributor O Ring Market Strategic Shifts
Virtual engineering environments are compressing design-validation loops from physical prototyping to simulation-first workflows, altering how sealing suppliers interact with OEM thermal management teams and tier-one integrators.
Digital twin platforms for elastomer compound behavior are virtualizing the traditional mold-flow and thermal-aging validation stages that once required 6-month physical test programs. Tier-one thermal management suppliers in Germany and Japan are adopting these tools at the concept phase. The compression of qualification timelines is virtualizing competitive advantage toward software-capable compounders with in-house finite element analysis teams.
REACH restrictions on perfluorinated substances are forcing reformulation investments across European supplier portfolios before 2027 enforcement windows. Compounders serving Stuttgart and Munich OEMs are accelerating hydrogenated nitrile and tetrafluoroethylene-propylene alternatives. The regulatory pressure is concentrating qualification resources on mid-temperature coolant applications where specialty fluoroelastomers previously dominated.
Direct OEM engagement with compound developers is displacing traditional tier-one distributor purchasing structures in thermal management procurement. Battery pack manufacturers in California and Bavaria are establishing material specifications that bypass conventional channel intermediaries. This disintermediation is most visible in high-voltage coolant circuit contracts where thermal runaway containment requirements demand compound-level technical dialogue.
Automotive Distributor O Ring Market Segmentation
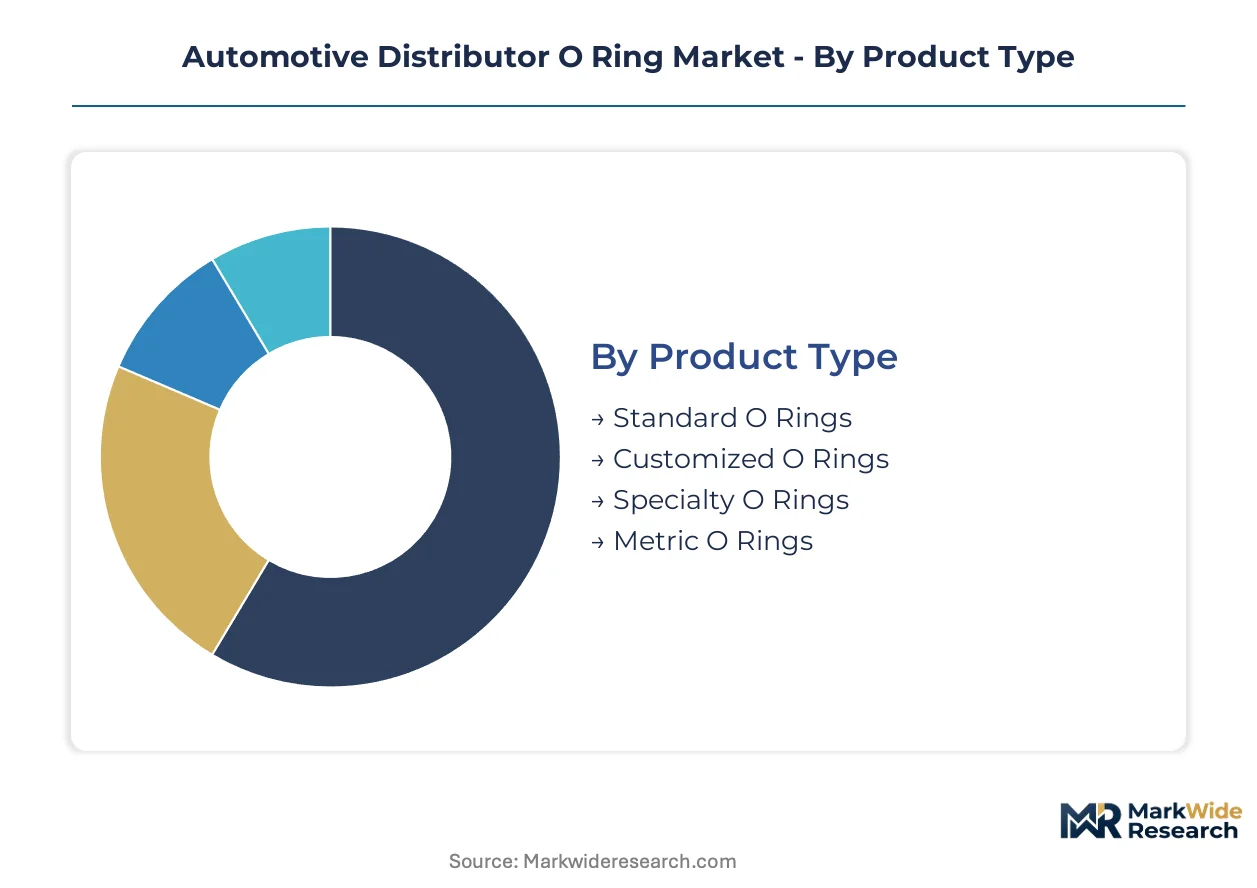
Segmentation in the automotive distributor O ring market reveals divergent margin structures and replacement cycles. After-sales-service intensity varies dramatically across product tiers, with standard hardware generating volume turnover while specialty compounds command technical premiums in thermal management procurement.
Product Type:
After-sales-service intensity correlates inversely with standardization—generic O rings move through high-velocity distribution with minimal technical support, while custom and specialty variants demand application engineering and compound qualification assistance.
- Standard O Rings:Molded to SAE J120 and ISO 3601-1 dimensions from fluorocarbon or nitrile rubber compounds rated for 150°C continuous operation. Demand concentrates in legacy internal combustion service bays across the United States and Germany, where interchangeability reduces inventory carrying costs for distributors serving multi-brand repair networks.
- Customized O Rings:Engineered to non-standard groove geometries and multi-material bonding specifications for electrified powertrain housings. Procurement is accelerating in China, where domestic automakers in Shenzhen and Shanghai specify unique sealing interfaces for battery thermal management modules that cannot leverage existing tooling.
- Specialty O Rings:Perfluoroelastomer formulations for continuous operation above 200°C in high-voltage coolant circuits.
- Metric O Rings:DIN 3771 dimension series serving European and Asian OEM assembly lines.
By volume, Standard O Rings leads. By growth pace, Specialty O Rings is ahead.
Material:
Cost tier stratification separates commodity elastomers from fluoropolymer grades, with compound selection directly determining thermal ceiling and chemical resistance in fuel versus coolant exposure environments.
- EPDM:Ethylene-propylene-diene monomer compounds excel in phosphate ester hydraulic fluids and steam applications but degrade in petroleum-based media; specification concentrates in European HVAC and cooling system procurement where REACH compliance favors non-fluorinated alternatives.
- Nitrile Rubber:Acrylonitrile-butadiene formulations balance oil resistance and cost for fuel system sealing across legacy distributor architectures.
- Neoprene:Chloroprene polymers serving refrigerant and moderate-temperature coolant exposure in air conditioning circuits.
- Silicone:VMQ compounds rated for -60°C to 230°C operation in extreme thermal cycling applications.
By volume, Nitrile Rubber leads. By margin expansion, EPDM is climbing the fastest.
End User:
Customer type determines procurement channel structure, with OEMs and tier-one integrators engaging compound developers directly while aftermarket flows through distribution intermediaries with divergent technical support requirements.
- OEMs:Vehicle manufacturers in Bavaria and California establish material specifications that bypass traditional channel intermediaries, particularly for high-voltage coolant circuits where thermal runaway containment demands compound-level technical dialogue.
- Tier-1 Suppliers:Thermal management integrators in Germany and Japan consolidate sealing procurement within broader system contracts.
- Aftermarket Providers:Independent distributors serving multi-brand repair networks with inventory breadth over technical depth.
- Dealerships:Authorized service channels capturing captive replacement demand under warranty and extended service programs.
By volume, Tier-1 Suppliers leads. By channel disintermediation momentum, OEMs is gaining share fastest.
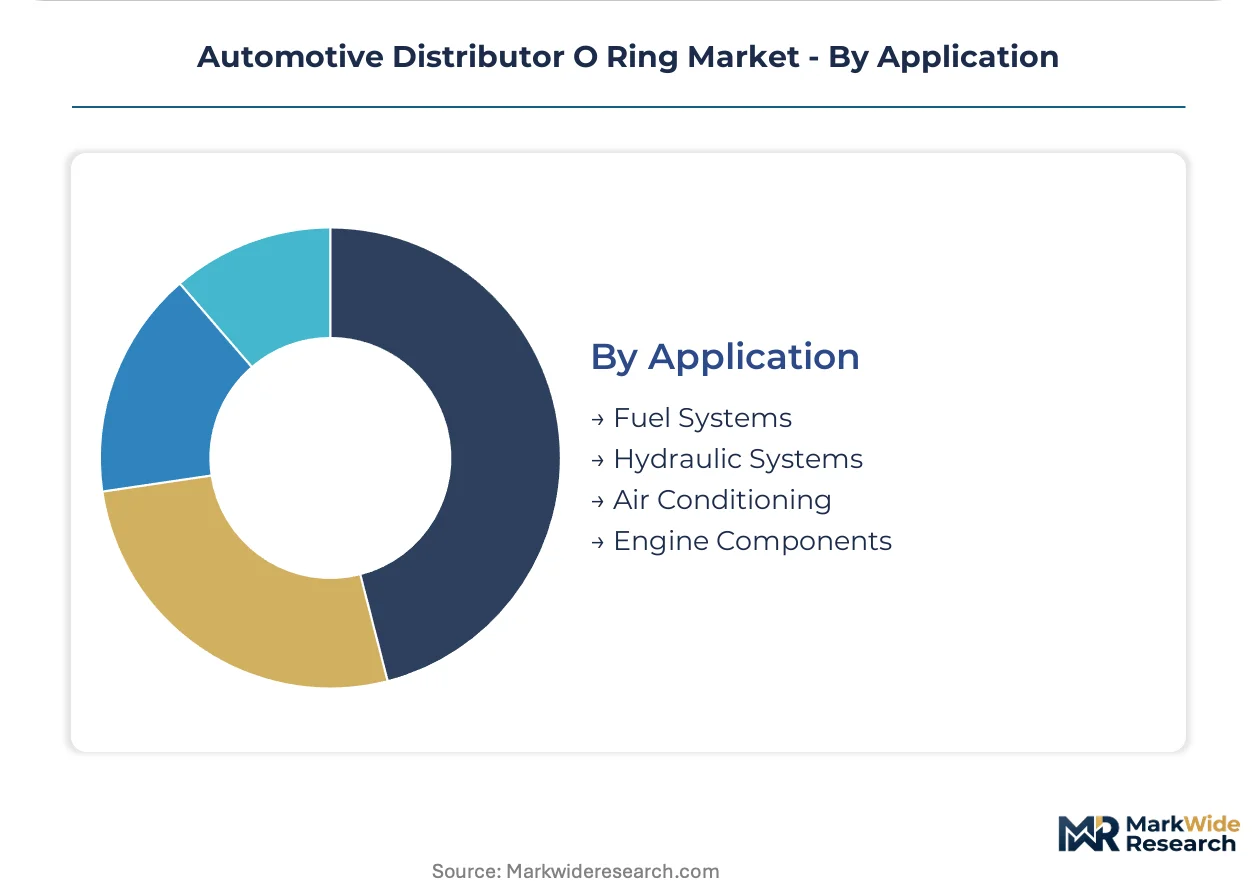
Application:
Application segmentation maps directly to regulatory exposure, with fuel system sealing subject to EPA evaporative emission thresholds and thermal management interfaces governed by refrigerant phase-down schedules under F-Gas and SNAP rules.
- Fuel Systems:Distributor interface seals preventing vacuum and hydrocarbon leakage under cyclic pressure loads; EPA Clean Air Act amendments tightening permeation limits are accelerating fluorocarbon replacement cycles across US light-duty fleets.
- Hydraulic Systems:Power steering and brake fluid sealing with phosphate ester compatibility requirements.
- Air Conditioning:R-1234yf refrigerant transition under EPA SNAP and EU F-Gas Regulation is accelerating demand for low-permeation seals in thermal expansion valve interfaces.
- Engine Components:Coolant and oil sealing in conventional powertrain architectures facing electrification displacement.
By volume, Engine Components leads. By regulatory tailwinds, Air Conditioning is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo port complex channels raw fluoropolymer feedstock and finished sealing components across the Asia-Pacific manufacturing belt, underwriting regional supply security for thermal management procurement.
United States
EPA Clean Air Act amendments and NHTSA fuel economy standards tighten evaporative emission thresholds for fuel system seals. Detroit-area OEMs accelerate fluorocarbon replacement cycles in legacy distributor assemblies. Molding demand concentrates in Michigan and Ohio service corridors serving multi-brand repair networks.
Germany
EU F-Gas Regulation and REACH perfluorinated substance restrictions reshape compound formulation roadmaps for Stuttgart and Munich OEMs. ECHA enforcement windows extend qualification timelines for thermal management seals. Bavarian thermal management integrators consolidate sealing procurement within broader system contracts.
China
MEE dual-carbon enforcement drives domestic automakers in Shenzhen and Shanghai to localize sealing procurement. Domestic content mandates for electrified powertrains compress import dependency in thermal management supply chains. Yangtze River Delta molding clusters absorb regional volume for battery coolant circuit specifications.
Japan
METI industrial standards and JIS certification requirements govern precision extrusion capabilities for hybrid distributor modules. Nagoya-area suppliers extend bearing-channel relationships into adjacent sealing procurement decisions. Kansai manufacturing belts serve premium OEM assembly lines with metric dimension series.
Thailand
Low-cost extrusion and compression molding capacity expands around Bangkok and Rayong, absorbing Southeast Asian regional volume. Government EV component localization mandates by 2027 open captive demand for locally molded sealing solutions. Eastern Economic Corridor infrastructure supports tier-one thermal management supplier expansion.
Automotive Distributor O Ring Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with compound-level technical dialogue. The vendor base separates into captive compound developers, precision extrusion houses, and bearing-channel extenders. Three archetypes dominate: European-Japanese fluoroelastomer compounders, Southeast Asian low-cost molders, and diversified industrial conglomerates with sealing divisions. Competitive moves concentrate on backward integration into monomer supply and multi-material bonding capability acquisition.
Among diversified industrial fabricators, Freudenberg Sealing Technologies and Trelleborg AB occupy positions reflecting European premium-tier specialization, while SKF sits within the bearing-channel extension archetype. These three exemplify how compound development capabilities, precision extrusion assets, and adjacent mechanical component relationships anchor competitive positioning in thermal management procurement.
| Leading Market Players |
|---|
| Freudenberg Sealing Technologies |
| Parker Hannifin |
| Trelleborg AB |
| MAHLE GmbH |
| NOK Corporation |
| Marco Rubber & Plastics, LLC |
| Apple Rubber Products, Inc |
| Precision Associates, Inc |
| SKF |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Ningbo port complex channels raw fluoropolymer feedstock and finished sealing components across the Asia-Pacific manufacturing belt, underwriting regional supply security while its freight cost dynamics compress margins for European compounders and amplify price differentiation between captive compound developers and independent molders serving aftermarket distributors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates perfluoroelastomer formulations for high-voltage coolant circuits from fluorocarbon grades in legacy fuel systems and nitrile rubber replacements in price-sensitive service bays. Price differentiation hinges on certification grade for REACH compliance and volume scale in OEM procurement contracts. Cost compression in the economy tier is intensifying because Thai molding clusters absorb regional aftermarket volume. Independent distributors serving multi-brand repair networks exhibit highest price sensitivity; battery pack manufacturers in California and Bavaria show lowest sensitivity due to thermal runaway containment requirements.
Supply Chain Analysis
Export-control regimes restricting advanced fluoropolymer synthesis technology limit compound development capacity concentration in Germany, Japan, and the United States, constraining supply expansion for specialty grades. Raw material flows draw from hexafluoropropylene monomer production in China, vinylidene fluoride feedstock in the United States, and perfluoroelastomer base polymers from Japanese suppliers. Single-source vulnerability concentrates in European perfluoroelastomer curing system expertise. Distribution runs through tier-one thermal management integrators in Germany and Japan that consolidate sealing procurement within broader system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive distributor O ring demand sits in early-cycle expansion as battery electric vehicle thermal management architectures multiply sealing interfaces per vehicle beyond legacy internal combustion platforms.
For Market Incumbents: Pre-empt compound formulation chemist scarcity by anchoring perfluoroelastomer curing expertise through captive R&D centers in Nagoya and Stuttgart before qualification timelines extend further under REACH enforcement. Defend margin position against Thai low-cost molders by accelerating multi-material bonding capability acquisition for hybrid metal-elastomer distributor modules. For New Entrants and Emerging Players: Build out Indonesian molding capacity to capture government-mandated domestic content requirements for 40% local EV component sourcing by 2027. Target white-space in Shenzhen and Shanghai battery thermal management procurement where domestic automakers specify non-standard groove geometries that cannot leverage existing tooling from established suppliers. For Investors and Strategic Acquirers: European-Japanese fluoroelastomer compounders with in-house finite element analysis teams represent the most defensible acquisition archetype as virtual engineering environments compress competitive advantage toward software-capable suppliers. Monitor ECHA enforcement windows for PFAS restrictions as the inflection signal that would accelerate consolidation toward hydrogenated nitrile and tetrafluoroethylene-propylene alternative portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive hexafluoropropylene sourcing insulates compounders from refrigerant phase-down price volatility. |
| Multi-Material Bonding Capability Acquisition | Co-molded seal expertise opens margin pools above standard O ring replacement business in hybrid modules. |
| Indonesian Manufacturing Footprint Expansion | Eastern Economic Corridor positioning captures government EV localization mandates by 2027 enforcement. |
| Virtual Engineering Platform Investment | Digital twin adoption compresses design-validation loops from physical prototyping to simulation-first workflows. |
| REACH Alternative Compound Qualification | Hydrogenated nitrile and tetrafluoroethylene-propylene portfolios preempt 2027 PFAS restriction enforcement. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA enforcement databases, ECHA regulatory filings, IHS Markit vehicle production data, and customs trade records through structured interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations managers, and compound development chemists at European and Japanese suppliers. Bottom-up volume estimates from molding capacity utilization and top-down demand triangulation from vehicle production forecasts were cross-validated.
Forecast inputs span propulsion architecture segmentation, content per vehicle trajectories for thermal management interfaces, and regional production cluster shifts across the projection horizon. CAGRs were derived from modeled replacement cycle compression in electrified powertrains and regulatory acceleration of fluorocarbon replacement timelines. Industry-specific inputs include battery pack energy density trajectories and refrigerant transition schedules under EPA SNAP and EU F-Gas Regulation.
Stress conditions across fluoropolymer feedstock price volatility, REACH enforcement timeline acceleration, and Thai molding capacity absorption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding electrification penetration and thermal management architecture evolution. Material shifts in perfluoroelastomer regulatory classification or battery thermal runaway containment standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Damper Control Unit Market
Automotive Components
South Korea Automotive Pneumatic Actuators Market
Automotive Components
Automotive Active Bonnet Market
Automotive Components
Asia-Pacific Automotive Upholstery Market
Automotive Components
Automotive Gear Shifter Market
Automotive Components
North America Heat Shrink Tubing for Automotive Market
Automotive Components
Auto Fender Market
Automotive Components
Advanced Automotive Materials Market
Automotive Components
Automotive Smart Actuator Market
Automotive Components
Automotive Actuators Market
Automotive Components
Bulgaria Commercial Vehicles Lubricants Market
Automotive Components
Global Automotive Noise Filter Market
Automotive Components
Automotive Retarders Market
Automotive Components
Automotive Sheet Metal Components Market
Automotive Components
Asia Pacific Automotive Actuators Market
Automotive Components
Automotive Brake Tube Market