
 Automotive Catalytic Converter Market | 2026-2036
Automotive Catalytic Converter Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Catalytic Converter Market Intelligence
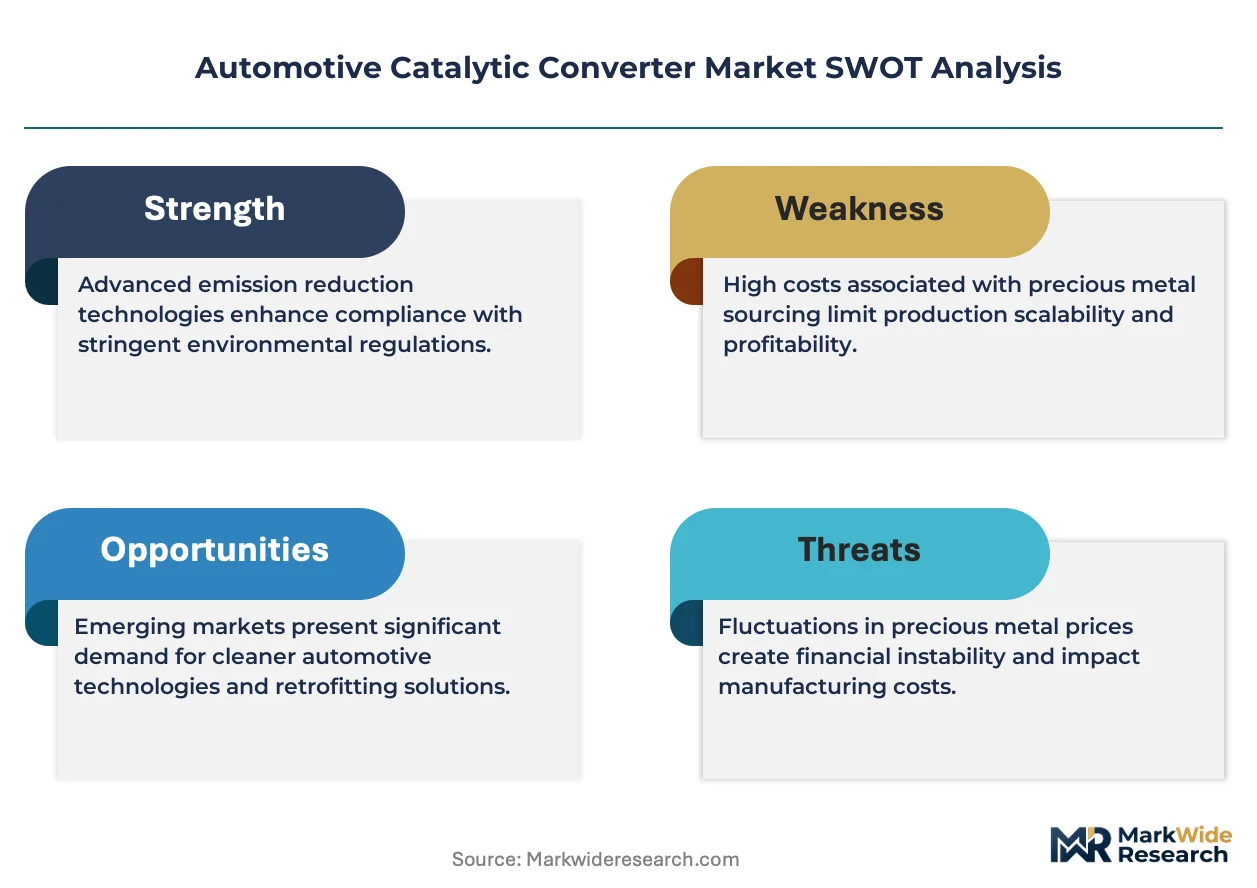
EURO 7 certification is reorganizing supplier eligibility across the Automotive Catalytic Converter Market, forcing substrate and coating investments that only scaled manufacturers can absorb. Faurecia leverages its integrated exhaust-aftertreatment platform to secure multi-year OEM supply agreements. Johnson Matthey anchors its position through captive rare-earth procurement and proprietary catalytic coating chemistry. Tenneco competes via dual-stream production serving both gasoline three-way and diesel oxidation catalyst architectures.
An automotive catalytic converter is an emissions-control device containing ceramic or metallic substrates coated with platinum-group metals that chemically transform toxic exhaust constituents into nitrogen, carbon dioxide, and water vapor through redox reactions at operating temperatures exceeding 300°C. Three-way converters dominate gasoline applications by simultaneously oxidizing hydrocarbons and carbon monoxide while reducing nitrogen oxides in a single catalyst bed. Diesel oxidation catalysts face structural pressure as commercial fleet operators accelerate selective catalytic reduction adoption to meet NOx thresholds without fuel-economy penalties. OEM installation channels capture the majority of value, though aftermarket replacement demand sustains margin pools in regions with aging vehicle parc.
The US EPA tailpipe standards and California Air Resources Board zero-emission vehicle mandates shape product development timelines, while the EU Green Deal and EURO 7 framework force platinum-group metal loading increases that alter cost structures. China's MIIT administers parallel GB VI compliance testing that foreign suppliers must navigate through joint-venture partnerships or wholly-owned local facilities. Stakeholders must monitor how battery-electric vehicle penetration rates in passenger segments redirect catalytic converter R&D spending toward hybrid-optimized architectures and commercial-vehicle durability requirements.
Market Dynamics
The Automotive Catalytic Converter Market is restructuring around platinum-group metal supply security and hybrid powertrain thermal cycling requirements, as OEMs face simultaneous pressure from EURO 7 loading mandates and China GB VI enforcement timelines.
Growth Catalysts
- EURO 7 emission thresholds:The European framework mandates higher precious metal loadings per unit, expanding addressable substrate volume for certified suppliers serving passenger and commercial programs.
- China's Yangtze River Delta automotive cluster:Dense OEM final assembly concentration generates localized demand for three-way catalyst procurement, with domestic coating specialists scaling to serve export-bound vehicle platforms.
- Hybrid thermal management:Start-stop cycling and lower exhaust temperatures in electrified powertrains require reformulated catalyst formulations, opening specification windows for next-generation substrate architectures.
Market Restraints
- Platinum-group metal price volatility:Rhodium and palladium spot markets expose converter manufacturers to input cost swings that contract pass-through clauses only partially offset.
- Substrate supply concentration:Ceramic honeycomb production clusters in Japan and Germany create geographic single-source risk for OEMs qualifying alternative substrate geometries.
- Battery-electric vehicle substitution:Zero-tailpipe platforms eliminate catalytic converter content entirely, compressing long-term demand visibility in passenger segments where electrification accelerates fastest.
Strategic Opportunities
- Commercial vehicle selective catalytic reduction integration:Heavy-duty diesel fleets in India and Brazil present untapped retrofit and OEM-fit demand as national regulators phase in Euro VI-equivalent standards.
- Waste catalyst recycling arbitrage:Closed-loop precious metal recovery from end-of-life units offers margin expansion independent of virgin metal procurement, with regulatory tailwinds from EU Critical Raw Materials Act circularity mandates.
- Gasoline particulate filter convergence:Direct-injection gasoline engines require combined three-way catalyst and particulate filter architectures, consolidating supplier value capture in a single assembly.
Industry Challenges
- EURO 7 certification timeline compression:Validation protocols for new substrate geometries and coating chemistries demand extended test-cell occupancy, straining R&D resource allocation across multiple OEM programs.
- Rare-earth procurement qualification:Cerium and zirconium supply chain due diligence requirements under EU Conflict Minerals Regulation add documentation burden without direct technical benefit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Catalytic Converter Market |
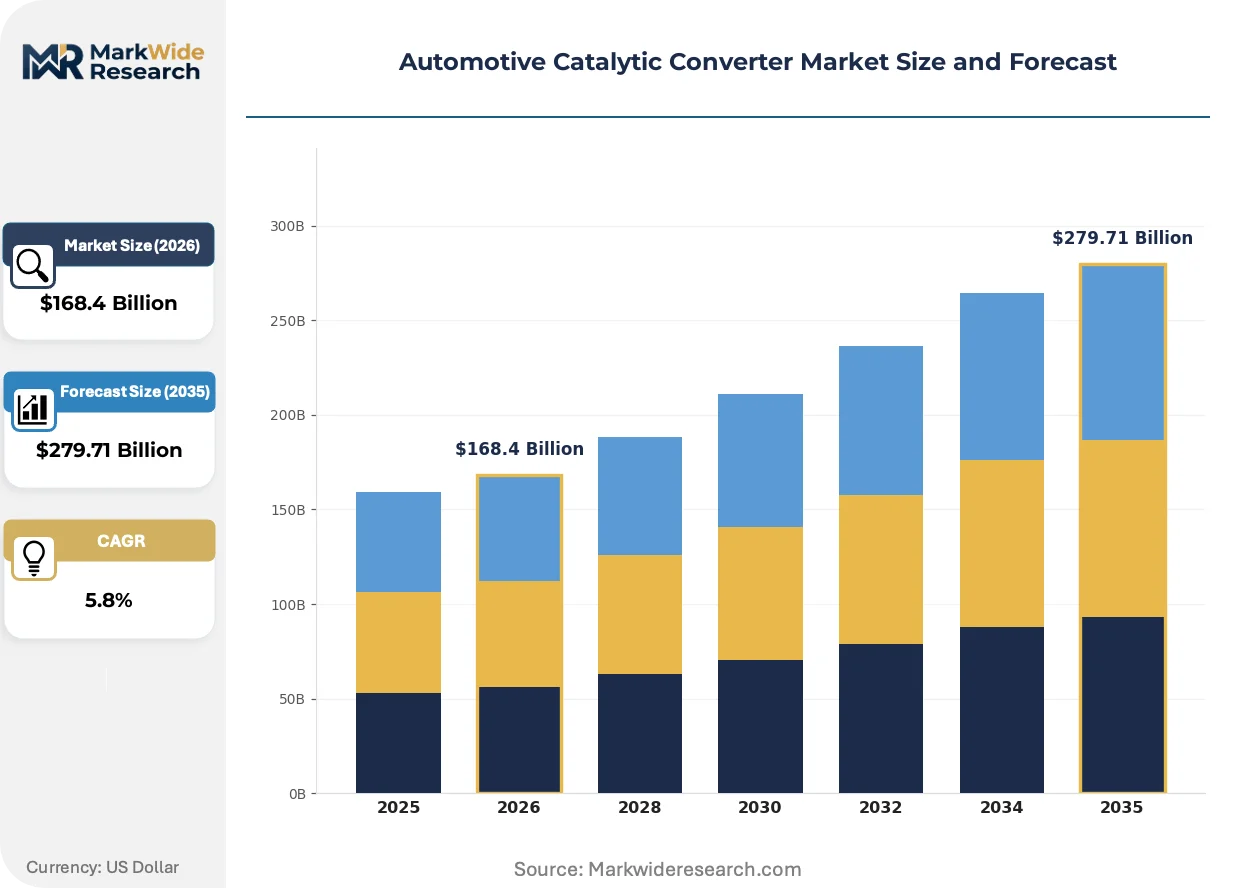
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $279.71 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Way Converters, Three-Way Converters, Diesel Oxidation Catalysts, Selective Catalytic Reduction Systems Technology: Catalytic Coating, Substrate Materials, Filtering Technologies, OBD Systems End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Installation: Original Equipment, Retrofit, Custom Installations, Replacement Parts |
| Companies Covered | Faurecia, Eberspächer, Johnson Matthey, Continental AG, Marelli Holdings, BASF SE, Tenneco, Katcon Global, Umicore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Catalytic Converter Market Strategic Shifts & Innovations
Active research frontiers in the Automotive Catalytic Converter Market center on thermal durability under hybrid duty cycles, regulatory loading mandates, and procurement consolidation among scaled OEM platforms.
Advanced zeolite-based selective catalytic reduction catalysts are decomposing the historical separation between diesel oxidation and SCR functions, enabling single-canister architectures. Commercial fleet operators in North America are adopting these integrated systems to reduce packaging volume and urea dosing complexity. The technology is decomposing aftermarket service margins previously captured by separate component suppliers.
China's MIIT GB VI-b enforcement timeline is accelerating coating chemistry investments among foreign joint-venture suppliers. The regulation's real-driving emissions testing protocol invalidates laboratory-optimized formulations, forcing reformulation for transient temperature performance. Domestic Chinese substrate manufacturers are capturing specification influence previously held by imported ceramic honeycomb suppliers.
Consolidated platform procurement by multinational OEMs is compressing supplier qualification cycles and favoring dual-source contracts over single-source arrangements. Tier 1 exhaust system integrators are absorbing catalyst specification authority previously exercised by OEM engineering departments. This shift is most visible in Germany and Japan, where platform-sharing agreements across brand portfolios concentrate purchasing leverage.
Automotive Catalytic Converter Market Segmentation
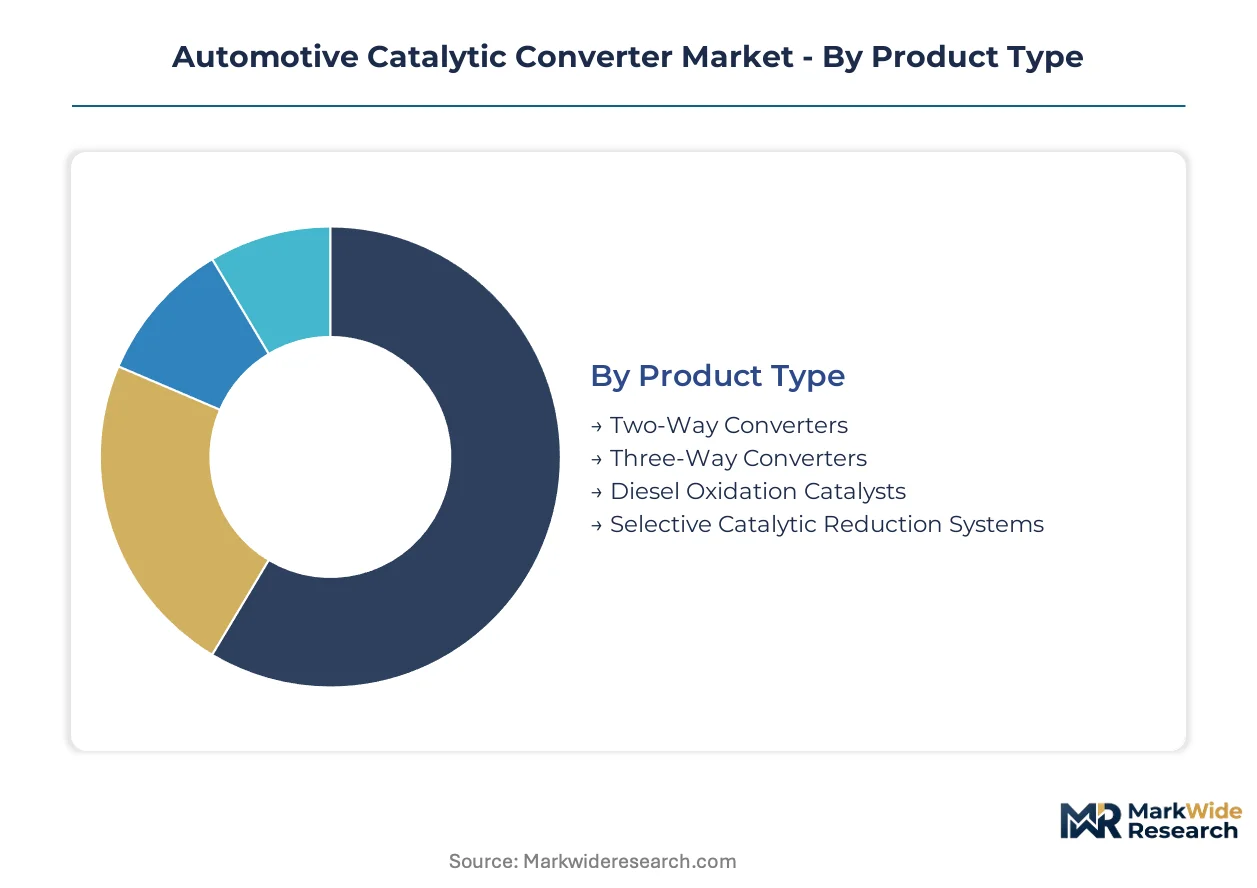
Catalytic converter procurement splits sharply between OEM specification authority and aftermarket margin capture, with technology choices determining platinum-group metal loading economics and thermal durability performance across powertrain architectures.
Product Type:
Margin pools concentrate in three-way and selective catalytic reduction architectures where precious metal loadings and coating complexity sustain pricing power.
- Three-Way Converters:Simultaneous oxidation of hydrocarbons and carbon monoxide with nitrogen oxide reduction in a single catalyst bed dominates gasoline passenger vehicle applications. China's Yangtze River Delta automotive cluster generates concentrated procurement volume as domestic OEMs expand export-bound platform production under MIIT GB VI-b compliance timelines.
- Selective Catalytic Reduction Systems:Urea-based NOx decomposition for diesel applications requires separate dosing hardware and zeolite catalyst formulations. Commercial fleet operators in India and Brazil are accelerating adoption as national regulators phase in Euro VI-equivalent standards, creating retrofit demand independent of new vehicle sales cycles.
- Two-Way Converters:Oxidation-only architectures for lean-burn gasoline and early diesel applications retain niche presence in legacy fleet service.
- Diesel Oxidation Catalysts:Platinum-catalyzed carbon monoxide and hydrocarbon conversion faces displacement pressure from integrated SCR-SCRF combinations in heavy-duty segments.
The dominant share belongs to three-way converters, while selective catalytic reduction systems are closing the gap fastest.
Technology:
Substrate material selection and coating chemistry differentiation determine thermal cycling survival and regulatory certification outcomes.
- Substrate Materials:Cordierite ceramic honeycomb structures from Japanese and German production clusters provide the dominant architecture, with metallic foil alternatives gaining specification in high-performance and commercial vehicle applications requiring improved thermal shock resistance.
- Catalytic Coating:Washcoat formulations incorporating platinum, palladium, and rhodium with cerium-zirconium oxygen storage components command the highest value-add per unit volume. EURO 7 loading mandates are forcing reformulation investments that only scaled coating specialists can absorb.
- Filtering Technologies:Gasoline particulate filter integration with three-way catalyst substrates consolidates functionality for direct-injection engines.
- OBD Systems:On-board diagnostic sensors and software for catalyst efficiency monitoring add electronic content to mechanical assemblies.
Substrate materials capture the largest technology share, though catalytic coating is expanding most quickly as loading requirements intensify.
End User:
OEM procurement concentration versus aftermarket fragmentation shapes pricing discipline and contract structure across the value chain.
- OEMs:Platform-sharing agreements across multinational brand portfolios concentrate purchasing leverage in Germany and Japan, with tier 1 exhaust integrators absorbing catalyst specification authority previously held by OEM engineering departments.
- Fleet Operators:Commercial vehicle procurement in North America and Europe favors integrated SCR systems with urea dosing service contracts over component-level sourcing.
- Aftermarket Providers:Aging vehicle parc in regions with extended fleet lifecycles sustains replacement demand for pre-certified converter assemblies.
- Vehicle Assemblers:Contract manufacturing arrangements for emerging market production transfer procurement responsibility to local joint-venture partners.
OEMs retain the dominant procurement share, while fleet operators are gaining specification influence fastest through integrated service contracting.
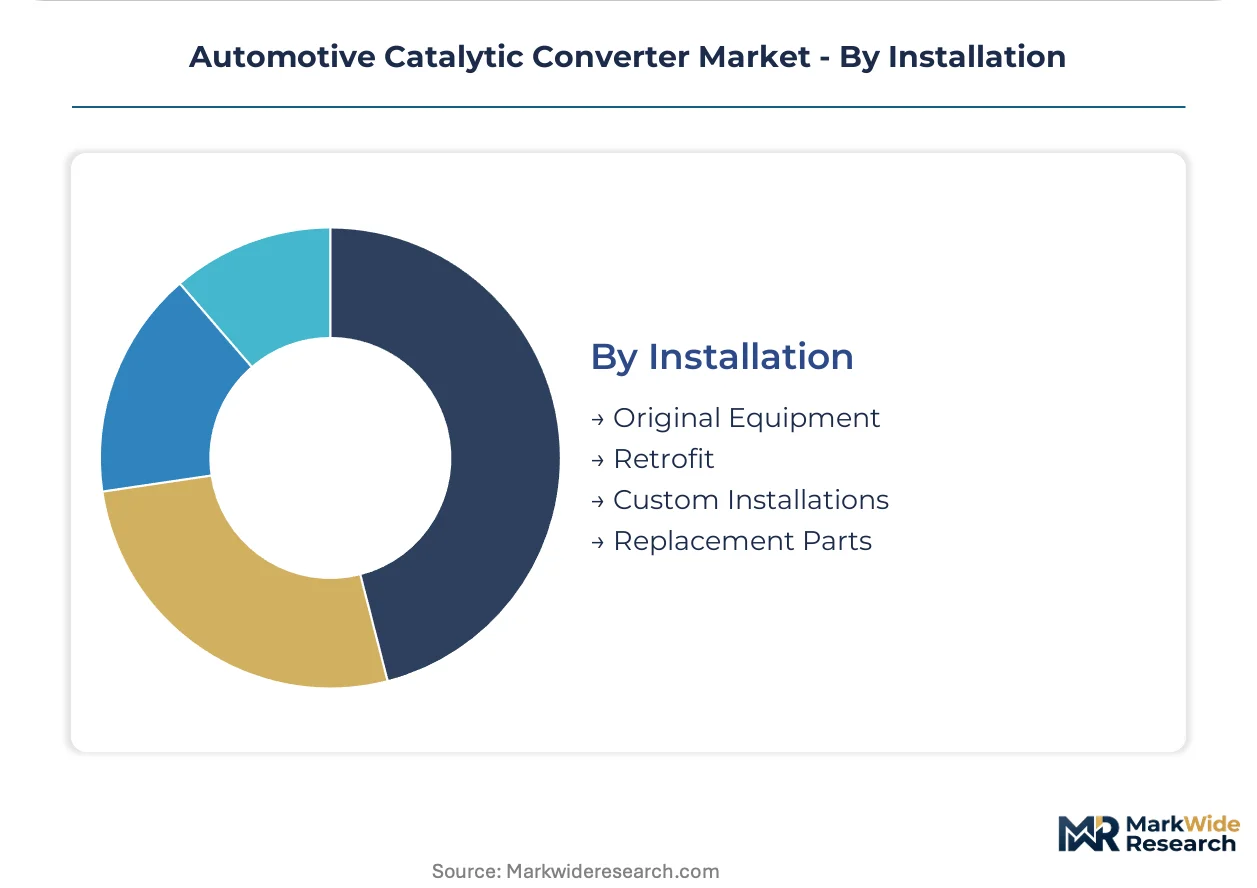
Installation:
Original equipment fitment versus retrofit and replacement demand divides margin stability from price volatility exposure.
- Original Equipment:Factory-integrated converter assemblies validated to full vehicle durability requirements capture the majority of lifetime value, with multi-year supply agreements locking in substrate and coating sourcing.
- Replacement Parts:Aftermarket demand concentrates in jurisdictions with mandatory periodic emissions testing, where pre-certified assemblies compete on price against refurbished units.
- Retrofit:Heavy-duty diesel fleet upgrades in India and Brazil present project-based procurement with irregular volume timing.
- Custom Installations:Performance and specialty vehicle applications require non-standard substrate geometries with limited supplier qualification.
Original equipment commands the dominant installation share, while replacement parts are climbing the fastest as regulatory testing expands geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta port cluster underwrites China's dominance in automotive catalytic converter procurement, while the Rhine-Ruhr corridor and Detroit-Windsor automotive corridor anchor European and North American supply security respectively.
China
Domestic OEMs in the Yangtze River Delta cluster are expanding three-way catalyst procurement for export-bound platforms. MIIT's GB VI-b real-driving emissions testing invalidates laboratory-optimized formulations, forcing coating reformulation investments. Shanghai and Jiangsu Province substrate manufacturers are capturing specification influence from imported ceramic honeycomb suppliers.
Germany
Platform-sharing agreements across Volkswagen Group, BMW, and Mercedes-Benz portfolios concentrate purchasing leverage in exhaust system procurement. EURO 7 certification timelines strain R&D resource allocation across multiple OEM validation programs. The Rhine-Ruhr industrial corridor hosts scaled coating specialists absorbing precious metal loading mandate costs.
United States
Commercial fleet operators in the Midwest and Southeast are adopting integrated selective catalytic reduction systems to reduce packaging volume. EPA tailpipe standards and California Air Resources Board zero-emission mandates shape product development timelines. The Detroit-Windsor automotive corridor maintains OEM specification authority over catalyst architecture decisions.
Japan
Cordierite ceramic honeycomb production clusters in Nagoya and Osaka create geographic supply concentration for substrate architectures. METI industrial policy supports domestic coating chemistry investments for hybrid powertrain thermal cycling requirements. Kanto region OEMs are consolidating platform procurement to compress supplier qualification cycles.
India
Heavy-duty diesel fleet operators in Maharashtra and Gujarat present untapped retrofit demand as national regulators phase in Euro VI-equivalent standards. BIS certification requirements for catalytic converter assemblies create entry barriers for unqualified suppliers. The Chennai-Bangalore automotive corridor is scaling domestic coating capacity to serve commercial vehicle programs.
Automotive Catalytic Converter Market Key Industry Players
Listed leaders compete with private specialists across precious metal procurement and coating chemistry scale. The vendor base splits between integrated exhaust-aftertreatment platforms and focused substrate-coating specialists. Three archetypes dominate: rare-earth captive integrators, dual-stream gasoline-diesel producers, and commercial vehicle SCR specialists. M&A activity concentrates on coating technology acquisitions, while capacity expansion targets China GB VI compliance capacity.
Within the integrated platform tier, Faurecia and Tenneco occupy positions spanning OEM specification authority. Johnson Matthey anchors the precious metal chemistry specialist segment. Continental AG and Marelli Holdings represent European and Italian-Japanese exhaust system integration archetypes respectively. Eberspächer exemplifies the private specialist model with focused thermal management expertise.
| Leading Market Players |
|---|
| Faurecia |
| Eberspächer |
| Johnson Matthey |
| Continental AG |
| Marelli Holdings |
| BASF SE |
| Tenneco |
| Katcon Global |
| Umicore |
| Others |
Cost & Logistics Intelligence
Ninety-day platinum-group metal inventory buffers at converter manufacturers now determine pricing leverage across the value chain, with OEMs absorbing coating cost pass-throughs while aftermarket distributors face spot-price volatility on replacement assemblies. This lead-time asymmetry between contract-covered OEM supply and spot-market aftermarket procurement concentrates margin protection with scaled integrators serving multi-year platform agreements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EURO 7-certified OEM assemblies from pre-certified aftermarket units and unbranded economy replacements. Price differentiation hinges on precious metal loading grades and MIIT GB VI-b certification status, with OEM channels commanding premiums for validated thermal cycling performance. Cost compression in the aftermarket tier is intensifying because spot rhodium and palladium exposure erodes distributor margins when contract pass-through clauses lag metal price swings. Fleet operators show least price sensitivity due to integrated SCR service contracting, while independent repair shops in aging-vehicle markets exhibit highest sensitivity to per-unit converter costs.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes now inflate inbound logistics costs for ceramic honeycomb substrates sourced from Japanese and German production clusters. Geographic supply concentration centers on Japan, Germany, and China, with cordierite ceramic honeycomb drawing from Nagoya and Osaka facilities while coating chemistry rests on rare-earth processing in Jiangsu Province. Raw material dependencies include platinum-group metals from South African and Russian mining operations, cerium-zirconium oxygen storage components, and specialized zeolite formulations. Single-source vulnerability persists in ceramic substrate architectures qualified to specific OEM thermal shock specifications. Distribution runs through Tier 1 exhaust system integrators who consolidate catalyst specification authority previously held by OEM engineering departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as consolidated OEM procurement and shared exhaust-aftertreatment architectures force supplier interoperability across brand portfolios, with tier 1 integrators absorbing specification authority previously decentralized to individual OEM engineering departments.
For Market Incumbents: Shield market position through captive rare-earth procurement agreements and backward integration into coating chemistry production, countering margin pressure from platinum-group metal spot volatility. Prioritize certification investment for hybrid-optimized substrate architectures as battery-electric substitution threatens gasoline passenger volume. Defend OEM channel control by locking multi-year platform agreements before EURO 7 timeline compression strains competitor R&D resources. For New Entrants and Emerging Players: Differentiate on waste catalyst recycling arbitrage, capturing closed-loop precious metal recovery margins independent of virgin metal procurement cost swings. Target commercial vehicle SCR retrofit demand in India and Brazil as national regulators phase in Euro VI-equivalent standards, presenting white-space opportunity outside incumbent OEM supply relationships. Pursue fleet operator direct contracting with integrated urea dosing service agreements rather than component-level distribution. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across EURO 7 coating chemistry investments, favoring scaled specialists over fragmented substrate producers. Long-term viability over the coming decade rests on hybrid powertrain thermal cycling expertise and circular economy positioning under EU Critical Raw Materials Act mandates. Monitor battery-electric vehicle penetration rates in passenger segments as the critical signal for catalytic converter demand trajectory compression versus commercial-vehicle durability requirement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Chemistry Scale-Up | EURO 7 loading mandates force precious metal formulation investments that only scaled manufacturers absorb. |
| Waste Catalyst Recovery Integration | Closed-loop arbitrage from end-of-life units offers margin expansion independent of virgin metal procurement. |
| Hybrid-Optimized Substrate Development | Start-stop cycling and lower exhaust temperatures in electrified powertrains require reformulated architectures. |
| Commercial Vehicle SCR Service Contracting | Fleet operators in India and Brazil favor integrated urea dosing agreements over component sourcing. |
| Joint Venture Localization in China | MIIT GB VI-b compliance requires foreign suppliers to navigate real-driving emissions testing through local partnerships. |
Research Approach
A spread of perspectives from OEM platform engineers, Tier 1 exhaust system procurement leads, aftermarket distributor operations managers, and coating chemistry R&D directors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, customs trade flows for platinum-group metals, and SEC filings from listed coating specialists. Bottom-up triangulation across substrate volume estimates and top-down reconciliation with OEM platform production schedules anchored the forecasting framework.
Segmentation dimensions modeled span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster across the analysis window. CAGRs were derived from slope analysis of historical procurement patterns projected against regulatory enforcement timelines. Industry-specific forecast inputs include MIIT GB VI-b phase-in schedules, EURO 7 certification protocol requirements, and commercial fleet SCR adoption curves in emerging markets.
The analysis sits within stated boundaries; outcomes outside sustained hybrid powertrain penetration, stable platinum-group metal supply, or accelerated battery-electric substitution would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement timing and OEM platform-sharing continuity. Specific risk factors that could revise projections include rhodium supply disruption from South African mining operations, faster-than-anticipated passenger vehicle electrification, or delayed Euro VI-equivalent enforcement in India and Brazil. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Clutch Disc Market
Automotive Components
Automotive Brake Tube Market
Automotive Components
Global Automotive Plastic Compounding Market
Automotive Components
Automotive Active Seat Headrests Market
Automotive Components
Automotive Push Rods Market
Automotive Components
Global Automotive Window Regulator Market
Automotive Components
Automotive Gear Shifter Market
Automotive Components
Automotive Air Intake Manifold Market
Automotive Components
Automotive Plastic Components Market
Automotive Components
Asia-Pacific Automotive Upholstery Market
Automotive Components
Torque Vectoring Market
Automotive Components
Automotive HVAC Ducts Market
Automotive Components
Automotive Tie Rod Market
Automotive Components
Europe Automotive Heat Exchanger Market
Automotive Components
Automotive Camshaft Phase Variator Market
Automotive Components
North America Heat Shrink Tubing for Automotive Market