
 Global Automotive Thermal Management Market | 2026-2036
Global Automotive Thermal Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Thermal Management Market Analysis
Modular packaging of battery thermal management with cabin HVAC systems is rebalancing buyer choice toward integrated subsystem procurement. DENSO Corporation leverages its vertical integration across compressor and heat pump production to anchor contracts with Japanese and European OEMs. Valeo SA competes through specialized electric compressor lines that dominate European EV platforms. Mahle GmbH sustains R&D intensity in thermal insulation materials, positioning its portfolio for next-generation solid-state battery architectures.
Automotive thermal management encompasses the engineered control of heat transfer across powertrain, cabin, and energy storage systems through heat exchangers, coolant loops, refrigerant circuits, and phase-change materials operating within defined temperature bands. Cooling systems and battery thermal management now command the fastest expansion as electric vehicle architectures replace conventional engine cooling demand with multi-loop thermal circuits for cells, inverters, and motors. Liquid cooling technology leads in value contribution due to its heat flux capacity, while passive thermal management retains cost-driven share in entry battery packs where energy density thresholds remain lower.
EPA tailpipe standards, the EU F-Gas Regulation, and China's MIIT dual carbon goals collectively mandate refrigerant phase-downs and energy efficiency gains that reshape product specifications and supplier qualification criteria. The EU AI Act and CE marking requirements add compliance layers for predictive thermal control software embedded in smart HVAC units. Stakeholders must monitor how refrigerant chemistry transitions and battery format standardization alter component interoperability and aftermarket service economics.
Market Dynamics
The transition from internal combustion engines to multi-loop electric architectures is compressing thermal management into unified battery-cabin-motor systems, forcing suppliers to abandon discrete component sales in favor of integrated subsystem contracts.
Growth Catalysts
- EPA tailpipe standards:The US Environmental Protection Agency's tightening emission thresholds compel OEMs to deploy heat pump HVAC systems, expanding the addressable market for integrated thermal modules.
- China's MIIT dual carbon goals:Beijing's manufacturing mandates accelerate domestic EV production scale, concentrating demand for liquid-cooled battery packs among cell manufacturers.
- Refrigerant chemistry transitions:The EU F-Gas Regulation's phase-down schedule for high-GWP refrigerants drives replacement cycles across European vehicle fleets, upgrading compressor specifications.
Market Restraints
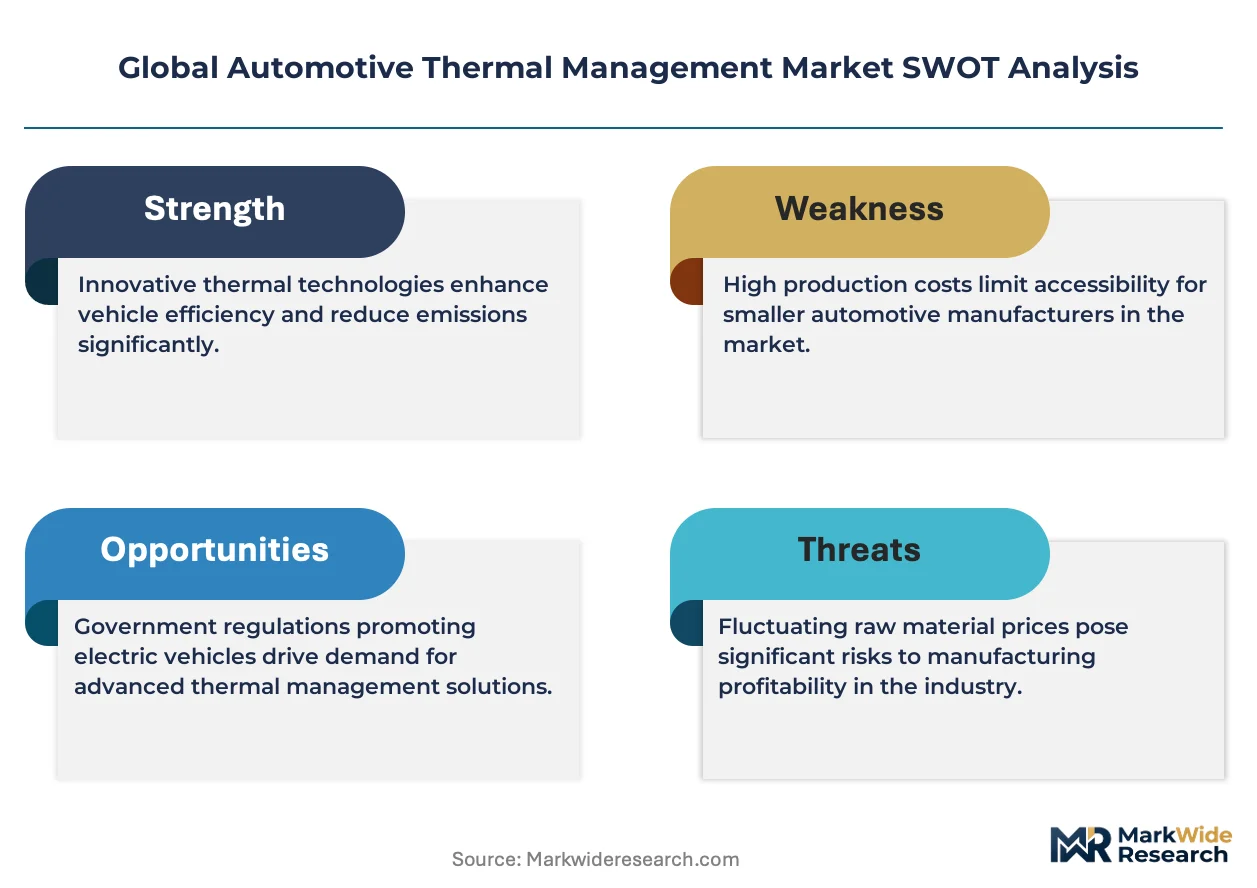
- Copper and aluminum price volatility:Raw material input swings compress margin predictability for heat exchanger fabricators locked into annual OEM supply agreements.
- Compressor supply concentration:Production of high-voltage electric compressors clusters among Japanese and German component specialists, creating single-source vulnerability for second-tier assemblers.
- Refrigerant interoperability limits:Divergent chemistries approved under EPA SNAP rules versus EU F-Gas classifications force dual-SKU inventory strategies, raising working capital requirements.
Strategic Opportunities
- India's PLI scheme for auto components:Production-linked incentives attract thermal module assembly capacity to serve domestic EV programs and export markets.
- Solid-state battery thermal interfaces:Next-generation cell architectures demand novel phase-change materials and dielectric coolants, opening white space beyond incumbent liquid-loop designs.
- Subscription-based thermal system monitoring:Predictive maintenance software bundled with HVAC hardware creates recurring revenue streams for tier-one suppliers.
Industry Challenges
- Systems integration engineering talent:The scarcity of engineers fluent in both refrigerant thermodynamics and battery electrochemistry delays program timelines for integrated thermal modules.
- CE marking under EU AI Act:Smart HVAC units with embedded predictive controls face expanded conformity assessment documentation, extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Thermal Management Market |
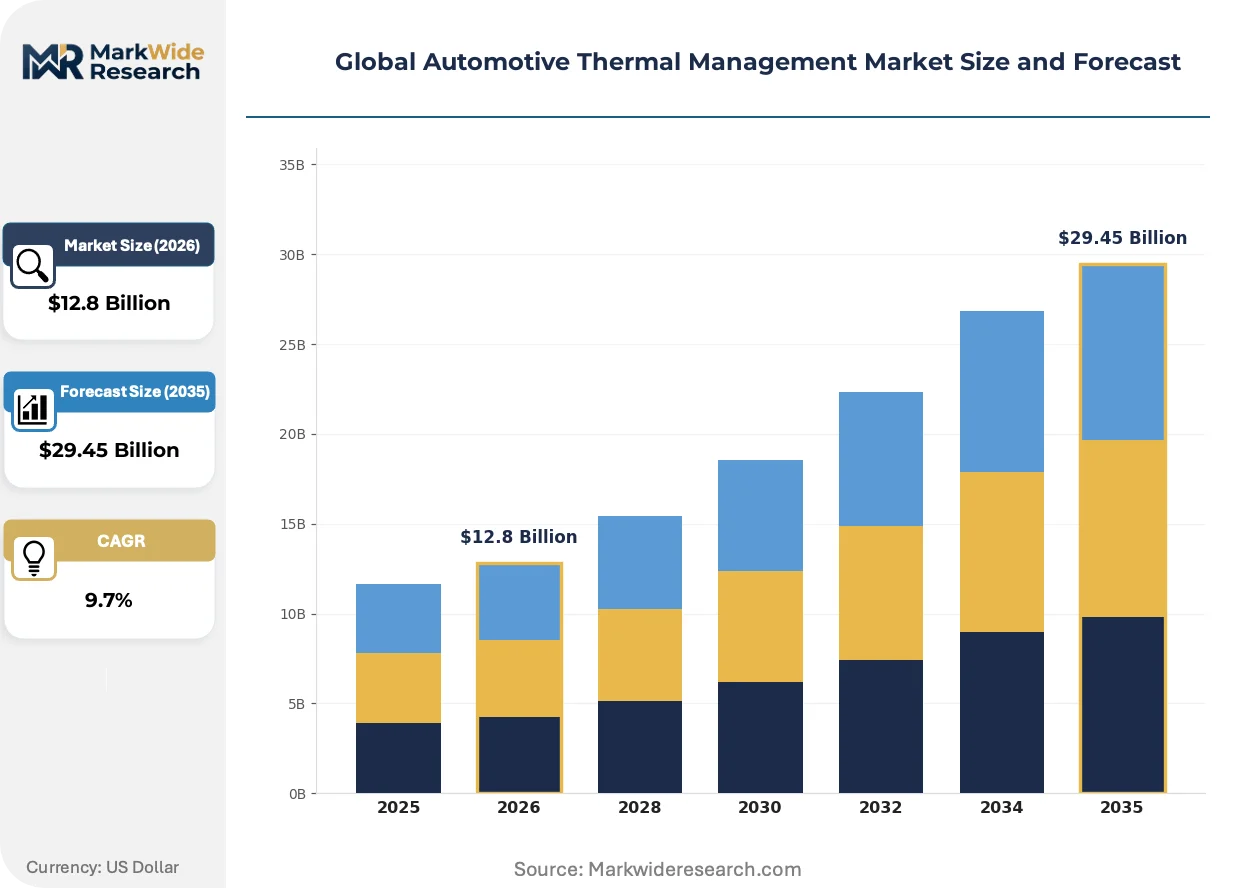
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $29.45 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heating Systems, Cooling Systems, Heat Exchangers, Thermal Insulation Technology: Passive Thermal Management, Active Thermal Management, Phase Change Materials, Liquid Cooling Application: HVAC, Engine Cooling, Battery Thermal Management, Exhaust Management End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Independent Workshops |
| Companies Covered | DENSO Corporation, Valeo SA, Mahle GmbH, Robert Bosch GmbH, BorgWarner Inc., Hanon Systems, Gentherm Incorporated, Continental AG, Dana Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Thermal Management Market Emerging Trajectories
Refrigerant circuit architectures and control software are converging to enable single-loop systems that service both cabin climate and battery conditioning, collapsing the traditional separation between HVAC and powertrain cooling.
Heat pump systems with integrated battery warming circuits are modularizing thermal management from three discrete subsystems into unified packages. Premium EV platforms in Germany and South Korea are adopting these configurations first. This consolidation is modularizing supplier relationships, compressing the vendor base from multiple single-component specialists to integrated module providers.
The EU F-Gas Regulation's 2024-2030 phase-down schedule for hydrofluorocarbon refrigerants is forcing chemistry transitions toward CO2 and HFO blends. Compressor manufacturers must redesign sealing and lubrication systems to accommodate new pressure and miscibility profiles. European EV platforms face the steepest retooling burden, with Swedish and German OEMs accelerating qualification timelines for alternative refrigerant architectures.
Fleet operators and ride-hail platforms are consolidating thermal system procurement at the vehicle-platform level rather than delegating to individual vehicle purchasers. This concentration shifts bargaining power toward high-volume buyers in China and the United States. Tier-one suppliers respond by offering performance-guaranteed service contracts that bundle hardware, installation, and predictive maintenance.
Global Automotive Thermal Management Market Segmentation
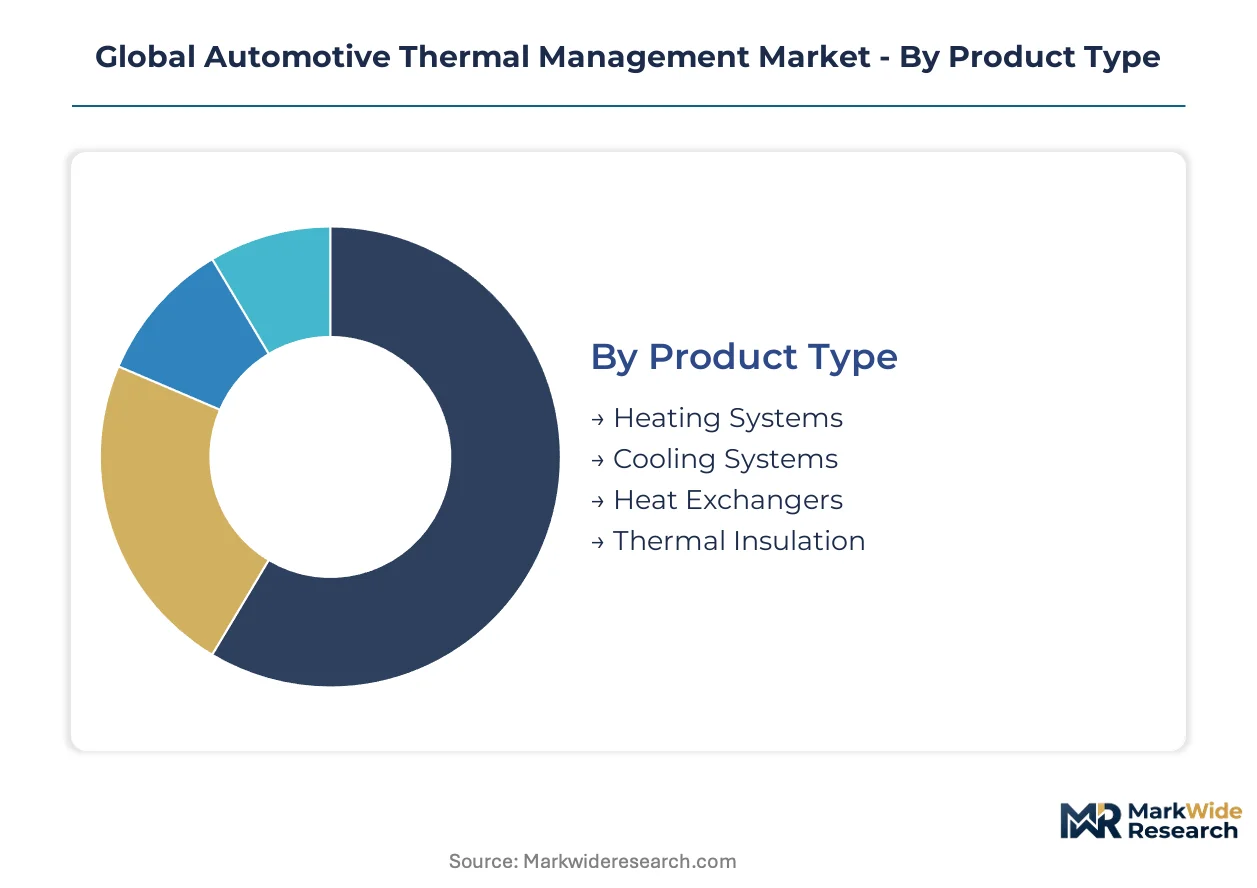
Segmentation in automotive thermal management reveals how buyer priorities diverge between integrated subsystem procurement and discrete component sourcing. Electric vehicle architectures collapse traditional boundaries between cabin climate, battery conditioning, and powertrain cooling, reshaping which segments capture value.
Product Type:
Buyers weigh thermal flux capacity against packaging constraints when selecting hardware categories.
- Cooling Systems:Multi-loop liquid circuits for battery cells, inverters, and electric motors dominate EV architectures. German and South Korean OEMs specify these as integrated modules rather than discrete radiators, compressing vendor counts.
- Heat Exchangers:Aluminum-brazed plate-and-fin designs handle refrigerant-to-coolant energy transfer in heat pump HVAC systems. China's MIIT efficiency mandates accelerate demand for compact, high-density configurations in domestic EV platforms.
- Heating Systems:High-voltage PTC heaters and heat pump compressors replace engine-sourced cabin warmth.
- Thermal Insulation:Aerogel and microporous materials manage cell-to-cell heat propagation in battery packs.
Volume sits with Heat Exchangers; growth tilts toward Cooling Systems.
Technology:
Cost tier determines technology selection, with premium EV platforms absorbing advanced active systems while entry segments retain passive approaches.
- Liquid Cooling:Ethylene-glycol and dielectric fluid loops achieve heat flux densities exceeding 50 W/cm² for fast-charging battery architectures. US EPA tailpipe standards indirectly mandate these systems by requiring heat pump HVAC integration that shares coolant infrastructure.
- Active Thermal Management:Electric pumps, valves, and controllers enable real-time thermal routing across battery, cabin, and motor loops. European OEMs under EU F-Gas Regulation timelines specify these for refrigerant circuit optimization.
- Passive Thermal Management:Heat sinks and natural convection suffice for low-energy-density battery packs.
- Phase Change Materials:Paraffin and salt-hydrate composites buffer thermal spikes during rapid discharge.
Passive Thermal Management retains volume in cost-sensitive segments; Liquid Cooling commands the steepest expansion trajectory.
Application:
Application selection tracks powertrain electrification depth, with battery-centric systems displacing engine cooling in procurement priority.
- Battery Thermal Management:Cell-level conditioning maintains 15-35°C operating windows for lithium-ion and emerging solid-state chemistries. China's CATL and BYD cell manufacturing scale concentrates demand for liquid-cooled pack architectures.
- HVAC:Heat pump systems with integrated battery warming circuits merge cabin and energy storage thermal control. Swedish and German OEMs lead platform-level adoption driven by EU F-Gas refrigerant phase-down requirements.
- Engine Cooling:Radiator and thermostat demand contracts as ICE production volumes decline.
- Exhaust Management:EGR coolers and catalytic converter thermal protection persist in hybrid applications.
Engine Cooling still holds installed base volume; Battery Thermal Management is climbing the fastest.
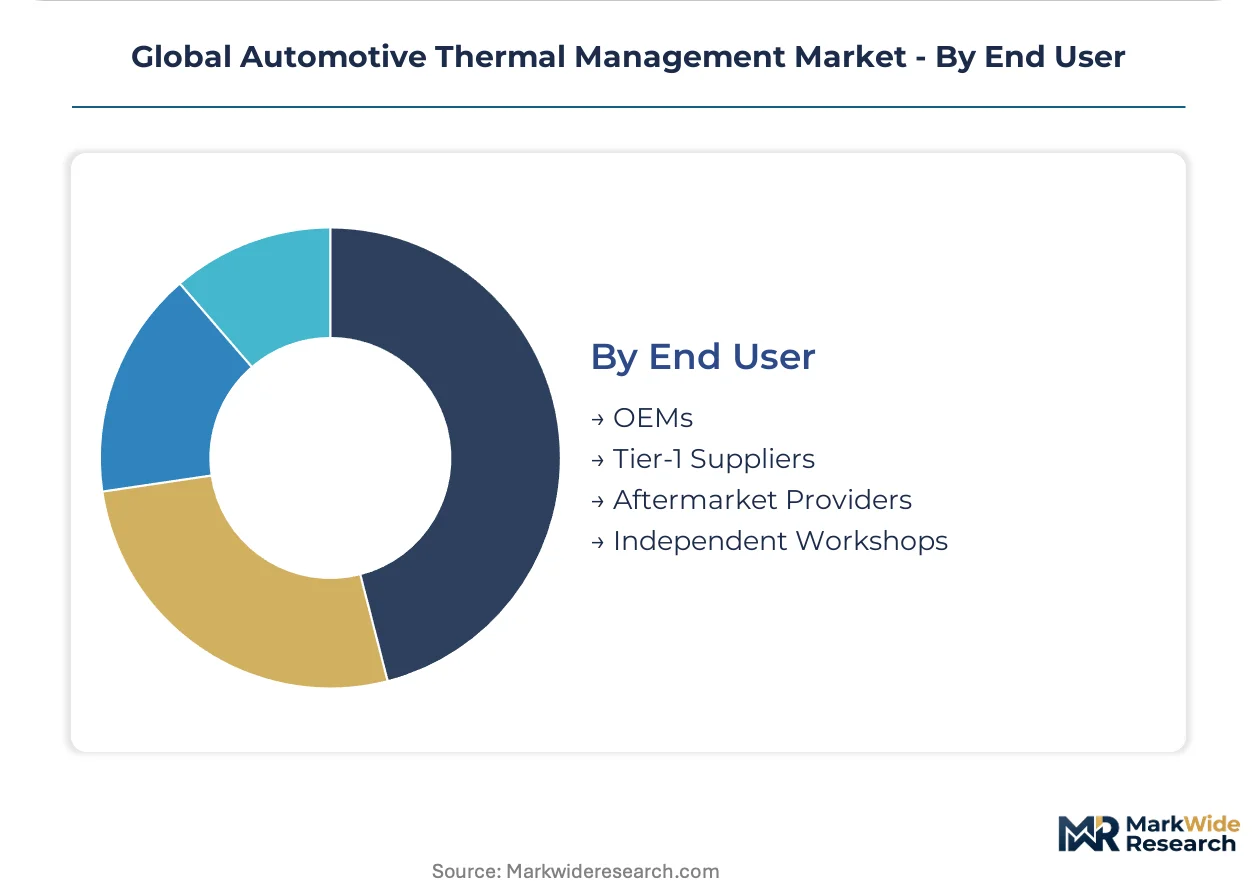
End User:
Procurement concentration favors direct OEM and Tier-1 relationships as thermal systems modularize into single-source contracts.
- OEMs:Volkswagen, Toyota, and Tesla specify complete thermal modules at platform development stage, bypassing component-level sourcing. Direct contracts with DENSO, Valeo, and Mahle lock in multi-year supply for integrated battery-HVAC systems.
- Tier-1 Suppliers:Bosch, Denso, and Hanon Systems aggregate compressors, heat exchangers, and control software into subsystem packages for OEM assembly lines.
- Aftermarket Providers:Refrigerant recharge and compressor replacement services address legacy fleet maintenance.
- Independent Workshops:Diagnostic and repair capabilities concentrate in established automotive service networks.
Aftermarket Providers capture legacy service volume; OEMs concentrate the fastest-growing procurement segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of battery thermal management hardware while Germany and the United States absorb premium integrated modules for domestic EV assembly. This production-consumption divide shapes supplier location strategies and trade flow patterns across the forecast window.
China
CATL and BYD cell manufacturing scale concentrates demand for liquid-cooled pack architectures in Fujian and Guangdong provinces. MIIT dual carbon goals mandate energy efficiency thresholds that accelerate domestic heat pump HVAC adoption. Shanghai-based thermal module suppliers are expanding capacity to serve both local OEMs and export markets.
Germany
Volkswagen, BMW, and Mercedes-Benz platform development programs specify complete battery-HVAC integrated systems at contract signing. EU F-Gas Regulation refrigerant phase-down timelines compress supplier qualification cycles for alternative chemistries. Stuttgart and Munich industrial clusters host development centers for CO2 compressor architectures.
United States
Tesla, Ford, and GM vertical integration strategies concentrate procurement decisions in California, Michigan, and Texas manufacturing corridors. EPA tailpipe standards indirectly mandate heat pump HVAC deployment through efficiency compliance pathways. Detroit-area suppliers are retooling radiator capacity toward battery cooling loop fabrication.
Japan
Toyota and Honda hybrid platform persistence sustains demand for dual-purpose engine-battery thermal systems in Aichi and Kanagawa prefectures. METI efficiency standards push refrigerant circuit optimization investments. Nagoya-based compressor specialists anchor regional supply chains for Asian OEM export programs.
South Korea
Hyundai and Kia EV platform rollouts concentrate battery thermal management procurement in Seoul Capital Area engineering centers. KBA-aligned efficiency benchmarks shape heat pump specification requirements. Busan-Ulsan manufacturing complexes are adding capacity for integrated thermal module assembly.
Global Automotive Thermal Management Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across contract tiers, creating a bifurcated structure where scale advantages clash with agility premiums. Tier-one automotive suppliers with multi-product portfolios anchor OEM relationships through bundled subsystem offerings. Three archetypes dominate: integrated module providers, component specialists, and materials innovators. Consolidation pressure operates through strategic partnerships for refrigerant circuit co-development and capacity joint ventures for electric compressor manufacturing.
Among Japanese and German integrated module providers, DENSO Corporation and Robert Bosch GmbH occupy positions exemplifying vertical scope across compressor and control system production. Valeo SA represents the European specialist archetype with concentrated electric compressor expertise. These three entities anchor competitive dynamics as OEMs consolidate vendor bases from discrete component sourcing toward single-source thermal module contracts.
| Leading Market Players |
|---|
| DENSO Corporation |
| Valeo SA |
| Mahle GmbH |
| Robert Bosch GmbH |
| BorgWarner Inc. |
| Hanon Systems |
| Gentherm Incorporated |
| Continental AG |
| Dana Incorporated |
| Others |
Supply Flow & Price Mechanics
OEM consolidation toward integrated battery-HVAC module procurement is compressing vendor counts and shifting bargaining power to high-volume buyers in China and Germany, forcing component suppliers to absorb raw material volatility through longer-term contract structures.
Pricing Analysis
Margin tightening in electric compressor tiers reflects copper and aluminum price volatility locked into annual OEM supply agreements. Three-tier pricing structure across premium, standard, and economy levels separates heat pump-integrated modules from discrete cooling loops and passive thermal management kits. Cost-down pressure on heat exchanger fabricators accelerates because buyers demand performance-guaranteed service contracts bundling hardware, installation, and predictive maintenance. Fleet operators and ride-hail platforms in the United States exhibit the highest price sensitivity through consolidated platform-level procurement, while German premium OEMs absorb premium pricing for CO2 compressor architectures.
Supply Chain Analysis
High-voltage electric compressor production rests on Japanese and German component specialists, creating single-source vulnerability for second-tier assemblers. Aluminum-brazed plate-and-fin heat exchanger fabrication draws from Chinese, German, and South Korean manufacturing bases. Raw material inputs hinge on copper cathode supply from Chile and Indonesia, aluminum sheet from China and Russia, and refrigerant precursors from Chinese chemical producers. Tariff exposure on aluminum imports into the United States and European Union threatens margin stability for radiator fabricators. Distribution runs through Tier-1 subsystem packagers who aggregate compressors, heat exchangers, and control software for direct OEM assembly line delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric compressor manufacturing capacity constraints in Japan and Germany are propping pricing power for integrated module providers, creating a supply-constrained market structure favoring incumbents with captive production.
For Market Incumbents: Acquire refrigerant circuit co-development partnerships and electric compressor manufacturing joint ventures to defend against emerging Chinese module suppliers. Backward integration into aluminum-brazed heat exchanger fabrication secures margin control against raw material volatility. Lock multi-year platform contracts with Volkswagen, Toyota, and Tesla before qualification cycles for EU F-Gas alternative chemistries conclude. For New Entrants and Emerging Players: India's PLI scheme for auto components opens a window for thermal module assembly capacity serving domestic EV programs and export markets. Target aftermarket predictive maintenance software bundled with HVAC hardware, where recurring revenue streams remain underpenetrated by incumbent hardware specialists. Pursue solid-state battery thermal interface development as a differentiated entry point beyond incumbent liquid-loop designs. For Investors and Strategic Acquirers: The window for entry favors materials innovators with phase-change material and dielectric coolant intellectual property. Five-to-ten year viability hinges on positioning for next-generation solid-state battery architectures before cell format standardization locks in incumbent relationships. Watch refrigerant chemistry qualification timelines under EPA SNAP rules versus EU F-Gas classifications as the inflection signal for dual-SKU inventory working capital requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Circuit Co-Development Partnership | Accelerates qualification timelines for CO2 and HFO blend compressor architectures under EU F-Gas Regulation. |
| Electric Compressor Manufacturing Joint Venture | Addresses single-source vulnerability by diversifying high-voltage compressor production beyond Japanese and German clusters. |
| Solid-State Battery Thermal Interface R&D | Positions portfolio for next-generation cell architectures requiring novel phase-change materials and dielectric coolants. |
| Predictive Maintenance Software Launch | Creates recurring revenue streams through subscription-based thermal system monitoring bundled with HVAC hardware. |
| India PLI Scheme Manufacturing Footprint | Captures production-linked incentives for thermal module assembly serving domestic EV programs and export markets. |
Methodological Framework
Independent corroboration across OEM platform engineering directors, Tier-1 supplier procurement leads, and aftermarket distributor operations underwrites the qualitative findings in this study. Primary interviews with thermal management R&D heads, refrigerant chemistry specialists, and battery pack engineering teams combined with secondary validation from vehicle production databases, IHS Markit registration data, EPA SNAP rule filings, and EU F-Gas Regulation implementation documents. Bottom-up segmentation modeling and top-down market sizing triangulate volume and value estimates.
Rate-of-change decomposition across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster structures the analytical framework. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs include MIIT dual carbon goal implementation timelines, EPA tailpipe standard compliance pathways, and battery format standardization trajectories.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for liquid cooling versus passive thermal management demand splits. Forecasts reflect assumptions regarding refrigerant chemistry transition schedules and copper-aluminum price stabilization. Regulatory acceleration or delay in EPA, EU F-Gas, and MIIT timelines, alongside breakthroughs in phase-change material performance, constitute the small set of triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Intelligent Torque Controlled Coupling (ITCC) Market
Automotive Components
Australia Automotive Glass Fiber Composites Market
Automotive Components
Automotive Active Seat Headrests Market
Automotive Components
France Automotive Electric Actuators Market
Automotive Components
Automotive Active Grille Shutter Actuator Gear Market
Automotive Components
India Passenger Vehicles Lubricants Market
Automotive Components
Global Automotive Mats Market
Automotive Components
Italy Automotive Actuators Market
Automotive Components
Automotive Aftermarket for Brake Components Market
Automotive Components
Automotive Stamped Component Market
Automotive Components
Global Automotive Condenser Market
Automotive Components
Sheet Molding Compound (SMC) for Automotive Market
Automotive Components
Latin America Automotive Electric Actuators Market
Automotive Components
Automotive Commutator Market
Automotive Components
Japan Automotive Actuators Market
Automotive Components
Germany Automotive Carbon Fiber Composites Market