
 Molecular Beam Epitaxy System Market | 2026-2036
Molecular Beam Epitaxy System Market Size, Share, and Industry Trends Forecast 2026-2036
Molecular Beam Epitaxy System Market Intelligence
The US Export Administration Regulations (EAR) on advanced semiconductor technology is recalibrating the cost-of-entry calculus for new participants in high-performance computing sectors. Veeco leverages its extensive patent portfolio and established service network to maintain its market position. Riber specializes in production-scale systems for the optoelectronics industry. Pengcheng Semiconductor Technology focuses on developing domestic capabilities within China to counter external supply chain restrictions.
Molecular beam epitaxy is a deposition method for growing single-crystal thin films in an ultra-high vacuum. This technique achieves atomic-layer control, essential for fabricating complex semiconductor heterostructures. Within applications, growth in Quantum Computing Components and Spintronics contrasts with the mature Semiconductor Devices segment. Research Laboratories represent a key end-user base, demanding flexible systems, while industrial fabs require high-throughput production tools.
Material use is governed by regulations like the EU's REACH and RoHS, which restrict certain hazardous substances in electronic equipment. Equipment safety standards, including Europe's CE marking and China's GB standards, are critical for market access. Stakeholders must therefore balance open scientific collaboration with increasing national controls on dual-use manufacturing technologies.
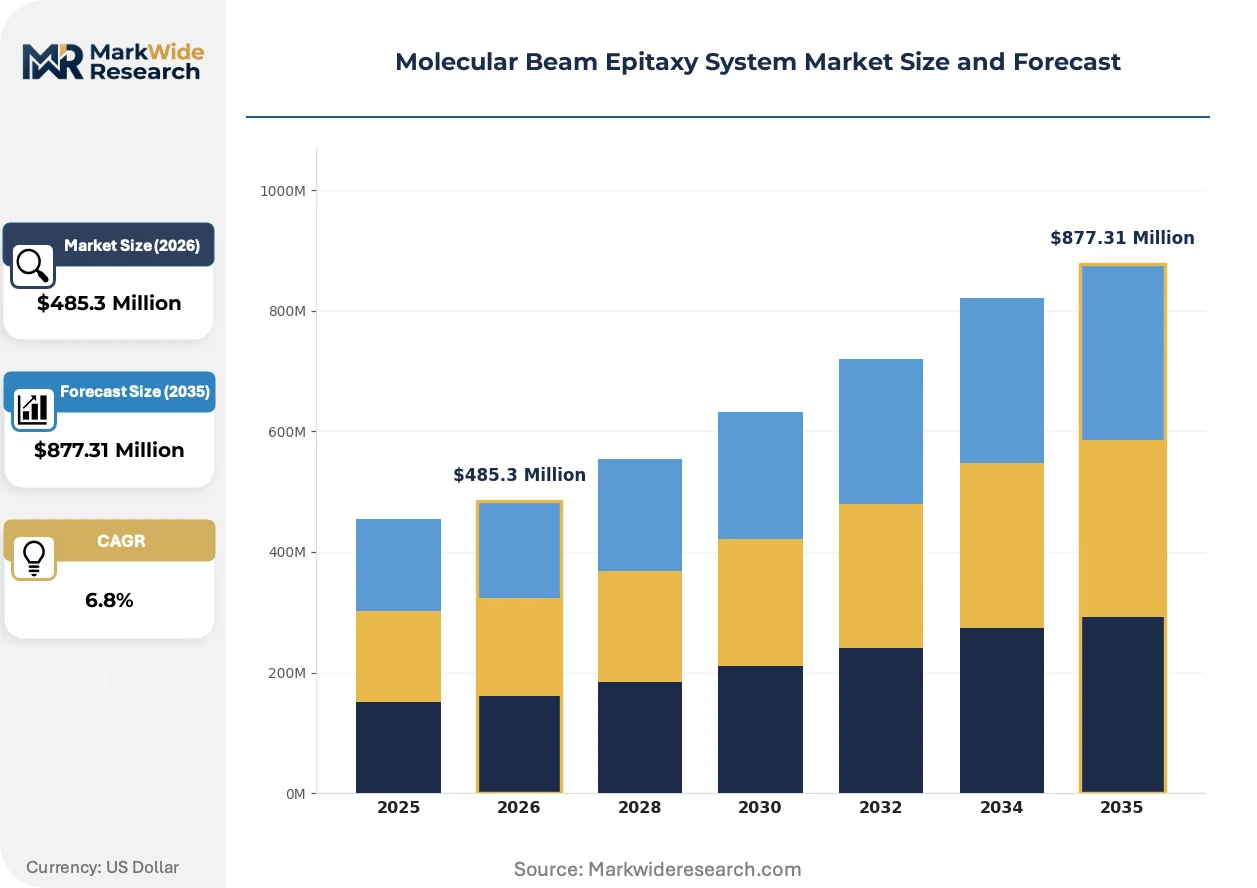
Market Dynamics
The central structural force shaping the market is the geopolitical contest over semiconductor sovereignty. National security-driven export controls on advanced manufacturing technology are compelling nations like China to accelerate domestic development, altering global supply chains and competitive dynamics.
Growth Catalysts
- III-V Compound Semiconductors:The fabrication of high-performance electronics, including 5G components and power devices, relies on the atomic-level precision that MBE provides for depositing III-V compound semiconductor materials like Gallium Arsenide (GaAs) and Gallium Nitride (GaN).
- Quantum Computing Components:Demand from the quantum computing sector is a significant catalyst, as MBE is essential for creating the complex, defect-free heterostructures required for fabricating qubits and other fundamental quantum information processing elements.
- China's Domestic Ecosystem:Government-led initiatives within China to achieve self-sufficiency in semiconductor production are fueling substantial investment in both research-grade and production-scale MBE systems to build out domestic fabrication capabilities and counter external restrictions.
Market Restraints
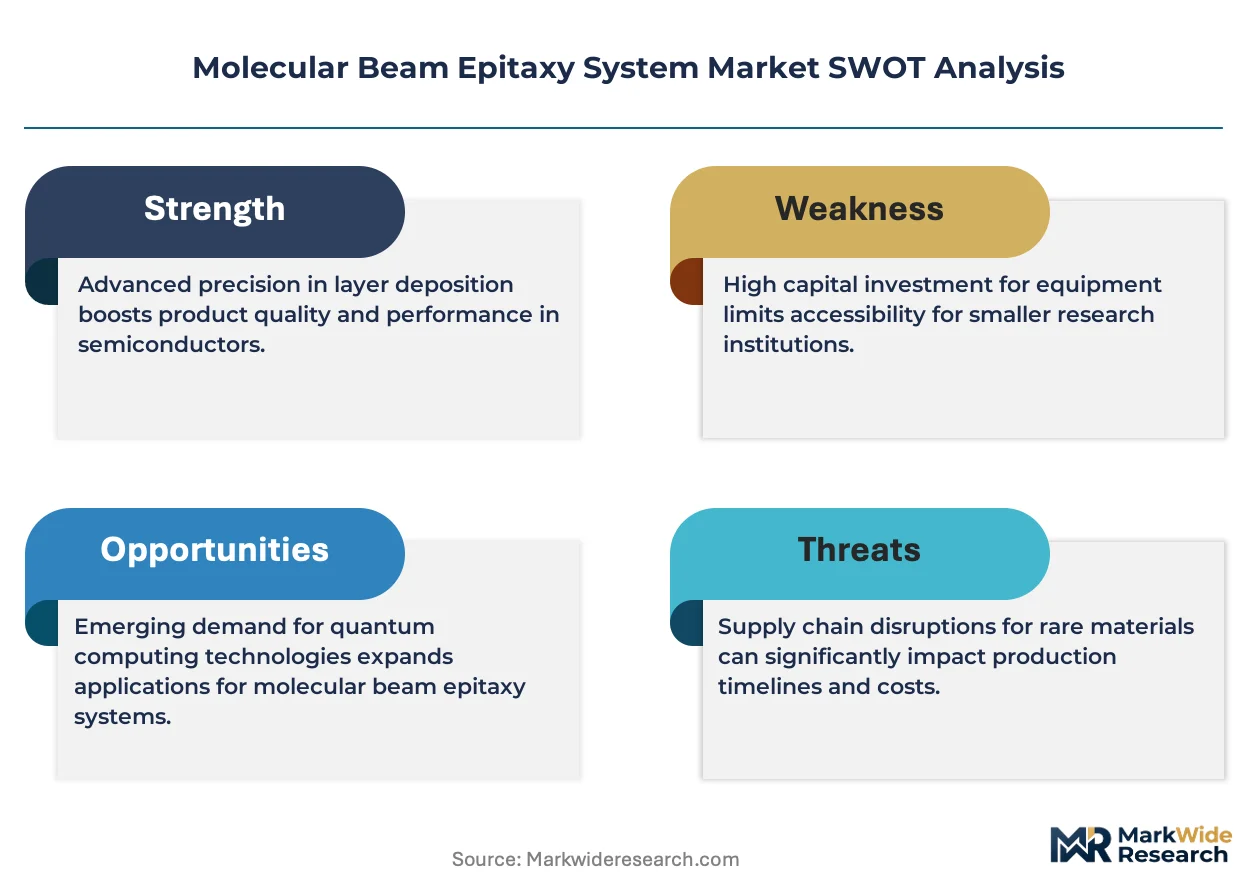
- High Capital & Operational Costs:The initial acquisition cost of MBE systems is substantial, and operational expenses are driven by the need for ultra-high vacuum conditions, specialized source materials, and continuous maintenance by highly skilled personnel, creating a high barrier to entry.
- Slow Deposition Rates:Compared to alternative thin-film deposition techniques like MOCVD, molecular beam epitaxy has a significantly slower growth rate, which can be a limiting factor for high-volume manufacturing applications where throughput is a primary concern.
- Export Control Regulations:The US Export Administration Regulations (EAR) and similar international frameworks restrict the sale and transfer of advanced dual-use technologies, complicating access to state-of-the-art MBE systems for entities in targeted countries.
Strategic Opportunities
- Spintronics Device Fabrication:The development of MBE systems optimized for depositing magnetic thin films and spintronic materials presents an opportunity to serve an emerging market beyond conventional semiconductor electronics, enabling next-generation memory and sensor technologies.
- AI-Integrated Process Control:Integrating artificial intelligence and machine learning algorithms for real-time analysis of RHEED patterns and other in-situ data can automate process optimization, improving film quality, increasing yield, and reducing reliance on operator experience.
- Emerging Research Hubs:Government-backed programs in countries like India, such as its Production Linked Incentive (PLI) scheme for semiconductors, create new market opportunities for MBE system vendors to supply equipment to nascent research consortia and universities.
Industry Challenges
- Specialized Talent Scarcity:The market faces a persistent shortage of physicists and engineers with the deep technical expertise required to operate, maintain, and develop advanced MBE systems and their associated ultra-high vacuum technologies.
- Divergent Safety Standards:Manufacturers must navigate and comply with a complex landscape of regional equipment safety regulations, including Europe's CE marking and China's GB standards, which increases design complexity and time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molecular Beam Epitaxy System Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $877.31 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: System with Load Lock, Cluster System, Single Chamber, Multi-Chamber Technology: Solid Source MBE, Gas Source MBE, Hybrid MBE, Plasma-Assisted MBE, MBE with RHEED Application: Semiconductor Devices, Quantum Computing Components, Optoelectronics, Spintronics, Photovoltaic Cells End User: Research Laboratories, Semiconductor Fabricators, Nanotechnology Centers, Electronic Component Manufacturers |
| Companies Covered | DCA, Dr. Eberl MBE-Komponenten GmbH, Veeco, Prevac, SKY, Riber, SVT Associates, Pengcheng Semiconductor Technology, Scienta Omicron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molecular Beam Epitaxy System Market Strategic Shifts & Innovations
The evolution of molecular beam epitaxy systems is being driven by the dual pressures of materials science advancement and geopolitical strategy. These forces are compelling innovations in both system architecture for new applications and supply chain resilience for established ones.
Technology Evolution
In-situ monitoring technologies, particularly Reflection High-Energy Electron Diffraction (RHEED), provide real-time feedback on crystal growth. Advanced research laboratories and industrial fabs are adopting enhanced analytical software to interpret this data. The integration of machine learning with these monitoring tools is rewriting the paradigm for process control, enabling adaptive optimization of growth parameters to achieve atomic precision with higher reproducibility.
Regulatory Shifts
The European Union's REACH and RoHS directives directly influence MBE system design and material selection. These regulations restrict the use of hazardous substances in electronic equipment, forcing manufacturers to find and validate alternative materials for system components and for the source materials used in deposition. System vendors targeting the EU market must ensure full compliance, impacting their global supply chain and material procurement strategies.
Demand-Side Shifts
A distinct shift is occurring from procuring general-purpose research systems to investing in application-specific production tools. This trend disrupts the traditional one-size-fits-all model, favoring dedicated MBE platforms optimized for high-throughput manufacturing of optoelectronics, power devices, or quantum components. This specialization is most pronounced in Asia's industrial fabrication centers, where scaling production volume is the primary objective.
Molecular Beam Epitaxy System Market Segmentation
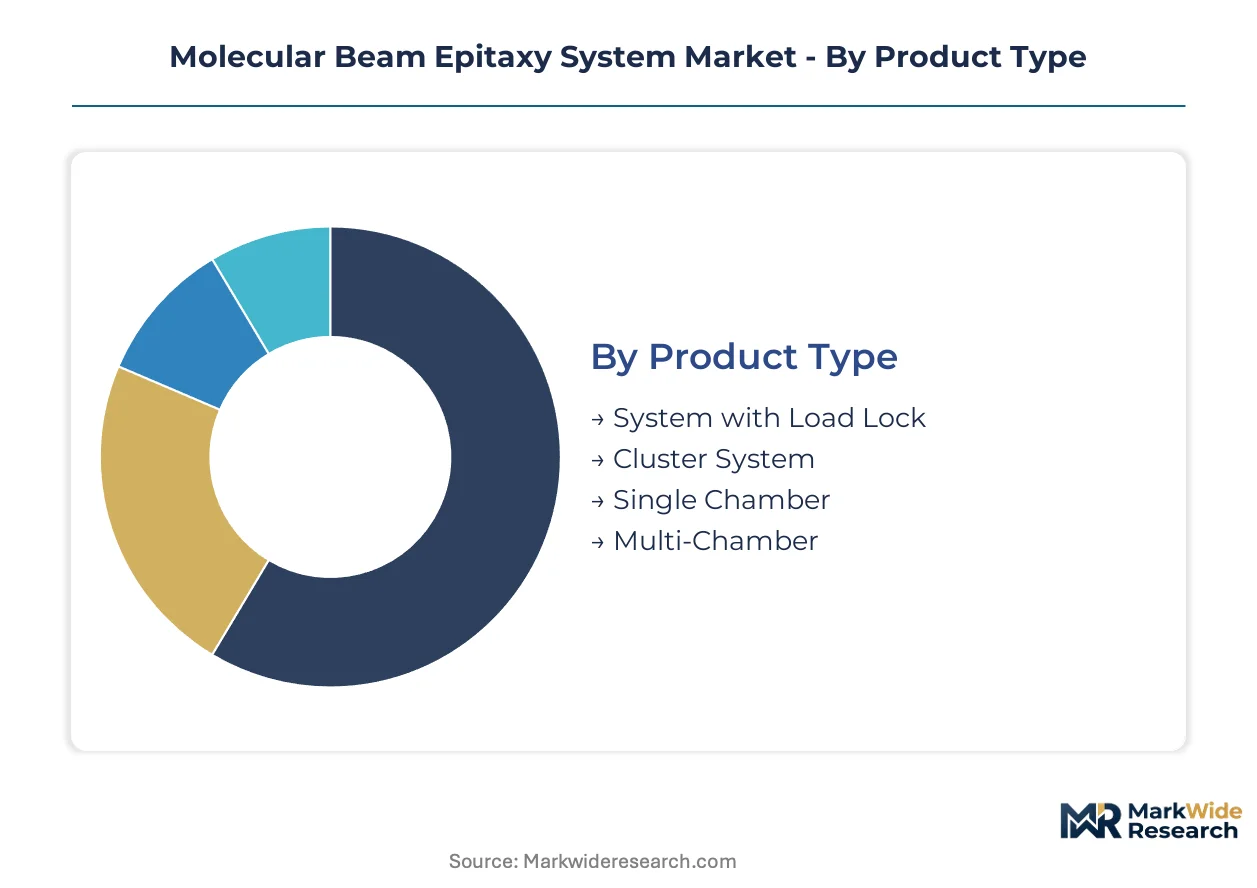
The Molecular Beam Epitaxy System Market segmentation reveals distinct demand patterns and technological requirements across its diverse applications and end-user bases. Understanding these segments is crucial for manufacturers to align product development with specific industry needs and for stakeholders to identify areas of concentrated investment.
Product Type:
Supply concentration in molecular beam epitaxy systems reflects specialized manufacturing capabilities required for diverse system architectures.
- Cluster System:These integrated platforms combine multiple process chambers, enabling sequential material growth and in-situ analysis without breaking vacuum. Demand concentrates in advanced semiconductor fabrication facilities in China, driven by the need for high-throughput, contamination-free processing of III-V compound semiconductors.
- Multi-Chamber:These systems offer flexibility for various growth processes or materials within a single vacuum envelope, allowing for diverse material combinations and complex heterostructures. Research laboratories in Germany utilize multi-chamber designs for experimental flexibility in quantum computing material development.
- System with Load Lock:This configuration allows sample introduction and removal without venting the main growth chamber, preserving ultra-high vacuum conditions.
- Single Chamber:These basic systems offer cost-effective entry points for fundamental research and material science studies in university settings.
Today's leader: Cluster System. Tomorrow's challenger: Multi-Chamber.
Technology:
Different molecular beam epitaxy technologies cater to specific application requirements, influencing material quality and process efficiency.
- Solid Source MBE:This traditional method uses heated effusion cells to sublime high-purity solid materials, providing precise control over deposition rates and film composition. Demand for solid source systems remains high in research laboratories in the US for fundamental studies of novel semiconductor structures.
- Plasma-Assisted MBE:This technique incorporates a plasma source to generate reactive species, particularly nitrogen, enabling the growth of high-quality nitride semiconductors like Gallium Nitride (GaN). Industrial fabs in Japan utilize plasma-assisted MBE for power electronics and optoelectronic device manufacturing.
- Gas Source MBE:This technology employs gaseous precursors, offering advantages in material flexibility and higher growth rates for specific compounds.
- Hybrid MBE:Hybrid systems combine solid and gaseous sources to leverage the benefits of both approaches for complex material systems.
- MBE with RHEED:Reflection High-Energy Electron Diffraction (RHEED) is an in-situ monitoring tool integrated with MBE systems for real-time analysis of surface morphology.
Solid Source MBE maintains its foundational role, while Plasma-Assisted MBE is expanding most quickly due to GaN device requirements.
Application:
The maturity of various applications for molecular beam epitaxy systems dictates investment priorities and technological specialization.
- Quantum Computing Components:MBE systems fabricate the atomic-level precision heterostructures essential for qubits and other quantum information processing elements. Demand for these highly specialized systems is accelerating in research hubs in the Netherlands, driven by national quantum technology initiatives.
- Optoelectronics:This segment uses MBE for manufacturing devices like laser diodes, LEDs, and photodetectors, requiring precise control over material interfaces and doping profiles. Industrial production in South Korea emphasizes high-throughput MBE for advanced display and communication components.
- Semiconductor Devices:MBE supports the production of high-performance transistors and integrated circuits, particularly those based on III-V compound semiconductors.
- Spintronics:This emerging field utilizes MBE to create magnetic thin films and heterostructures for novel memory and sensor applications.
- Photovoltaic Cells:MBE contributes to the development of high-efficiency solar cells by enabling precise layering of different semiconductor materials.
Semiconductor Devices remain a core segment, but Quantum Computing Components are gaining share fastest as research transitions to development.
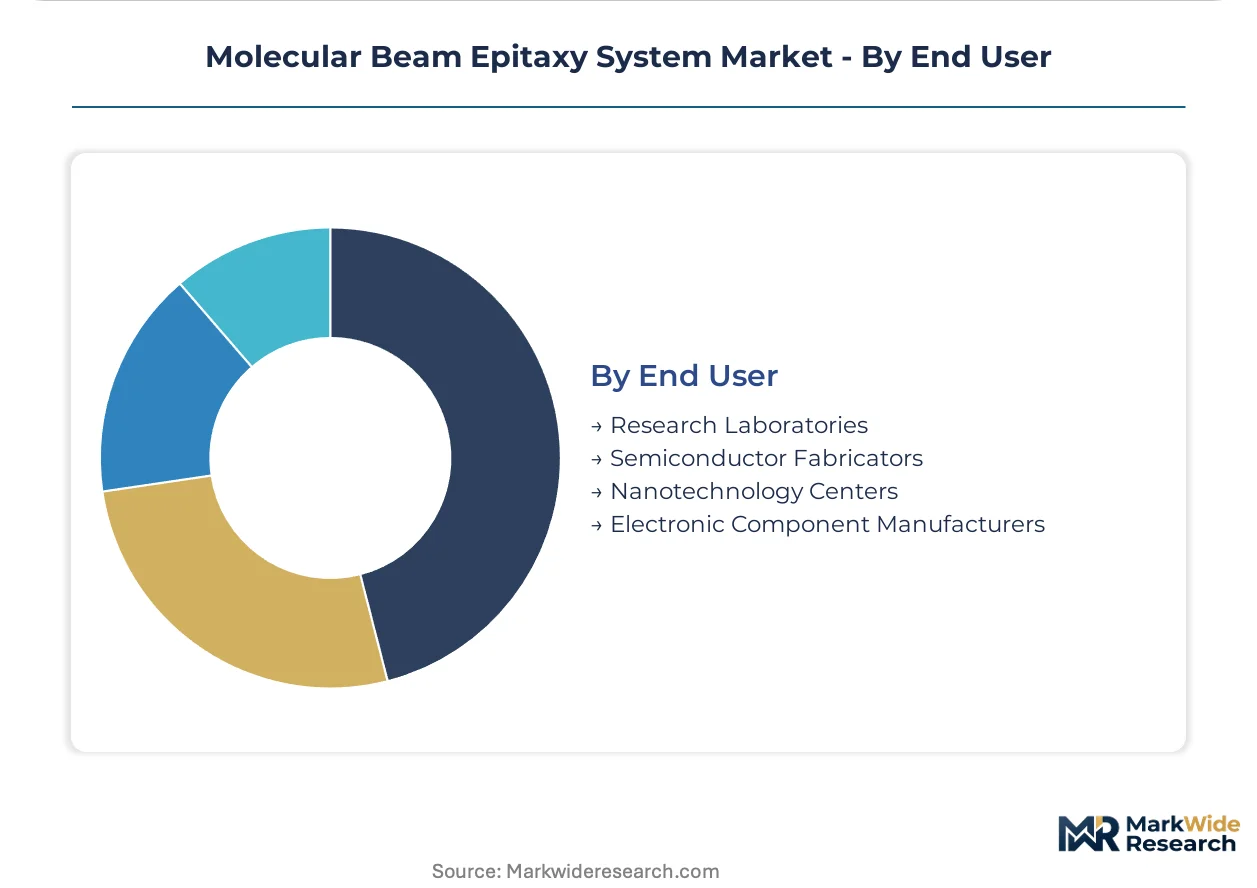
End User:
Customer type directly influences the scale, complexity, and support requirements for molecular beam epitaxy system installations.
- Research Laboratories:These institutions require flexible MBE systems for exploring novel materials, developing new processes, and fundamental scientific investigation. Universities in the United Kingdom prioritize systems with extensive in-situ monitoring capabilities for experimental versatility.
- Semiconductor Fabricators:Industrial fabs demand high-throughput, reliable MBE systems optimized for continuous production of specific semiconductor devices. Manufacturers in Taiwan invest in automated systems for scaling production of advanced III-V compound semiconductor wafers.
- Nanotechnology Centers:These centers leverage MBE for creating nanoscale structures and devices, often pushing the boundaries of material science.
- Electronic Component Manufacturers:These entities integrate MBE-grown wafers into their production lines for specialized high-performance electronic components.
Research Laboratories form the foundational customer base, while Semiconductor Fabricators are climbing the fastest in terms of system procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A highly specialized talent pool in advanced materials science anchors key regions in the molecular beam epitaxy system market. These skilled professionals drive innovation in ultra-high vacuum technology and semiconductor fabrication processes. Their expertise is crucial for developing next-generation quantum computing components and high-performance electronic devices.
China
China's significant investment in domestic semiconductor production fuels demand for both research and production-scale MBE systems. Government-led initiatives, alongside GB standards for equipment safety, drive local development efforts. Industrial fabrication centers in Shenzhen and Shanghai are rapidly expanding their capabilities for advanced III-V compound semiconductor manufacturing.
United States
The United States demonstrates strong demand for MBE systems in quantum computing research and novel semiconductor structure development. US Export Administration Regulations (EAR) shape the availability of advanced dual-use technologies. Research laboratories across Silicon Valley and Boston require flexible systems for experimental versatility in materials science.
Japan
Japanese industrial fabs require advanced MBE systems for high-volume manufacturing of power electronics and optoelectronic devices. METI policies support the development of next-generation semiconductor technologies within the country. Major industrial hubs like Tokyo and Osaka concentrate production for specialized Gallium Nitride (GaN) devices.
Germany
German research laboratories utilize multi-chamber MBE systems for experimental flexibility in quantum computing material development. The EU's REACH and RoHS directives mandate compliance for system components and source materials. Academic institutions in Dresden and Munich are key centers for advanced material science investigations.
Netherlands
National quantum technology initiatives in the Netherlands drive demand for highly specialized MBE systems for qubit fabrication. Compliance with Europe's CE marking is essential for market access of advanced equipment. Research hubs in Delft and Eindhoven are at the forefront of developing fundamental quantum information processing elements.
Molecular Beam Epitaxy System Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the molecular beam epitaxy system market. The market exhibits a tiered structure, with established manufacturers offering broad portfolios alongside niche providers specializing in specific applications. Strategic partnerships for technology co-development and targeted capacity expansion represent dominant competitive moves.
Specialists in production-scale systems for the optoelectronics industry include Riber, which occupies a position serving industrial fabs with its targeted offerings. Veeco leverages its extensive patent portfolio and established service network, anchoring a significant market share across various advanced semiconductor fabrication segments. Pengcheng Semiconductor Technology, a China-based entity, exemplifies the strategic focus on developing domestic capabilities within its home market to counter external supply chain restrictions and build indigenous capacity for high-performance electronics.
| Leading Market Players |
|---|
| DCA |
| Dr. Eberl MBE-Komponenten GmbH |
| Veeco |
| Prevac |
| SKY |
| Riber |
| SVT Associates |
| Pengcheng Semiconductor Technology |
| Scienta Omicron |
| Others |
Cost & Logistics Intelligence
Ultra-high vacuum system components, critical for MBE operation, influence the cost structure for both research-grade and industrial production tools. This upstream cost passes through to end-user pricing, affecting market entry for new participants.
Pricing Analysis
Bundled after-sales service and unbundled system sales define the pricing models for molecular beam epitaxy systems. The dominant structure is a hybrid of contract-based long-term offtake for industrial fabs and transactional sales for research labs. Customization level for specific material growth and comprehensive after-sales service drive price differentiation. Pricing softness reflects the high capital expenditure required for these systems, with university research laboratories exhibiting higher price sensitivity than large semiconductor fabricators.
Supply Chain Analysis
Specialized ultra-high vacuum components supply rests heavily on precision manufacturers in Germany and Japan. High-purity source materials like Gallium and Arsenic draw from a global but concentrated base, with advanced system supply notable in the United States and Germany. Single-source vulnerability for critical sub-components and export control regulations pose a structural risk. Distribution runs through direct sales channels to research laboratories and industrial fabrication facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Molecular Beam Epitaxy System market presents a geographic-arbitrage play, driven by China's domestic development initiatives countering US export controls. This regulatory differential creates distinct market opportunities for localized supply chains.
For Market Incumbents: Anticipate increased competition from domestic Chinese players like Pengcheng Semiconductor Technology, driven by national self-sufficiency goals. Reinforce market position through strategic partnerships for technology co-development and targeted capacity additions in regions like Taiwan. Invest in advanced in-situ monitoring R&D to counter the threat of alternative deposition techniques. Leverage existing patent portfolios and established service networks to maintain market share.
For New Entrants and Emerging Players: Launch via direct sales channels targeting emerging research hubs in countries like India, leveraging government-backed PLI schemes. Focus on developing specialized MBE systems for Spintronics Device Fabrication or AI-Integrated Process Control, addressing unmet needs. The most penetrable segment involves universities and nascent research consortia requiring flexible systems. Offer cost-effective, modular single-chamber systems as a primary go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized talent scarcity and high R&D costs limit organic growth. The long-term viability of advanced MBE technology remains strong, driven by quantum computing and high-performance electronics. Target acquisition archetypes include niche specialists in plasma-assisted MBE or AI-integrated process control. The signal to watch is the increasing adoption rate of production-scale systems by semiconductor fabricators in Asia.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Support increasing demand from China's domestic semiconductor ecosystem. |
| Strategic Partnership | Co-develop advanced RHEED interpretation software with AI firms. |
| Technology Licensing | Broaden access to specialized GaN growth processes for power devices. |
| Geographic Expansion | Establish service hubs in emerging research centers like India. |
| Product Launch | Introduce application-specific MBE systems for spintronics device fabrication. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with physicists, process engineers, R&D directors, and procurement leads from industrial fabs provided qualitative insights. Secondary validation drew from academic publications, patent databases, government reports from METI and MIIT, and company financial filings. This approach ensured robust triangulation of market data.
Historical trendline analysis established baseline market dynamics across the analysis window. Segmentation dimensions modeled include product type, technology, application, end-user, and regional demand patterns. Compound annual growth rates were derived from a multi-factor regression model. Key forecast inputs included projected R&D spending in quantum computing and government investment in III-V semiconductor fabrication.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical trade restriction shifts. Forecasts reflect assumptions on technology adoption rates and material science breakthroughs. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Wafer CMP Machine Market
Semiconductor Equipment
Ion Beam Etching System Market
Semiconductor Equipment
Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Asia-Pacific Semiconductor Etch Equipment Market
Semiconductor Equipment
Dicing Equipment Market
Semiconductor Equipment
Europe Chip Mounter Market
Semiconductor Equipment
Vacuum Coating Equipment Market
Semiconductor Equipment
Global Semiconductor Wafer Polishing and Grinding Equipment Market
Semiconductor Equipment
Unscrambling Machine Market
Semiconductor Equipment
Semiconductor Production Equipment Market
Semiconductor Equipment
Lithography Systems Market
Semiconductor Equipment
Global Semiconductor Machinery Market
Semiconductor Equipment
Semiconductor Wafer Fab Equipment (WFE) Market
Semiconductor Equipment
Vacuum & Low Pressure Diffusion Furnace Market
Semiconductor Equipment
Die Bonder Equipment Market
Semiconductor Equipment
Analog and Digital IC Development Tools Market