
 Global Semiconductor Coolers Market | 2026-2036
Global Semiconductor Coolers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Semiconductor Coolers Market Outlook
Distributor networks serving foundry equipment procurement are reconfiguring around direct OEM partnerships and regional stocking hubs. II-VI Incorporated leverages its compound semiconductor heritage to dominate thermoelectric module supply for lithography systems. Ferrotec Corporation anchors East Asian supply chains through vertically integrated ceramic-metal assembly capabilities. Laird PLC competes on electromagnetic shielding-integrated thermal platforms for automotive ECU applications.
Semiconductor coolers are thermal management devices engineered to maintain junction temperatures below specified thresholds, typically employing thermoelectric modules with bismuth telluride pellets or liquid cold plates with sub-5K thermal resistance to protect logic and memory chips from performance degradation. Thermoelectric coolers lead product type revenue due to solid-state reliability in vacuum environments, while liquid cooling systems capture the fastest growth trajectory as AI training clusters exceed 700W per socket. Peltier Effect technology occupies mature industrial positioning, whereas water cooling extends into data center buildouts where refrigerant restrictions constrain vapor-compression alternatives.
EPA energy efficiency standards and the EU F-Gas Regulation are restricting synthetic refrigerant deployment, redirecting R&D investment toward Peltier and water-based architectures. China's GB standards and MIIT directives mandate domestic thermal management certification for imported semiconductor manufacturing equipment. Japan's METI subsidizes next-generation cooler development through national semiconductor revitalization programs. Stakeholders must monitor evolving refrigerant phase-down schedules and foundry capacity announcements to align thermal product roadmaps with regional compliance windows and fabrication demand pulses.
Market Dynamics
AI chip thermal densities exceeding 700W per socket are forcing a wholesale architecture shift from air-cooled to liquid-cooled and thermoelectric systems across data center and foundry deployments.
Growth Catalysts
- EU F-Gas Regulation:Synthetic refrigerant phase-down mandates are redirecting capital toward Peltier-based and water-cooling alternatives in European semiconductor manufacturing facilities.
- East Asian foundry expansion:Taiwan and South Korea are adding precision thermal management capacity to support advanced node lithography and 3D packaging ramp-ups.
- AI training clusters:Hyperscale data center operators in the United States and Germany are deploying direct liquid cooling to manage GPU socket thermal loads.
Market Restraints
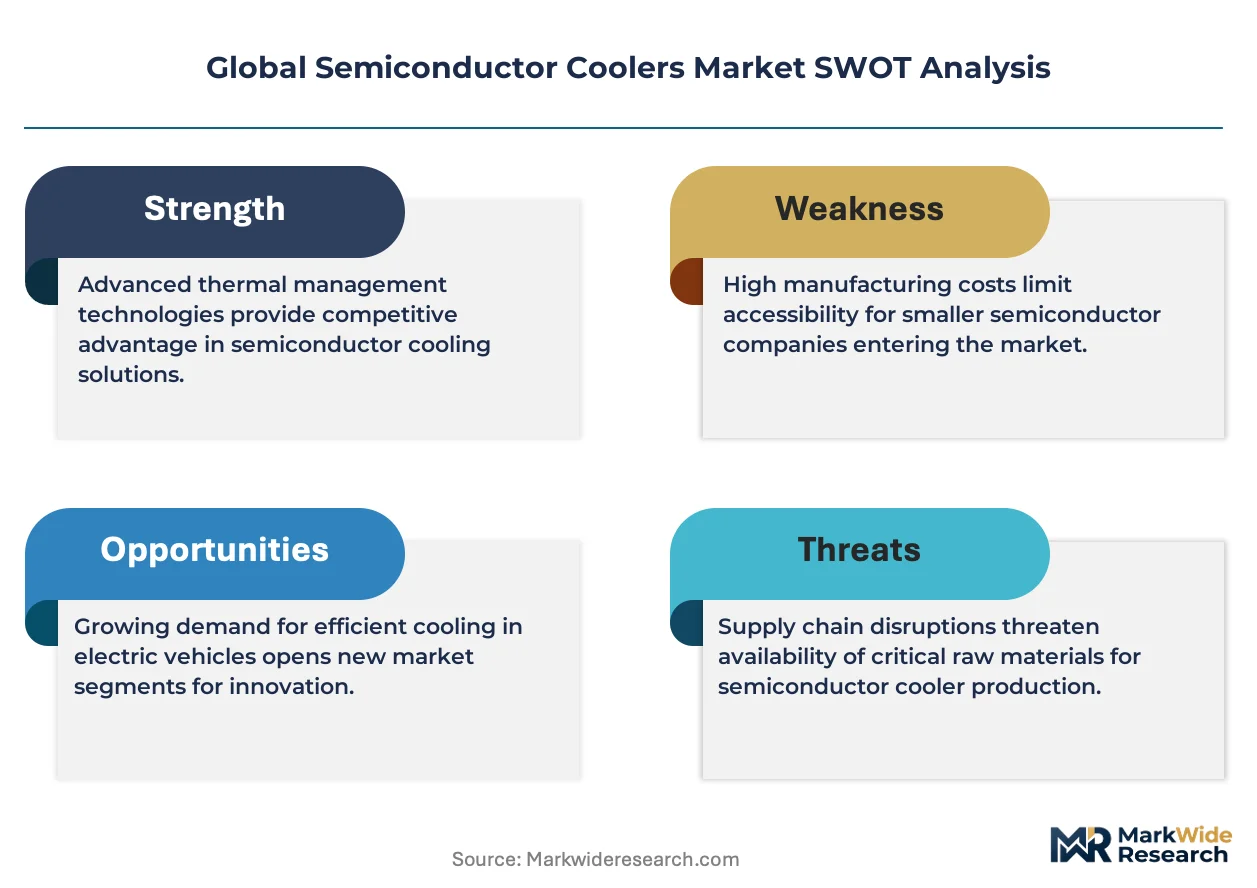
- Bismuth telluride supply concentration:Thermoelectric pellet feedstock depends on Chinese and Korean smelter capacity, exposing module assemblers to input volatility.
- Water cooling capex intensity:Infrastructure requirements for coolant distribution units and leak-detection systems raise total cost of ownership versus vapor-compression alternatives.
- Technical integration barriers:Legacy server rack designs lack plumbing infrastructure, slowing retrofit adoption in brownfield data centers.
Strategic Opportunities
- India's semiconductor PLI scheme:Domestic fabrication incentives are creating first-mover thermal management procurement windows for cooler vendors establishing local assembly.
- Automotive ECU thermal platforms:Electrified powertrain controllers require electromagnetic shielding-integrated cooling, opening adjacent product lines.
- Two-phase cooling convergence:Immersion and cold-plate architectures are merging into hybrid systems for next-generation AI accelerators.
Industry Challenges
- Thermal engineer scarcity:Expertise in computational fluid dynamics and two-phase heat transfer remains concentrated among foundry equipment OEMs and Tier-1 suppliers.
- Multi-regional certification timelines:China's GB standards and MIIT directives require separate domestic thermal management certification for imported semiconductor manufacturing equipment, extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Semiconductor Coolers Market |
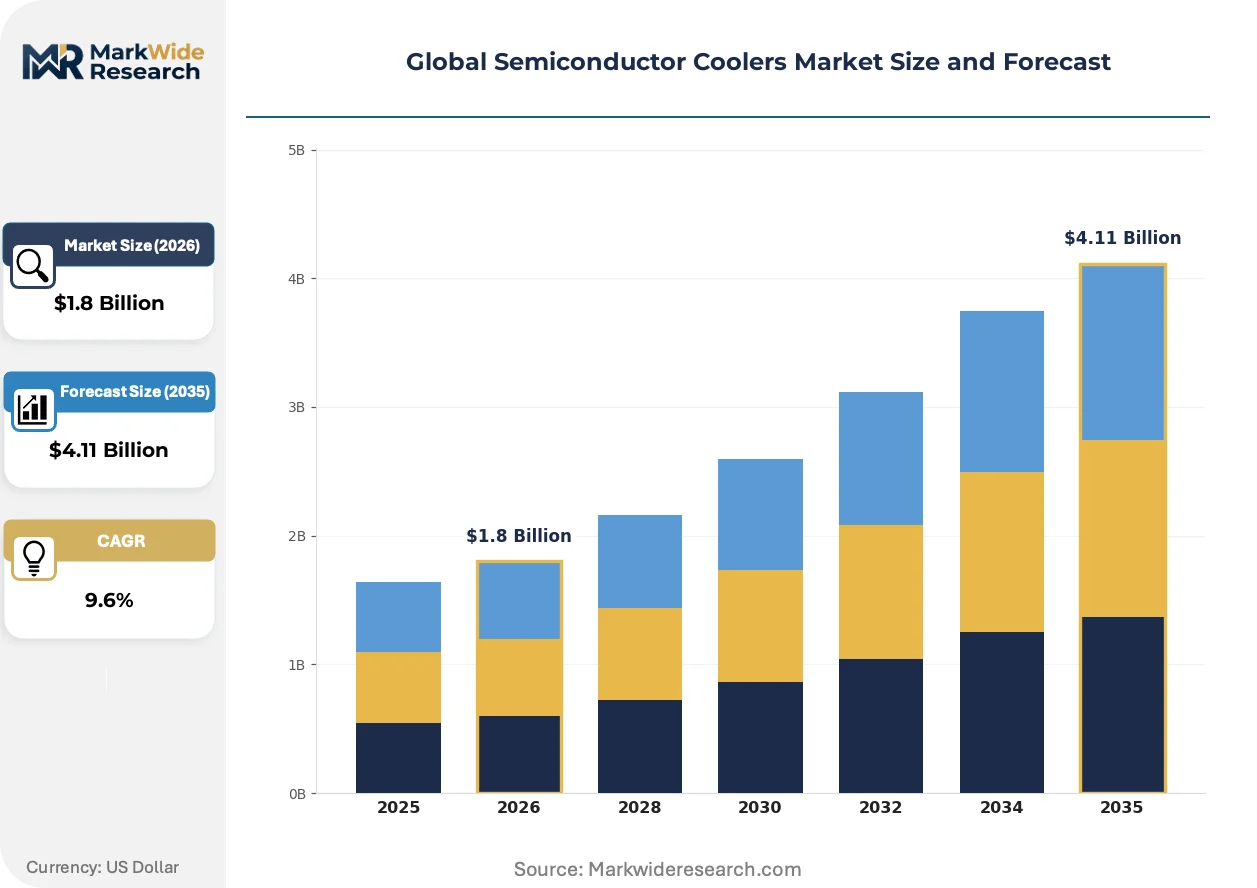
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.11 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoelectric Coolers, Heat Sinks, Liquid Cooling Systems, Phase Change Coolers Application: Consumer Electronics, Automotive Electronics, Industrial Equipment, Data Centers Technology: Vortex Tube, Peltier Effect, Refrigeration Cycles, Water Cooling End User: OEMs, Aftermarket Providers, System Integrators, Research Institutions |
| Companies Covered | II-VI Incorporated, Laird PLC, Ferrotec Corporation, Wellen Technology Co Ltd, RMT Ltd, KELK Ltd, TE Technology Inc, Hicooltec Electronic, Thermion Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Semiconductor Coolers Market Strategic Shifts
Thermal management architectures are converging around solid-state reliability for vacuum environments and liquid-based density for high-power compute, with regulatory pressure accelerating technology substitution cycles.
Microchannel cold plates with sub-5K thermal resistance are hybridizing with thermoelectric modules to create temperature-stabilized substrates for EUV lithography stages. ASML and Nikon lithography system integrators are specifying these hybrid assemblies for next-generation wafer positioning. The convergence is compressing vendor qualification timelines as foundries demand single-source thermal subsystem responsibility.
The EPA's energy efficiency standards and the EU F-Gas Regulation are jointly constraining synthetic refrigerant deployment in data center cooling. This regulatory compression is redirecting R&D budgets from vapor-compression toward water-based and Peltier architectures. European manufacturing and US hyperscale facilities are responding fastest, with Asian markets trailing by two to three compliance cycles.
Direct OEM partnerships are displacing traditional distributor networks for foundry equipment procurement. II-VI Incorporated and Ferrotec Corporation are establishing regional stocking hubs adjacent to TSMC and Samsung fabrication clusters. This channel consolidation is most visible in Taiwan and South Korea, where equipment procurement teams now specify thermal subsystems at the lithography platform design stage rather than through aftermarket distribution.
Global Semiconductor Coolers Market Segmentation
Semiconductor cooler procurement patterns diverge sharply across thermal load requirements, regulatory environments, and integration complexity. Foundry equipment OEMs specify precision thermal subsystems at the lithography platform design stage, while data center operators retrofit liquid infrastructure around existing rack geometries.
Product Type:
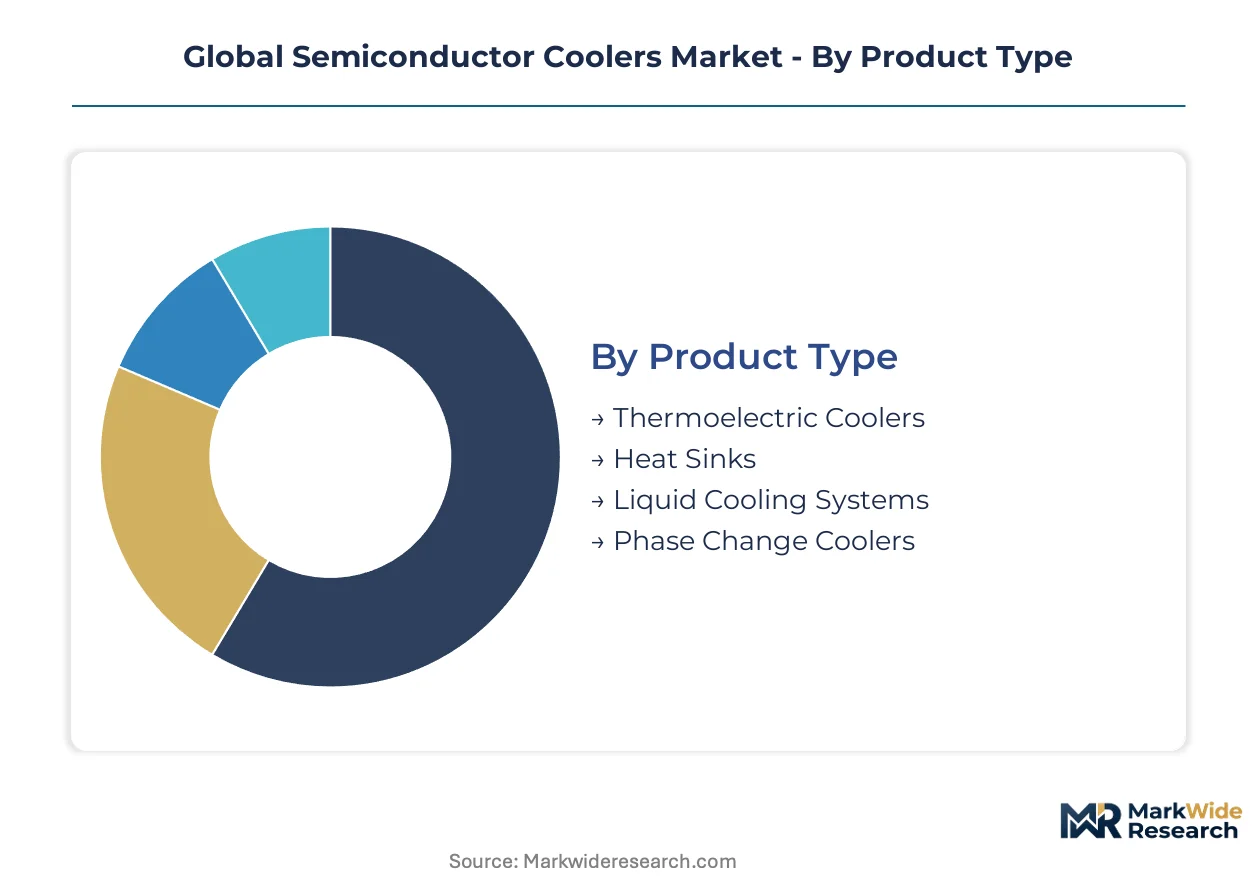
Equipment procurement teams specify thermal solutions spanning solid-state reliability for vacuum environments to high-flow liquid architectures for AI training clusters.
- Thermoelectric Coolers:Solid-state modules employing bismuth telluride pellets deliver maintenance-free operation in EUV lithography vacuum chambers. Taiwan and South Korean foundries specify these for wafer positioning stages where mechanical vibration must approach zero.
- Liquid Cooling Systems:Direct-to-chip cold plates with sub-5K thermal resistance manage GPU socket loads exceeding 700W in United States and German hyperscale facilities. EPA energy efficiency standards and EU F-Gas Regulation constraints accelerate deployment where synthetic refrigerant phase-downs prohibit vapor-compression alternatives.
- Heat Sinks:Aluminum and copper fin arrays serve cost-sensitive consumer electronics and legacy industrial controllers with sub-150W thermal budgets.
- Phase Change Coolers:Two-phase immersion systems target next-generation AI accelerators merging cold-plate and bath architectures for extreme density compute.
The dominant share belongs to thermoelectric coolers, while liquid cooling systems are closing the gap fastest.
Application:
End-use thermal specifications range from millikelvin stability for lithography to volume-cost optimization for consumer devices.
- Data Centers:Direct liquid cooling deployments concentrate in United States and German facilities managing AI training cluster thermal densities. Infrastructure capex for coolant distribution units and leak-detection systems raises total cost of ownership versus air-cooled alternatives.
- Automotive Electronics:Electrified powertrain controllers require electromagnetic shielding-integrated thermal platforms. Laird PLC and comparable suppliers compete on combined EMI suppression and junction temperature management for ECU modules.
- Consumer Electronics:Smartphones, laptops, and gaming consoles drive high-volume heat sink procurement with severe cost constraints and form-factor limitations.
- Industrial Equipment:Factory automation controllers and process instrumentation specify ruggedized thermal solutions with extended temperature range certification.
Data centers command premium pricing for performance-grade systems, whereas automotive electronics is expanding most quickly as electrification multiplies controller thermal loads.
Technology:
Regulatory pressure on synthetic refrigerants is redirecting R&D investment toward water-based and solid-state thermal architectures.
- Peltier Effect:Bismuth telluride-based modules achieve precise temperature stabilization without moving parts. Supply concentration in Chinese and Korean smelter capacity exposes assemblers to input volatility.
- Water Cooling:Closed-loop cold plates and immersion baths capture foundry and data center demand where F-Gas Regulation phase-downs constrain traditional refrigeration. Brownfield server rack retrofits face technical integration barriers from legacy plumbing infrastructure absence.
- Vortex Tube:Compressed air-driven cooling serves niche industrial applications requiring explosion-proof operation without electrical components.
- Refrigeration Cycles:Vapor-compression systems face declining semiconductor manufacturing adoption as EPA standards and EU directives restrict high-GWP refrigerant deployment.
Peltier Effect technology holds mature industrial positioning, while water cooling is gaining share fastest on data center buildout momentum.
End User:
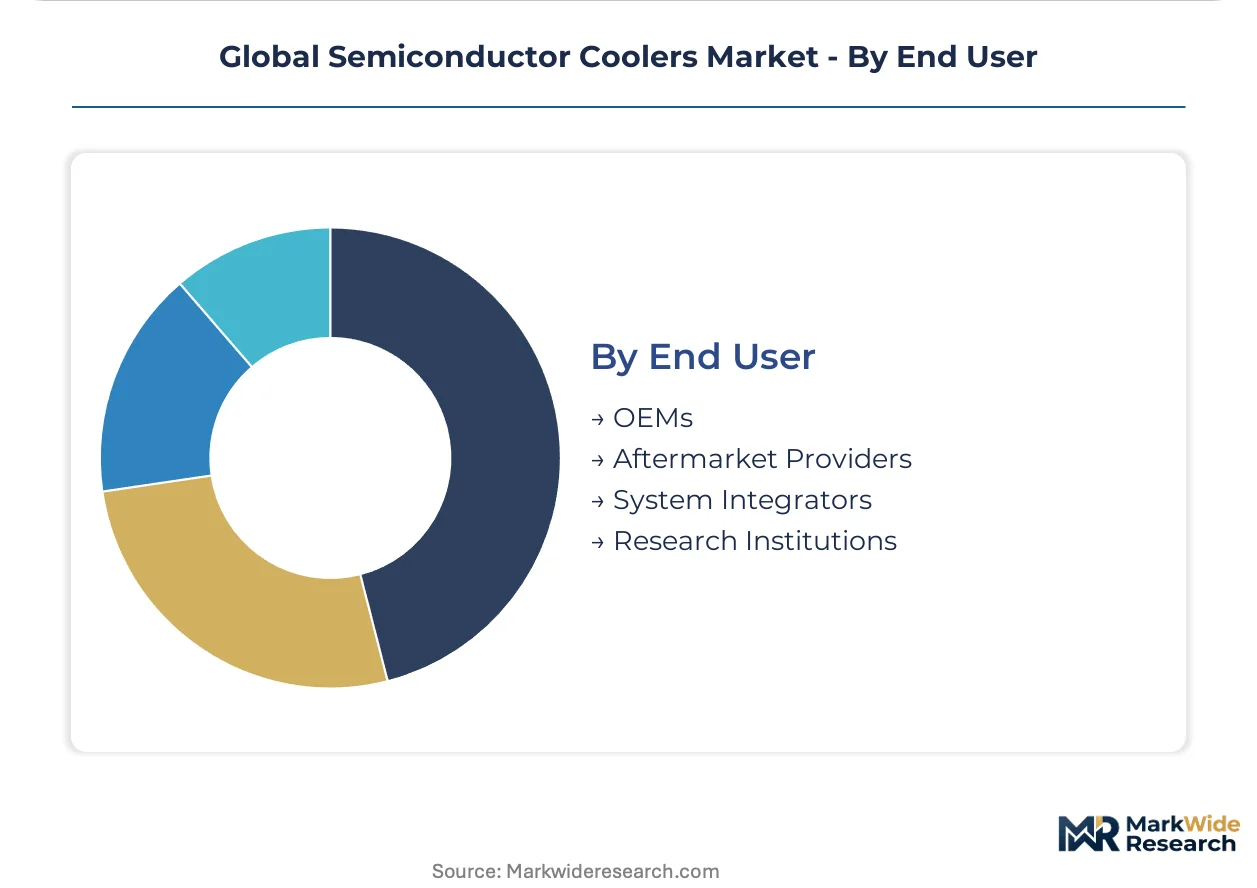
Procurement authority is concentrating at the lithography platform OEM level, displacing traditional aftermarket distribution channels.
- OEMs:ASML and Nikon specify thermal subsystems during lithography system design, forcing cooler vendors into direct partnership models. II-VI Incorporated and Ferrotec Corporation have established regional stocking hubs adjacent to TSMC and Samsung fabrication clusters.
- System Integrators:Hyperscale data center operators in United States and Germany contract thermal infrastructure as part of turnkey facility construction, bundling coolers with coolant distribution and heat rejection systems.
- Aftermarket Providers:Legacy server maintenance and industrial equipment refurbishment sustain replacement cooler demand through distributor networks.
- Research Institutions:National laboratories and university fabrication facilities procure specialized thermal solutions for experimental device characterization and prototype packaging.
OEMs dominate procurement volume through platform-level specification authority, while system integrators are climbing the fastest on data center construction cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation is redirecting European capital toward Peltier-based and water-cooling alternatives. United States hyperscale operators are deploying direct liquid cooling for AI training clusters. East Asian foundry expansion in Taiwan and South Korea drives precision thermal management procurement.
United States
Hyperscale data center operators in Northern Virginia and Texas are installing direct liquid cooling systems to manage GPU socket loads exceeding 700W. EPA energy efficiency standards are restricting synthetic refrigerant deployment in facility cooling. Phoenix and Dallas-Fort Worth clusters are seeing accelerated buildouts where coolant distribution infrastructure is bundled with turnkey construction contracts.
Germany
Industrial automation OEMs in Bavaria and Baden-Württemberg are specifying electromagnetic shielding-integrated thermal platforms for electrified powertrain controllers. The EU F-Gas Regulation is accelerating shifts away from vapor-compression systems in manufacturing facilities. Dresden's semiconductor fabrication cluster is procuring precision thermoelectric modules for EUV lithography stages.
Taiwan
TSMC and foundry equipment integrators are specifying thermal subsystems at the lithography platform design stage rather than through aftermarket channels. METI-subsidized programs in Japan are indirectly pressuring Taiwanese suppliers to accelerate next-generation cooler development. The Hsinchu Science Park concentration is driving regional stocking hub establishment by module assemblers.
South Korea
Samsung Electronics and domestic foundry operators are adding precision thermal management capacity to support advanced node lithography ramp-ups. The country's national industrial regulator mandates domestic thermal management certification for imported semiconductor manufacturing equipment. Pyeongtaek and Giheung fabrication clusters are seeing direct OEM partnership models displace traditional distributor networks.
China
MIIT directives and GB standards require separate domestic thermal management certification for imported semiconductor manufacturing equipment. Yangtze River Delta fabrication clusters are driving demand for bismuth telluride pellet supply despite feedstock concentration risks. Shanghai and Beijing data center operators are trailing European and US compliance cycles by two to three phases on refrigerant restrictions.
Global Semiconductor Coolers Market Competitive Environment
On the supply side, the industry is consolidating around compound semiconductor heritage players and vertically integrated ceramic-metal assemblers. Three strategic archetypes dominate: lithography system thermal subsystem specialists, electromagnetic shielding-integrated platform providers, and regional stocking hub operators. Competitive moves center on direct OEM partnership establishment and geographic proximity to foundry clusters.
Within the compound semiconductor specialist tier, II-VI Incorporated and Ferrotec Corporation exemplify supply chain positioning adjacent to East Asian fabrication centers. Laird PLC occupies a position representing electromagnetic shielding-integrated thermal platform supply for automotive ECU applications. These three anchors illustrate how vendor qualification timelines compress when foundries demand single-source thermal subsystem responsibility.
| Leading Market Players |
|---|
| II-VI Incorporated |
| Laird PLC |
| Ferrotec Corporation |
| Wellen Technology Co Ltd |
| RMT Ltd |
| KELK Ltd |
| TE Technology Inc |
| Hicooltec Electronic |
| Thermion Company |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor carries bismuth telluride pellet shipments from Chinese smelters to European module assemblers, with freight cost volatility amplifying price spreads between certified and uncertified thermal components. This logistics artery connects concentrated upstream feedstock to fragmented downstream buyers, compressing margins for non-integrated distributors while rewarding regional stocking hub operators.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with EU F-Gas Regulation-compliant modules commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by thermal resistance specification and after-sales service bundling. Cost compression in the economy tier is intensifying because foundry equipment OEMs are consolidating procurement authority at the platform design stage. Data center operators exhibit highest price sensitivity due to capex-intensive liquid cooling infrastructure requirements, while lithography system integrators prioritize performance certification over unit cost.
Supply Chain Analysis
Bismuth telluride pellet feedstock draws from Chinese and Korean smelter capacity, with ceramic substrates and copper interconnects sourced from Japanese and Taiwanese suppliers. This upstream concentration rests on rare earth refining capabilities concentrated in East Asian chemical processing corridors. Single-source vulnerability in thermoelectric material supply exposes module assemblers to export restriction risk from Chinese environmental regulators. Distribution runs through direct OEM partnerships displacing traditional distributor networks, particularly for foundry equipment procurement adjacent to TSMC and Samsung fabrication clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority is concentrating among lithography platform OEMs and hyperscale data center operators, shifting buyer power toward consolidated specification authority and compressing vendor margins through single-source thermal subsystem demands.
For Market Incumbents: Entrench position through backward integration into bismuth telluride pellet supply and captive ceramic-metal assembly capabilities. Establish regional stocking hubs adjacent to Taiwan and South Korean foundry clusters to compress lead times below competitor reach. Defend against emerging Chinese module assemblers by accelerating EU F-Gas Regulation certification timelines for next-generation thermoelectric platforms. For New Entrants and Emerging Players: India's semiconductor PLI scheme represents the most penetrable entry point, with domestic fabrication incentives creating first-mover procurement windows for cooler vendors establishing local assembly. Automotive electromagnetic shielding-integrated thermal platforms offer adjacent white-space with less consolidated buyer power than foundry equipment. Target system integrators bundling thermal infrastructure with turnkey data center construction rather than competing for OEM platform specification. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down schedules reshape the acquisition landscape toward water-cooling and Peltier-based technology portfolios over vapor-compression assets. Long-term viability favors compound semiconductor heritage players with established foundry equipment relationships and in-house ceramic processing. Watch for foundry capacity announcements from TSMC and Samsung as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Direct OEM Partnership Establishment | ASML and Nikon platform specification authority eliminates aftermarket distributor intermediation. |
| Regional Stocking Hub Deployment | Proximity to Hsinchu and Pyeongtaek fabrication clusters compresses qualification timelines. |
| Bismuth Telluride Supply Integration | Upstream control over Chinese and Korean smelter feedstock insulates against input volatility. |
| EU F-Gas Certification Investment | Regulatory compliance unlocks premium pricing in European manufacturing and data center segments. |
| Hybrid Thermal Architecture Development | Microchannel cold plate and thermoelectric module convergence addresses EUV lithography stage demands. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with foundry equipment procurement managers, thermal subsystem engineers at lithography OEMs, data center infrastructure planners, and semiconductor fabrication facility directors; alongside secondary validation through EPA energy efficiency filings, EU F-Gas Regulation implementation documents, MIIT directive announcements, and SEC disclosures from thermal management vendors. Bottom-up triangulation across equipment procurement volumes and top-down validation against foundry capex announcements anchored market sizing.
Forecast inputs span product type segmentation across thermoelectric coolers, liquid cooling systems, heat sinks, and phase change architectures; technology categories including Peltier Effect, water cooling, and refrigeration cycles; and end-user distinctions between OEMs, system integrators, aftermarket providers, and research institutions. CAGRs were derived from regression analysis against foundry capacity expansion schedules and AI training cluster deployment trajectories. Thermal load density projections for GPU sockets and EUV lithography stages served as industry-specific demand drivers.
Stress conditions across bismuth telluride supply disruption, EU F-Gas Regulation acceleration, and foundry construction delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory compliance timelines and equipment procurement patterns. Cross-checking against TSMC and Samsung capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
X-Ray Lithography Equipment Market
Semiconductor Equipment
FOUP Cleaning System Market
Semiconductor Equipment
Semiconductor CVD Equipment Market
Semiconductor Equipment
Vacuum Spin Coaters Market
Semiconductor Equipment
150mm Probe Station Market
Semiconductor Equipment
Pulsed Laser Deposition Systems Market
Semiconductor Equipment
Global Atomic Layer Deposition (ALD) Equipment Market
Semiconductor Equipment
Global Sputtering Equipment Market
Semiconductor Equipment
Selective Soldering Equipment Market
Semiconductor Equipment
Lithographic Photomasks Market
Semiconductor Equipment
Asia-Pacific Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Ion Milling System Market
Semiconductor Equipment
Electrolytic Etching Machine Market
Semiconductor Equipment
Automatic Flip Chip Bonders Market
Semiconductor Equipment
North America Semiconductor Etch Equipment Market
Semiconductor Equipment
APAC Die Attach Equipment Market