
 Photolithography Market | 2026-2036
Photolithography Market Size, Share, and Industry Trends Forecast 2026-2036
Photolithography Market Intelligence
The SEMI S2 safety standard for manufacturing equipment is unwinding the historical separation between tool suppliers and foundry operators, requiring deeper integration. ASML Holdings dominates the Extreme UV (EUV) segment, controlling the critical technology for next-generation chip production. In the mature Deep UV (DUV) market, Nikon Corporation and Canon Inc. compete for share among foundries and integrated device manufacturers. This creates a clear technology and market access hierarchy.
Photolithography is an optical process used to transfer a geometric pattern from a photomask to a light-sensitive chemical photoresist on a substrate. This technique utilizes specific wavelengths of light, such as 193nm for Deep UV, to create the intricate circuit patterns essential for modern semiconductor fabrication. Extreme UV (EUV) technology represents the highest-margin segment, though Deep UV systems still constitute the largest installed base. While semiconductor fabrication is the primary application, the process is also fundamental for manufacturing MEMS.
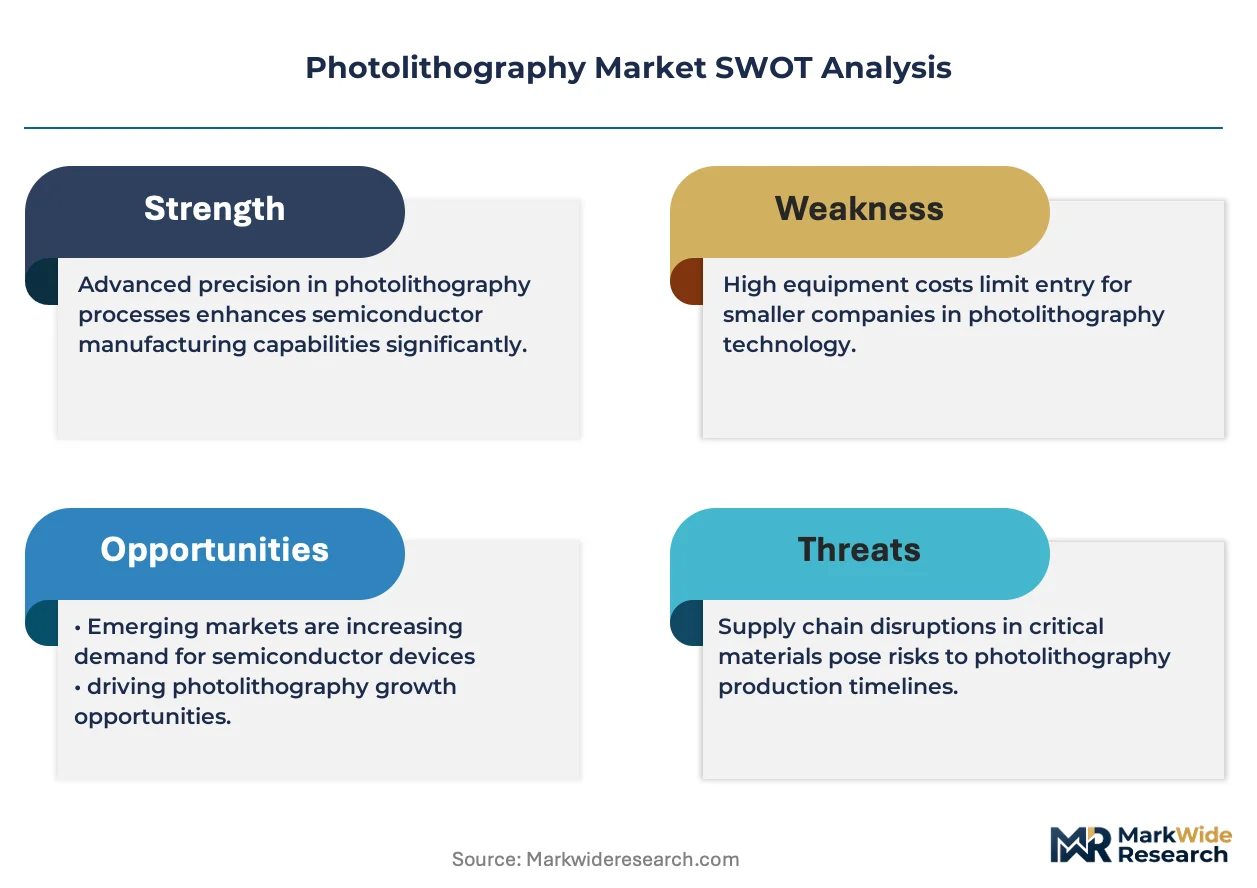
Regulations from the European Chemicals Agency (ECHA) under REACH and the US Environmental Protection Agency (EPA) govern the chemical composition of photoresists. In parallel, China's Ministry of Ecology and Environment (MEE) imposes strict standards on emissions and waste from fabrication facilities, influencing equipment design. Foundries and chipmakers must now balance investments in next-generation lithography tools with compliance costs across these divergent regulatory landscapes.
Market Dynamics
The extreme capital intensity required for Extreme UV (EUV) lithography is the central force shaping the market. This financial barrier concentrates advanced manufacturing capability within a handful of top-tier foundries, directly influencing global semiconductor supply chain geography and resilience.
Growth Catalysts
- Sub-10nm Transition:The semiconductor industry's migration to advanced process nodes for next-generation logic and memory chips is the primary demand driver, necessitating investment in EUV and advanced immersion DUV systems.
- MEMS Manufacturing:Adoption of photolithography for creating micro-electromechanical systems is expanding the technology's application base beyond traditional integrated circuits into sensors, actuators, and other miniaturized devices.
- Semiconductor Sovereignty Policies:National initiatives, such as the US CHIPS Act and the EU Chips Act, provide significant subsidies for new fabrication plant construction, directly stimulating lithography tool procurement.
Market Restraints
- Extreme Capital Cost:The prohibitive acquisition and operating costs of EUV lithography systems create a significant barrier to entry, limiting adoption to only the largest and most well-capitalized semiconductor manufacturers.
- EUV Technology Control:Monopolistic control over the production and supply of EUV systems by a single vendor creates a critical supply chain bottleneck and significant pricing power, limiting negotiating leverage for buyers.
- Photoresist Chemistry Limits:Developing photoresists that balance sensitivity, resolution, and line-edge roughness for EUV wavelengths remains a significant technical hurdle, constraining the throughput and yield of advanced processes.
Strategic Opportunities
- Advanced Packaging:The growth of heterogeneous integration and advanced packaging techniques, such as Fan-Out Wafer-Level Packaging (FOWLP), creates new opportunities for DUV lithography tools in redistribution layer patterning.
- Directed Self-Assembly (DSA):The convergence of lithography with materials science in the form of DSA offers a potential pathway to augment EUV and extend the resolution limits for future manufacturing nodes.
- Emerging Foundry Ecosystems:National semiconductor initiatives in countries like India create greenfield opportunities for established DUV lithography systems as these regions build out their foundational manufacturing capabilities.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of engineers and physicists with the requisite skills to operate, maintain, and optimize advanced EUV and immersion DUV lithography tools constrains fab productivity.
- Divergent Regulatory Compliance:Equipment and material suppliers must navigate conflicting chemical regulations from the ECHA under REACH and the EPA, alongside strict emissions rules from China's MEE.
- Legacy System Integration:Foundries face significant technical challenges and operational downtime when integrating new-generation lithography tools with existing factory automation, metrology, and process control software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photolithography Market |
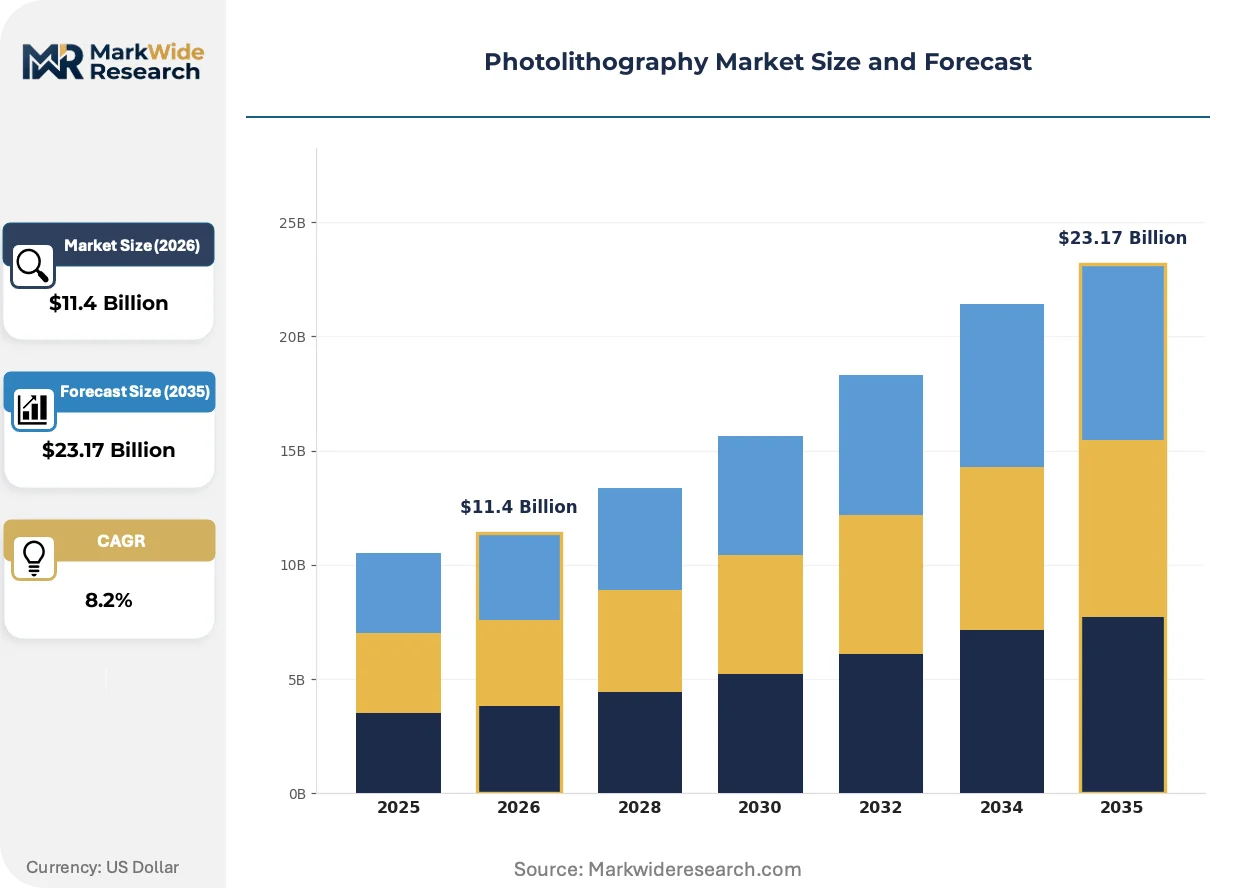
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $23.17 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steppers, Scanners, Mask Aligners, Direct Write Systems Technology: Deep UV, Extreme UV, Electron Beam, Nanoimprint, X-Ray Application: Semiconductor Fabrication, MEMS Manufacturing, Printed Circuit Boards, Photovoltaic Cells End User: Chipmakers, Electronics Manufacturers, Research Laboratories, Foundries |
| Companies Covered | ASML Holdings, Nikon Corporation, Canon Inc., JEOL Ltd., SUSS MicroTec, EV Group, Veeco Instruments Inc., NuFlare Technology, Rudolph Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photolithography Market Strategic Shifts & Innovations
The market is defined by a technological bifurcation. Frontier innovation is exclusively focused on advancing EUV for leading-edge logic, while a separate innovation track seeks to extend the economic life and performance of the vast installed base of DUV systems.
Extreme UV (EUV) lithography enables the intricate patterning of features required for sub-10nm semiconductor process nodes. Leading-edge foundries and memory chipmakers are rapidly adopting this technology for their most critical layers. As adoption accelerates, EUV is displacing complex and costly multi-patterning DUV techniques, thereby reducing manufacturing steps and improving yields for advanced devices.
European Union chemical regulations under REACH are compelling a significant reformulation of photoresist chemistries. The framework restricts or requires authorization for specific substances, forcing chemical suppliers to invest in research for compliant alternatives without compromising performance. This shift most acutely affects suppliers of advanced photoresists for EUV and immersion DUV, who must balance regulatory adherence with stringent technical specifications from chipmakers.
Foundry procurement models are evolving from simple transactional equipment purchases to demands for integrated, long-term service partnerships. This shift disrupts the traditional sales model, requiring tool suppliers to provide holistic solutions encompassing process optimization, yield management, and predictive maintenance. The trend is most visible in the dense foundry clusters of Taiwan and South Korea, where intense competition on cycle time and wafer output drives demand for deeper supplier collaboration.
Photolithography Market Segmentation
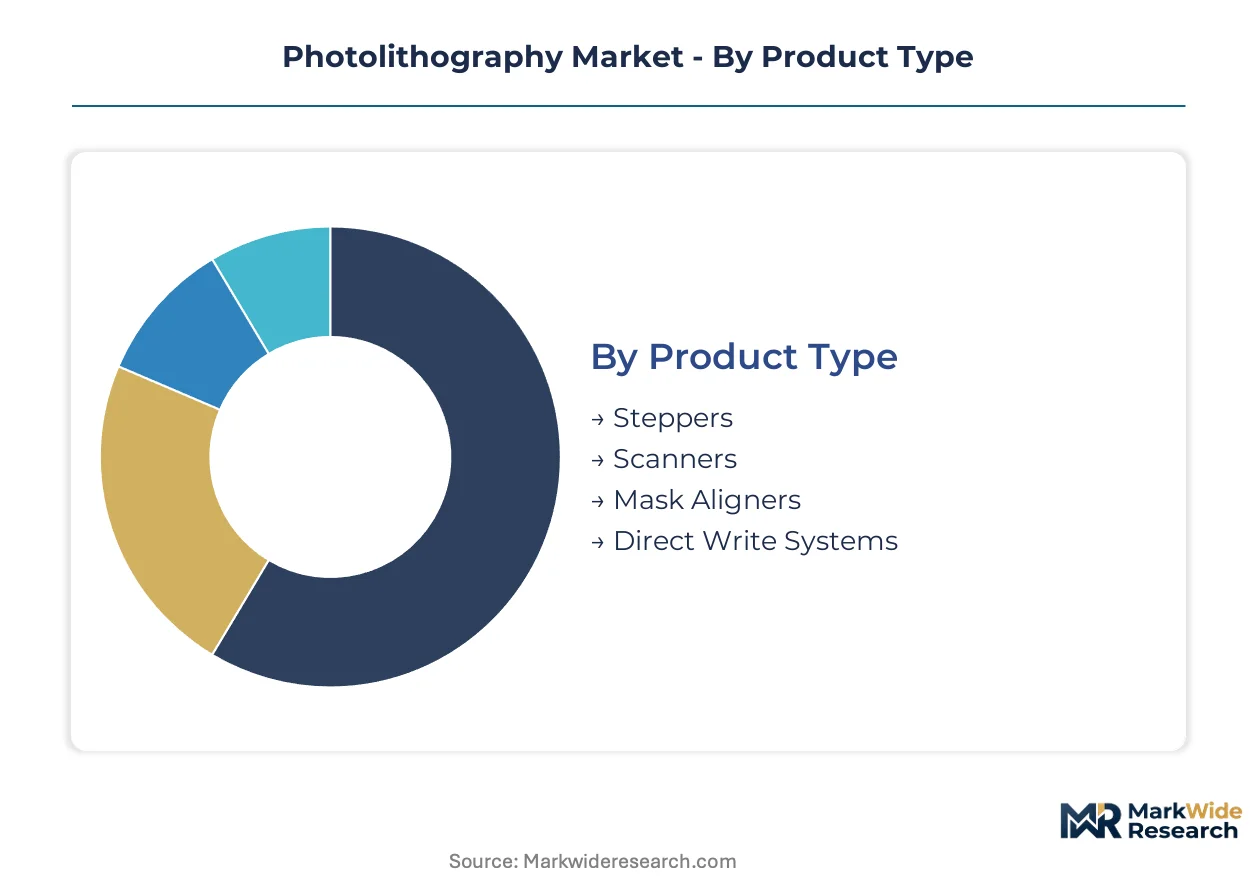
The photolithography market categorizes core components, technologies, and end-use sectors driving its expansion. Understanding these distinctions reveals how equipment suppliers align their offerings with specific industry needs. This segmentation highlights the diverse paths for technology deployment and market penetration.
Product Type:
The distribution of photolithography equipment varies significantly across different manufacturing channels and facility types, each serving distinct operational scales and precision requirements.
- Scanners:These advanced systems project intricate patterns onto wafers, often integrating immersion or Extreme UV light sources. Demand concentrates in leading-edge foundries in Taiwan and South Korea, driven by the sub-10nm process node transition.
- Steppers:Steppers expose individual die areas sequentially, balancing throughput and resolution for less critical layers. The installed base remains substantial in integrated device manufacturers and specialized fabs producing mature technologies.
- Mask Aligners:These systems physically contact the mask with the wafer, suitable for less demanding applications like MEMS.
- Direct Write Systems:Direct write systems pattern wafers without a photomask, used for prototyping and low-volume manufacturing.
By volume, Mask Aligners represent a significant portion. By growth pace, Scanners are expanding most quickly, driven by advanced node requirements.
Technology:
The margin profile of different photolithography technologies varies significantly, reflecting their complexity, development costs, and market exclusivity. Each technology addresses distinct resolution and throughput requirements for semiconductor manufacturing.
- Extreme UV:EUV technology uses 13.5nm wavelength light for sub-10nm features, enabling next-generation logic and memory chips. High acquisition cost and monopolistic control ensure its high-margin status for advanced foundries.
- Deep UV:DUV lithography uses 193nm or 248nm light for features 10nm and above, including advanced immersion DUV. This mature technology forms the largest installed base, serving a broad range of chipmakers.
- Electron Beam:Electron beam lithography offers ultra-high resolution but low throughput, suitable for photomask fabrication.
- Nanoimprint:This technology physically stamps patterns onto a resist, offering a low-cost, high-resolution alternative for specific applications.
- X-Ray:X-ray lithography provides high resolution but faces mask fabrication and infrastructure cost challenges, limiting commercial adoption.
The ongoing transition to Extreme UV redefines the performance benchmarks for advanced semiconductor manufacturing processes.
Application:
The application focus delineates where photolithography processes are deployed, ranging from the core semiconductor industry to diverse micro-device manufacturing. Each application has distinct requirements for resolution, throughput, and cost.
- Semiconductor Fabrication:This core application involves patterning integrated circuits on silicon wafers for logic, memory, and power devices. Demand for advanced lithography tools is driven by the relentless pursuit of smaller feature sizes.
- MEMS Manufacturing:Photolithography is fundamental for creating micro-electromechanical systems, including sensors, actuators, and microfluidic devices. This application is expanding into new markets like automotive and healthcare.
- Printed Circuit Boards:Photolithography is used in PCB manufacturing for creating intricate conductive patterns and solder masks on high-density interconnect boards.
- Photovoltaic Cells:This application utilizes photolithography to pattern electrodes and anti-reflective coatings on solar cells, enhancing efficiency.
The diversification of photolithography applications underscores its broad industrial relevance across multiple high-tech sectors.
End User:
The customer type for photolithography equipment dictates procurement strategies, service requirements, and the scale of investment. Different end-user segments possess varying internal capabilities and production volumes.
- Chipmakers:These entities design and often manufacture their own integrated circuits, ranging from large Integrated Device Manufacturers to specialized fabless companies. Chipmakers require lithography solutions tailored to their specific product portfolios.
- Foundries:Foundries are specialized manufacturers producing chips for multiple fabless design companies. Their demand for advanced EUV and Deep UV systems is driven by the need for leading-edge process nodes and high volume production.
- Electronics Manufacturers:These companies integrate components into final electronic products, using photolithography for advanced packaging or specialized production.
- Research Laboratories:Academic institutions and R&D centers use photolithography for fundamental research and prototyping novel devices.
Understanding the distinct procurement models of Foundries and Chipmakers is crucial for strategic market engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National semiconductor sovereignty policies, including the US CHIPS Act and the EU Chips Act, actively stimulate investment in new fabrication plant construction. These legislative frameworks directly influence lithography tool procurement, driving regional shifts in advanced manufacturing capabilities. This strategic push aims to localize critical semiconductor supply chains, impacting global distribution of photolithography demand.
Taiwan
Demand for advanced photolithography tools in Taiwan centers on the relentless pursuit of sub-10nm process nodes for logic and memory devices. The government actively supports the semiconductor industry through various incentive programs, fostering a robust ecosystem. Major foundries in the Hsinchu Science Park and Tainan Science Park continuously invest in Extreme UV systems to maintain their leading-edge manufacturing capabilities.
South Korea
South Korea's photolithography market focuses on the rapid adoption of Extreme UV technology for next-generation chip production, particularly in memory and advanced logic. The Ministry of Trade, Industry and Energy (MOTIE) promotes domestic semiconductor R&D and manufacturing, providing substantial subsidies. Large-scale fabrication facilities in Gyeonggi Province, including Pyeongtaek, drive significant procurement of high-end lithography equipment.
United States
The United States market experiences a surge in demand for photolithography equipment driven by the resurgence of domestic chip manufacturing and advanced packaging initiatives. The US CHIPS Act provides billions in subsidies for new fabrication facilities and R&D, encouraging local production. New foundries and research hubs in Arizona and New York are expanding their capacities for both leading-edge and mature process technologies.
China
China's photolithography sector is propelled by national efforts to achieve semiconductor self-sufficiency and upgrade manufacturing capabilities. The Ministry of Ecology and Environment (MEE) imposes strict standards on emissions and waste, influencing equipment design and material choices. Key industrial clusters in the Yangtze River Delta and Pearl River Delta are building new fabs and enhancing existing ones, requiring a diverse range of lithography tools.
India
India represents a greenfield opportunity for photolithography, with national semiconductor initiatives aiming to establish foundational manufacturing capabilities. The government's Production Linked Incentive (PLI) scheme attracts investments in semiconductor fabrication and assembly, creating demand for DUV systems. Emerging semiconductor parks in Gujarat and Karnataka are poised to become hubs for chip manufacturing, necessitating new lithography infrastructure.
Photolithography Market Key Industry Players
Listed leaders compete with private specialists across the photolithography technology spectrum, reflecting a highly specialized and capital-intensive market. The industry structure bifurcates between a monopolistic segment for Extreme UV and a more competitive landscape for Deep UV technologies. Strategic partnerships between equipment suppliers and foundries, alongside continuous R&D investment, represent dominant competitive moves.
ASML Holdings represents the monopolistic control over the Extreme UV segment, providing critical technology for next-generation chip production. Nikon Corporation and Canon Inc. occupy a strong position within the mature Deep UV market, competing for share among foundries and integrated device manufacturers. These companies exemplify the tiered nature of the photolithography market, with distinct technology leadership and market access hierarchies.
| Leading Market Players |
|---|
| ASML Holdings |
| Nikon Corporation |
| Canon Inc. |
| JEOL Ltd. |
| SUSS MicroTec |
| EV Group |
| Veeco Instruments Inc. |
| NuFlare Technology |
| Rudolph Technologies |
| Others |
Cost & Logistics Intelligence
European Union chemical regulations under REACH, alongside US EPA and China MEE standards, gate supply qualification and simultaneously influence price differentiation for photoresists and lithography equipment. These regulatory frameworks demand specific material compositions and emission controls, directly impacting production costs and market access for suppliers.
Pricing Analysis
Product performance differentiation creates the primary spread in photolithography system pricing, reflecting resolution capabilities and throughput rates. The pricing model for advanced EUV and DUV systems remains largely transactional, involving high upfront capital investments. Customization levels for specific fab integration requirements and after-sales service contracts also drive price differentiation. Pricing pressure stems from the high capital intensity required by foundries, particularly for mature DUV systems. Research laboratories exhibit the most price-sensitive procurement behavior, while leading-edge foundries are least price-sensitive for EUV systems.
Supply Chain Analysis
Monopolistic control over Extreme UV system production by a single vendor creates a significant supply chain chokepoint. Geographic supply concentration centers on the Netherlands for EUV systems, with key optical components and specialized materials sourcing from Japan and Germany. Raw material dependencies include ultra-pure silicon wafers, specialized optical glass, and proprietary photoresist chemicals. Single-source vulnerability for EUV systems represents a critical structural risk. Equipment distribution runs through direct sales and long-term service partnerships with major foundries and integrated device manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a substitution defense strategy, navigating the threat of alternative patterning technologies and the high cost of advanced lithography. Incumbents must safeguard their technological lead against these emerging challenges.
For Market Incumbents:
Compound existing technological advantages by investing heavily in next-generation EUV research, specifically for higher numerical aperture systems. Expand long-term service partnerships with leading foundries in Taiwan and South Korea to deepen process integration and secure recurring revenue streams. Defend against emerging patterning techniques like Directed Self-Assembly by exploring hybrid lithography solutions that augment EUV capabilities.
For New Entrants and Emerging Players:
Anchor in specialized niches where DUV lithography remains competitive, such as advanced packaging or MEMS manufacturing. Target emerging foundry ecosystems in regions like India, where foundational manufacturing capabilities require established DUV systems. A go-to-market angle focusing on cost-effective, high-reliability DUV solutions for non-leading-edge applications offers a viable entry point.
For Investors and Strategic Acquirers:
Capital-intensity ratios are inflecting upwards across the advanced lithography segment, driven by EUV system costs. Long-term viability frames around companies with proprietary optical component manufacturing or advanced photoresist chemistry portfolios. Acquisition target archetypes include specialized suppliers of critical sub-components or firms developing novel patterning materials. The signal to watch is the adoption rate of High-NA EUV systems in leading foundries.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhance High-NA EUV R&D | Accelerates feature miniaturization for next-generation logic chips, extending technological leadership. |
| Expand Service and Support Networks | Deepens foundry relationships, ensuring optimal equipment performance and reducing operational downtime. |
| Invest in Advanced Photoresist Development | Optimizes material performance for EUV, improving yield and throughput in advanced manufacturing. |
| Strategic Partnerships in Emerging Regions | Secures market access and establishes a foothold in greenfield semiconductor manufacturing hubs. |
| Develop Hybrid Lithography Solutions | Combines EUV with complementary technologies to push resolution limits and reduce manufacturing steps. |
Research Approach
Desk research of industry reports, financial filings, and technical publications preceded structured interviews with R&D directors, fab managers, procurement leads, and regulatory specialists. This primary and secondary data collection facilitated a comprehensive understanding of market dynamics, triangulating insights from both top-down market sizing and bottom-up demand analysis.
Variance decomposition formed the basis of the analytical framework, segmenting the market by product type, technology, application, and end-user across the analysis window. This approach enabled detailed modeling of growth rates (CAGRs) derived from historical trends and projected technological shifts. Key forecast inputs included semiconductor capital expenditure cycles and global chip demand projections.
Material uncertainties — including geopolitical shifts affecting supply chains or unforeseen technological breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding market evolution and regulatory stability. Revision becomes warranted when significant changes in chip manufacturing investments or trade policies cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Wet Bench Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Dicing Equipment Market
Semiconductor Equipment
Wafer Chucks Market
Semiconductor Equipment
Africa Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Global Photoresist Market
Semiconductor Equipment
Semiconductor Dielectric Etching Equipment Market
Semiconductor Equipment
Global Sputtering Equipment Market
Semiconductor Equipment
Quantum Annealing Equipment Market
Semiconductor Equipment
Global Semiconductor Machinery Market
Semiconductor Equipment
Semiconductor CVD Equipment Market
Semiconductor Equipment
150mm Probe Station Market
Semiconductor Equipment
Lithographic Photomasks Market
Semiconductor Equipment
Semiconductor Capital Equipment Market
Semiconductor Equipment
Vacuum Chambers Market
Semiconductor Equipment
Asia-Pacific Semiconductor Etch Equipment Market