
 Optical Fiber Array Market | 2026-2036
Optical Fiber Array Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Fiber Array Market Insights
Project finance for captive cleanroom facilities is narrowing the field of viable competitors in precision fiber array manufacturing. Corning Incorporated leverages its in-house fused silica supply chain to sustain cost advantages at scale. Fujikura Ltd. anchors its position through backward integration into specialty fiber drawing operations in Japan. Sumitomo Electric Industries dominates submarine-grade array certification, a barrier few rivals navigate.
An optical fiber array is a precisely aligned assembly of multiple optical fibers fixed in a rigid substrate, typically manufactured using V-groove silicon etching or ceramic ferrule machining to achieve pitch tolerances below one micron; its primary purpose is to enable parallel optical signal transmission between photonic integrated circuits, transceivers, and backplane interconnects. High-density arrays command premium positioning in data center switch-to-switch links where port count per rack unit determines facility economics. Customized arrays capture expanding margin pools in medical technologies, where patient-specific endoscope configurations require non-standard fiber counts and bend radii. Standard arrays face commoditization pressure in telecommunications trunk lines, though volume throughput sustains producer cash flows.
FCC equipment authorization rules shape transceiver interoperability requirements that cascade into array connector specifications for US data center deployments. Japan's METI funding for photonics foundries accelerates domestic demand for embedded solutions with integrated array-to-chip coupling. REACH substance restrictions in Europe constrain epoxy and coating chemistries, forcing reformulation of fiber bonding adhesives. Stakeholders must monitor which regulatory jurisdiction certifies first on next-generation co-packaged optics, as that standard will likely propagate across supplier qualification programs worldwide.
Market Dynamics
Co-packaged optics architectures are collapsing traditional pluggable transceiver form factors, forcing fiber array suppliers to requalify products for tighter bend radii and reduced insertion loss budgets in data center switch designs.
Growth Catalysts
- Data Center Interconnect Bandwidth Surge:Hyperscale operators in Ashburn, Frankfurt, and Singapore are deploying 800G switch fabrics that demand parallel fiber counts exceeding 32 fibers per array. This density requirement sustains premium pricing for sub-micron pitch tolerance products.
- China's GB Standard Tightening:The country's national reliability standards for optical components now mandate extended thermal cycling tests that disqualify lower-grade imported arrays. Domestic certification accelerates substitution of foreign suppliers in state-funded infrastructure projects.
- Silicon Photonics Foundry Expansion:Japan's METI-funded photonics foundries in Tsukuba and Sendai are scaling embedded array-to-chip coupling processes. This integration trend pulls demand for customized V-groove substrates that match specific PIC geometries.
Market Restraints
- Fused Silica Supply Concentration:High-purity synthetic silica precursor production concentrates among three Japanese and German chemical suppliers. Any disruption to this feedstock cascades into six-month lead times for array substrate manufacturing.
- Submarine-Grade Certification Barriers:IEC 60794-2-20 deep-sea qualification requires 25-year reliability testing that few array assemblers can fund. This creates a permanent supply ceiling for undersea cable projects.
- Polymer Ferrule Substitution Threat:Molded liquid crystal polymer ferrules from Korean suppliers are penetrating cost-sensitive telecom trunk applications. These polymers tolerate wider pitch tolerances at one-third the ceramic cost.
Strategic Opportunities
- Medical Endoscope Customization:Patient-specific configurations requiring non-standard fiber counts and sub-millimeter bend radii command margin premiums three to five times standard telecom arrays. German and Swiss surgical device OEMs are consolidating supplier relationships.
- India's PLI Scheme for Telecom:Production-linked incentives for domestic optical component manufacturing are attracting cleanroom investments in Pune and Chennai. Early entrants capture qualification advantages for state-owned network tenders.
- Co-Packaged Optics Standardization:The first jurisdiction to certify next-generation CPO modules will propagate its fiber interface specifications globally. Suppliers aligned with that standard gain preferential access to hyperscale procurement programs.
Industry Challenges
- Precision Assembly Talent Scarcity:V-groove alignment technicians with sub-micron visual acuity are concentrated in Japan's Nagoya precision manufacturing corridor. Training cycles exceed 18 months, constraining capacity expansion.
- Cleanroom Capex Intensity:Class 1000 or better facilities for fiber array assembly require capital commitments exceeding $50 million per production line. This threshold narrows the viable competitor field to vertically integrated material suppliers.
- REACH Reformulation Timelines:European substance restrictions on epoxy chemistries force 12-18 month adhesive requalification cycles. Bonding failures during this transition period risk customer defection to qualified alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Fiber Array Market |
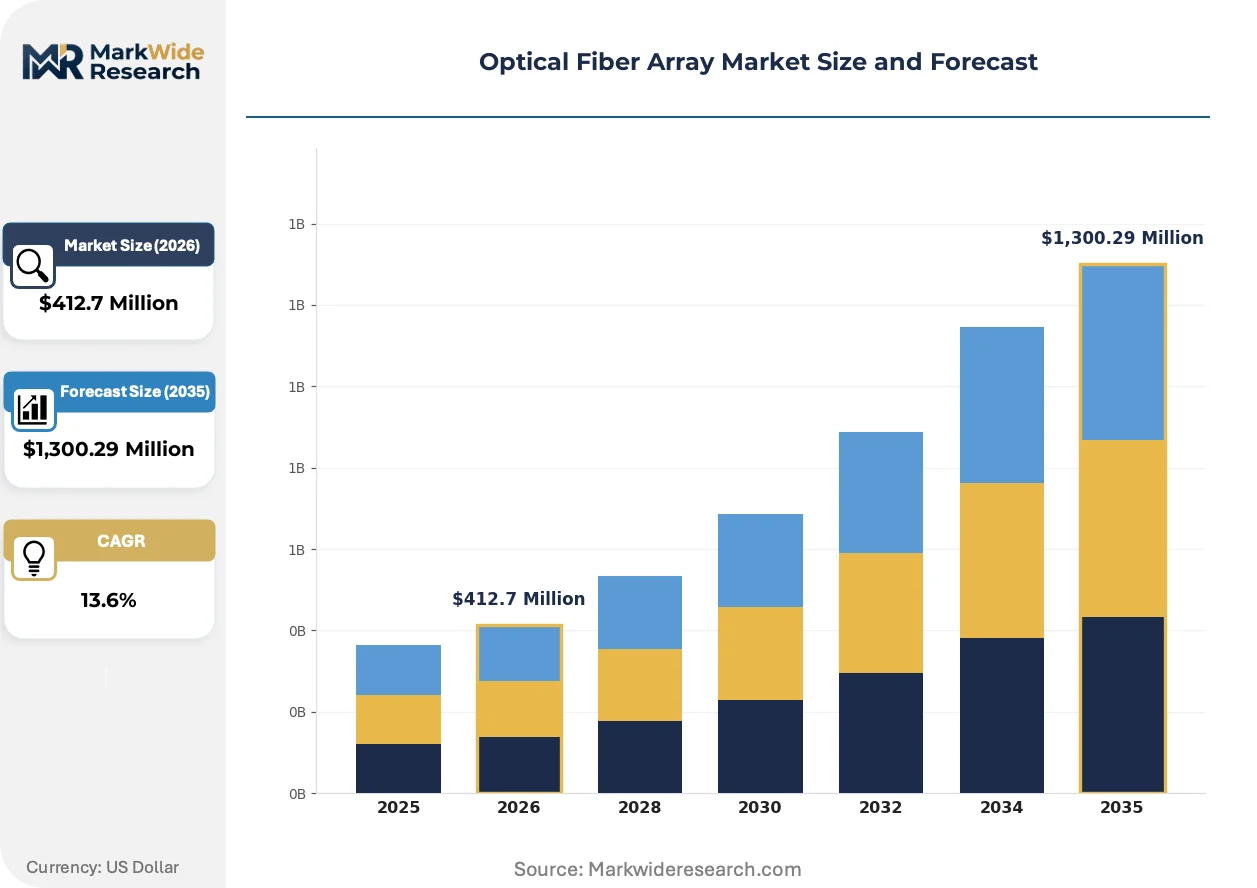
| Market Size in 2026 | $412.7 Million |
| Market Size in 2035 | $1,300.29 Million |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Array, Customized Array, Miniature Array, High-Density Array Application: Telecommunications, Data Centers, Aerospace, Medical Technologies End User: Telecom Operators, Research Institutions, Military, Healthcare Facilities Technology: Passive Components, Active Components, Embedded Solutions, Specialty Fibers |
| Companies Covered | Corning Incorporated, Fujikura Ltd., Sumitomo Electric Industries, Ltd., Molex LLC, Adamant Namiki Precision Jewel Co., Ltd., FiberTech Optica, OFS Fitel, LLC, TE Connectivity, Kohoku Kogyo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Fiber Array Market Trends and Innovations
Packaging density imperatives are compressing fiber array form factors while reliability standards harden across submarine, medical, and aerospace qualification tiers. Suppliers must simultaneously miniaturize and ruggedize.
Silicon nitride interposers are collapsing the traditional gap between fiber arrays and photonic integrated circuits. Hyperscale data center operators in Northern Virginia and the Netherlands are piloting these substrates for 51.2T switch co-packaged optics. The technology is collapsing legacy connectorized interfaces into direct chip-attach configurations that eliminate two optical junctions per link.
Japan's METI has expanded funding for domestic photonics foundries through fiscal 2025, conditioning grants on embedded optical I/O adoption. This policy is accelerating demand for array suppliers capable of wafer-level bonding to silicon photonics dies. Medical device manufacturers in Tokyo and Osaka are responding fastest, integrating these capabilities into endoscopic imaging systems.
Hyperscale buyers are consolidating optical component procurement under direct long-term supply agreements that bypass traditional distribution channels. Cloud operators in Dublin, Singapore, and São Paulo now specify fiber array performance at the switch subsystem level rather than through transceiver vendors. This pattern is most visible in 800G deployment programs where array qualification delays risk entire platform launches.
Optical Fiber Array Market Segmentation
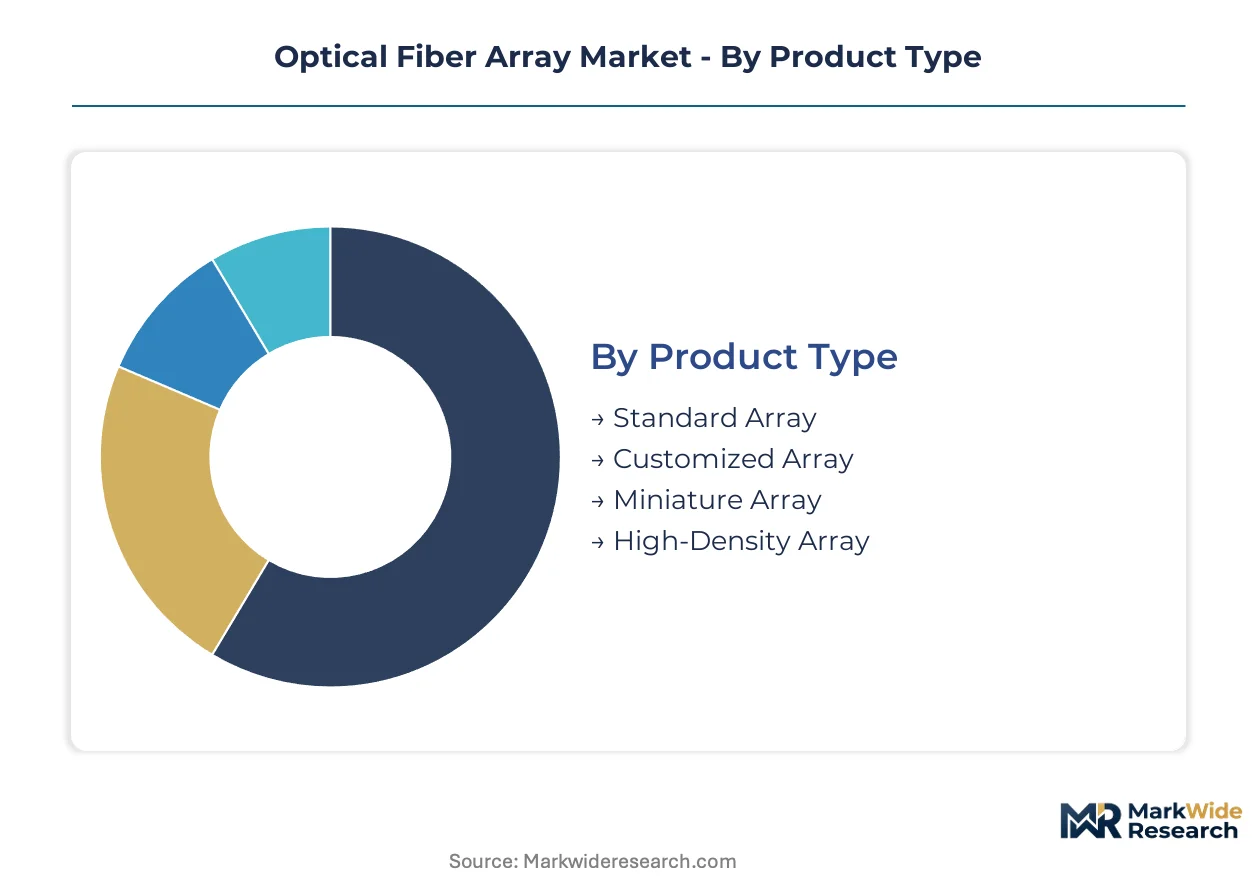
Segmentation in optical fiber arrays determines qualification pathways, pricing tiers, and supplier-customer bonding intensity. Technical specifications diverge sharply across end-use verticals, with medical and submarine applications demanding dedicated service relationships that standard telecom deployments rarely require.
Product Type:
After-sales service intensity escalates dramatically from standard catalog products to patient-specific medical configurations, with field support engineers embedding directly at customer cleanrooms for high-density array deployments.
- Standard Array:Mass-produced V-groove assemblies with fixed fiber counts and pitch tolerances serve telecommunications trunk lines. Procurement concentrates among tier-one operators in Germany and Japan who prioritize volume pricing over customization support.
- Customized Array:Patient-specific medical endoscope configurations require non-standard fiber counts and sub-millimeter bend radii. German and Swiss surgical device OEMs demand 24-hour engineering response and dedicated bonding technicians.
- Miniature Array:Compact form factors for aerospace avionics and portable diagnostic equipment.
- High-Density Array:Sub-micron pitch tolerances for 800G data center switch fabrics with embedded field application engineering.
By volume, Standard Array leads. By growth pace, Customized Array is ahead.
Application:
Application-driven cost tiers separate commodity interconnects from mission-critical deployments where failure costs dwarf component pricing.
- Telecommunications:Long-haul trunk lines and metro networks deploy standard pitch arrays with ceramic ferrules. Chinese state-funded infrastructure projects now mandate GB-certified domestic suppliers, displacing lower-grade imports.
- Data Centers:Hyperscale operators in Northern Virginia and the Netherlands pilot silicon nitride interposers for 51.2T co-packaged optics switch fabrics. Direct procurement agreements bypass traditional distribution.
- Aerospace:Radiation-hardened arrays for satellite optical interconnects with extended qualification cycles.
- Medical Technologies:Endoscopic imaging systems in Tokyo and Osaka integrate wafer-level bonded arrays with embedded optical I/O.
Telecommunications generates the highest shipment volumes. Medical Technologies commands the steepest expansion trajectory.
End User:
Customer type determines contract structure, with military and healthcare buyers insisting on multi-year service level agreements that telecom operators rarely match.
- Telecom Operators:Volume procurement through consolidated optical component programs with standardized qualification. India's PLI scheme attracts cleanroom investments in Pune and Chennai for state-owned network tenders.
- Research Institutions:Tsukuba and Sendai photonics foundries drive embedded array-to-chip coupling demand with METI-funded grants.
- Military:Submarine-grade IEC 60794-2-20 certification requirements with 25-year reliability testing.
- Healthcare Facilities:Patient-specific configurations requiring dedicated application engineering and rapid prototyping support.
Telecom Operators anchor procurement scale. Healthcare Facilities are gaining share fastest.
Technology:
Technology maturity separates established passive interconnects from emerging active and embedded solutions requiring co-development partnerships.
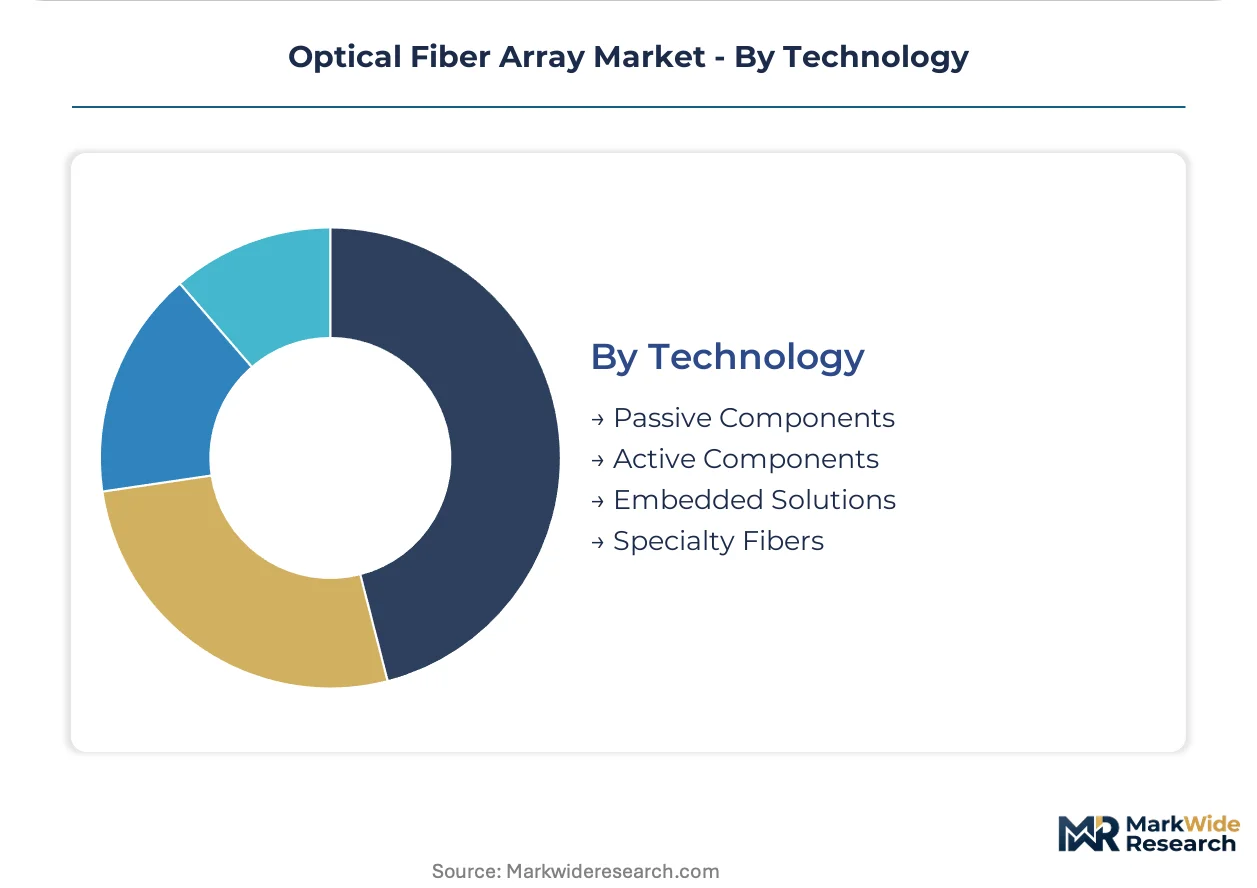
- Passive Components:Standard V-groove silicon substrates and ceramic ferrules dominate established telecommunications and data center applications with proven reliability records.
- Active Components:Transceiver-integrated arrays with signal conditioning electronics for high-speed switch fabrics. FCC equipment authorization rules shape interoperability specifications.
- Embedded Solutions:Wafer-level bonding to photonic integrated circuits eliminates connectorized interfaces. METI funding accelerates domestic adoption in Japan.
- Specialty Fibers:Polarization-maintaining and rare-earth-doped configurations for sensing and amplification applications.
Passive Components still dominates unit economics. Embedded Solutions shows the most rapid technology adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI funding for photonics foundries is accelerating embedded optical I/O adoption across precision manufacturing clusters. China's GB standard tightening is reshaping supplier qualification requirements for state-funded infrastructure. Germany's REACH enforcement is forcing adhesive reformulation timelines that cascade through European supply chains.
United States
FCC equipment authorization rules govern transceiver interoperability specifications that cascade into array connector requirements for hyperscale data center deployments. Northern Virginia operators pilot silicon nitride interposers for 51.2T switch fabrics. Ashburn facilities specify fiber array performance at the switch subsystem level rather than through transceiver vendors.
China
GB standards for optical component reliability now mandate extended thermal cycling tests that disqualify lower-grade imported arrays. State-funded infrastructure projects accelerate substitution of foreign suppliers. Domestic certification requirements concentrate procurement among qualified local fabricators in Shenzhen and Wuhan.
Japan
METI funding through fiscal 2025 conditions grants on embedded optical I/O adoption in domestic photonics foundries. Tsukuba and Sendai facilities scale array-to-chip coupling processes. Nagoya's precision manufacturing corridor concentrates V-groove alignment technicians with sub-micron visual acuity.
Germany
REACH substance restrictions constrain epoxy and coating chemistries used in fiber bonding adhesives. Surgical device OEMs in Munich and Stuttgart demand 24-hour engineering response for patient-specific endoscope configurations. Reformulation cycles extend 12-18 months, risking customer defection during transition periods.
India
PLI scheme incentives for domestic optical component manufacturing attract cleanroom investments in Pune and Chennai. State-owned network tenders favor early entrants with qualification advantages. Production-linked incentives narrow viable competitor fields to vertically integrated material suppliers with capital commitments exceeding threshold levels.
Optical Fiber Array Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated material suppliers with captive cleanroom capabilities. Three archetypes dominate: fused silica supply chain owners, specialty fiber drawing operators, and submarine-grade certification holders. Competitive moves center on backward integration into precursor production and strategic partnerships with photonics foundries for embedded solution co-development.
Within the certification-intensive tier, Sumitomo Electric Industries, Ltd. occupies a position exemplifying submarine-grade array qualification. Among precision manufacturing specialists, Fujikura Ltd. and Adamant Namiki Precision Jewel Co., Ltd. represent archetypes of backward integration into specialty fiber operations and micron-tolerance machining respectively. Corning Incorporated anchors the material-integrated segment through in-house fused silica supply chain control.
| Leading Market Players |
|---|
| Corning Incorporated |
| Fujikura Ltd. |
| Sumitomo Electric Industries, Ltd. |
| Molex LLC |
| Adamant Namiki Precision Jewel Co., Ltd. |
| FiberTech Optica |
| OFS Fitel, LLC |
| TE Connectivity |
| Kohoku Kogyo |
| Others |
Pricing and Supply Chain Analysis
Fused silica precursor concentration among three Japanese and German chemical suppliers determines both the premium-to-commodity spread across certification tiers and the geographic clustering of viable array manufacturing. This single-source dependency cascades into six-month substrate lead times that compress margins for unintegrated assemblers while rewarding captive supply chain owners with pricing power at the high-density end of the market.
Pricing Analysis
Certification level creates the primary spread between submarine-grade IEC 60794-2-20 qualified arrays and standard telecom configurations. Pricing stratifies across premium, standard, and economy tiers with medical endoscope customization commanding three-to-five-fold premiums over trunk-line commodity products. Cost compression in standard arrays is intensifying because Korean polymer ferrule substitutes tolerate wider pitch tolerances at one-third ceramic cost. Telecom operators exhibit highest price sensitivity while surgical device OEMs in Germany and Switzerland prioritize 24-hour engineering response over unit economics.
Supply Chain Analysis
Contract manufacturing for V-groove silicon etching concentrates among precision machining specialists in Japan's Nagoya corridor and ceramic ferrule fabricators in China's Shenzhen hub. High-purity synthetic silica feedstock draws from Japanese and German chemical suppliers while specialty fiber drawing rests on backward-integrated operations in Japan. Single-source vulnerability in precursor production represents the dominant structural risk. Distribution runs through direct long-term supply agreements that hyperscale operators in Northern Virginia and the Netherlands now specify at the switch subsystem level.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Co-packaged optics architectures are collapsing traditional pluggable transceiver form factors, creating a high-growth disruption window as fiber array suppliers requalify products for tighter bend radii and reduced insertion loss budgets.
For Market Incumbents: Build certification moats around submarine-grade IEC 60794-2-20 qualification and METI-funded photonics foundry partnerships. Sumitomo Electric Industries anchors this position through 25-year reliability testing capabilities that few rivals can fund. Corning Incorporated sustains advantage through in-house fused silica supply chain control that compresses substrate lead times. Defend against Korean polymer ferrule substitution by embedding field application engineers at hyperscale data center operators. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme for telecom by securing cleanroom investments in Pune or Chennai before state-owned network tenders consolidate qualification advantages. Target patient-specific medical endoscope configurations where German and Swiss surgical device OEMs demand rapid prototyping support and pay premium multiples. Pursue co-development partnerships with Tsukuba and Sendai photonics foundries for wafer-level bonding capabilities. For Investors and Strategic Acquirers: METI funding through fiscal 2025 reshapes the acquisition landscape by conditioning grants on embedded optical I/O adoption, favoring targets with proven array-to-chip coupling processes. Over the projection horizon, vertically integrated material suppliers with captive cleanroom capabilities and Class 1000 or better facilities represent the most defensible acquisition archetype. Monitor which jurisdiction certifies first on next-generation co-packaged optics as the signal for which supplier qualification programs will propagate globally.| Strategic Initiative | Industry Significance |
|---|---|
| Submarine-Grade Certification Investment | IEC 60794-2-20 qualification creates permanent supply ceiling for undersea cable projects. |
| Photonics Foundry Partnership | METI-funded Tsukuba and Sendai facilities accelerate embedded array-to-chip coupling demand. |
| Cleanroom Capacity Expansion | Class 1000 facilities in Pune and Chennai capture PLI scheme advantages for state tenders. |
| Specialty Fiber Drawing Integration | Backward integration into fiber operations secures pitch tolerance control for medical configurations. |
| Direct Procurement Agreement | Hyperscale operators in Ashburn and Frankfurt now specify performance at switch subsystem level. |
Research Methodology
A spread of perspectives from V-groove alignment technicians, photonics foundry process engineers, hyperscale data center procurement directors, and surgical device OEM supply chain managers converged on the working assumptions underlying this analysis. Primary fieldwork combined with secondary validation from SEC filings of listed optical component suppliers, METI grant disbursement records, and GB standard certification databases. Bottom-up unit economics across fiber count and pitch tolerance tiers were triangulated against top-down market sizing from telecommunications infrastructure deployment trackers.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by product type, application vertical, end-user contract structure, and technology maturity tier. CAGRs were derived from installed base replacement cycles for 800G switch fabrics and penetration curves for co-packaged optics architectures. Forecast inputs incorporated hyperscale capex disclosures for Northern Virginia and Netherlands facilities alongside India's PLI scheme cleanroom investment timelines.
Stress conditions across fused silica supply disruption, REACH adhesive reformulation delays, and polymer ferrule substitution velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about METI funding continuity and GB standard enforcement intensity. Quarterly review of certification jurisdiction progress and hyperscale direct procurement contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Faraday Rotator Market
Optical Components
100G Optical Transceivers Market
Optical Components
Low-E Glass Magnetron Sputtering Coating Line Market
Optical Components
High Power Double-Clad Fiber Bragg Grating Market
Optical Components
Fluorophore Market
Optical Components
Optical Amplifier Market
Optical Components
Europe Tunable Laser Market
Optical Components
Erbium-Doped Fiber Amplifier Market
Optical Components
Global Optical Coating Equipment Market
Optical Components
CW Fiber Amplifier Market
Optical Components
Global Adaptive Optics Market
Optical Components
Silicon Photonics Market
Optical Components
Optical Film Market
Optical Components
North America Lithium Niobate Modulator Market
Optical Components
Global Non Dispersive Infrared (NDIR) Market
Optical Components
Nonlinear Optical Crystals Market