
 Underfill Dispenser Market | 2026-2036
Underfill Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Underfill Dispenser Market Analytics
Buyer concentration among semiconductor companies and large electronics manufacturers is hardening as advanced packaging scales drive volume commitments toward fewer, larger vendors. Nordson Corporation leverages its precision fluid management portfolio to sustain leadership in jet dispensing architectures. Henkel AG & Co. KGaA anchors its position through integrated adhesive and equipment offerings that reduce process variability for high-volume chipmakers. ASM Pacific Technology Ltd. differentiates via deep specialization in flip chip and wafer-level packaging workflows across Asian manufacturing clusters.
An underfill dispenser is a precision fluid deposition system engineered to deliver controlled volumes of liquid encapsulant—typically epoxy-based formulations with filler particles below 10 micrometers—beneath semiconductor dies to reinforce solder interconnects against thermal-mechanical stress. Automated dispensers dominate capital expenditure budgets as semiconductor fabs prioritize throughput rates exceeding 50,000 units per hour, while jet dispensing technology leads growth trajectories due to its non-contact accuracy at tight pad pitches below 40 micrometers. Manual dispensers retain niche positions in medical device maker workflows where batch sizes remain small and validation protocols favor operator oversight over cycle speed.
FDA device manufacturing regulations and ISO 13485 quality standards constrain material selection and process documentation for medical device makers, while EPA hazardous air pollutant rules shape solvent-based formulation availability across US electronics manufacturing. The EU RoHS directive and REACH chemical restrictions in Europe compel reformulation of underfill chemistries to eliminate restricted substances without sacrificing capillary flow properties. Stakeholders must monitor how emerging packaging architectures—hybrid bonding, chiplets, and 3D stacking—alter dispense pattern complexity and material property requirements before committing to next-generation equipment platforms.
Market Dynamics
Semiconductor packaging architectures are compressing pad pitches below 40 micrometers while simultaneously demanding throughput rates exceeding 50,000 units per hour, forcing equipment vendors to reconcile precision with speed in ways that reshape capital allocation patterns across the supply base.
Growth Catalysts
- Flip chip packaging migration:Advanced packaging facilities in Taiwan and South Korea are converting wire bond lines to flip chip workflows, generating installed base refresh cycles for jet dispensing platforms capable of non-contact deposition at tight geometries.
- EU RoHS and REACH compliance:Mercury-free underfill formulation mandates are accelerating equipment replacement timelines as legacy chemistries lose regulatory authorization across European electronics manufacturing.
- China advanced packaging buildout:OSATs and IDMs are constructing massive capacity for 2.5D and 3D integration, concentrating demand for high-throughput automated dispensers in Shanghai, Wuxi, and Beijing manufacturing clusters.
Market Restraints
- Specialized nozzle supply concentration:Precision tungsten carbide and ceramic dispensing nozzles for sub-50 micrometer applications depend on a concentrated supplier base in Japan and Germany, creating input vulnerability.
- Epoxy resin price volatility:Underfill formulations rely on bisphenol-A and specialty hardener feedstocks exposed to petrochemical cycle swings and force majeure events at BASF and Huntsman production sites.
- Capillary flow physics limitations:Conventional capillary underfill materials face fundamental viscosity constraints below 10 micrometer gap heights, restricting applicability in hybrid bonding transitions.
Strategic Opportunities
- India semiconductor packaging emergence:Micron Technology's Gujarat assembly and test facility and Tata Electronics' planned OSAT operations create first-mover equipment positioning windows for dispensing system vendors.
- Medical device microelectronics:FDA-regulated pacemaker and neuromodulator manufacturers require validated manual dispensing workflows for die-attach and underfill, commanding premium pricing and long-term service contracts.
- AI accelerator chiplet architectures:AMD and Intel chiplet-based GPU and AI processor designs multiply die count per package, increasing underfill dispense pattern complexity and material volume per unit.
Industry Challenges
- Multiphysics simulation talent scarcity:Fluid dynamics and thermal-mechanical modeling expertise for optimizing dispense patterns in heterogeneous integration packages remains concentrated among a small cohort of PhD-level specialists.
- ISO 13485 and IATF 16949 certification timelines:Medical and automotive qualification protocols extend equipment validation cycles to 18-24 months, compressing vendor revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underfill Dispenser Market |
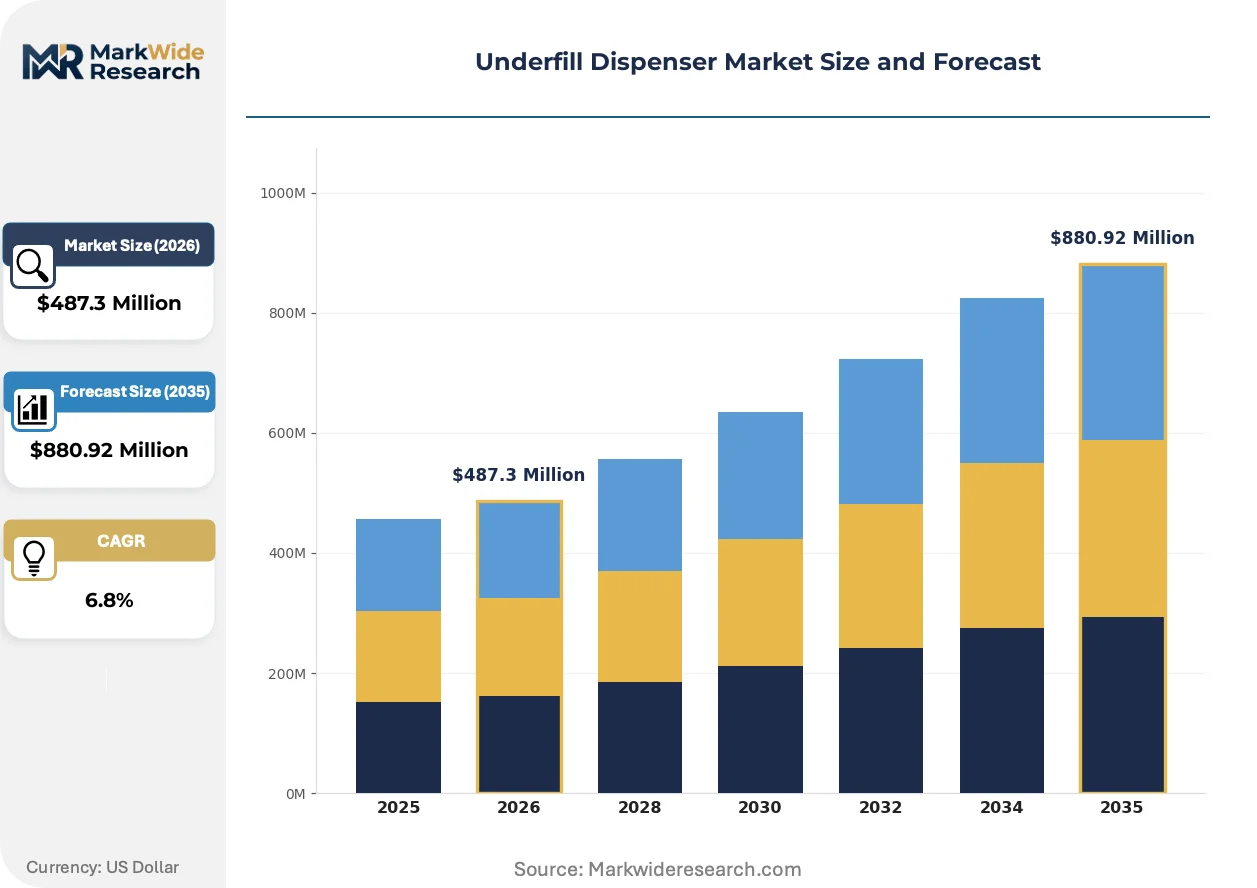
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Dispensers, Manual Dispensers, Benchtop Dispensers, Inline Dispensers End User: Electronics Manufacturers, Semiconductor Companies, Automotive OEMs, Medical Device Makers Technology: Jet Dispensing, Needle Dispensing, Mass Flow Dispensing, Non-Contact Dispensing Application: Surface Mount Technology, Underfill Applications, Chip-on-Board Assembly, Flip Chip Bonding |
| Companies Covered | Shenzhen STIHOM Machine Electronics, Master Bond, Henkel AG & Co. KGaA, Essemtec AG, Zmation, Nordson Corporation, Illinois Tool Works, ASM Pacific Technology Ltd., MKS Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underfill Dispenser Market Evolving Landscape
Jet dispensing architectures are displacing time-pressure and auger systems as the dominant capital equipment category, while regulatory chemistry constraints and buyer consolidation are simultaneously reshaping vendor competitive requirements.
Laser-integrated dispensing heads are unifying real-time bead inspection with closed-loop volume correction in single-platform architectures. OSATs in Taiwan and memory manufacturers in South Korea are adopting these systems at replacement cycle pace. This convergence is unifying process control and deposition functions that previously required separate capital equipment, compressing cleanroom footprint and qualification overhead for advanced packaging lines.
REACH authorization restrictions on boron-containing epoxy hardeners are forcing reformulation of capillary underfill chemistries across European electronics manufacturing. ECHA's sunset date enforcement is eliminating legacy product lines from authorized supply chains. Automotive radar module producers in Germany and medical device manufacturers in Switzerland are accelerating supplier audits to secure compliant material streams before authorization deadlines.
Consolidated procurement through semiconductor equipment consortia is displacing individual fab purchasing for dispensing platforms. TSMC's supplier rationalization program and Intel's copy-exact methodology are concentrating vendor selection authority at corporate engineering centers rather than site procurement teams. This concentration is most visible in Arizona and Oregon fab construction projects, where equipment qualification decisions now occur 12-18 months ahead of tool installation.
Underfill Dispenser Market Segmentation
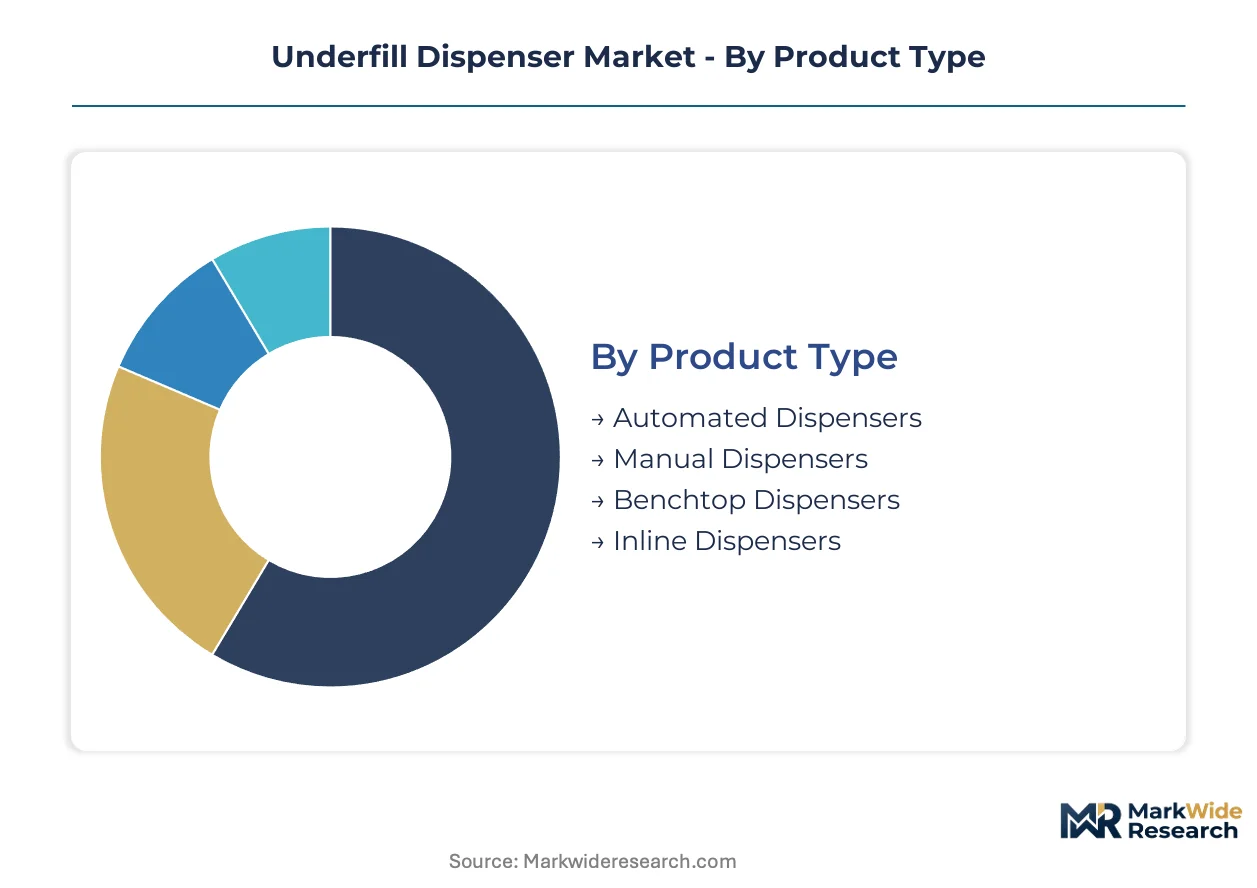
Equipment refresh cycles in advanced packaging fabs create divergent growth trajectories across dispenser categories. Semiconductor manufacturers prioritize throughput and precision specifications that reshape vendor R&D allocation and pricing power across each segment dimension.
Product Type:
Upgrade cycles favor platforms that reconcile speed with micron-level accuracy as pad pitches compress below 40 micrometers.
- Automated Dispensers:High-throughput systems integrate vision alignment and closed-loop pressure control for continuous production lines exceeding 50,000 units per hour. Demand concentrates at TSMC and Samsung packaging facilities where copy-exact methodology mandates vendor consolidation.
- Jet Dispensers:Non-contact deposition architectures eliminate Z-axis movement delays, enabling sub-50 micrometer pitch accuracy at speeds matching time-pressure systems. OSATs in Taiwan and memory manufacturers in South Korea drive replacement demand as flip chip lines displace wire bond capacity.
- Manual Dispensers:Operator-controlled systems serve FDA-regulated medical device workflows where batch validation protocols override cycle speed requirements.
- Benchtop Dispensers:Compact units address R&D prototyping and low-volume automotive radar module pilot lines in Germany and Michigan.
- Inline Dispensers:Conveyor-integrated systems support high-mix electronics contract manufacturing in Shenzhen and Penang.
Automated dispensers sit at the top of the volume ranking, with jet dispensers climbing the fastest.
End User:
Customer procurement authority is migrating from site-level buyers to corporate engineering centers as scale concentrates.
- Semiconductor Companies:IDMs and foundries mandate equipment platforms capable of supporting heterogeneous integration roadmaps including chiplets and 3D stacking. Intel's Arizona and Oregon fab construction projects concentrate qualification decisions 12-18 months ahead of installation.
- Electronics Manufacturers:Contract assemblers in Vietnam and Mexico prioritize flexible dispensing platforms that accommodate rapid product changeovers for consumer electronics.
- Automotive OEMs:Tier-1 suppliers in Stuttgart and Detroit require IATF 16949-certified equipment for ADAS module underfill, extending validation cycles to 18-24 months.
- Medical Device Makers:Pacemaker and neuromodulator manufacturers in Switzerland and Minnesota command premium pricing for validated manual workflows with long-term service contracts.
Semiconductor companies command the largest equipment budgets, while medical device makers sustain the highest margin per unit.
Technology:
Deposition physics and control architectures determine applicability across shrinking pad geometries and novel package form factors.
- Jet Dispensing:Piezoelectric valve systems eject discrete droplets without substrate contact, eliminating wire sweep in fine-pitch applications. Taiwan OSATs deploy these systems for memory and logic device advanced packaging at replacement cycle pace.
- Needle Dispensing:Time-pressure and auger-driven contact deposition retains cost advantages in larger-pitch consumer electronics assembly.
- Mass Flow Dispensing:Continuous extrusion systems serve automotive power module and industrial electronics applications where bead consistency outweighs pitch miniaturization.
- Non-Contact Dispensing:Laser-integrated heads unify real-time bead inspection with closed-loop volume correction, compressing cleanroom footprint for advanced packaging lines in South Korea.
Jet dispensing dominates new capital allocation, with laser-integrated non-contact systems expanding most quickly.
Application:
Package architecture evolution redefines dispense pattern complexity and material property requirements.
- Flip Chip Bonding:Capillary underfill flows beneath dies mounted face-down on substrates, reinforcing solder interconnects against thermal-mechanical stress. China OSATs in Shanghai and Wuxi build massive capacity for 2.5D and 3D integration.
- Underfill Applications:Edge and corner dispensing variants address chip-on-board and ball grid array reinforcement requirements in communications infrastructure.
- Surface Mount Technology:SMT underfill protects leadless and small-outline packages in automotive and industrial electronics subject to vibration and thermal cycling.
- Chip-on-Board Assembly:Direct die attach to PCB substrates serves LED lighting and power electronics where package cost minimization drives process selection.
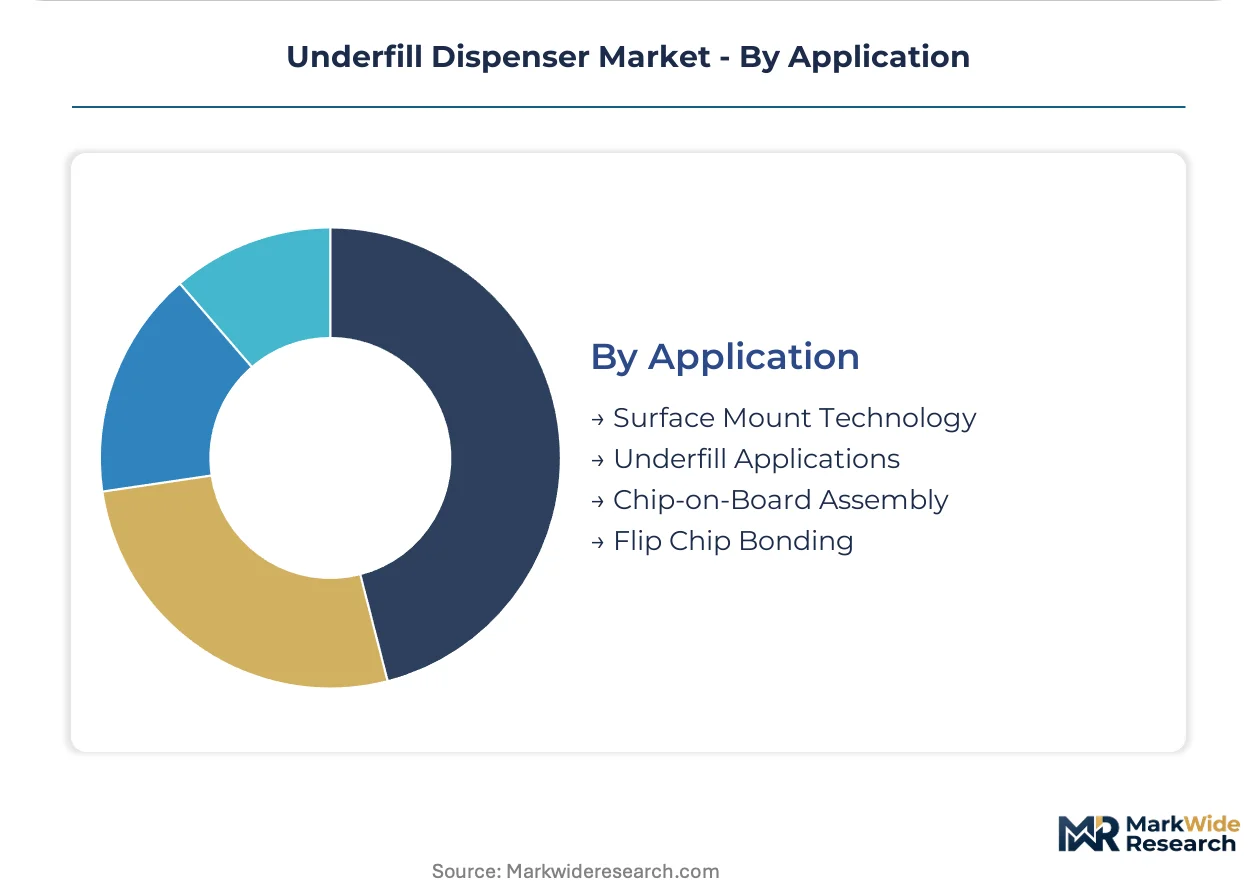
Flip chip bonding anchors equipment revenue, with underfill applications for heterogeneous integration gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fluid dynamics engineers and precision manufacturing technicians concentrate in Taiwan, South Korea, and Germany, anchoring the geographic distribution of underfill dispenser demand. These talent clusters align with advanced packaging fab locations and precision equipment supply chains. Regional procurement patterns diverge based on regulatory timelines and packaging technology roadmaps.
United States
Intel's Arizona and Oregon fab construction projects drive capital equipment commitments for heterogeneous integration packaging. EPA hazardous air pollutant rules constrain solvent-based formulation availability across domestic electronics manufacturing. Equipment qualification decisions in Chandler and Hillsboro now occur 12-18 months ahead of tool installation, compressing vendor revenue recognition windows.
China
OSATs and IDMs are constructing massive capacity for 2.5D and 3D integration in Shanghai, Wuxi, and Beijing manufacturing clusters. MIIT industrial policy and dual carbon goals shape equipment energy efficiency requirements and local content preferences. Capillary underfill demand concentrates in Yangtze River Delta packaging facilities serving domestic memory and logic device production.
Germany
Automotive radar module producers in Stuttgart and medical device manufacturers in Switzerland accelerate supplier audits for REACH-compliant material streams. ECHA sunset date enforcement on boron-containing epoxy hardeners eliminates legacy product lines from authorized supply chains. Precision equipment fabricators in Baden-Württemberg supply tungsten carbide dispensing nozzles for sub-50 micrometer applications.
South Korea
Memory manufacturers drive replacement demand for jet dispensing platforms as flip chip lines displace wire bond capacity. MFDS pharmaceutical regulations and industrial chemical controls shape medical device manufacturing workflows. Samsung and SK Hynix packaging facilities in Suwon and Icheon prioritize throughput rates exceeding 50,000 units per hour.
Japan
Precision tungsten carbide and ceramic dispensing nozzle suppliers concentrate in Osaka and Nagoya industrial corridors. METI technology roadmaps for semiconductor packaging guide equipment R&D allocation toward sub-40 micrometer pitch applications. Materials suppliers in Kansai region face feedstock volatility from petrochemical cycle swings affecting bisphenol-A and specialty hardener availability.
Underfill Dispenser Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment and materials segments, creating a tiered vendor structure. The market exhibits moderate consolidation with three to five dominant players capturing majority capital expenditure flows. Strategic archetypes include integrated adhesive-equipment providers, precision fluid management specialists, and regional fabrication equipment houses. Competitive moves center on supplier rationalization program compliance and copy-exact methodology adoption by semiconductor foundries.
Within the integrated materials-equipment tier, Henkel AG & Co. KGaA anchors a position through combined adhesive and dispensing system offerings. Among precision fluid management specialists, Nordson Corporation and ASM Pacific Technology Ltd. occupy positions serving high-volume chipmaker workflows. Illinois Tool Works and MKS Instruments exemplify diversified industrial conglomerates with electronics assembly equipment portfolios. Shenzhen STIHOM Machine Electronics represents Chinese regional fabrication capacity serving domestic OSAT demand.
| Leading Market Players |
|---|
| Shenzhen STIHOM Machine Electronics |
| Master Bond |
| Henkel AG & Co. KGaA |
| Essemtec AG |
| Zmation |
| Nordson Corporation |
| Illinois Tool Works |
| ASM Pacific Technology Ltd. |
| MKS Instruments |
| Others |
Value Network & Pricing Analysis
Precision tungsten carbide nozzle costs cascade from Osaka and Nagoya fabricators through three distinct equipment tiers, with REACH-compliant chemistry premiums layering onto base hardware pricing for European-bound shipments.
Pricing Analysis
Bundled adhesive-equipment packages command 15-25% premiums over standalone hardware sales, while unbundled dispensing systems compete on throughput specifications alone. Price differentiation hinges on ISO 13485 certification tier for medical device workflows and volume scale commitments from semiconductor foundries. Cost compression in mid-tier automated dispensers intensifies as Chinese OSATs consolidate procurement through equipment consortia. Contract assemblers in Vietnam and Mexico exhibit highest price sensitivity, whereas Swiss pacemaker manufacturers accept premium pricing for validated manual workflows with decade-long service agreements.
Supply Chain Analysis
Workforce availability for precision fluid dynamics engineering concentrates in Taiwan, South Korea, and Germany, anchoring fabrication capacity and vendor R&D centers. Tungsten carbide nozzles, piezoelectric valve assemblies, and bisphenol-A epoxy feedstocks draw from Japanese, German, and US chemical production clusters. Single-source vulnerability in sub-50 micrometer ceramic nozzle supply creates exposure to force majeure events. Distribution runs through semiconductor equipment OEMs and direct sales to IDM corporate engineering centers, bypassing traditional industrial distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment vendors can exploit geographic arbitrage between REACH-mandated chemistry reformulation costs in Europe and unregulated formulation availability in Asian manufacturing clusters, capturing margin from dual-track product line strategies.
For Market Incumbents: Acquire precision nozzle fabrication capabilities to reduce dependence on Osaka and Nagoya suppliers. Consolidate adhesive-equipment bundling advantages before copy-exact methodology standardizes vendor selection at Intel and TSMC. Invest in IATF 16949 certification capacity to capture automotive radar module demand in Stuttgart and Detroit. For New Entrants and Emerging Players: Begin with validated manual dispensing workflows for FDA-regulated neuromodulator manufacturers in Minnesota and Switzerland, where premium pricing sustains smaller-scale operations. Target India's emerging OSAT capacity in Gujarat before incumbent qualification cycles conclude. Position through long-term service contracts rather than equipment-only sales. For Investors and Strategic Acquirers: Consolidation pressure builds where jet dispensing architecture R&D costs exceed $50 million annual burn rates, forcing mid-cap specialists toward strategic sale. Five-to-ten-year viability favors integrated materials-equipment providers with captive adhesive chemistry. Watch for ECHA sunset date enforcement on boron-containing hardeners as inflection signal for compliant-formulation equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nozzle Fabrication | Captive tungsten carbide supply secures sub-50 micrometer precision against Japanese supplier concentration. |
| REACH-Compliant Chemistry Certification | ECHA authorization timelines determine European market access for capillary underfill equipment lines. |
| India Manufacturing Footprint Establishment | Micron Gujarat and Tata Electronics OSAT operations create first-mover positioning windows. |
| Laser-Integrated Head Platform Launch | Unified inspection-deposition architectures compress cleanroom footprint for Samsung and SK Hynix lines. |
| Medical Device Workflow Validation Partnership | FDA-regulated pacemaker manufacturers command decade-long service contracts at premium pricing. |
Research Methodology
Coverage spans Asia-Pacific, North America, and Europe, with primary inputs from each region's advanced packaging clusters. Semiconductor equipment procurement directors, fluid dynamics R&D leads, OSAT operations managers, and epoxy formulation chemists provided structured interviews. Secondary validation drew from SEC 10-K filings, ECHA REACH authorization databases, SEMI equipment market data, and customs trade records. Bottom-up unit demand estimates triangulated against top-down capital expenditure forecasts.
Granularity-level modeling operated at equipment type, end-user industry, deposition technology, and regional manufacturing cluster dimensions across the projection horizon. CAGRs derived from regression analysis of historical capital intensity ratios and forward-looking fab capacity announcements. Forecast inputs incorporated MIIT policy targets for Chinese domestic packaging capacity, Intel copy-exact vendor consolidation timelines, and ECHA sunset date enforcement schedules.
Several conditions sit outside the modeled scope, including force majeure events at BASF or Huntsman chemical production sites, abrupt shifts in US EPA hazardous air pollutant enforcement, and breakthrough hybrid bonding technologies eliminating capillary underfill demand. Forecasts reflect documented assumptions about regulatory timeline adherence and foundry capacity buildout pacing. Material deviation in REACH authorization enforcement or China dual carbon policy implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Lithography Systems Market
Semiconductor Equipment
Laser Micro Perforation Equipment Market
Semiconductor Equipment
Middle East and Africa Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Dicing Equipment Market
Semiconductor Equipment
SMT Reflow Soldering Equipment Market
Semiconductor Equipment
Photoresist for Semiconductor Market
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
Semiconductor Equipment Market
Semiconductor Equipment
Global Capacitor Winding Machines Market
Semiconductor Equipment
India Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Vacuum Chambers Market
Semiconductor Equipment
Semiconductor Wafer Process Control Equipment Market
Semiconductor Equipment
Global Tamping Machine Market
Semiconductor Equipment
Global Semiconductor Front-End Equipment Market
Semiconductor Equipment
Molecular Beam Epitaxy System Market
Semiconductor Equipment
North America Battery Manufacturing Equipment Market