
 Partition Inserter Machines Market | 2026-2036
Partition Inserter Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Partition Inserter Machines Market Analytics
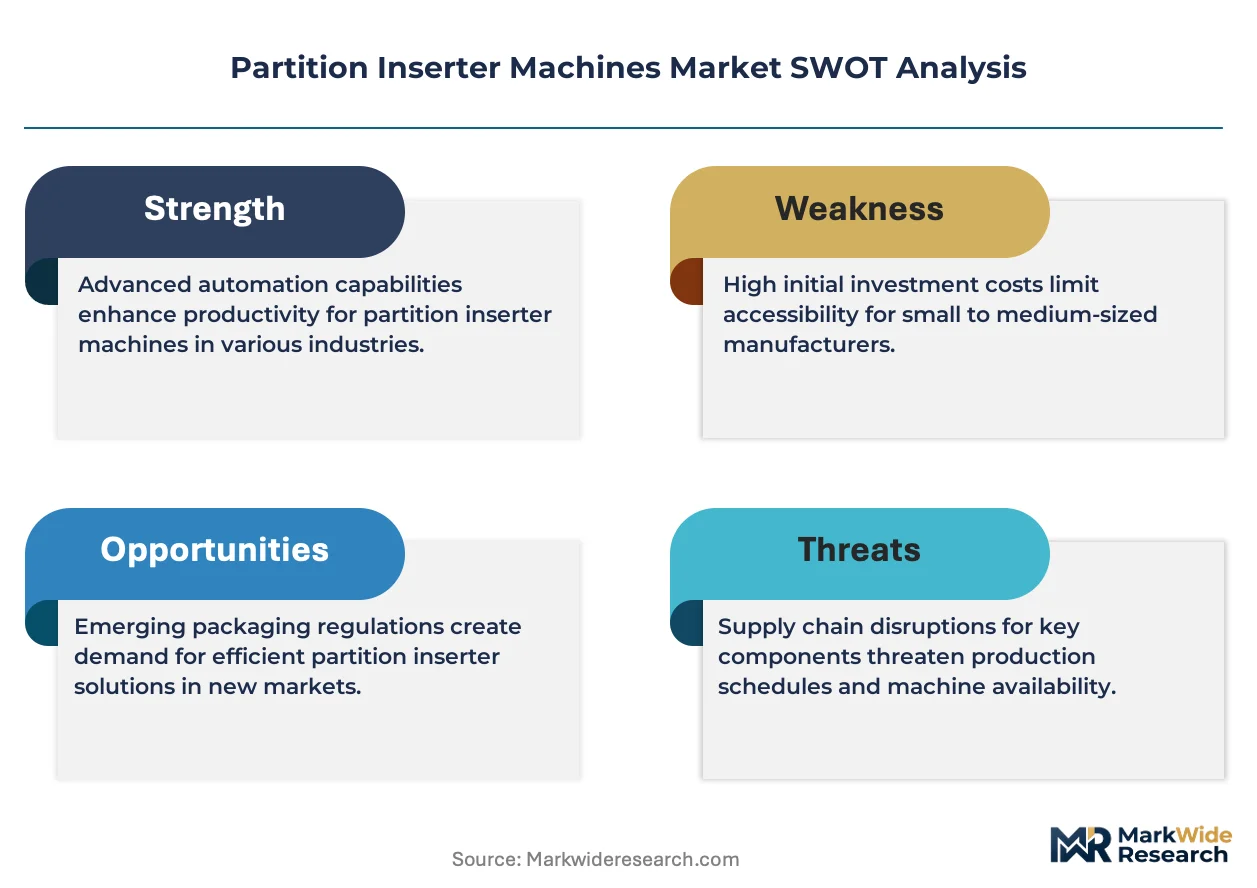
The gap between premium robotic partition inserters and commodity mechanical units is repositioning how buyers evaluate total cost of ownership versus upfront capital outlay. Pearson Packaging Systems leverages deep integration with downstream case packing lines to command premium positioning in North American food and beverage plants. Wayne Automation sustains competitive pressure through specialized servo-driven architectures that reduce changeover downtime for mid-volume electronics contract manufacturers. Hamrick Manufacturing anchors its presence in pharmaceutical-grade installations where cleanroom-compatible construction and validation documentation carry disproportionate weight in procurement decisions.
A partition inserter machine is automated or semi-automated equipment designed to erect and insert corrugated or paperboard dividers into cases, trays, or cartons at speeds typically ranging from 30 to 120 cycles per minute depending on configuration and product complexity. These machines serve primary industrial functions in protective packaging for fragile goods, multi-SKU consolidation, and shelf-ready display formation across high-velocity consumer goods operations. Automatic product type configurations dominate installed base value due to their integration with centralized plant control systems and labor reduction economics, while robotic technology segments are capturing disproportionate new order growth as vision-guided articulation enables gentler handling of curved or irregular container geometries. Sensor-based technology applications remain concentrated in quality-critical pharmaceutical and electronics end users where real-time divider-position verification prevents downstream line stoppages and product damage claims.
FDA cGMP regulations for pharmaceutical packaging equipment validation, EU machinery directive CE marking requirements for safety interlocks and emergency stop architectures, and OSHA lockout/tagout standards for maintenance access collectively elevate compliance costs for market entrants while protecting incumbent positions of established suppliers. The EPA's emphasis on corrugated recycling stream purity is indirectly shaping material specifications for partition substrates, which in turn influences knife design, vacuum pickup head geometry, and dust extraction integration in machine specifications. Stakeholders must monitor convergence between collaborative robot safety certifications and traditional fixed-guard machinery standards as hybrid human-robot partition insertion cells emerge in contract packaging operations with extreme SKU variability.
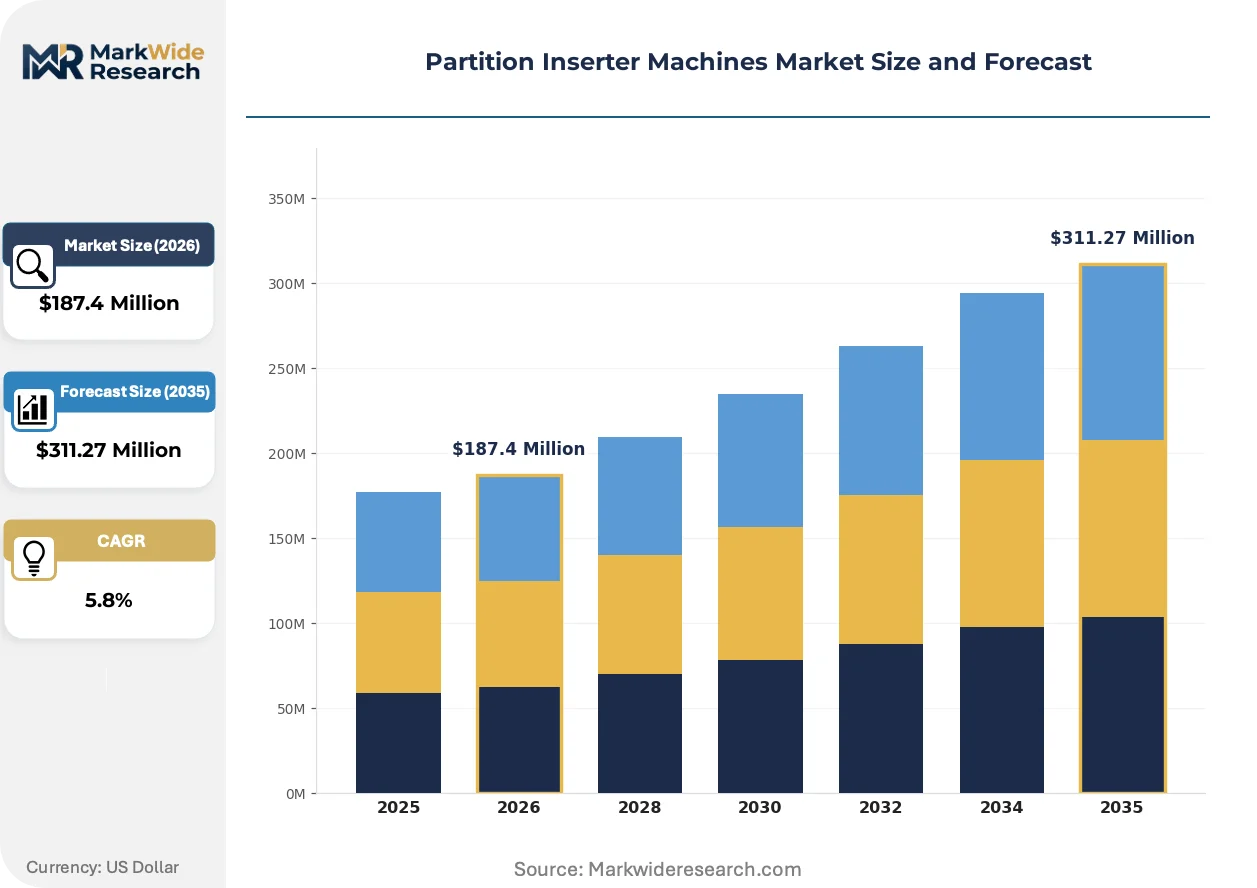
Market Dynamics
E-commerce fulfillment velocity requirements and FDA pharmaceutical packaging integrity mandates are compressing equipment procurement cycles while elevating specifications for automated partition insertion systems across corrugated packaging operations.
Growth Catalysts
- EU machinery directive CE marking:Safety interlock and emergency stop architecture requirements are accelerating replacement of legacy mechanical partition inserters with compliant servo-driven systems in European consumer goods plants.
- Corrugated substrate recycling mandates:EPA emphasis on recycling stream purity is forcing knife redesign and vacuum head geometry adaptations that favor new equipment purchases over retrofitting older machines.
- Electronics contract manufacturing:Multi-SKU consolidation needs in mid-volume electronics assembly are pulling automated partition insertion into facilities previously served by manual operations.
Market Restraints
- Specialized servo motor supply concentration:Dependence on precision motion control components from limited German and Japanese suppliers creates lead time vulnerability and input cost volatility.
- Cleanroom validation documentation burden:FDA cGMP pharmaceutical equipment validation requirements extend sales cycles by 8-14 months and elevate engineering resource intensity for market entrants.
- Collaborative robot safety standard fragmentation:Divergence between ISO/TS 15066 collaborative robot certifications and traditional fixed-guard machinery standards creates specification uncertainty for hybrid human-robot cells.
Strategic Opportunities
- Contract packaging SKU variability:Extreme product mix volatility in third-party logistics operations is creating demand for vision-guided robotic partition inserters with sub-5-minute changeover capability.
- India pharmaceutical manufacturing expansion:CDSCO regulatory alignment with FDA standards is opening export-compliant packaging equipment opportunities in emerging bulk drug and formulation facilities.
- Sensor-based quality verification convergence:Integration of real-time divider-position sensors with centralized plant control systems is expanding addressable market in quality-critical electronics and pharmaceutical end uses.
Industry Challenges
- Mechatronics technician scarcity:Shortage of technicians qualified in servo drive tuning, vision system calibration, and pneumatic-vacuum integration is constraining installation and commissioning capacity.
- Legacy Allen-Bradley and Siemens PLC integration:Retrofitting automated partition inserters into existing case packing lines with proprietary control architectures requires custom gateway development and extended factory acceptance testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Partition Inserter Machines Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Custom End User: Food & Beverage, Electronics, Pharmaceuticals, E-Commerce Application: Packaging, Assembly, Sorting, Distribution Technology: Robotic, Conveyor, Sensor-Based, Mechanical |
| Companies Covered | Pearson Packaging Systems, Wayne Automation, Hamrick Manufacturing, Delkor Systems, BW Integrated Systems, Robopac USA, nVenia, Aagard Group, Combi Packaging Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Partition Inserter Machines Market Evolving Landscape
Vision-guided robotic articulation and real-time sensor feedback are displacing mechanical cam-driven architectures across mid-to-high volume installations, while regulatory compliance automation is reshaping vendor qualification workflows.
Articulated robotic partition inserters with 6-axis kinematics and integrated 2D/3D vision systems are expanding into curved and irregular container handling applications previously excluded from automated processing. Beverage and personal care manufacturers with diverse bottle geometries are adopting these systems at 2-3x the rate of conventional mechanical units. The technology is expanding into contract packaging operations where extreme SKU variability would otherwise require dedicated changeover labor.
CE marking under the EU machinery directive is mandating standardized safety interlock architectures and emergency stop circuit redundancy across all automated packaging equipment categories. Pharmaceutical and food-contact packaging lines in Germany, France, and the Netherlands are prioritizing suppliers with pre-validated safety function documentation to compress commissioning timelines. Mid-tier equipment vendors without established notified body relationships are losing specification position to incumbents with streamlined conformity assessment pathways.
After-sales service unbundling is separating preventive maintenance contracts from spare parts supply and remote diagnostics subscriptions in North American capital equipment procurement. Large food and beverage conglomerates are negotiating direct parts sourcing agreements with component OEMs while retaining vendor technicians for calibration and safety system verification. This pattern is most visible in California and Texas packaging automation clusters where in-house maintenance capabilities have matured through successive equipment generations.
Partition Inserter Machines Market Segmentation
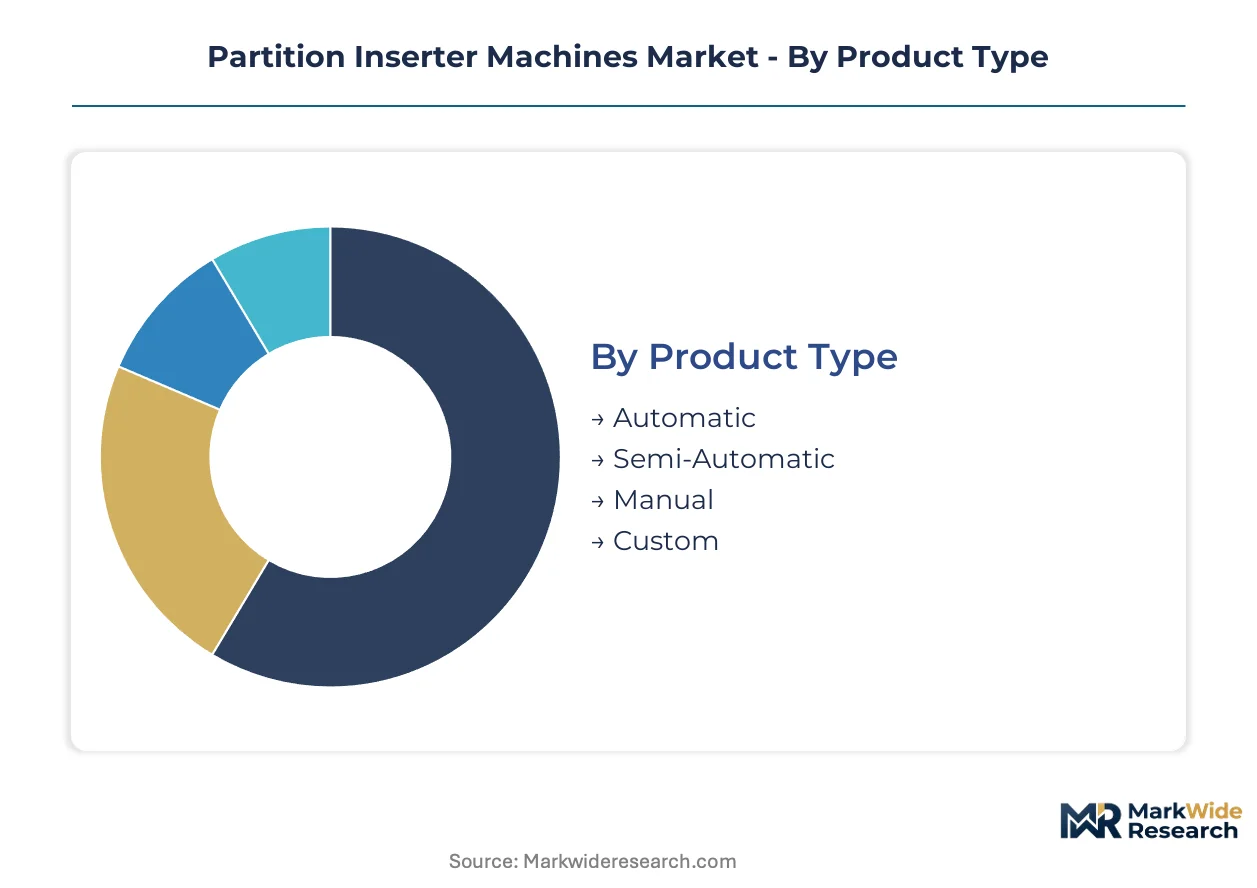
Partition inserter machine segmentation reveals divergent procurement logics across automation maturity levels and regulatory exposure. Buyers in pharmaceutical and electronics verticals prioritize validation documentation and sensor integration over throughput metrics that dominate food and beverage specifications.
Product Type:
Cost tier differentiation separates capital-intensive integrated lines from flexible entry-level units serving contract packaging volatility.
- Automatic:These systems achieve 60-120 cycles per minute through servo-driven kinematics and centralized PLC architecture. Food and beverage plants in Germany and the United States specify automatic configurations for 24/7 operations where labor reduction economics justify seven-figure capital outlays.
- Semi-Automatic:Hybrid designs combine automated partition erection with manual case loading, occupying the mid-volume electronics contract manufacturing niche. Chinese facilities in Guangdong and Jiangsu provinces favor these units for multi-SKU consolidation where full automation cannot amortize across product mix volatility.
- Manual:Hand-fed units with pneumatic assist serve low-volume pharmaceutical packaging for orphan drugs and clinical trial materials.
- Custom:Engineered-to-order systems accommodate non-standard container geometries in premium personal care and medical device packaging.
Automatic configurations lead volumes today; robotic-enhanced automatic variants are gaining share fastest in e-commerce fulfillment.
End User:
Application maturity and regulatory burden reshape equipment specifications more than throughput requirements alone.
- Food & Beverage:High-velocity bottling and canning operations in California and Texas packaging clusters demand stainless steel construction and washdown compatibility. FDA food contact surface regulations and 3A sanitary standards elevate material specifications above general industrial grades.
- Electronics:Fragile component protection drives demand for vision-guided gentle handling in semiconductor and consumer electronics assembly. South Korean and Taiwanese contract manufacturers specify sub-millimeter placement accuracy for smartphone and tablet packaging.
- Pharmaceuticals:Cleanroom-compatible construction and IQ/OQ/PQ validation documentation dominate procurement criteria. Indian CDSCO alignment with FDA standards is expanding export-compliant equipment demand in Hyderabad and Ahmedabad bulk drug facilities.
- E-Commerce:Extreme SKU variability and seasonal volume spikes favor robotic systems with rapid changeover in third-party logistics operations.
Food and beverage anchors installed base value; e-commerce is expanding most quickly as fulfillment velocity requirements intensify.
Application:
Functional positioning determines integration depth with upstream case forming and downstream palletizing systems.
- Packaging:Protective divider insertion for fragile goods represents the core function across all verticals. Corrugated partition placement into retail-ready cases dominates beverage and personal care operations in France and the Netherlands.
- Assembly:Multi-component kit consolidation in electronics and medical device manufacturing requires precise divider positioning for component segregation.
- Sorting:Automated partition insertion enables mixed-SKU consolidation for distribution center cross-docking operations.
- Distribution:Final-mile packaging configuration for parcel carrier compatibility drives specification in e-commerce hubs.
Packaging commands current revenue concentration; assembly applications are climbing the fastest as electronics manufacturing complexity increases.
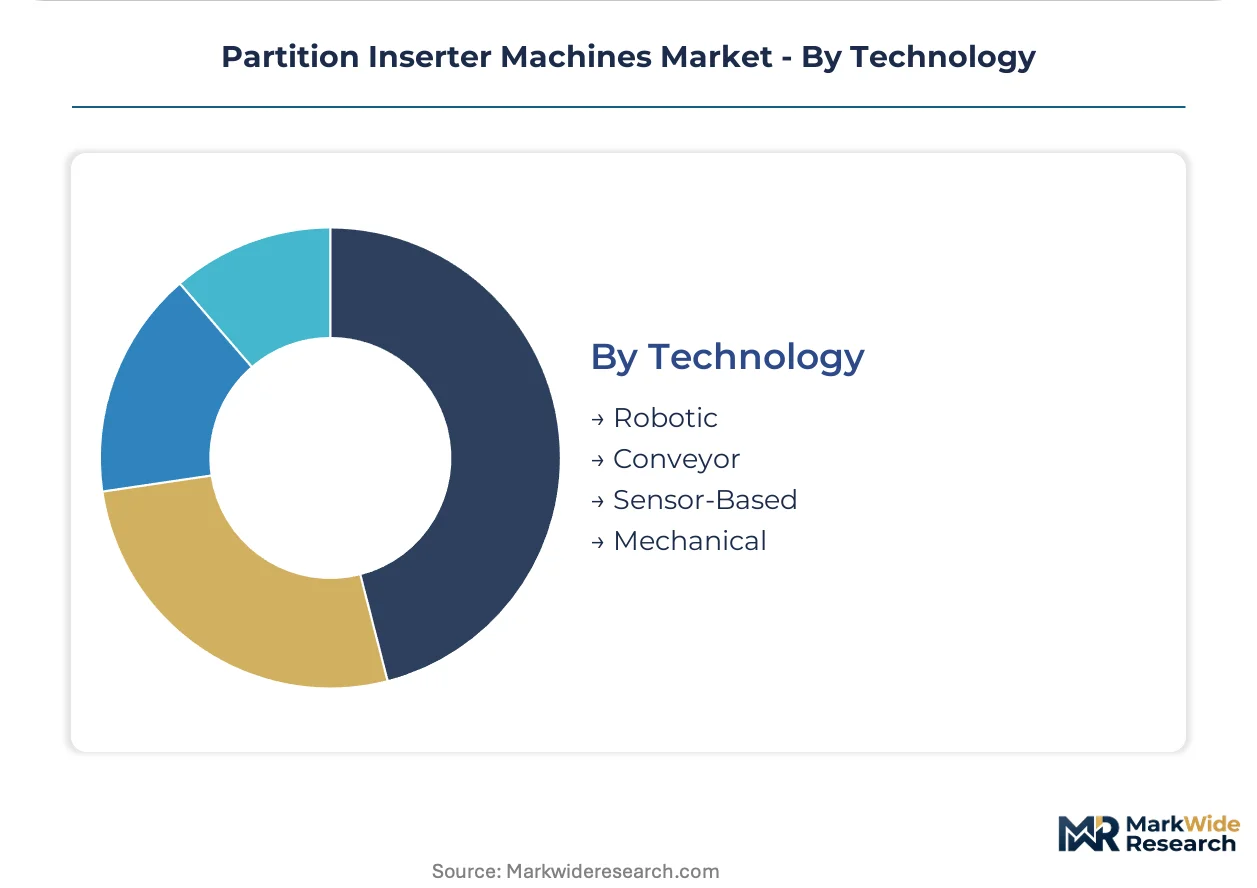
Technology:
Architecture selection trades mechanical simplicity against flexibility and regulatory compliance automation.
- Robotic:Six-axis articulated arms with integrated 2D/3D vision enable curved and irregular container handling previously excluded from automation. Japanese automotive parts suppliers and German pharmaceutical packagers specify these systems for geometric flexibility.
- Conveyor:Linear transport systems with fixed-station insertion mechanisms serve high-volume standardized product flows.
- Sensor-Based:Real-time divider-position verification prevents downstream line stoppages in quality-critical pharmaceutical and electronics end uses.
- Mechanical:Cam-driven architectures persist in legacy food and beverage installations where product geometries remain stable.
Mechanical systems retain legacy installed base; robotic technology is capturing disproportionate new order growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium equipment specifications through CE marking rigor, while China scales manufacturing capacity for mid-tier export markets. India and the United States concentrate demand growth in pharmaceutical and e-commerce verticals respectively.
United States
E-commerce fulfillment velocity and FDA pharmaceutical packaging mandates drive automated partition insertion demand. OSHA lockout/tagout standards elevate maintenance access specifications for domestic equipment procurement. California and Texas packaging clusters prioritize stainless steel washdown-compatible systems for food and beverage operations.
Germany
EU machinery directive CE marking requirements accelerate servo-driven system replacements in consumer goods plants. EMA pharmaceutical equipment standards and BSI safety certifications compress vendor qualification timelines. Bavaria and North Rhine-Westphalia anchor corrugated packaging automation investments across automotive parts and personal care manufacturing.
China
Domestic e-commerce logistics expansion and electronics contract manufacturing pull automated partition insertion into Guangdong and Jiangsu facilities. MIIT industrial automation incentives and GB machinery safety standards reshape equipment specifications for export-compliant production. Yangtze River Delta and Pearl River Delta clusters concentrate mid-volume multi-SKU consolidation demand.
India
CDSCO regulatory alignment with FDA standards opens pharmaceutical packaging equipment opportunities in bulk drug and formulation facilities. PLI scheme incentives for manufacturing automation support capital equipment adoption in Gujarat and Maharashtra. Hyderabad and Ahmedabad pharmaceutical hubs specify cleanroom-compatible partition inserters with IQ/OQ/PQ validation documentation.
Japan
Semiconductor and consumer electronics packaging demand precision placement accuracy for fragile component protection. METI industrial automation roadmaps and JIS machinery standards elevate specifications for vision-guided gentle handling systems. Kansai and Chubu regions concentrate contract manufacturing demand for smartphone and tablet packaging automation.
Partition Inserter Machines Market Competitive Landscape
Top-tier vendors anchor integrated line positioning, while mid-tier specialists compete on changeover flexibility and regional service density. The vendor base stratifies across three archetypes: systems integrators with downstream case packing line control, servo-driven architecture specialists, and pharmaceutical-grade validation documentation providers. Dominant competitive moves include strategic partnerships with corrugated substrate suppliers and geographic expansion through distributor networks in emerging pharmaceutical manufacturing regions.
Within the systems integrator tier, Pearson Packaging Systems and Wayne Automation exemplify North American positioning through deep downstream line integration and servo-driven architecture specialization respectively. Hamrick Manufacturing occupies a position within the pharmaceutical-grade validation tier, anchoring cleanroom-compatible equipment supply where regulatory documentation carries disproportionate procurement weight. These three vendors represent divergent competitive vectors: integrated line control, motion engineering specialization, and compliance automation depth.
| Leading Market Players |
|---|
| Pearson Packaging Systems |
| Wayne Automation |
| Hamrick Manufacturing |
| Delkor Systems |
| BW Integrated Systems |
| Robopac USA |
| nVenia |
| Aagard Group |
| Combi Packaging Systems |
| Others |
Value Network & Pricing Analysis
Mechatronics technician concentration in German and Japanese industrial corridors widens pricing-tier spreads, as labor-cost differentials between servo-drive calibration specialists and mechanical maintenance generalists stratify equipment quotations across premium robotic and standard mechanical configurations.
Pricing Analysis
Bundled preventive maintenance contracts are unbundling from spare parts supply and remote diagnostics subscriptions across North American procurement. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking validation depth and IQ/OQ/PQ documentation completeness. Pricing pressure stems from mid-tier vendor competition in Chinese export markets. Contract packaging operations exhibit highest price sensitivity; pharmaceutical manufacturers show least.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and China's MIIT industrial automation incentives are reshaping sourcing patterns for servo motors and precision motion components. Supply concentrates in Germany, Japan, and China for specialized servo drives, vacuum pumps, and vision system cameras. Component dependencies include precision ball screws, harmonic gearboxes, and machine-vision sensors. Single-source vulnerability runs through Japanese harmonic drive suppliers. Distribution runs through OEM direct sales and regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. FDA pharmaceutical packaging integrity mandates and EU machinery directive CE marking requirements are pulling demand toward premium servo-driven and robotic configurations with full validation documentation.
For Market Incumbents: Deploy aftermarket service unbundling as a margin defense lever. Separate preventive maintenance contracts from spare parts supply to retain vendor technician relationships for calibration and safety system verification while conceding direct component sourcing to large food and beverage conglomerates. Deepen backward integration into servo motor supply partnerships to mitigate lead time vulnerability from German and Japanese component concentration. For New Entrants and Emerging Players: Begin with contract packaging operations in third-party logistics hubs where extreme SKU variability and seasonal volume spikes create demand for vision-guided robotic partition inserters with sub-5-minute changeover capability. Target Indian pharmaceutical manufacturing expansion in Hyderabad and Ahmedabad where CDSCO regulatory alignment with FDA standards opens export-compliant equipment opportunities lacking established incumbent relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier servo-driven architecture specialists without pre-validated safety function documentation for EU machinery directive compliance. Long-term viability favors vendors with streamlined notified body relationships and IQ/OQ/PQ validation depth. Watch for convergence between collaborative robot safety certifications and traditional fixed-guard machinery standards as inflection indicator for hybrid human-robot cell demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Validation Documentation Investment | IQ/OQ/PQ packages compress pharmaceutical sales cycles against FDA cGMP requirements. |
| Servo-Driven Architecture Specialization | Precision motion control reduces changeover downtime for mid-volume electronics manufacturers. |
| Vision-Guided Robotic Integration | 2D/3D vision systems enable handling of curved beverage containers previously excluded from automation. |
| Aftermarket Service Unbundling | Separating maintenance contracts from parts supply responds to mature in-house capabilities in California and Texas clusters. |
| Geographic Expansion Through Distributor Networks | Regional service density captures pharmaceutical equipment demand in emerging Indian bulk drug facilities. |
Research Methodology
Multiple input streams — plant engineer interviews, OEM procurement team discussions, aftermarket service head consultations, and regulatory affairs lead exchanges — were reconciled against secondary validation from SEC equipment manufacturer filings, EU machinery directive notified body registries, FDA cGMP guidance documents, and customs trade data for corrugated packaging machinery. Bottom-up installed base estimates and top-down equipment spending projections were cross-referenced to anchor volume figures.
Historical shipment data was cross-referenced against panel input from packaging automation specialists to model adoption curves across the projection horizon. Segmentation dimensions included automation level, end-use vertical, technology architecture, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and greenfield facility investment patterns. Forecast inputs incorporated e-commerce fulfillment velocity requirements and pharmaceutical packaging integrity mandate compliance timelines.
Caveats apply where servo motor supply disruptions, collaborative robot safety standard fragmentation, or mechatronics technician scarcity could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement continuity and capital equipment procurement cycle normalization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Semiconductor CVD Equipment Market
Semiconductor Equipment
Dicing Equipment Market
Semiconductor Equipment
Global Microelectronics Cleaning Equipment Market
Semiconductor Equipment
Global Laser Dicing Systems Market
Semiconductor Equipment
Laser Micro Perforation Equipment Market
Semiconductor Equipment
Wafer Back-Grinding Machine Market
Semiconductor Equipment
Global Sputtering Equipment Market
Semiconductor Equipment
Vacuum Spin Coaters Market
Semiconductor Equipment
Semiconductor Wafer Cleaning Equipment Market
Semiconductor Equipment
Wafer Chucks Market
Semiconductor Equipment
Semiconductor LPCVD Furnaces Market
Semiconductor Equipment
Global Atomic Layer Deposition (ALD) Equipment Market
Semiconductor Equipment
Semiconductor Lithography Equipment Market
Semiconductor Equipment
Cathode Stripping Machines Market
Semiconductor Equipment
Lithography Equipment Market
Semiconductor Equipment
Semiconductor Manufacturing Equipment Market