
 Wet Bench Market | 2026-2036
Wet Bench Market Size, Share, and Industry Trends Forecast 2026-2036
Wet Bench Market Insights
The gap between premium automated wet benches and commodity manual systems is broadening as foundries at 7nm and below demand precision chemical delivery while legacy fabs prioritize cost containment. Modutek Corporation leverages its California-based manufacturing to dominate North American retrofit cycles for EPA-compliant installations. MEI Wet Processing Systems anchors its position through deep specialization in semiconductor-grade wet etch stations. RENA Technologies competes aggressively in European MEMS fabrication with modular configurations that reduce facility downtime.
A wet bench is a contained workstation engineered from polypropylene, PVDF, or quartz that delivers controlled chemical baths for substrate cleaning, etching, stripping, or deposition in controlled cleanroom environments. Process parameters include temperature uniformity within ±0.5°C, chemical concentration tolerance below 1%, and exhaust capture rates meeting SEMI S2 safety standards. Chemical wet benches command the largest installed base due to their ubiquity in front-end-of-line semiconductor processing, while photoresist wet benches capture disproportionate margin pools from lithography-intensive advanced logic production. Clean wet benches for wafer cleaning applications represent the fastest-expanding segment as single-wafer tools displace batch systems in contamination-critical nodes.
OSHA process safety management standards and EPA hazardous air pollutant rules in the United States compel wet bench operators to install automated chemical delivery and emergency containment systems, directly inflating replacement demand. REACH chemical authorization in Europe and Korea's KOSHA industrial safety framework similarly restrict manual handling protocols, creating regulatory convergence around automation. Stakeholders must monitor how SEMI safety guidelines evolve alongside local emissions rules to anticipate compliance-driven upgrade cycles.
Market Dynamics
Semiconductor foundries in Taiwan and South Korea are compressing wet bench replacement cycles as advanced node production demands sub-1% chemical concentration tolerances and automated chemical delivery systems that manual platforms cannot deliver.
Growth Catalysts
- EPA Hazardous Air Pollutant Rules:US-based semiconductor operators face mandated upgrades to automated chemical containment and exhaust capture systems, directly accelerating replacement demand for legacy manual wet benches.
- Single-wafer Processing Migration:Front-end-of-line contamination control requirements at 7nm and below nodes are forcing batch wet bench displacement by precision single-wafer tools in Taiwan and South Korean foundries.
- East Asian Manufacturing Clusters:Concentrated capital expenditure from TSMC, Samsung, and SK Hynix in Hsinchu, Taichung, and Pyeongtaek is concentrating wet bench procurement volume in these geographies.
Market Restraints
- High-purity Fluoropolymer Supply Concentration:PVDF and PFA liner materials for corrosion-resistant wet bench construction depend on concentrated Japanese and German chemical suppliers, exposing lead time risk.
- Quartz Component Fragility:Process chamber quartzware requires frequent replacement and specialized handling protocols that inflate total cost of ownership versus metal alternatives.
- REACH Chemical Authorization Delays:European wet bench operators face extended approval timelines for novel chemistries used in advanced etch processes, slowing process development cycles.
Strategic Opportunities
- Indian Semiconductor Mission Incentives:India's production-linked incentive scheme for semiconductor fabrication is attracting greenfield fab investments in Gujarat and Karnataka that require complete wet bench infrastructure buildouts.
- MEMS Sensor Manufacturing Expansion:Automotive and consumer MEMS fabrication in European clusters is creating demand for modular wet bench configurations that accommodate smaller batch sizes and rapid process changeovers.
- SEMI S2 Safety Standard Convergence:Global alignment around automated emergency shutdown and chemical containment protocols is enabling platform standardization that reduces engineering customization costs for wet bench OEMs.
Industry Challenges
- Cleanroom Integration Complexity:Wet bench installation requires precise coordination with facility HVAC, exhaust, and chemical distribution infrastructure that extends commissioning timelines and inflates project risk.
- Process Engineer Scarcity:Specialized expertise in chemical bath temperature uniformity control and contamination prevention is concentrating at established foundries, constraining talent availability for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wet Bench Market |
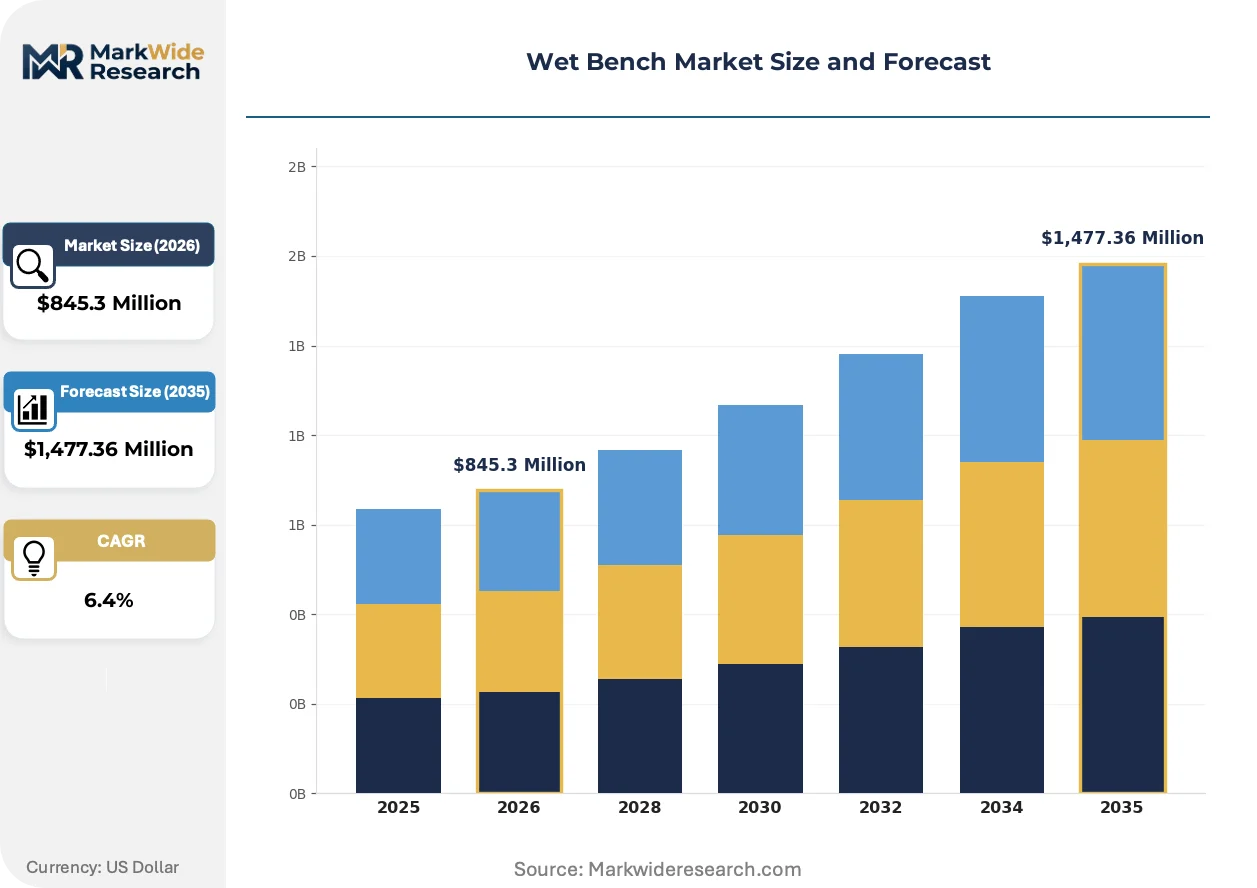
| Market Size in 2026 | $845.3 Million |
| Market Size in 2035 | $1,477.36 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Wet Bench, Photoresist Wet Bench, Clean Wet Bench, Etch Wet Bench Application: Semiconductor Processing, MEMS Fabrication, Wafer Cleaning, Solar Cell Manufacturing End User: Foundries, Research Institutions, Electronics Manufacturers, Solar Manufacturers Installation: On-site, Modular, Integrated, Removable |
| Companies Covered | Modutek Corporation, MEI Wet Processing Systems, RENA Technologies, MT Systems, Amerimade Technology, ClassOne Technology, AP&S International, JST Manufacturing, Technic Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wet Bench Market Trends and Innovations
Wet bench architecture is absorbing automation pressure from two directions simultaneously: front-end semiconductor nodes demanding precision chemical delivery, and regulatory frameworks mandating reduced manual handling of hazardous substances.
Quartz immersion heaters and in-situ chemical concentration sensors are absorbing the precision requirements previously managed through operator intervention. Taiwan-based foundries at 5nm and 3nm nodes are deploying these integrated metrology packages at scale. The technology is absorbing operator judgment into closed-loop control systems that maintain temperature uniformity within ±0.5°C without human adjustment.
REACH chemical authorization in Europe and Korea's KOSHA industrial safety framework are converging on automated chemical delivery mandates that manual wet benches cannot satisfy. Semiconductor operators in Germany and South Korea face parallel compliance deadlines for eliminating open-bath chemical handling. Front-end-of-line processing segments with the highest chemical throughput are responding fastest, with foundries in Dresden and Yongin completing automated retrofits ahead of enforcement dates.
Capital equipment procurement is consolidating through direct OEM relationships as foundries internalize wet bench specification expertise previously held by systems integrators. Tier-one semiconductor manufacturers in Taiwan and South Korea now negotiate platform configurations directly with Modutek, MEI, and RENA, compressing distributor margins and accelerating feedback loops between process requirements and engineering development. This disintermediation is most visible in advanced logic fabrication where proprietary process recipes demand customized bath sequencing and chemical compatibility validation.
Wet Bench Market Segmentation
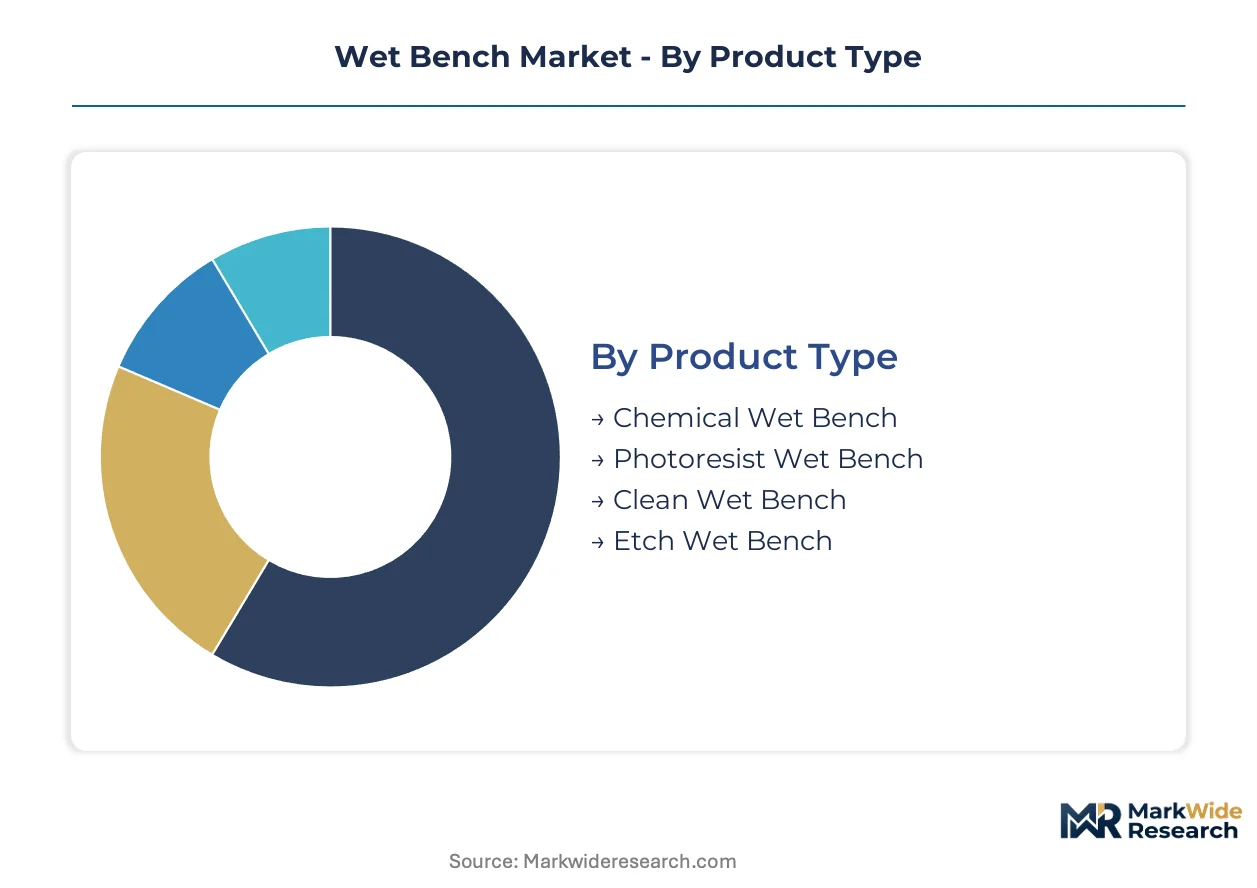
Wet bench procurement patterns diverge sharply across product architectures and end-use environments. Semiconductor foundries prioritize precision chemical delivery systems while MEMS and solar manufacturers optimize for throughput and footprint flexibility.
Product Type:
Supply concentration in fluoropolymer liner materials and quartzware fabrication favors established product categories with proven supply chains over novel architectures.
- Chemical Wet Bench:Engineered from PVDF, polypropylene, or quartz for corrosive acid and solvent handling with temperature uniformity within ±0.5°C. Front-end-of-line semiconductor processing in Taiwan and South Korea drives replacement demand as EPA and KOSHA compliance deadlines eliminate manual chemical handling.
- Clean Wet Bench:Designed for ultra-pure water and specialized cleaning chemistries with contamination control protocols meeting SEMI standards. Single-wafer processing migration at 7nm and below nodes in Hsinchu and Pyeongtaek foundries accelerates displacement of batch systems.
- Photoresist Wet Bench:Delivers controlled developer, stripper, and rinse sequences for lithography-intensive production.
- Etch Wet Bench:Configures selective material removal through acid-based or solvent-based chemistries with exhaust capture integration.
Chemical wet benches absorb the bulk of installed capacity; clean wet benches are expanding most quickly.
Application:
Cost tier differentiation separates capital-intensive front-end semiconductor installations from price-sensitive solar and emerging MEMS configurations.
- Semiconductor Processing:Front-end-of-line cleaning, etching, and stripping operations requiring sub-1% chemical concentration tolerances. TSMC, Samsung, and SK Hynix capital expenditure in Taichung and Yongin concentrates procurement volume for automated platforms.
- Wafer Cleaning:Pre-diffusion and post-etch surface preparation with particle contamination thresholds below 0.1 particles per cm². Migration from batch to single-wafer tools in advanced logic fabs drives fastest segment expansion.
- MEMS Fabrication:Modular configurations accommodating smaller batch sizes and rapid process changeovers for automotive and consumer sensors.
- Solar Cell Manufacturing:Texturing and cleaning sequences for silicon wafer substrates with throughput optimization over precision.
Semiconductor processing commands dominant procurement value; wafer cleaning applications are climbing the fastest.
End User:
Customer type determines specification complexity, with foundries internalizing platform expertise previously held by systems integrators.
- Foundries:Tier-one semiconductor manufacturers negotiating direct OEM relationships for proprietary process recipes. Direct engagement with Modutek, MEI, and RENA compresses distributor margins and accelerates engineering feedback loops.
- Research Institutions:Flexible configurations supporting experimental chemistries and rapid process development cycles.
- Electronics Manufacturers:Backend packaging and substrate processing with standardized bath sequences.
- Solar Manufacturers:Volume-oriented procurement prioritizing equipment uptime and chemical consumption efficiency.
Foundries absorb dominant capital allocation; research institutions are gaining share fastest through government-funded cleanroom expansions.
Installation:
Maturity gradients separate standardized modular platforms from customized integrated systems requiring extended commissioning timelines.
- Integrated:Permanent installations with facility-wide HVAC, exhaust, and chemical distribution hard-piping. Cleanroom construction in Dresden and Gujarat greenfield fabs drives demand for complete infrastructure buildouts.
- Modular:Pre-engineered skids reducing facility downtime and enabling rapid process changeovers. European MEMS clusters adopt these configurations for smaller batch flexibility.
- On-site:Custom-fabricated installations tailored to specific cleanroom footprints and process sequences.
- Removable:Portable configurations for pilot lines and temporary capacity expansion.
Integrated installations hold dominant installed base; modular platforms are expanding most quickly through retrofit cycles and MEMS adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors the most concentrated wet bench procurement activity globally, with Taiwan's foundry ecosystem driving precision equipment demand for sub-7nm node production.
United States
EPA Hazardous Air Pollutant rules and OSHA process safety management standards are compelling semiconductor operators to replace manual wet benches with automated chemical containment systems. The South Bay area of Silicon Valley and Austin's semiconductor corridor concentrate retrofit demand from legacy fabs upgrading for compliance deadlines.
South Korea
KOSHA industrial safety frameworks are eliminating open-bath chemical handling protocols across Samsung and SK Hynix operations. Yongin and Pyeongtaek foundry clusters are completing automated wet bench installations ahead of enforcement timelines for advanced logic and memory production.
Japan
METI industrial policy and domestic semiconductor revitalization initiatives are channeling capital toward Kyushu's silicon island and the Tohoku region. Yokohama and Osaka-based equipment suppliers are tightening fluoropolymer liner supply chains for corrosion-resistant wet bench construction.
Germany
REACH chemical authorization delays are constraining novel etch chemistry deployment, yet Dresden's Silicon Saxony cluster is expanding wet bench infrastructure for automotive sensor and power semiconductor fabrication. ECHA compliance timelines are accelerating automated system adoption.
India
The Production-Linked Incentive scheme for semiconductor fabrication is attracting greenfield investments to Gujarat's Dholera Special Investment Region and Karnataka's Electronics City Phase II. Complete wet bench infrastructure buildouts are accompanying these first domestic fab projects.
Wet Bench Market Competitive Landscape
Capital-heavy wet bench OEMs compete with asset-light systems integrators in a market structure that rewards direct foundry relationships over distributor networks. The vendor base stratifies across three tiers: established platform specialists with proprietary chemical delivery IP, regional fabricators serving retrofit cycles, and modular specialists targeting MEMS and research applications. Consolidation pressure is intensifying as tier-one foundries internalize specification expertise and compress procurement channels. Dominant competitive moves include geographic proximity manufacturing for regulatory compliance and vertical integration into fluoropolymer component supply.
Among California-based wet bench specialists, Modutek Corporation occupies a position exemplifying the regulatory-proximity archetype through domestic manufacturing for EPA-compliant installations. MEI Wet Processing Systems represents the deep-specialization archetype with focused positioning on semiconductor-grade wet etch platforms. RENA Technologies anchors the modular-configuration archetype for European MEMS fabrication, with its German origins supporting regional service density. These three companies collectively illustrate how geographic concentration, application focus, and architectural flexibility define competitive positioning in wet bench supply.
| Leading Market Players |
|---|
| Modutek Corporation |
| MEI Wet Processing Systems |
| RENA Technologies |
| MT Systems |
| Amerimade Technology |
| ClassOne Technology |
| AP&S International |
| JST Manufacturing |
| Technic Inc. |
| Others |
Pricing and Supply Chain Analysis
Automated chemical delivery mandates from EPA and KOSHA are forcing foundries to specify corrosion-resistant fluoropolymer linings and precision quartzware that only concentrated Japanese and German suppliers can deliver, compressing procurement leverage and inflating platform costs. Tier-one semiconductor manufacturers in Taiwan and South Korea now negotiate directly with wet bench OEMs, bypassing systems integrators and exposing price transparency that legacy distributors cannot match.
Pricing Analysis
Yield-guarantee contracts anchor wet bench pricing, with foundries paying premiums for platforms delivering sub-1% chemical concentration tolerances and temperature uniformity within ±0.5°C. Three-tier pricing structure across premium, standard, and economy levels separates fully automated EPA-compliant installations from manual retrofit candidates and commodity batch systems. Cost compression in standard-tier configurations is intensifying because PVDF and PFA liner supply bottlenecks extend lead times and inflate material pass-through costs. Solar manufacturers exhibit highest price sensitivity, prioritizing throughput metrics over precision specifications, while advanced logic foundries absorb premium pricing for proprietary process recipe validation.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale foundry demand, with Modutek, MEI, and RENA managing configuration negotiations without distributor intermediaries. Fluoropolymer liner fabrication concentrates in Japan and Germany, while quartzware production anchors in Japan and the United States, creating geographic dependency for corrosion-resistant components. Single-source vulnerability runs through specialized PVDF resin supply from Japanese chemical conglomerates, exposing wet bench OEMs to allocation risk during semiconductor capital expenditure surges. Distribution runs through regional service hubs co-located with major foundry clusters in Hsinchu, Yongin, and Dresden to minimize commissioning downtime.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wet bench OEMs are racing to secure captive supply of fluoropolymer liners and quartz components as supply concentration shifts procurement leverage upstream to materials suppliers. Foundry direct-engagement models reward players with in-house fabrication capabilities and geographic proximity to regulatory enforcement zones.
For Market Incumbents: To counter distributor disintermediation and margin compression, deepen backward integration into PVDF and PFA liner production through partnership with Japanese chemical suppliers or acquisition of regional fabricators. Prioritize California-based manufacturing capacity to defend EPA-compliant retrofit cycles in US legacy fabs, while expanding Dresden and Yongin service density to capture KOSHA-driven replacement demand. For New Entrants and Emerging Players: Capture modular wet bench demand from European MEMS clusters and Indian greenfield fab buildouts, where specification expertise gaps create entry latitude against entrenched platform specialists. Target Gujarat's Dholera Special Investment Region and Karnataka's Electronics City Phase II for first-mover relationships with domestic semiconductor mission beneficiaries, leveraging standardized skid configurations that reduce facility integration complexity. For Investors and Strategic Acquirers: The window for entry favors wet bench OEMs with proven SEMI S2 safety certification and established foundry reference accounts. Mid-cap specialists with captive fluoropolymer supply relationships or quartzware fabrication capabilities offer strongest acquisition rationale given materials scarcity dynamics. Monitor EPA enforcement timeline acceleration and REACH chemical authorization backlog resolution as inflection indicators for replacement cycle velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Supply | Captive PVDF liner production insulates against Japanese supplier allocation risk during foundry capex surges. |
| Geographic Manufacturing Proximity | California-based fabrication accelerates EPA-compliant retrofit delivery to Silicon Valley and Austin corridors. |
| Direct OEM-Foundry Engagement Model | Eliminating distributor layers compresses feedback loops between TSMC process requirements and engineering development. |
| Modular Platform Standardization | Pre-engineered skids reduce European MEMS facility downtime and enable rapid automotive sensor process changeovers. |
| SEMI S2 Safety Certification Investment | Automated emergency shutdown compliance opens KOSHA-mandated replacement cycles in Samsung and SK Hynix facilities. |
Research Methodology
Multi-period observation of wet bench procurement patterns, foundry capital expenditure disclosures, and regulatory enforcement timelines anchored the trend analysis, supplemented by interviews with semiconductor process engineers, cleanroom facility managers, wet bench OEM product directors, and fluoropolymer supplier sales executives. Secondary validation drew from SEMI industry reports, EPA hazardous air pollutant enforcement records, KOSHA industrial safety filings, and customs trade data for PVDF and quartzware imports. Bottom-up equipment unit forecasts triangulated against top-down semiconductor fabrication capacity expansion estimates.
Segment-weighting across product type, application, end user, and installation architecture distributed value projections proportionally to observed procurement patterns. Chemical wet bench, clean wet bench, photoresist wet bench, and etch wet bench categories were modeled separately with divergent growth assumptions reflecting single-wafer processing migration and batch system displacement dynamics. CAGRs derived from regression against historical foundry equipment spending correlations with node transition timelines, with explicit modeling of EPA and KOSHA compliance deadline effects on replacement cycle acceleration.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to fluoropolymer supply concentration, REACH chemical authorization delays for novel etch chemistries, and potential relaxation of semiconductor fabrication incentives in India or elsewhere. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Wafer Grinding Machine Market
Semiconductor Equipment
Europe Chip Mounter Market
Semiconductor Equipment
Ion Milling System Market
Semiconductor Equipment
UV-Based Nanoimprint Lithography (UV-NIL) System Market
Semiconductor Equipment
Automatic Laser PCB Depaneling Machines Market
Semiconductor Equipment
Automatic Flip Chip Bonders Market
Semiconductor Equipment
Semiconductor Lithography Equipment Market
Semiconductor Equipment
Semiconductor Wafer Fab Equipment (WFE) Market
Semiconductor Equipment
China Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Semiconductor Production Equipment Market
Semiconductor Equipment
Semiconductor Assembly Equipment Market
Semiconductor Equipment
Semiconductor Wafer Process Control Equipment Market
Semiconductor Equipment
Middle East and Africa Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Thin Wafer Processing and Dicing Equipment Market
Semiconductor Equipment
Global Wafer Cleaning Equipment Market
Semiconductor Equipment
OLED Vacuum Evaporation Machine Market