
 Selective Soldering Equipment Market | 2026-2036
Selective Soldering Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Selective Soldering Equipment Market Outlook
Tier-one automotive electronics suppliers is reorganizing procurement priorities toward selective soldering systems that handle mixed-technology boards with through-hole components. Ersa GmbH leverages its German engineering base to dominate high-mix, low-volume contract manufacturing across European automotive tier suppliers. Nordson Corporation sustains technology leadership in precision flux deposition and thermal control modules that anchor its North American installed base. JUKI Corporation competes aggressively on footprint efficiency and total cost of ownership for Asian consumer electronics contract manufacturers.
Selective soldering equipment employs programmable wave or dip soldering heads that apply molten alloy to specific through-hole component leads on printed circuit assemblies, operating at temperatures between 240°C and 300°C with nitrogen inerting to control oxidation and improve joint reliability. The equipment serves electronics manufacturers requiring thermal precision beyond mass wave soldering capabilities for mixed-technology boards. Fully automatic selective soldering systems capture the dominant share of new capital expenditure as labor costs rise and traceability requirements tighten across automotive and aerospace value chains. Infrared heating technology leads installed capacity for standard thermal profiles, while laser soldering grows fastest in microelectronics applications demanding sub-millimeter accuracy without thermal damage to adjacent surface-mount devices.
EPA hazardous air pollutant standards for electronics manufacturing and RoHS substance restrictions enforced by ECHA directly shape equipment specifications, flux chemistry approvals, and capital investment timelines across OEM and contract manufacturer facilities. ISO 9001 quality management and IPC-A-610 acceptability criteria further constrain supplier qualification and system validation protocols. Stakeholders must monitor evolving automotive functional safety standards and semiconductor packaging miniaturization trends to align R&D roadmaps with the next generation of thermal process requirements.
Market Dynamics
Automotive functional safety requirements and semiconductor packaging miniaturization are compressing thermal process tolerances, forcing equipment manufacturers to integrate sub-millimeter precision with real-time traceability systems that satisfy tier-one supplier audits.
Growth Catalysts
- EV Powertrain Electrification:Battery management systems and inverter control modules require through-hole components that withstand high-vibration environments, pulling selective soldering into EV supply chains across Germany, China, and the United States.
- RoHS Lead-Free Mandates:ECHA enforcement of substance restrictions across European electronics manufacturing is eliminating exempted leaded processes, compelling capital replacement cycles for compliant thermal systems.
- Nitrogen Inerting Technology:Controlled atmosphere soldering reduces oxidation defects below 50 ppm, enabling automotive tier suppliers to meet IPC-A-610 Class 3 reliability standards without rework stations.
Market Restraints
- High-Purity Alloy Cost Volatility:Tin-silver-copper solder bar prices fluctuate with LME tin futures, squeezing operating margins for high-mix contract manufacturers running nitrogen-assisted processes.
- German Engineering Concentration:Precision motion control systems and thermal profiling software originate from a concentrated supplier base in Baden-Württemberg and Bavaria, creating single-source vulnerability.
- Laser Soldering Substitution:Solid-state laser systems achieve spot sizes below 0.3 mm for microelectronics packaging, threatening selective soldering's position in sub-millimeter joint applications.
Strategic Opportunities
- Indian Electronics Manufacturing:PLI scheme incentives for semiconductor assembly and testing facilities create virgin installed base potential as domestic PCB capacity scales under government production-linked support.
- Aerospace Wire Harness Integration:MIL-STD-202G qualification requirements for high-reliability connectors open selective soldering applications in defense and satellite hardware previously dominated by hand soldering.
- Laser-Thermal Hybrid Convergence:Combined infrared preheating with precision laser finishing addresses mixed-technology boards containing both large thermal mass connectors and heat-sensitive surface-mount devices.
Industry Challenges
- Process Engineer Talent Scarcity:Thermal profiling expertise combining materials science with statistical process control commands premium compensation in automotive electronics clusters, constraining operational scaling.
- ISO 9001 Validation Timelines:New equipment qualification protocols require 90-120 day production trials with full traceability documentation before tier-one suppliers approve supplier status.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Selective Soldering Equipment Market |
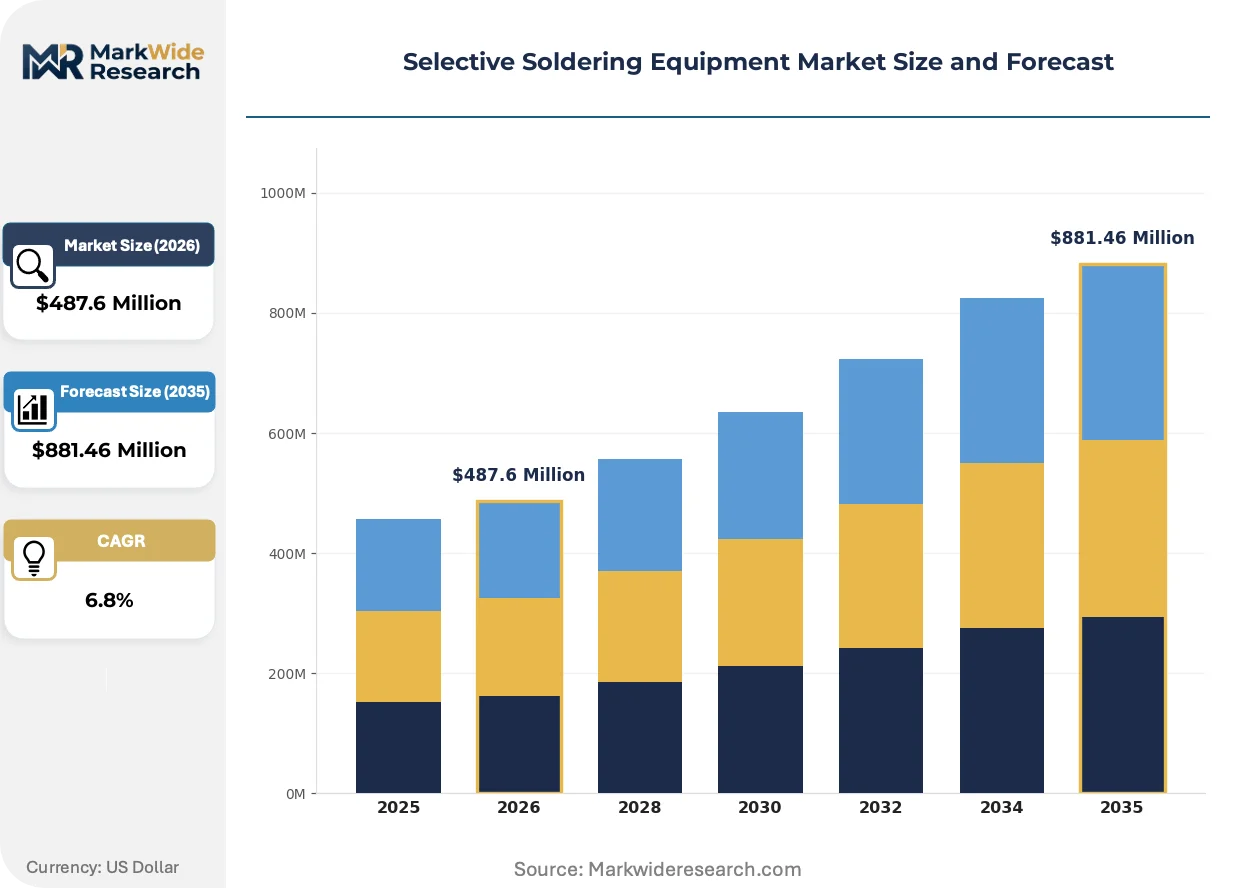
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Selective Soldering, Semi-Automatic Selective Soldering, Fully Automatic Selective Soldering, Hybrid Systems Technology: Infrared Heating, Hot Air, Laser, Contact Heating End User: Aerospace, Automotive, Consumer Electronics, Industrial Electronics Application: Circuit Board Assembly, Prototyping, Repair & Maintenance, Low-Volume Production |
| Companies Covered | Pillarhouse International, Manncorp, Ersa GmbH, JUKI Corporation, Blundell Production Equipment, SEHO Systems GmbH, Nordson Corporation, Hentec Industries, RPS Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Selective Soldering Equipment Market Strategic Shifts
Equipment architectures are converging toward closed-loop thermal control with machine vision feedback, eliminating the gap between programmed and actual solder joint formation. This shift is compressing the acceptable defect rate threshold while extending automation deeper into high-mix production environments.
Infrared heating technology dominates standard thermal profiles for through-hole component soldering, delivering consistent energy transfer across varying board geometries. Automotive electronics manufacturers in Stuttgart and Detroit are standardizing on multi-zone IR preheat modules that reduce thermal shock to multilayer PCBs. Laser soldering is supplanting miniature wave nozzles in camera module and medical sensor applications where adjacent surface-mount devices cannot tolerate radiant heat exposure.
EPA hazardous air pollutant standards for electronics manufacturing are mandating fume extraction efficiency above 98% for flux vapor capture, forcing equipment redesigns with integrated filtration modules. The regulation compresses facility layout flexibility as ducting and blower systems become embedded in machine footprints. Contract manufacturers in the United States are responding by specifying integrated vapor containment systems from initial procurement rather than retrofitting existing lines.
Service contract unbundling is fragmenting the traditional equipment-plus-maintenance bundle into separate capital and operational expenditure lines. Asian consumer electronics contract manufacturers now procure selective soldering systems through equipment-as-a-service arrangements where thermal module replacement and software updates shift to vendor responsibility. This pattern is most visible in Shenzhen and Suzhou manufacturing parks where facility ownership prefers operational flexibility over asset-heavy balance sheets.
Selective Soldering Equipment Market Segmentation
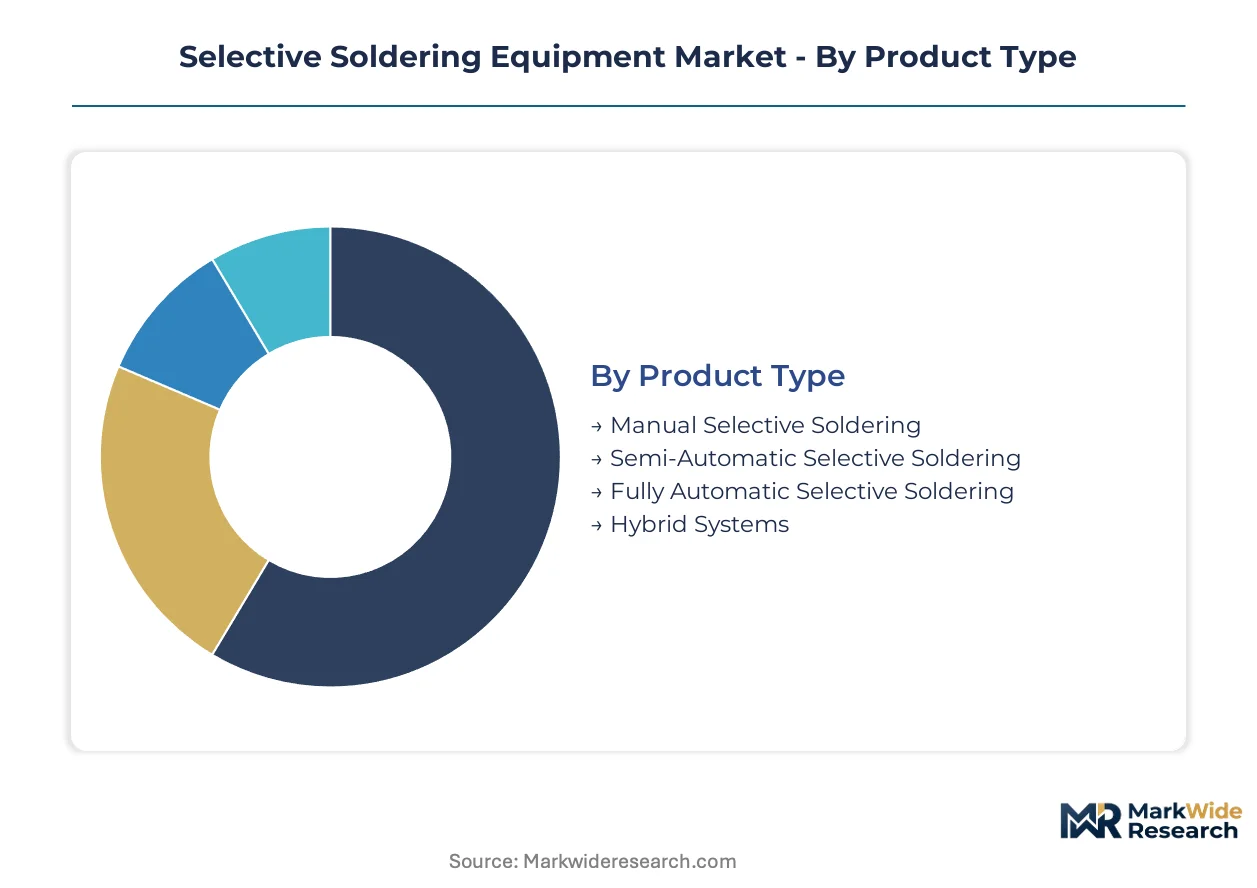
Selective soldering equipment segments diverge sharply in automation intensity and thermal precision, with substitution threats from laser soldering and hand soldering reshaping investment priorities across automotive and aerospace value chains. Equipment buyers balance capital efficiency against traceability mandates that favor fully automatic systems in tier-one supplier audits.
Product Type:
Laser soldering systems exert the strongest substitution pressure on manual and semi-automatic equipment, particularly in microelectronics packaging where spot precision below 0.3 mm displaces traditional wave nozzle approaches.
- Fully Automatic Selective Soldering:These systems integrate programmable wave heads with nitrogen inerting and real-time thermal profiling software. Automotive electronics manufacturers in Germany and the United States specify fully automatic lines to satisfy IPC-A-610 Class 3 reliability audits without dedicated rework stations.
- Manual Selective Soldering:Operator-controlled dip soldering stations serve prototype labs and repair facilities requiring rapid process changeover without programming overhead. Demand concentrates in Indian electronics manufacturing clusters where government PLI scheme incentives are building domestic PCB capacity from greenfield bases.
- Semi-Automatic Selective Soldering:Hybrid operator-machine workflows suit mid-volume contract manufacturers balancing flexibility against throughput targets in European automotive tier-two supplier networks.
- Hybrid Systems:Configurations combining selective soldering modules with surface-mount reflow capabilities address mixed-technology board requirements in aerospace wire harness integration programs.
Fully automatic selective soldering retains volume leadership; hybrid systems hold the steepest expansion curve as board complexity blurs traditional process boundaries.
Technology:
Cost tier differentiation separates high-investment laser platforms from standardized infrared infrastructure, with customer type determining thermal technology selection more than application requirements alone.
- Infrared Heating:Multi-zone IR preheat modules deliver consistent energy transfer across varying board geometries and component densities. Stuttgart and Detroit automotive electronics clusters standardize on infrared systems to reduce thermal shock in multilayer PCBs during high-volume production campaigns.
- Laser:Solid-state laser systems achieve sub-millimeter spot accuracy without radiant heat exposure to adjacent surface-mount devices. Camera module and medical sensor manufacturers in Asian consumer electronics contract manufacturing parks specify laser soldering where miniature wave nozzles risk thermal damage.
- Hot Air:Convective heating approaches serve low-thermal-mass applications in prototyping environments requiring rapid temperature ramp profiles.
- Contact Heating:Direct thermal transfer methods address specific through-hole connector types in defense and satellite hardware qualification programs under MIL-STD-202G protocols.
Infrared heating commands the largest installed base; laser soldering is expanding most quickly in precision electronics packaging segments.
End User:
Application maturity varies dramatically across end-use sectors, with automotive functional safety requirements compressing thermal process tolerances faster than consumer electronics volume demands.
- Automotive:Battery management systems and inverter control modules for EV powertrains require through-hole components that withstand high-vibration environments. Tier-one suppliers in Germany, China, and the United States are reorganizing procurement priorities toward selective soldering systems with full production traceability.
- Aerospace:MIL-STD-202G qualification requirements for high-reliability connectors open selective soldering applications in defense and satellite hardware previously dominated by hand soldering operations.
- Consumer Electronics:Asian contract manufacturers in Shenzhen and Suzhou manufacturing parks prioritize footprint efficiency and total cost of ownership in high-mix production environments.
- Industrial Electronics:Process control and automation equipment manufacturers specify selective soldering for legacy through-hole components in long-lifecycle industrial hardware platforms.
Automotive end-use retains volume leadership; aerospace applications are gaining share fastest as defense procurement shifts from manual to automated thermal processes.
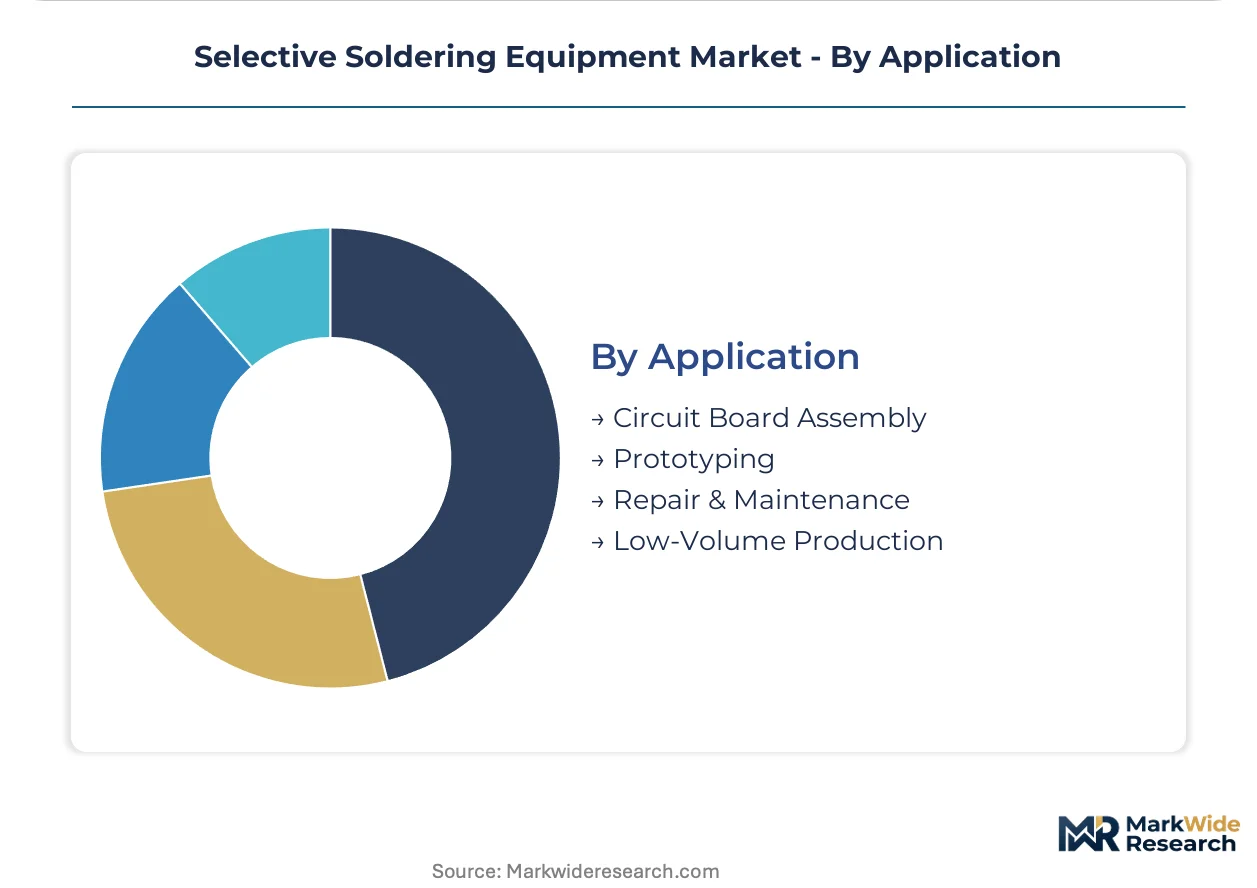
Application:
Customer type concentration determines application segmentation, with OEMs and contract manufacturers diverging sharply in equipment specification priorities and validation timelines.
- Circuit Board Assembly:High-volume production lines for mixed-technology boards integrate selective soldering as a complementary process to surface-mount reflow. ISO 9001 validation protocols require 90-120 day production trials with full traceability documentation before tier-one supplier approval.
- Prototyping:Engineering validation and new product introduction environments demand rapid thermal profile development without dedicated programming resources. Equipment-as-a-service arrangements are penetrating this segment in Asian manufacturing parks where facility ownership prefers operational flexibility.
- Repair & Maintenance:Depot repair operations for aerospace and industrial electronics require selective soldering capability for field-returned assemblies with localized joint failures.
- Low-Volume Production:Specialty electronics manufacturers serving medical and scientific instrumentation markets configure selective soldering for batch sizes below 100 units with frequent changeover requirements.
Circuit board assembly dominates capital expenditure; prototyping applications are climbing the fastest as NPI cycle compression accelerates equipment refresh rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive electronics manufacturers in Germany, China, and the United States drive capital deployment for selective soldering systems, with EV powertrain electrification and RoHS compliance mandates reshaping procurement priorities across precision manufacturing clusters.
Germany
Baden-Württemberg hosts the densest concentration of automotive tier-one electronics suppliers requiring IPC-A-610 Class 3 reliability certification. ECHA enforcement of REACH substance restrictions accelerates lead-free soldering process transitions. Stuttgart manufacturing corridors standardize on multi-zone infrared preheat modules to reduce thermal shock in multilayer PCBs during high-volume EV component production.
China
Shenzhen and Suzhou manufacturing parks prioritize footprint efficiency and total cost of ownership for consumer electronics contract manufacturers. MIIT industrial upgrading guidelines push domestic PCB fabricators toward automated thermal processes. Yangtze River Delta electronics clusters are absorbing nitrogen inerting technology to meet export market quality specifications for automotive and medical device customers.
United States
Detroit automotive electronics corridors reorganize procurement toward fully automatic systems with full production traceability. EPA hazardous air pollutant standards mandate fume extraction efficiency above 98% for flux vapor capture, embedding integrated filtration into machine specifications. Midwest manufacturing facilities specify vapor containment systems from initial procurement rather than retrofitting existing assembly lines.
India
Maharashtra and Karnataka electronics manufacturing zones benefit from PLI scheme incentives building domestic PCB capacity from greenfield bases. BIS quality standards for electronics hardware create validation frameworks for imported selective soldering equipment. Tamil Nadu semiconductor assembly and testing facilities represent virgin installed base potential as government production-linked support scales domestic precision manufacturing capability.
Japan
Kanto region precision equipment manufacturers supply thermal profiling software and motion control systems to global selective soldering OEMs. METI technology roadmaps for next-generation electronics packaging emphasize sub-millimeter accuracy requirements. Osaka-based industrial electronics clusters maintain demand for mixed-technology board processing in long-lifecycle automation and control hardware platforms.
Selective Soldering Equipment Market Competitive Environment
Player mix skews toward German engineering specialists and diversified industrial technology conglomerates with precision automation portfolios. The vendor base concentrates around motion control and thermal management expertise originating from Baden-Württemberg and Bavaria engineering networks. Two strategic archetypes dominate: precision thermal system specialists serving automotive tier-one audits, and diversified automation suppliers leveraging cross-platform software integration. Competitive positioning depends on M&A activity consolidating thermal module suppliers and strategic partnerships linking equipment vendors with nitrogen inerting technology providers.
Among German precision engineering specialists, Ersa GmbH and SEHO Systems GmbH occupy positions exemplifying high-mix, low-volume contract manufacturing expertise across European automotive supply chains. Nordson Corporation anchors the diversified industrial technology tier, representing the convergence of precision flux deposition capability with broad automation platform integration. JUKI Corporation sits within the Asian footprint efficiency archetype, serving contract manufacturers prioritizing total cost of ownership in high-mix consumer electronics environments.
| Leading Market Players |
|---|
| Pillarhouse International |
| Manncorp |
| Ersa GmbH |
| JUKI Corporation |
| Blundell Production Equipment |
| SEHO Systems GmbH |
| Nordson Corporation |
| Hentec Industries |
| RPS Automation |
| Others |
Value Chain & Pricing Dynamics
Laser soldering displacement of miniature wave nozzles in microelectronics packaging simultaneously redraws component sourcing geographies and compresses thermal module pricing tiers, as Asian contract manufacturers arbitrage precision specifications against nitrogen inerting cost structures.
Pricing Analysis
Cost-plus contracts with LME tin indexation dominate solder bar procurement for high-mix contract manufacturers, embedding commodity volatility directly into equipment operating economics. Three-tier pricing structure across premium, standard, and economy levels separates IPC-A-610 Class 3 certified systems from general industrial configurations, with automotive tier-one suppliers showing lowest price sensitivity due to audit-driven qualification requirements. Cost compression in nitrogen-assisted process tiers is intensifying because tin-silver-copper alloy prices track futures volatility. Consumer electronics contract manufacturers in Shenzhen manufacturing parks exhibit highest price sensitivity, prioritizing total cost of ownership over thermal precision specifications.
Supply Chain Analysis
Baden-Württemberg precision motion control suppliers create single-source vulnerability for thermal profiling software and programmable wave head actuators, concentrating critical component origins in German engineering networks. Equipment manufacturers draw from Japanese Kanto region suppliers for solid-state laser modules, Chinese Yangtze River Delta fabricators for nitrogen inerting systems, and Bavarian specialists for multi-zone infrared preheat assemblies. Supply chain risk centers on tariff exposure for laser optics imported under dual-use technology classifications. Distribution runs through direct OEM sales for automotive tier-one accounts and regional distributor networks serving mid-volume contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Selective soldering equipment constitutes a defensive-moat market where IPC-A-610 Class 3 certification requirements create switching costs that lock tier-one automotive suppliers into validated equipment platforms through multi-year production trials.
For Market Incumbents: Consolidate thermal module supplier relationships through captive supply arrangements for precision motion control systems originating in Baden-Württemberg engineering clusters. Acquire nitrogen inerting technology providers to anchor process chemistry integration against emerging laser soldering substitution threats in microelectronics packaging segments. For New Entrants and Emerging Players: Anchor in Indian PLI scheme electronics manufacturing zones where greenfield PCB capacity creates virgin installed base demand without incumbent equipment replacement cycles. Target manual selective soldering configurations for prototype labs and repair facilities in Maharashtra and Karnataka, leveraging equipment-as-a-service financing to bypass capital expenditure barriers among domestic contract manufacturers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed German precision automation specialists holding Ersa GmbH-type positions in European automotive tier supplier networks. Long-term viability hinges on convergence play execution between infrared thermal and laser precision technologies. Monitor MIL-STD-202G qualification pipeline expansion in aerospace wire harness integration as inflection signal for defense procurement automation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Laser-Thermal Hybrid Development | Combined infrared preheating with precision laser finishing addresses mixed-technology board complexity in automotive EV modules. |
| Nitrogen Inerting Integration | Controlled atmosphere soldering modules enable IPC-A-610 Class 3 compliance without dedicated rework stations for tier-one suppliers. |
| Equipment-as-a-Service Launch | Operational expenditure financing models penetrate Asian contract manufacturing parks where facility ownership avoids asset-heavy balance sheets. |
| Indian Manufacturing Footprint | PLI scheme incentives for semiconductor assembly create virgin installed base potential as domestic PCB capacity scales. |
| Aerospace Qualification Investment | MIL-STD-202G certification opens defense and satellite hardware applications previously dominated by hand soldering operations. |
Study Parameters
Operator-level perspectives from thermal process engineers, automotive tier-one procurement directors, contract manufacturing operations managers, and precision equipment maintenance heads anchored the qualitative base for this study. Primary fieldwork combined with secondary validation drew from IPC-A-610 certification databases, EPA hazardous air pollutant compliance filings, ECHA REACH substance restriction registers, and automotive supplier quality audit documentation. Bottom-up equipment shipment tracking and top-down electronics manufacturing capital expenditure analysis provided triangulation across the analysis window.
Sensitivity analysis tested forecast robustness against tin price volatility scenarios and laser soldering substitution pace variations. The analytical framework modeled segmentation across automation intensity, thermal technology type, end-use sector, and geographic production cluster throughout the forecast period. CAGRs derived from equipment replacement cycle analysis, EV powertrain electrification penetration curves, and RoHS compliance mandate timelines. Industry-specific inputs included nitrogen inerting adoption rates and IPC Class 3 certification pipeline data.
Material uncertainties — alloy cost volatility, regulatory enforcement timing, and laser thermal convergence pace — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding automotive functional safety standard evolution and semiconductor packaging miniaturization trajectories. Practitioners should keep alternative scenarios live as ECHA substance restriction enforcement patterns and MIIT industrial upgrading guidelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Epitaxy Equipment Market
Semiconductor Equipment
North America Semiconductor Etch Equipment Market
Semiconductor Equipment
Global Semiconductor Machinery Market
Semiconductor Equipment
Remote Plasma Source Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Semiconductor Process and Control Equipment Market
Semiconductor Equipment
Slide Processing System Market
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
Global Semiconductor Thermal Evaporators Market
Semiconductor Equipment
Temperature Calibration Equipment Market
Semiconductor Equipment
Dry Reactor Market
Semiconductor Equipment
SMT Machine Market
Semiconductor Equipment
China Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
FOUP Cleaning System Market
Semiconductor Equipment
Photolithography Market
Semiconductor Equipment
Semiconductor Bonding Equipment Market