
 Vapor Blasting Machine Market | 2026-2036
Vapor Blasting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Vapor Blasting Machine Market Insights
Specialized equipment distributors is reconfiguring their inventory mix to prioritize automated vapor blasting systems over legacy dry-blast portfolios. Rösler Oberflächentechnik GmbH leverages its German manufacturing base to dominate European supply channels for precision finishing equipment. Vapormatt Ltd. sustains a technology leadership position in wet blasting applications for aerospace component restoration. Empire Abrasive Equipment competes through extensive distributor networks across North American industrial corridors.
A vapor blasting machine injects water and abrasive media into a pressurized stream to clean, finish, or prepare metal surfaces without dimensional distortion; operating pressures typically range from 30 to 120 psi depending on substrate sensitivity. The equipment serves critical functions in aerospace MRO, automotive remanufacturing, and heritage restoration where substrate preservation outweighs stock removal speed. Automated systems command premium positioning due to integration complexity and repeatability requirements in high-volume production environments. Wet blasting technology leads adoption curves as facilities phase out silica-based dry processes under tightening occupational exposure mandates. Restoration applications represent an emerging margin pool as heritage conservation agencies formalize technical specifications for non-destructive surface cleaning.
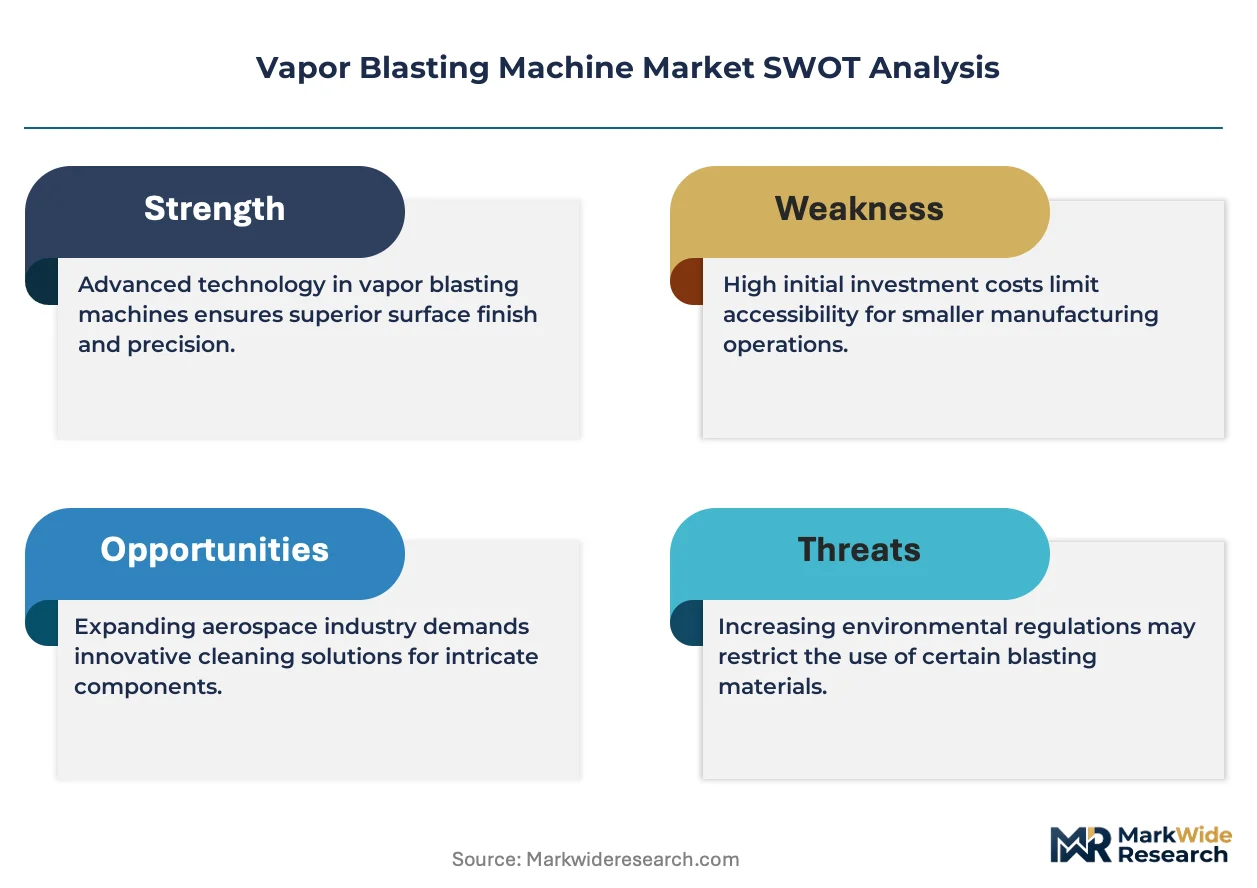
EPA enforcement of silica permissible exposure limits and REACH restrictions on hazardous abrasive classifications are accelerating capital replacement cycles toward closed-loop wet systems. OSHA inspection protocols and CE marking requirements under the Machinery Directive shape procurement specifications for workplace safety integration. Stakeholders must monitor evolving MEE discharge standards in China and emerging state-level variants of silica rules across the United States to anticipate regional equipment specification divergences.
Market Dynamics
EPA enforcement of silica permissible exposure limits and REACH restrictions on hazardous abrasive classifications are accelerating capital replacement cycles toward closed-loop wet systems across aerospace, automotive, and heritage restoration sectors.
Growth Catalysts
- REACH hazardous substance restrictions:European manufacturers face mandated phase-out of silica-based dry blasting media, forcing facility upgrades to wet process equipment that captures airborne particulates through water injection systems.
- Aerospace MRO expansion:Turbine component restoration facilities in Germany, France, and the United States are standardizing vapor blasting protocols for precision surface finishing without substrate distortion.
- Closed-loop water recycling:Advanced filtration modules now enable zero-discharge operation, reducing water consumption costs and aligning with MEE discharge standards in Chinese manufacturing zones.
Market Restraints
- High-purity garnet supply concentration:Premium abrasive media sourcing depends on limited Indian and Australian mining operations, creating input cost volatility and procurement lead time uncertainty.
- CE marking compliance complexity:Machinery Directive conformity assessment procedures extend equipment delivery timelines by four to eight months for European market entry.
- Dry CO2 blasting substitution:Cryogenic cleaning systems compete for heritage restoration contracts where water contact risks substrate damage, particularly in manuscript and textile conservation.
Strategic Opportunities
- India automotive remanufacturing:Engine rebuild clusters in Chennai and Pune remain underpenetrated by automated wet blasting systems, presenting first-mover equipment placement potential.
- ISO 14001 certification mandates:Corporate sustainability frameworks are embedding environmental management system requirements that favor closed-loop surface preparation technologies.
- Robotic integration convergence:Collaborative robot arms paired with vision-guided blasting nozzles enable unmanned operation in high-mix, low-volume precision finishing environments.
Industry Challenges
- Process technician certification gaps:Qualified operators who understand substrate-specific pressure calibration and media selection remain scarce in emerging manufacturing regions.
- Legacy dry-blast infrastructure stranded assets:Facilities with recent investments in pneumatic recovery systems face write-down pressure when converting to wet process layouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vapor Blasting Machine Market |
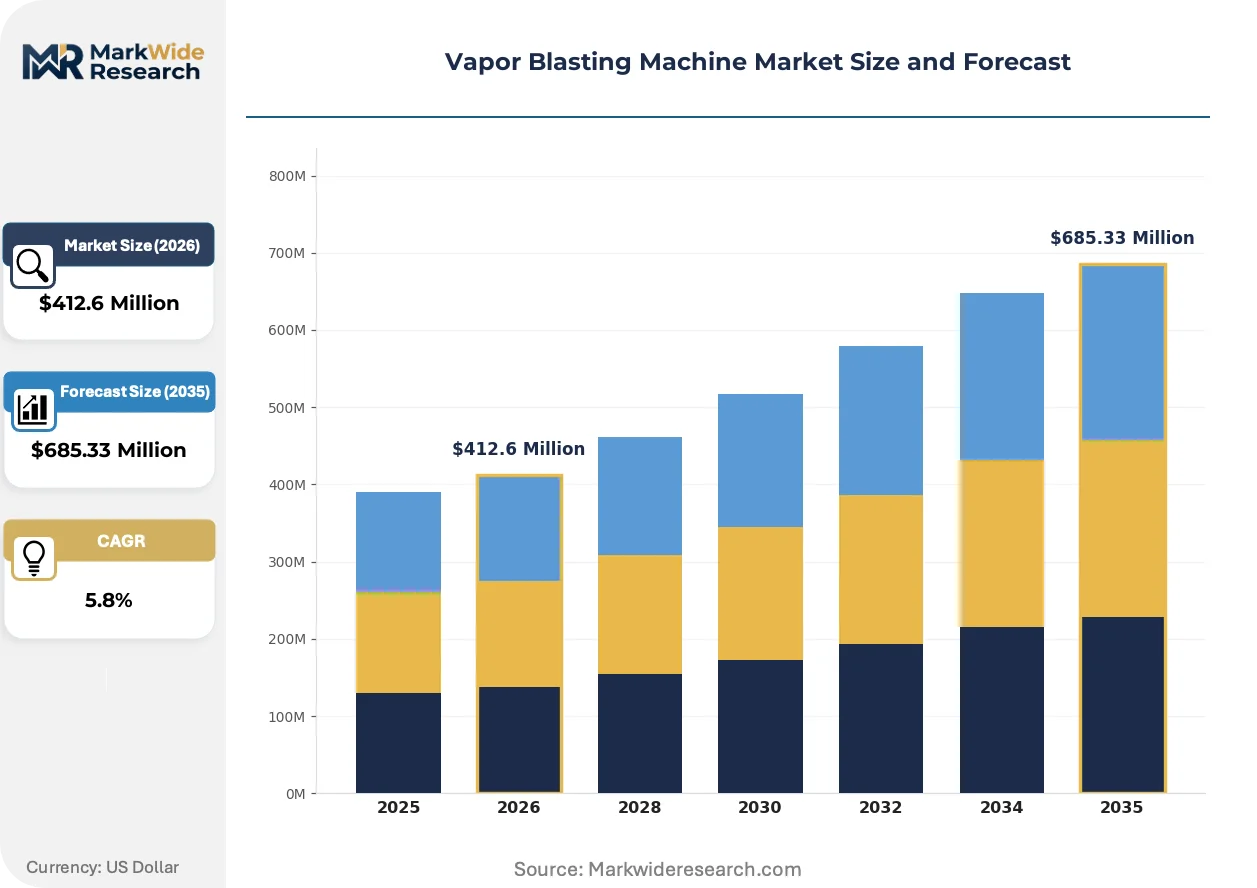
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Machines, Tabletop Machines, Automated Systems, Built-in Units Technology: Wet Blasting, Steam Blasting, Eco-Blasting, Vacuum Blasting End User: Aerospace, Automotive, Manufacturing, Restoration Application: Surface Preparation, Cleaning, Finishing, Coating Removal |
| Companies Covered | Rösler Oberflächentechnik GmbH, Vapor Honing Technologies, Vapormatt Ltd., Empire Abrasive Equipment, Wheelabrator Group, Guyson Corporation, Clemco Industries Corp., Graco Inc., Vixen Surface Treatments Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vapor Blasting Machine Market Trends and Innovations
Wet blasting technology is actively displacing legacy dry abrasive methods as occupational exposure mandates tighten and precision finishing requirements intensify across regulated industries.
Ultrafine abrasive suspension systems are migrating from batch-operated cabinet designs to continuous-flow automated lines. Tier-one automotive suppliers in Stuttgart and Munich are deploying these configurations for powertrain remanufacturing at volumes exceeding five hundred components per shift. The technology is migrating from specialty restoration shops into high-throughput production environments, compressing equipment payback periods below thirty-six months.
OSHA respirable crystalline silica standards are triggering facility-wide process audits at US metalworking plants. Compliance officers are mandating engineering controls that eliminate visible dust generation, redirecting capital budgets toward water-based media delivery systems. Surface preparation contractors in Michigan and Ohio are responding by retrofitting existing booths with pressurized slurry injection modules rather than constructing greenfield installations.
Specification-driven procurement now dominates capital equipment selection for aerospace tier suppliers. Airlines and OEMs are embedding vapor blasting process requirements directly into component repair authorizations, bypassing traditional distributor channels. This pattern concentrates most visibly in Toulouse and Hamburg maintenance corridors, where approved vendor lists determine equipment sourcing eligibility.
Vapor Blasting Machine Market Segmentation
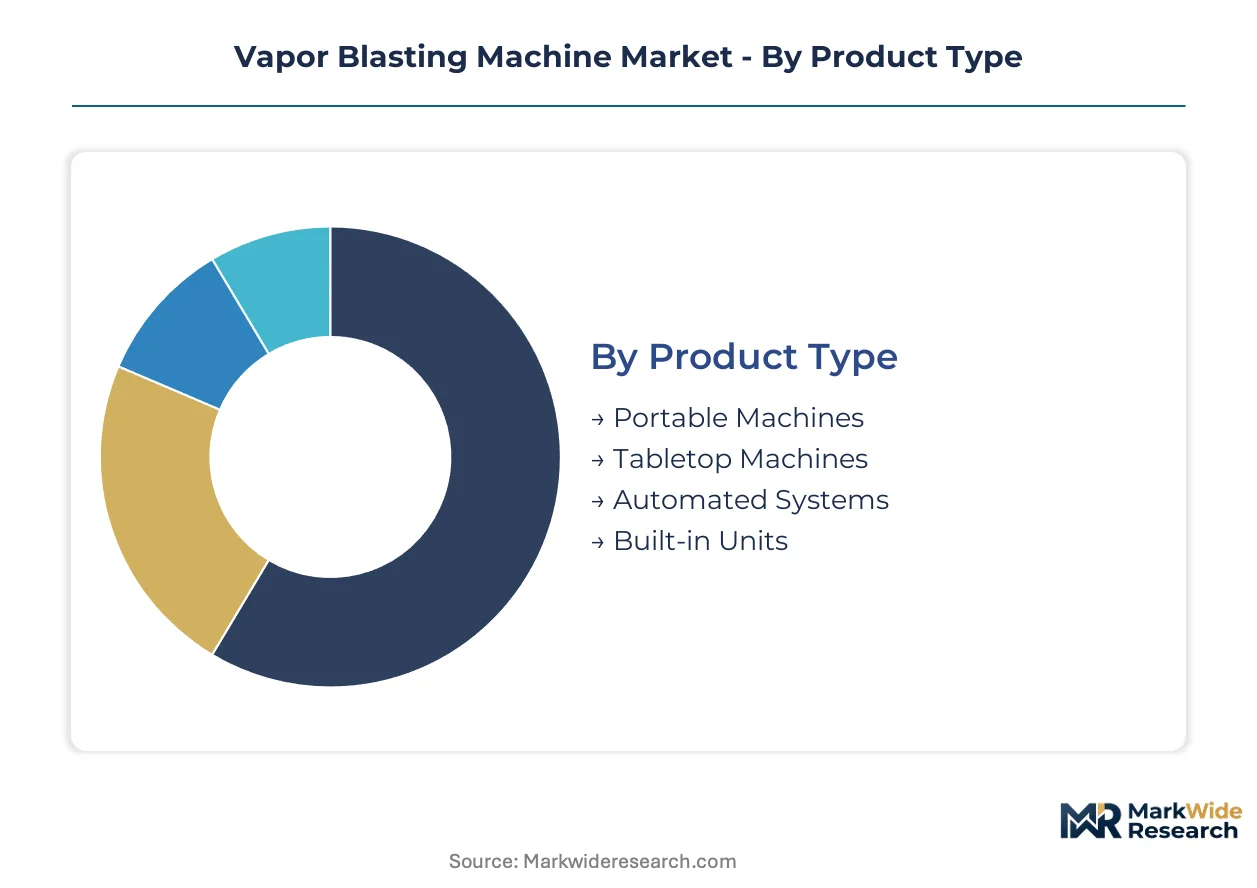
Equipment specification diverges sharply across end-use requirements, with aerospace MRO demanding precision automation while restoration contractors prioritize portability and substrate safety. Understanding these segment boundaries clarifies procurement patterns and technology migration pathways across the forecast window.
Product Type:
Cost tier positioning determines capital deployment cycles and margin capture potential across facility upgrade decisions.
- Portable Machines:Compact wheeled units with integrated water tanks and 20-50 psi operating ranges serve mobile contractors and heritage restoration sites. Demand concentrates in French and Italian conservation corridors where cathedral stonework and bronze monument cleaning requires on-location deployment without fixed infrastructure.
- Automated Systems:CNC-integrated wet blasting cells with robotic nozzle positioning and vision-guided path planning dominate aerospace tier-one supplier facilities. German powertrain remanufacturing clusters around Stuttgart standardize these configurations for turbine blade restoration at volumes exceeding three hundred components per shift.
- Tabletop Machines:Bench-mounted cabinet systems with manual part manipulation address small-batch precision finishing for dental and medical instrument manufacturers.
- Built-in Units:Custom-engineered booth installations with slurry recovery and filtration modules integrate into greenfield production lines.
Automated Systems hold installed capacity. Portable Machines are rotating up the share rankings.
Technology:
Application severity and substrate sensitivity dictate media delivery mechanism selection across regulatory environments.
- Wet Blasting:Pressurized water-abrasive slurry systems operating at 30-120 psi eliminate airborne silica exposure while preserving dimensional tolerances. REACH-mandated phase-outs of dry abrasive processes in European manufacturing zones accelerate replacement demand.
- Eco-Blasting:Biodegradable media suspension systems using organic abrasives and closed-loop water chemistry address MEE discharge standards in Chinese industrial zones. Surface preparation contractors in Shanghai and Shenzhen adopt these configurations to preempt enforcement actions under tightening wastewater protocols.
- Steam Blasting:Superheated vapor injection systems combine thermal energy with minimal abrasive loading for delicate substrate cleaning.
- Vacuum Blasting:Negative-pressure recovery systems capture spent media at the point of contact for hazardous material containment.
Wet Blasting commands the dominant revenue position. Eco-Blasting exhibits the steepest expansion trajectory among emerging technology categories.
End User:
Customer type maturity shapes specification complexity and aftermarket service attachment rates.
- Aerospace:FAA-regulated MRO facilities and OEM repair stations mandate vapor blasting for turbine disk and compressor blade restoration. Component repair authorizations from Airbus and Boeing embed process requirements directly into supplier contracts, bypassing traditional equipment distribution channels.
- Automotive:Engine remanufacturing clusters in Germany and emerging rebuild centers in India drive automated system adoption. OEM warranty programs for remanufactured powertrain components standardize wet blasting surface preparation to ensure coating adhesion and fatigue resistance.
- Manufacturing:General metal fabrication and tool-and-die shops deploy vapor blasting for mold cleaning and die refurbishment.
- Restoration:Heritage conservation agencies and monument preservation specialists specify low-pressure wet systems for non-destructive cleaning of historic substrates.
Aerospace holds installed capacity. Automotive is rotating up the share rankings.
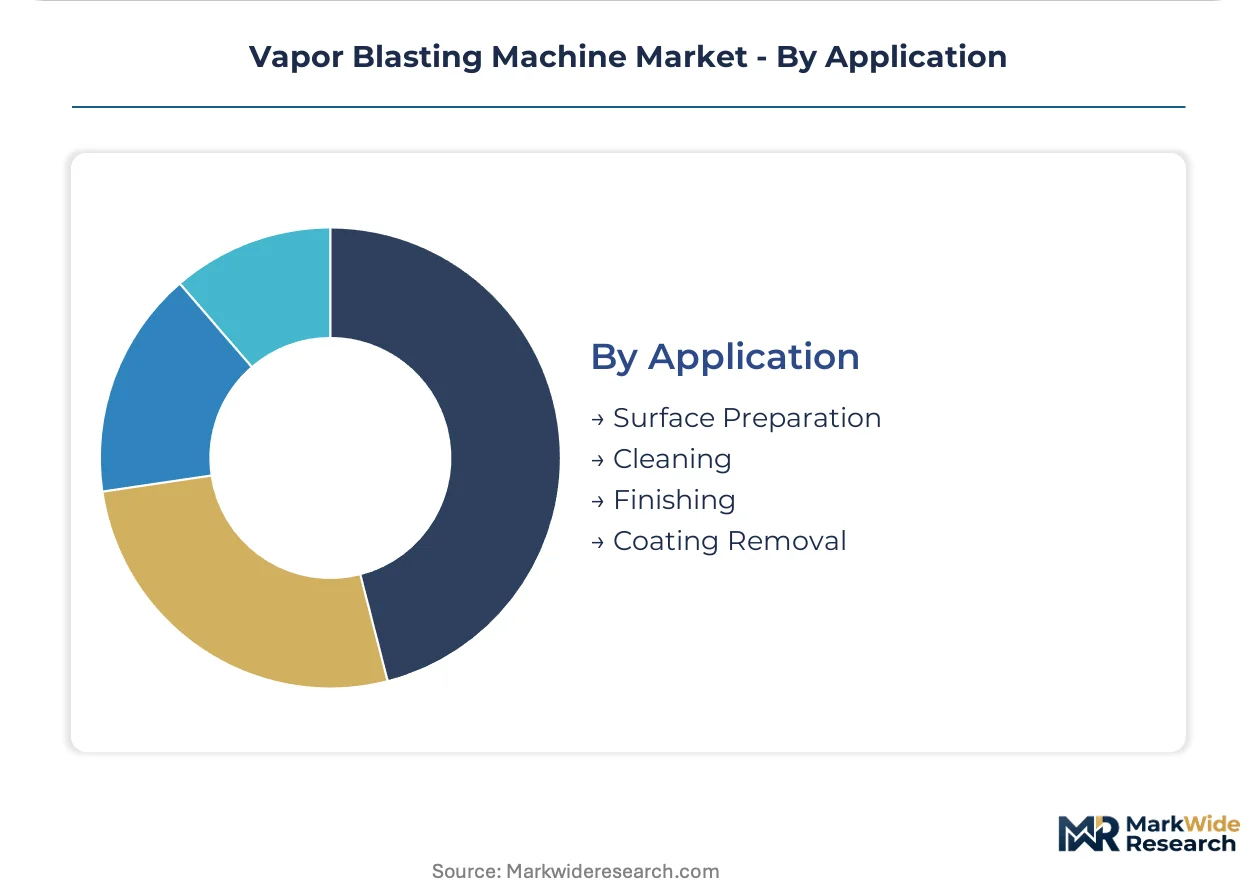
Application:
Volume throughput requirements separate high-mix precision environments from bulk surface conditioning operations.
- Surface Preparation:Pre-coating activation and adhesion promotion for thermal spray, plating, and organic finishes. Automotive remanufacturing facilities in Michigan and Ohio deploy these processes for crankshaft and camshaft restoration under EPA silica enforcement pressure.
- Finishing:Cosmetic surface refinement and uniform matte texture generation for architectural metalwork and consumer products. Italian design-manufacturing clusters around Milan specify vapor blasting for premium hardware and fixture production.
- Cleaning:Degreasing and contaminant removal without substrate removal for maintenance and repair operations.
- Coating Removal:Selective stripping of degraded paints, primers, and thermal barriers from complex geometries.
Surface Preparation holds installed capacity. Finishing is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers command premium pricing power for precision-engineered wet blasting systems, while Chinese fabricators compete on cost-efficient standardized units for emerging industrial zones.
United States
EPA enforcement of respirable crystalline silica standards drives facility-wide process audits at metalworking plants in Michigan and Ohio. OSHA inspection protocols mandate engineering controls that eliminate visible dust generation, redirecting capital budgets toward water-based media delivery systems. Surface preparation contractors in the Great Lakes industrial corridor retrofit existing booths with pressurized slurry injection modules.
Germany
REACH-mandated phase-outs of silica-based dry blasting media force manufacturing upgrades to wet process equipment. The Machinery Directive shapes procurement specifications through CE marking conformity assessments that extend delivery timelines. Precision engineering clusters around Stuttgart and Munich drive replacement cycles for automated vapor blasting cells in powertrain remanufacturing facilities.
China
MEE discharge standards tighten wastewater protocols in Shanghai and Shenzhen manufacturing zones, accelerating adoption of closed-loop water recycling configurations. Surface preparation contractors deploy eco-blasting systems with biodegradable media suspensions to preempt enforcement actions. Yangtze River Delta industrial parks standardize zero-discharge wet blasting for automotive component restoration.
India
Engine rebuild clusters in Chennai and Pune remain underpenetrated by automated wet blasting systems, presenting first-mover equipment placement potential. The country's national environmental regulator tightens industrial discharge norms for surface treatment operations. Automotive remanufacturing facilities in Maharashtra and Tamil Nadu phase in water-based media delivery to replace legacy pneumatic systems.
France
Heritage conservation agencies formalize technical specifications for non-destructive surface cleaning of cathedral stonework and bronze monuments. ANSM oversight of occupational exposure limits aligns with broader European hazardous substance restrictions. Conservation corridors in Paris and Lyon drive demand for portable low-pressure wet systems with mobile deployment capabilities.
Vapor Blasting Machine Market Competitive Landscape
German precision-engineering specialists and North American diversified industrial conglomerates split the market between premium automated systems and broad distribution coverage. Equipment specification complexity favors players with captive manufacturing capabilities and established service networks. Three archetypes dominate: vertically integrated European specialists with in-house component production, North American distributors leveraging extensive dealer networks, and Asian fabricators competing on standardized unit economics. Consolidation pressure intensifies through strategic partnerships for robotic integration and geographic expansion into underpenetrated remanufacturing clusters.
Within the European specialist tier, Rösler Oberflächentechnik GmbH exemplifies precision-engineering dominance through its Baden-Württemberg manufacturing base. Vapormatt Ltd. occupies a position in wet blasting technology leadership for aerospace component applications. Empire Abrasive Equipment represents North American distribution-scale competitiveness across industrial corridors. These three anchors illustrate the geographic and strategic segmentation that defines procurement patterns for specification-driven buyers.
| Leading Market Players |
|---|
| Rösler Oberflächentechnik GmbH |
| Vapor Honing Technologies |
| Vapormatt Ltd. |
| Empire Abrasive Equipment |
| Wheelabrator Group |
| Guyson Corporation |
| Clemco Industries Corp. |
| Graco Inc. |
| Vixen Surface Treatments Ltd. |
| Others |
Pricing and Supply Chain Analysis
Stuttgart precision engineering clusters anchor European supply capacity for automated vapor blasting cells, translating manufacturing density into premium pricing power for configured-to-order systems while standard portable units face cost compression from Asian fabricators.
Pricing Analysis
Customization-premium spreads separate configured-to-order automated systems from standardized portable units. Pricing stratifies across premium, standard, and economy tiers based on CE certification grade and robotic integration complexity. Cost compression in economy-tier portable machines intensifies due to Chinese fabricator capacity expansion. Automotive remanufacturing facilities exhibit highest price sensitivity, while aerospace MRO stations prioritize specification compliance over unit economics.
Supply Chain Analysis
Supplier-financing facilities with 90-120 day extended terms have become standard for European equipment procurement, easing capital deployment for facility upgrades. Component sourcing draws from Germany for precision-engineered slurry pumps, China for filtration modules, and India for garnet abrasive media. Single-source vulnerability concentrates in high-purity garnet supply from Australian and Indian mining operations. Distribution runs through specialized industrial equipment distributors with factory-trained service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vapor blasting machine market represents an early-cycle expansion story, with REACH-mandated dry abrasive phase-outs and EPA silica enforcement creating sustained replacement demand across regulated manufacturing corridors.
For Market Incumbents: Pre-empt dry CO2 blasting substitution in heritage restoration by embedding closed-loop water recycling as a standard feature rather than optional upgrade. Deepen in-house production of precision slurry pumps to defend margin position against Chinese component imports. Accelerate CE marking pre-certification for next-generation robotic integration modules. For New Entrants and Emerging Players: Engine rebuild clusters in Chennai and Pune represent the most penetrable entry point for automated wet blasting systems, given underpenetration by established European suppliers. Target mobile contractor segments in French conservation corridors with portable units featuring integrated water tanks and rapid-deployment chassis. Pursue specification-driven procurement channels by aligning with Airbus and Boeing approved vendor list requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists with captive manufacturing of precision finishing components over pure-play distributors. Long-term viability hinges on robotic integration convergence and aftermarket service attachment rates. Monitor MEE enforcement intensity in Yangtze River Delta industrial parks as an inflection indicator for Chinese market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Integration Partnership | Collaborative robot arm deployment enables unmanned precision finishing in high-mix aerospace environments. |
| Closed-Loop Water Recycling Certification | Zero-discharge system validation aligns with MEE standards and ISO 14001 sustainability mandates. |
| CE Marking Pre-Assessment Investment | Accelerated Machinery Directive conformity reduces delivery timelines for European market entry. |
| Garnet Supply Agreement Diversification | Dual-sourcing from Indian and Australian mining operations mitigates input cost volatility exposure. |
| Heritage Conservation Specification Development | ANSM-aligned technical standards for non-destructive cleaning open institutional procurement channels. |
Research Methodology
The analysis maps portable machines, automated systems, tabletop units, and built-in installations, each validated through equipment procurement managers, plant engineers, aftermarket service heads, and OEM technical directors. Primary fieldwork combined structured interviews with secondary validation against EPA enforcement records, REACH substance restriction databases, SEC 10-K filings from diversified industrial conglomerates, and customs data for abrasive media trade flows. Bottom-up equipment shipment analysis triangulated against top-down capital expenditure surveys across aerospace MRO, automotive remanufacturing, and heritage restoration sectors.
Assumptions held fixed include REACH hazardous substance restrictions and EPA silica permissible exposure limits, while variables included MEE discharge standard tightening velocity and robotic integration adoption curves. Segmentation modeling incorporated product type, technology mechanism, end-user industry, and application severity across the projection horizon. CAGRs derived from equipment replacement cycle analysis and facility upgrade intention surveys, with specific inputs from aerospace component repair authorization trends and automotive powertrain remanufacturing volume projections.
Practitioners should monitor regulatory enforcement intensity variations and substitute technology performance advances for early signals of demand trajectory shifts. Forecasts reflect documented assumptions; deviation in macroeconomic conditions, regulatory implementation timelines, or wet blasting technology substitution rates would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
North America Battery Manufacturing Equipment Market
Semiconductor Equipment
X-Ray Lithography Equipment Market
Semiconductor Equipment
DUV Lithography Systems Market
Semiconductor Equipment
Automatic Dicing Saw Market
Semiconductor Equipment
Wafer Back-Grinding Machine Market
Semiconductor Equipment
Remote Plasma Source Market
Semiconductor Equipment
Global Equipment Front End Module (EFEM) Market
Semiconductor Equipment
Solar Module Production Equipment Market
Semiconductor Equipment
Underfill Dispenser Market
Semiconductor Equipment
North America Semiconductor Etch Equipment Market
Semiconductor Equipment
4-Inch SiC Laser Annealing Equipment Market
Semiconductor Equipment
Multi-Touch Equipment Market
Semiconductor Equipment
Global Atomic Layer Deposition (ALD) Equipment Market
Semiconductor Equipment
SMT Reflow Soldering Equipment Market
Semiconductor Equipment
Nanoimprint Lithography System Market
Semiconductor Equipment
Laser Annealing System Market