
 Quadriplegia Treatment Market | 2026-2036
Quadriplegia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Quadriplegia Treatment Market Analytics
Buyer concentration among large hospital systems and integrated rehabilitation networks is realigning procurement standards for quadriplegia care technologies. Medtronic plc leverages its neurostimulation portfolio to sustain institutional contracts across major academic medical centers. Stryker Corporation anchors its position through orthopedic and rehabilitation equipment integration within hospital supply chains. Sanofi S.A. competes via pharmaceutical interventions targeting secondary complications of spinal cord injury.
Quadriplegia treatment encompasses medical, surgical, and rehabilitative interventions targeting complete or incomplete cervical spinal cord lesions resulting in impairment of all four limbs and torso. Functional electrical stimulation parameters typically operate at 20-50 Hz pulse frequencies to activate paralyzed musculature for movement restoration. Neuromodulation technologies capture premium positioning due to implantable device complexity and specialized surgical placement requirements. Rehabilitation centers represent the fastest-growing end user segment as payers shift reimbursement toward intensive outpatient protocols. Assistive robotics commands concentrated R&D investment despite higher per-unit costs, while mobility aids maintain volume leadership through established distribution.
The FDA breakthrough device program and CMS national coverage determination processes shape market access timelines for novel neural interfaces and closed-loop stimulation systems. ISO 13485 quality management requirements and IEC 60601 electrical safety standards govern manufacturing compliance for active implantable rehabilitation devices. The EU Medical Device Regulation imposes additional clinical evidence burdens on manufacturers seeking European market entry. Stakeholders must monitor reimbursement parity between institutional and home-based settings as technology miniaturization expands care delivery options.
Market Dynamics
The FDA breakthrough device designation pathway is compressing commercialization timelines for neural interface developers, while CMS reimbursement decisions for closed-loop neuromodulation systems determine institutional adoption rates across specialized rehabilitation centers.
Growth Catalysts
- Breakthrough Device Designation:The FDA's accelerated review pathway for neural interfaces reduces regulatory timelines, enabling faster patient access to brain-computer implant technologies.
- Intensive Outpatient Protocols:Payer reimbursement shifts toward rehabilitation centers as the primary delivery site for functional electrical stimulation therapy, expanding addressable patient volumes.
- Neuromodulation Platform Expansion:Hospital networks are integrating implantable pulse generators with robotic rehabilitation systems to restore upper extremity function in cervical spinal cord injury patients.
Market Restraints
- Implantable Device Costs:The specialized surgical placement requirements and biocompatible materials in neural interfaces create prohibitive per-procedure expenses for standard insurance coverage tiers.
- Clinical Evidence Burdens:The EU Medical Device Regulation imposes additional prospective trial requirements on manufacturers seeking CE marking for active implantable rehabilitation devices.
- Technical Limitation:Current functional electrical stimulation systems operate within constrained 20-50 Hz pulse frequency ranges that limit fine motor control restoration in high-cervical lesions.
Strategic Opportunities
- Home-Based Care Delivery:Technology miniaturization is enabling portable neuromodulation systems for patient-managed therapy outside institutional settings, expanding reimbursement parity negotiations.
- Assistive Robotics Convergence:The integration of exoskeleton platforms with real-time neural signal processing creates closed-loop mobility restoration protocols for incomplete spinal cord injuries.
- Secondary Complication Prevention:Pharmaceutical interventions targeting autonomic dysreflexia and pressure ulcer management represent adjacent revenue streams for rehabilitation networks.
Industry Challenges
- Neurorehabilitation Specialist Scarcity:The limited pool of physicians trained in functional electrical stimulation parameter programming constrains patient throughput at implanting centers.
- ISO 13485 Compliance Intensity:Active implantable device manufacturers face extended quality management system certification timelines that delay product launches by 18-24 months.
- Legacy System Integration:Closed-loop stimulation platforms require extensive retrofitting of existing hospital electromyography infrastructure, creating deployment friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quadriplegia Treatment Market |
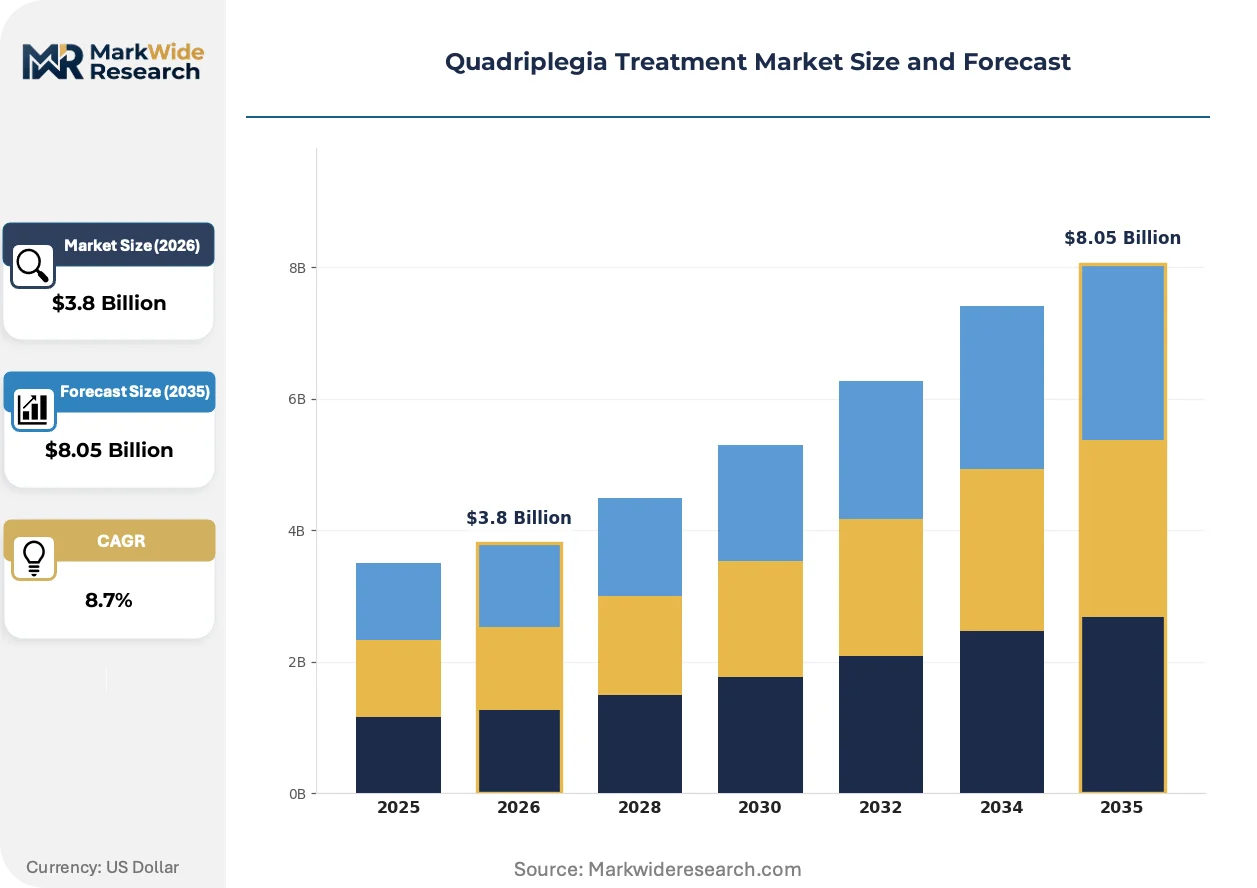
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rehabilitation Devices, Physiotherapy Equipment, Mobility Aids, Neuromodulation Technologies End User: Hospitals, Rehabilitation Centers, Home Care, Long-term Care Facilities Technology: Electrical Stimulation, Assistive Robotics, Virtual Reality, Biofeedback Systems Application: Neurological Rehabilitation, Pain Management, Functional Training, Occupational Therapy |
| Companies Covered | Johnson & Johnson Services Inc., Merck & Co., Sanofi S.A., Bristol Myers Squibb Co., AstraZeneca plc, Medtronic plc, Stryker Corporation, GlaxoSmithKline plc, Roche Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quadriplegia Treatment Market Evolving Landscape
Neural signal processing architectures are migrating toward edge-computing implementations, enabling real-time adaptive stimulation without cloud dependency. This shift is compressing latency thresholds for brain-controlled prosthetic systems.
Wireless power transfer systems for implantable neuromodulation devices are decentralizing surgical follow-up requirements by eliminating percutaneous leads. Academic medical centers in the United States are piloting transcutaneous energy delivery platforms that reduce infection risk profiles. The structural consequence is decentralizing care delivery from tertiary centers toward community-based rehabilitation facilities.
The EU Medical Device Regulation's enhanced clinical evidence requirements are forcing manufacturers to conduct prospective post-market surveillance studies for neural interface longevity claims. European notified bodies are demanding extended follow-up data on electrode degradation rates in cervical spinal cord applications. Manufacturers are responding by front-loading clinical trial investment to secure CE marking before pursuing FDA parallel submissions.
Hospital procurement committees are consolidating vendor contracts for rehabilitation technology stacks, bundling neuromodulation hardware with ongoing programming services. Integrated delivery networks are negotiating multi-year service agreements that lock in technical support and parameter optimization visits. This concentration is most visible in the United States, where specialized spinal cord injury centers operate within consolidated health systems.
Quadriplegia Treatment Market Segmentation
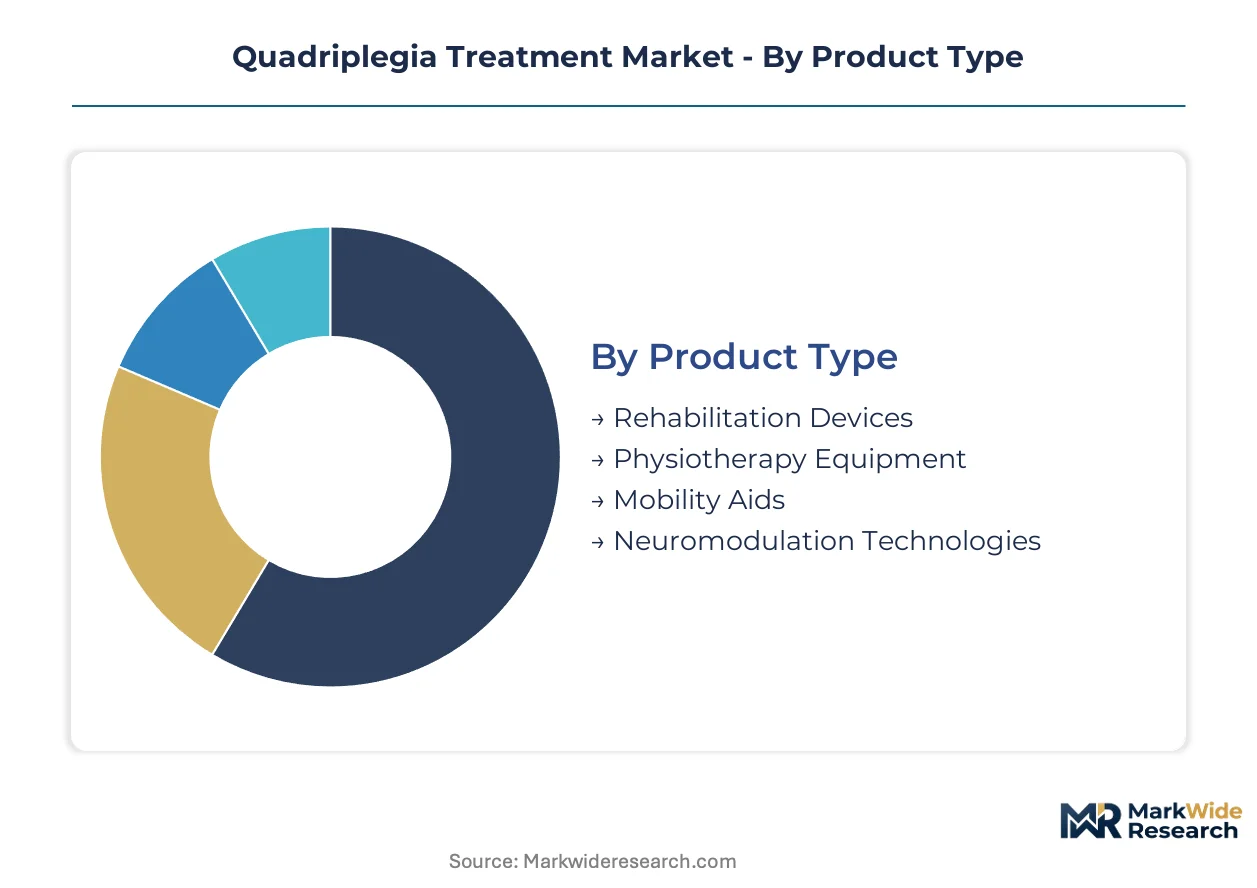
Quadriplegia treatment markets fragment across four distinct taxonomies that determine procurement pathways and reimbursement logic. Product type segmentation governs capital expenditure cycles, while end-user classification shapes regulatory submission strategies. Technology and application dimensions further differentiate clinical outcomes and payer coverage tiers.
Product Type:
Procurement committees differentiate capital equipment by surgical invasiveness and programming complexity.
- Neuromodulation Technologies:Implantable pulse generators with biocompatible electrode arrays require specialized surgical placement and ongoing parameter optimization. United States academic medical centers concentrate demand for these systems as payers expand coverage for functional restoration protocols.
- Rehabilitation Devices:Functional electrical stimulation platforms operating at 20-50 Hz pulse frequencies activate paralyzed musculature for movement restoration. Rehabilitation centers in the United States are expanding utilization as intensive outpatient protocols gain reimbursement parity.
- Mobility Aids:Wheelchairs, patient lifts, and transfer equipment maintain established distribution through durable medical equipment suppliers.
- Physiotherapy Equipment:Range-of-motion and strength-training devices support secondary complication prevention in institutional settings.
Mobility aids lead volumes today; neuromodulation technologies are gaining share fastest.
End User:
Care delivery site determines device classification under FDA pathways and CMS reimbursement codes.
- Rehabilitation Centers:Specialized spinal cord injury facilities integrate neuromodulation platforms with robotic systems for upper extremity function restoration. Payer reimbursement shifts toward these sites are expanding addressable patient volumes beyond traditional hospital settings.
- Hospitals:Academic medical centers anchor implantable device placement through neurosurgical and physiatry departments. FDA breakthrough device designations accelerate commercial timelines for developers targeting these institutional contracts.
- Home Care:Technology miniaturization enables portable stimulation systems for patient-managed therapy outside institutional settings.
- Long-term Care Facilities:Skilled nursing operations concentrate demand for pressure ulcer prevention and autonomic dysreflexia management protocols.
Hospitals retain the highest revenue per patient; rehabilitation centers are expanding most quickly.
Technology:
Technical architecture determines latency thresholds and integration requirements with existing electromyography infrastructure.
- Electrical Stimulation:Functional and transcutaneous systems deliver targeted muscle activation with constrained pulse frequency ranges. Current limitations in fine motor control for high-cervical lesions are driving R&D toward adaptive parameter algorithms.
- Assistive Robotics:Exoskeleton platforms with real-time neural signal processing create closed-loop mobility restoration for incomplete injuries. Convergence with neuromodulation systems commands concentrated investment despite higher per-unit costs.
- Virtual Reality:Immersive environments for motor imagery and task-specific training support neuroplasticity protocols in rehabilitation centers.
- Biofeedback Systems:Surface electromyography and physiological monitoring enable patient-driven parameter adjustment during therapy sessions.
Electrical stimulation dominates installed base; assistive robotics is climbing the fastest.
Application:
Clinical indication determines outcome measurement frameworks and payer evidence requirements.
- Neurological Rehabilitation:Motor and sensory function restoration protocols target ASIA impairment scale improvements. FDA breakthrough designations and CMS national coverage determinations shape market access timelines for novel interventions.
- Functional Training:Activities of daily living restoration drives reimbursement for upper extremity neuroprosthetics and grasp-release systems. United States specialized centers concentrate demand for these outcomes-based protocols.
- Pain Management:Neuropathic and musculoskeletal pain interventions address secondary complications of spinal cord injury.
- Occupational Therapy:Adaptive equipment and environmental modification support community reintegration goals.
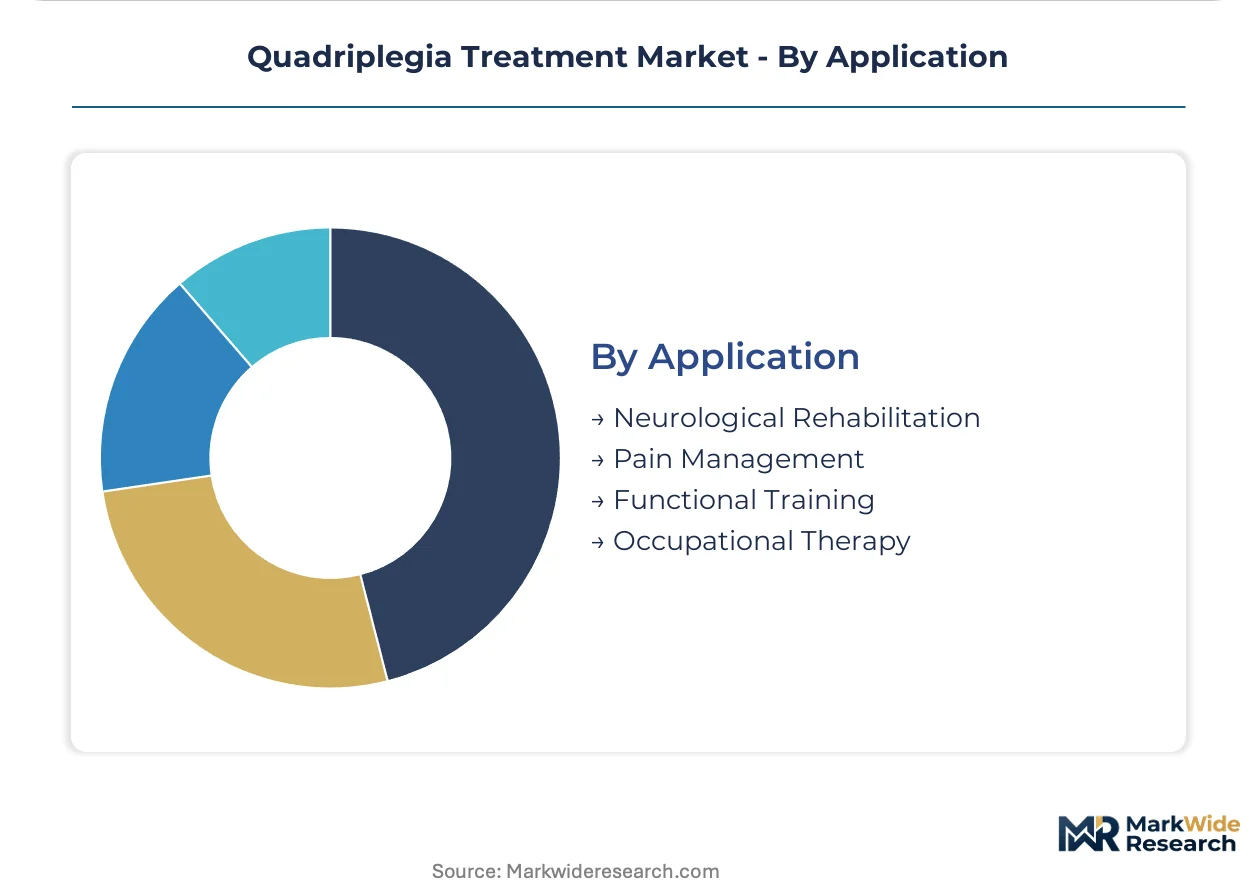
Neurological rehabilitation captures the largest addressable population; functional training is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized neurorehabilitation physicians and neurosurgeons concentrate in established academic medical centers across five national markets. Their institutional affiliations determine patient access to advanced mobility restoration protocols and implantable neuromodulation systems.
United States
FDA breakthrough device designations accelerate commercial timelines for neural interface developers targeting academic medical centers. CMS national coverage determinations for closed-loop neuromodulation systems shape institutional adoption rates. The Baltimore-Washington corridor and Boston-Cambridge cluster anchor specialized spinal cord injury rehabilitation networks with concentrated payer-funded access.
Germany
EU Medical Device Regulation clinical evidence requirements drive extended post-market surveillance studies for neural interface longevity claims. The country's national pharmaceutical regulator enforces stringent biocompatibility standards for active implantable devices. The Heidelberg-Mannheim medical technology corridor concentrates rehabilitation engineering research and specialized neurosurgical placement capabilities.
Japan
PMDA regulatory frameworks govern approval pathways for functional electrical stimulation systems targeting cervical spinal cord injuries. METI industrial policy supports assistive robotics convergence with neuromodulation platforms. The Tokyo-Osaka corridor hosts specialized rehabilitation centers integrating exoskeleton systems with real-time neural signal processing.
Switzerland
Swissmedic certification requirements for active implantable devices align with ISO 13485 quality management standards. The country's national pharmaceutical regulator emphasizes extended follow-up data on electrode degradation rates. The Zurich-Basel corridor anchors neurotechnology R&D clusters with specialized surgical placement expertise.
United Kingdom
NICE technology appraisal processes determine reimbursement eligibility for novel neural interfaces within NHS specialized rehabilitation services. The country's national pharmaceutical regulator coordinates with MHRA post-Brexit device certification pathways. The London-Oxford-Cambridge golden triangle concentrates neuroprosthetics research and clinical trial infrastructure.
Quadriplegia Treatment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across implantable device and pharmaceutical intervention segments. The market structure tiers across three distinct competitive archetypes: diversified medical technology conglomerates with neurostimulation portfolios, orthopedic and rehabilitation equipment integrators, and pharmaceutical developers targeting secondary complications. Strategic moves concentrate on institutional contract consolidation and multi-year service agreement negotiations.
Within the diversified medical technology tier, Medtronic plc and Stryker Corporation occupy anchor positions. Medtronic exemplifies the neurostimulation-focused conglomerate archetype through its institutional contract presence across major academic medical centers. Stryker represents the orthopedic-rehabilitation integration model within hospital supply chains. Sanofi S.A. sits within the pharmaceutical intervention segment, targeting autonomic dysreflexia and pressure ulcer management as adjacent revenue streams.
| Leading Market Players |
|---|
| Johnson & Johnson Services Inc. |
| Merck & Co. |
| Sanofi S.A. |
| Bristol Myers Squibb Co. |
| AstraZeneca plc |
| Medtronic plc |
| Stryker Corporation |
| GlaxoSmithKline plc |
| Roche Holdings Inc. |
| Others |
Value Network & Pricing Analysis
Neurosurgeon and biomedical engineer concentrations in the Baltimore-Washington corridor and Boston-Cambridge cluster create labor-cost differentials that widen pricing-tier spreads between academic medical centers and community rehabilitation facilities.
Pricing Analysis
The bundled-vs-unbundled service split separates institutional procurement contracts from discrete device transactions. Three-tier pricing structure across premium implantable systems, standard rehabilitation platforms, and economy mobility aids reflects FDA breakthrough designation premiums and ISO 13485 certification tiers. Pricing pressure stems from CMS reimbursement parity negotiations between institutional and home-based settings. Hospital systems demonstrate lowest price sensitivity due to bundled multi-year service agreements, while long-term care facilities face acute budget constraints.
Supply Chain Analysis
Direct-to-hospital channels handle high-complexity neuromodulation demand, while durable medical equipment distributors manage volume mobility aid flows. Manufacturing concentrates in the United States, Germany, and Switzerland for active implantable devices, with component sourcing from Japan and South Korea for electrode arrays and pulse generators. Supply chain risk centers on single-source vulnerability for biocompatible electrode materials. Distribution runs through GPO-negotiated contracts for integrated delivery networks and specialized rehabilitation center procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology miniaturization is compressing per-unit production costs while expanding premium-tier home-based system demand, creating margin expansion headroom across neuromodulation portfolios.
For Market Incumbents: Deepen institutional contract consolidation by locking multi-year parameter optimization service agreements with major academic medical centers. Expand backward integration into electrode biocompatibility testing to deflect ISO 13485 certification delays threatening product launch timelines. Counter emerging portable neuromodulation entrants by accelerating FDA breakthrough pathway submissions for next-generation closed-loop systems.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in assistive robotics presents white-space capture opportunity. Target rehabilitation centers in the United States pursuing intensive outpatient protocol expansion as the most penetrable end-user segment. Pursue strategic partnerships with exoskeleton developers to bundle neural signal processing capabilities without captive hardware manufacturing.
For Investors and Strategic Acquirers: Diversified medical technology conglomerates are the most active acquirer in this space, consolidating neurostimulation portfolios through platform integration plays. Five-to-ten year viability hinges on reimbursement strategy execution for home-based care delivery. Watch CMS national coverage determination timelines for closed-loop neuromodulation as the critical inflection signal for institutional adoption acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerates commercial timelines for neural interface developers targeting academic medical center contracts. |
| CE Marking Pathway Investment | Front-loads clinical trial expenditure to satisfy EU Medical Device Regulation post-market surveillance demands. |
| Hospital System Partnership | Locks multi-year service agreements bundling neuromodulation hardware with ongoing programming support. |
| Software Companion Development | Enables real-time adaptive stimulation parameter adjustment without specialized physician intervention. |
| Reimbursement Strategy Execution | Secures CMS coverage parity between institutional and home-based functional electrical stimulation therapy. |
Research Methodology
Multiple input streams — primary interviews with neurosurgeons, rehabilitation physicians, hospital procurement managers, and biomedical engineers; secondary validation against FDA 510(k) filings, CMS national coverage determination records, and hospital GPO contract databases; and trade data on implantable device component flows — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, end user, technology architecture, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from installed base growth rates, replacement cycle compression, and reimbursement expansion modeling. Forecast inputs incorporated neural interface longevity assumptions and electrode degradation rate trajectories from European post-market surveillance studies.
Caveats apply where FDA breakthrough designation revocation, CMS reimbursement code denial, or EU Medical Device Regulation notified body capacity constraints could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cerebral Folate Deficiency Market
Specialty Medicine
Neuroendocrine Carcinoma Treatment Market
Specialty Medicine
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market
Specialty Medicine
Piriformis Syndrome Treatment Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Tropical Spastic Paraparesis Market
Specialty Medicine
Cerebral Vasospasm Market
Specialty Medicine
Hereditary Angioedema Market
Specialty Medicine
APOL1 Mediated Kidney Disease Market
Specialty Medicine
Chromoblastomycosis Treatment Market
Specialty Medicine
Iron Deficiency Anemia Therapy Market
Specialty Medicine
Anal Cancer Market
Specialty Medicine
Global Gastrointestinal Therapeutics Market
Specialty Medicine
Global Laryngeal Cancer Therapeutics Market
Specialty Medicine
Mucous Membrane Pemphigoid Treatment Market
Specialty Medicine
Global Attention Deficit Hyperactivity Disorder Market