
 Major Depressive Disorder (MDD) Treatment Market | 2026-2036
Major Depressive Disorder (MDD) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Major Depressive Disorder (MDD) Treatment Market Outlook
FDA Breakthrough Therapy Designation is rotating the competitive threshold for MDD drug developers, elevating candidates with novel mechanisms above conventional antidepressant portfolios. Eli Lilly and Company leverages its CNS research infrastructure to sustain a pipeline of next-generation serotonergic modulators. Johnson & Johnson (Janssen) anchors its position through esketamine-based intranasal platforms for treatment-resistant depression. Pfizer Inc. competes across both established SSRI franchises and emerging gene-therapy adjacencies.
Major Depressive Disorder treatment encompasses pharmacological interventions targeting monoaminergic and glutamatergic neurotransmission, with therapeutic indices calibrated against Hamilton Depression Rating Scale endpoints and sustained remission thresholds. The primary commercial purpose is restoration of functional capacity in patients failing first-line selective serotonin reuptake inhibitor protocols. Among product type categories, atypical antidepressants occupy the fastest-expanding margin pool as clinicians seek alternatives to sexual dysfunction and weight gain profiles associated with earlier drug classes. Injectable delivery modes command premium positioning within hospital settings where rapid behavioral stabilization is clinically mandated, while oral formulations retain volume dominance across outpatient and homecare channels.
FDA, EMA, and national equivalents such as Japan's PMDA govern MDD treatment approval through distinct efficacy and safety evidentiary standards, with FDA's accelerated approval pathways creating earlier revenue recognition opportunities than EMA's conditional marketing authorization structure. Regulatory divergence in suicidality warning requirements directly shapes prescriber liability exposure and product label differentiation across jurisdictions. Stakeholders must monitor how CMS and private payor coverage determinations for digital therapeutics adjuncts will reshape traditional drug-centric reimbursement models.
Market Dynamics
FDA breakthrough therapy designations for rapid-acting antidepressants are compressing clinical trial timelines and redirecting R&D investment toward glutamatergic mechanisms, reshaping competitive entry barriers for novel MDD therapeutics.
Growth Catalysts
- Esketamine intranasal platforms:Treatment-resistant depression protocols in United States outpatient clinics are expanding addressable patient pools beyond conventional SSRI failures.
- Japan's PMDA accelerated review pathways:Novel serotonergic modulators receive priority status, shortening time-to-market for next-generation antidepressant candidates.
- Digital therapeutics adjuncts:Reimbursement experiments by CMS and private payors are creating parallel revenue streams alongside pharmacological interventions.
Market Restraints
- Specialty psychiatric administration requirements:Esketamine Risk Evaluation and Mitigation Strategy mandates limit dispensing to certified treatment centers, constraining prescriber base expansion.
- Suicidality warning divergence:FDA black box requirements differ from EMA precautionary language, complicating unified global labeling and liability exposure.
- Generic SSRI saturation:Patent-expired fluoxetine and sertraline formulations command minimal reimbursement rates, compressing margin pools for oral antidepressant portfolios.
Strategic Opportunities
- Home-based intranasal administration:Post-induction maintenance protocols are shifting administration from clinics to patient residences, opening pharmacy-dispensed revenue channels.
- Biomarker-guided patient selection:Pharmacogenomic testing integration with prescribing workflows is reducing trial-and-error treatment cycles and improving remission rates.
- Gene therapy adjacencies:Preclinical vectors targeting BDNF expression pathways represent long-term mechanistic diversification beyond small-molecule neurotransmission modulation.
Industry Challenges
- Psychiatrist workforce scarcity:Certified esketamine administration requires specialist oversight, creating bottleneck capacity constraints in rural and underserved geographic clusters.
- Placebo response variability:High and fluctuating placebo rates in MDD trials inflate required sample sizes and extend study durations, elevating clinical development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Major Depressive Disorder (MDD) Treatment Market |
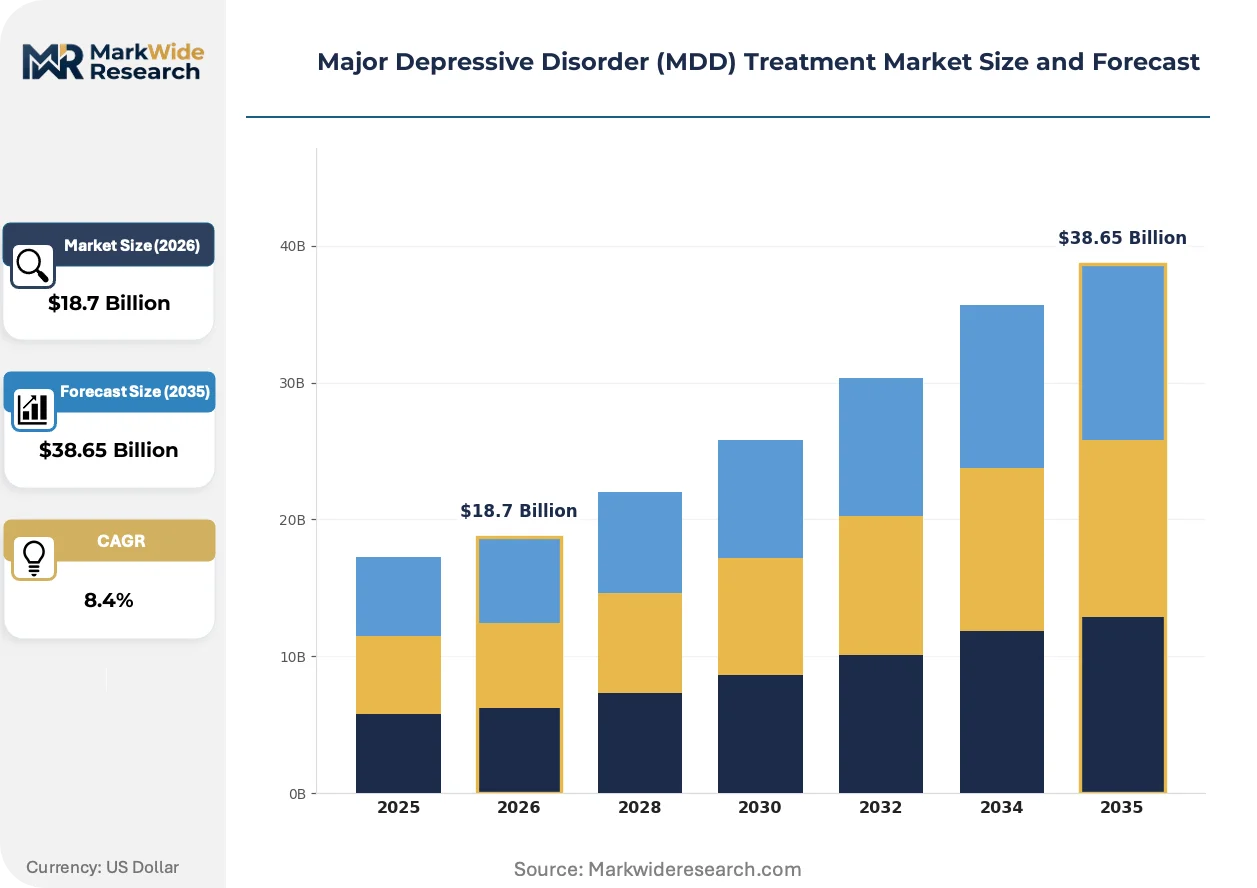
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SSRIs, SNRIs, Atypical Antidepressants, Tricyclic Antidepressants Delivery Mode: Oral, Injectable, Transdermal, Intranasal End User: Hospitals, Outpatient Clinics, Homecare, Rehabilitation Centers Therapy Area: Psychiatry, Neurology, Family Medicine, General Practice |
| Companies Covered | Johnson & Johnson (Janssen), Eli Lilly and Company, Pfizer Inc., GlaxoSmithKline plc (GSK), Otsuka Pharmaceutical Co., Ltd., H. Lundbeck A/S, Takeda Pharmaceutical Company Limited, AstraZeneca plc, Alkermes plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Major Depressive Disorder (MDD) Treatment Market Strategic Shifts
Neurostimulation devices and digital phenotyping tools are converging with pharmacotherapy, creating multimodal treatment protocols that challenge traditional drug-centric MDD management paradigms.
Transcranial magnetic stimulation coils are miniaturizing into portable helmet configurations. Outpatient psychiatric practices in Germany and Australia are adopting these systems for home rental programs. The technology is miniaturizing hardware costs and expanding addressable patient populations beyond clinic-bound delivery models.
EMA's conditional marketing authorization framework is demanding adaptive trial designs with real-world evidence supplementation. This regulatory posture accelerates early access but mandates post-approval outcome commitments. European sponsors are responding by embedding digital monitoring tools into commercialization strategies to satisfy evidentiary requirements.
Patient self-monitoring through smartphone-based mood tracking applications is displacing retrospective clinic interviews as the primary symptom assessment modality. Telepsychiatry platforms in the United States are integrating these data streams into prescribing decisions. Mental health technology vendors are capturing treatment response data that previously resided exclusively in clinical encounters.
Major Depressive Disorder (MDD) Treatment Market Segmentation
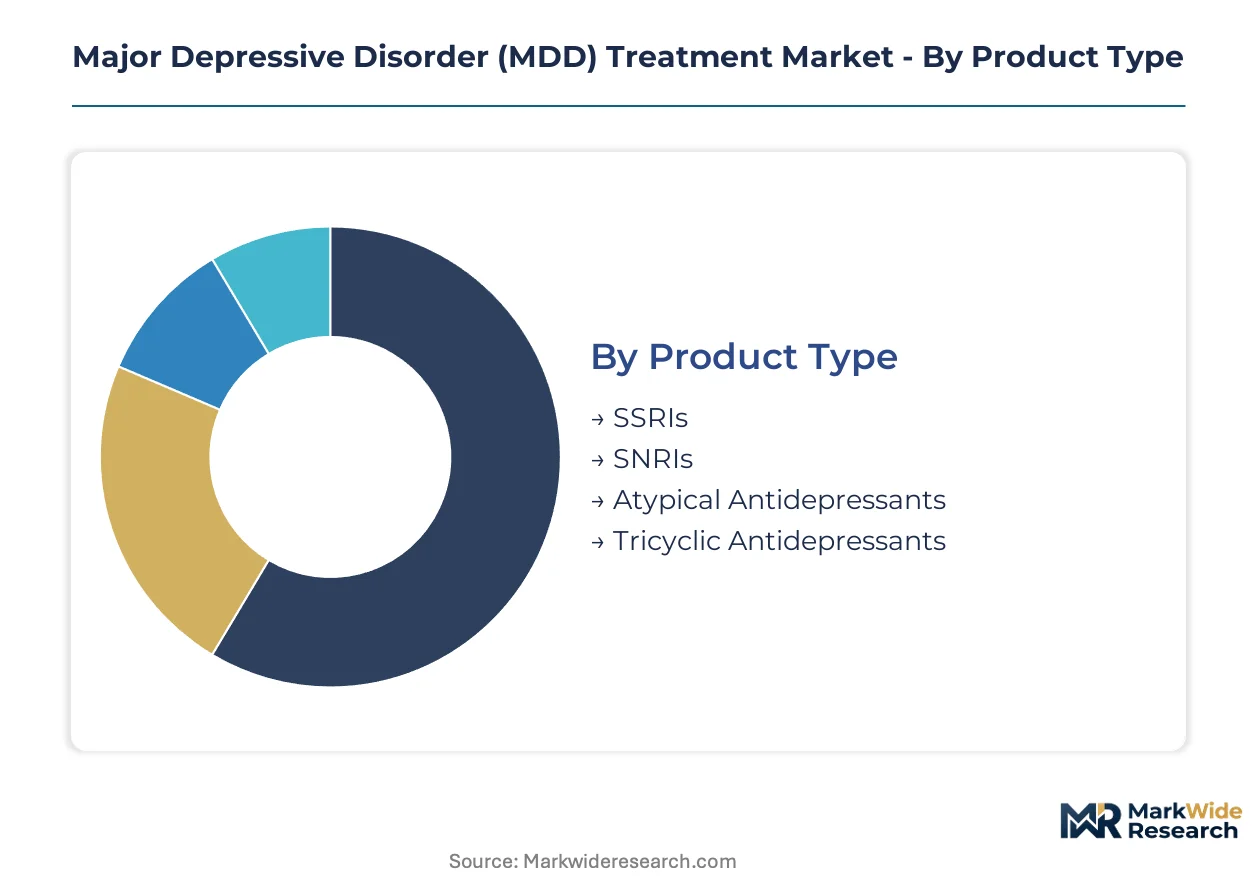
MDD treatment segmentation reveals how therapeutic modalities align with care settings and prescriber workflows. Channel economics and reimbursement structures determine which formulations achieve commercial traction across outpatient, institutional, and home-based environments.
Product Type:
Pharmaceutical portfolios flow through distinct commercial channels based on patent status and prescriber familiarity, with newer mechanisms commanding specialty pharmacy distribution while established classes saturate retail networks.
- SSRIs:First-line serotonergic agents including fluoxetine and sertraline dominate primary care prescribing through retail pharmacy channels. Volume concentrates in the United States where generic substitution laws accelerate cost compression.
- Atypical Antidepressants:Mechanistically diverse agents targeting multimodal neurotransmission achieve premium positioning through specialty psychiatric distribution. Bupropion and vortioxetine formulations expand fastest in outpatient clinics seeking alternatives to sexual dysfunction profiles.
- SNRIs:Dual reuptake inhibitors serve moderate-to-severe depression protocols in hospital discharge planning.
- Tricyclic Antidepressants:Legacy amitriptyline and nortriptyline compounds persist in pain-comorbid depression through institutional formularies.
By volume, SSRIs lead. By growth pace, atypical antidepressants are expanding most quickly.
Delivery Mode:
Formulation engineering determines administration setting requirements, with invasive delivery commanding prescriber certification and facility investment while non-invasive routes enable patient self-management.
- Oral:Tablet and capsule formulations constitute the foundational patient-administered channel across all care settings. Retail pharmacy dispensing dominates in the United States where mail-order 90-day supplies reduce patient cost burden.
- Intranasal:Rapid-absorption esketamine platforms require Risk Evaluation and Mitigation Strategy-certified administration facilities. United States outpatient clinics in urban clusters capture the initial patient volume as REMS infrastructure expands.
- Injectable:Long-acting injectables serve treatment adherence challenges in community mental health centers.
- Transdermal:Patch formulations address gastrointestinal intolerance in elderly populations through Medicare Part D channels.
By volume, oral administration leads. By growth pace, intranasal delivery is gaining share fastest.
End User:
Care setting segmentation tracks how reimbursement codes and prescriber specialty shape treatment selection, with facility-based administration attracting premium pricing against home-based maintenance protocols.
- Outpatient Clinics:Specialty psychiatric practices and general medicine offices manage the majority of incident MDD cases through scheduled monitoring protocols. United States federally qualified health centers in underserved counties expand access through 340B drug pricing.
- Hospitals:Inpatient psychiatric units and emergency departments handle acute suicidality and catatonic presentations requiring rapid stabilization. Academic medical centers in Boston and San Francisco anchor clinical trial recruitment for novel mechanisms.
- Homecare:Post-discharge maintenance and telepsychiatry-supported self-administration gain traction through remote patient monitoring reimbursement.
- Rehabilitation Centers:Substance use disorder facilities integrate depression treatment into dual-diagnosis protocols.
By patient volume, outpatient clinics lead. By structural investment, hospitals command capital deployment priority.
Therapy Area:
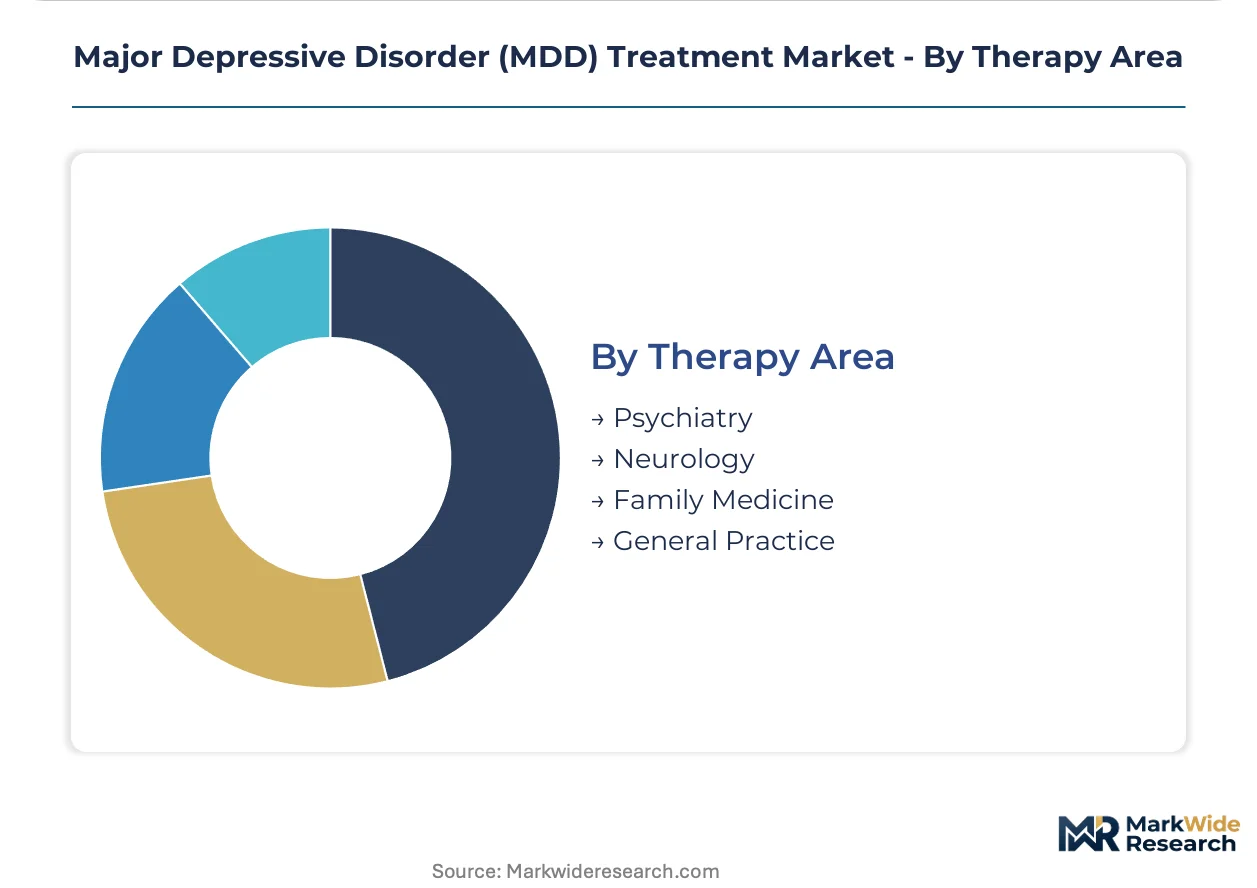
Prescriber specialty segmentation determines diagnostic coding patterns and prior authorization requirements, with psychiatric specialists managing complex cases against primary care gatekeepers handling initial presentations.
- Psychiatry:Board-certified specialists manage treatment-resistant depression and polypharmacy protocols through Diagnostic and Statistical Manual criteria. United States metropolitan markets concentrate psychiatric workforce supply, creating access disparities in rural counties.
- Family Medicine:Generalist physicians capture first-line SSRI prescribing through integrated health system protocols. Kaiser Permanente and Veterans Health Administration models embed depression screening into routine primary care workflows.
- Neurology:Movement disorder and stroke specialists address post-neurological event depression through interdisciplinary clinics.
- General Practice:Independent physicians and urgent care settings handle acute symptom recognition and referral coordination.
By prescription volume, family medicine leads. By complexity premium, psychiatry commands the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty psychiatric practices and certified treatment centers concentrate demand in urban corridors where reimbursement infrastructure supports novel mechanism adoption. Hospital systems and outpatient clinics in metropolitan clusters drive intranasal platform penetration. Regulatory pathway differentiation across jurisdictions shapes where developers prioritize clinical trial investment and early commercialization.
United States
Federally qualified health centers and academic medical centers in Boston and San Francisco anchor esketamine administration infrastructure. FDA breakthrough therapy designations compress review timelines for glutamatergic candidates. The 340B drug pricing program expands access in underserved counties while REMS certification requirements limit prescriber base growth.
Germany
Outpatient psychiatric practices in Berlin and Munich adopt portable transcranial magnetic stimulation systems for home rental programs. EMA conditional marketing authorization demands adaptive trial designs with real-world evidence supplementation. The statutory health insurance system covers digital therapeutics adjuncts, creating parallel reimbursement channels alongside pharmacotherapy.
Japan
Metropolitan psychiatric clinics in Tokyo and Osaka prioritize novel serotonergic modulators through PMDA accelerated review pathways. The Ministry of Health, Labour and Welfare integrates depression screening into workplace health mandates. Prefecture-level mental health centers concentrate specialist workforce supply, creating rural access disparities.
United Kingdom
NHS England's Improving Access to Psychological Therapies program embeds depression screening into primary care workflows. The National Institute for Health and Care Excellence evaluates digital therapeutics for formulary inclusion. London's academic health science centers anchor clinical trial recruitment for next-generation antidepressant mechanisms.
Australia
Telepsychiatry platforms in Sydney and Melbourne integrate smartphone-based mood tracking into prescribing decisions. The Therapeutic Goods Administration aligns with FDA breakthrough pathways for priority review of rapid-acting formulations. Rural health networks face psychiatrist workforce scarcity, constraining certified administration capacity for specialty therapies.
Major Depressive Disorder (MDD) Treatment Market Competitive Environment
Player mix skews toward diversified pharmaceutical conglomerates with established CNS research infrastructure and specialty biopharmaceutical developers focused on mechanistic innovation. Market structure concentrates around three strategic tiers: legacy SSRI franchise holders defending volume positions, intranasal platform specialists capturing treatment-resistant depression premiums, and gene therapy adjacent developers pursuing long-term mechanistic diversification. Dominant competitive moves include portfolio diversification into digital therapeutics partnerships and geographic expansion through accelerated regulatory pathway utilization.
Within the intranasal platform tier, Johnson & Johnson (Janssen) and Eli Lilly and Company occupy anchor positions representing divergent strategic bets on delivery innovation versus serotonergic modulation. Pfizer Inc. exemplifies the diversified conglomerate archetype spanning established oral franchises and emerging therapeutic modalities. These three entities collectively illustrate how competitive positioning in MDD treatment increasingly depends on regulatory relationship depth and psychiatric specialty channel access rather than primary care prescribing volume alone.
| Leading Market Players |
|---|
| Johnson & Johnson (Janssen) |
| Eli Lilly and Company |
| Pfizer Inc. |
| GlaxoSmithKline plc (GSK) |
| Otsuka Pharmaceutical Co., Ltd. |
| H. Lundbeck A/S |
| Takeda Pharmaceutical Company Limited |
| AstraZeneca plc |
| Alkermes plc |
| Others |
Value Chain & Pricing Dynamics
FDA Risk Evaluation and Mitigation Strategy certification gates both supply qualification and price differentiation simultaneously, limiting intranasal esketamine dispensing to certified treatment centers while enabling premium positioning against uncertified channels. This regulatory architecture concentrates pricing power among REMS-compliant facilities and forces supply chain investments into specialized cold-chain distribution networks.
Pricing Analysis
Cost-plus contracts with pharmaceutical price indexation dominate intranasal platform procurement between Janssen and United States specialty pharmacy networks. Price differentiation rests on REMS certification status and prescriber specialty tier, with academic medical centers commanding steeper discounts than community clinics. Cost compression in oral SSRI tiers intensifies because generic substitution laws accelerate reimbursement parity. Federally qualified health centers exhibit highest price sensitivity; private outpatient psychiatric practices show lowest.
Supply Chain Analysis
Just-in-time inventory strategies prevail for oral antidepressant distribution through retail pharmacy channels, while intranasal platforms demand strategic stockpiling at REMS-certified facilities to accommodate induction dosing schedules. Active pharmaceutical ingredient production concentrates in India, China, and the United States. Formulation inputs draw from specialized nasal spray device manufacturers and controlled-substance API suppliers. Single-source vulnerability in esketamine API production represents the dominant structural risk. Distribution runs through specialty pharmacy networks for certified therapies and mail-order channels for maintenance oral regimens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in MDD treatment are inflecting around digital therapeutics interoperability, with smartphone-based mood tracking applications integrating into prescribing workflows and creating data-layer ecosystems that reshape traditional drug-centric commercial models.
For Market Incumbents: Fortify REMS certification infrastructure against digital therapeutic substitution threats by embedding proprietary monitoring tools into patient onboarding protocols. Deepen backward integration into pharmacogenomic testing services to lock in biomarker-guided patient selection workflows and defend margin position against generic SSRI erosion.
For New Entrants and Emerging Players: Differentiate on home-based intranasal maintenance protocols as the most penetrable white space, targeting United States rural counties with psychiatrist workforce scarcity through telepsychiatry-supported self-administration models. Pursue pharmacy-dispensed revenue channels as the primary go-to-market angle, bypassing facility-based REMS bottlenecks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital therapeutics adjacencies as software development costs displace traditional clinical trial expenditure. Long-term viability across the analysis window favors platform plays with recurring revenue streams over single-molecule dependencies. Acquisition target archetype: specialty psychiatric administration networks with embedded REMS infrastructure. The signal to watch is CMS coverage determination timing for digital therapeutic adjuncts.
| Strategic Initiative | Industry Significance |
|---|---|
| REMS Certification Expansion | Johnson & Johnson's esketamine infrastructure locks in prescriber channel control against emerging glutamatergic competitors. |
| Digital Therapeutics Partnership | Smartphone mood-tracking integration with prescribing workflows captures treatment response data previously held in clinical encounters. |
| Pharmacogenomic Testing Integration | Biomarker-guided patient selection reduces trial-and-error cycles and improves remission rate metrics for payor contract negotiations. |
| Home-Based Administration Protocol | Post-induction maintenance shifting to patient residences opens pharmacy-dispensed revenue channels beyond facility-based REMS constraints. |
| Gene Therapy Pipeline Diversification | Preclinical BDNF expression vectors represent long-term mechanistic hedging against small-molecule patent cliff exposure. |
Study Parameters
Desk research of FDA REMS program documentation, ClinicalTrials.gov registration data, and CMS coverage determination precedents preceded structured interviews with formulary directors, specialty pharmacy procurement leads, and psychiatric practice administrators. Secondary validation drew from EMA conditional marketing authorization decisions, PMDA accelerated review pathway filings, and hospital system GPO contract databases. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored segmentation outputs.
Variance decomposition across therapeutic modality, delivery mode, and prescriber specialty dimensions structured the analytical framework over the projection horizon. CAGRs were derived from patent expiration schedules, generic entry probability assessments, and regulatory pathway timeline differentials. Treatment-resistant depression prevalence trajectories and reimbursement code expansion schedules served as industry-specific forecast inputs.
Material uncertainties — FDA label expansion decisions, CMS digital therapeutic coverage determinations, and psychiatrist workforce supply shocks — sit outside the modeled envelope. Forecasts reflect assumptions about REMS infrastructure buildout rates and telepsychiatry reimbursement permanence. Revision becomes warranted when placebo-response variability in MDD trials crosses thresholds that inflate required sample sizes beyond sponsor funding capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Ragweed Pollen Allergy Treatment Market
Specialty Medicine
Amino Acid Metabolism Disorders Treatment Market
Specialty Medicine
Global Cancer Immunotherapies Market
Specialty Medicine
Endometriosis Market
Specialty Medicine
Global Autism Spectrum Disorders Market
Specialty Medicine
Small Molecule Targeted Cancer Therapy Market
Specialty Medicine
Rosacea Therapeutics Market
Specialty Medicine
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market
Specialty Medicine
Ankylosing Spondylitis Treatment Market
Specialty Medicine
Dyschromia Therapeutics Market
Specialty Medicine
Kinase Inhibitor in Autoimmune Diseases Market
Specialty Medicine
HER2 Positive Gastric Cancer Market
Specialty Medicine
Hemangioma Treatment Market
Specialty Medicine
Global Hormone Replacement Therapy Market
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
Global Urea Cycle Disorder Market