
 Global Monoclonal Antibody Therapeutics Market | 2026-2036
Global Monoclonal Antibody Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Monoclonal Antibody Therapeutics Market Foresight
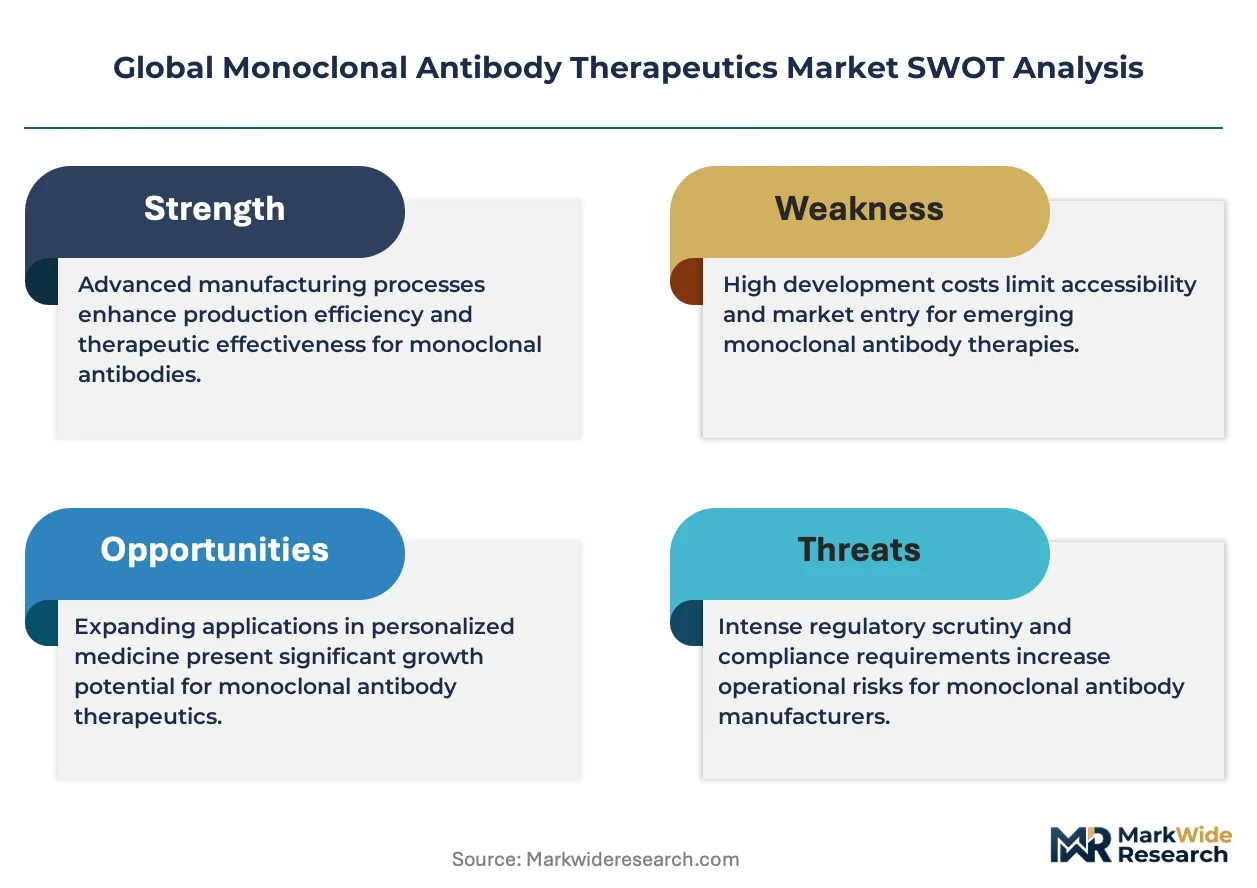
The EU Green Deal is expanding sustainability requirements across pharmaceutical supply chains, compelling manufacturers to reduce carbon intensity in biologics production. F. Hoffmann-La Roche Ltd leverages its Swiss manufacturing base to sustain energy-efficient fermentation processes. AbbVie Inc anchors its North American capacity with advanced single-use bioreactor systems. Johnson & Johnson Services, Inc. competes through integrated sterile fill-finish operations across multiple continents.
Monoclonal antibody therapeutics are recombinant proteins engineered to bind specific antigens with high affinity, typically produced via mammalian cell culture in bioreactors exceeding 10,000-liter scale. These agents function as targeted immunotherapies that modulate disease pathways in oncology, autoimmune disorders, and infectious diseases. Fully human antibodies command premium positioning due to reduced immunogenicity risk versus murine constructs. Oncology applications generate the dominant revenue pool within therapy area segmentation, while subcutaneous delivery modes are gaining preference for patient convenience and reduced infusion center burden.
FDA, EMA, and NMPA each enforce distinct biosimilar approval frameworks that determine market exclusivity periods and interchangeability standards. The FDA's biosimilar pathway under the Biologics Price Competition and Innovation Act shapes developer investment timelines, while EMA's scientific advice procedures influence European trial design. Stakeholders must monitor evolving post-market surveillance requirements as regulators tighten pharmacovigilance expectations for novel antibody formats.
Market Dynamics
FDA's accelerated approval pathways for breakthrough therapies compress development timelines, while Medicare reimbursement policies in the United States favor biologic therapies over small molecules. This regulatory-reimbursement nexus is reshaping how developers prioritize pipeline assets and manufacturing investments.
Growth Catalysts
- Biologics Price Competition and Innovation Act:The FDA's biosimilar pathway creates abbreviated approval routes that reduce development costs and accelerate market entry for follow-on biologics.
- Oncology precision medicine:Hospital systems deploy monoclonal antibodies for targeted cancer immunotherapy, expanding addressable patient populations through biomarker-driven selection.
- Subcutaneous delivery innovation:Formulation advances enable self-administration, reducing infusion center burden and improving patient adherence across chronic indications.
Market Restraints
- Mammalian cell culture feedstock volatility:Serum and media component costs fluctuate with agricultural commodity markets, squeezing gross margins for contract manufacturers.
- Single-source supplier concentration:Chromatography resins and single-use bioreactor bags concentrate among German and US suppliers, creating vulnerability to geopolitical disruption.
- EMA post-market surveillance tightening:Enhanced pharmacovigilance requirements for novel antibody formats extend compliance timelines and inflate regulatory affairs headcount.
Strategic Opportunities
- India's CDMO expansion:Contract development and manufacturing organizations in India leverage cost arbitrage and growing technical capabilities to capture outsourced biologics production.
- EU Green Deal compliance services:Sustainability consulting and carbon-neutral fermentation process engineering create adjacent revenue streams for equipment vendors and engineering firms.
- Bispecific antibody formats:Dual-targeting constructs address resistance mechanisms in oncology, opening new mechanism-of-action categories previously inaccessible to monospecific agents.
Industry Challenges
- Cell line development expertise scarcity:Qualified molecular biologists and bioprocess engineers command premium compensation, constraining expansion timelines for emerging biotechs.
- Multi-product facility qualification:Switching campaigns between antibody products require extensive cleaning validation and regulatory filing amendments, compressing effective utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Monoclonal Antibody Therapeutics Market |
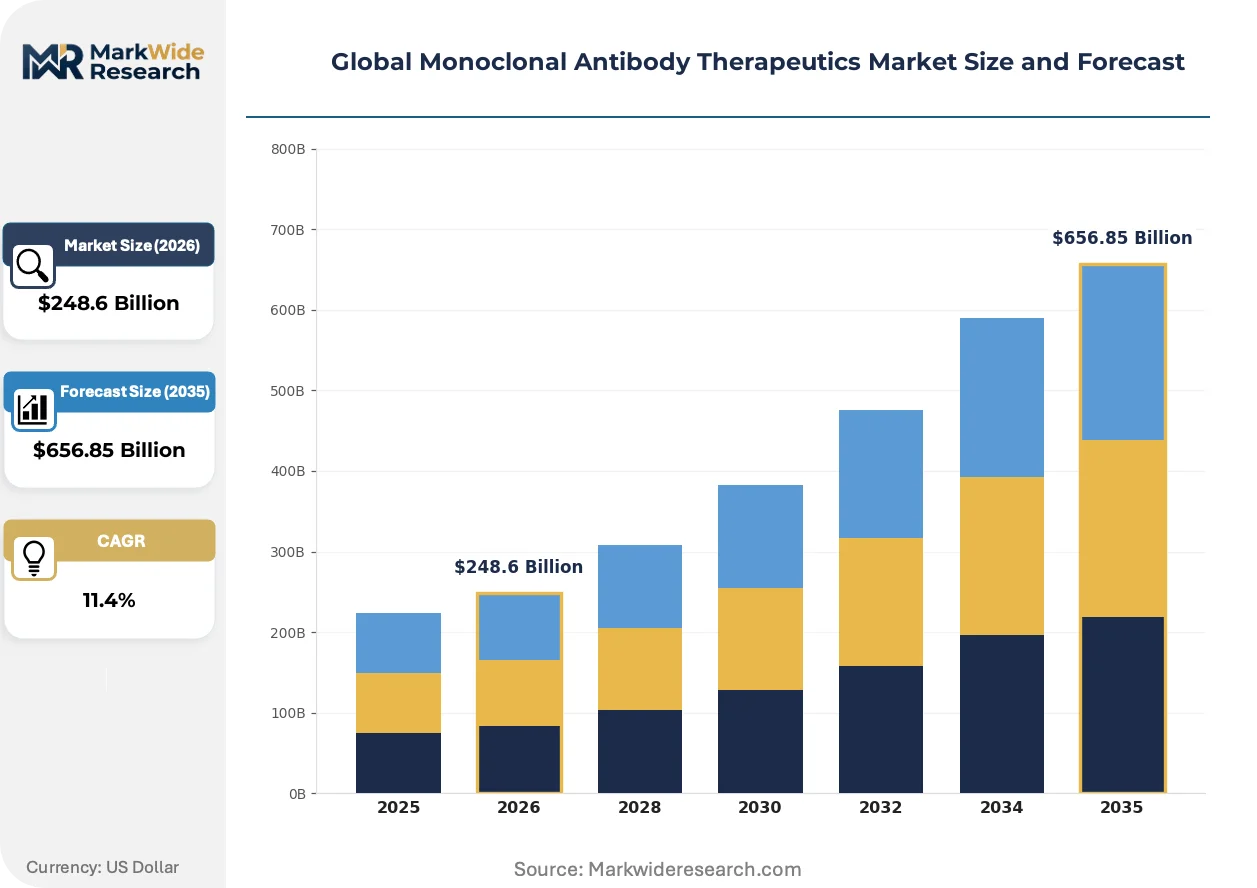
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $656.85 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chimeric, Humanized, Fully Human, Murine Therapy Area: Oncology, Autoimmune Disorders, Infectious Diseases, Neurological Disorders End User: Hospitals, Specialty Clinics, Research Laboratories, Biotechnology Firms Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral |
| Companies Covered | F. Hoffmann-La Roche Ltd, AbbVie Inc, Johnson & Johnson Services, Inc., Merck & Co., Inc., Amgen Inc, Bristol-Myers Squibb, Novartis AG, Sanofi, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Monoclonal Antibody Therapeutics Market Shifts & Advancements
Continuous manufacturing technologies and artificial intelligence-driven cell line engineering are compressing development timelines while improving yield consistency. These innovations intersect with evolving regulatory frameworks and shifting site-of-care preferences to redefine competitive positioning.
Single-use bioreactor systems is rewriting how manufacturers configure production networks. Biotech startups and mid-cap developers deploy disposable 2,000-liter trains to enable flexible, multi-product facilities without stainless steel capital commitments. This modularity is compressing facility build-out timelines from five years to eighteen months, enabling geographic diversification of manufacturing footprints.
REACH authorization requirements for novel chemical substances in chromatography resins are forcing suppliers to reformulate purification media. EMA's tightening expectations for leachable and extractable profiles extend qualification timelines for downstream processing equipment. European manufacturers respond by accelerating in-house resin synthesis capabilities to control supply security and regulatory documentation.
Hospital procurement committees now mandate health economic evidence alongside clinical efficacy data for formulary inclusion. Integrated delivery networks in the United States consolidate purchasing through centralized biologics tenders, displacing individual physician preference as the primary selection criterion. This concentration is most visible in oncology, where pharmacy benefit managers negotiate indication-specific rebates that reshape net pricing structures.
Global Monoclonal Antibody Therapeutics Market Segmentation
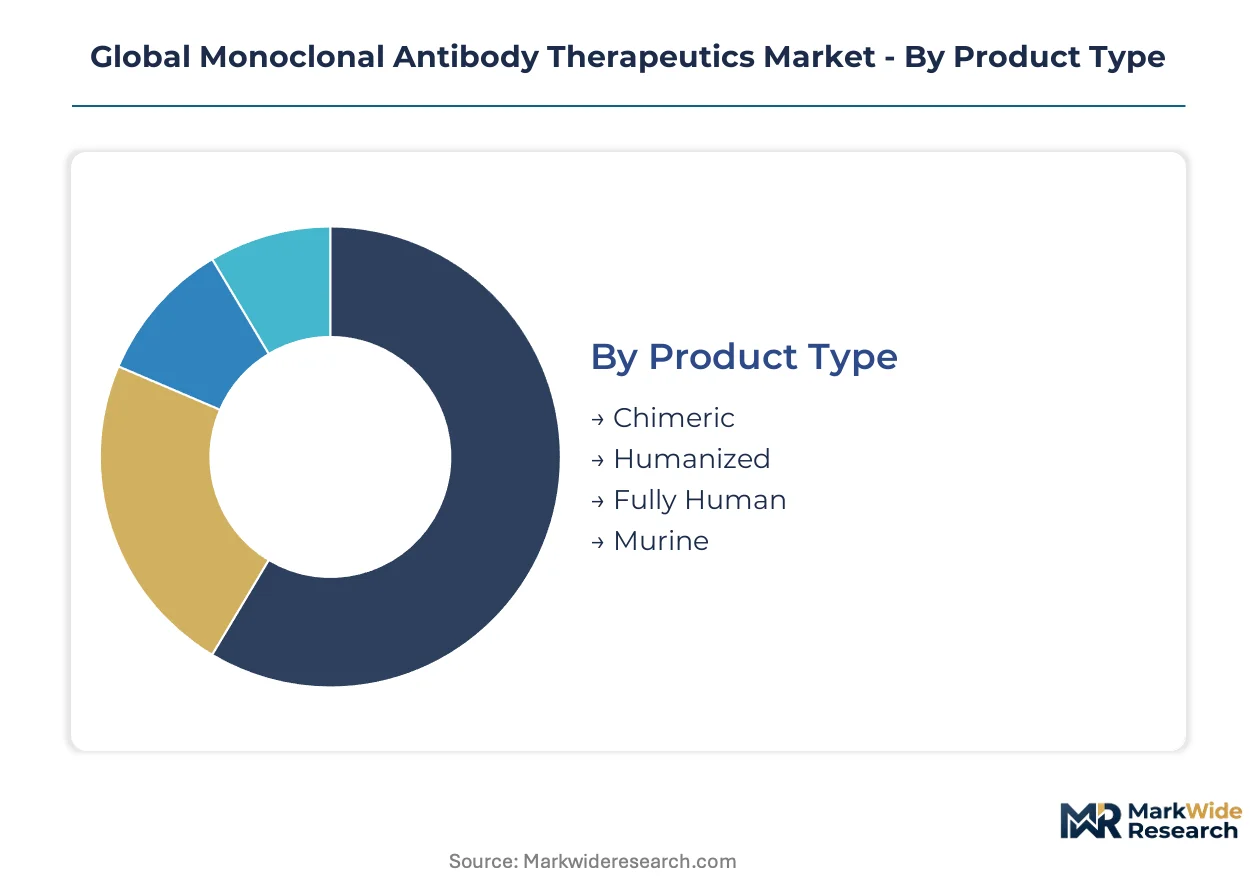
Monoclonal antibody therapeutics demand heterogeneous manufacturing capabilities, regulatory pathways, and commercial strategies across distinct molecular formats and clinical settings. Segment-level analysis reveals where biopharma capital allocation concentrates and which patient access models command premium positioning.
Product Type:
Immunogenicity risk and patent expiry timelines drive procurement committee preferences for molecular format selection.
- Fully Human:Recombinant antibodies derived from transgenic mouse or phage display platforms eliminate human anti-mouse antibody responses. United States hospital systems prioritize these agents for chronic autoimmune indications where long-term dosing is required.
- Humanized:Engineered constructs retain murine complementarity-determining regions within human framework regions, balancing affinity with reduced immunogenicity. European oncology departments favor humanized antibodies where biosimilar competition has compressed pricing on earlier-generation molecules.
- Chimeric:Fusion proteins combining murine variable regions with human constant domains.
- Murine:Fully mouse-derived antibodies with elevated immunogenicity risk, now largely restricted to diagnostic and radioimmunoconjugate applications.
Fully Human leads on scale; Humanized leads on momentum.
Therapy Area:
Reimbursement density and development success rates determine which disease categories attract pipeline investment.
- Oncology:Checkpoint inhibitors, antibody-drug conjugates, and bispecific T-cell engagers dominate hospital pharmacy budgets. FDA breakthrough therapy designations compress approval timelines for solid tumor indications, accelerating commercialization.
- Autoimmune Disorders:Rheumatoid arthritis, psoriasis, and inflammatory bowel disease generate recurring revenue through chronic administration. Subcutaneous formulation advances enable self-injection, reducing infusion center dependency.
- Infectious Diseases:Antibody prophylaxis and treatment for resistant bacterial and viral pathogens.
- Neurological Disorders:Blood-brain barrier penetration challenges constrain therapeutic antibody development for Alzheimer's and multiple sclerosis.
Oncology leads on scale; Autoimmune Disorders leads on momentum.
End User:
Site-of-care economics and formulary control structures shape distribution channel priorities.
- Hospitals:Integrated delivery networks consolidate purchasing through centralized biologics tenders, displacing individual physician preference. Medicare reimbursement policies favor hospital outpatient administration for infused antibodies.
- Specialty Clinics:Independent infusion centers capture volume for stable chronic indications with established safety profiles. United States private payers increasingly mandate site-of-care optimization programs.
- Research Laboratories:Academic medical centers and contract research organizations drive early-phase clinical trial demand.
- Biotechnology Firms:In-house manufacturing and process development activities.
Hospitals lead on scale; Specialty Clinics leads on momentum.
Delivery Mode:
Patient convenience and healthcare resource utilization determine formulation investment priorities.
- Intravenous:Established administration route for high-dose oncology antibodies requiring controlled infusion rates. Hospital infusion centers maintain capacity for complex monitoring protocols.
- Subcutaneous:Self-administration devices reduce healthcare facility burden and improve adherence in chronic indications. EMA guidelines on immunogenicity assessment for subcutaneous formulations influence European development timelines.
- Intramuscular:Limited applications for prophylactic antibody administration.
- Oral:Gastrointestinal degradation challenges constrain bioavailability for protein therapeutics.
Intravenous leads on scale; Subcutaneous leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Monoclonal antibody therapeutics originated in hybridoma technology developed at the Medical Research Council in Cambridge, UK, during the 1970s. The industry subsequently scaled manufacturing in Swiss and German biotech clusters before dispersing production across North American, European, and Asian pharmaceutical hubs. Today, regulatory frameworks and reimbursement density determine where developers concentrate clinical trials and commercial infrastructure.
United States
Medicare Part B reimbursement rates for infused biologics sustain hospital outpatient administration volumes, while FDA breakthrough therapy designations compress approval timelines for oncology indications. The Biologics Price Competition and Innovation Act shapes biosimilar entry strategies and patent litigation patterns. The Greater Boston and San Francisco Bay Area clusters anchor early-stage antibody engineering, with contract manufacturing organizations expanding in Research Triangle Park, North Carolina.
Germany
EMA centralized procedures and Germany's statutory health insurance system create predictable pricing corridors for novel antibodies, attracting Phase III trial investment. REACH authorization requirements for chromatography resins force downstream process redesigns, extending equipment qualification timelines. The Rhine-Main biotech corridor around Frankfurt and Heidelberg concentrates monoclonal antibody process development expertise and sterile fill-finish capacity.
Switzerland
Swissmedic's alignment with EMA scientific advice procedures accelerates European market entry for antibodies developed in Basel and Zurich laboratories. The country's bilateral trade agreements with China and ASEAN markets facilitate export-oriented production strategies. The Basel metropolitan region hosts integrated biologics campuses combining mammalian cell culture, purification, and packaging operations within concentrated geographic footprints.
China
NMPA's reform of biologics approval pathways under the 2019 Drug Administration Law enables domestic developers to reference overseas clinical data, shortening registration timelines. National reimbursement drug list negotiations compress net pricing for imported antibodies, pressuring multinational profit margins. The Shanghai Zhangjiang and Suzhou BioBAY clusters attract foreign direct investment in contract development and manufacturing capacity for regional supply.
India
CDSCO's biosimilar guidelines and the Production Linked Incentive scheme for pharmaceuticals incentivize domestic fermentation capacity expansion for export markets. Cost arbitrage in mammalian cell culture operations positions Indian contract manufacturers to capture outsourced production from Western developers. The Hyderabad Genome Valley and Bengaluru Biotech clusters scale single-use bioreactor installations and analytical testing services for international clients.
Global Monoclonal Antibody Therapeutics Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across distinct value chain positions in monoclonal antibody therapeutics. Integrated pharmaceutical conglomerates operate captive biologics manufacturing at 10,000-liter scale, while emerging biotechs outsource process development and commercial production to contract manufacturing organizations. Three archetypes dominate: diversified biopharma majors with oncology-focused antibody portfolios, mid-cap specialists in autoimmune or rare disease indications, and platform-technology companies licensing cell line engineering capabilities. Competitive dynamics center on manufacturing capacity expansion in Asia-Pacific markets and strategic partnerships to secure fill-finish capacity in regulated jurisdictions.
Among diversified biopharma majors, F. Hoffmann-La Roche Ltd anchors the Swiss-domiciled tier with integrated development-through-commercialization infrastructure. AbbVie Inc represents the North American archetype of immunology-focused portfolio concentration. Johnson & Johnson Services, Inc. occupies a position spanning pharmaceutical, medical device, and consumer health segments with biologics manufacturing distributed across multiple continents. These entities exemplify how scale and therapeutic area depth determine competitive positioning in antibody markets.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| AbbVie Inc |
| Johnson & Johnson Services, Inc. |
| Merck & Co., Inc. |
| Amgen Inc |
| Bristol-Myers Squibb |
| Novartis AG |
| Sanofi |
| Pfizer Inc. |
| Others |
Supply & Pricing Matrix
Qualified molecular biologists and bioprocess engineers concentrated in the Greater Boston and San Francisco Bay Area clusters command premium compensation that propagates through pricing-tier spreads across fully human, humanized, and biosimilar antibody categories.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates fully human antibodies with reduced immunogenicity risk from humanized constructs facing biosimilar competition and emerging-market biosimilars. Price differentiation hinges on FDA breakthrough therapy designation status and manufacturing scale, with chronic autoimmune indications showing highest price sensitivity due to Medicare Part B reimbursement pressure. Oncology checkpoint inhibitors face cost compression from pharmacy benefit manager rebate negotiations, while hospital outpatient administration retains lowest price sensitivity due to favorable reimbursement differentials over specialty clinics.
Supply Chain Analysis
Direct-to-hospital channels handle infused antibody demand through integrated delivery network tenders, while specialty clinic distribution captures stable chronic indications. Manufacturing concentrates in the United States, Switzerland, and Germany, with mammalian cell culture media and chromatography resins drawing from German and US suppliers. Single-source supplier concentration for single-use bioreactor bags creates vulnerability to geopolitical disruption. Distribution runs through cold-chain logistics networks anchored in regional fill-finish facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's accelerated approval pathway for breakthrough therapies functions as a regulatory compounder, compressing development timelines and amplifying returns for developers with validated manufacturing platforms.
For Market Incumbents: Hedge biosimilar erosion in autoimmune indications by accelerating subcutaneous formulation transitions that extend franchise longevity. Backward integration into chromatography resin synthesis reduces REACH authorization dependency and secures downstream process control against German supplier concentration.
For New Entrants and Emerging Players: Enter via India's CDMO expansion corridor, where cost arbitrage in mammalian cell culture operations meets growing technical capabilities for international clients. Target bispecific antibody formats in oncology, where dual-targeting constructs address resistance mechanisms inaccessible to monospecific agents and command premium positioning.
For Investors and Strategic Acquirers: Platform-technology companies licensing cell line engineering capabilities are the most active acquirer targets in this space, with transaction momentum concentrated among mid-cap specialists seeking manufacturing differentiation. Watch for inflection signals in CDSCO biosimilar guideline enforcement that would accelerate Indian domestic capacity absorption.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA breakthrough therapy designations compress oncology approval timelines for solid tumor indications. |
| Manufacturing Scale-Up | Single-use bioreactor deployments in Research Triangle Park enable eighteen-month facility build-outs. |
| Regulatory Approval Pathway | EMA scientific advice procedures accelerate European market entry for Basel-developed antibodies. |
| Backward Integration | In-house resin synthesis capabilities control REACH documentation and chromatography supply security. |
| Pipeline Diversification | Bispecific formats open mechanism-of-action categories resistant to monospecific checkpoint inhibition. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers grounded qualitative insights, validated against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up and top-down triangulation reconciled antibody volume estimates with Medicare reimbursement data and payer access specialist interviews.
Bottom-up modeling aggregated patient population projections, treatment penetration rates, and dosing schedules across therapy area, molecular format, and administration route segments. Top-down validation cross-checked aggregate market expansion against biologics industry revenue trends and CDMO capacity announcements. CAGRs were derived from regression analysis of historical approval velocity and reimbursement policy trajectories across the analysis window.
Inputs from clinical trial registries and statutory health insurance pricing corridors were available through the study window; gaps in real-time biosimilar uptake data introduce uncertainty bands around substitution rate assumptions. Forecasts reflect documented assumptions regarding FDA breakthrough therapy designation velocity and EMA pharmacovigilance tightening timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Oral Anti-Diabetic Drugs Market
Pharmaceuticals
Global Online Pharmacy Market
Pharmaceuticals
Anti-Obesity Drugs Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Global Urothelial Cancer Drugs Market
Pharmaceuticals
Metformin HCL Drugs Market
Pharmaceuticals
Guaifenesin Market
Pharmaceuticals
Oral & Topical Anaesthetics Market
Pharmaceuticals
Global Janus Kinase Inhibitor (JAK) Market
Pharmaceuticals
Asia-Pacific Aneurysmal Subarachnoid Hemorrhage Drugs Market
Pharmaceuticals
North America Travel Vaccines Market
Pharmaceuticals
Saudi Arabia Diabetes Drugs Market
Pharmaceuticals
Global Prophylactic HIV Drugs Market
Pharmaceuticals
Global Cold and Flu Drugs Market
Pharmaceuticals
Global Opioid Induced Constipation Market
Pharmaceuticals
Pharmacy and Drug Store Franchises Market