
 Fibroadenoma Market | 2026-2036
Fibroadenoma Market Size, Share, and Industry Trends Forecast 2026-2036
Fibroadenoma Market Analysis
CE marking under the EU Medical Device Regulation (MDR) is rotating as the primary gating qualification for fibroadenoma device vendors seeking European market access. Koninklijke Philips N.V. leverages its integrated imaging-to-intervention portfolio to dominate ultrasound-guided procedural workflows. Siemens Healthineers anchors its position through deep R&D intensity in MRI-compatible ablation platforms. Hologic Inc specializes in mammography-guided biopsy systems that extend into treatment planning for fibroadenoma cases.
A fibroadenoma is a benign breast tumor composed of glandular and stromal tissue, typically presenting as a well-circumscribed, mobile mass measuring 1-5 cm in diameter, diagnosed primarily through imaging and confirmed by core needle biopsy. The condition serves a critical commercial purpose in driving demand for minimally invasive treatment alternatives to surgical excision in outpatient settings. Cryoablation and radiofrequency ablation segments are capturing the fastest expansion as patients seek same-day procedures with reduced scarring and recovery times. Surgical excisions remain the largest revenue pool despite slower growth, sustained by reimbursement familiarity and broad physician training. Mammography and ultrasound diagnosis methods command the densest installed base, though MRI-guided pathways are carving out premium positioning for complex or inconclusive cases.
FDA 510(k) premarket notification requirements and EU MDR conformity assessment procedures shape device approval timelines and clinical evidence burdens for manufacturers across both markets. The US national pharmaceutical regulator oversees pharmacological therapy options used in conservative management protocols, while WHO breast cancer early detection guidelines indirectly influence screening intensity that surfaces fibroadenoma cases. Stakeholders must monitor evolving reimbursement codes for office-based ablation procedures as payer policies will determine whether cryoablation shifts from specialty centers to mainstream ambulatory adoption.
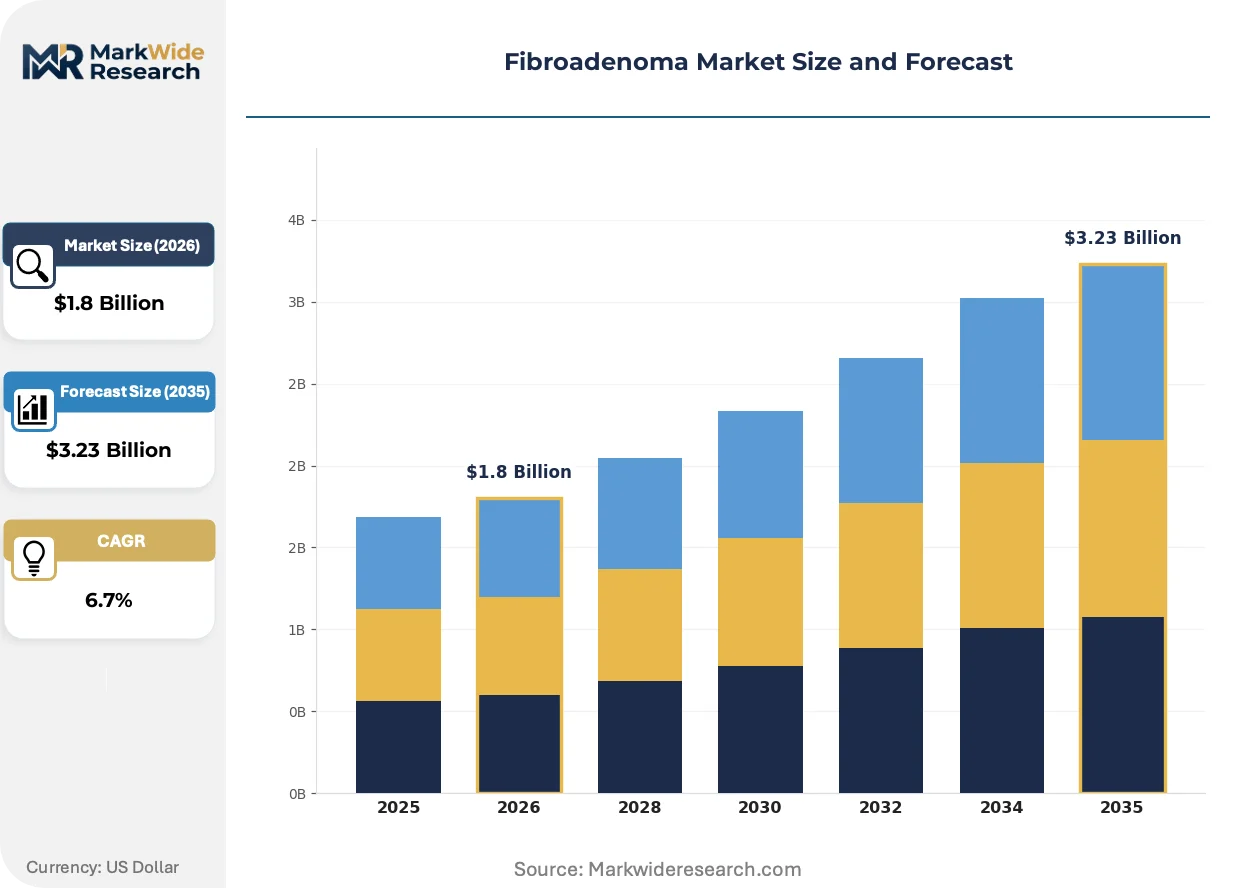
Market Dynamics
Minimally invasive ablation technology is decomposing the surgical excision monopoly in fibroadenoma treatment, forcing reimbursement frameworks and physician training pathways to adapt faster than institutional timelines typically permit.
Growth Catalysts
- Office-Based Procedure Migration:Cryoablation systems enable same-day discharge from ambulatory surgical centers, reducing facility overhead and patient recovery burden compared to hospital-based excision.
- FDA 510(k) Streamlining:Predicate device pathways for thermal ablation platforms compress premarket notification timelines, accelerating commercialization for device manufacturers targeting outpatient breast care.
- Germany's Dedicated Breast Clinic Model:Regional networks of specialized ambulatory centers integrate ultrasound-guided systems into standardized diagnostic-treatment workflows, creating concentrated demand pull.
Market Restraints
- Reimbursement Code Fragmentation:Inconsistent CPT coding for image-guided ablation across US commercial payers creates prior authorization friction and payment uncertainty.
- Physician Training Gaps:Interventional radiology fellowship programs emphasize oncologic ablation over benign breast disease, constraining qualified operator supply in community settings.
- Device Capital Intensity:MRI-compatible ablation platforms require magnet-compatible consumables and specialized installation, elevating entry costs for imaging centers.
Strategic Opportunities
- India's Diagnostic Infrastructure Buildout:PLI scheme incentives for medical device manufacturing and expanding private hospital networks create first-mover positioning for ultrasound-guided system vendors.
- EU MDR Conformity Acceleration:Notified body capacity expansion for Class IIa/IIb device reviews under the Medical Device Regulation offers faster European market entry than pre-2021 transition periods.
- AI-Integrated Imaging Workflows:Machine learning algorithms for automated lesion characterization in mammography systems converge with ablation planning software, compressing diagnostic-to-treatment intervals.
Industry Challenges
- Clinical Evidence Generation Burden:Long-term recurrence data requirements for FDA de novo pathways demand extended follow-up registries, stretching R&D timelines for novel energy modalities.
- Legacy EMR Integration Complexity:Ablation procedure documentation templates lack standardization across Epic, Cerner, and MEDITECH installations, forcing custom interface development.
- Supply Chain Concentration in Cryogen:Medical-grade argon and helium sourcing concentrates among three industrial gas suppliers, exposing device manufacturers to input volatility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fibroadenoma Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Excisions, Cryoablation, Radiofrequency Ablation, Medications End User: Hospitals, Ambulatory Surgical Centers, Dedicated Clinics, Research Institutions Diagnosis Method: Mammography, Ultrasound, MRI, Biopsy Treatment Approach: Conservative Management, Surgical Treatment, Pharmacological Therapy, Observation |
| Companies Covered | Koninklijke Philips N.V., Fujifilm Holdings Corporation, GE Healthcare, Hitachi Ltd, IceCure Medical, Siemens Healthineers, Canon Medical Systems Corporation, Dilon Technologies, Hologic Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fibroadenoma Market Emerging Trajectories
Image-guided thermal ablation is displacing cold steel across benign breast disease management, while regulatory frameworks and procurement behaviors recalibrate around outpatient value metrics rather than surgical throughput.
Cryoablation technology is decomposing the traditional surgical referral pathway by enabling radiologists to complete diagnosis and treatment in a single encounter. Community imaging centers in the United States are adopting ultrasound-guided platforms at accelerating rates, compressing the interval between abnormal mammogram and definitive intervention from weeks to hours. This procedural consolidation threatens hospital outpatient department revenue models built on surgical excision volume.
EU MDR conformity assessment procedures are reshaping device commercialization timelines by requiring clinical evaluation reports with post-market surveillance integration for Class IIa thermal ablation systems. Manufacturers must now demonstrate equivalence to predicate devices through biological safety and performance testing under notified body oversight, extending European market entry by 12-18 months compared to pre-2021 Medical Device Directive pathways. Germany's breast clinic networks are absorbing this friction through early engagement with BSI and TÜV SÜD for parallel US-EU submissions.
Patient self-referral patterns are fragmenting traditional gynecology-to-surgery referral chains as direct-to-consumer imaging and online scheduling platforms enable women to bypass primary care gatekeepers. US metropolitan markets witness this disintermediation most acutely, where dedicated breast imaging centers market cryoablation as a scar-minimizing alternative through social media and patient advocacy channels. This channel shift pressures hospital systems to deploy consumer-facing pricing transparency or lose benign breast volume to ambulatory competitors.
Fibroadenoma Market Segmentation
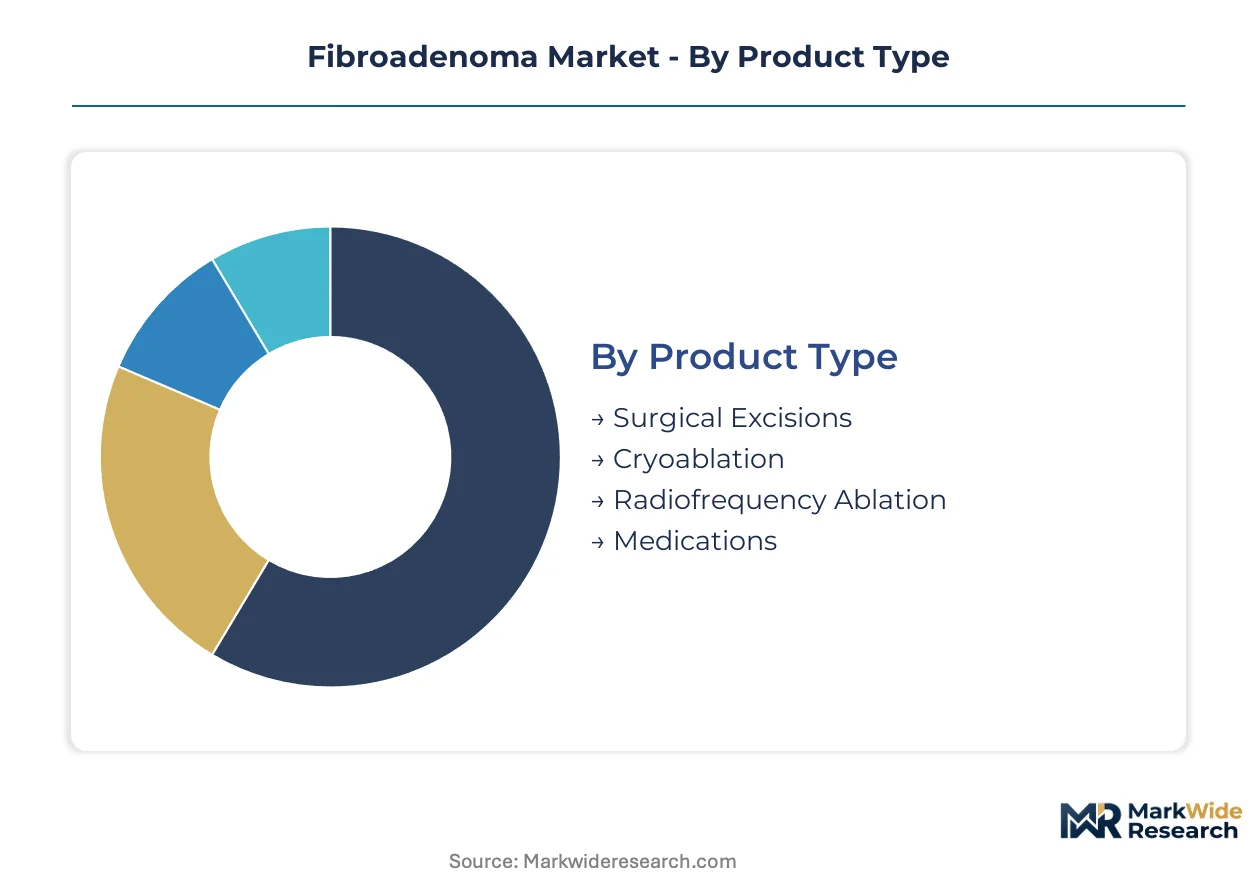
Fibroadenoma treatment pathways fragment across four critical dimensions, each shaping procurement patterns and reimbursement negotiation leverage. Product type and end-user configuration determine capital intensity and workflow integration requirements for facility operators.
Product Type:
Domestic demand concentrates in surgical excision systems across US hospital outpatient departments, while cryoablation platforms export predominantly to Germany's specialized breast clinic networks.
- Surgical Excisions:Cold knife and electrocautery excision systems remain the reimbursed standard across US commercial payers. Hospital outpatient departments in Texas and Florida sustain the densest installed base due to high-volume breast surgery programs.
- Cryoablation:Argon-based freezing systems enable same-day discharge with cosmetic preservation. German dedicated breast clinics drive European demand through standardized ultrasound-guided protocols.
- Radiofrequency Ablation:Thermal coagulation platforms target mobile lesions under 3cm. Italian and Spanish ambulatory centers pilot RF systems for cost-sensitive patient populations.
- Medications:Hormonal modulators and NSAID protocols serve observation-eligible patients. Indian private hospital networks integrate pharmacological pathways into conservative management workflows.
Surgical Excisions commands the established base. The steepest expansion runs through Cryoablation.
End User:
Capital deployment intensity separates high-investment hospital installations from lean ambulatory configurations, with margin structures varying threefold across the spectrum.
- Hospitals:Comprehensive breast centers integrate diagnosis through surgery in centralized campuses. Academic medical centers in Massachusetts and California anchor US training pipelines for excision techniques.
- Ambulatory Surgical Centers:Medicare-certified facilities exploit site-of-service differentials for ablation procedures. Florida and Arizona witness the fastest ASC enrollment in cryoablation credentialing.
- Dedicated Clinics:Single-specialty breast imaging centers compress diagnostic-to-treatment intervals. Germany's regional clinic networks standardize ultrasound-guided ablation as first-line intervention.
- Research Institutions:NIH-funded centers generate recurrence data for FDA de novo submissions. Long-term outcome registries at Duke and MD Anderson shape payer coverage determinations.
Hospitals retain the revenue concentration. Dedicated Clinics capture the volume migration.
Diagnosis Method:
Imaging modality selection dictates downstream treatment eligibility, with mammography screening volume determining ablation candidate pipeline depth.
- Mammography:Digital breast tomosynthesis systems generate the initial lesion detection volume. US screening compliance rates in the Northeast corridor sustain the densest detection throughput.
- Ultrasound:Handheld and automated breast ultrasound clarifies indeterminate mammographic findings. German clinic networks deploy ultrasound as the primary ablation guidance platform.
- MRI:Contrast-enhanced magnetic resonance resolves multifocal or inconclusive presentations. Academic centers leverage MRI for surgical planning in complex fibroadenoma cases.
- Biopsy:Core needle and vacuum-assisted sampling confirms histology prior to treatment planning. US community radiology practices integrate biopsy-capable ultrasound systems for same-visit confirmation.
Mammography anchors the detection funnel. Ultrasound gains the workflow integration.
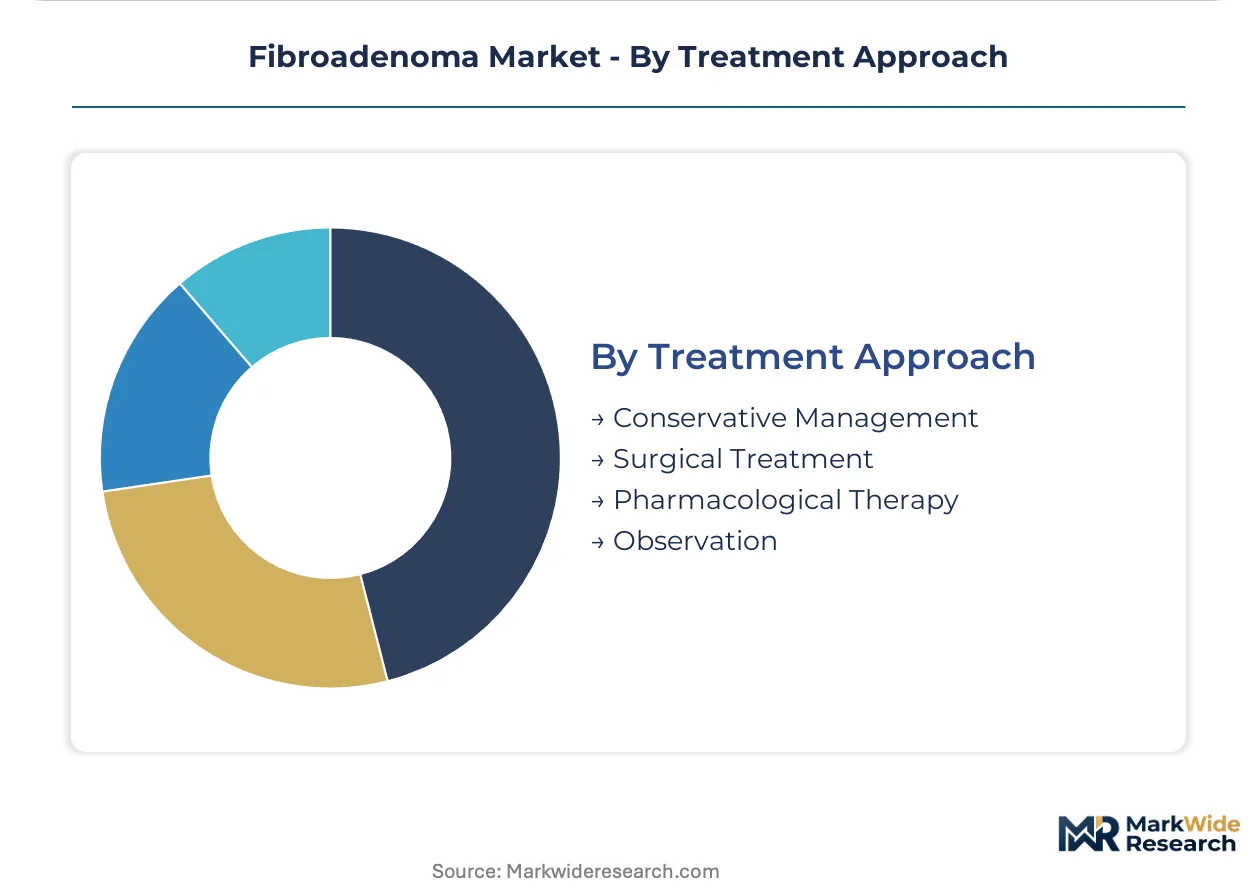
Treatment Approach:
Patient selection criteria and reimbursement authorization timelines segment approaches by acuity and cosmetic priority.
- Conservative Management:Surveillance protocols with interval imaging suit asymptomatic patients. UK NHS pathways emphasize conservative management for lesions under 2cm in premenopausal women.
- Surgical Treatment:Excision with pathological analysis remains the definitive standard. US hospital systems defend surgical volume through bundled payment contracts.
- Pharmacological Therapy:Hormonal suppression addresses symptomatic or growing lesions. Indian gynecology practices integrate danazol protocols for patient populations declining intervention.
- Observation:Active surveillance with patient-reported outcome monitoring. Younger patient cohorts in metropolitan US markets select observation to defer scarring.
Surgical Treatment holds the reimbursement lock. Conservative Management climbs the eligibility criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement teams and dedicated breast clinic operators concentrate demand across four national markets with divergent reimbursement frameworks and facility investment cycles.
United States
Ambulatory surgical centers in Florida and Arizona drive cryoablation system deployments through Medicare site-of-service differentials. FDA 510(k) predicate pathways compress premarket timelines for thermal ablation platforms. Texas Medical Center anchors the densest hospital outpatient excision volume through high-throughput breast surgery programs.
Germany
Regional networks of dedicated breast clinics standardize ultrasound-guided ablation as first-line intervention for mobile lesions under 3cm. EU MDR conformity assessment through BSI and TÜV SÜD extends device approval cycles by 12-18 months compared to prior directive timelines. North Rhine-Westphalia clusters the highest per-capita density of integrated diagnostic-treatment workflows.
India
Private hospital networks in Maharashtra and Karnataka integrate conservative management protocols into gynecology outpatient departments. PLI scheme incentives for medical device manufacturing reduce import dependency for ablation consumables. Delhi-NCR imaging centers deploy biopsy-capable ultrasound systems for same-visit diagnosis and patient counseling.
Japan
Academic medical centers in the Kanto region generate long-term recurrence data for MRI-compatible ablation platforms seeking PMDA approval. METI funding for minimally invasive oncology devices accelerates cryoablation clinical validation timelines. Osaka-based breast imaging networks pilot AI-integrated lesion characterization to compress diagnostic-to-treatment intervals.
United Kingdom
NHS England surveillance pathways emphasize conservative management for premenopausal women with lesions under 2cm, constraining procedural volume growth. MHRA post-Brexit regulatory autonomy enables faster UKCA marking timelines for Class IIa thermal ablation devices. London breast screening hubs concentrate MRI referral volume for inconclusive mammographic findings.
Fibroadenoma Market Vendor Landscape
Player mix skews toward diversified imaging conglomerates with integrated diagnostic-to-intervention portfolios. The vendor base concentrates among three tiers: full-platform imaging houses, ablation technology specialists, and regional diagnostic equipment fabricators. Dominant competitive moves include portfolio diversification into MRI-compatible consumables and strategic partnerships with ambulatory surgery chains for cryoablation system placement.
Among diversified imaging conglomerates, Koninklijke Philips N.V. and Siemens Healthineers occupy positions exemplifying the integrated workflow archetype, while Hologic Inc represents the mammography-guided specialization tier. IceCure Medical sits within the ablation technology specialist segment. These three entities collectively illustrate the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Fujifilm Holdings Corporation |
| GE Healthcare |
| Hitachi Ltd |
| IceCure Medical |
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| Dilon Technologies |
| Hologic Inc |
| Others |
Supply Flow & Price Mechanics
Long-term cryogen supply contracts with industrial gas suppliers lock in both argon and helium access and price visibility for cryoablation device manufacturers, insulating procurement teams from spot market volatility while anchoring consumable cost structures across US and German installed bases.
Pricing Analysis
Cost-plus contracts indexed to argon and helium commodity benchmarks dominate cryoablation consumable pricing, with medical-grade gas purity tiers creating differentiation between premium magnet-compatible formulations and standard ultrasound-guided applications. Price differentiation hinges on FDA 510(k) clearance tier and bundled service contracts for probe replacement programs. Pricing pressure stems from reimbursement code fragmentation across US commercial payers, which compresses allowable charges for office-based procedures. Community imaging centers exhibit highest price sensitivity due to capital constraints, while academic medical centers prioritize MRI-compatible premium tiers regardless of cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for Japanese-manufactured MRI-compatible ablation platforms and Korean-sourced ultrasound transducers. Manufacturing concentrates in the United States for cryoablation system assembly, Germany for precision probe fabrication, and China for standard consumable components. Raw material dependencies center on medical-grade argon, helium, and specialized polymers for probe insulation. Single-source vulnerability in cryogen supply exposes device manufacturers to production interruptions. Distribution runs through GPO-negotiated contracts for hospital systems and direct sales forces for dedicated breast clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fibroadenoma treatment market sits in early-cycle expansion, with cryoablation penetration still below 15% of addressable benign breast volume despite accelerating patient preference for same-day discharge protocols.
For Market Incumbents: Shield surgical excision revenue streams by embedding cryoablation platforms within hospital outpatient departments before volume migrates to independent imaging centers, while accelerating EU MDR conformity investments to preempt notified body bottlenecks that delay European market defense against emerging entrants. For New Entrants and Emerging Players: Lead with ultrasound-guided cryoablation systems targeting India's private hospital networks, where PLI scheme incentives reduce import dependency and gynecology outpatient departments remain underpenetrated by thermal ablation technology, deploying direct clinical specialist training as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Ablation technology specialists with proprietary probe designs and established reimbursement consulting capabilities represent the most defensible acquisition archetype, with long-term viability hinging on recurrence data generation capacity for FDA de novo pathway expansion; watch for CMS national coverage determination signals as the critical inflection indicator for mainstream ambulatory adoption.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Pathway Optimization | Accelerated clearance timelines compress commercialization lag for thermal ablation platforms targeting outpatient breast care. |
| EU MDR Conformity Acceleration | Parallel US-EU submissions through BSI and TÜV SÜD reduce European market entry friction for Class IIa devices. |
| Hospital System Partnership | GPO-negotiated contracts with Texas Medical Center and Massachusetts academic networks anchor high-volume excision revenue. |
| Software Companion Development | AI-integrated lesion characterization in mammography systems compresses diagnostic-to-treatment intervals for same-visit intervention. |
| Reimbursement Strategy | CPT code consolidation advocacy targets prior authorization friction reduction across commercial payers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with interventional radiologists, breast imaging center administrators, biomedical engineers, and GPO contracts managers, cross-referenced against FDA 510(k) filings, CMS reimbursement databases, hospital procurement records, and EU MDR notified body documentation, with bottom-up installed base counts triangulated against top-down market sizing from device manufacturer revenue disclosures.
Across the analysis window, the forecasting framework models volume and value trajectories by product type, end-user configuration, diagnosis method, and treatment approach, with CAGRs derived from procedure volume elasticity to screening compliance rates and technology substitution curves for ablation versus excision, incorporating cryogen supply constraints and reimbursement authorization timelines as boundary conditions.
The analysis sits within stated boundaries; outcomes outside sustained FDA 510(k) streamlining, stable cryogen supply contracting, and expanded CPT code coverage would require recalibration. Forecasts reflect documented assumptions regarding patient preference shifts toward cosmetic preservation and ambulatory convenience. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Disruptive Behavior Disorder (DBD) Treatment Market
Specialty Medicine
Meningitis Treatment Market
Specialty Medicine
Cervical Dystonia Market
Specialty Medicine
Soft Tissue Sarcoma Market
Specialty Medicine
Global Fungal Keratitis Treatment Market
Specialty Medicine
Generalized Anxiety Disorder Treatment Market
Specialty Medicine
Veno-Occlusive Hepatic Disease Therapeutics Market
Specialty Medicine
Pleurodynia Treatment Market
Specialty Medicine
Global Appendicitis Market
Specialty Medicine
Neuromyelitis Optica Market
Specialty Medicine
Anophthalmia and Microphthalmia Market
Specialty Medicine
Tinnitus Management Market
Specialty Medicine
Intestine (Small) Cancer Therapeutics Market
Specialty Medicine
Global Calciphylaxis Treatment Market
Specialty Medicine
ADHD Therapeutics Market
Specialty Medicine
Americas Gerd and Nerd Treatment Market