
 Image Guided Radiotherapy Market | 2026-2036
Image Guided Radiotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Image Guided Radiotherapy Market Outlook
Aftermarket service revenue is tilting toward software maintenance and adaptive planning subscriptions as hardware sales mature. Varian Medical Systems leverages its installed base of linear accelerators to sustain recurring revenue through calibration and upgrade contracts. Elekta AB anchors its competitive stance with integrated MRI-linac systems that command premium service attach rates. Siemens Healthineers differentiates through diagnostic imaging synergies that extend its reach into radiation oncology workflow integration.
Image guided radiotherapy combines real-time anatomical imaging with radiation beam delivery to enable precise tumor targeting while sparing healthy tissue, typically achieving spatial accuracy within one to two millimeters through cone-beam CT or onboard MRI verification. The technology serves primarily to enable dose escalation, margin reduction, and adaptive replanning in curative cancer protocols. CT-based guidance occupies the largest installed footprint among technology segments due to universal compatibility with existing linac infrastructure, while MRI-guided systems represent the fastest-growing category as real-time soft-tissue visualization enables online adaptive workflows. Cancer treatment applications generate the dominant revenue share, though tumor localization services are gaining traction as standalone offerings in proton and heavy-ion centers where beam range uncertainty demands sub-millimeter precision.
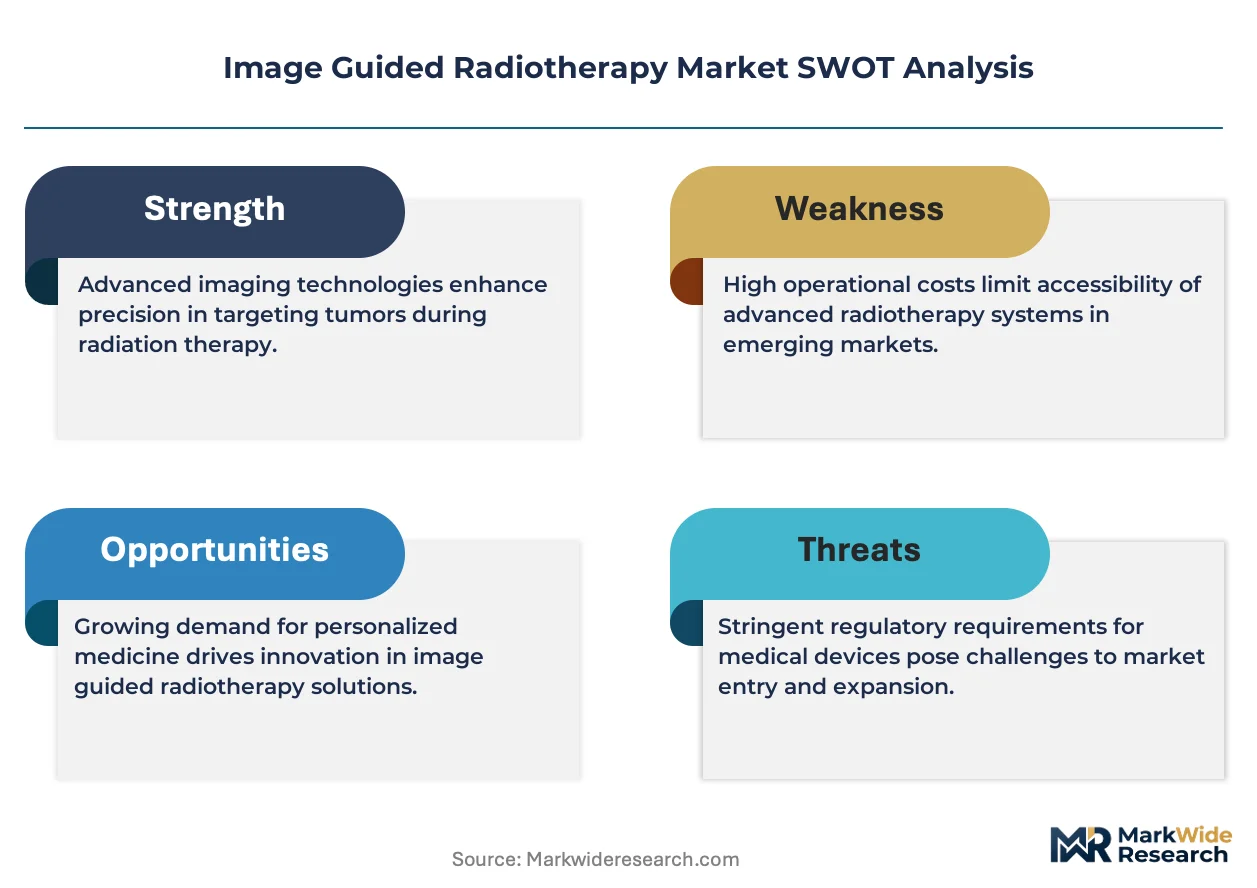
The FDA regulates IGRT devices under 21 CFR 892.5050 with software validation requirements that shape development timelines and post-market surveillance obligations. CE marking under the EU MDR imposes clinical evidence standards that filter market access for smaller device manufacturers. ISO 13485 quality management certification functions as a baseline procurement criterion for hospital capital committees evaluating multi-million dollar radiation therapy suites. Stakeholders must monitor how reimbursement coding for adaptive radiotherapy fractions evolves relative to standard fractionation schedules.
Market Dynamics
Adaptive replanning workflows are compressing treatment margins and forcing hardware-software integration investments across radiation oncology departments. The shift from offline to online adaptation is redistributing competitive advantage toward vendors with real-time imaging pipelines.
Growth Catalysts
- Hypofractionated Protocol Reimbursement:CMS alignment for shorter treatment courses in the United States accelerates capital deployment toward high-precision delivery systems. Academic medical centers lead adoption curves.
- CE Marking Under EU MDR:Stricter clinical evidence standards filter market access, consolidating share among established manufacturers with robust quality management systems. Smaller device entrants face extended timelines.
- Proton Therapy Center Construction:Beam range uncertainty demands sub-millimeter tumor localization, driving demand for integrated imaging verification. Heavy-ion facilities extend this requirement.
Market Restraints
- Superconducting Magnet Supply Concentration:Cryogenic component sourcing narrows to a handful of specialized suppliers, creating vulnerability in MRI-linac production pipelines. Geographic concentration in East Asian manufacturing amplifies this.
- FDA 510(k) Software Validation:Documentation burdens for algorithm updates extend product iteration cycles and inflate regulatory compliance costs. Post-market surveillance obligations compound this friction.
- Linear Accelerator Hardware Maturity:Extended replacement cycles for installed base units depress new equipment sales velocity. Service revenue tilts toward software maintenance without offsetting hardware refresh.
Strategic Opportunities
- India Diagnostic Imaging Expansion:Underpenetrated radiation oncology infrastructure creates whitespace for CT-guided system deployment. Government hospital procurement programs channel capital toward first-time installations.
- AI-Assisted Contouring Convergence:Automated segmentation algorithms hybridizing with manual planning workflows compress treatment preparation timelines. Integration partnerships between imaging and software vendors unlock this.
- Japan Heavy-Ion Therapy Mandate:National cancer strategy prioritizes particle therapy capacity expansion, creating demand for specialized tumor localization services. METI funding mechanisms support facility construction.
Industry Challenges
- Medical Physics Talent Scarcity:Adaptive workflow complexity outpaces training pipeline output for dosimetrists and physicists. Specialized certification programs remain insufficient to fill staffing gaps.
- Legacy Linac Integration Friction:Retrofitting cone-beam CT capabilities onto aging accelerator platforms demands custom mechanical engineering. Interoperability gaps between vendor ecosystems persist.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Image Guided Radiotherapy Market |
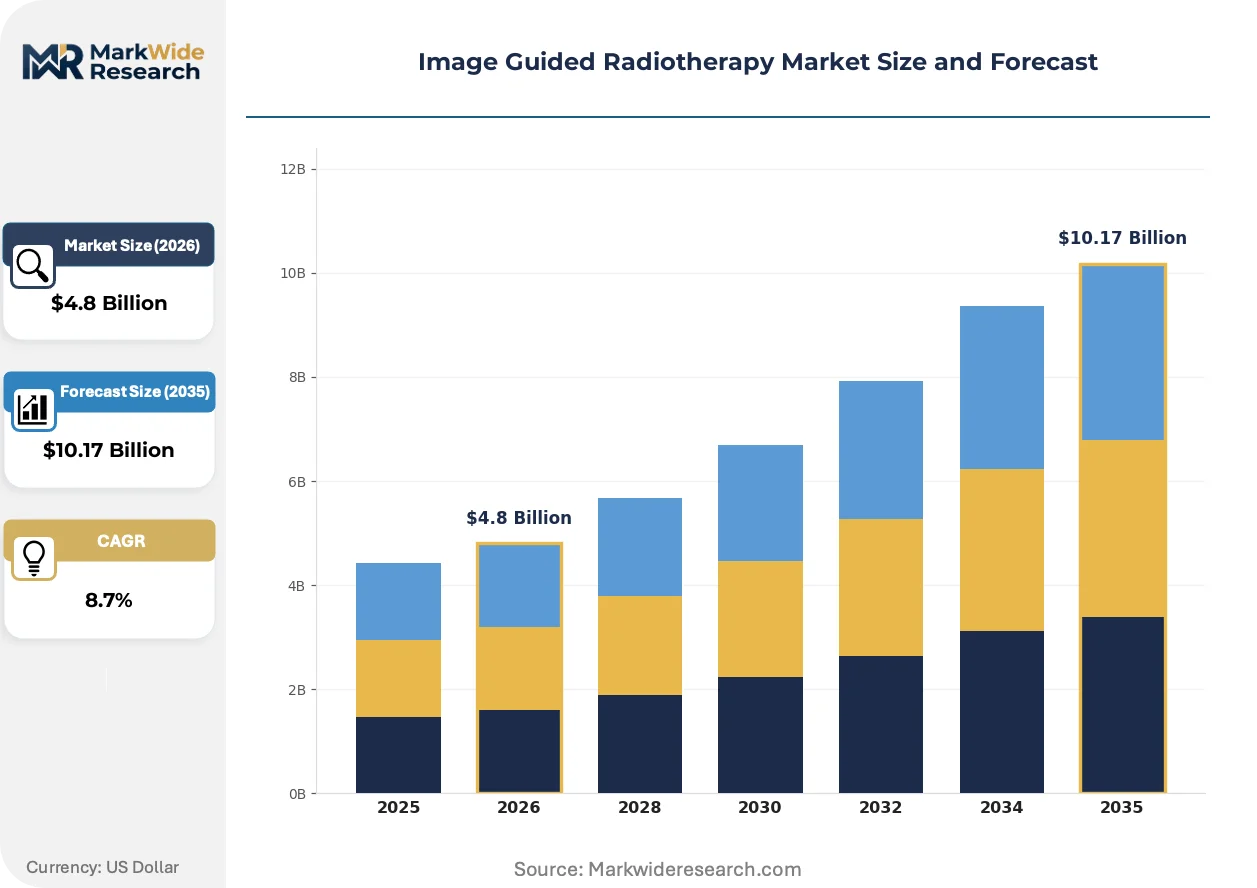
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: CT, MRI, PET, Ultrasound Application: Cancer Treatment, Tumor Localization, Patient Positioning, Dose Measurement End User: Hospitals, Cancer Centers, Research Institutions, Outpatient Facilities Solution: Software, Hardware, Services, Training |
| Companies Covered | Varian Medical Systems, Elekta AB, Siemens Healthineers, Accuray Incorporated, GE Healthcare, Koninklijke Philips N.V., ViewRay, Hitachi Ltd., IBA Worldwide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Image Guided Radiotherapy Market Strategic Shifts
Real-time soft-tissue visualization is displacing anatomical surrogates in treatment verification, compressing planning target volumes and enabling dose escalation protocols previously deemed too risky.
MRI-guided radiotherapy is hybridizing electromagnetic beam delivery with continuous magnetic resonance imaging to enable intrafraction motion management. Oncology departments at major academic centers in the United States and Germany are adopting these systems for abdominal and pelvic malignancies. The technology is compressing the gap between diagnostic imaging quality and therapeutic guidance precision.
The FDA's 510(k) clearance pathway for software-as-medical-device updates is accelerating algorithm deployment cycles while tightening post-market surveillance obligations. Manufacturers must maintain robust cybersecurity frameworks and real-world evidence collection systems. Adaptive planning software modules face heightened scrutiny relative to hardware-only submissions.
Hospital procurement committees are unbundling after-sales service contracts from initial capital purchases, forcing vendors to compete on maintenance pricing transparency. Third-party calibration providers are gaining footholds in mature linac installed bases. This pattern is most visible in United States proton therapy centers where multi-vendor environments complicate exclusive service arrangements.
Image Guided Radiotherapy Market Segmentation
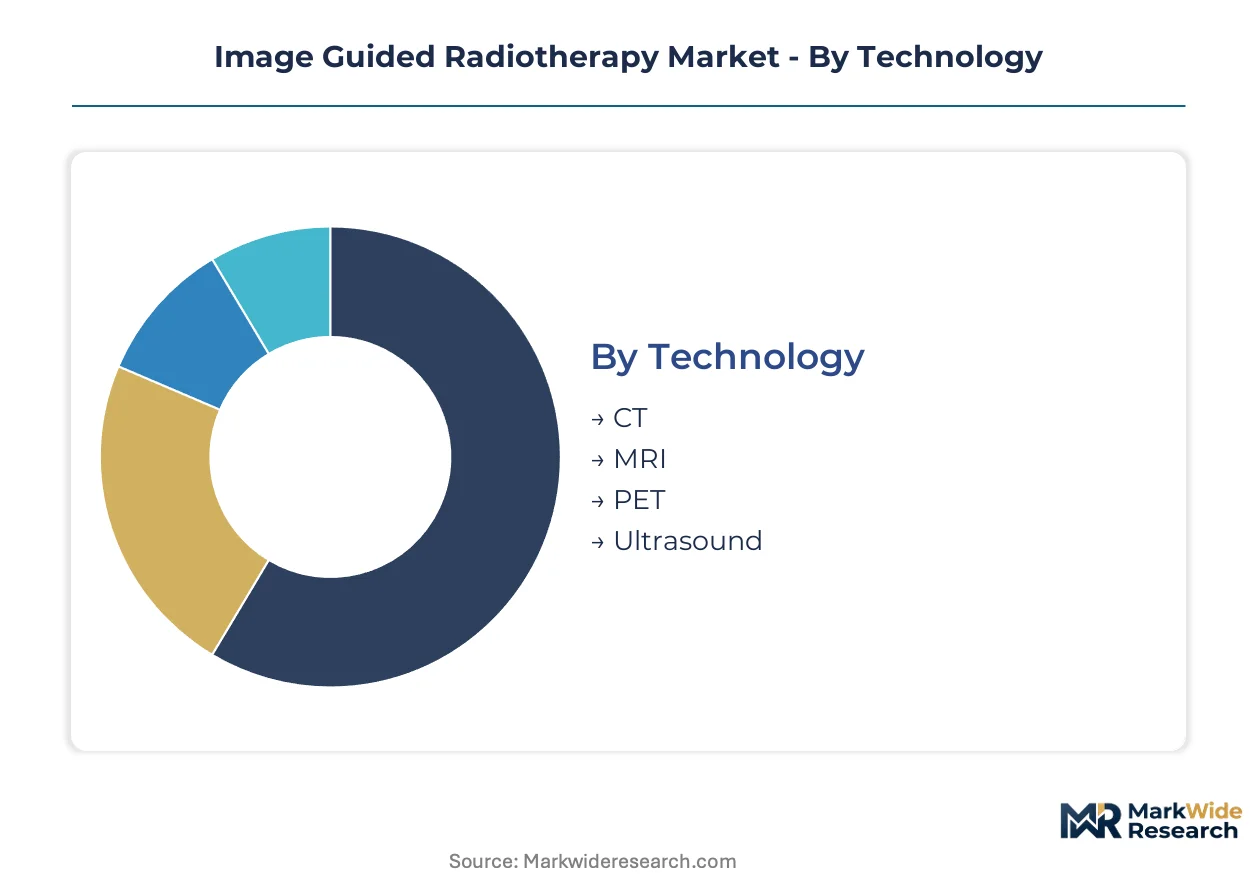
Image guided radiotherapy vendors configure product portfolios across four intersecting dimensions. Technology selection determines hardware architecture, while application focus shapes software development priorities. End-user targeting and solution bundling complete the commercial positioning matrix.
Technology:
Mature imaging modalities anchor installed base revenue; emerging magnetic resonance platforms command premium positioning in academic medical centers.
- CT:Cone-beam CT systems integrate universally with existing linear accelerator infrastructure through retractable kV imaging arms. Demand concentrates in United States community oncology practices where CMS reimbursement alignment for hypofractionated protocols accelerates capital deployment toward verification-capable units.
- MRI:Integrated MRI-linac systems enable continuous soft-tissue visualization during beam delivery, supporting online adaptive replanning workflows. German university hospitals and United States NCI-designated cancer centers lead procurement for abdominal and pelvic malignancy protocols where intrafraction motion management proves critical.
- PET:Positron emission tomography guidance supports biologically targeted dose escalation through metabolic tumor volume delineation. PET-CT fusion systems serve primarily in United States proton therapy centers where beam range uncertainty demands functional imaging verification.
- Ultrasound:Transabdominal and transperineal ultrasound systems provide cost-effective soft-tissue localization for prostate and gynecologic applications without ionizing radiation exposure.
CT retains volume leadership among installed systems; MRI holds the steepest expansion curve.
Application:
Clinical utility spans curative treatment delivery through technical measurement functions, with revenue concentration tilting toward therapeutic endpoints.
- Cancer Treatment:Curative radiotherapy protocols generate dominant revenue share through dose escalation and margin reduction enabled by real-time verification. United States academic medical centers deploy adaptive replanning for head-and-neck and lung malignancies where anatomical changes during fractionated courses compromise target coverage.
- Tumor Localization:Standalone positioning services address beam range uncertainty in particle therapy facilities. Japanese heavy-ion centers and United States proton therapy installations purchase specialized optical and electromagnetic tracking systems for sub-millimeter precision requirements.
- Patient Positioning:Surface guidance and fiducial tracking systems reduce setup variability without volumetric imaging dose. Outpatient facilities favor these for efficiency gains in high-throughput environments.
- Dose Measurement:In vivo dosimetry and portal imaging verification support quality assurance protocols and regulatory compliance documentation.
Cancer Treatment commands revenue concentration; Tumor Localization is climbing the fastest as particle therapy capacity expands.
End User:
Capital intensity and clinical complexity stratify procurement authority across institutional types.
- Hospitals:Integrated delivery networks in the United States consolidate radiation oncology service lines within multi-specialty campuses. These institutions prioritize vendor consolidation and enterprise-wide service contracts.
- Cancer Centers:Dedicated oncology facilities in Germany and the United States command premium technology budgets for competitive differentiation in referral markets. Freestanding proton centers exemplify this concentration.
- Research Institutions:National laboratories and university hospitals host technology evaluation programs that shape subsequent commercial adoption curves.
- Outpatient Facilities:Community-based practices in United States metropolitan areas seek CT-guided systems with streamlined workflows and lower physics staffing requirements.
Hospitals retain volume leadership; Cancer Centers hold the steepest expansion curve.
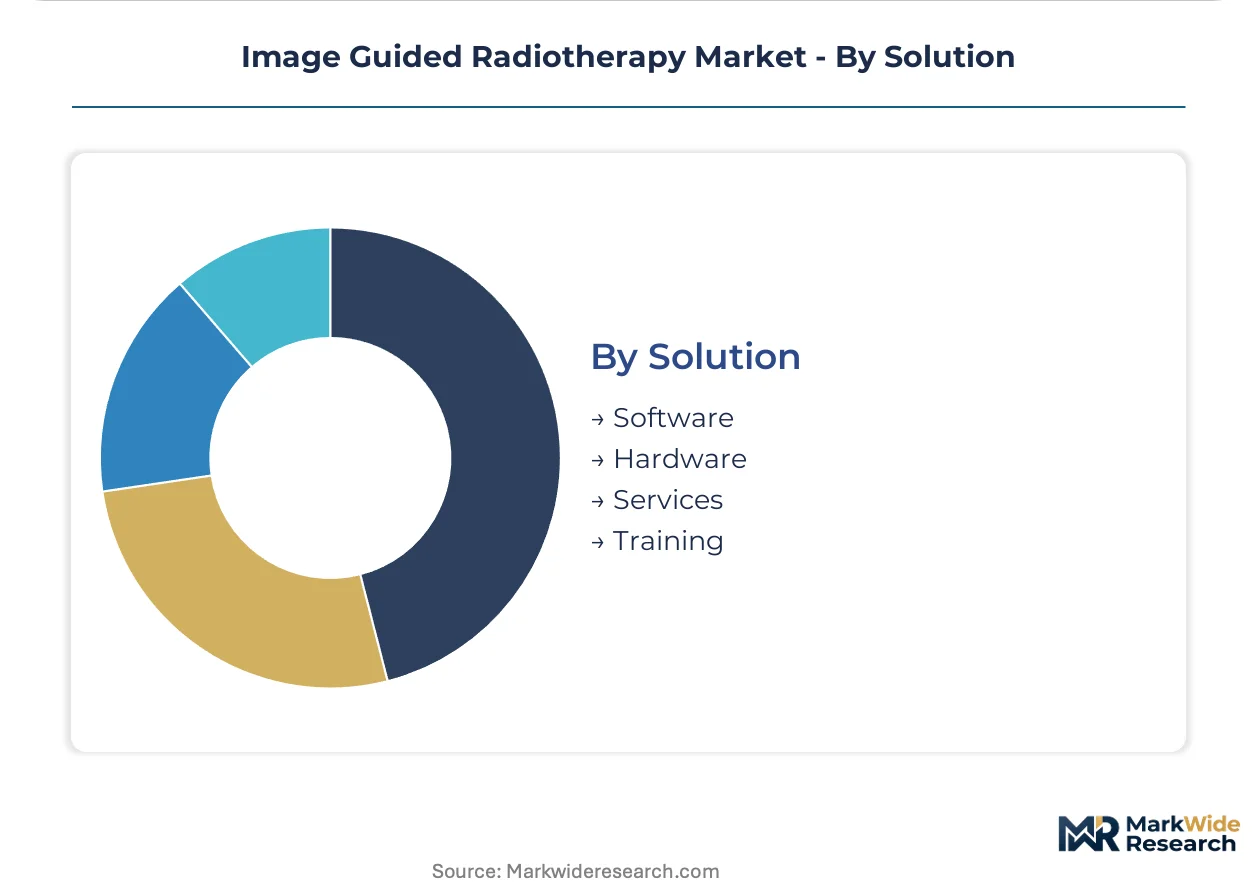
Solution:
Revenue mix is tilting toward recurring software and service streams as hardware sales mature across developed markets.
- Software:Adaptive planning modules and AI-assisted contouring tools compress treatment preparation timelines while tightening FDA 510(k) validation requirements for algorithm updates.
- Hardware:Linear accelerator and imaging subsystem sales face extended replacement cycles in mature installed bases, depressing new equipment velocity.
- Services:Calibration contracts and uptime guarantees generate predictable revenue streams. United States proton centers increasingly unbundle maintenance from initial capital purchases.
- Training:Medical physics education programs address workforce scarcity in adaptive workflow complexity, with specialized certification remaining insufficient to fill staffing gaps.
Software retains volume leadership; Services hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. United States buyers absorb premium pricing for adaptive systems, while Indian procurement prioritizes cost-effective CT-guided platforms. European purchasers navigate stricter clinical evidence requirements under revised regulatory frameworks.
United States
Academic medical centers drive capital deployment toward MRI-linac systems for hypofractionated protocols. CMS reimbursement alignment for shorter treatment courses accelerates adoption curves. NCI-designated cancer centers in Boston and Houston anchor demand concentration for real-time adaptive workflows.
Germany
University hospitals prioritize integrated imaging verification for abdominal malignancies where intrafraction motion management proves critical. CE marking under EU MDR imposes extended clinical evidence timelines that filter market access. The Heidelberg ion therapy center extends demand for sub-millimeter tumor localization services.
Japan
National cancer strategy prioritizes heavy-ion therapy capacity expansion with METI funding mechanisms supporting facility construction. PMDA regulatory pathways shape software validation requirements for algorithm updates. Chiba and Hyogo prefectures host particle therapy clusters driving specialized positioning system procurement.
India
Government hospital procurement programs channel capital toward first-time CT-guided installations in underpenetrated radiation oncology infrastructure. CDSCO device registration requirements extend product entry timelines for foreign manufacturers. Maharashtra and Karnataka state medical colleges anchor public sector demand concentration.
China
Provincial cancer hospital construction drives demand for verification-capable linear accelerators with diagnostic imaging synergies. NMPA medical device classification rules shape software-as-medical-device approval pathways. Beijing and Shanghai tertiary hospitals lead adoption of adaptive planning modules.
Image Guided Radiotherapy Market Competitive Environment
Integrated system vendors and diagnostic imaging conglomerates split the market between therapy-focused hardware and workflow-integrated platforms. The vendor base concentrates among established manufacturers with robust quality management certifications. Two strategic archetypes dominate: linear accelerator specialists commanding installed base service contracts, and imaging conglomerates leveraging diagnostic synergies into radiation oncology workflows. Competitive moves center on software maintenance subscription expansion and adaptive planning module integration partnerships.
Within the integrated-system tier, Varian Medical Systems and Elekta AB exemplify contrasting geographic anchoring and service model architectures. Siemens Healthineers occupies a position bridging diagnostic imaging and therapeutic delivery workflows. These three represent the archetype spectrum from therapy-pure to imaging-integrated competitive positioning.
| Leading Market Players |
|---|
| Varian Medical Systems |
| Elekta AB |
| Siemens Healthineers |
| Accuray Incorporated |
| GE Healthcare |
| Koninklijke Philips N.V. |
| ViewRay |
| Hitachi Ltd. |
| IBA Worldwide |
| Others |
Value Chain & Pricing Dynamics
East Asian superconducting magnet manufacturing concentrates upstream control over MRI-linac production pipelines, anchoring margin pools in adaptive planning software subscriptions and long-term service attach contracts rather than hardware sales alone.
Pricing Analysis
Software maintenance and calibration subscriptions generate lifetime value exceeding initial capital outlays. Three-tier pricing structure across premium MRI-linac systems, standard cone-beam CT configurations, and economy ultrasound-guided platforms reflects service bundling intensity and regulatory certification tiers. Cost compression in hardware sales intensifies as extended replacement cycles depress new equipment velocity, while academic medical centers show least price sensitivity due to research funding insulation.
Supply Chain Analysis
Extended payment terms from Japanese and German component suppliers finance working capital for system integrators facing hospital procurement delays. Superconducting wire production concentrates in Japan, South Korea, and Germany; cryogenic cooling systems draw from specialized Austrian and Swiss engineering houses. Single-source vulnerability in niobium-titanium superconductor supply creates exposure to export licensing shifts. Distribution runs through direct hospital sales teams supplemented by regional service depots for uptime-critical maintenance response.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adaptive planning software subscriptions expand faster than linear accelerator hardware sales, repositioning this market as a service-attach opportunity where recurring revenue stability outweighs capital equipment cyclicality.
For Market Incumbents: Insulate installed base relationships through exclusive calibration contracts and predictive maintenance algorithms that raise switching costs. Deepen backward integration into superconducting magnet supply through captive sourcing agreements with Japanese wire manufacturers. FDA 510(k) software validation expertise functions as a defensive moat against agile software entrants. For New Entrants and Emerging Players: Underpenetrated government hospital procurement programs in India represent the most penetrable entry point for cost-effective CT-guided platforms. AI-assisted contouring modules for existing linac installed bases offer a software-only beachhead avoiding capital-intensive hardware manufacturing. Partnership with established imaging conglomerates accelerates regulatory pathway navigation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed proton therapy center operators consolidating regional footprints. Five-to-ten-year viability hinges on reimbursement alignment for hypofractionated protocols expanding addressable treatment volumes. Watch CMS coding decisions for adaptive radiotherapy fractions as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements filter market access toward established manufacturers with robust quality systems. |
| Hospital System Partnership | Integrated delivery networks in the United States consolidate vendor relationships through enterprise-wide service contracts. |
| Software Companion Development | AI-assisted contouring modules compress treatment preparation timelines while tightening FDA validation scrutiny. |
| Reimbursement Strategy | CMS alignment for hypofractionated protocols accelerates capital deployment toward verification-capable systems. |
| Geographic Expansion | Provincial cancer hospital construction in China drives demand for diagnostic imaging synergies in radiation oncology workflows. |
Study Parameters
Operator-level perspectives from radiation oncology department heads, medical physicists, hospital procurement committee chairs, and GPO contracts managers anchored the qualitative base. Primary interview findings triangulated against FDA 510(k) clearance databases, CMS reimbursement coding updates, hospital capital expenditure disclosures, and EU MDR notified body reports. Bottom-up equipment installation tracking and top-down healthcare infrastructure spending analysis converged on segment-level sizing.
Scenario-bracketing around reimbursement policy shifts and proton therapy construction pipelines shaped the analytical framework across the projection horizon. Technology segmentation modeled CT, MRI, PET, and ultrasound modalities against cancer treatment, tumor localization, patient positioning, and dose measurement applications. End-user stratification captured hospitals, cancer centers, research institutions, and outpatient facilities. CAGRs derived from equipment replacement cycle analysis and software subscription attach rate trajectories, with superconducting magnet supply constraints and medical physics workforce scarcity as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, CMS reimbursement rates, or East Asian export controls would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway timelines and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Contrast Media Market
Medical Imaging
US Gadolinium-Based Contrast Media Market
Medical Imaging
US Magnetic Resonance Angiography Market
Medical Imaging
Global Dental Radiology and Dental Imaging Devices Market
Medical Imaging
3D Medical and Surgical Imaging Platform Market
Medical Imaging
Brazil Digital Radiology Market
Medical Imaging
X-Ray Flat Panel Detectors Market
Medical Imaging
Veterinary CT Imaging Market
Medical Imaging
South America Mammography Market
Medical Imaging
Mexico Mammography Market
Medical Imaging
Global Veterinary Radiography System Market
Medical Imaging
Europe Medical Imaging Market
Medical Imaging
Radio-Fluoroscopy Systems Market
Medical Imaging
Teleradiology Market
Medical Imaging
AI-Enabled Diagnostic Imaging Market
Medical Imaging
Breast Imaging Equipment Market