
 Hairy Cell Leukemia Therapeutics Market | 2026-2036
Hairy Cell Leukemia Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Hairy Cell Leukemia Therapeutics Market Intelligence
The rise of outcome-based pricing models and venture-backed drug development pipelines is tilting the competitive field toward companies with flexible financing. F. Hoffmann-La Roche Ltd leverages its extensive R&D infrastructure to develop novel monoclonal antibodies for refractory patient populations. Gilead Sciences differentiates by applying its core competencies in cellular pathway targeting. Meanwhile, Novartis AG competes through its broad oncology portfolio and established relationships with specialized cancer centers.
Hairy cell leukemia therapeutics comprise treatments for a rare, chronic B-cell lymphoproliferative disorder. These therapies function by targeting and destroying malignant lymphocytes, which are identifiable by their fine, hair-like cytoplasmic projections under a microscope. While Purine Nucleoside Analogues form the established backbone for first-line treatment, Monoclonal Antibodies are gaining significant traction. This latter category is increasingly crucial for treating relapsed/refractory cases, offering a more targeted mechanism of action.
Regulatory pathways established by the U.S. FDA and the European Medicines Agency (EMA) facilitate orphan drug designation, which accelerates development for rare conditions like HCL. These agencies, along with Japan's PMDA, enforce strict clinical data requirements for market approval, particularly for novel combination therapies. Future market access depends on demonstrating superior efficacy in achieving and maintaining minimal residual disease negativity.
Market Dynamics
The market's structure is defined by the dual pressures of achieving minimal residual disease negativity and managing treatment for an orphan disease. This dynamic elevates the importance of targeted therapies like monoclonal antibodies, which benefit from accelerated regulatory pathways established by agencies such as the FDA and EMA.
Growth Catalysts
- Orphan Drug Designation:The U.S. FDA's orphan drug policies, alongside similar frameworks from the EMA in Europe, provide critical development incentives. These programs accelerate clinical trial timelines and offer market exclusivity, encouraging investment in therapies for rare conditions like HCL.
- Advanced Diagnostics:The increasing use of flow cytometry to detect minimal residual disease (MRD) is a key catalyst. This precision allows for earlier intervention in relapsed cases, creating demand for more effective second-line and third-line treatments.
- Specialized Cancer Centers:A concentration of treatment within specialized academic and cancer centers, particularly in the United States and Germany, drives adoption of novel protocols. These institutions serve as hubs for clinical trials and early uptake of next-generation therapeutics.
Market Restraints
- High Treatment Cost:The significant expense associated with developing and administering monoclonal antibodies creates access barriers. Payer pushback and reimbursement hurdles, especially in single-payer healthcare systems, can limit patient access to these advanced agents.
- Patient Population Heterogeneity:Hairy cell leukemia presents with variations, including a classic and a variant form (HCL-V), which responds differently to standard therapies. This biological complexity complicates clinical trial design and the development of universally effective treatments.
- Dominance of First-Line Generics:The effectiveness and established profile of Purine Nucleoside Analogues like cladribine for first-line treatment limit the initial market for newer agents. Many patients achieve long-term remission with these older, less expensive therapies.
Strategic Opportunities
- Untapped Markets in Asia:Expanding diagnostic capabilities and increasing healthcare expenditure in countries like South Korea and Australia present opportunities. Navigating regulatory bodies like the MFDS and TGA could unlock new patient populations for advanced therapeutics.
- Combination Therapy Regimens:There is significant white space in developing and validating combination therapies, such as pairing a PNA with a monoclonal antibody. This approach aims to deepen responses and achieve durable MRD negativity, a key goal for regulators like Japan's PMDA.
- Next-Generation Antibody Constructs:The development of antibody-drug conjugates or bispecific antibodies tailored for HCL offers a path to improved efficacy. These constructs can target B-cell markers with greater precision than existing monoclonal antibodies, potentially overcoming treatment resistance.
Industry Challenges
- Slow Patient Recruitment:The rarity of hairy cell leukemia makes enrolling patients in clinical trials a significant operational hurdle. This challenge extends trial timelines and increases costs, particularly for studies required by the FDA and EMA for novel drug approvals.
- Manufacturing Complexity:Manufacturing monoclonal antibodies involves complex and costly cell culture processes that require specialized facilities. Ensuring consistent quality and scaling production to meet potential demand poses a persistent challenge for drug developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hairy Cell Leukemia Therapeutics Market |
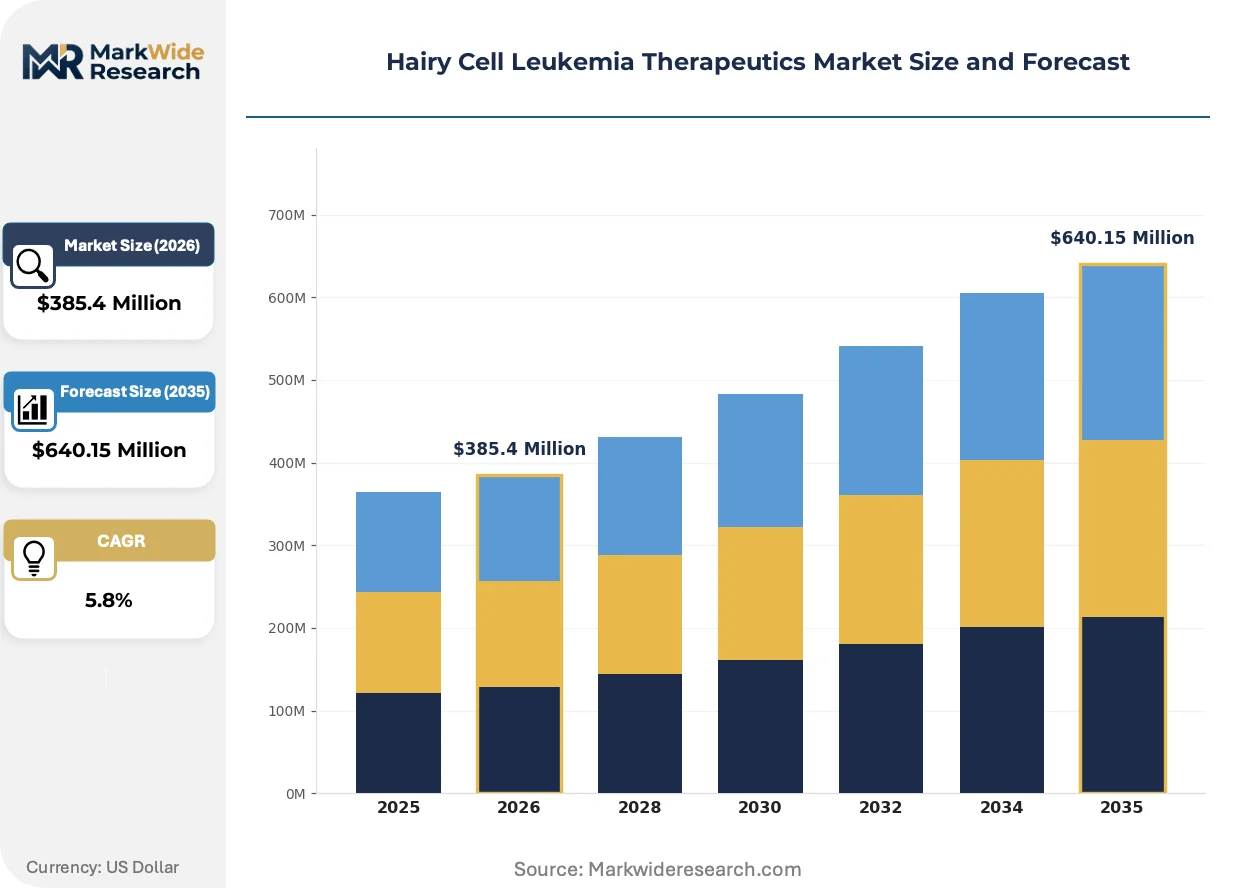
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Purine Nucleoside Analogues, Interferons, Chemotherapy Agents Therapy Area: First-Line Treatment, Relapsed/Refractory Cases, Maintenance Therapy, Minimal Residual Disease Management End User: Oncology Clinics, Specialized Cancer Centers, Research Institutes, Ambulatory Care Facilities Delivery Mode: Intravenous, Subcutaneous, Oral, Combination Therapy |
| Companies Covered | Teva Pharmaceutical Industries Ltd, AstraZeneca PLC, F. Hoffmann-La Roche Ltd, Gilead Sciences, AbbVie Inc., Novartis AG, Amgen Inc., Dr. Reddy's Laboratories Ltd, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hairy Cell Leukemia Therapeutics Market Strategic Shifts & Innovations
A fundamental transition from cytotoxic agents to targeted biologicals is redefining treatment paradigms and clinical endpoints in hairy cell leukemia. This evolution is driven by deeper molecular understanding of the disease and supported by regulatory frameworks that prioritize durable remission.
Targeted Biological Agents
Next-generation monoclonal antibodies are engineered to target specific cell surface markers like CD22 with high affinity. Specialized oncology clinics are adopting these therapies for patients who have relapsed or are refractory to initial PNA treatments. This targeted approach is rendering obsolete the reliance on less specific, more toxic salvage chemotherapy regimens for this patient population.
Accelerated Regulatory Pathways
The U.S. FDA's Real-Time Oncology Review (RTOR) program, along with the EMA's PRIME scheme, is accelerating the approval of promising HCL therapies. These initiatives permit earlier submission and review of clinical data, shortening the timeline from trial completion to market access. Consequently, therapies demonstrating significant efficacy in achieving minimal residual disease negativity are reaching patients faster.
Value-Based Reimbursement Models
Value-based care models are influencing treatment decisions and reimbursement negotiations for expensive HCL therapeutics. Instead of simple volume-based purchasing, payers and hospital systems are increasingly tying payments to long-term patient outcomes, such as duration of remission. This trend is most prominent in integrated health systems within the United States and parts of Western Europe.
Hairy Cell Leukemia Therapeutics Market Segmentation
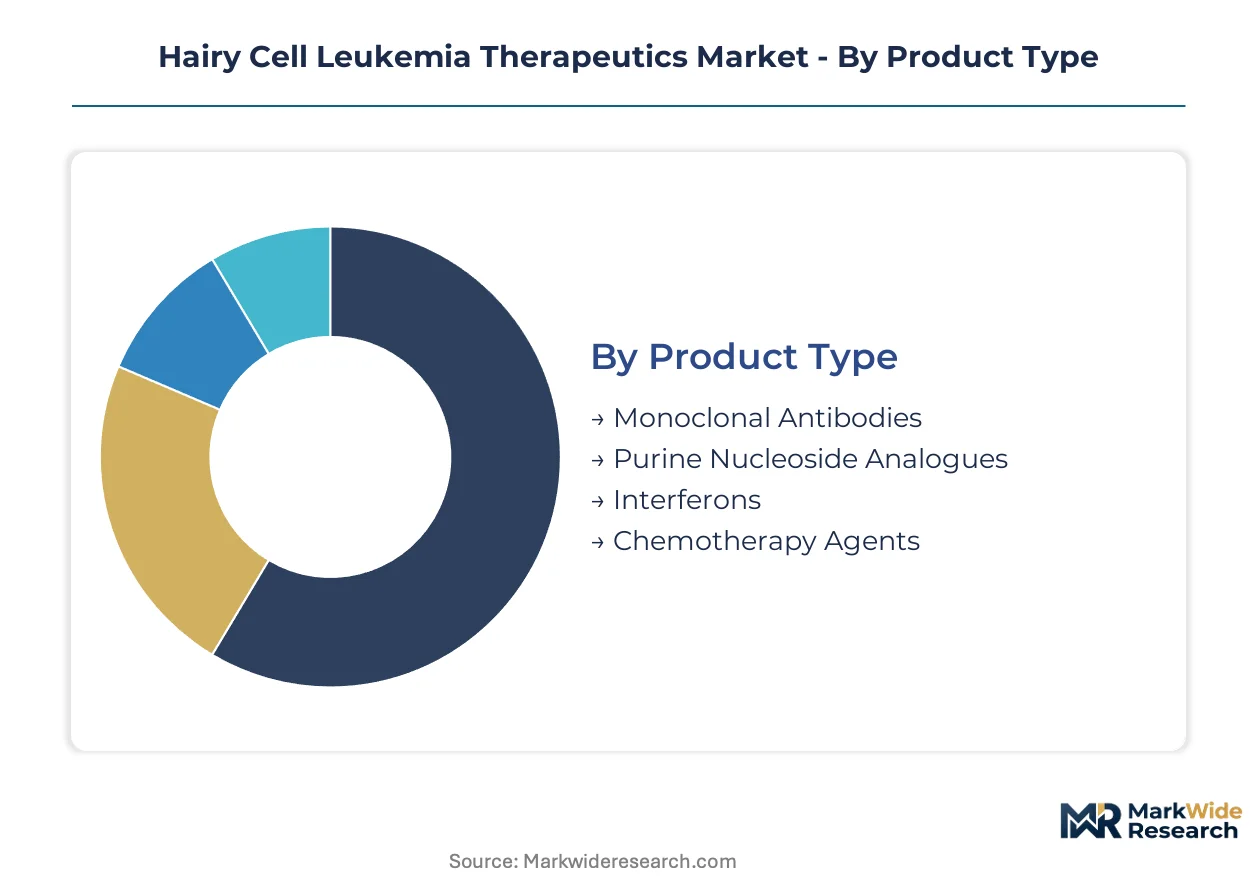
The Hairy Cell Leukemia Therapeutics market segmentation provides a granular view of treatment approaches and their deployment across various clinical settings. Analyzing these segments reveals how therapeutic innovation and patient care pathways influence market dynamics. This detailed breakdown helps stakeholders identify areas of high growth and established treatment paradigms within this orphan disease landscape.
Product Type:
The market's product type dimension highlights the diverse pharmacological mechanisms employed against Hairy Cell Leukemia.
- Monoclonal Antibodies:These targeted biological agents specifically bind to B-cell markers like CD22, leading to precise destruction of malignant lymphocytes. Demand for these antibodies concentrates in specialized cancer centers for relapsed or refractory HCL cases, driven by their superior efficacy over traditional chemotherapy.
- Purine Nucleoside Analogues:Serving as the established backbone for first-line treatment, PNAs like cladribine induce long-term remission by interfering with DNA synthesis in leukemic cells. Their effectiveness and established safety profile ensure a significant market presence, particularly in newly diagnosed HCL patients.
- Interferons:These biological response modifiers modulate the immune system to inhibit leukemic cell proliferation, often used in patients who cannot tolerate PNAs or as a maintenance therapy.
- Chemotherapy Agents:Traditional cytotoxic drugs, while less targeted, are sometimes employed in HCL, particularly in specific variant forms or as part of salvage regimens.
Purine Nucleoside Analogues commands the established base. The steepest expansion runs through Monoclonal Antibodies.
Therapy Area:
Therapy area segmentation delineates the specific clinical contexts where HCL treatments are applied, reflecting different disease stages and treatment goals.
- Relapsed/Refractory Cases:This segment addresses patients whose disease has returned or failed to respond to initial treatment, driving significant demand for novel monoclonal antibodies and targeted agents. Specialized cancer centers prioritize these advanced therapies for patients with resistant HCL.
- First-Line Treatment:This area encompasses initial therapies administered upon diagnosis, primarily dominated by Purine Nucleoside Analogues due to their high efficacy and established long-term remission rates. Regulatory bodies like the U.S. FDA recognize the importance of effective first-line options.
- Maintenance Therapy:These treatments aim to sustain remission and prevent disease recurrence, though specific maintenance strategies for HCL are still evolving.
- Minimal Residual Disease Management:This segment focuses on detecting and treating residual leukemic cells after initial therapy to achieve deeper and more durable remissions, a key regulatory and clinical endpoint.
Relapsed/refractory cases drive demand for novel agents, while first-line treatment remains a foundational segment.
End User:
End-user categories reflect where HCL therapeutics are administered, highlighting the specialized nature of treatment delivery.
- Specialized Cancer Centers:These institutions serve as primary hubs for HCL diagnosis, treatment, and clinical trials, adopting advanced protocols and next-generation therapeutics. Their concentration in the United States and Germany facilitates early uptake of innovative therapies.
- Oncology Clinics:Providing comprehensive cancer care, oncology clinics manage a broader range of HCL patients, including those receiving standard first-line treatments and follow-up care.
- Research Institutes:These entities focus on drug discovery, preclinical development, and clinical trials, contributing to the pipeline of future HCL therapeutics.
- Ambulatory Care Facilities:These settings may handle less complex HCL cases or provide supportive care and monitoring for patients in remission.
Specialized cancer centers represent the primary hubs for advanced HCL treatment. Oncology clinics ensure broader patient access across regions.
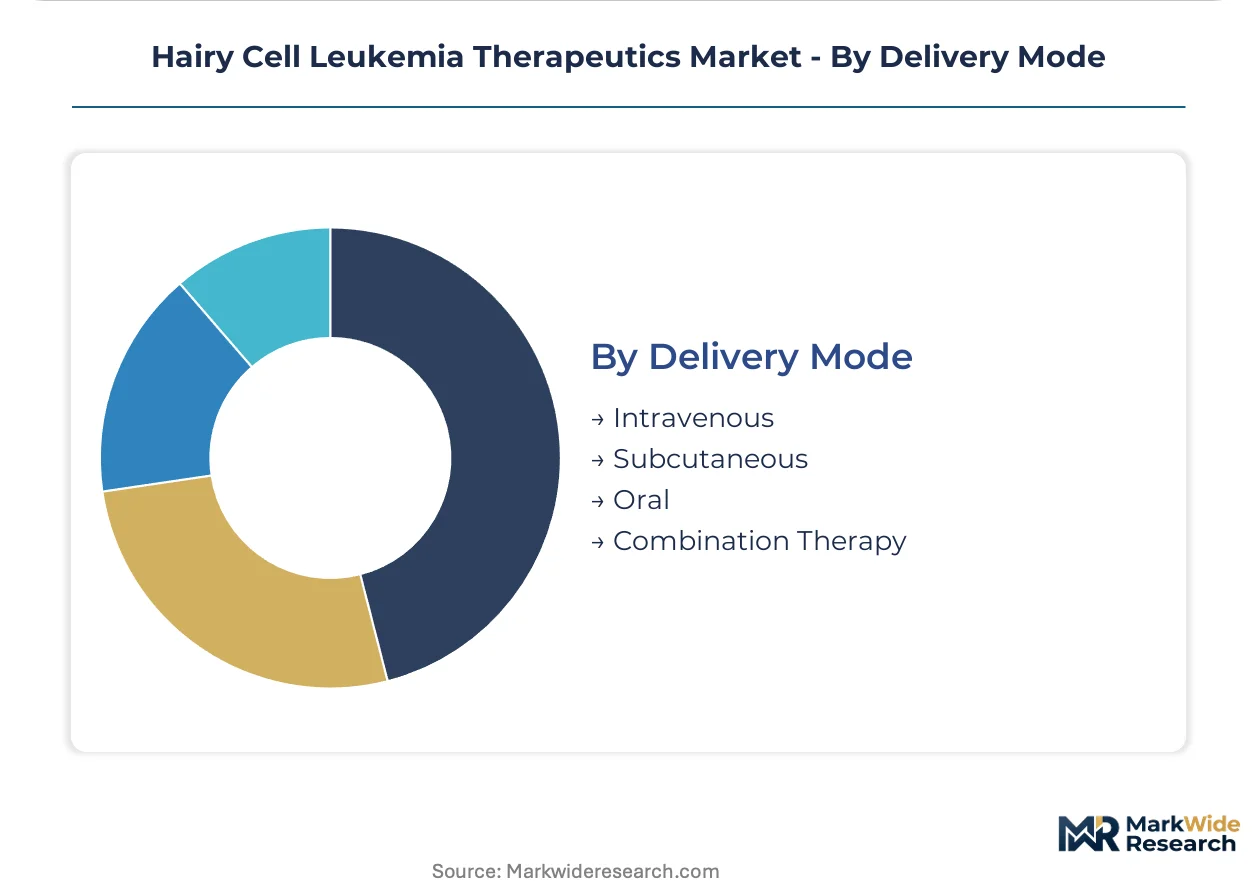
Delivery Mode:
Delivery mode options influence patient convenience and treatment adherence, impacting overall therapy management for HCL patients.
- Intravenous:This mode involves administering drugs directly into the bloodstream, a common method for monoclonal antibodies and many chemotherapy agents in a controlled clinical setting. Many advanced HCL therapies are delivered intravenously in specialized cancer centers.
- Subcutaneous:Administered under the skin, subcutaneous delivery offers potential for greater patient convenience and reduced need for frequent clinic visits for certain HCL treatments. This mode is gaining preference for its ease of use in some oncology settings.
- Oral:Oral medications provide the highest level of patient convenience, allowing for home administration, though fewer HCL therapeutics are available in this form.
- Combination Therapy:This mode refers to the delivery of multiple therapeutic agents simultaneously or sequentially to achieve enhanced efficacy and deeper responses.
Intravenous administration remains the standard for many HCL therapies. Subcutaneous options are gaining preference for their ease of use.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orphan drug designations, such as those from the U.S. FDA and European Medicines Agency, significantly accelerate therapeutic development for rare conditions like hairy cell leukemia. These incentives foster investment in advanced treatments across key global markets. Specialized cancer centers worldwide drive the adoption of novel protocols.
United States
The United States market benefits from significant research funding and a high concentration of leading pharmaceutical companies. U.S. FDA's orphan drug policies and the RTOR program accelerate drug approvals for rare diseases. Biopharma hubs in Boston and the San Francisco Bay Area drive innovation in next-generation monoclonal antibodies.
Germany
Germany's specialized cancer centers and robust healthcare infrastructure drive adoption of advanced HCL therapeutics. European Medicines Agency frameworks support orphan drug development and market access within the region. Research institutions in Munich and Berlin contribute to clinical trials and early uptake of novel treatments.
Japan
Japan emphasizes superior efficacy in achieving minimal residual disease negativity for HCL therapeutics. Japan's PMDA enforces strict clinical data requirements for market approval, particularly for novel combination therapies. Major medical centers in Tokyo and Osaka are crucial for advanced diagnostics and treatment implementation.
United Kingdom
Advanced diagnostics and specialized oncology clinics propel demand for HCL treatments across the United Kingdom. The UK's MHRA facilitates market access for innovative therapies, supporting patient access to new drugs. Academic medical centers in London and Cambridge are pivotal for clinical research and early adoption.
South Korea
Expanding diagnostic capabilities and increasing healthcare expenditure fuel demand for HCL therapeutics in South Korea. The MFDS regulatory body plays a crucial role in approving and overseeing advanced medical treatments. Major hospitals in Seoul and Gyeonggi province lead the implementation of new HCL treatment protocols.
Hairy Cell Leukemia Therapeutics Market Key Industry Players
Channel-controlling players compete with product-specialist players, defining the HCL therapeutics market structure. The landscape exhibits a tiered consolidation, where large pharmaceutical companies with extensive R&D infrastructure operate alongside smaller, agile biotech firms. Strategic archetypes include those with diversified oncology portfolios, focused orphan drug developers, and generics manufacturers. Companies primarily engage in strategic partnerships and advanced R&D investment to enhance their competitive positioning and pipeline.
Within the diversified oncology portfolio tier, F. Hoffmann-La Roche Ltd and Novartis AG exemplify established players leveraging broad R&D capabilities. Gilead Sciences occupies a distinct position by applying its core competencies in cellular pathway targeting, representing a specialized innovator. These companies, through their extensive infrastructure and targeted approaches, drive innovation in advanced HCL treatments. Their strategic focus aims at addressing refractory patient populations and achieving minimal residual disease negativity. Such firms often contribute significantly to the development of next-generation monoclonal antibodies and combination therapies.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd |
| AstraZeneca PLC |
| F. Hoffmann-La Roche Ltd |
| Gilead Sciences |
| AbbVie Inc. |
| Novartis AG |
| Amgen Inc. |
| Dr. Reddy's Laboratories Ltd |
| Pfizer Inc. |
| Others |
Cost & Logistics Intelligence
Specialized biologics manufacturing, concentrated in key biopharma hubs, directly influences the margin pools of advanced Hairy Cell Leukemia therapeutics. This upstream focus ensures that companies with robust R&D and production capabilities capture significant value.
Pricing Analysis
Superior efficacy in achieving minimal residual disease negativity creates the primary pricing spread for HCL therapeutics. Value-based models are increasingly influencing reimbursement negotiations for high-cost monoclonal antibodies, especially in integrated health systems within the United States. Payer pushback and reimbursement hurdles exert pricing pressure on novel agents, particularly in single-payer healthcare systems. Specialized cancer centers prioritize therapies demonstrating superior clinical outcomes, while general oncology clinics are more sensitive to the cost of established purine nucleoside analogues.
Supply Chain Analysis
Extended payment terms and specialized supply-chain finance facilities support the complex manufacturing of HCL therapeutics, particularly biologics. Geographic supply concentration for advanced biologics rests primarily in the United States, Germany, and Switzerland, reflecting concentrated R&D and production capabilities. Manufacturing complexity for monoclonal antibodies represents a significant structural risk, demanding specialized facilities and stringent quality controls. Distribution runs through a highly specialized cold chain network to dedicated cancer centers and oncology clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HCL therapeutics market presents a landscape defined by the limited availability of specialized expertise in orphan drug development. This scarcity of deep molecular understanding and clinical trial experience for rare blood cancers creates unique opportunities for focused strategic action.
For Market Incumbents:
Entrench market leadership by investing in next-generation antibody constructs, such as bispecific antibodies, to address refractory patient populations. Consolidate R&D efforts on combination therapies that achieve durable minimal residual disease negativity, countering payer pushback on single-agent costs. The threat of generic erosion for purine nucleoside analogues necessitates a strong pipeline of novel, differentiated biologics. Leverage extensive R&D infrastructure and established relationships with specialized cancer centers.
For New Entrants and Emerging Players:
Untapped markets in Asia, particularly South Korea, represent a penetrable entry point for novel HCL therapeutics. Focus on developing therapies for the HCL variant form (HCL-V), a segment with distinct treatment challenges. A go-to-market angle emphasizing superior efficacy in achieving deeper, more sustained remissions can differentiate new players. Combination therapy regimens also offer significant white space for innovative approaches.
For Investors and Strategic Acquirers:
Secondary-cycle assets sit with venture-backed biotechs specializing in rare disease oncology, offering attractive acquisition targets. The long-term viability of HCL therapeutics rests on demonstrating superior efficacy and achieving durable minimal residual disease negativity. Investors should target companies with advanced clinical-stage pipelines for next-generation monoclonal antibodies or novel combination therapies. A key signal to watch is successful Phase 3 clinical trial readouts for therapies addressing relapsed/refractory HCL.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Clinical Trial Design | Accelerates FDA and EMA approval for novel HCL therapies by demonstrating superior efficacy. |
| Combination Therapy Development | Aims to deepen patient responses and achieve durable minimal residual disease negativity. |
| Targeted Antibody-Drug Conjugates | Offers improved efficacy against B-cell markers, overcoming treatment resistance in HCL. |
| Expansion in Asian Markets | Unlocks new patient populations and revenue streams in countries like South Korea. |
| Value-Based Reimbursement Partnerships | Secures market access for expensive HCL therapeutics by aligning payments with patient outcomes. |
Research Approach
A spread of perspectives from drug development executives, regulatory affairs leads, specialized oncologists, and hospital pharmacy directors converged on the working assumptions. This study combined extensive primary interviews with rigorous secondary validation. Data was triangulated using bottom-up market sizing and top-down validation. Secondary sources included FDA and EMA filings, clinical trial databases, and medical journal publications.
Demand-supply balance analysis underpinned the quantitative projections across the analysis window. The analytical framework modeled market dynamics by product type, therapy area, end-user, and regional regulatory frameworks. Compound annual growth rates were derived through a comprehensive assessment of historical trends and projected future growth drivers. Key forecast inputs included disease incidence rates, treatment adoption curves, and R&D pipeline progress.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure or regulatory policy shifts would shift the trajectory. Forecasts reflect documented assumptions regarding clinical trial success and market access. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Herpes Market
Specialty Medicine
Cat Scratch Disease (CSD) Treatment Market
Specialty Medicine
Global Melanoma Therapeutics Market
Specialty Medicine
Global Melanoma Diagnostics and Therapeutics Market
Specialty Medicine
Mantle Cell Lymphoma Market
Specialty Medicine
Brain Metastasis Therapeutics Market
Specialty Medicine
Wet Age-Related Macular Degeneration (Wet AMD) Market
Specialty Medicine
Checkpoint Inhibitor Refractory Cancer Market
Specialty Medicine
Intussusception Market
Specialty Medicine
Idiopathic Short Stature Market
Specialty Medicine
Nephrogenic Systemic Fibrosis (NSF) Treatment Market
Specialty Medicine
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market
Specialty Medicine
Herpangina Treatment Market
Specialty Medicine
Bacteriophages Therapy Market
Specialty Medicine
Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market
Specialty Medicine
Global Allergic Rhinitis Market