
 Anaplastic Astrocytoma Market | 2026-2036
Anaplastic Astrocytoma Market Size, Share, and Industry Trends Forecast 2026-2036
Anaplastic Astrocytoma Market Analysis
North American biopharma manufacturing capacity for high-grade glioma therapeutics is decoupling from European API sourcing dependencies as domestic sterile production investments mature. Merck & Co., Inc. leverages its oncology manufacturing scale across multiple FDA-inspected sites to sustain supply continuity for temozolomide formulations. Novartis AG anchors its neuro-oncology portfolio through integrated radioligand therapy development pipelines. Novocure Ltd. differentiates with tumor treating fields technology leadership in recurrent disease settings.
Anaplastic astrocytoma denotes a WHO grade III malignant glioma characterized by mitotically active astrocytic cells with nuclear atypia and absence of necrosis or microvascular proliferation, typically presenting in adults aged 30-50 years with frontal lobe predilection. The primary therapeutic purpose centers on prolonging progression-free survival through multimodal interventions combining maximal safe resection with adjuvant chemoradiation. Chemotherapy regimens anchored by temozolomide occupy the largest current revenue share among product type categories, while targeted therapy segments addressing IDH-mutant subpopulations represent the fastest-expanding margin pool. Newly diagnosed indication pathways command greater treatment intensity than recurrent disease segments, though residual tumor protocols are gaining traction as adjuvant therapy extends into earlier intervention windows.
FDA orphan drug designations and breakthrough therapy pathways compress development timelines for anaplastic astrocytoma therapeutics, while EMA's PRIME eligibility criteria create parallel European access frameworks that shape trial design priorities. HIPAA-compliant real-world evidence collection infrastructure in the United States enables post-market surveillance that regulators increasingly require for sustained reimbursement eligibility. Stakeholders must monitor evolving biomarker-driven trial endpoints and companion diagnostic co-development requirements as precision oncology redefines standard-of-care boundaries across major oncology markets.
Market Dynamics
FDA breakthrough therapy designations for IDH-mutant glioma therapeutics are compressing clinical trial timelines and redirecting R&D investment toward precision oncology endpoints. This regulatory acceleration is reshaping how sponsors prioritize biomarker-driven development programs across the neuro-oncology pipeline.
Growth Catalysts
- Orphan Drug Incentives:FDA's orphan drug designation framework delivers seven-year market exclusivity and tax credits for anaplastic astrocytoma indications, drawing venture capital into previously deprioritized CNS oncology programs.
- Radioligand Therapy Expansion:Targeted alpha-emitter and beta-emitter platforms for recurrent glioma are advancing through Phase II trials, creating new intervention windows beyond standard chemoradiation protocols.
- Real-World Evidence Infrastructure:HIPAA-compliant data networks in the United States enable post-market surveillance that satisfies payor demands for progression-free survival validation outside controlled trial settings.
Market Restraints
- Temozolomide Supply Concentration:API production for alkylating agents clusters in select Asian manufacturing hubs, exposing formulation sponsors to single-source dependencies and geopolitical logistics disruptions.
- Blood-Brain Barrier Limitations:Systemic chemotherapy penetration into CNS tissue remains pharmacokinetically constrained, capping efficacy ceilings for small-molecule approaches regardless of target selectivity.
- Clinical Trial Recruitment Friction:EMA's divergent endpoint requirements for central nervous system malignancies force sponsors to maintain parallel trial designs, inflating development costs for European market access.
Strategic Opportunities
- IDH-Mutant Subpopulation Targeting:Isocitrate dehydrogenase inhibitor development represents an addressable patient segment with distinct molecular pathology and unmet need for adjuvant alternatives to temozolomide.
- Companion Diagnostic Co-Development:FDA's parallel review pathway for drug-device combinations creates regulatory efficiency for sponsors integrating biomarker assays with novel therapeutic submissions.
- Home-Based Tumor Treating Fields:Transdermal delivery systems enabling outpatient administration of alternating electric field therapy are expanding addressable patient populations beyond academic medical center catchment areas.
Industry Challenges
- Neuro-Oncology Specialist Scarcity:Fellowship-trained neuro-oncologists concentrate at NCI-designated cancer centers, limiting protocol enrollment capacity and site activation velocity for multi-arm adaptive trials.
- CGMP Sterile Manufacturing Capacity:Aseptic fill-finish capacity for parenteral biologics commands premium pricing and extended lead times, constraining launch scale for novel immunotherapy formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anaplastic Astrocytoma Market |
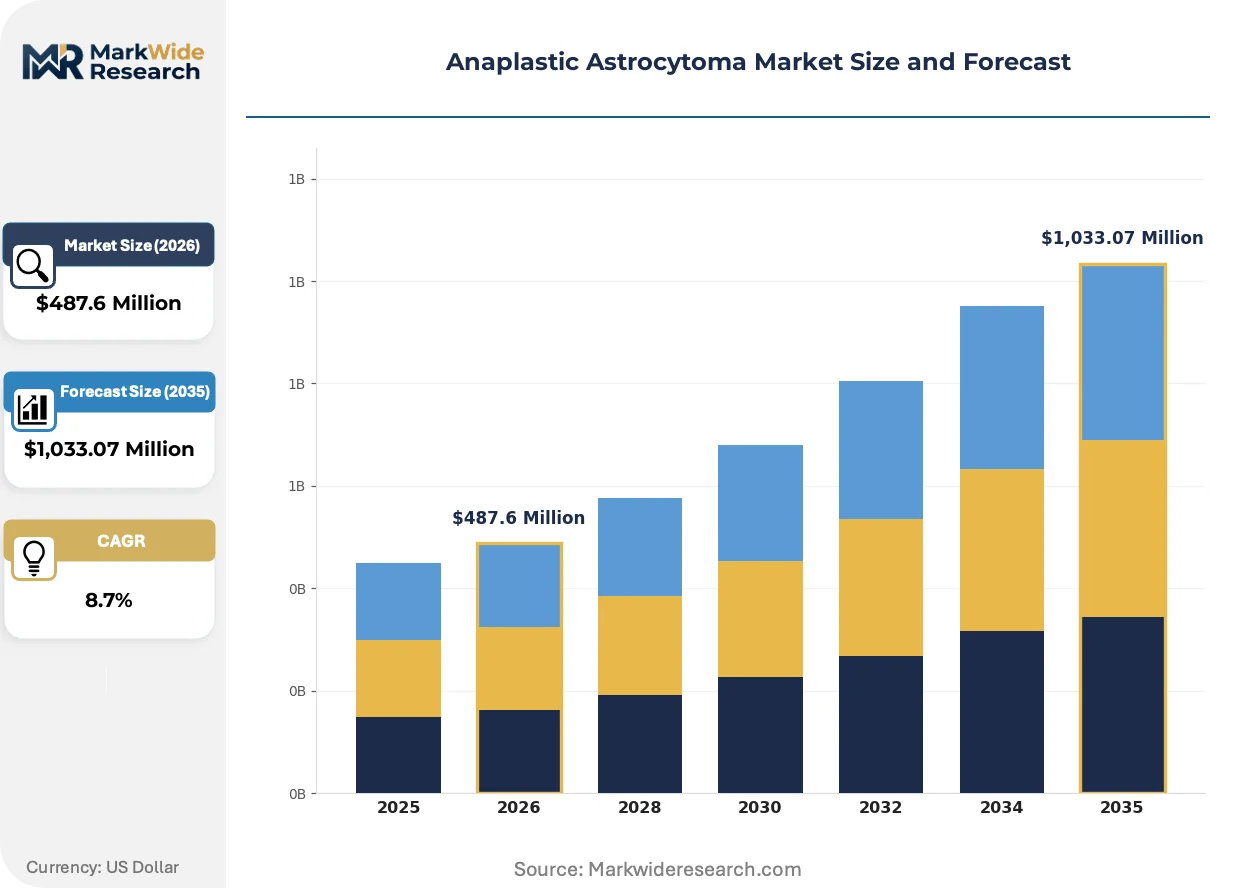
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiation Therapy, Chemotherapy, Targeted Therapy, Surgical Intervention Indication: Recurrent Disease, Newly Diagnosed, Secondary Tumors, Residual Tumors Delivery Mode: Intravenous, Oral, Intracavitary, Regional End User: Hospitals, Outpatient Clinics, Research Institutions, Specialty Cancer Centers |
| Companies Covered | Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., Pfizer Inc., Novartis AG, Servier, Agios Pharmaceuticals, Novocure Ltd., Accord Healthcare Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anaplastic Astrocytoma Market Emerging Trajectories
Biomarker stratification is fragmenting what was historically a histology-defined market into molecularly distinct addressable populations with divergent treatment pathways and regulatory requirements.
Next-generation sequencing panels for glioma classification are absorbing diagnostic workflow volume from traditional immunohistochemistry protocols, enabling simultaneous IDH, MGMT, and TERT status determination. Academic medical centers and specialty cancer centers are adopting these platforms at replacement cycle pace, collapsing the time between tissue acquisition and treatment selection. This molecular upstaging is absorbing patient volume from empiric chemotherapy regimens into targeted therapy eligibility screening.
EMA's PRIME eligibility criteria for regenerative and advanced therapy medicinal products are creating parallel European priority review frameworks that shape trial design priorities for glioma sponsors. The industrial consequence is a bifurcation in endpoint selection, with European submissions emphasizing overall survival over progression-free survival surrogates. High-grade glioma programs with transatlantic ambitions are responding by powering trials for dual-primary endpoints, inflating enrollment targets but securing simultaneous FDA and EMA filing readiness.
Site-of-care migration is redistributing anaplastic astrocytoma treatment delivery from inpatient surgical corridors toward ambulatory infusion centers and home-based device administration. Specialty pharmacy networks and durable medical equipment channels are capturing service revenue previously retained by hospital outpatient departments. This channel disintermediation is most visible in the United States, where Medicare reimbursement differentials between facility and non-facility settings accelerate patient steering toward lower-acuity venues.
Anaplastic Astrocytoma Market Segmentation
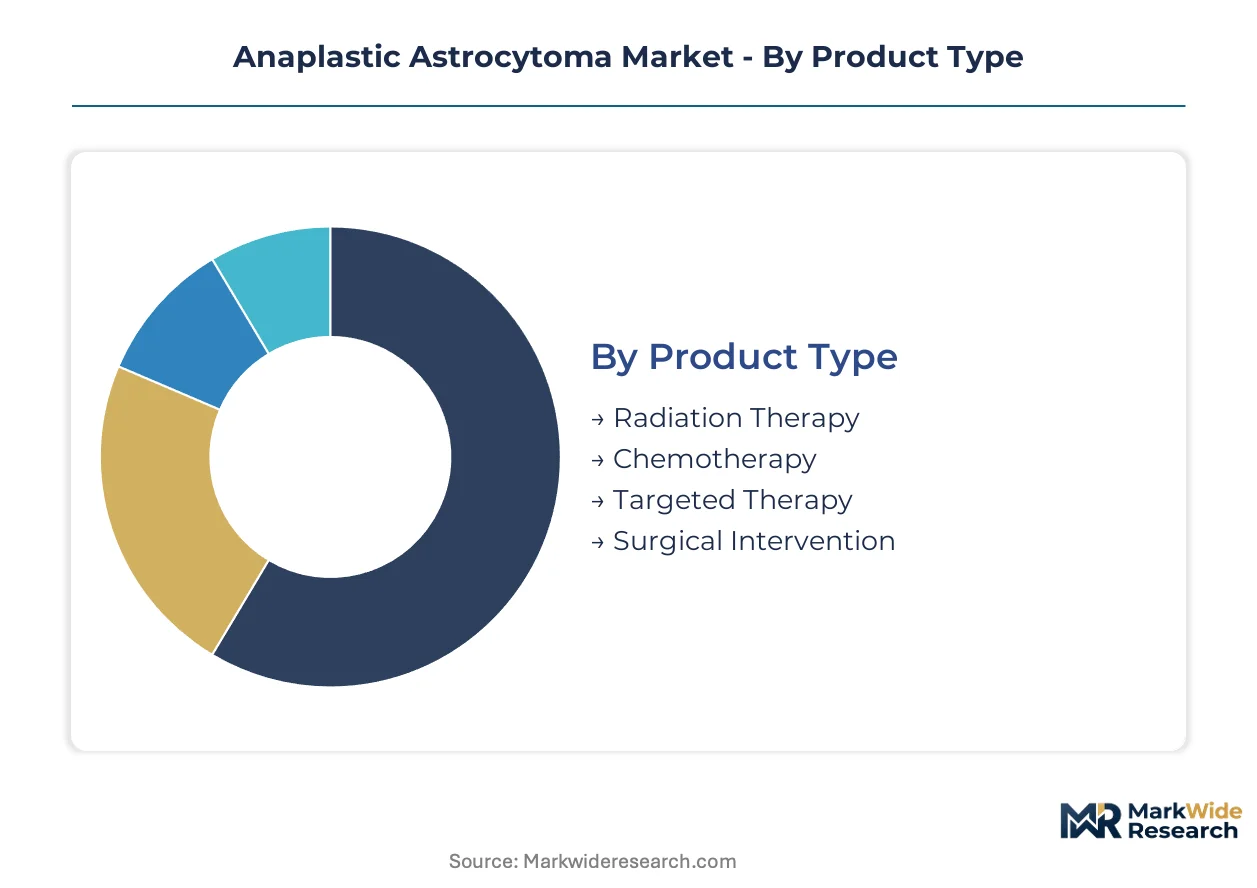
Molecular stratification is fragmenting anaplastic astrocytoma treatment pathways into distinct addressable populations with divergent intervention intensities and reimbursement profiles. Segmentation reveals how technology modality, disease stage, and site-of-care configuration shape commercial opportunity across the neuro-oncology landscape.
Product Type:
Technology modality determines clinical positioning and margin structure across the therapeutic continuum.
- Chemotherapy:Alkylating agents—principally temozolomide—constitute the backbone of adjuvant protocols following maximal safe resection. Demand concentrates at NCI-designated cancer centers in the United States where MGMT methylation testing guides treatment selection; supply continuity depends on API sourcing from Asian manufacturing hubs exposed to geopolitical logistics risk.
- Targeted Therapy:IDH-mutant inhibitors and receptor tyrosine kinase antagonists represent precision oncology approaches with companion diagnostic dependencies. Clinical trial recruitment accelerates at academic medical centers in Germany where biomarker stratification protocols are most mature; regulatory pathways through FDA breakthrough therapy designations compress development timelines for sponsors.
- Radiation Therapy:Fractionated external beam protocols remain standard-of-care for newly diagnosed patients, with proton beam facilities capturing high-acuity cases.
- Surgical Intervention:Maximal safe resection with intraoperative imaging and fluorescence-guided techniques enables tissue diagnosis and cytoreduction.
Chemotherapy leads on scale; targeted therapy leads on momentum.
Indication:
Disease stage at presentation dictates treatment intensity and duration of therapy.
- Newly Diagnosed:First-line protocols combine surgery with concurrent chemoradiation followed by adjuvant temozolomide cycles. Treatment volume concentrates at specialty cancer centers in the United States where multidisciplinary tumor boards coordinate care; reimbursement intensity peaks in this segment with the longest duration of monitored therapy.
- Recurrent Disease:Second-line interventions encompass re-irradiation, alternate chemotherapy regimens, and tumor treating fields application. Patient volume distributes across outpatient clinic networks in Germany where salvage protocol enrollment is most systematic; clinical trial access shapes treatment selection where standard options have failed.
- Secondary Tumors:Progression from lower-grade gliomas or treatment-related malignancies requires modified protocol design.
- Residual Tumors:Adjuvant therapy for incompletely resected disease is gaining traction as early intervention windows expand.
Newly diagnosed indications dominate current revenue; recurrent disease segments are expanding most quickly through trial enrollment.
Delivery Mode:
Route of administration shapes site-of-care economics and patient compliance profiles.
- Oral:Temozolomide capsules enable outpatient administration with reduced infusion center dependency. Prescription volume flows through specialty pharmacy networks in the United States where home delivery and adherence monitoring programs improve persistence; bioequivalence requirements for generic formulations create pricing pressure on originator products.
- Intravenous:Parenteral biologics and cytotoxic agents require infusion center capacity with aseptic handling protocols. Service revenue concentrates at hospital outpatient departments in Germany where facility fees offset drug margin compression; CGMP sterile manufacturing constraints limit supply scale for novel immunotherapies.
- Intracavitary:Localized delivery via implanted reservoirs or convection-enhanced platforms targets residual tumor beds.
- Regional:Arterial or intrathecal administration remains investigational for blood-brain barrier penetration enhancement.
Oral delivery commands the largest patient volume; intravenous routes retain the highest per-treatment value.
End User:
Site-of-care configuration determines reimbursement mechanics and protocol enrollment capacity.
- Specialty Cancer Centers:NCI-designated comprehensive cancer centers aggregate neuro-oncology specialists, advanced imaging, and trial access. Patient referrals concentrate from community oncology practices in the United States seeking molecular profiling and experimental therapy eligibility; these sites capture the highest acuity cases with the most complex multimodal protocols.
- Hospitals:General acute care facilities provide emergency stabilization and initial surgical management. Service distribution spans regional medical centers in Germany where neurosurgical capacity is geographically dispersed; inpatient stays generate facility revenue that cross-subsidizes oncology program investment.
- Outpatient Clinics:Ambulatory infusion centers and community oncology practices handle stable patients on oral regimens.
- Research Institutions:Academic medical centers with principal investigator networks drive Phase I/II enrollment.
Specialty cancer centers lead on protocol complexity; outpatient clinics are gaining share fastest through site-of-care migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States specialty cancer centers deploy multimodal protocols at greater intensity than German outpatient networks, yet both markets converge on biomarker-driven patient stratification as the defining care pathway.
United States
NCI-designated comprehensive cancer centers in Houston and Boston aggregate neuro-oncology fellowship-trained specialists and advanced imaging infrastructure. FDA breakthrough therapy designations for IDH-mutant therapeutics compress clinical trial timelines, redirecting venture capital toward precision oncology endpoints. The Greater Boston biopharma corridor anchors domestic sterile manufacturing investments that decouple API sourcing from Asian supply dependencies.
Germany
Academic medical centers in Munich and Heidelberg maintain Europe's most systematic biomarker stratification protocols for glioma classification. EMA's PRIME eligibility criteria for advanced therapy medicinal products shape trial design priorities, with sponsors emphasizing overall survival endpoints for European submissions. The Baden-Württemberg medical technology cluster supports integrated radioligand therapy development pipelines.
United Kingdom
London's tertiary neuro-oncology units concentrate Phase I/II trial enrollment for novel immunotherapy formulations. The Medicines and Healthcare products Regulatory Agency's early access to medicines scheme creates parallel pathways for pre-approval patient access. The Oxford-Cambridge arc anchors real-world evidence collection infrastructure that satisfies post-market surveillance requirements.
Japan
Tokyo's National Cancer Center drives adoption of next-generation sequencing panels for simultaneous IDH, MGMT, and TERT status determination. PMDA's sakigake designation system accelerates review timelines for regenerative and advanced therapy medicinal products. The Kansai region's proton beam facilities capture high-acuity cases requiring precision radiation delivery.
Switzerland
Basel's pharmaceutical research ecosystem anchors integrated drug-device combination development for tumor treating fields technology. Swissmedic's parallel review pathway for companion diagnostic co-development creates regulatory efficiency for biomarker-integrated therapeutic submissions. The Lake Geneva biotech cluster supports transatlantic trial designs powered for dual-primary endpoints.
Anaplastic Astrocytoma Market Vendor Landscape
United States pharmaceutical manufacturers anchor one tier with oncology manufacturing scale across multiple FDA-inspected sites; European and Israeli specialists hold differentiated positions in device-mediated and targeted therapy segments. Market structure reflects moderate consolidation around alkylating agent supply continuity and emerging fragmentation in precision oncology development. Three archetypes dominate: diversified oncology majors with sterile production infrastructure, radioligand therapy developers with integrated diagnostic pipelines, and device-centric innovators with transdermal delivery platforms. Competitive moves center on companion diagnostic co-development partnerships and site-of-care migration toward home-based administration modalities.
Among diversified pharmaceutical manufacturers, Merck & Co., Inc. and Novartis AG exemplify scale-driven archetypes with established neuro-oncology portfolios, while Novocure Ltd. occupies a distinct position in device-mediated intervention. Merck & Co., Inc. represents manufacturing breadth across sterile formulation sites, Novartis AG anchors radioligand therapy integration, and Novocure Ltd. exemplifies outpatient delivery system innovation. These three entities collectively illustrate how technology modality—small-molecule chemotherapy, targeted radiotherapy, and electric field intervention—determines competitive positioning within addressable patient populations.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| Novartis AG |
| Servier |
| Agios Pharmaceuticals |
| Novocure Ltd. |
| Accord Healthcare Ltd. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up sterile manufacturing specialists in the United States are consolidating aseptic fill-finish capacity, tightening pricing discipline for parenteral biologics while pressuring originator margins on oral alkylating agents through specialty pharmacy channel consolidation.
Pricing Analysis
Capacity additions in the United States are reshaping price floors for CGMP sterile manufacturing services, compressing margins for novel immunotherapy formulations while oral temozolomide faces bioequivalence-driven erosion through generic substitution. Three-tier pricing structure across originator brand, authorized generic, and commodity generic levels stratifies by FDA approval pathway and MGMT testing bundling. Pricing pressure stems from Medicare reimbursement differentials between facility and non-facility settings. Community oncology practices exhibit highest price sensitivity; NCI-designated centers prioritize protocol compliance over acquisition cost.
Supply Chain Analysis
Regional distribution centers in Germany and the United States operate hub-and-spoke patterns for radioligand therapy isotopes with 72-hour half-life constraints. API production for alkylating agents concentrates in India and China, drawing from acetonitrile and hydrazine hydrate feedstocks. Single-source vulnerability in isotope generation reactors creates supply continuity exposure for alpha-emitter platforms. Distribution runs through specialty pharmacy networks with cold-chain validation for biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anaplastic astrocytoma therapeutics represent a late-cycle quality story as demand concentrates in IDH-mutant subpopulations requiring companion diagnostic integration and premium pricing justification through biomarker stratification.
For Market Incumbents: Acquire CGMP sterile manufacturing assets in the Greater Boston corridor to secure aseptic fill-finish capacity for parenteral biologics. Consolidate radioligand therapy isotope sourcing through long-term offtake agreements with European reactor operators. Novocure's tumor treating fields delivery infrastructure poses substitution threat to adjuvant chemotherapy persistence; counter through MGMT methylation testing bundling with oral alkylating agents. For New Entrants and Emerging Players: Specialty pharmacy networks with home delivery capabilities offer lowest-friction channel access for oral regimen market entry. Target recurrent disease segments in German outpatient clinics where salvage protocol enrollment lacks systematic coordination. Pursue FDA breakthrough therapy designation for IDH-mutant inhibitors to compress development timelines against established alkylating agent protocols. For Investors and Strategic Acquirers: Valuations sit cheapest among device-mediated therapy developers with transdermal delivery platforms and real-world evidence generation infrastructure. Five-to-ten-year viability hinges on successful companion diagnostic co-development and Medicare reimbursement establishment for novel modalities. Watch FDA accelerated approval conversion rates to full approval as inflection indicator for precision oncology platform durability.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA parallel review pathway compresses regulatory timelines for IDH-mutant inhibitor submissions. |
| Home-Based Tumor Treating Fields Expansion | Transdermal delivery systems extend addressable populations beyond academic medical center catchment areas. |
| Radioligand Therapy Pipeline Advancement | Targeted alpha-emitter platforms create intervention windows beyond standard chemoradiation protocols. |
| Real-World Evidence Infrastructure Investment | HIPAA-compliant data networks satisfy payor demands for progression-free survival validation outside trials. |
| CGMP Sterile Manufacturing Scale-Up | Domestic aseptic fill-finish capacity decouples from Asian API sourcing dependencies and geopolitical risk. |
Methodological Framework
Bottom-up patient volume modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with neuro-oncology fellowship directors, specialty pharmacy procurement managers, formulary access specialists at major payors, and regulatory affairs leads at glioma-focused biopharma sponsors were validated against secondary sources including FDA orphan drug designation filings, EMA PRIME eligibility determinations, ClinicalTrials.gov protocol registrations, and CMS Medicare reimbursement databases. This triangulation ensures demand-side patient flow estimates align with supply-side manufacturing capacity disclosures.
Historical trendline analysis of treatment episode costs and progression-free survival outcomes by molecular subtype informed the projection framework across the analysis window. Segmentation dimensions modeled include technology modality, disease stage at presentation, route of administration, and site-of-care configuration. CAGRs were derived from slope analysis of patent expiry curves, generic entry timelines, and biomarker penetration rates. Forecast inputs incorporated MGMT methylation testing adoption curves and IDH-mutant inhibitor clinical trial enrollment velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to blood-brain barrier penetration breakthroughs and radioligand therapy isotope supply continuity. Outputs reflect documented assumptions regarding regulatory pathway success rates and reimbursement establishment timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Acute Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Nonerosive Reflux Disease Treatment Market
Specialty Medicine
Osteomyelitis Market
Specialty Medicine
Intramedullary Osteosarcoma Treatment Market
Specialty Medicine
Cat Scratch Disease (CSD) Treatment Market
Specialty Medicine
Global Laryngeal Cancer Therapeutics Market
Specialty Medicine
Dementia Management Market
Specialty Medicine
Global Eye Allergy Therapeutics Market
Specialty Medicine
Global Fungal Keratitis Treatment Market
Specialty Medicine
Global Graves Disease Market
Specialty Medicine
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market
Specialty Medicine
Global Tourette Syndrome Treatment Market
Specialty Medicine
Immunoglobulin (Igg) Replacement Therapy Market
Specialty Medicine
Chemotherapy Induced Thrombocytopenia Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Europe Idiopathic Pulmonary Fibrosis Treatment Market