
 Postmenopausal Osteoporosis Treatment Market | 2026-2036
Postmenopausal Osteoporosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Postmenopausal Osteoporosis Treatment Market Intelligence
Patient support programs and outcome-based reimbursement frameworks is broadening what pharmaceutical manufacturers sell beyond the pill itself. Amgen Inc. leverages its established infrastructure in bone health to sustain loyalty among rheumatology practices. Eli Lilly and Company anchors its competitive stance through differentiated delivery mechanisms for anabolic therapies. Pfizer Inc. competes on manufacturing scale, controlling distribution networks that reach community-based infusion sites.
Postmenopausal osteoporosis treatment encompasses pharmacologic and non-pharmacologic interventions targeting bone mineral density loss following ovarian hormone decline, with biologics requiring cold-chain logistics and precise dosing schedules measured in milligrams per kilogram of body weight. The primary purpose is fracture prevention and skeletal integrity maintenance in women with elevated ten-year fracture risk scores. Bisphosphonates still occupy the largest volume share due to generic availability and decades of clinical familiarity, though RANKL inhibitors command premium positioning in high-risk patient pools. Monoclonal antibodies represent the fastest-expanding margin pool as physicians gain confidence in their reversible bone turnover suppression. Hormonal therapies face structural headwinds from cardiovascular safety scrutiny, constraining their growth trajectory despite historical dominance.
The FDA oversees post-market surveillance for osteoporosis biologics through its Risk Evaluation and Mitigation Strategy requirements, while the EMA's Pharmacovigilance Risk Assessment Committee shapes European prescriber confidence through periodic safety updates. The EU MDR imposes stricter clinical evidence standards on diagnostic devices used in bone density screening, indirectly filtering which treatment pathways gain reimbursement traction. Stakeholders must monitor how payer consolidation across integrated delivery networks will reshape contracting dynamics for injectable versus oral therapies.
Market Dynamics
Medicare reimbursement policies favoring outpatient infusion centers are concentrating demand around specialized delivery infrastructure, while specialty osteoporosis clinics expand biologic therapy capacity to capture this shift.
Growth Catalysts
- Biologics cold-chain infrastructure:Expanded refrigeration networks at rheumatology practices enable precise dosing schedules measured in milligrams per kilogram, supporting monoclonal antibody administration.
- FDA Risk Evaluation and Mitigation Strategy:Structured post-market surveillance requirements build physician confidence in reversible bone turnover suppression therapies.
- United States:Medicare outpatient infusion center reimbursement creates concentrated demand pull for injectable anabolic therapies over oral alternatives.
Market Restraints
- EMA Pharmacovigilance Risk Assessment Committee:Periodic safety update requirements create regulatory friction that slows prescriber adoption velocity for newer biologics.
- Bisphosphonate generics:Decades of clinical familiarity and cost compression block premium positioning for novel mechanisms in standard-risk patient pools.
- Cardiovascular safety scrutiny:Structural headwinds constrain hormonal therapy growth despite historical dominance in bone mineral density maintenance.
Strategic Opportunities
- Community-based infusion sites:Distribution channel innovation reaches patients outside specialty hospital networks, expanding addressable population for RANKL inhibitors.
- Integrated delivery networks:Payer consolidation creates contracting leverage for bundled bone health programs spanning screening through treatment.
- EU MDR diagnostic standards:Stricter clinical evidence requirements on bone density screening devices filter reimbursement traction toward validated treatment pathways.
Industry Challenges
- Rheumatology workforce constraints:Limited specialist availability creates bottlenecks for biologic therapy initiation and monitoring protocols.
- EU MDR certification timelines:Extended approval cycles for companion diagnostic devices delay coordinated screening-to-treatment workflow deployment.
- Legacy electronic health record integration:Ten-year fracture risk scoring tools require costly interoperability upgrades for seamless clinical decision support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Postmenopausal Osteoporosis Treatment Market |
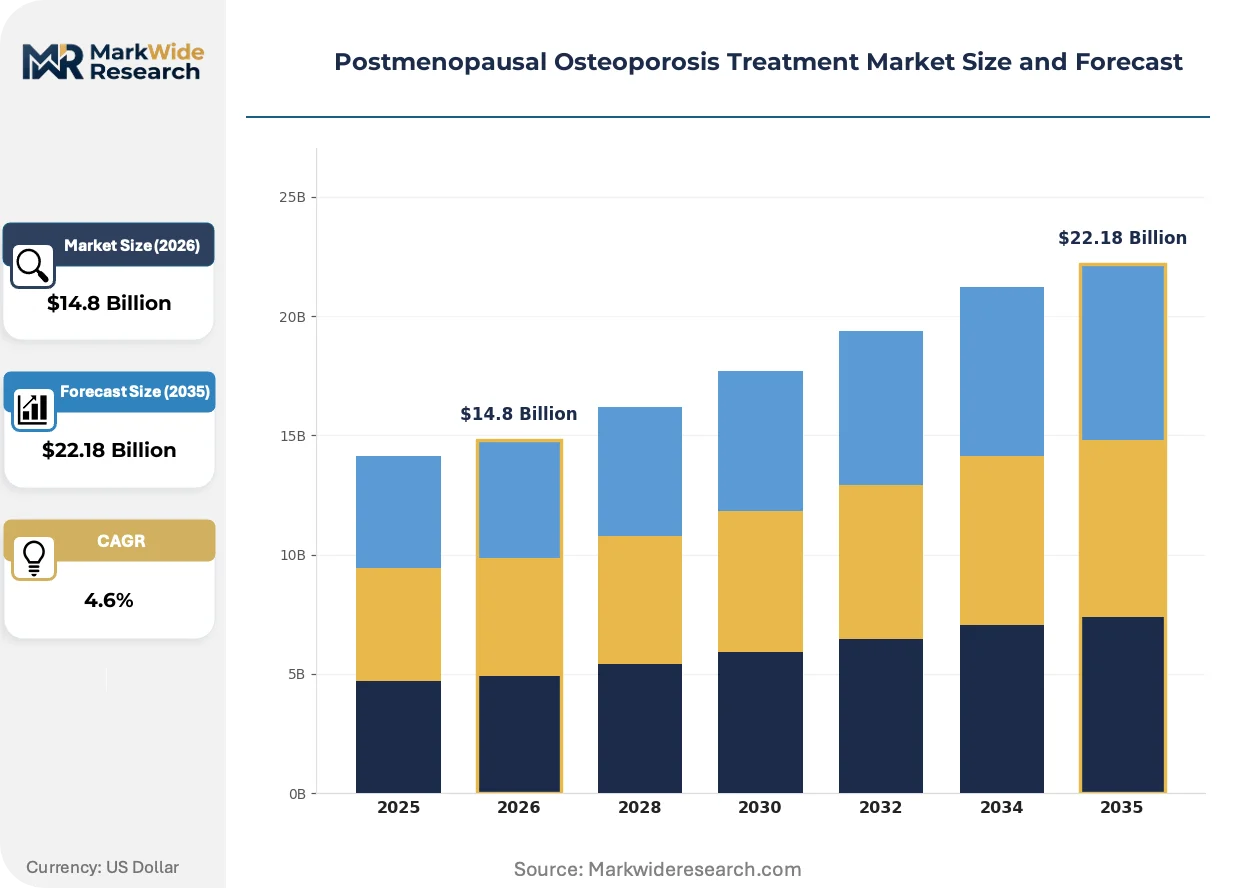
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bisphosphonates, Hormonal Therapies, Monoclonal Antibodies, RANKL Inhibitors Route of Administration: Oral, Subcutaneous, Intravenous, Transdermal End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Treatment Stage: Preventive, Early Intervention, Advanced Therapy, Post-treatment |
| Companies Covered | Amgen Inc., Eli Lilly and Company, Merck & Co., Inc., Pfizer Inc., Novartis AG, AbbVie Inc., F. Hoffmann-La Roche Ltd., Teva Pharmaceutical Industries Ltd., Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Postmenopausal Osteoporosis Treatment Market Strategic Shifts & Innovations
Biologic delivery mechanisms and diagnostic integration are compressing treatment initiation timelines while regulatory frameworks evolve to match long-term pharmacovigilance needs.
Monoclonal antibodies targeting RANKL signaling are overtaking bisphosphonates in high-risk patient stratification. Rheumatology practices with dedicated infusion capacity adopt these therapies at accelerated rates for patients with elevated ten-year fracture scores. This mechanism shift is compressing the window between diagnosis and biologic initiation from months to weeks.
EMA Pharmacovigilance Risk Assessment Committee periodic safety updates now mandate real-world evidence collection for all osteoporosis biologics. European prescribers face heightened documentation requirements that reshape confidence thresholds for therapy selection. High-risk patient pools in Germany and France demonstrate strongest response to these structured surveillance frameworks.
Specialty osteoporosis clinics now unbundle after-care monitoring from initial therapy administration, creating discrete service lines for bone turnover marker tracking. Community-based infusion sites in the United States absorb this monitoring function through remote patient support programs. This service fragmentation is most visible in Medicare Advantage networks seeking capitated bone health outcomes.
Postmenopausal Osteoporosis Treatment Market Segmentation
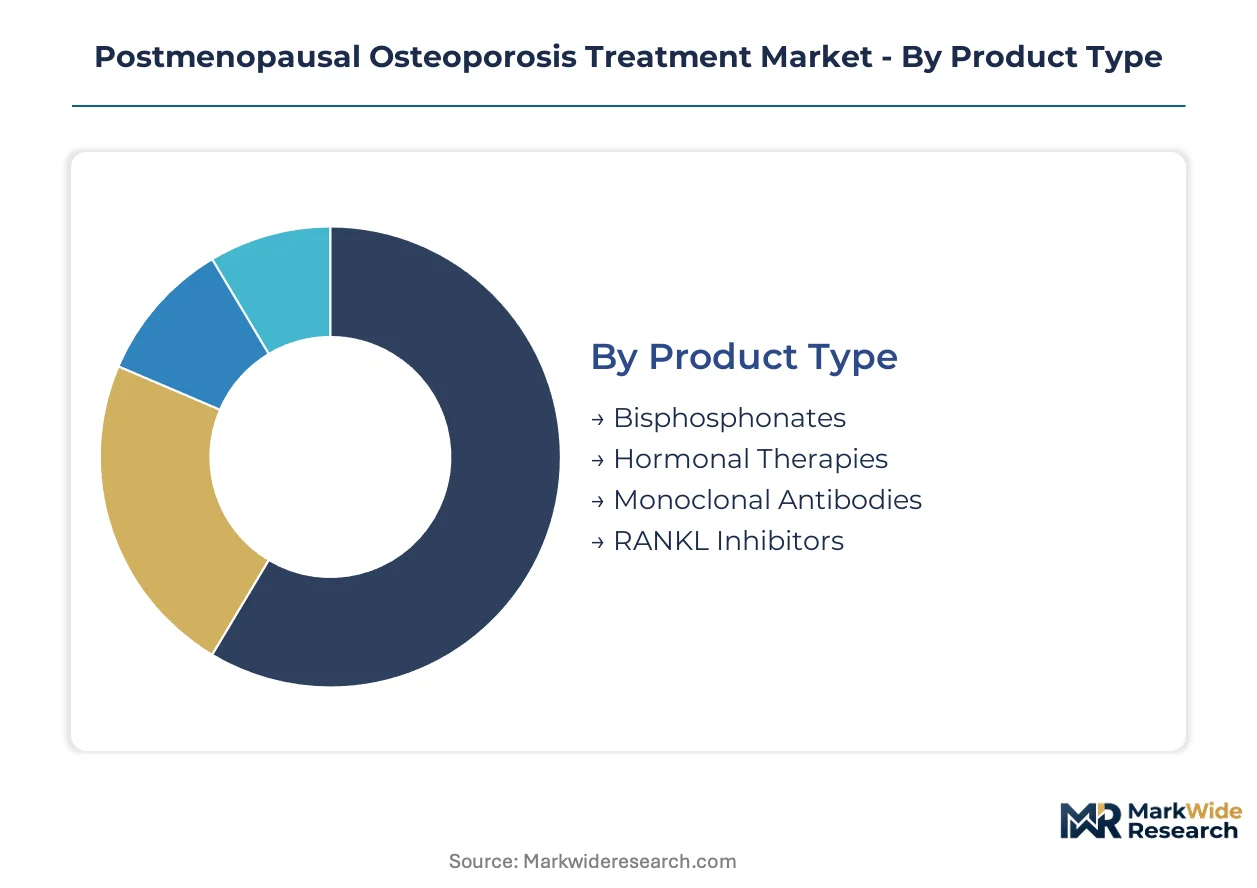
Segmentation in postmenopausal osteoporosis treatment reveals how therapeutic decisions cascade from molecular mechanism through delivery logistics to care setting economics. Each dimension shapes reimbursement pathways and prescriber workflow requirements differently.
Product Type:
Customization intensifies as mechanisms move from oral small molecules to precision biologics requiring cold-chain handling and weight-based dosing protocols.
- Bisphosphonates:Oral and intravenous nitrogen-containing compounds bind hydroxyapatite to suppress osteoclast-mediated resorption. Demand concentrates in Medicare Advantage networks prioritizing generic alendronate for standard-risk patients with ten-year fracture scores below threshold for biologic escalation.
- Monoclonal Antibodies:Fully humanized IgG2 constructs targeting sclerostin or RANKL signaling require refrigerated storage and subcutaneous administration by trained staff. Rheumatology practices with dedicated infusion capacity capture disproportionate volume for high-risk patients with prior vertebral fractures.
- Hormonal Therapies:Selective estrogen receptor modulators and tissue-selective estrogen complexes face constrained utilization following FDA cardiovascular safety labeling revisions.
- RANKL Inhibitors:Denosumab and emerging biosimilars command premium positioning in oncology-adjacent bone health protocols.
Most installed capacity flows through Bisphosphonates. Expansion is steepest in Monoclonal Antibodies.
Route of Administration:
Patient risk stratification and site-of-care economics determine whether therapy shifts toward self-administered injections or supervised infusions.
- Oral:Weekly or monthly bisphosphonate tablets dominate first-line prescribing for treatment-naïve patients with adequate gastrointestinal absorption and medication adherence capacity.
- Intravenous:Zoledronic acid and ibandronate infusions concentrate in outpatient infusion centers benefiting from Medicare reimbursement differentials that favor facility-based administration over physician office settings.
- Subcutaneous:Prefilled syringe and auto-injector formats for denosumab and romosozumab enable quarterly or monthly dosing with reduced healthcare utilization.
- Transdermal:Experimental estradiol patches for bone health remain limited to hormone therapy indications with cardiovascular risk mitigation protocols.
Oral routes retain the largest patient volume base. Subcutaneous delivery is gaining share fastest among biologic-naïve patients transitioning from bisphosphonates.
End User:
Care setting fragmentation reflects divergent capabilities for biologic storage, fracture risk assessment integration, and longitudinal monitoring.
- Specialty Osteoporosis Clinics:Dedicated bone health centers combine DXA imaging, fracture liaison services, and infusion capacity to capture high-complexity patients requiring anabolic sequencing. United States metropolitan markets show fastest site expansion where Medicare reimbursement supports bundled bone health outcomes.
- Hospitals:Academic medical centers anchor regional referral networks for complex cases with secondary osteoporosis etiologies or imminent fracture risk requiring inpatient coordination.
- Home Care:Visiting nurse services administer subcutaneous therapies for mobility-limited patients in rural or underserved geographies distant from infusion infrastructure.
- Long-term Care Facilities:Skilled nursing facilities manage oral bisphosphonate compliance for institutionalized populations with elevated fall and fracture risk profiles.
Specialty clinics absorb the majority of new biologic initiations. Home care channels are expanding most quickly for established patients on maintenance dosing.
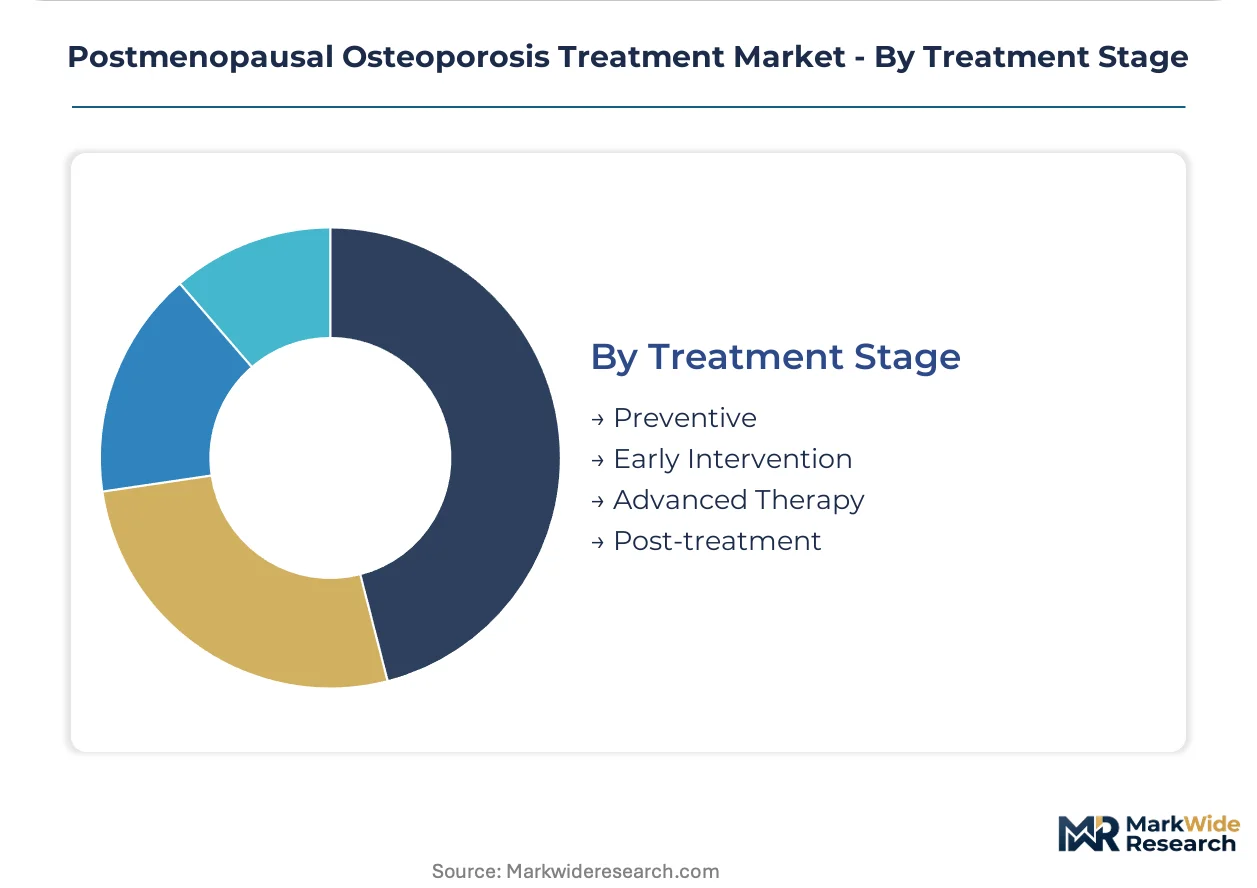
Treatment Stage:
Patient journey positioning determines therapy intensity, monitoring frequency, and reimbursement coding requirements.
- Preventive:Calcium, vitamin D, and lifestyle interventions target perimenopausal women with normal bone density seeking to delay pharmacologic escalation.
- Early Intervention:Oral bisphosphonates or hormonal therapies for patients with osteopenia and additional risk factors represent the largest addressable population by volume.
- Advanced Therapy:Anabolic agents followed by antiresorptive sequencing for severe osteoporosis with fragility fracture history command highest per-patient expenditure and specialist involvement.
- Post-treatment:Drug holidays, bone turnover marker surveillance, and re-treatment protocols for patients completing initial therapeutic courses.
Early intervention stages handle the greatest patient throughput. Advanced therapy segments show the steepest expenditure trajectory as anabolic sequencing becomes standard of care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement structures diverge sharply from European capitation models, while Japan's aging demographic density creates distinct site-of-care economics for injectable therapies.
United States
Medicare outpatient infusion center reimbursement pulls demand toward supervised administration of RANKL inhibitors and anabolic agents. The FDA's Risk Evaluation and Mitigation Strategy requirements shape prescriber confidence thresholds for biologic initiation. Rheumatology practices in metropolitan clusters across Florida, Texas, and Arizona expand dedicated infusion capacity to capture this reimbursement differential.
Germany
EMA Pharmacovigilance Risk Assessment Committee periodic safety updates mandate real-world evidence collection that slows adoption velocity for newer mechanisms. Germany's statutory health insurance system maintains preference for oral bisphosphonates in standard-risk stratification. Academic medical centers in Berlin and Munich anchor regional referral networks for complex anabolic sequencing protocols.
Japan
PMDA post-market surveillance requirements for osteoporosis biologics align with the country's concentrated geriatric population in urban corridors. Japan's community-based long-term care insurance system supports home care administration of subcutaneous therapies. Specialist osteoporosis centers in Tokyo, Osaka, and Nagoya coordinate fracture liaison services with municipal health departments.
United Kingdom
NICE technology appraisal processes create staged access barriers for premium-priced anabolic agents outside severe osteoporosis indications. The UK's integrated care systems consolidate bone health pathway contracting across screening, diagnosis, and treatment phases. London and Manchester academic health science networks pilot bundled reimbursement for fracture prevention outcomes.
France
ANSM pharmacovigilance reporting requirements for biologics intersect with HAS evaluation criteria for hospital formulary inclusion. France's regional health agencies coordinate osteoporosis screening campaigns that feed into specialist referral queues. The Lyon and Paris hospital clusters maintain the highest concentration of dedicated bone mineral density imaging and infusion capacity.
Postmenopausal Osteoporosis Treatment Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with research-intensive pharmaceutical companies commanding premium positioning in biologic therapies while generic manufacturers capture volume in oral bisphosphonate maintenance. The market structure concentrates around three strategic archetypes: vertically integrated innovators with cold-chain distribution control, mid-scale specialists with rheumatology practice loyalty programs, and biosimilar entrants targeting European price-sensitive tenders. Dominant competitive moves include backward integration into diagnostic device partnerships and geographic expansion through specialty clinic acquisition.
Within the innovator tier, Amgen Inc. and Eli Lilly and Company occupy positions defined by anabolic therapy differentiation and delivery mechanism patents. Pfizer Inc. exemplifies scale-driven manufacturing and distribution reach into community infusion sites. These three anchors represent divergent strategic bets on whether clinical outcomes data or logistical proximity will determine prescriber selection in the next treatment protocol cycle.
| Leading Market Players |
|---|
| Amgen Inc. |
| Eli Lilly and Company |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Novartis AG |
| AbbVie Inc. |
| F. Hoffmann-La Roche Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Sanofi S.A. |
| Others |
Cost & Logistics Intelligence
Cold-chain logistics costs for monoclonal antibodies cascade through three pricing tiers as biologics move from contract manufacturing organizations through specialty distributors to outpatient infusion centers in the United States. Medicare reimbursement differentials for facility-based administration create price floors that oral bisphosphonate generics cannot match, segmenting the market by delivery infrastructure investment rather than molecule efficacy alone.
Pricing Analysis
Capacity additions in United States outpatient infusion centers are reshaping price floors for injectable anabolic therapies. Three-tier pricing structure across premium biologics, standard branded agents, and economy generic bisphosphonates reflects reimbursement coding complexity and cold-chain handling requirements. Price differentiation hinges on site-of-care economics and FDA Risk Evaluation and Mitigation Strategy compliance burden. Cost compression in the oral generic tier is intensifying because Medicare Advantage plans favor alendronate for standard-risk patients. Community-based infusion sites show highest price sensitivity; specialty osteoporosis clinics with bundled outcomes contracts show lowest.
Supply Chain Analysis
Returns of expired biologics from rheumatology practices and specialty clinics create reverse-logistics flows that cold-chain carriers must manage under FDA temperature excursion protocols. Active pharmaceutical ingredient production concentrates in Ireland, Singapore, and Puerto Rico for monoclonal antibody cell culture. Finished formulation draws from sterile fill-finish capacity in Switzerland, Belgium, and North Carolina. Single-source vulnerability in IgG2 construct manufacturing creates supply risk during facility contamination events. Distribution runs through specialty pharmacy networks with refrigerated last-mile capabilities rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Postmenopausal osteoporosis treatment represents a late-cycle quality story where demand shifts toward anabolic agents with demonstrated vertebral fracture reduction data, rewarding manufacturers with robust real-world evidence generation infrastructure.
For Market Incumbents: Extend formulary protection through outcome-based contracting with integrated delivery networks, locking in multi-year bone health pathway agreements before biosimilar denosumab entrants reach European tenders. Deepen cold-chain infrastructure control through captive distribution partnerships with community infusion sites, defending against margin erosion from oral generic switches in standard-risk stratification. For New Entrants and Emerging Players: Launch via home care nursing networks for subcutaneous maintenance dosing, capturing mobility-limited patients in rural geographies distant from hospital-based infusion capacity. Target Medicare Advantage plans with capitated bone health outcomes as the most penetrable payer segment, offering remote patient monitoring bundles that unbundle after-care from initial therapy administration. For Investors and Strategic Acquirers: Consolidation pressure builds where rheumatology practice management platforms lack biologic dispensing infrastructure to capture Medicare reimbursement differentials. Five-to-ten year viability favors acquirers of specialty osteoporosis clinics with DXA-imaging-to-infusion workflow integration. Watch FDA biosimilar interchangeability determinations for denosumab as the inflection signal triggering acquisition multiples compression.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Real-world evidence collection under EMA pharmacovigilance mandates accelerates prescriber confidence in novel mechanisms. |
| Regulatory Approval Pathway | FDA Risk Evaluation and Mitigation Strategy certification differentiates biologics from oral alternatives in high-risk pools. |
| Manufacturing Scale-Up | Cell culture capacity expansion in Puerto Rico and Singapore secures supply for RANKL inhibitor demand concentration. |
| Pipeline Diversification | Sclerostin antibody sequencing protocols address anabolic therapy gaps in severe osteoporosis with multiple fractures. |
| Reimbursement Strategy | Medicare outpatient infusion center contracting captures site-of-care economics favoring injectable over oral administration. |
Research Approach
Coverage spans the United States, Germany, Japan, the United Kingdom, and France, with primary inputs from each market's reimbursement and regulatory environment. Drug development executives, regulatory affairs leads at EMA and FDA, formulary directors at integrated delivery networks, and hospital procurement managers provided qualitative grounding. Secondary validation drew from FDA filings, EMA periodic safety update reports, ClinicalTrials.gov osteoporosis intervention listings, and CMS Medicare claims data. Bottom-up patient-flow modeling and top-down pharmaceutical expenditure triangulation anchored volume estimates.
Rate-of-change decomposition separated volume effects from price mix shifts across the projection horizon. Segmentation dimensions included molecular mechanism, route of administration, care setting, and treatment line positioning. CAGRs derived from logistic diffusion curves for biologic penetration rates, calibrated to historical analogs in rheumatoid arthritis and oncology bone health. Forecast inputs incorporated Medicare reimbursement rulemaking timelines and EU MDR diagnostic device certification cycle lengths.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA biosimilar interchangeability determinations and EMA pharmacovigilance committee safety signal actions. Practitioners should monitor Medicare Advantage plan bone health outcome metric adoption and rheumatology workforce expansion rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
Global Appendiceal Cancer Treatment Market
Specialty Medicine
Vitiligo Treatment Market
Specialty Medicine
Global Chronic Lower Back Pain (CLBP) Market
Specialty Medicine
Muscle Wasting Disorders Market
Specialty Medicine
Anaplastic Astrocytoma Market
Specialty Medicine
Carcinoid Syndrome Diarrhea Treatment Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
Epileptic Seizures Treatment Market
Specialty Medicine
Immunology Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Phenylketonuria Therapeutics Market
Specialty Medicine
Monoclonal Antibody Therapy Market
Specialty Medicine
Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Adenomyosis Market
Specialty Medicine
Odontogenic Tumor Market