
 Castrate Resistant Prostate Cancer Therapeutics Market | 2026-2036
Castrate Resistant Prostate Cancer Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Castrate Resistant Prostate Cancer Therapeutics Market Outlook
Precision oncology biomarker stratification is fragmenting traditional trial design and commercial deployment across the CRPC landscape. Johnson & Johnson anchors its position through deep urology franchise integration spanning diagnostics through therapy. Pfizer competes via broad immuno-oncology platform extension into prostate-specific indications. Astellas Pharma specializes in androgen receptor pathway modulation, sustaining geographic concentration in Japanese and North American markets.
Castrate resistant prostate cancer therapeutics comprise pharmaceutical agents designed to suppress tumor progression following failure of androgen deprivation therapy, encompassing small-molecule inhibitors, biologics, and cytotoxic agents formulated for intravenous or oral administration. These therapies target persistent androgen receptor signaling, alternative survival pathways, or immune evasion mechanisms in metastatic and non-metastatic disease states. Hormonal agents occupy the dominant revenue position given established enzalutamide and abiraterone portfolios, while immunotherapy represents the fastest-expanding development frontier despite prior sipuleucel-T commercial constraints. Targeted therapy segments directed at PARP-mutant populations concentrate emerging margin pools as companion diagnostic linkages tighten.
FDA oncology center review standards and EMA adaptive pathway frameworks govern trial design requirements and post-market surveillance obligations across all development programs. The IRA Medicare price negotiation provisions reshape US commercial forecasting for approved agents approaching exclusivity expiration. Stakeholders must monitor biomarker-defined subpopulation fragmentation and its implications for trial recruitment economics and label expansion feasibility.
Market Dynamics
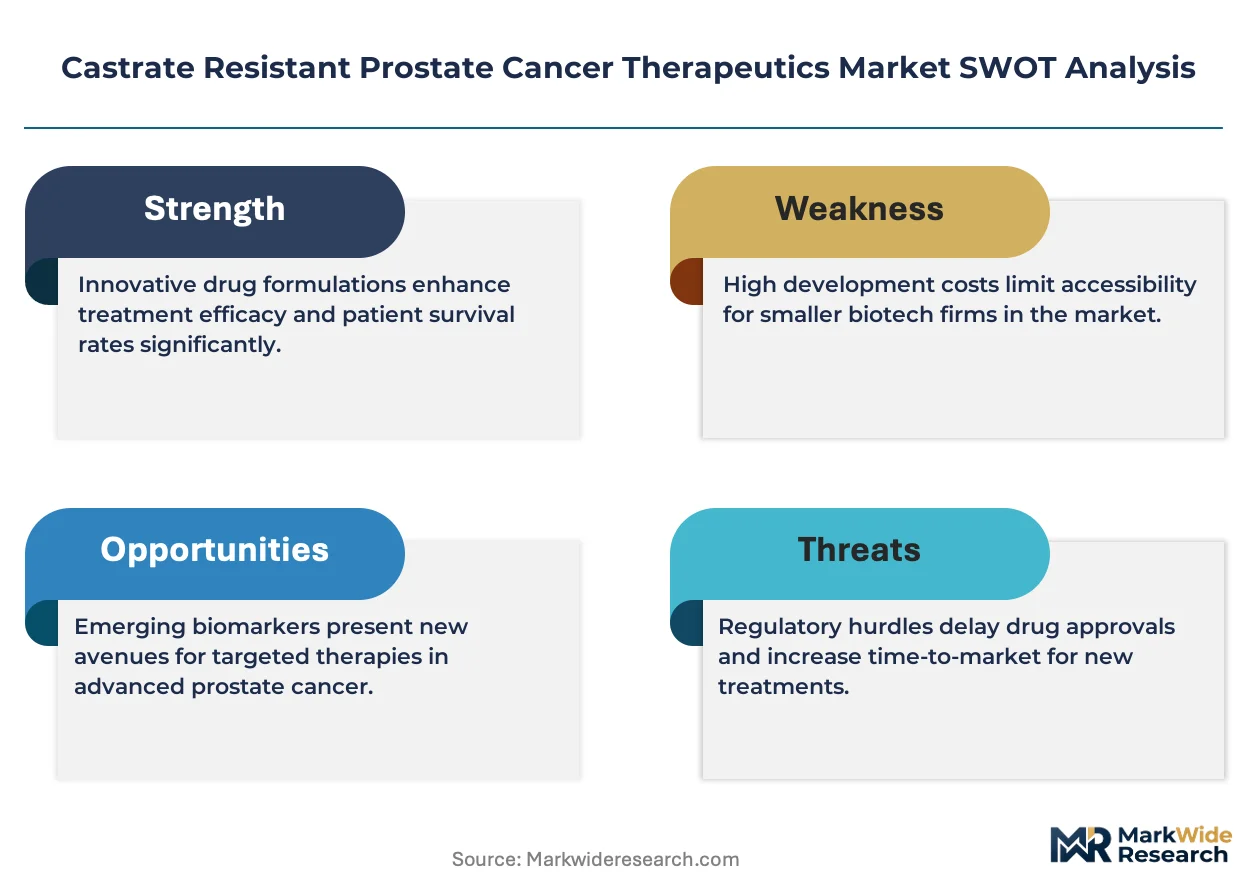
Biomarker stratification is fragmenting trial design and commercial deployment across the castrate resistant prostate cancer landscape, forcing developers to recalibrate recruitment economics and label expansion feasibility around molecularly defined subpopulations rather than broad histologic indications.
Growth Catalysts
- IRA Medicare Price Negotiation Provisions:The US Inflation Reduction Act creates new commercial forecasting imperatives for agents approaching exclusivity expiration, accelerating lifecycle management investments and indication sequencing strategies.
- Hospital Oncology Department Expansion:Tertiary cancer centers in the United States are deepening adoption of novel hormonal agents, concentrating demand within integrated delivery networks that capture longitudinal patient journeys.
- PARP Inhibitor Biomarker Linkages:Companion diagnostic requirements for BRCA-mutant and HRR-deficient populations are tightening, creating defendable margin pools through test-treatment bundling.
Market Restraints
- Accelerated Approval Pathway Uncertainty:The FDA's oncology center review standards for confirmatory trial requirements create post-market surveillance obligations that compress commercial runway timelines and raise regulatory capital intensity.
- Immunotherapy Development Friction:Sipuleucel-T's commercial constraints have chilled investor appetite for prostate-specific immunotherapy platforms, limiting funding availability for cellular therapy approaches.
- Androgen Receptor Pathway Saturation:Deep enzalutamide and abiraterone penetration in first-line metastatic settings narrows the addressable population for subsequent hormonal mechanisms, intensifying competition for limited progression events.
Strategic Opportunities
- Radioligand Therapy Convergence:The intersection of PSMA-targeted imaging and therapeutic radiopharmaceuticals creates a theranostic platform opportunity that redefines treatment sequencing and site-of-care economics.
- EMA Adaptive Pathway Framework:Conditional marketing authorization mechanisms in Europe enable earlier revenue generation from limited datasets, compressing development-to-commercialization timelines for novel mechanisms.
- Japanese Market Concentration:Astellas Pharma's established urology franchise infrastructure provides a template for geographic expansion into Asian markets with aging demographics and rising prostate cancer incidence.
Industry Challenges
- Companion Diagnostic Integration Complexity:PARP inhibitor programs require synchronized CDx development and commercialization with molecular pathology laboratories, creating coordination friction across diagnostic and therapeutic organizations.
- Trial Recruitment Economics Compression:Biomarker-defined eligibility criteria shrink addressable patient pools, extending enrollment timelines and inflating per-patient acquisition costs for registrational studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Castrate Resistant Prostate Cancer Therapeutics Market |
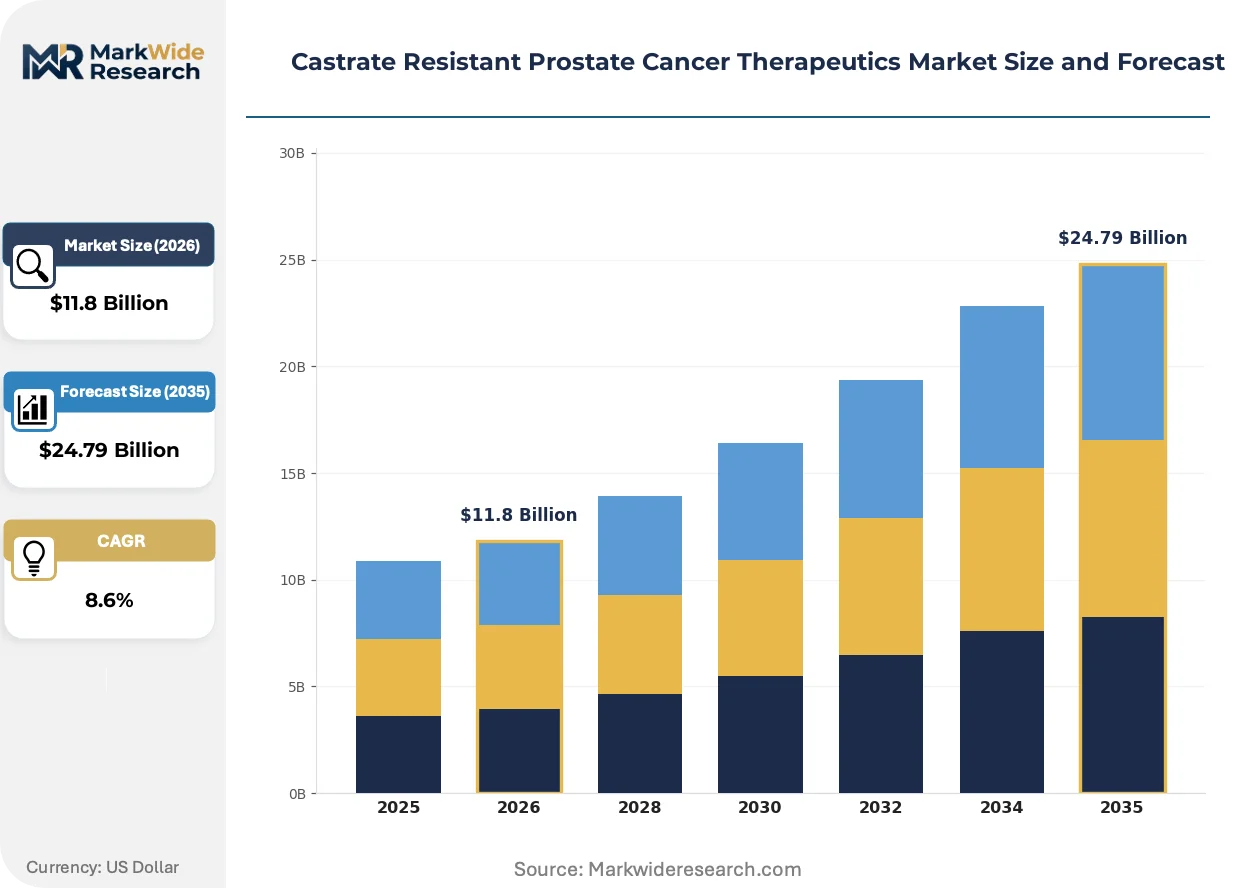
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.79 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Agents, Chemotherapy, Targeted Therapy, Immunotherapy Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular End User: Hospitals, Oncology Clinics, Research Institutions, Homecare Pricing Model: Premium, Discounted, Tiered, Volume-Based |
| Companies Covered | AstraZeneca, Sanofi, Johnson & Johnson, Merck, Novartis, Pfizer, Bayer, Exelixis, Astellas Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Castrate Resistant Prostate Cancer Therapeutics Market Strategic Shifts
Precision oncology platforms are actively restructuring competitive positioning in castrate resistant prostate cancer, with molecular stratification displacing histology-first approaches and radiopharmaceutical theranostics emerging as a distinct modality category.
Next-generation androgen receptor degraders are rendering obsolete conventional competitive antagonism strategies that rely on ligand-binding domain occupancy. Academic medical centers with integrated molecular tumor boards are adopting these proteolysis-targeting chimeras at accelerated cadence for AR-amplified and AR-mutant populations. The structural consequence is a compression of development timelines for agents dependent on pure antagonist mechanisms.
The FDA's Project Optimus dose-optimization mandate is reshaping oncology trial design requirements, compelling sponsors to incorporate randomized dose-ranging rather than defaulting to maximum tolerated dose selection. This industrial consequence extends phase I/II timelines and increases patient exposure requirements. Early-phase programs for PARP and AKT inhibitors are most affected, with sponsors responding through adaptive trial designs and expanded biomarker correlative science.
Site-of-care migration toward hospital outpatient departments is disrupting traditional community oncology infusion patterns for cytotoxic and biologic agents. Integrated delivery networks are capturing these volumes through captive specialty pharmacy arrangements and in-house nuclear medicine capabilities. This shift concentrates most visibly in United States metropolitan markets with dominant health system presence.
Castrate Resistant Prostate Cancer Therapeutics Market Segmentation
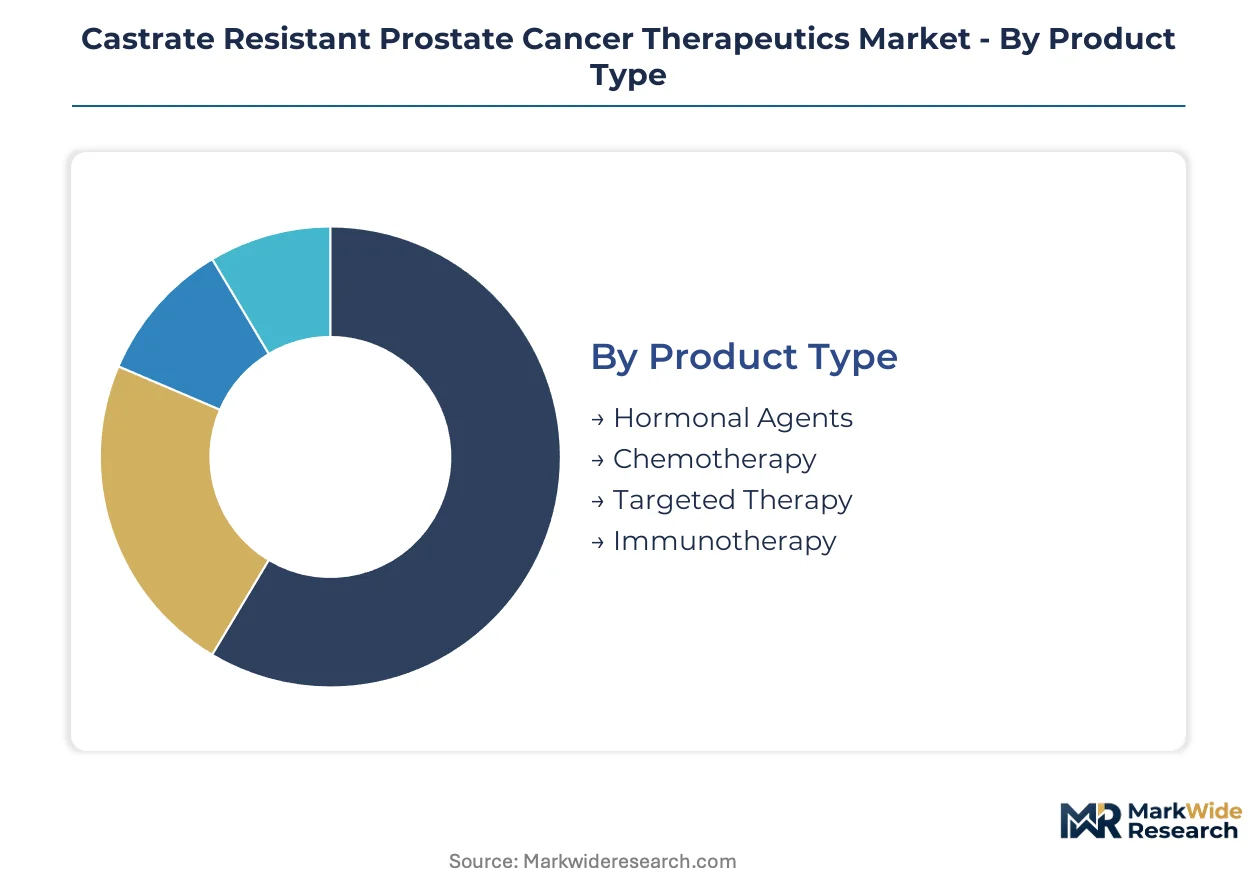
Precision oncology is fragmenting the CRPC market into molecularly defined subpopulations, forcing manufacturers to align formulation strategies with companion diagnostic workflows and site-of-care economics. Segmentation now determines reimbursement pathways, trial recruitment feasibility, and lifecycle management investments across hormonal, cytotoxic, and biologic modalities.
Product Type:
After-sales service intensity concentrates in hormonal agents and targeted therapy segments, where manufacturers maintain field-based medical liaisons to support biomarker testing integration and adverse event management.
- Hormonal Agents:Small-molecule androgen receptor antagonists and androgen synthesis inhibitors dominate current prescribing patterns. Enzalutamide and abiraterone portfolios anchor revenue concentration in US hospital outpatient departments and Japanese urology centers, though pathway saturation in first-line metastatic settings narrows subsequent-line opportunities.
- Targeted Therapy:PARP inhibitors and AKT pathway modulators require synchronized companion diagnostic deployment. Demand clusters in academic medical centers with integrated molecular tumor boards in Boston, Heidelberg, and Tokyo, where BRCA-mutant and HRR-deficient testing infrastructure supports test-treatment bundling.
- Chemotherapy:Taxane-based cytotoxic regimens retain utility in rapid-progression phenotypes.
- Immunotherapy:Cellular therapy platforms face chilled investor appetite following prior commercial constraints.
By volume, hormonal agents lead. By growth pace, targeted therapy is ahead.
Delivery Mode:
Cost tier stratification separates intravenous formulations requiring infusion infrastructure from oral agents suitable for pharmacy benefit management.
- Intravenous:Cytotoxic and biologic agents requiring supervised administration concentrate demand in hospital outpatient departments with captive specialty pharmacy arrangements. Site-of-care migration toward integrated delivery networks in US metropolitan markets disrupts traditional community oncology infusion patterns.
- Oral:Small-molecule hormonal agents and targeted therapies enable pharmacy benefit management capture and patient convenience positioning. Prescription volume concentrates in Medicare Part D and commercial pharmacy networks, with prior authorization friction shaping access dynamics.
- Subcutaneous:Reduced administration burden appeals to homecare settings.
- Intramuscular:Limited applications in luteinizing hormone-releasing hormone agonist depot formulations.
Oral delivery captures the largest prescription volume. Intravenous maintains the highest revenue per patient.
End User:
Customer type fragmentation splits between institutional purchasers with formulary control and emerging direct-to-patient channels.
- Hospitals:Tertiary cancer centers with integrated molecular pathology laboratories capture longitudinal patient journeys through diagnosis, treatment sequencing, and progression monitoring. US academic medical centers in Houston, New York, and Los Angeles anchor adoption of novel hormonal agents and radioligand theranostics.
- Oncology Clinics:Community-based practices face reimbursement compression and site-of-care migration pressures, concentrating remaining volume in physician-owned infusion centers with pharmacy benefit management carve-outs.
- Research Institutions:Phase I/II trial enrollment and correlative science programs.
- Homecare:Oral agent administration and patient support services.
Hospitals command the highest patient acuity. Oncology clinics retain the broadest geographic reach.
Pricing Model:
Margin structure varies across mechanisms that extract value from clinical differentiation versus those that compete on access expansion.
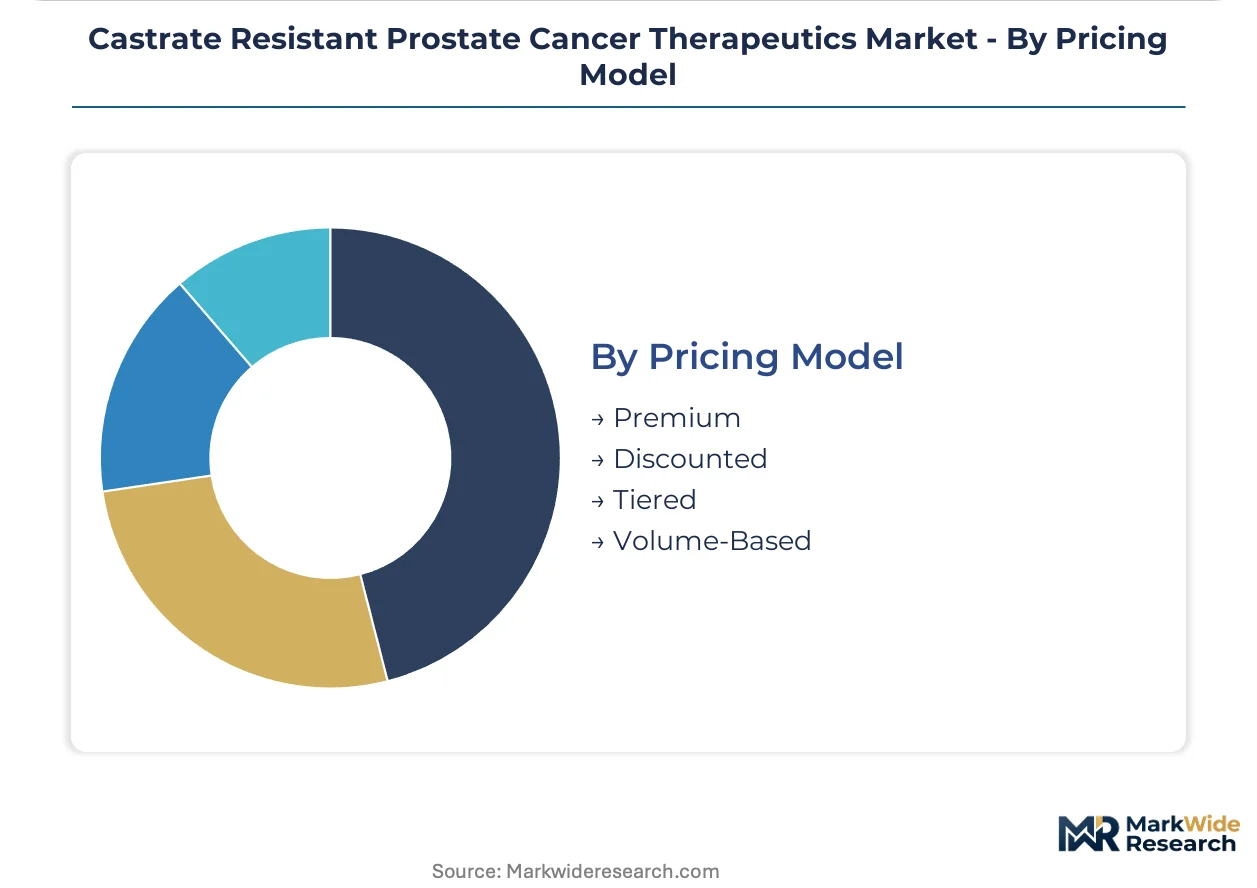
- Premium:Novel mechanisms with biomarker-defined indications and orphan-drug positioning command list-price premiums with limited rebate exposure. PARP inhibitors in BRCA-mutant populations and radioligand therapies exemplify this tier.
- Discounted:Post-exclusivity hormonal agents face IRA Medicare price negotiation provisions, accelerating lifecycle management investments to defend revenue prior to statutory price-setting timelines.
- Tiered:Three-level pricing separates premium formulations from standard and economy alternatives based on indication sequence and combination requirements.
- Volume-Based:Integrated delivery network contracts with performance guarantees.
Premium pricing sustains the highest absolute margins. Volume-based contracts are expanding fastest among institutional purchasers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical exports supply oncology departments across European tertiary centers. Japanese manufacturers ship hormonal agents to North American hospital networks. Swiss radiopharmaceutical developers serve theranostic programs in United States metropolitan markets.
United States
MD Anderson Cancer Center in Houston and Memorial Sloan Kettering in New York anchor adoption of novel hormonal agents and PARP inhibitor protocols. The FDA's accelerated approval pathways compress development timelines for biomarker-defined subpopulations. Reimbursement density concentrates demand within integrated delivery networks capturing longitudinal patient journeys through diagnosis, treatment sequencing, and progression monitoring.
Germany
Heidelberg University Hospital and Charité Berlin drive molecular tumor board adoption for BRCA-mutant stratification. The EMA adaptive pathway framework enables conditional marketing authorization from limited datasets. Bavarian and Baden-Württemberg oncology clusters specialize in companion diagnostic integration with PARP inhibitor deployment.
Japan
Aging demographics and rising prostate cancer incidence expand addressable populations for androgen receptor pathway modulators. The PMDA's Sakigake designation system fast-tracks innovative oncology agents for domestic approval. Tokyo and Osaka urology centers concentrate prescription volume for novel hormonal agents through Astellas Pharma's established franchise infrastructure.
Switzerland
Radioligand theranostic development clusters around Basel and Zurich nuclear medicine capabilities. Swissmedic's streamlined oncology review procedures attract radiopharmaceutical sponsors seeking European market entry. The country's diagnostic imaging heritage supports PSMA-targeted imaging and therapeutic convergence.
United Kingdom
The NHS Cancer Drugs Fund provides managed access agreements for novel CRPC agents pending full NICE appraisal. London's Royal Marsden and Manchester's Christie Hospital anchor academic trial enrollment for next-generation androgen receptor degraders. UK molecular pathology laboratories tighten BRCA and HRR testing infrastructure to support PARP inhibitor eligibility.
Castrate Resistant Prostate Cancer Therapeutics Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented therapeutic categories. Large-cap pharmaceutical conglomerates with integrated oncology franchises dominate hospital formulary access and companion diagnostic bundling. Mid-tier biotechnology specialists concentrate on single-mechanism depth in androgen receptor modulation or DNA damage response pathways. Emerging radiopharmaceutical developers occupy a distinct theranostic niche requiring nuclear medicine infrastructure partnerships.
Within the large-cap integrated tier, Johnson & Johnson and Pfizer exemplify channel-controlling strategies spanning diagnostics through therapy. Astellas Pharma occupies a specialist position in androgen receptor pathway modulation with geographic concentration in Japanese and North American markets. These three anchors illustrate divergent competitive archetypes: franchise integration versus platform extension versus mechanism-specific depth.
| Leading Market Players |
|---|
| AstraZeneca |
| Sanofi |
| Johnson & Johnson |
| Merck |
| Novartis |
| Pfizer |
| Bayer |
| Exelixis |
| Astellas Pharma |
| Others |
Value Chain & Pricing Dynamics
Radiopharmaceutical manufacturing clusters in Basel and northern Switzerland concentrate margin pools downstream in United States hospital outpatient departments, where PSMA-targeted theranostic bundling commands premium positioning against conventional hormonal agents.
Pricing Analysis
Next-generation androgen receptor degraders command substantial premiums over conventional antagonists like enzalutamide, while post-exclusivity abiraterone faces IRA Medicare price negotiation compression. Three-tier pricing structure across premium, standard, and economy levels stratifies by biomarker-defined indication status and companion diagnostic bundling. Pricing pressure stems from biosimilar entry anticipation in hormonal segments and site-of-care migration toward integrated delivery networks. Community oncology clinics exhibit highest price sensitivity; academic medical centers with captive specialty pharmacy arrangements demonstrate lowest sensitivity.
Supply Chain Analysis
Tariff exposure between Switzerland and the United States dominates radioligand supply chain risk profiles, with lutetium-177 production requiring just-in-time isotope logistics from European reactors. Active pharmaceutical ingredient synthesis concentrates in India and China, with formulation and fill-finish operations anchored in Switzerland and the United States. Cold-chain distribution for cellular therapies and radiopharmaceuticals rests on single-source vulnerability at isotope production facilities. Distribution runs through hospital captive specialty pharmacy arrangements and integrated delivery network formulary controls.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Theranostic platform economics are restructuring competitive moats around PSMA imaging-therapy convergence, with interoperability between diagnostic radiology and nuclear medicine departments creating new ecosystem control points.
For Market Incumbents: Harden companion diagnostic bundling through molecular pathology laboratory partnerships, locking in test-treatment workflows before PARP inhibitor commoditization accelerates. Deepen vertical integration into radiopharmaceutical manufacturing infrastructure to secure isotope supply chains against European reactor maintenance cycles. Prioritize formulary control within integrated delivery networks capturing longitudinal patient journeys. For New Entrants and Emerging Players: Build out radioligand therapy capabilities in underserved United States metropolitan markets lacking nuclear medicine infrastructure, targeting community hospital systems seeking site-of-care expansion. Concentrate initial deployment on Japanese urology centers outside Tokyo-Osaka corridors, where Astellas Pharma's franchise coverage thins. Pursue EMA adaptive pathway conditional authorization to compress development-to-commercialization timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across radiopharmaceutical manufacturing, with isotope production infrastructure and cyclotron networks requiring sustained deployment. Long-term viability favors platform players with theranostic integration capabilities rather than single-mechanism developers. Target acquisition archetypes include nuclear medicine infrastructure operators and companion diagnostic commercialization specialists. Watch FDA Project Optimus dose-optimization enforcement patterns as inflection indicator for early-phase program timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | Synchronized CDx deployment with PARP inhibitors tightens test-treatment bundling in BRCA-mutant populations. |
| Radiopharmaceutical Manufacturing Scale-Up | Cyclotron and isotope production investments secure supply chains for PSMA-targeted lutetium-177 therapies. |
| EMA Adaptive Pathway Utilization | Conditional marketing authorization from limited datasets compresses European development timelines for novel mechanisms. |
| Hospital System Partnership | Integrated delivery network formulary control captures longitudinal patient journeys through diagnosis and progression monitoring. |
| Next-Generation AR Degrader Advancement | Proteolysis-targeting chimera development renders conventional competitive antagonism strategies obsolete in AR-amplified populations. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across drug development executives, regulatory affairs leads, formulary directors at integrated delivery networks, and payer access specialists. Secondary validation drew from FDA oncology center filings, EMA adaptive pathway submissions, ClinicalTrials.gov protocol registries, and Medicare Part D formulary databases. Bottom-up patient-flow modeling and top-down revenue reconciliation triangulated market sizing across the analysis window.
Calibration against historical approval timelines and pricing evolution informed projection mechanics throughout the forecast period. Segmentation dimensions spanned treatment line, administration route, biomarker-defined patient population, and regional regulatory cluster. CAGRs were derived from epidemiological incidence projections, therapy sequencing assumptions, and reimbursement density differentials. Forecast inputs incorporated IRA Medicare price negotiation implementation timelines and EMA conditional authorization conversion rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by radiopharmaceutical specialists or next-generation AR degrader developers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Short Bowel Syndrome Market
Specialty Medicine
Nerve Entrapment Syndrome Therapeutics Market
Specialty Medicine
Intestine (Small) Cancer Therapeutics Market
Specialty Medicine
Hypophosphatasia Treatment Market
Specialty Medicine
Autoimmune Hemolytic Anemia Therapeutics Market
Specialty Medicine
Botulism Treatment Market
Specialty Medicine
Geographic Atrophy Market
Specialty Medicine
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Neurodegenerative Disease Market
Specialty Medicine
Nocturnal Polyuria Treatment Market
Specialty Medicine
North America Alopecia Market
Specialty Medicine
Congenital Neutropenia Treatment Market
Specialty Medicine
Herpes Zoster (Shingles) Market
Specialty Medicine
Bipolar Disorders Treatment Market
Specialty Medicine
Strep Throat Treatment Market
Specialty Medicine
Global Dry Eye Syndrome Treatment Market