
 Global Anthocyanin Market | 2026-2036
Global Anthocyanin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anthocyanin Market Intelligence
The adoption of asset-light operational models for sourcing and primary extraction is tilting the competitive landscape toward formulation specialists. This structural change allows companies to prioritize value-added activities like stability enhancement. Chr. Hansen Holding A/S leverages its deep expertise in bioscience to develop highly stable color solutions for the dairy sector. Sensient Technologies Corporation differentiates through its broad portfolio and extensive global manufacturing footprint, serving diverse end-user industries.
Anthocyanins are a class of water-soluble flavonoid pigments responsible for the red, purple, and blue colors in many fruits, vegetables, and flowers. Their primary commercial function is as a natural colorant, offering a clean-label alternative to synthetic dyes in various consumer products. Extract powder forms dominate the product landscape due to superior shelf stability and ease of transport compared to liquid concentrates. The food & beverage application remains the largest consumer, while the nutraceuticals segment represents the fastest-growing opportunity for these antioxidant-rich compounds.
Regulatory frameworks from the European Food Safety Authority (EFSA) and the U.S. Food and Drug Administration (FDA) govern approved sources and usage levels for anthocyanins as color additives. In parallel, China's GB standards for food additives impose strict quality and purity criteria, influencing production. Future competitiveness depends on securing stable raw material supply chains and advancing extraction technologies to improve color stability and vibrancy.
Market Dynamics
The central dynamic shaping the anthocyanin market is the food and beverage industry's reformulation away from synthetic colorants. This shift, driven by consumer demand for clean-label ingredients, creates a powerful commercial pull for natural alternatives with verifiable health benefits.
Growth Catalysts
- Regulatory Scrutiny:Stricter reviews of synthetic food dyes by regulatory bodies like the European Food Safety Authority (EFSA) compel food manufacturers to seek compliant, natural-source colorants to maintain market access.
- Nutraceutical Demand:The expansion of the nutraceuticals sector leverages anthocyanins not just for color but for their antioxidant properties, creating new product applications in dietary supplements and functional foods.
- Raw Material Concentration:China's agricultural capacity for anthocyanin-rich crops, such as black rice and purple sweet potato, provides a scalable and cost-effective raw material base that supports global supply.
Market Restraints
- Technical Instability:Anthocyanin pigments exhibit inherent instability in response to pH shifts, heat, and light, which limits their use in certain food processing methods and transparent packaging formats.
- Agricultural Volatility:Supply of key raw materials like elderberries and black carrots is subject to seasonal and climatic variations, leading to unpredictable input costs and potential sourcing disruptions.
- Cost Disparity:The higher production cost of natural anthocyanin extracts compared to synthetic alternatives like Allura Red AC (Red 40) remains a significant barrier to adoption in price-sensitive consumer goods categories.
Strategic Opportunities
- Cosmetics Formulation:Untapped potential exists in the personal care and cosmetics industry for using anthocyanins as natural colorants in products like lip tints, blushes, and hair dyes, aligning with green beauty trends.
- Encapsulation Technologies:Advances in microencapsulation and nanoencapsulation offer a pathway to improve the stability and extend the shelf life of anthocyanins, unlocking applications in baked goods and shelf-stable beverages.
- Emerging Market Penetration:Rising disposable incomes and a growing middle class in countries like India and Brazil are fueling demand for processed foods, creating new markets for clean-label ingredients.
Industry Challenges
- Color Standardization:Achieving consistent color expression and intensity across different batches of raw materials from varied agricultural sources presents a significant quality control challenge for global food and beverage brands.
- Regulatory Divergence:Navigating the fragmented landscape of international food additive regulations, including different approved sources and usage levels between the US FDA and China's GB standards, complicates global product rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anthocyanin Market |
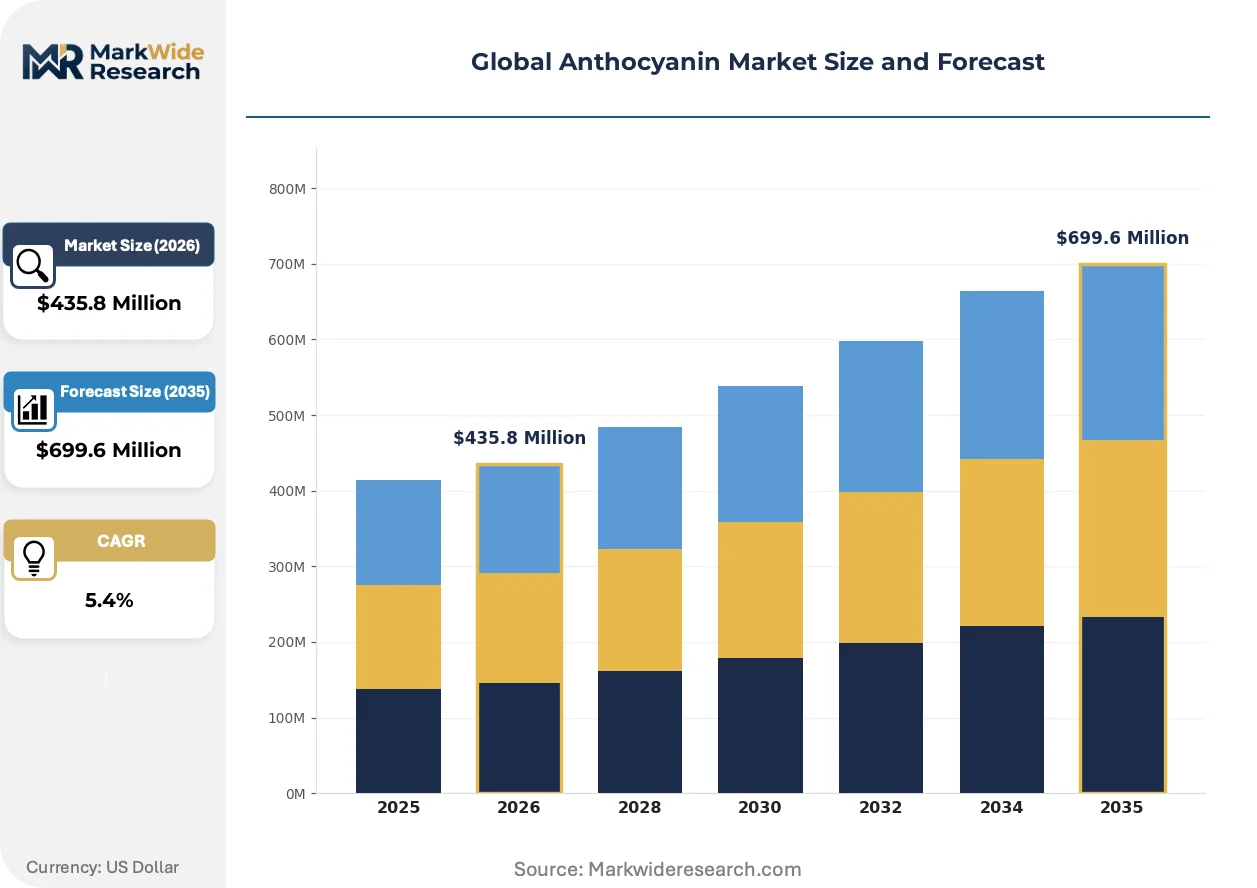
| Market Size in 2026 | $435.8 Million |
| Market Size in 2035 | $699.6 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extract Powder, Liquid Concentrate, Spray Dry, Gel Form Application: Food & Beverage, Cosmetics, Nutraceuticals, Natural Dye End User Industry: Pharmaceuticals, Dietary Supplements, Personal Care, Animal Nutrition Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers, Exporters |
| Companies Covered | Sensient Technologies Corporation, Chr. Hansen Holding A/S, Symrise AG, Archer Daniels Midland Company, Givaudan, DDW The Color House, Naturex S.A., Kalsec Inc., GNT Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anthocyanin Market Strategic Shifts & Innovations
Product development is evolving beyond simple coloration toward functional benefits. Technology and formulation science now concentrate on enhancing pigment stability and bioavailability, transforming anthocyanins from a basic commodity into a value-added functional ingredient for health-conscious consumers.
Advanced extraction techniques are fundamentally altering the purity and yield achievable from raw plant materials. Methods like supercritical CO2 and enzyme-assisted extraction allow for the isolation of anthocyanins without harsh chemical solvents. Nutraceutical and premium beverage manufacturers are rapidly adopting these processes to ensure a cleaner final product, and this adoption is rendering obsolete older, solvent-based methods that introduced impurities and degraded the compounds' antioxidant capacity.
European Union food policy continues to reinforce the clean-label movement, influencing global formulation strategies. The continuous re-evaluation of authorized food additives by the EFSA places persistent pressure on manufacturers to justify the use of synthetic ingredients. This regulatory environment accelerates the reformulation of products, particularly within the dairy, confectionery, and beverage sectors, which are substituting synthetic colors to meet consumer expectations for simple and understandable ingredient lists.
Consumer purchasing criteria are shifting from a singular focus on color vibrancy to a more holistic evaluation of an ingredient's origin and functional properties. This change disrupts traditional commodity sales models, creating an advantage for suppliers who offer transparent sourcing, traceability, and scientific data supporting the antioxidant benefits of their extracts. This demand for a "source story" is most pronounced in the North American and European functional food markets, where brand differentiation often depends on ingredient provenance.
Global Anthocyanin Market Segmentation
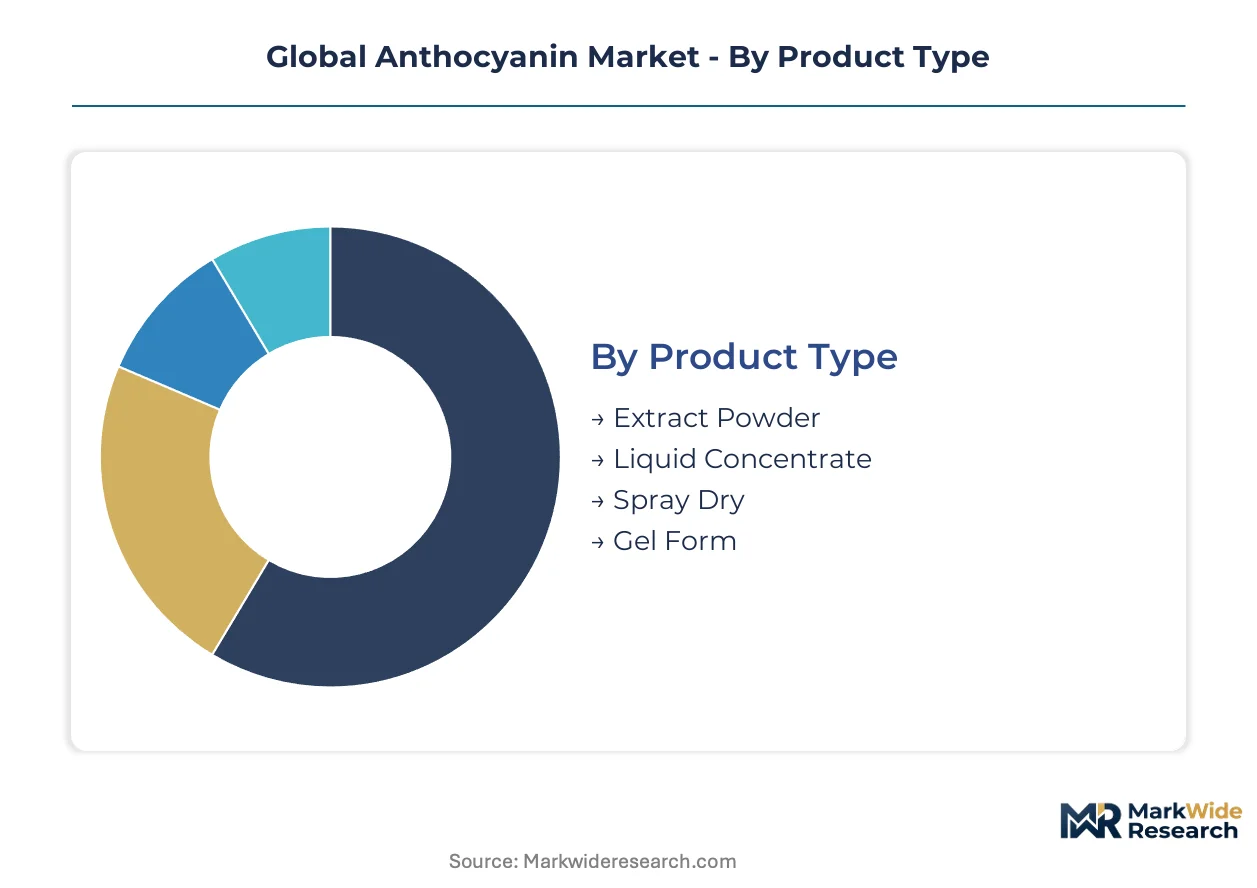
Market segmentation provides a structured view of the anthocyanin landscape, detailing how product forms, end-use applications, and distribution networks shape commercial activity. Understanding these distinct segments helps manufacturers align product development and market penetration strategies with specific demand drivers. Each category reflects unique consumer needs and regulatory considerations, influencing market dynamics.
Product Type:
The physical state of anthocyanin products dictates their handling, stability, and integration into various formulations.
- Extract Powder:This dominant product form consists of dried, concentrated anthocyanin pigments, valued for its superior shelf stability and ease of transport. Demand concentrates in the global food and beverage sector for dry mix applications and encapsulation.
- Liquid Concentrate:These highly pigmented solutions offer convenience in liquid formulations, though they typically exhibit reduced stability compared to powder forms. The beverage industry, particularly in North America and Europe, utilizes liquid concentrates for vibrant color in drinks.
- Spray Dry:Spray-dried anthocyanins offer improved dispersibility and controlled release properties, often used to protect sensitive compounds. This form finds application in functional food and nutraceutical products requiring precise ingredient delivery.
- Gel Form:Gel-based anthocyanin products provide unique textural properties and controlled release, suitable for specific confectionery and pharmaceutical applications. The pharmaceutical industry explores gel forms for targeted drug delivery systems.
Extract Powder commands the established base. The steepest expansion runs through Liquid Concentrate.
Application:
The utility of anthocyanins is delineated by their primary function within consumer products, driven by color and functional attributes.
- Food & Beverage:This segment represents the largest consumer of anthocyanins, leveraging them as natural colorants in clean-label products. Demand is particularly strong in the dairy, confectionery, and beverage sectors across Europe and North America.
- Nutraceuticals:Anthocyanins are valued for their antioxidant properties in this rapidly expanding sector, serving as active ingredients in dietary supplements and functional foods. Asian markets, especially China, show strong demand for antioxidant-rich nutraceuticals.
- Cosmetics:This segment utilizes anthocyanins as natural colorants in personal care products like lip tints, blushes, and hair dyes. Green beauty trends in Europe and the US drive product innovation in this area.
- Natural Dye:Anthocyanins serve as natural dyes for textiles and other industrial applications, offering an eco-friendly alternative to synthetic pigments. Small-scale artisanal producers and specialty manufacturers employ these dyes.
Consumer product integration defines the bulk of demand. Specialized health applications are gaining traction.
End User Industry:
Customer type segmentation reveals distinct purchasing behaviors and regulatory requirements across different industrial sectors.
- Dietary Supplements:This industry integrates anthocyanins for their health-promoting properties, particularly their antioxidant capacity, into capsules, tablets, and powders. Manufacturers in the US and Germany formulate supplements targeting immune support and vision health.
- Personal Care:The personal care sector incorporates anthocyanins as natural colorants and beneficial compounds in skincare, haircare, and cosmetic formulations. Brands in France and Japan prioritize natural ingredients for their premium product lines.
- Pharmaceuticals:Anthocyanins are explored for their potential therapeutic effects in drug development, including anti-inflammatory and cardiovascular benefits. Research institutions and pharmaceutical companies in Switzerland investigate novel delivery methods.
- Animal Nutrition:This industry uses anthocyanins as natural feed additives to improve animal health, enhance product quality, and provide natural coloration in certain animal products. The livestock sector in Brazil utilizes natural supplements to boost animal welfare.
Mainstream wellness products drive substantial volume. Targeted health solutions expand product diversity.
Distribution Channel:
The pathway to market is shaped by diverse distribution models, influencing market reach and pricing strategies.
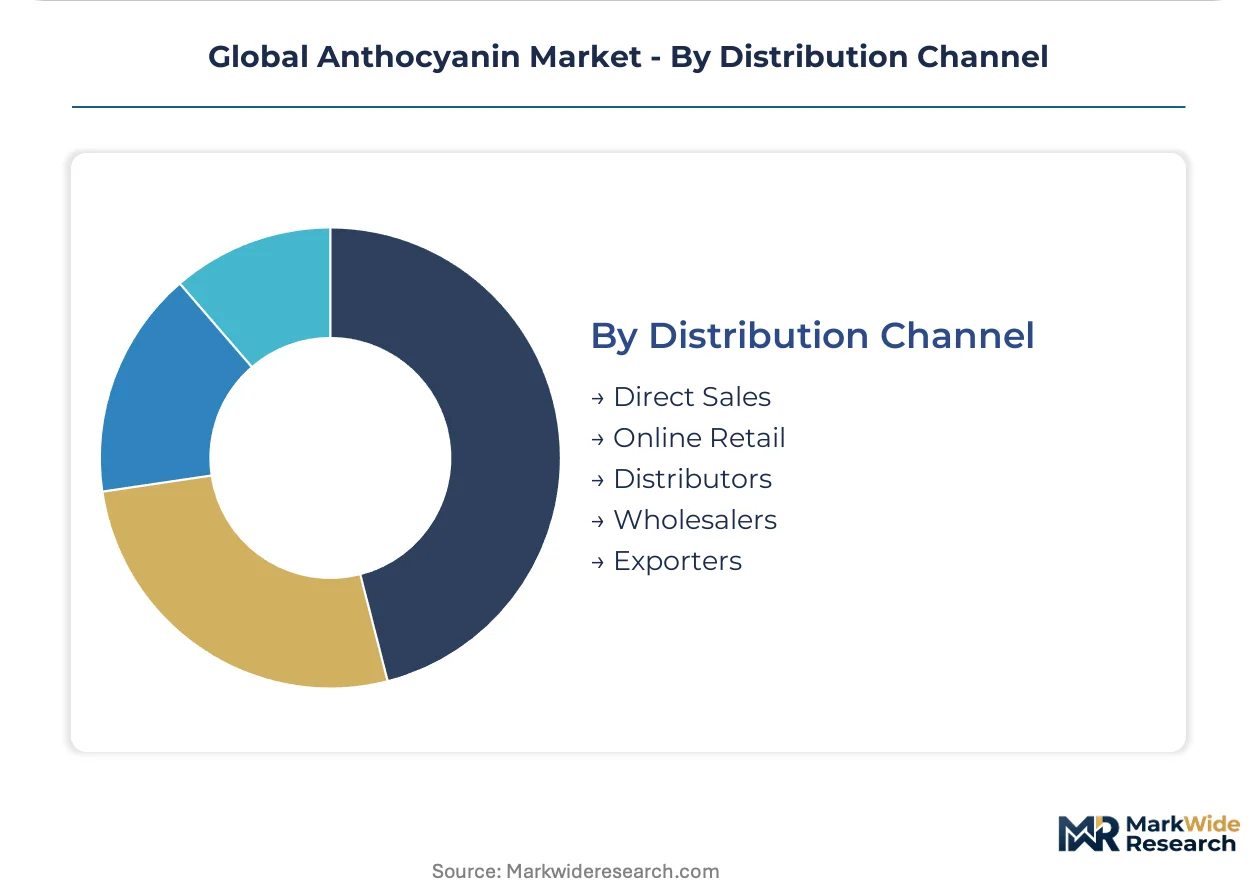
- Direct Sales:Manufacturers engage in direct sales to large industrial clients, ensuring bulk supply and customized product specifications. Key food and beverage corporations in China often procure directly from anthocyanin producers.
- Distributors:Distributors serve as intermediaries, providing regional market access and logistical support to a wide range of smaller manufacturers. European distributors manage complex supply chains for specialty ingredient companies.
- Online Retail:E-commerce platforms facilitate the sale of anthocyanin products, particularly for smaller businesses and niche markets. Consumers in North America increasingly purchase dietary supplements containing anthocyanins through online channels.
- Wholesalers:Wholesalers purchase large volumes from manufacturers and distribute to retailers or smaller businesses, offering cost efficiencies. Asian wholesalers play a crucial role in supplying traditional medicine markets.
- Exporters:Exporters manage international logistics and regulatory compliance for cross-border trade of anthocyanin products. Companies in South America export raw materials and processed extracts to global markets.
Established intermediaries facilitate broad market access. Digital platforms offer emerging sales avenues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry exists between regions with abundant raw material sources and those with high consumer demand for premium, clean-label products. China, with its cost-effective raw material base, holds a significant position. Conversely, markets like the United States and Germany drive demand for value-added, stable anthocyanin formulations.
China
China's robust agricultural capacity for crops like purple sweet potato drives raw material supply. The country's GB standards for food additives ensure strict quality control for domestic and export products. Manufacturing hubs around the Yangtze River Delta concentrate on large-scale extraction and processing facilities.
United States
Consumer demand for clean-label ingredients and nutraceuticals fuels anthocyanin consumption in the United States. The Food and Drug Administration (FDA) regulates approved sources and usage levels for color additives. Research clusters in California explore advanced encapsulation technologies for enhanced stability.
Germany
European consumers prioritize natural colorants in dairy and confectionery products, boosting demand in Germany. The European Food Safety Authority (EFSA) continuously reviews food additives, favoring natural-source alternatives. Specialized ingredient manufacturers in North Rhine-Westphalia develop sophisticated anthocyanin formulations.
Brazil
Growing processed food markets and an expanding middle class increase anthocyanin demand in Brazil. ANVISA, the national health surveillance agency, regulates food and supplement ingredients. Agricultural regions in Minas Gerais focus on cultivating anthocyanin-rich fruits for local and export markets.
India
The expanding nutraceuticals sector and a preference for natural ingredients drive anthocyanin usage in India. The Food Safety and Standards Authority of India (FSSAI) sets standards for natural food additives. Pharmaceutical and supplement manufacturers in Maharashtra integrate anthocyanins into health products.
Global Anthocyanin Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, focusing on raw material extraction and stability enhancement. The market exhibits a tiered structure, with large ingredient houses offering broad portfolios alongside niche players specializing in advanced formulations. Formulation specialists gain competitive advantage through bioscience expertise and stability enhancement. Companies pursue strategic partnerships and portfolio diversification to serve diverse end-user industries.
On the value-added formulation tier, Sensient Technologies Corporation occupies a position with its broad portfolio and extensive global manufacturing footprint, serving diverse end-user industries. This US-based entity differentiates through its capability to provide customized color solutions across multiple application areas. Chr. Hansen Holding A/S, a Danish bioscience company, exemplifies expertise in developing highly stable color solutions, particularly for demanding applications like dairy products. Givaudan, a Swiss-based flavor and fragrance company, further anchors this segment by integrating natural colorants into its comprehensive ingredient offerings, leveraging its established expertise in taste and well-being solutions globally.
| Leading Market Players |
|---|
| Sensient Technologies Corporation |
| Chr. Hansen Holding A/S |
| Symrise AG |
| Archer Daniels Midland Company |
| Givaudan |
| DDW The Color House |
| Naturex S.A. |
| Kalsec Inc. |
| GNT Group |
| Others |
Cost & Logistics Intelligence
China's concentration of raw material production significantly influences global anthocyanin pricing, as cost-effective supply from this region underpins margin structures for downstream formulation specialists. This upstream dominance provides a competitive advantage for Chinese producers, impacting pricing power across the entire value chain.
Pricing Analysis
Configured-to-order solutions command a premium over standard extract powders, reflecting the value of stability enhancement and customized formulations. The dominant pricing model is a hybrid of contract-based long-term offtake for large volumes and transactional pricing for spot purchases. Price differentiation stems from the purity grade of the extract and the level of customization required for specific applications. Pricing pressure originates from the higher production cost of natural anthocyanins compared to synthetic dyes like Allura Red AC. Nutraceutical manufacturers and premium food brands exhibit lower price sensitivity, prioritizing quality and functional benefits.
Supply Chain Analysis
Upstream feedstock, primarily from anthocyanin-rich crops, anchors the global supply chain. Geographic supply concentrates heavily in China, which cultivates purple sweet potato and black rice, and in regions like Brazil for various fruits. Raw material dependencies include elderberries and black carrots, whose availability fluctuates seasonally. Agricultural volatility represents a significant structural risk, leading to unpredictable input costs. Distribution runs through a dual model, with direct sales to large industrial clients and regional distributors serving a broader base of smaller manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market signals a power shift towards ingredient suppliers capable of delivering stable, clean-label anthocyanin solutions, driven by consolidating consumer demand for natural products.
For Market Incumbents: Entrench market position by accelerating investment in bioscience research to enhance pigment stability and bioavailability. Secure long-term, diversified raw material sourcing contracts to mitigate agricultural volatility and ensure supply consistency. This strategy counters the threat of technical instability and positions companies against emerging synthetic alternatives. Focus R&D on advanced encapsulation technologies to broaden application suitability, particularly in challenging food matrices.
For New Entrants and Emerging Players: Establish a beachhead in niche, high-value segments like cosmetics formulation or premium nutraceuticals. The personal care industry, driven by green beauty trends, offers a penetrable segment for innovative natural colorants. A go-to-market angle focusing on advanced, solvent-free extraction techniques and transparent sourcing provides a strong differentiation point, appealing to health-conscious consumers and ethical brands.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-sized ingredient firms possessing proprietary stability-enhancing technologies or unique raw material processing capabilities. Long-term viability rests on the sustained global shift towards natural and functional ingredients. Target acquisition archetypes include specialized formulation houses with strong intellectual property in encapsulation or advanced extraction. The signal to watch is the successful commercialization of novel, highly stable anthocyanin products in demanding applications like baked goods.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Extraction Technology Deployment | Enhances purity and yield, reducing reliance on harsh chemical solvents in production. |
| Encapsulation Technology Investment | Improves pigment stability for broader food and beverage applications, extending shelf life. |
| Long-term Raw Material Sourcing Agreements | Mitigates agricultural volatility and ensures supply consistency for manufacturers. |
| Cosmetics Portfolio Expansion | Captures demand from the green beauty trend in personal care and beauty products. |
| Emerging Market Distribution Partnerships | Accesses new consumer bases in regions like India and Brazil for clean-label ingredients. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to establish a comprehensive market perspective. Primary interviews with food scientists, procurement managers, regulatory affairs specialists, and R&D directors provided qualitative insights. This primary data was then cross-referenced with secondary sources, including European Food Safety Authority (EFSA) reports, U.S. Food and Drug Administration (FDA) guidance documents, and China's GB standards for food additives, ensuring robust data triangulation.
The calibration approach integrated historical market performance with projected growth drivers across the analysis window. Segmentation dimensions modeled included product type, application, end-user industry, and regional consumption patterns. Compound annual growth rates were derived from a synthesis of historical trends, identified market drivers, and expert projections. Key industry-specific forecast inputs included anticipated regulatory changes concerning food additives and evolving consumer clean-label preferences.
Stress conditions across agricultural supply disruptions and regulatory shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding technological advancements in extraction and stabilization. Cross-checking against national food safety agency reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Liquid Flavors Market
Flavorings and Food Additives
Licorice Extract Market
Flavorings and Food Additives
Global Chicory Market
Flavorings and Food Additives
Tangerine Essential Oil Market
Flavorings and Food Additives
Coloring Foodstuffs Market
Flavorings and Food Additives
Jujube Extracts Market
Flavorings and Food Additives
Smoked Condensates Market
Flavorings and Food Additives
South America Food Flavor and Enhancer Market
Flavorings and Food Additives
Food Texturizers Market
Flavorings and Food Additives
FTNF Flavors Market
Flavorings and Food Additives
Natural Acerola Cherry Extract Market
Flavorings and Food Additives
North America Food Flavor Market
Flavorings and Food Additives
Food-Grade Gellan Gum Market
Flavorings and Food Additives
Feed Flavors, Sweeteners and Natural Enhancers Market
Flavorings and Food Additives
Edible Food Paints Market
Flavorings and Food Additives
Poria Cocos Extract Market