
 Liquid Flavors Market | 2026-2036
Liquid Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Flavors Market Insights
India is tilting toward expanded liquid flavor production as domestic food manufacturers localize supply chains. Givaudan leverages its botanical extraction expertise to serve beverage and dairy clients across South Asia. Kerry Group plc anchors its position through integrated taste and nutrition solutions for food manufacturers. Firmenich SA differentiates via proprietary encapsulation technologies that extend flavor stability in heat-processed applications.
Liquid flavors are concentrated aromatic preparations, typically comprising volatile organic compounds suspended in propylene glycol, ethanol, or triacetin carriers, manufactured through distillation, solvent extraction, or biotechnological fermentation to impart taste and odor to finished food and beverage products. Natural flavors command premium positioning as clean-label formulations displace artificial alternatives in beverage and dairy applications. Synthetic flavors retain cost advantages in confectionery and mass-market bakery segments where heat stability and reproducibility outweigh provenance claims. Concentrates and extracts dominate formulation demand, with concentrates capturing margin pools in high-volume carbonated soft drink supply contracts.
The FDA governs flavor ingredient safety through its food additive and GRAS frameworks, while the EPA regulates solvent emissions from extraction facilities, pushing manufacturers toward supercritical CO2 and enzymatic processes. The EU's REACH and flavoring regulation frameworks impose substance registration and purity thresholds that constrain market access for non-compliant suppliers. Stakeholders must monitor evolving biotech-derived flavor classifications as regulators in the United States and Europe deliberate novel food status for precision-fermented aromatic molecules.
Market Dynamics
Beverage manufacturers are consolidating liquid flavor procurement around solvent-free extraction platforms as the EU F-Gas Regulation and EPA emission mandates phase out conventional solvent-based processes, compressing supplier margins while rewarding biotech-fermentation capabilities.
Growth Catalysts
- Clean-label beverage mandates:Carbonated and functional drink portfolios across Germany, France, and Italy now require natural flavor declarations, pulling demand toward botanical extraction systems.
- REACH substance registration thresholds:The EU flavoring regulation framework is forcing non-compliant suppliers to exit, concentrating volume among registered producers with verified purity documentation.
- Supercritical CO2 extraction scale-up:Equipment manufacturers in Frankfurt's chemical corridor are deploying commercial-scale systems that eliminate solvent residue concerns for dairy applications.
Market Restraints
- Propylene glycol price volatility:Carrier solvent costs fluctuate with petrochemical feedstock markets, squeezing formulation margins for mid-tier flavor houses.
- Botanical raw material concentration:Vanilla, citrus, and spice sourcing clusters in Madagascar, Kerala, and Indonesia create climate and geopolitical exposure.
- Heat stability limitations:Natural flavor compounds degrade above 85°C, restricting deployment in UHT dairy and baked goods without encapsulation investment.
Strategic Opportunities
- Precision-fermented aromatic molecules:Biotech-derived flavors await novel food status rulings from FDA and EFSA, opening a regulatory pathway for lab-grown alternatives.
- India domestic supply chain localization:Food manufacturers in Mumbai and Bangalore are qualifying local extraction capacity to reduce import dependence.
- Direct-to-manufacturer digital platforms:Flavor houses are bypassing traditional distribution layers through proprietary customer portals with formulation tools.
Industry Challenges
- Flavor chemist talent scarcity:Universities in Germany and Switzerland produce fewer graduates with combined organic chemistry and sensory science training than replacement demand requires.
- Encapsulation equipment capex intensity:Spray-drying and coacervation lines require 18-24 month payback periods that strain mid-capitalization producers.
- GRAS self-determination documentation:FDA notification timelines for new natural flavor substances extend 12-18 months, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Flavors Market |
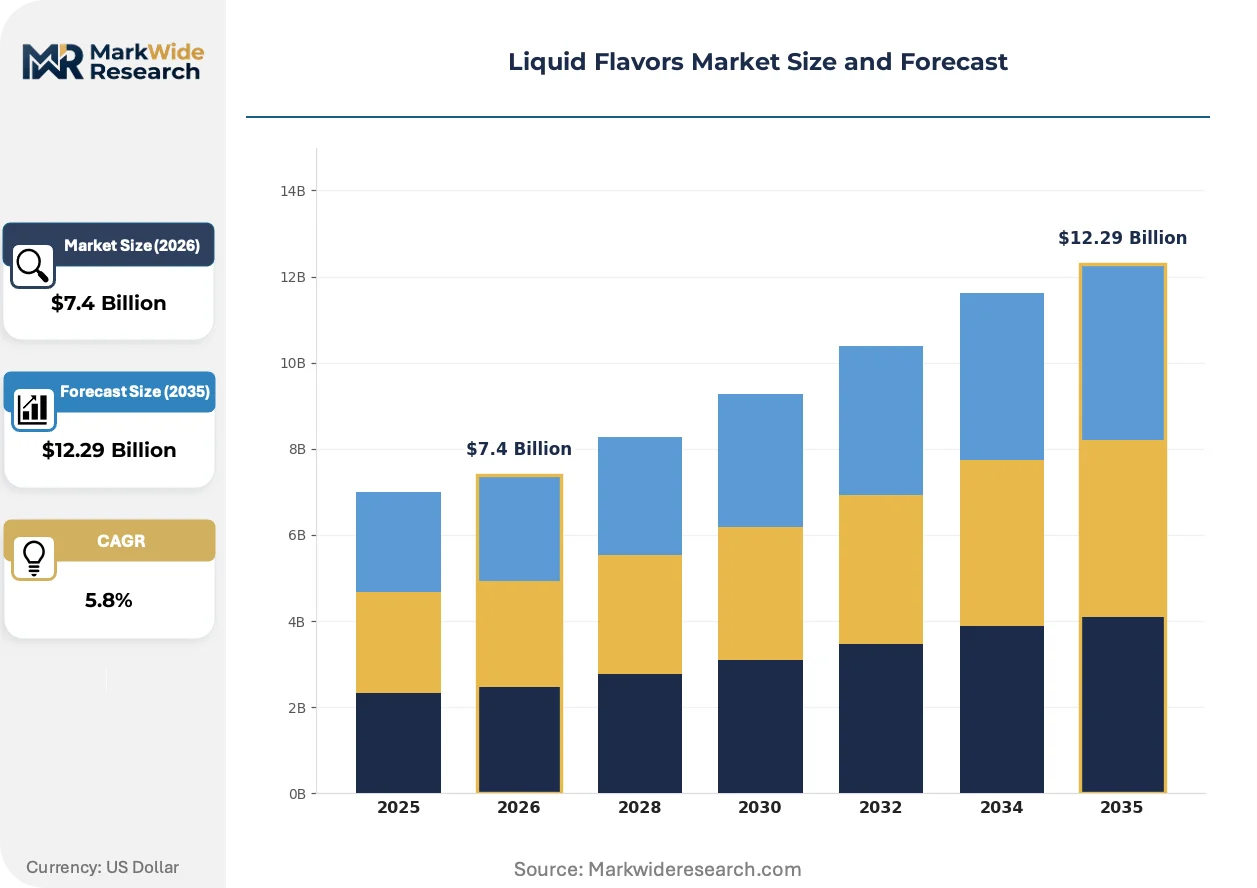
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Organic Flavors, Synthetic Flavors Application: Beverages, Bakery, Dairy, Confectionery Formulation: Concentrates, Extracts, Solutions, Powders End User: Food Manufacturers, Beverage Companies, Restaurants, Home Consumers |
| Companies Covered | Givaudan, International Flavors & Fragrances Inc., Firmenich SA, Kerry Group plc, Symrise AG, Takasago International Corporation, Sensient Technologies Corporation, Gold Coast Ingredients, Nature's Flavors, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Flavors Market Trends and Innovations
Flavor manufacturing is bifurcating between legacy solvent extraction and fermentation-derived platforms, with regulatory chemistry defining competitive positioning more than sensory performance alone.
Enzymatic biotransformation is migrating from pilot-scale novelty to commercial production for terpene and ester synthesis. Beverage multinationals in North America and Western Europe are qualifying enzymatic outputs for clean-label claims. This shift is compressing demand for petrochemical-derived synthetic precursors while expanding contract manufacturing relationships with industrial biotechnology firms.
REACH authorization requirements for flavoring substances are tightening purity thresholds for residual solvents and process contaminants. Manufacturers must now submit full analytical dossiers for substances above 10 tonnes annual volume. Carbonated soft drink and alcoholic beverage categories face the steepest compliance burden as they utilize the highest concentration of complex flavor blends.
Food manufacturers are unbundling flavor procurement from legacy full-service ingredient distributors. Direct technical partnerships with flavor houses now include co-development agreements with exclusive supply terms. This pattern is most pronounced in Germany, where dairy and confectionery producers have consolidated supplier panels from twelve to four primary partners over the past five years.
Liquid Flavors Market Segmentation
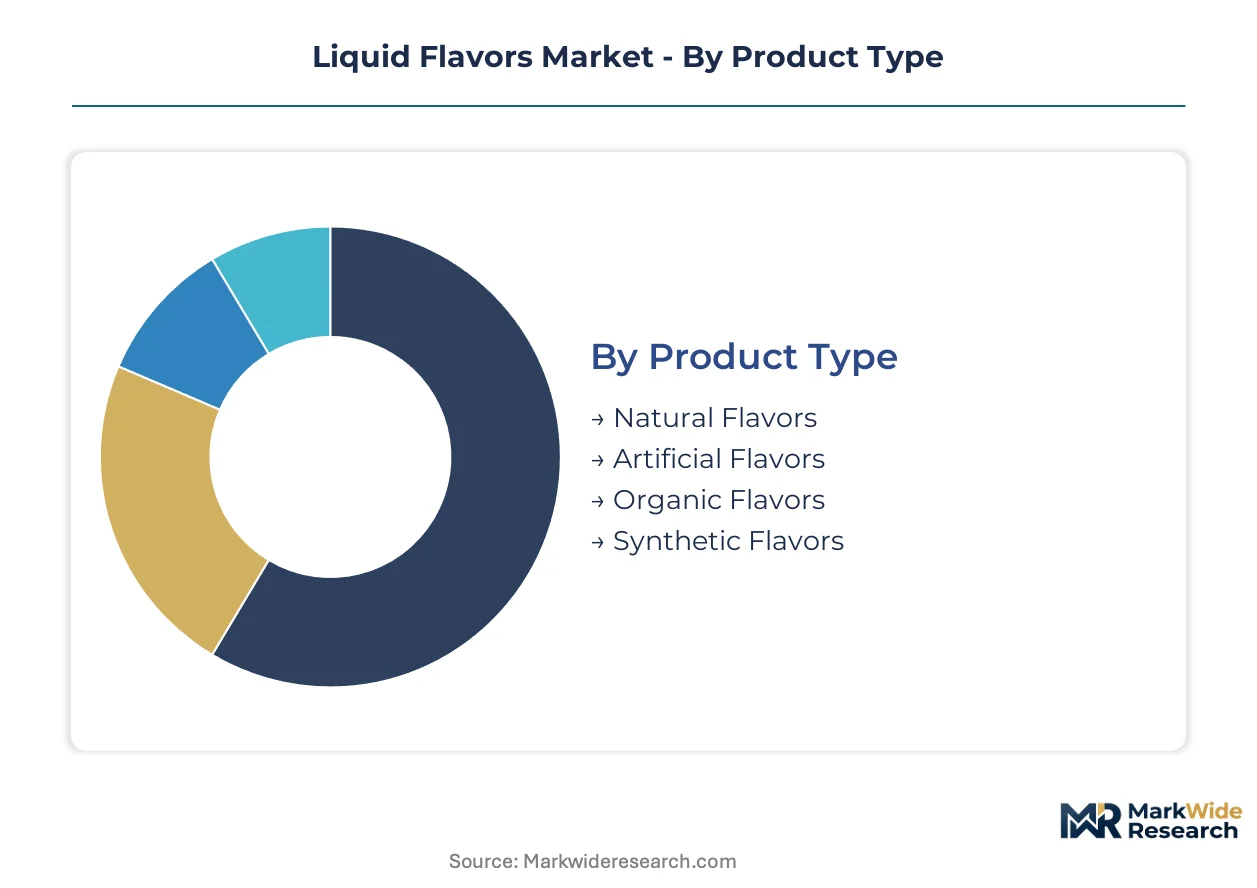
Liquid flavor segmentation determines procurement strategy, regulatory pathway, and margin structure for buyers and suppliers alike. Technical specifications vary sharply across natural versus synthetic platforms, while application requirements dictate heat stability, carrier solvent, and concentration thresholds.
Product Type:
After-sales service intensity runs highest for natural flavor contracts, where botanical sourcing volatility demands ongoing technical support and reformulation assistance.
- Natural Flavors:Volatile organic compounds extracted through distillation, solvent extraction, or enzymatic processes from plant and animal sources. Beverage manufacturers in Germany and France now mandate natural declarations for carbonated portfolios, pulling procurement toward botanical extraction systems with full traceability documentation.
- Synthetic Flavors:Petrochemical-derived aromatic molecules engineered for reproducibility and heat stability. Confectionery and mass-market bakery segments in the United States favor these formulations where cost control outweighs provenance claims.
- Artificial Flavors:Chemically synthesized compounds that mimic natural taste profiles without botanical origin. Food service distributors specify these for standardized menu applications requiring batch-to-batch consistency.
- Organic Flavors:USDA- and EU-certified organic botanical extracts with restricted processing aids. Premium dairy processors in Switzerland and Austria qualify these for clean-label positioning in retail yogurt and ice cream.
By volume, Synthetic Flavors leads. By growth pace, Natural Flavors is gaining share fastest as clean-label mandates tighten across Western Europe.
Application:
Margin structure varies by thermal processing intensity, with UHT dairy and baked goods demanding encapsulation investments that beverage applications avoid.
- Beverages:Carbonated soft drinks, functional waters, and alcoholic beverages utilize high-volume liquid concentrates with ethanol or propylene glycol carriers. The EU F-Gas Regulation and EPA emission mandates are compressing demand for solvent-based extraction in favor of supercritical CO2 systems.
- Dairy:Milk, yogurt, and ice cream applications require heat-stable formulations surviving pasteurization and UHT treatment. Encapsulation technologies from Firmenich SA and Givaudan extend flavor stability above 85°C degradation thresholds.
- Bakery:Bread, pastry, and cake applications favor oil-soluble flavors with high-temperature resistance. Mid-tier producers face margin pressure from propylene glycol price volatility linked to petrochemical feedstock markets.
- Confectionery:Chocolate, candy, and chewing gum formulations prioritize reproducibility and cost efficiency over natural claims. Synthetic terpenes and esters dominate procurement for mass-market segments.
By revenue contribution, Beverages dominates. By formulation complexity, Dairy commands premium positioning.
Formulation:
Supply concentration clusters around concentrates for high-volume contracts, while extracts serve niche botanical positioning.
- Concentrates:Highly concentrated aromatic preparations diluted at point-of-use, typically 50-100x strength. Carbonated soft drink supply contracts in Germany and the United States capture margin pools through multi-year concentrate agreements with exclusive terms.
- Extracts:Direct botanical extractions retaining full volatile compound profiles. Craft beverage producers and premium dairy clients specify these for authentic taste positioning and clean-label compliance.
- Solutions:Pre-diluted liquid flavors ready for direct incorporation. Small and mid-sized food manufacturers favor these to reduce formulation error and inventory complexity.
- Powders:Spray-dried or encapsulated flavors for dry mix applications. Bakery and confectionery segments specify these for extended shelf stability and reduced moisture sensitivity.
By procurement volume, Concentrates leads. By expansion trajectory, Extracts climbs fastest as botanical authenticity claims proliferate.
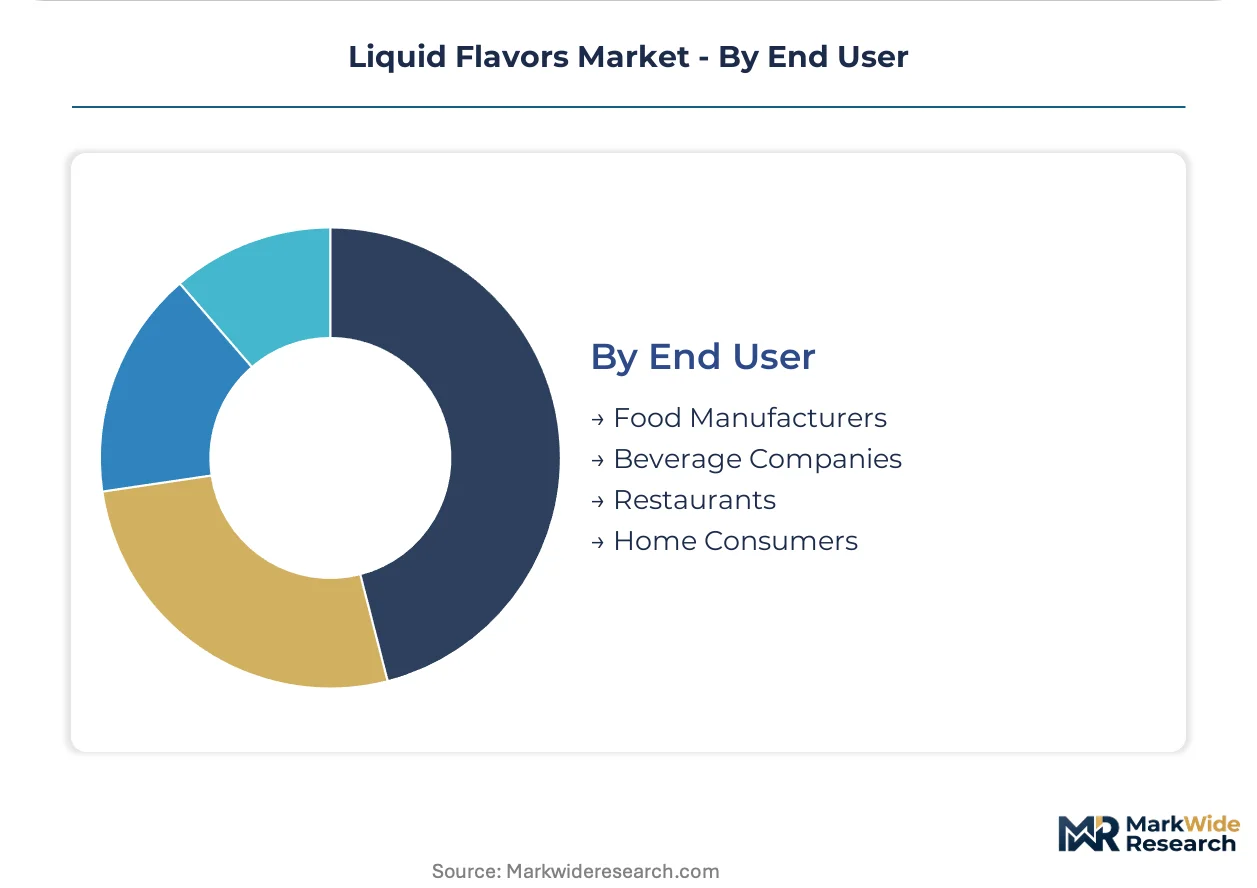
End User:
Technical partnership depth separates food manufacturers from beverage companies, with co-development agreements concentrated among the largest processors.
- Food Manufacturers:Integrated processors of bakery, dairy, and confectionery products with in-house R&D capabilities. These buyers unbundle procurement from legacy distributors, consolidating supplier panels from twelve to four primary partners over the past five years.
- Beverage Companies:Carbonated, functional, and alcoholic drink producers with high-volume, low-SKU concentration. Direct technical partnerships now include exclusive supply terms and co-development agreements for proprietary flavor systems.
- Restaurants:Food service chains and independent operators sourcing through distributors. Standardized menu requirements favor artificial flavors with batch consistency over botanical variation.
- Home Consumers:Retail purchasers of small-format flavor extracts and essences. E-commerce platforms and specialty retailers serve this fragment with limited technical support requirements.
By absolute volume, Beverage Companies dominates procurement. By supplier margin capture, Food Manufacturers commands premium positioning through integrated service relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes liquid flavors primarily through high-specification beverage and dairy applications requiring REACH-compliant documentation, while India sources the same inputs for cost-sensitive mass-market localization with lighter regulatory overhead.
Germany
Carbonated soft drink manufacturers in Frankfurt's chemical corridor mandate supercritical CO2 extraction systems for clean-label compliance. The EU F-Gas Regulation phases out solvent-based processes by 2030, forcing extraction facility upgrades. Flavor houses cluster around Hesse and Baden-Württemberg to serve pan-European dairy clients with full traceability documentation.
United States
Beverage multinationals in the Midwest and Southeast qualify precision-fermented aromatic molecules for novel GRAS determinations. FDA notification timelines extend 12-18 months for new natural flavor substances, delaying product launches. Propylene glycol carrier costs fluctuate with Gulf Coast petrochemical feedstock markets, squeezing mid-tier formulation margins.
India
Food manufacturers in Mumbai and Bangalore localize supply chains to reduce import dependence on European flavor houses. FSSAI purity standards for solvent residues remain less stringent than REACH thresholds, enabling faster qualification of domestic extraction capacity. Botanical sourcing clusters in Kerala supply vanilla and spice raw materials to regional processors.
Switzerland
Premium dairy processors qualify USDA- and EU-certified organic flavor extracts for retail yogurt and ice cream positioning. Swissmedic maintains alignment with EFSA novel food classifications for biotech-derived molecules. The Basel-Zurich corridor hosts specialized encapsulation technology providers serving heat-sensitive UHT applications.
China
Carbonated beverage producers in the Yangtze River Delta scale enzymatic biotransformation for terpene and ester synthesis. SAMR flavor additive standards tighten documentation requirements for imported extraction solvents. Domestic equipment manufacturers deploy commercial-scale supercritical systems to displace legacy petrochemical-derived synthetic precursors.
Liquid Flavors Market Competitive Landscape
Capability concentration sits with integrated taste-and-nutrition specialists; scale advantage sits with diversified fragrance-flavor conglomerates. The vendor base organizes around three tiers: global diversified houses with fermentation platforms, regional specialists with botanical extraction expertise, and mid-cap producers competing on formulation service intensity. Consolidation pressure favors M&A for biotech capabilities and direct-to-manufacturer digital platform investments.
Within the integrated solutions tier, Kerry Group plc and Givaudan exemplify divergent strategic positions. Kerry anchors integrated taste and nutrition service relationships with food manufacturers seeking bundled ingredient procurement. Givaudan occupies a position emphasizing botanical extraction depth for beverage and dairy clients across South Asia. Firmenich SA sits within the technology-differentiated segment, its proprietary encapsulation capabilities representing the stability-extension archetype for heat-processed applications. These three patterns—bundled service, botanical depth, and technology differentiation—capture the competitive fault lines reshaping supplier relationships.
| Leading Market Players |
|---|
| Givaudan |
| International Flavors & Fragrances Inc. |
| Firmenich SA |
| Kerry Group plc |
| Symrise AG |
| Takasago International Corporation |
| Sensient Technologies Corporation |
| Gold Coast Ingredients |
| Nature's Flavors, Inc. |
| Others |
Pricing and Supply Chain Analysis
Frankfurt's chemical processing corridor concentrates supercritical CO2 extraction capacity for beverage-grade natural flavors, concentrating upstream pricing power among equipment-integrated flavor houses serving pan-European dairy and carbonated drink clients. Carrier solvent costs and botanical raw material volatility transmit downstream as margin pressure on mid-tier formulators lacking captive supply agreements.
Pricing Analysis
Long-term offtake contracts dominate procurement for high-volume carbonated soft drink supply, locking in multi-year concentrate agreements with exclusive formulation terms. Price differentiation hinges on certification grade—REACH-compliant documentation commands premiums over FSSAI-qualifying alternatives—and volume scale, with tiered pricing separating global beverage multinationals from regional dairy processors. Cost compression in synthetic flavor tiers is intensifying because propylene glycol feedstock volatility squeezes mid-cap houses dependent on spot chemical markets. Mass-market bakery and confectionery segments exhibit highest price sensitivity, while premium organic dairy processors in Switzerland and Austria absorb certification premiums with limited volume negotiation.
Supply Chain Analysis
Contract manufacturing concentration sits with integrated flavor houses in Germany, India, and Switzerland that operate captive extraction and encapsulation lines. Raw material dependencies center on vanilla and citrus botanicals from Madagascar and Kerala, spice oleoresins from Indonesia, and petrochemical-derived carrier solvents from Gulf Coast refineries. Single-source vulnerability runs through Madagascar vanilla harvests exposed to cyclone disruption and geopolitical instability. Distribution runs through direct technical partnerships with food manufacturers, bypassing legacy full-service ingredient distributors as procurement unbundling accelerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service attachments—reformulation assistance, botanical sourcing volatility management, and co-development agreements—are expanding faster than base flavor concentrate sales as food manufacturers consolidate supplier panels. This service-layer growth outpaces hardware-equipment margins, creating recurring revenue pools for integrated houses.
For Market Incumbents: Insulate margin position through backward integration into botanical extraction capacity in Kerala and Madagascar, securing captive supply of vanilla and spice raw materials against climate and geopolitical disruption. Deepen encapsulation technology R&D to extend heat stability above 85°C degradation thresholds, defending premium positioning in UHT dairy against synthetic alternatives. For New Entrants and Emerging Players: Pursue domestic supply chain localization opportunities in India, where FSSAI purity standards enable faster qualification of Mumbai and Bangalore extraction capacity than REACH-compliant European alternatives. Target craft beverage producers and premium dairy clients seeking authentic botanical extracts with full traceability documentation, deploying direct-to-manufacturer digital platforms with proprietary formulation tools as the go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biotech-fermentation capabilities awaiting novel food status rulings from FDA and EFSA, offering regulatory pathway optionality for lab-grown aromatic molecules. Long-term viability across the analysis window hinges on precision-fermentation scale-up and enzymatic biotransformation commercialization. The signal to watch is EFSA novel food classification timelines for precision-fermented terpenes and esters, which would unlock clean-label claims and compress demand for petrochemical-derived synthetic precursors.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Scale-Up | Eliminates solvent residue concerns for EU F-Gas Regulation compliance in dairy applications. |
| Precision-Fermentation Capability Acquisition | Positions for FDA and EFSA novel food status rulings on lab-grown aromatic molecules. |
| Direct-to-Manufacturer Digital Platform Launch | Bypasses legacy distributors with proprietary customer portals integrating formulation tools. |
| Botanical Sourcing Integration in South Asia | Captures Kerala vanilla and spice supply clusters serving regional food manufacturers. |
| Encapsulation Technology R&D Partnership | Extends flavor stability above 85°C for UHT dairy with Firmenich SA and Givaudan archetype positioning. |
Research Methodology
Initial hypotheses were tested against primary input from flavor chemists at integrated houses, procurement leads at beverage multinationals, dairy R&D directors, and extraction equipment manufacturers, then refined against secondary validation. Bottom-up triangulation combined customs and trade data, EU REACH substance registration databases, SEC 10-K filings from listed flavor houses, and FSSAI purity standard documentation. Top-down cross-checks utilized beverage industry production statistics and dairy processing capacity surveys.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling volume and value outputs through segmentation dimensions spanning natural versus synthetic platforms, application heat-stability requirements, formulation concentration tiers, and end-user technical partnership depth. CAGRs were derived from growth rate convergence modeling applied to each segment's baseline and projected penetration. Industry-specific inputs included supercritical CO2 equipment deployment timelines and precision-fermentation commercialization readiness assessments.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock pricing, EU regulatory enforcement intensity, or botanical harvest yields would shift the trajectory. Forecasts reflect documented assumptions regarding REACH compliance timelines and FSSAI standard evolution. Quarterly review of EFSA novel food status rulings, Madagascar vanilla crop forecasts, and propylene glycol futures indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Global Bitterness Suppressors and Flavor Carriers Market
Flavorings and Food Additives
Global Eucalyptus Essential Oil Market
Flavorings and Food Additives
Carvone Market
Flavorings and Food Additives
Natural Acerola Cherry Extract Market
Flavorings and Food Additives
Global Syrup Market
Flavorings and Food Additives
Shelf-Stable Mezze Fermentation Ingredient Systems Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market
Flavorings and Food Additives
Orange Terpenes Market
Flavorings and Food Additives
Royal Jelly Extract Market
Flavorings and Food Additives
Europe Food Flavor Market
Flavorings and Food Additives
American Spikenard Extract Market
Flavorings and Food Additives
Jujube Extracts Market
Flavorings and Food Additives
Savory Extract Market
Flavorings and Food Additives
Global Vanilla (B2B) Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
Chokeberry Extract Market