
 Europe Fruits and Vegetables Juice Market | 2026-2036
Europe Fruits and Vegetables Juice Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fruits and Vegetables Juice Market Foresight
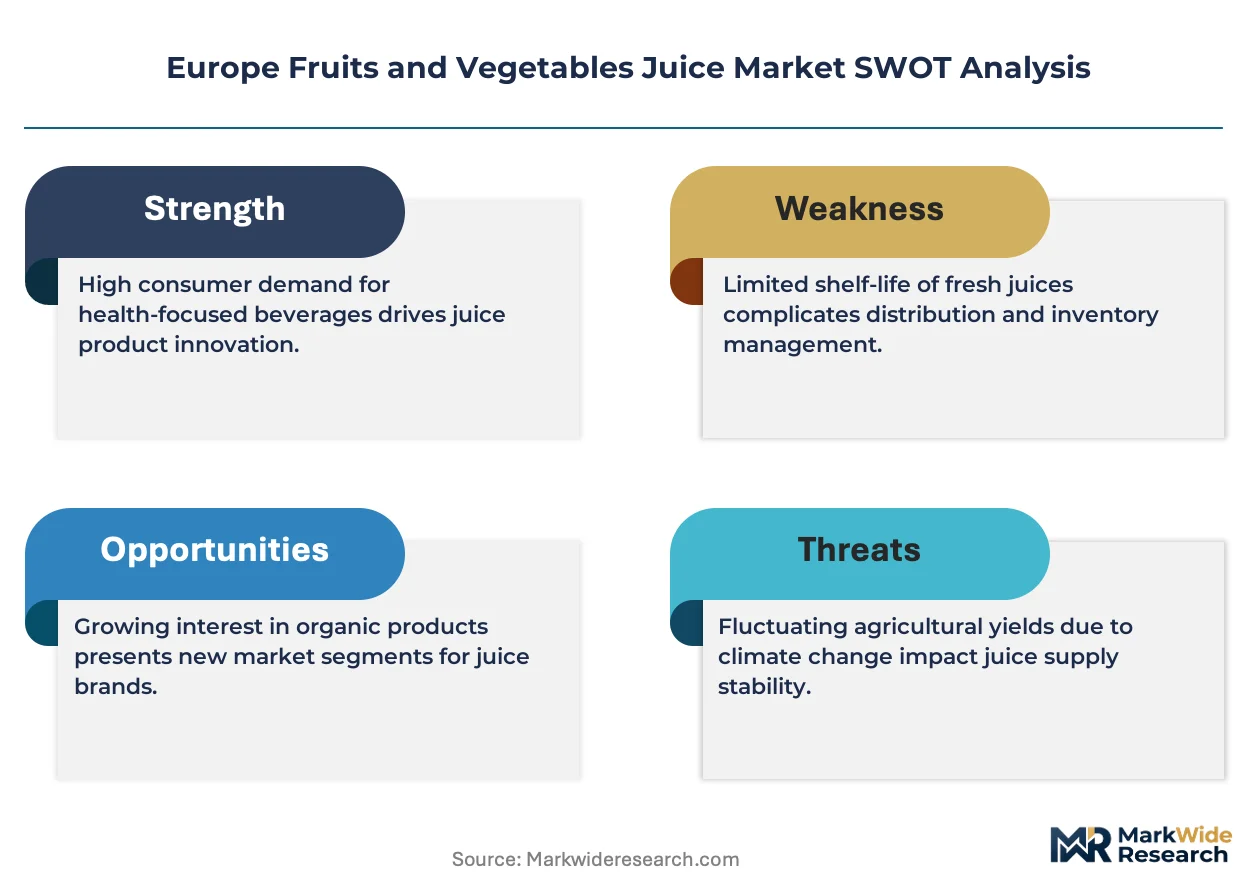
High-pressure processing technology is recalibrating juice preservation economics across European manufacturing lines. Eckes-Granini Group GmbH leverages its German bottling infrastructure to dominate private-label contracts for discount chains. Refresco Group anchors volume production through co-manufacturing agreements with multinational beverage brands. PepsiCo Inc. competes via direct-to-retail distribution control in Iberian markets.
Europe fruits and vegetables juice comprises single-strength or reconstituted liquids extracted from raw produce, typically processed through cold-press, centrifugal, or enzymatic methods with residual solids ranging from zero to twelve percent for clarified or nectar-grade products. This category serves retail shelf-stable consumption, foodservice fountain dispensing, and ingredient supply to dairy and bakery applications. Fresh juice commands premium shelf positioning in urban supermarkets while concentrated juice sustains industrial margin pools through bulk export logistics. Tetra Packs capture dominant share in ambient distribution channels, though pouches gain traction among convenience-oriented commuters.
EFSA nutrition claims regulation shapes permissible front-of-package health statements, while EU Green Deal packaging rules mandate recycled content thresholds for plastic bottles sold in member states. REACH compliance governs migration limits from cap liners and label adhesives into acidic fruit matrices. Stakeholders must monitor pending revisions to the EU Fruit Juice Directive that could redefine minimum Brix standards for diluted offerings.
Market Dynamics
High-pressure processing technology is compressing shelf-life economics while EU Green Deal packaging mandates force capital redeployment toward recyclable bottle formats across German and French bottling corridors.
Growth Catalysts
- Cold-press technology diffusion:German health-conscious households are expanding purchases of non-thermal processed variants, pulling investment into HPP equipment installations across Bavarian manufacturing clusters.
- EU Green Deal packaging rules:Recycled content thresholds for plastic bottles sold in member states are accelerating material science partnerships between juice processors and packaging converters.
- Urban retail corridor concentration:Paris and Amsterdam supermarket chains are dedicating premium shelf positioning to fresh juice, concentrating demand pull in Western European metropolitan centers.
Market Restraints
- Input cost volatility:Spanish citrus concentrate supply fluctuations are compressing margin pools for reconstituted juice manufacturers dependent on bulk import logistics.
- Regulatory friction:EFSA nutrition claims regulation restricts permissible front-of-package health statements, limiting differentiation tactics for functional juice positioning.
- Substitution threat:Flavored sparkling water and plant-based beverages are capturing convenience-oriented consumption occasions previously held by ambient juice cartons.
Strategic Opportunities
- Eastern European underpenetration:Polish and Romanian urban markets show whitespace for cold-pressed premium positioning as disposable income convergence accelerates.
- Foodservice fountain innovation:Automated fresh juice dispensing systems are opening channel expansion into Dutch and Belgian workplace cafeteria contracts.
- REACH compliance as barrier:Migration limit enforcement for cap liners and label adhesives is advantaging integrated processors with captive laboratory testing capabilities.
Industry Challenges
- HPP equipment capex intensity:Cold-press manufacturing lines require substantial capital deployment, constraining mid-scale processors from matching Eckes-Granini's German bottling infrastructure scale.
- EFSA claim substantiation timelines:Clinical validation requirements for novel functional ingredients are extending product development cycles beyond traditional juice innovation cadences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fruits and Vegetables Juice Market |
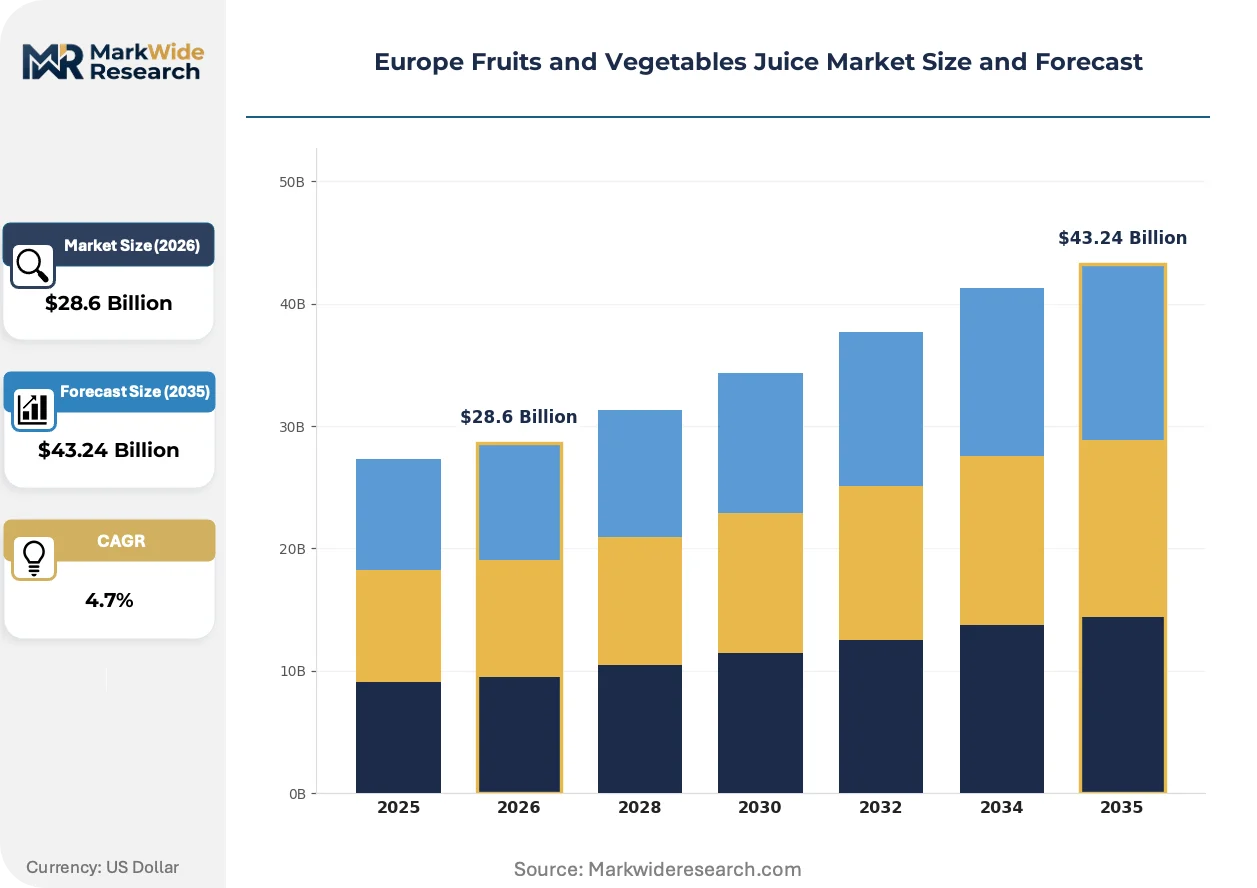
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Juice, Concentrated Juice, Puree, Smoothie Packaging Type: Bottles, Tetra Packs, Cans, Pouches Distribution Channel: Supermarkets, Health Stores, Online Retailers, Convenience Stores End User: Households, Restaurants, Cafes, Food Services |
| Companies Covered | Eckes-Granini Group GmbH, PepsiCo Inc., The Coca-Cola Company, Capri Sun Group Holding AG, Refresco Group, La Linea Verde Societa Agricola SpA, Del Monte Foods, Nestlé, Keurig Dr Pepper, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fruits and Vegetables Juice Market Shifts & Advancements
Pulsed electric field preservation is disrupting thermal processing conventions while regulatory pressure on packaging materials forces concurrent innovation across equipment and substrate domains.
Pulsed electric field technology applies short electrical pulses to liquid foods, inactivating microorganisms without thermal degradation of heat-sensitive vitamins. Dutch research institutes and Spanish citrus processors are piloting industrial-scale installations at accelerating frequency. This non-thermal approach is electrifying competitive positioning in the premium chilled segment by enabling clean-label shelf-life extension previously unattainable without pasteurization trade-offs.
EU Green Deal packaging sustainability mandates establish recycled content thresholds for plastic bottles sold across member states. Industrial consequence falls heaviest on ambient distribution channels where Tetra Pack dominance faces pressure from rigid bottle alternatives with higher post-consumer recyclability. German discount chains are responding by rewriting private-label procurement specifications to prioritize mono-material PET formats.
Direct-to-retail distribution control is displacing traditional wholesale intermediation in Iberian peninsula markets. PepsiCo's captive logistics infrastructure in Spain and Portugal exemplifies this channel compression, capturing margin pools previously distributed through layered distributor networks. French and Italian retail consolidation is amplifying this pattern as buying power concentrates in fewer banner operators.
Europe Fruits and Vegetables Juice Market Segmentation
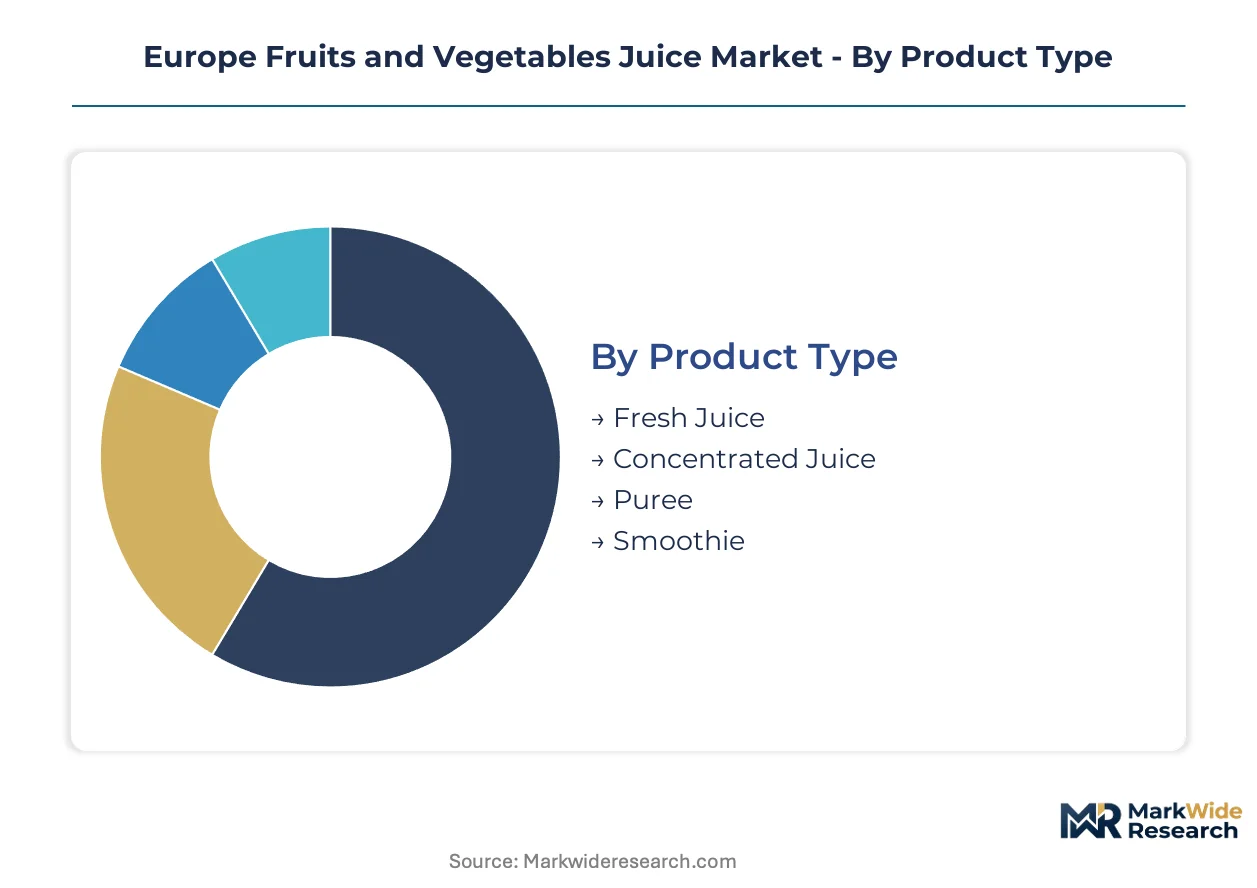
Segmentation in the Europe fruits and vegetables juice market reveals divergent margin structures across preservation technologies and channel economics. Cold-pressed variants command premium shelf positioning distinct from bulk concentrate operations, while packaging format choices directly determine recyclability compliance under EU Green Deal mandates.
Product Type:
Fresh juice operates as a standalone consumption category with minimal downstream processing, while concentrated and pureed formats embed into industrial ingredient systems and foodservice fountain operations.
- Fresh Juice:Cold-pressed or minimally processed liquids retaining full enzymatic activity and vitamin profiles, typically HPP-treated for shelf-life extension. German and French health-conscious households in urban corridors drive demand, constrained by refrigerated logistics costs and compressed shelf stability windows.
- Concentrated Juice:Water-reduced extracts standardized to specific Brix levels for reconstitution or industrial use. Spanish citrus processors dominate supply, with bulk export logistics sustaining margin pools for manufacturers serving ambient retail channels across Western Europe.
- Puree:Coarse-filtered fruit or vegetable matrices retaining pulp and fiber content for bakery and dairy ingredient applications.
- Smoothie:Blended combinations incorporating multiple produce sources, often with added functional ingredients targeting convenience-oriented consumption.
Volume placements concentrate in Concentrated Juice; the faster expansion belongs to Fresh Juice.
Packaging Type:
Packaging cost tiers separate premium positioning from economy access, with material recyclability becoming a decisive procurement filter under EU regulatory pressure.
- Bottles:Rigid PET or glass formats enabling resealability and premium visual presentation. German discount chains are rewriting private-label specifications to prioritize mono-material PET for post-consumer recyclability compliance.
- Tetra Packs:Multilayer cartons dominating ambient distribution through aseptic filling compatibility. Paris and Amsterdam supermarket chains maintain heavy placement despite EU Green Deal pressure on composite material recyclability.
- Cans:Aluminum formats suited to single-serve convenience and outdoor consumption occasions.
- Pouches:Flexible lightweight alternatives gaining traction among Dutch and Belgian commuters seeking portable portion control.
Current volume leadership sits with Tetra Packs; steepest expansion trajectory is in Bottles as recyclability specifications tighten.
Distribution Channel:
Channel selection determines margin capture versus volume throughput, with direct-to-retail compression displacing traditional wholesale intermediation in consolidated markets.
- Supermarkets:Multi-banner retail commanding dominant volume placement through centralized procurement and dedicated chilled fixture space. Iberian peninsula markets show PepsiCo's captive logistics infrastructure capturing margin pools previously distributed through layered networks.
- Health Stores:Specialized retail emphasizing organic certification and functional positioning. Cold-pressed premium variants cluster here, supported by EFSA nutrition claims regulation compliance for permissible front-of-package health statements.
- Online Retailers:Direct-to-consumer platforms enabling subscription models and expanded SKU availability beyond physical shelf constraints.
- Convenience Stores:Impulse-oriented outlets prioritizing single-serve formats and immediate consumption occasions.
Supermarkets anchor volume concentration; Health Stores claim the most rapid share gain as functional positioning intensifies.
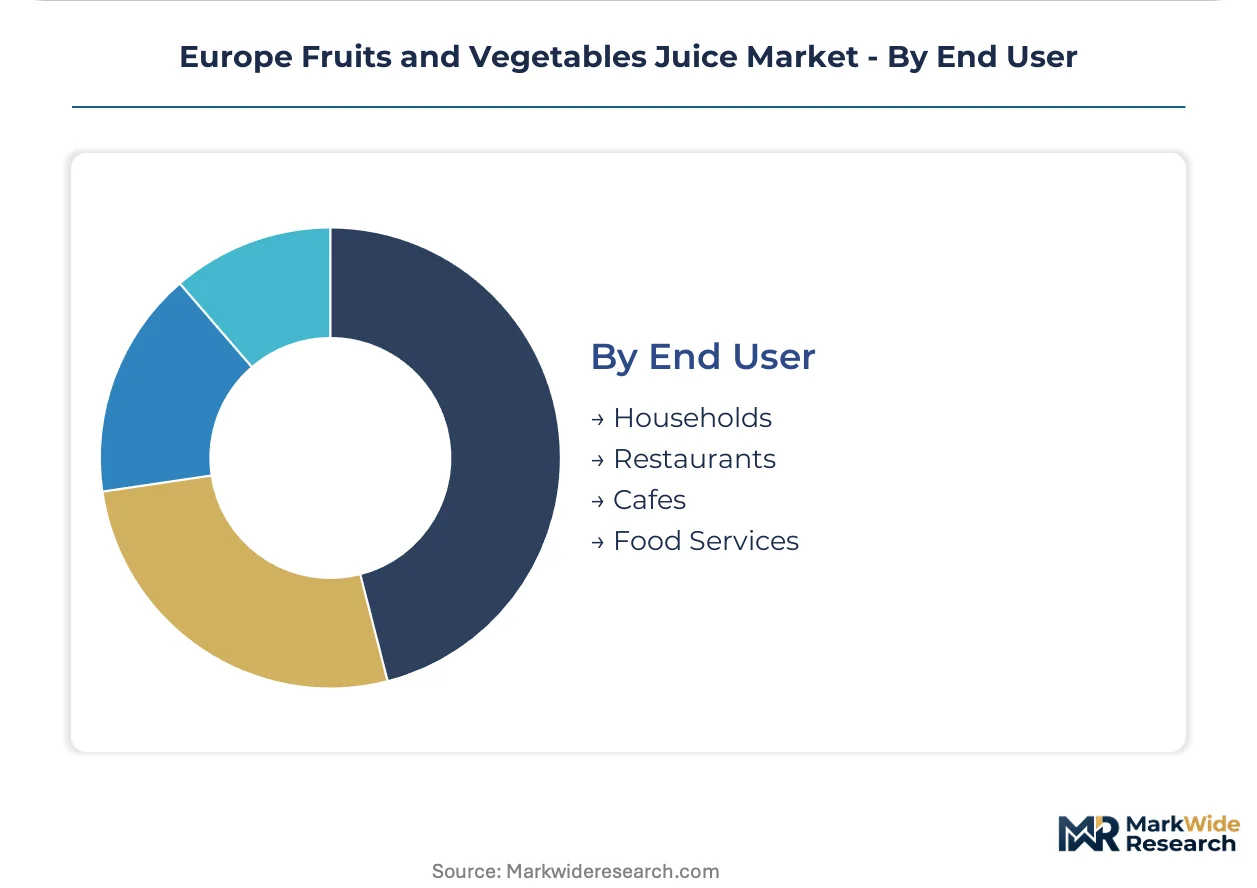
End User:
End-user segmentation maps to distinct consumption occasions and preparation requirements, from at-home consumption to out-of-home fountain dispensing systems.
- Households:Residential purchasers selecting multi-serve formats for refrigerator storage and family consumption. Bavarian manufacturing clusters target this segment with HPP-equipped lines serving German health-conscious demand.
- Restaurants:Foodservice operators requiring consistent quality for menu integration and portion-controlled dispensing.
- Cafes:Beverage-focused outlets emphasizing premium presentation and customizable blending options.
- Food Services:Institutional catering and workplace cafeteria contracts, where automated fresh juice dispensing systems are opening channel expansion into Dutch and Belgian facilities.
Households generate the dominant volume base; Food Services presents the fastest-climbing expansion opportunity through fountain automation penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Poland and Romania are attracting cold-press equipment investments through tax incentives and streamlined customs procedures. These zones concentrate new manufacturing capacity near urban consumption corridors.
Germany
Bavarian manufacturing clusters host the densest concentration of high-pressure processing lines serving health-conscious households in Munich and Frankfurt. EU Green Deal packaging rules mandate recycled content thresholds for plastic bottles, forcing material science partnerships between processors and converters. Eckes-Granini leverages its German bottling infrastructure to dominate private-label contracts for discount chains.
France
Paris supermarket corridors dedicate premium shelf positioning to fresh juice variants, pulling demand toward non-thermal processed offerings. EFSA nutrition claims regulation restricts permissible front-of-package health statements, limiting functional positioning tactics. The Île-de-France region anchors import logistics for Spanish citrus concentrate feeding reconstituted juice production.
Netherlands
Amsterdam retail chains maintain heavy Tetra Pack placement despite EU pressure on composite material recyclability. Dutch research institutes pilot pulsed electric field preservation at industrial scale, electrifying competitive positioning in premium chilled segments. Automated fresh juice dispensing systems are penetrating workplace cafeteria contracts across Dutch and Belgian facilities.
Spain
Spanish citrus processors dominate concentrated juice supply, with bulk export logistics sustaining margin pools for ambient retail channels. Direct-to-retail distribution control is displacing wholesale intermediation in Iberian markets. Valencia and Murcia growing regions feed processing clusters that supply reconstituted juice manufacturers across Western Europe.
Poland
Polish urban markets show whitespace for cold-pressed premium positioning as disposable income convergence accelerates. REACH compliance enforcement for cap liners and label adhesives advantages integrated processors with captive laboratory testing. Warsaw and Kraków retail corridors are attracting branded juice entrants seeking first-mover positioning in underpenetrated Eastern European demand.
Europe Fruits and Vegetables Juice Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with private-label volume concentrating in German discount chains and premium positioning clustering in French health stores. The vendor base organizes into three tiers: multinational beverage conglomerates with captive distribution, mid-scale regional bottlers with co-manufacturing specialization, and niche cold-press operators with health-channel focus. Dominant competitive moves include backward integration into citrus concentrate sourcing and geographic expansion through direct-to-retail logistics compression.
Within the multinational tier, PepsiCo Inc. and The Coca-Cola Company exemplify scale-driven distribution control, while Eckes-Granini Group GmbH anchors the European specialist position through German bottling infrastructure dominance. Refresco Group occupies the co-manufacturing archetype, serving multinational brands through volume production partnerships.
| Leading Market Players |
|---|
| Eckes-Granini Group GmbH |
| PepsiCo Inc. |
| The Coca-Cola Company |
| Capri Sun Group Holding AG |
| Refresco Group |
| La Linea Verde Societa Agricola SpA |
| Del Monte Foods |
| Nestlé |
| Keurig Dr Pepper |
| Others |
Supply & Pricing Matrix
Cold-press premiumization against concentrate commodity tiers splits the European juice market into divergent margin architectures, with HPP-equipped Bavarian lines commanding shelf-price multiples while Spanish citrus bulk exports sustain penny-margin ambient cartons. This bifurcation feeds directly into procurement patterns: German discount chains rewrite private-label specifications for mono-material PET recyclability, while Paris supermarkets absorb refrigerated logistics premiums for fresh positioning.
Pricing Analysis
Volume placements concentrate in reconstituted concentrate sold through Tetra Pack ambient channels, while margin pools accrue to HPP-treated fresh variants in refrigerated fixtures. Three-tier pricing structure across premium, standard, and economy levels reflects preservation technology intensity, with cold-press certification and EU organic logos as primary price differentiation drivers. Cost compression in the concentrate tier is intensifying because Spanish citrus supply fluctuations transmit directly into input costs. Discount chain buyers in Germany exhibit highest price sensitivity, whereas Dutch health-store consumers absorb premiums for pulsed electric field preservation claims.
Supply Chain Analysis
Dual-sourcing qualification requirements from major German and French retailers mandate Spanish citrus processors maintain backup concentrate supply from Greek or Italian origins. Raw material dependencies center on Valencia orange concentrate, Bavarian apple pressing, and Dutch vegetable puree feedstocks. Single-source vulnerability concentrates in HPP equipment supply, where Italian and German machinery builders face order backlogs. Distribution runs through direct-to-retail compression in Iberian markets, displacing layered wholesale intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European juice sector sits in a technology-transition phase, with pulsed electric field and HPP preservation displacing thermal pasteurization legacy infrastructure. This shift recalibrates capital deployment priorities across incumbent, entrant, and investor archetypes.
For Market Incumbents: Deepen backward integration into Spanish citrus concentrate sourcing to defend margin pools against input cost volatility. Secure captive HPP equipment capacity through long-term Italian machinery builder contracts, as order backlogs now stretch eighteen months. Channel control through direct-to-retail logistics compression in France and Italy anchors pricing power against wholesale intermediation erosion.
For New Entrants and Emerging Players: The mid-tier price-point gap between Paris premium fresh juice and German discount concentrate offers whitespace for pulsed electric field positioning with clean-label shelf-life extension. Polish and Romanian urban corridors present the most penetrable geography, with disposable income convergence accelerating and cold-press penetration below Western European levels. A foodservice fountain automation go-to-market angle bypasses saturated supermarket shelf competition.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale regional bottlers possessing co-manufacturing specialization and REACH-compliant laboratory infrastructure, given EU Green Deal packaging enforcement advantages. Long-term viability over a five-to-ten-year window favors processors with integrated testing capabilities over pure brand plays. The signal to watch is EFSA nutrition claims regulation revision timing, which would unlock functional positioning premiums for clinically validated ingredients.
| Strategic Initiative | Industry Significance |
|---|---|
| HPP Equipment Capacity Expansion | Bavarian manufacturing clusters capture German health-conscious household demand through non-thermal processing scale. |
| Mono-Material PET Transition | German discount chain procurement rewrites favor post-consumer recyclability compliance under EU Green Deal mandates. |
| Direct-to-Retail Distribution Compression | PepsiCo's Iberian captive logistics infrastructure captures margin pools from layered distributor networks. |
| Pulsed Electric Field Pilot Scaling | Dutch research institute partnerships electrify competitive positioning in premium chilled segments. |
| Eastern European Geographic Expansion | Warsaw and Kraków retail corridors attract branded entrants seeking first-mover positioning in underpenetrated demand. |
Research Methodology
Independent corroboration across juice processing executives, retail category buyers, packaging converter technical directors, and EFSA regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from EU Fruit Juice Directive revision tracking, REACH compliance documentation, Nielsen retail audit data for Western European supermarket channels, and customs records of Spanish citrus concentrate export flows. Bottom-up demand modeling across household, foodservice, and industrial ingredient segments triangulates against top-down value chain reconstructions.
Comparable-period anchoring to pre-pandemic consumption baselines and post-2022 inflation-adjusted purchasing patterns shapes the projection horizon. Segmentation dimensions span preservation technology, packaging format recyclability tier, distribution channel control structure, and regional regulatory cluster. CAGRs derive from installed HPP equipment capacity trajectories, EU Green Deal implementation phase-ins, and urban retail corridor premium shelf-space allocation trends.
Underlying measurement precision varies by segment; fresh juice volume carries tighter precision than concentrate given Nielsen refrigerated fixture tracking granularity. Forecasts reflect assumptions on EFSA claim substantiation timelines, Spanish citrus yield stability, and German discount chain procurement consolidation. Deviation in EU Fruit Juice Directive Brix standard revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
US Bubble Tea Market
Beverages
United States Sports and Energy Drinks Market
Beverages
Alternative Waters (Plant Based Waters) Market
Beverages
Asia-Pacific Juices Market
Beverages
Milk Tea Powder Market
Beverages
Chocolate Malt Drink Market
Beverages
Japan Kombucha Market
Beverages
Adaptogenic Beverages Market
Beverages
Rose Floral Water Market
Beverages
Powdered Soft Drinks Market
Beverages
Apple Juice Market
Beverages
Caffeine Mint Market
Beverages
Detox Drinks Market
Beverages
Botanical Infused Beverages Market
Beverages
Solid Beverages Market
Beverages
Kvass Market