
 Food Texturizers Market | 2026-2036
Food Texturizers Market Size, Share, and Industry Trends Forecast 2026-2036
Food Texturizers Market Foresight
Clean-label hydrocolloid innovation is tilting formulation priorities toward minimally processed, label-friendly stabilizers across bakery and dairy alternative portfolios. Cargill Inc. leverages its North American agricultural supply base to secure consistent tapioca and corn starch feedstock for texturizer production. Kerry Group plc anchors European demand through specialized protein texturization systems designed for meat substitute applications. DuPont de Nemours Inc. competes on microbial fermentation-derived gums that reduce dependency of botanical harvest cycles.
Food texturizers comprise functional ingredients that modify viscosity, gelation, mouthfeel, and structural integrity in processed foods, typically derived from polysaccharide, protein, or lipid matrices through physical modification, enzymatic treatment, or chemical derivatization. Hydrocolloids such as xanthan and gellan gum function at concentrations of 0.1% to 1.0% to yield pseudoplastic flow behavior critical for pourable dressings and plant-based beverages. Starches dominate volume consumption across sauces and dressings where cost efficiency and shear-thinning properties protect margin pools in commoditized segments. Proteins represent the fastest-growing category as extrusion technologies for meat substitutes demand texturizers capable of anisotropic fiber alignment.
FDA food additive regulations under 21 CFR and EU REACH chemical safety standards govern purity thresholds and migration limits for texturizers entering cross-border supply chains. The European Food Safety Authority evaluates novel hydrocolloids through centralized risk assessment protocols that delay market entry for fermentation-derived alternatives. China's National Health Commission maintains separate GB standards for food-grade gums that foreign suppliers must navigate for import clearance. Stakeholders must monitor evolving definitions of "natural" and "clean label" across jurisdictions, as regulatory divergence between FDA guidance and EU food information rules threatens to fragment formulation strategies and complicate global product platform development.
Market Dynamics
Clean-label formulation mandates are compressing R&D timelines for hydrocolloid and starch suppliers serving plant-based dairy and meat substitute manufacturers. This regulatory-consumer convergence is forcing ingredient portfolios toward single-source, minimally processed texturizers that satisfy both FDA 21 CFR labeling expectations and EU food information transparency rules.
Growth Catalysts
- EU REACH compliance deadlines:Purity thresholds for cross-border gum imports are accelerating investment in fermentation-derived alternatives that bypass agricultural harvest variability.
- Precision fermentation facilities:Cell-cultured protein production in Germany, the United States, and China requires advanced anisotropic fiber alignment systems that protein-based texturizers uniquely provide.
- Shear-thinning starch demand:Sauces and dressings manufacturers prioritize cost-efficient viscosity modification to protect margin pools in commoditized condiment segments.
Market Restraints
- Botanical harvest dependency:Tapioca and corn starch supply chains concentrate in specific agricultural belts, exposing texturizer producers to climate-induced input volatility.
- EFSA novel food assessments:Centralized risk assessment protocols for fermentation-derived hydrocolloids create 18-24 month market entry delays that advantage incumbent gum suppliers.
- Protein texturizer capex barriers:Extrusion equipment for meat substitute fiber alignment demands specialized capital deployment that mid-tier ingredient houses struggle to fund.
Strategic Opportunities
- China GB standards navigation:Foreign hydrocolloid suppliers who establish dedicated regulatory affairs capabilities for National Health Commission import clearance capture underserved premium beverage accounts.
- Enzymatic starch modification:Converging enzyme engineering and physical processing technologies enable clean-label viscosity control without chemical derivatization.
- Direct-to-manufacturer digital channels:Specialty texturizer houses bypass traditional distributor markups by building formulation technical service platforms accessible via e-procurement portals.
Industry Challenges
- Fermentation scale-up talent scarcity:Microbial gum production facilities face acute shortages of bioprocess engineers capable of translating lab yields to commercial bioreactor throughput.
- Dual certification complexity:Simultaneous FDA food additive petitions and EFSA novel food dossiers strain regulatory affairs teams at ingredient suppliers targeting transatlantic accounts.
- Legacy starch plant retrofit costs:Converting conventional modified starch lines to enzyme-based clean-label output requires substantial capital reallocation with uncertain payback timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Texturizers Market |
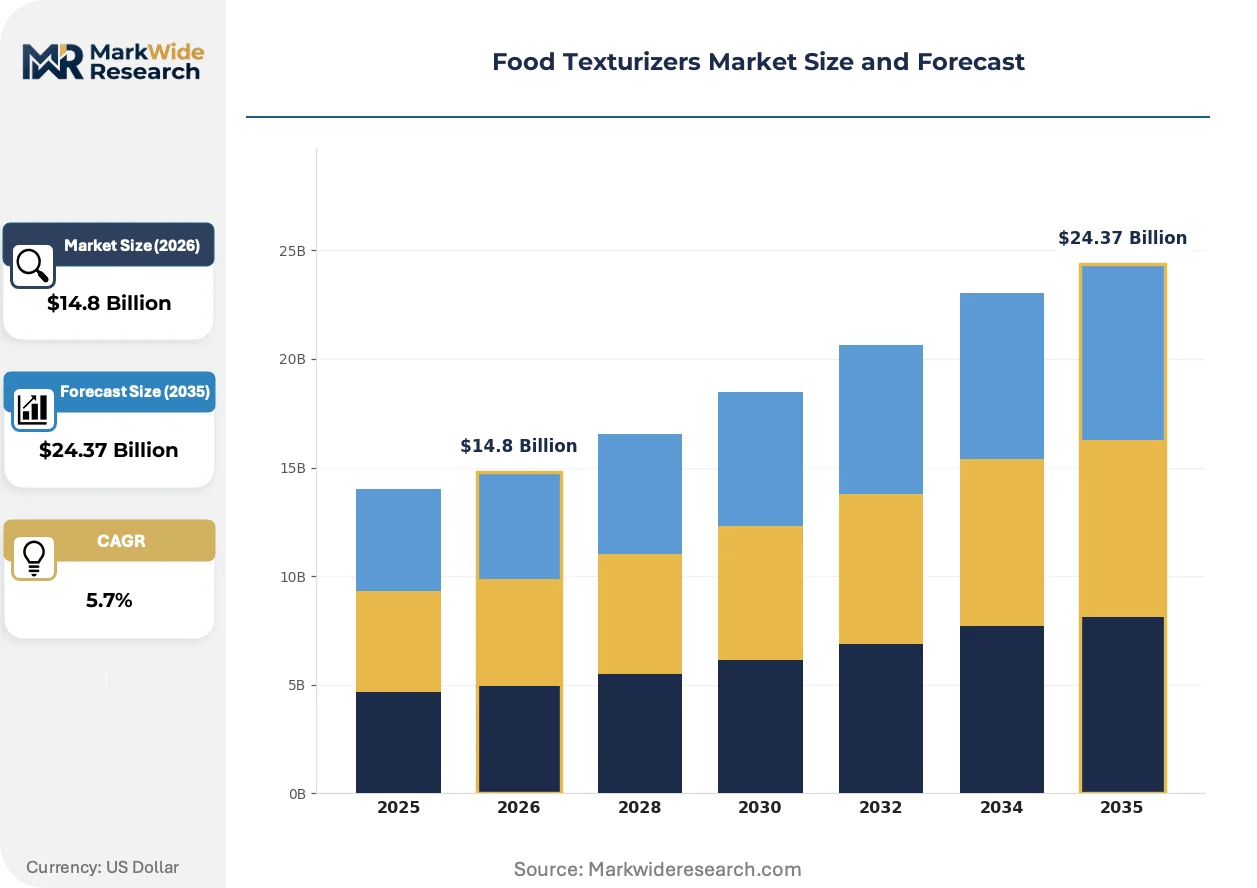
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starches, Gums, Proteins, Emulsifiers, Hydrocolloids Application: Bakery, Dairy Alternatives, Meat Substitutes, Confectionery, Sauces & Dressings Form: Powder, Liquid, Gel, Paste, Flakes End User: Food Manufacturers, Ingredient Suppliers, Food Service Providers, Nutraceutical Companies, Research Laboratories |
| Companies Covered | Archer Daniels Midland Co., Cargill Inc., DuPont de Nemours Inc., Ingredion Inc., Kerry Group plc, Tate & Lyle PLC, CP Kelco, FMC Corporation, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Texturizers Market Shifts & Advancements
Digital formulation platforms and bioprocess automation are compressing development cycles for texturizer suppliers. These converging capabilities enable real-time viscosity modeling and predictive stability testing that previously required months of bench-scale iteration.
Precision fermentation infrastructure is virtualizing the botanical supply chain for hydrocolloid production. Gellan and xanthan gum manufacturers deploy microbial cell factories to decouple output from cassava or corn harvest cycles. Plant-based dairy formulators in North America and Western Europe adopt these fermentation-derived alternatives at accelerating rates. This technology is virtualizing geographic supply constraints and compressing price volatility exposure for industrial buyers.
EU F-Gas Regulation phase-down mandates are reshaping solvent recovery requirements for starch modification facilities. Manufacturers face capital decisions on closed-loop processing systems or solvent substitution pathways. The regulatory pressure concentrates most acutely on mid-scale European starch houses serving sauces and dressings markets, many of whom delay compliance investments pending clearer enforcement timelines.
Formulation service unbundling is fragmenting traditional distributor relationships in the ingredient channel. Meat substitute startups and precision fermentation ventures now procure texturizers through technical-direct relationships that embed application scientists within customer R&D labs. This pattern is most visible in Germany and the Netherlands, where plant-based protein clusters concentrate purchasing influence among a handful of scaled manufacturers who demand co-development partnerships rather than commodity supply.
Food Texturizers Market Segmentation
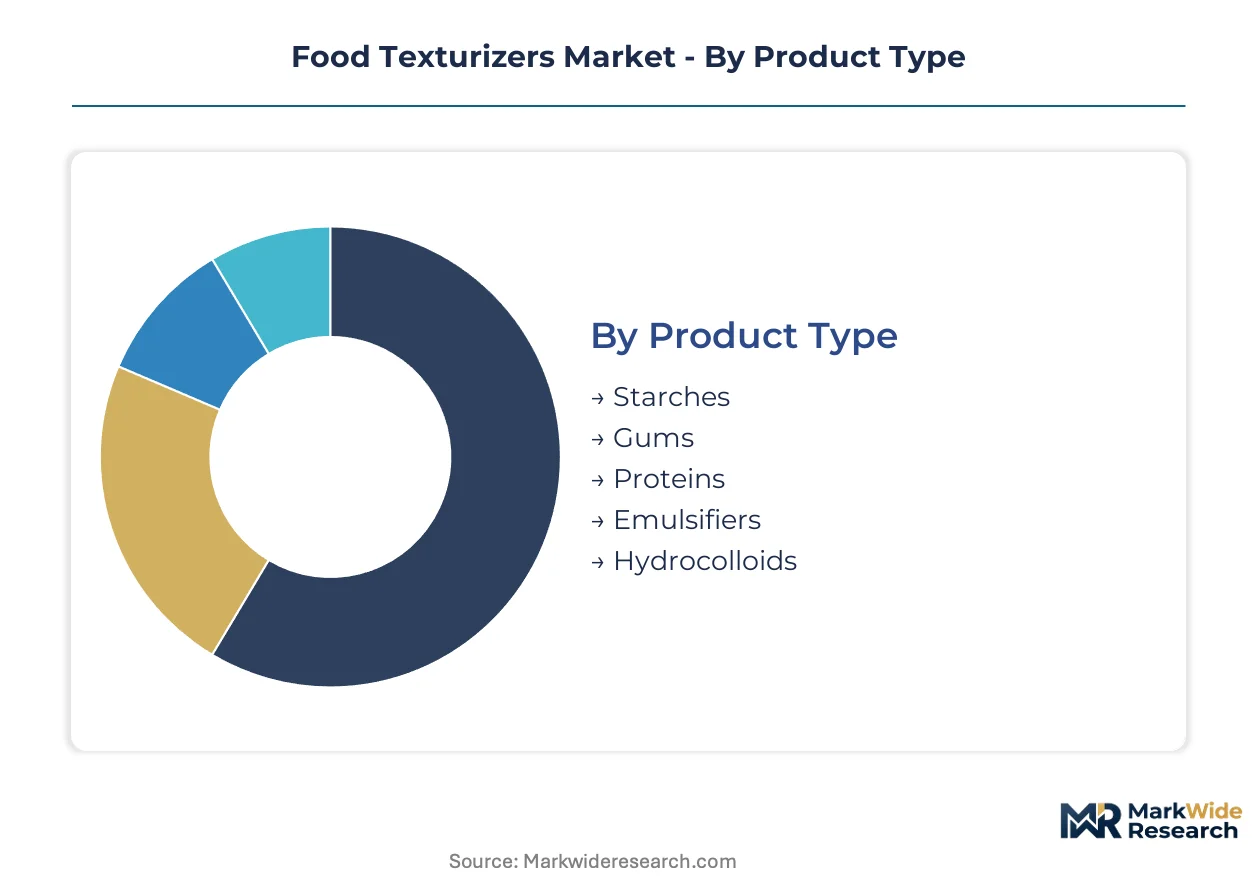
Texturizer segmentation reveals how functional requirements diverge across processing conditions, end-product architectures, and customer technical capabilities. Each dimension carries distinct margin structures, certification burdens, and formulation service intensity that reshape supplier engagement models.
Product Type:
Cost tier stratification separates commodity volume plays from premium functional specialties with divergent raw material exposure and capital intensity.
- Starches:Modified and native starch derivatives deliver shear-thinning viscosity control at 0.5-5.0% inclusion rates. Demand concentrates in sauces and dressings manufacturing across the United States and Germany where cost efficiency protects margin pools in commoditized condiment segments. Corn and tapioca feedstock dependency exposes processors to climate-induced input volatility.
- Hydrocolloids:Polysaccharide matrices including xanthan, gellan, and guar gum function at 0.1-1.0% concentrations to yield pseudoplastic flow behavior. Clean-label formulation momentum in North American and Western European plant-based dairy alternatives is accelerating fermentation-derived hydrocolloid adoption that bypasses agricultural harvest cycles.
- Proteins:Plant and fermentation-derived protein texturizers enable anisotropic fiber alignment through extrusion and shear-cell technologies. Meat substitute manufacturers in Germany and the Netherlands drive specialized protein texturization system procurement.
- Gums:Botanical and microbial gum variants provide suspension, emulsion stabilization, and film-forming properties. EFSA novel food assessment protocols for fermentation-derived alternatives create 18-24 month market entry delays.
- Emulsifiers:Lipid-based and polyglycerol ester systems stabilize oil-water interfaces in bakery and confectionery applications. Mono- and diglyceride demand tracks industrial bakery capacity expansion.
Starches hold installed capacity. Hydrocolloids is rotating up the share rankings.
Application:
Application segmentation maps formulation complexity gradients against customer R&D sophistication and co-development willingness.
- Dairy Alternatives:Plant-based milk, yogurt, and cheese analogs demand hydrocolloid and starch systems that replicate mouthfeel, creaminess, and thermal stability of conventional dairy. Precision fermentation facilities in the United States and China scale advanced texturization infrastructure for next-generation dairy alternatives.
- Meat Substitutes:Extruded and shear-textured protein products require texturizers capable of anisotropic fiber alignment and bite resistance. German and Dutch plant-based protein clusters concentrate purchasing influence among scaled manufacturers demanding embedded application scientists.
- Bakery:Bread, pastry, and cake applications leverage starch and emulsifier systems for crumb structure, shelf-life extension, and dough handling. Clean-label mandates compress R&D timelines for hydrocolloid and starch suppliers.
- Sauces & Dressings:Pourable and spoonable condiments prioritize shear-thinning viscosity modification and freeze-thaw stability. Cost efficiency imperatives dominate procurement in commoditized segments.
- Confectionery:Gummies, jellies, and aerated confections utilize gelling hydrocolloids and starch-based glazing systems. Texture-modified sugar reduction formulations drive specialty gum demand.
Dairy Alternatives commands formulation service intensity. Meat Substitutes is climbing the fastest.
Form:
Physical form selection determines handling infrastructure requirements, dissolution kinetics, and supply chain moisture sensitivity.
- Powder:Spray-dried and milled particulate forms dominate bulk industrial procurement for dry blending operations. Powder handling systems require dust control and pneumatic conveying infrastructure.
- Liquid:Pre-hydrated suspensions and solutions eliminate dispersion challenges in high-throughput continuous processing. Liquid form demand tracks automated dosing system adoption.
- Gel:Pre-formed gel matrices enable precise portioning and reduced hydration time in specialized applications. Gel concentrates serve small-batch artisanal manufacturers.
- Paste:Semi-solid preparations combine texturizer and carrier for direct incorporation into dough and batter systems. Paste forms reduce weighing error in manual operations.
- Flakes:Laminated and granular flake structures provide controlled hydration rates in instant and ready-to-eat applications. Flake morphology supports visual texture differentiation.
Powder holds installed capacity. Liquid is rotating up the share rankings.
End User:
Customer type segmentation separates formulation-capable integrated manufacturers from ingredient-dependent processors with divergent technical service requirements.
- Food Manufacturers:Integrated CPG and private-label producers operate captive R&D labs with direct texturizer specification authority. Technical-direct procurement relationships embed supplier scientists within customer innovation pipelines.
- Ingredient Suppliers:Blenders, premix houses, and compounders intermediate texturizers into functional systems for downstream food processors. Ingredient suppliers demand multi-texturizer compatibility data and stability matrices.
- Food Service Providers:Commercial and institutional kitchen operators procure finished texturized bases and concentrates. Food service channels prioritize consistent performance across variable preparation conditions.
- Nutraceutical Companies:Supplement and functional food producers utilize texturizers for controlled-release matrices and palatability enhancement. Nutraceutical applications require pharmaceutical-grade documentation and allergen segregation.
- Research Laboratories:Academic and corporate R&D facilities pilot novel texturizer applications and processing technologies. Laboratory-scale procurement emphasizes sample flexibility and technical collaboration.
Food Manufacturers holds installed capacity. Ingredient Suppliers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision fermentation-derived hydrocolloids to Dutch and Danish plant-based protein manufacturers, establishing a cross-border trade corridor that anchors European texturizer demand.
United States
Precision fermentation facilities in California and Massachusetts scale cell-cultured protein production requiring advanced anisotropic fiber alignment systems. FDA 21 CFR food additive petitions govern novel hydrocolloid market entry timelines. Chicago and Minneapolis starch processors serve commoditized sauces and dressings markets with cost-efficient shear-thinning formulations.
Germany
Plant-based meat substitute clusters in Cologne and Berlin drive specialized protein texturization system procurement from domestic suppliers. EU REACH compliance deadlines for gum purity thresholds accelerate fermentation-derived alternative investment. Bavaria hosts extrusion technology centers developing next-generation fiber alignment capabilities for European meat analog manufacturers.
China
Yangtze River Delta beverage manufacturers import premium hydrocolloids for plant-based dairy alternatives targeting domestic premium segments. National Health Commission GB standards for food-grade gums create regulatory navigation requirements for foreign suppliers. Shanghai and Hangzhou precision fermentation ventures build captive texturization infrastructure for cell-cultured protein commercialization.
Netherlands
Wageningen University-corporate research partnerships anchor European plant-based protein R&D concentration. EFSA novel food assessment protocols for fermentation-derived hydrocolloids create 18-24 month market entry delays that advantage established suppliers. Eindhoven and Rotterdam house technical-direct procurement relationships embedding supplier scientists within customer innovation pipelines.
Food Texturizers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Agricultural conglomerates leverage feedstock security and vertical integration into starch and gum production. Fermentation technology specialists command premium positioning through microbial cell factory capabilities. Strategic moves concentrate on enzymatic modification capacity expansion and clean-label portfolio diversification to capture plant-based formulation mandates.
Among North American agricultural processors, Cargill Inc. and Ingredion Inc. exemplify feedstock-anchored scale archetypes. DuPont de Nemours Inc. occupies a position representing microbial fermentation-derived gum specialization. Kerry Group plc anchors European technical service intensity for meat substitute applications. These three entities collectively illustrate the competitive tension between agricultural supply security and biotechnology-driven formulation innovation.
| Leading Market Players |
|---|
| Archer Daniels Midland Co. |
| Cargill Inc. |
| DuPont de Nemours Inc. |
| Ingredion Inc. |
| Kerry Group plc |
| Tate & Lyle PLC |
| CP Kelco |
| FMC Corporation |
| BASF SE |
| Others |
Supply & Pricing Matrix
Iowa corn belt processing capacity anchors North American starch supply, with Des Moines and Cedar Rapids facilities translating agricultural harvest volumes into downstream pricing leverage for modified starch derivatives. This geographic concentration enables bulk buyers to negotiate contract-based offtake terms while exposing spot purchasers to climate-induced input volatility.
Pricing Analysis
Prior-generation chemically modified starches command economy-tier positioning against next-generation enzymatically processed alternatives that capture clean-label premiums. Pricing stratifies across fermentation-derived hydrocolloids, native starches, and commodity modified derivatives based on purity certification and EFSA novel food dossier status. Cost compression in standard-grade starches intensifies as Brazilian tapioca processors expand export capacity. Meat substitute manufacturers demonstrate lowest price sensitivity due to fiber alignment performance requirements, while sauces and dressings producers prioritize volume-scale procurement.
Supply Chain Analysis
Extended payment terms from German precision fermentation ventures to bioprocess equipment vendors illustrate supply-chain finance facilities penetrating upstream capital deployment. Raw material flows draw from United States corn belts, Southeast Asian cassava plantations, and Chinese microbial cell factory facilities. Single-source vulnerability concentrates in fermentation-derived gum production where commercial-scale bioreactor capacity remains limited. Distribution runs through technical-direct relationships embedding supplier scientists within customer R&D operations rather than traditional ingredient distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label formulation fragmentation creates niche opportunities as plant-based dairy and meat substitute manufacturers abandon one-size-fits-all texturizer portfolios for application-specific systems.
For Market Incumbents: Insulate fermentation-derived hydrocolloid margins by securing captive bioprocess engineering talent pools before precision fermentation scale-up accelerates. Accelerate backward integration into tapioca starch supply through Southeast Asian agricultural partnerships to neutralize climate volatility exposure. EFSA novel food assessment bottlenecks protect incumbent gum positions but require proactive regulatory affairs investment to defend against microbial cell factory entrants. For New Entrants and Emerging Players: Mid-tier European starch houses serving sauces and dressings markets represent the most penetrable entry point for enzymatic modification technology licensing. China's Yangtze River Delta beverage manufacturers offer underserved premium hydrocolloid accounts for foreign suppliers establishing dedicated National Health Commission regulatory capabilities. Direct-to-manufacturer digital channels bypassing traditional distributor markups provide the strongest go-to-market angle for specialty texturizer houses. For Investors and Strategic Acquirers: Carve-out targets emerge from agricultural conglomerates seeking to divest non-core texturizer divisions amid clean-label portfolio repositioning. Long-term viability centers on fermentation infrastructure ownership rather than botanical harvest-dependent assets. Watch for EFSA enforcement timeline clarity on novel hydrocolloid assessments as the inflection signal for microbial gum production valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial cell factories decouple gellan and xanthan output from cassava harvest cycles. |
| Enzymatic Modification Transition | Clean-label starch processing eliminates chemical derivatization for EU REACH compliance. |
| Technical-Direct Channel Development | Embedded application scientists within German meat substitute R&D labs capture formulation influence. |
| Regulatory Affairs Capability Buildout | Dedicated China GB standards navigation unlocks National Health Commission import clearance. |
| Backward Integration into Feedstock | Captive tapioca and corn supply neutralizes climate-induced input price volatility. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR petitions, EFSA novel food dossiers, and National Health Commission GB standards documentation. The study combines structured interviews with hydrocolloid R&D directors, starch procurement leads at CPG manufacturers, and regulatory affairs specialists at fermentation technology ventures with customs trade data and SEC filings from agricultural processors. Bottom-up segment sizing triangulates against top-down market validation across product type, application, and regional demand clusters.
Forecast inputs incorporate hydrocolloid concentration rates by application, starch inclusion percentages across sauces and dressings formulations, and protein texturizer adoption curves in extruded meat substitutes. The analytical framework models product type segmentation against end-user technical capabilities and geographic regulatory divergence throughout the forecast period. CAGRs derive from weighted scenario analysis of precision fermentation commercialization timelines and clean-label mandate enforcement intensity.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity indices, bioprocess equipment capital costs, or transatlantic regulatory harmonization would shift the trajectory. Forecasts reflect documented assumptions regarding EFSA assessment throughput, China import clearance velocity, and fermentation scale-up engineering availability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Middle East Food Premix Market
Flavorings and Food Additives
Smoked Condensates Market
Flavorings and Food Additives
FTNF Flavors Market
Flavorings and Food Additives
Bitter Apricot Extract Market
Flavorings and Food Additives
Ylang Ylang Extract Market
Flavorings and Food Additives
Citrus Concentrate Market
Flavorings and Food Additives
Seaweed Flavor Market
Flavorings and Food Additives
Citrus-Based Sugar-Reduction Flavor Modulators Market
Flavorings and Food Additives
Cocoa Extract Market
Flavorings and Food Additives
Botanical Flavors Market
Flavorings and Food Additives
Anthocyanin Food Colors Market
Flavorings and Food Additives
Roast Flavoring Market
Flavorings and Food Additives
De Oiled Lecithin Market
Flavorings and Food Additives
Keto Friendly Flavors Market
Flavorings and Food Additives
Fractionated Lecithin Market
Flavorings and Food Additives
Canola Lecithin Market