
 Food-Grade Gellan Gum Market | 2026-2036
Food-Grade Gellan Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Food-Grade Gellan Gum Market Analysis
EU Green Deal compliance is hardening requirements for sustainable food ingredient sourcing across European supply chains. CP Kelco leverages its integrated fermentation capacity to serve beverage and dairy formulators with consistent low acyl gellan supply. Jungbunzlauer anchors European distribution through specialized hydrocolloid blending operations. Ingredion Incorporated competes by extending its clean-label starch-gum portfolio into plant-based dessert applications.
Food-grade gellan gum is a high-molecular-weight exopolysaccharide produced via aerobic fermentation of Sphingomonas elodea, with acyl substitution patterns determining gel texture from soft elastic to firm brittle. Its primary commercial purpose centers on suspension, gelation, and fluid thickening in heat-processed foods requiring thermal stability across pH ranges. High acyl gellan dominates dairy and beverage applications where soft, flexible gels improve mouthfeel without syneresis. Low acyl gellan leads bakery and confectionery segments where brittle, firm gels support structured layering and clean flavor release. Powder form occupies the largest volume share due to extended shelf stability and ease of dry blending into industrial food production lines.
FDA food additive regulations under 21 CFR 172.665 govern gellan gum safety thresholds and labeling in the United States, while EFSA evaluates novel food applications and purity standards across EU member states. China's SAMR enforces GB standards for microbial polysaccharide use in domestic food processing, creating divergent compliance pathways for exporters. BIS certification requirements in India add another layer of market access control for imported hydrocolloid ingredients. Stakeholders must monitor evolving clean-label definitions and regional purity thresholds to align product portfolios with tightening additive approval frameworks.
Market Dynamics
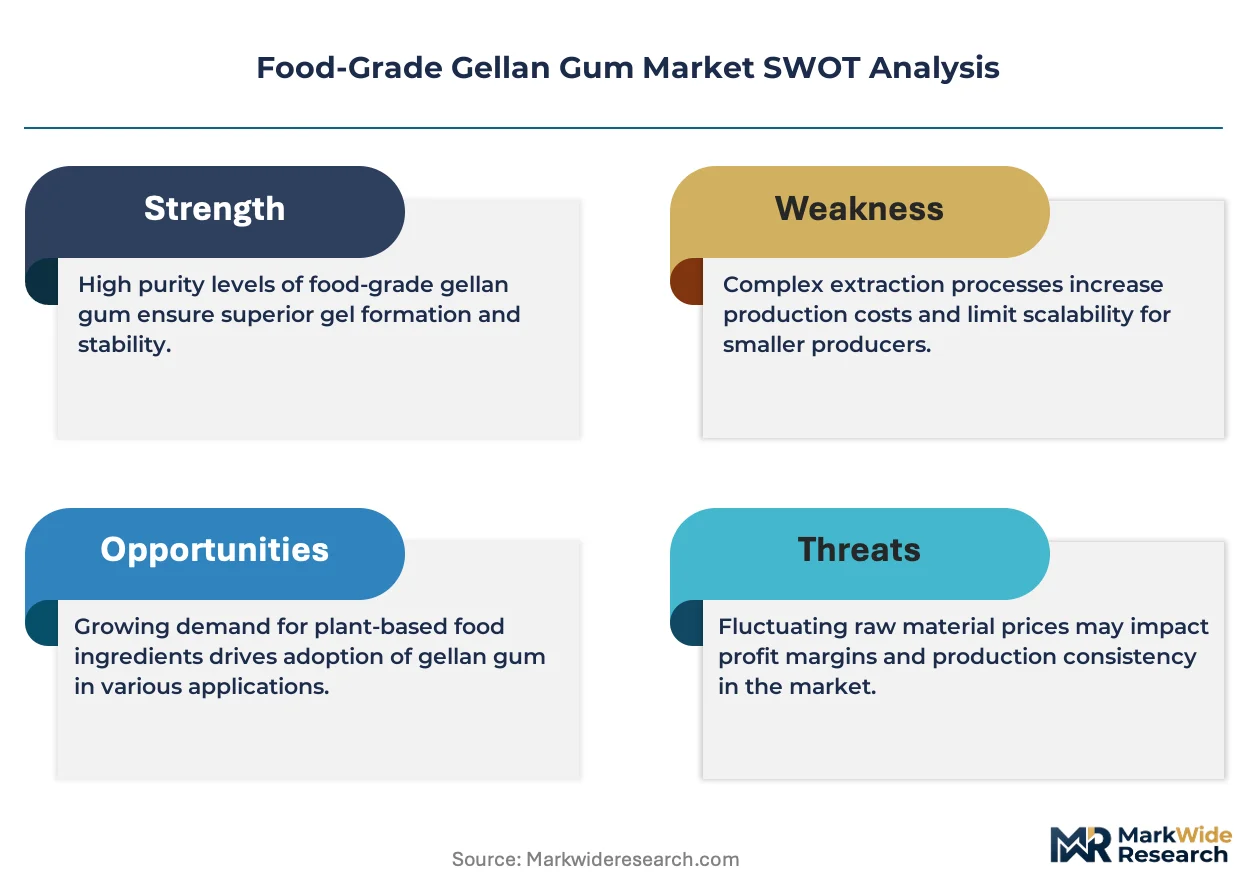
Clean-label ingredient mandates are compressing formulation windows for food-grade gellan gum as manufacturers face simultaneous pressure to reduce additive counts while maintaining suspension stability in plant-based beverages.
Growth Catalysts
- EU Green Deal sourcing mandates:Sustainable fermentation feedstock requirements are accelerating supplier certification upgrades across European dairy alternative supply chains.
- Plant-based beverage suspension:Oat and almond milk processors require thermal-stable hydrocolloids to prevent phase separation during UHT processing.
- China GB standard harmonization:SAMR microbial polysaccharide purity rules are consolidating domestic supplier qualification tiers for imported gellan gum.
Market Restraints
- Fermentation substrate cost volatility:Glucose and yeast extract prices fluctuate with corn and sugar beet harvest cycles, squeezing contract margin predictability.
- Supplier concentration in fermentation capacity:Commercial-scale Sphingomonas elodea production clusters among three integrated bioprocess operators globally.
- Carrageenan substitution in cost-sensitive segments:Conventional stabilizers retain foothold in private-label dessert applications where texture tolerance is wider.
Strategic Opportunities
- India FSSAI clean-label pathway:Domestic plant-based dairy formulators seek imported hydrocolloid alternatives ahead of stricter additive disclosure rules.
- Precision fermentation convergence:Cell-cultured protein beverages require novel suspension systems compatible with neutral pH and low-heat processing.
- E-commerce ingredient sourcing:Direct-to-manufacturer platforms bypass traditional distributor markups for mid-scale bakery and confectionery processors.
Industry Challenges
- Fermentation scale-up technician scarcity:Aerobic bioprocess engineering expertise concentrates among legacy pharmaceutical and enzyme producers.
- Dual acyl certification timelines:Separate high-acyl and low-acyl grade approvals delay multi-application product launches in regulated markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food-Grade Gellan Gum Market |
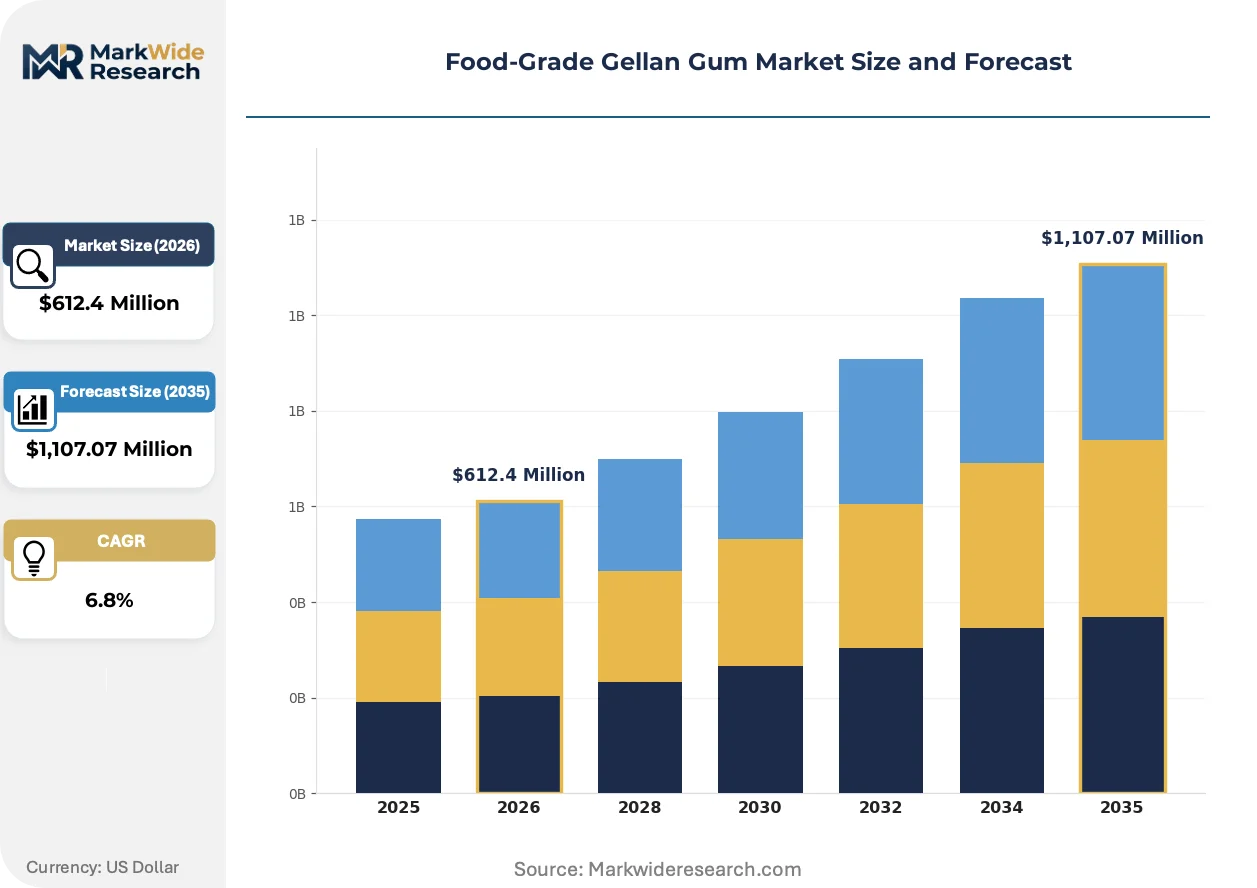
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Acyl Gellan, Low Acyl Gellan, Blends, Hydrocolloid Combinations Application: Dairy Products, Bakery Items, Sauces, Meat Products End User: Food Manufacturers, Food Service Providers, Retail Chains, Private Label Brands Form: Powder, Granules, Gel, Liquid |
| Companies Covered | Ingredion Incorporated, Dancheng Caixin Sugar Industry Co. Ltd., CP Kelco, Hebei Xinhe Biochemical Co. Ltd., Fufeng Group, Jungbunzlauer, Cargill Incorporated, Hawkins Watts, DowDuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food-Grade Gellan Gum Market Emerging Trajectories
Fermentation process intensification and regulatory disclosure tightening are redefining competitive advantage in food-grade gellan gum, separating integrated bioprocess operators from toll-dependent compounders.
Continuous fermentation with real-time rheology monitoring is integrating into commercial Sphingomonas elodea production lines. Beverage manufacturers in Germany and the United States are adopting these supply streams to reduce batch-to-batch viscosity variation. This process control architecture is integrating predictive quality assurance into long-term supply agreements, compressing qualification cycles for new plant-based product launches.
EFSA novel food evaluation timelines are extending purity documentation requirements for exopolysaccharide ingredients. European formulators now face eighteen-month approval windows for new acyl-substitution variants in infant nutrition applications. Dairy alternative processors are responding by locking multi-year supply contracts with established low-acyl gellan suppliers to preempt formulation disruption.
Direct procurement from fermentation operators is displacing traditional hydrocolloid distributor relationships among North American clean-label brands. Mid-scale plant-based yogurt manufacturers now negotiate volume commitments directly with bioprocess facilities, bypassing regional blending houses. This channel compression is most visible in California and New York state clusters where formulation speed-to-market determines shelf placement.
Food-Grade Gellan Gum Market Segmentation
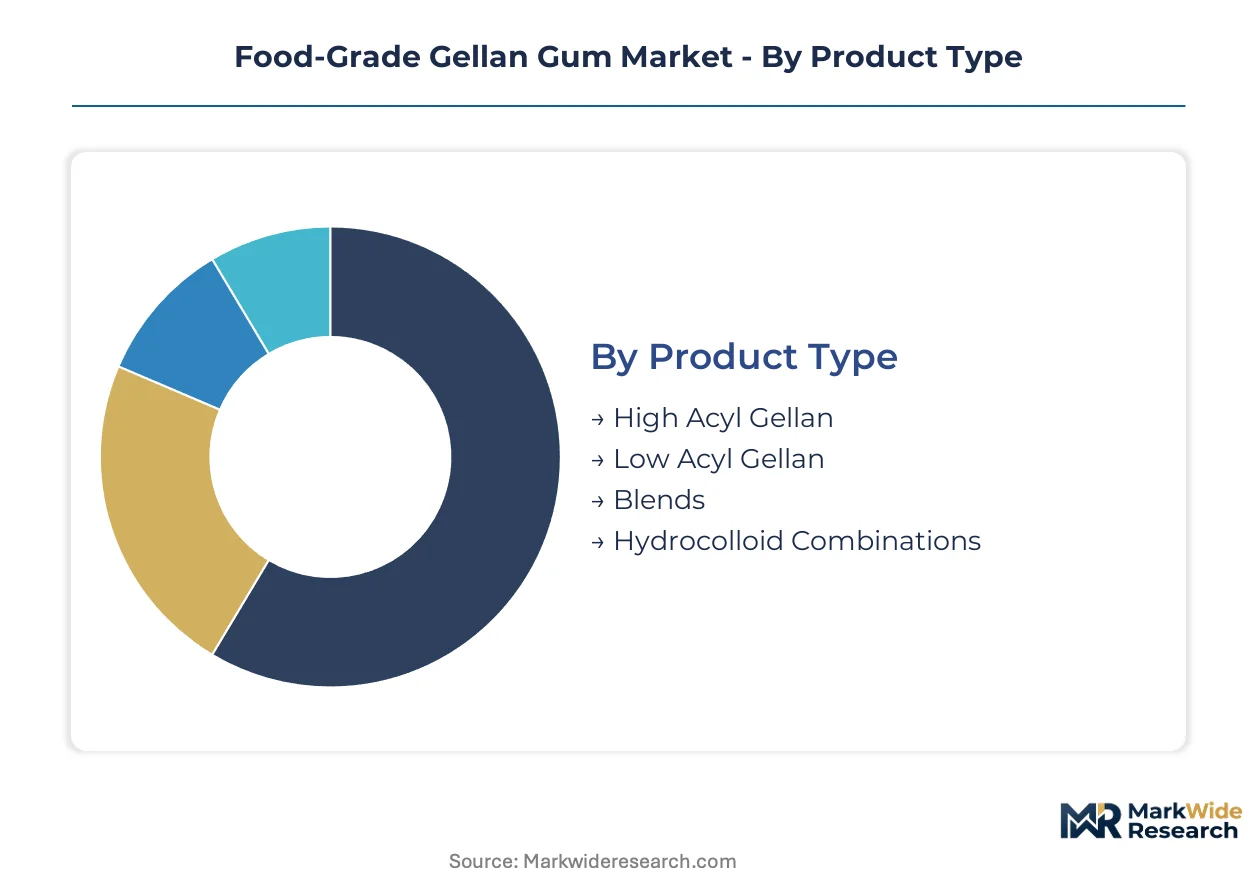
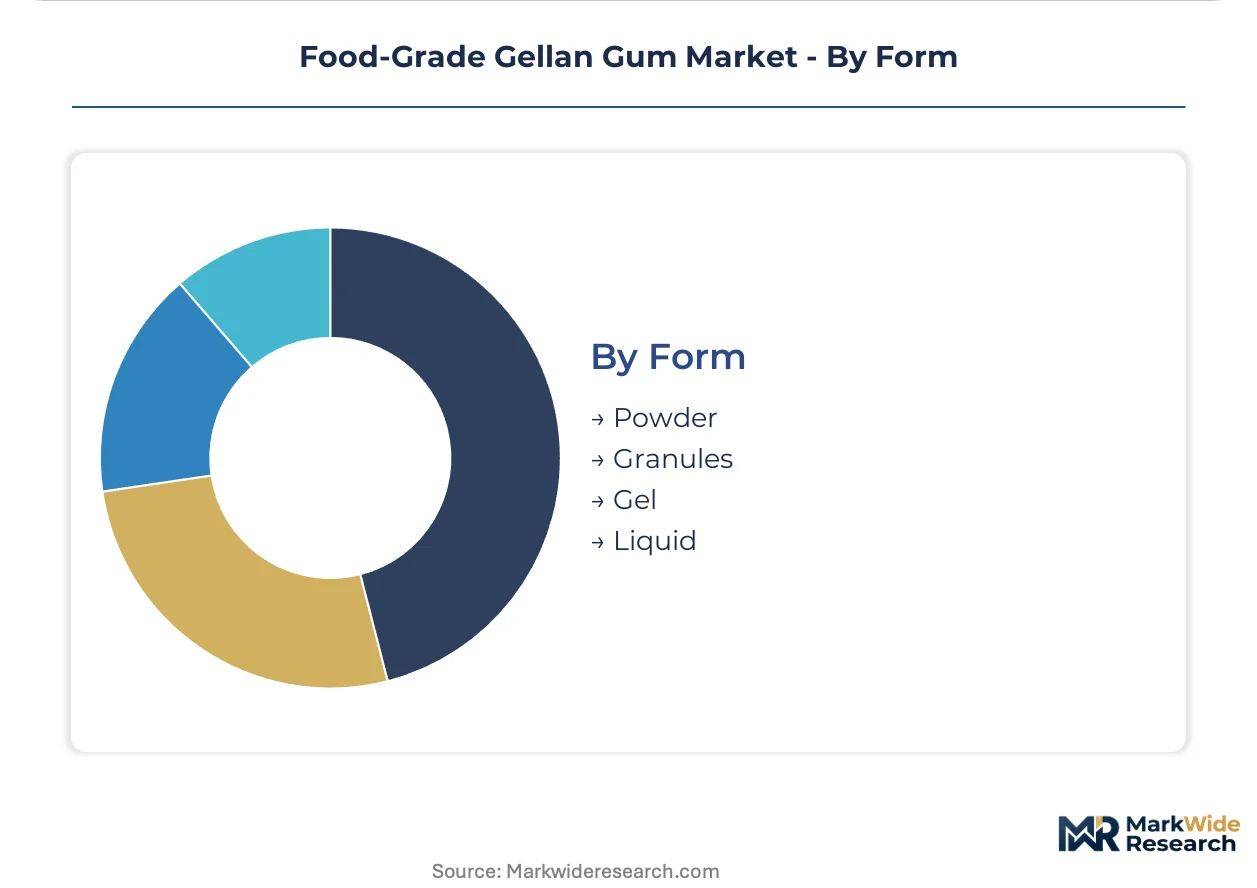
Segmentation in food-grade gellan gum reveals how acyl substitution patterns, physical forms, and customer procurement scale determine pricing power and supply chain access. Manufacturers configure production campaigns around these divisions to match fermentation batch economics with formulation requirements.
Product Type:
Fermentation capacity concentrates differentially across acyl grades, with integrated bioprocess operators optimizing strain selection and feedstock ratios for specific gel textures.
- High Acyl Gellan:Produced with native acyl groups intact, yielding soft, elastic gels that deform under shear and recover without syneresis. Dairy alternative processors in Germany and the United States specify this grade for oat milk suspension systems requiring thermal stability through UHT tunnels.
- Low Acyl Gellan:Deacylated via alkaline treatment to create firm, brittle gels with sharp fracture profiles and clean flavor release. Bakery and confectionery formulators in China leverage this grade for layered dessert structures and heat-stable glazes.
- Blends:Pre-mixed ratios of high and low acyl grades targeting intermediate texture profiles.
- Hydrocolloid Combinations:Co-processed with xanthan, locust bean, or starch for synergistic rheology in complex food matrices.
Low acyl gellan absorbs the bulk of installed capacity; high acyl gellan is expanding most quickly.
Application:
Formulation complexity and thermal processing intensity determine hydrocolloid specification tiers across food manufacturing segments.
- Dairy Products:Plant-based yogurts and fermented alternatives require suspension stability across acidic pH ranges and refrigerated distribution. European clean-label brands specify gellan for protein stabilization without carrageenan.
- Bakery Items:Heat-stable gelation supports fruit fillings, glazes, and structured layers in industrial production lines.
- Sauces:Pourable viscosity with particulate suspension drives demand in pourable dressings and cooking sauces.
- Meat Products:Injection brines and formed meat matrices use gellan for moisture retention and sliceability.
Dairy applications command premium pricing tiers; bakery segments show the steepest specification diversification.
End User:
Procurement scale and technical service requirements stratify the customer base into distinct commercial relationship models.
- Food Manufacturers:Multinational processors negotiate direct fermentation supply contracts with volume commitments and joint formulation development.
- Food Service Providers:Institutional and restaurant chain distributors purchase through regional hydrocolloid blending houses with shorter lead times.
- Retail Chains:Private-label product development teams source through ingredient distributors with technical support for label-friendly claims.
- Private Label Brands:Emerging clean-label startups access gellan through e-commerce platforms and specialty ingredient marketplaces.
Food manufacturers lock the majority of long-term supply agreements; private label brands are gaining share fastest.
Form:
Physical presentation determines handling economics, shelf stability, and integration speed into production environments.
- Powder:Spray-dried, free-flowing particles with extended ambient stability and direct dry-blending compatibility. Powder dominates industrial procurement in the United States and China due to logistics efficiency and dosing precision.
- Granules:Agglomerated particles reducing dust generation and improving dispersion in high-shear mixing systems.
- Gel:Pre-hydrated concentrated suspensions eliminating dissolution steps for small-batch processors.
- Liquid:Ready-to-use solutions for beverage manufacturers with continuous processing lines and automated dosing.
Powder form commands the largest volume commitments; liquid dispersions are climbing the fastest in beverage sector adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors fermentation capacity expansion for food-grade gellan gum, with Yangtze River Delta bioprocess facilities supplying hydrocolloid stabilizers to plant-based dairy formulators across Asia-Pacific and European export markets.
United States
California and New York clusters drive clean-label beverage formulation demand. FDA 21 CFR 172.665 governs additive safety thresholds and labeling requirements. CP Kelco leverages integrated fermentation capacity in San Diego to serve oat milk processors requiring thermal-stable suspension systems.
China
Domestic plant-based yogurt manufacturers scale gellan adoption for protein stabilization. SAMR enforces GB standards for microbial polysaccharide purity in food processing. Shandong Province fermentation operators supply both high-acyl and low-acyl grades to bakery and confectionery exporters.
Germany
European dairy alternative brands specify gellan to replace carrageenan in clean-label positioning. EU Green Deal mandates accelerate sustainable feedstock certification across supplier networks. Jungbunzlauer anchors hydrocolloid blending operations in Basel to serve German and French formulators.
India
Maharashtra and Gujarat food manufacturers seek imported gellan ahead of stricter FSSAI additive disclosure rules. BIS certification requirements control market access for hydrocolloid imports. Mumbai-based plant-based dairy startups negotiate direct procurement from fermentation operators to bypass distributor markups.
Food-Grade Gellan Gum Market Vendor Landscape
Premium-margin players sit above commodity-margin players across fermentation integration depth, with integrated bioprocess operators commanding supply security premiums while toll-dependent compounders compete on formulation service speed. Three integrated specialists dominate commercial-scale Sphingomonas elodea production globally. Regional blending houses and specialty distributors occupy mid-tier positions with shorter lead times but higher per-kilogram costs. Capacity expansion and backward integration into fermentation feedstock sourcing represent the dominant competitive moves.
Among North American integrated operators, CP Kelco exemplifies the fermentation-anchored archetype with captive bioprocess infrastructure. Jungbunzlauer represents the European distribution-specialist model with hydrocolloid blending capabilities. Ingredion Incorporated occupies a position bridging clean-label starch portfolios with gum-based stabilizer extensions for plant-based dessert applications.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Dancheng Caixin Sugar Industry Co. Ltd. |
| CP Kelco |
| Hebei Xinhe Biochemical Co. Ltd. |
| Fufeng Group |
| Jungbunzlauer |
| Cargill Incorporated |
| Hawkins Watts |
| DowDuPont |
| Others |
Supply Flow & Price Mechanics
Aerobic bioprocess engineering talent concentrates in legacy pharmaceutical and enzyme production hubs across the United States and Germany, and this workforce scarcity widens spreads between premium fermentation-grade supply and commodity blending tiers. Labor-cost differentials between integrated Sphingomonas elodea operators and toll-dependent compounders translate directly into pricing-tier spreads for high-acyl and low-acyl gellan grades.
Pricing Analysis
Suspension performance in UHT-processed oat milk serves as the value-based pricing anchor, with beverage manufacturers paying premiums for batch-to-batch viscosity consistency. Three-tier pricing structure across premium, standard, and economy levels separates certified low-acyl fermentation supply from regional blending house output and carrageenan substitutes. Cost compression in economy tiers is intensifying because glucose and yeast extract feedstock prices fluctuate with corn and sugar beet harvest cycles. Private-label dessert processors show highest price sensitivity, while multinational dairy alternative brands prioritize supply security over per-kilogram cost.
Supply Chain Analysis
Dual-sourcing requirements from European clean-label brands mandate multi-supplier qualification for both high-acyl and low-acyl grades, compressing single-source relationships. Commercial-scale production clusters in the United States, China, and Germany anchor global supply. Fermentation draws from corn-derived glucose, yeast extract, and alkaline deacylation reagents. Single-source vulnerability concentrates in Sphingomonas elodea strain banks held by integrated bioprocess operators. Distribution runs through regional hydrocolloid blending houses in Basel and direct procurement platforms for mid-scale North American processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food-grade gellan gum operates as a supply-constrained market where fermentation scale-up technician scarcity props pricing for integrated operators. Capacity bottlenecks in aerobic bioprocess engineering limit expansion velocity, sustaining margin premiums for captive production assets.
For Market Incumbents: Acquire fermentation feedstock sourcing infrastructure to secure margin predictability against glucose price volatility. Deepen backward integration into corn processing and yeast extract supply to defend against carrageenan substitution in cost-sensitive private-label segments. Lock multi-year offtake agreements with European dairy alternative brands ahead of EFSA novel food evaluation timeline extensions. For New Entrants and Emerging Players: Mid-scale plant-based yogurt manufacturers in California and New York represent an underserved buyer archetype seeking direct procurement relationships bypassing distributor markups. Precision fermentation convergence for cell-cultured protein beverages offers a white-space application requiring novel neutral-pH suspension systems. E-commerce ingredient platforms provide the most penetrable go-to-market angle for rapid qualification cycles. For Investors and Strategic Acquirers: Re-rating potential sits with integrated bioprocess operators given EU Green Deal sustainable feedstock certification requirements tightening across European supply chains. Long-term viability over a five-to-ten year horizon favors fermentation-anchored specialists with captive Sphingomonas elodea capacity over toll-dependent compounders. Watch dual acyl certification timeline compression as the inflection indicator for multi-application product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstock | Corn processing and yeast extract sourcing secures margin predictability against harvest cycle volatility. |
| Dual Acyl Grade Certification Investment | Simultaneous high-acyl and low-acyl approvals accelerate multi-application product launches in regulated markets. |
| Direct-to-Manufacturer E-Commerce Platform | Bypassing regional blending houses captures mid-scale bakery and confectionery procurement shifts. |
| Continuous Fermentation Process Intensification | Real-time rheology monitoring reduces batch-to-batch variation for UHT beverage suspension systems. |
| EU Green Deal Feedstock Certification | Sustainable sourcing credentials unlock premium positioning with European dairy alternative formulators. |
Methodological Framework
Trade databases, fermentation industry association publications, and regulatory filing repositories formed the secondary backbone for this analysis. Primary interviews with bioprocess engineering directors, hydrocolloid procurement leads at multinational food manufacturers, technical R&D managers at plant-based dairy startups, and distribution channel partners in European blending operations complemented secondary validation. Bottom-up segmentation modeling and top-down macroeconomic trend analysis enabled cross-verification of volume and value estimates.
Historical trendline analysis of acyl grade production volumes and application-specific pricing spreads anchored the forecast framework. Segmentation dimensions modeled include acyl substitution pattern, physical form, end-use application, and customer procurement scale across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating plant-based beverage adoption rates and clean-label regulatory tightening. Fermentation capacity utilization rates and EFSA approval timeline assumptions served as industry-specific forecast inputs.
Revisions become necessary when dual acyl certification timelines extend beyond modeled assumptions or when glucose feedstock price volatility exceeds historical bands. Forecasts reflect documented assumptions about EU Green Deal implementation velocity and SAMR GB standard harmonization progress. Deviation in precision fermentation convergence timelines for cell-cultured protein applications would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Roast Flavoring Market
Flavorings and Food Additives
Savory Extract Market
Flavorings and Food Additives
Citrus Concentrate Market
Flavorings and Food Additives
Africa Food Colorants Market
Flavorings and Food Additives
Smoked Condensates Market
Flavorings and Food Additives
Global Floral Flavors Market
Flavorings and Food Additives
South America Flavors and Fragrances Market
Flavorings and Food Additives
Maple Extracts Market
Flavorings and Food Additives
Oryzanol Market
Flavorings and Food Additives
Natural Flavor Extract Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
Sour Flavor Ingredient Market
Flavorings and Food Additives
Blueberry Extract Market
Flavorings and Food Additives
Global Anthocyanin Market
Flavorings and Food Additives
Pumpkin Spice Products Market
Flavorings and Food Additives
Flavoring Oil Market