
 Licorice Extract Market | 2026-2036
Licorice Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Licorice Extract Market Intelligence
The capital-intensity divergence between solvent-extraction specialists and root-sourcing traders is unwinding competitive stability across the licorice extract value chain. MAFCO Worldwide LLC leverages captive farming partnerships in Afghanistan and Azerbaijan to secure raw root supply. Norevo GmbH sustains pharmaceutical-grade certification across its Hamburg processing campus. Sepidan Osareh Jonoob Co. dominates Iran's glycyrrhizin concentrate exports through vertical control of Fars Province harvests.
Licorice extract comprises glycyrrhizic acid, flavonoids, and coumarins derived from Glycyrrhiza glabra and Glycyrrhiza uralensis roots via aqueous or ethanol extraction, yielding standardized potencies for industrial formulation. Powdered licorice leads volume throughput in food and beverage applications where flavor masking and sweetening functions command stable offtake, while liquid glycerin extracts capture expanding cosmetics demand for melanin-inhibiting and anti-inflammatory actives. Pharmaceutical-grade extracts retain the highest margin pools due to pharmacopeial compliance burdens and API registration requirements.
FDA botanical drug guidance, EMA herbal monograph standards, and Iran's national standardization institute collectively elevate extraction protocol rigor and traceability mandates. These frameworks compel processors to document geographic origin, harvest batch testing, and residual solvent thresholds as conditions of market access. Stakeholders must monitor evolving pharmacopeial alignment between European and Asian regulatory regimes to anticipate certification cost shifts and qualification timeline extensions.
Market Dynamics
EMA's tightened botanical drug guidelines are forcing pharmaceutical-grade extractors to rebuild purification protocols while Iranian root harvests face mounting climate volatility.
Growth Catalysts
- Pharmaceutical API demand:German formulators are scaling glycyrrhizin procurement as EMA elevates extract purity requirements for botanical drug submissions.
- Cosmetics actives expansion:Melanin-inhibiting and anti-inflammatory properties in liquid glycerin extracts are capturing formulation contracts from skincare manufacturers.
- Fars Province cultivation clusters:Traditional harvest concentration in Iran feeds processing contracts across European and Asian contract manufacturers.
Market Restraints
- Root supply concentration:Afghan and Azerbaijani farming partnerships face geopolitical disruption risk that threatens captive raw material security.
- Pharmacopeial compliance costs:FDA botanical drug guidance and EMA herbal monograph standards impose documentation and testing burdens that squeeze processor margins.
- Residual solvent thresholds:Aqueous and ethanol extraction methods must meet tightening purity limits that disqualify legacy equipment configurations.
Strategic Opportunities
- Underpenetrated nutraceutical channels:Functional food formulators in North America remain underserved by glycyrrhizin concentrate suppliers holding pharmaceutical certification.
- Regulatory tailwind from CSRD:EU corporate sustainability reporting mandates favor traceable supply chains where geographic origin documentation already exists.
- Clean-label sweetener substitution:Natural flavor masking applications in beverage formulation are displacing artificial alternatives as consumer preference shifts.
Industry Challenges
- Analytical chemist scarcity:Pharmacopeial batch testing and residual solvent verification require specialized talent pools that processors struggle to staff.
- Harvest-to-certificate timeline compression:EMA qualification extensions and geographic origin documentation demands are elongating new supplier onboarding cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Licorice Extract Market |
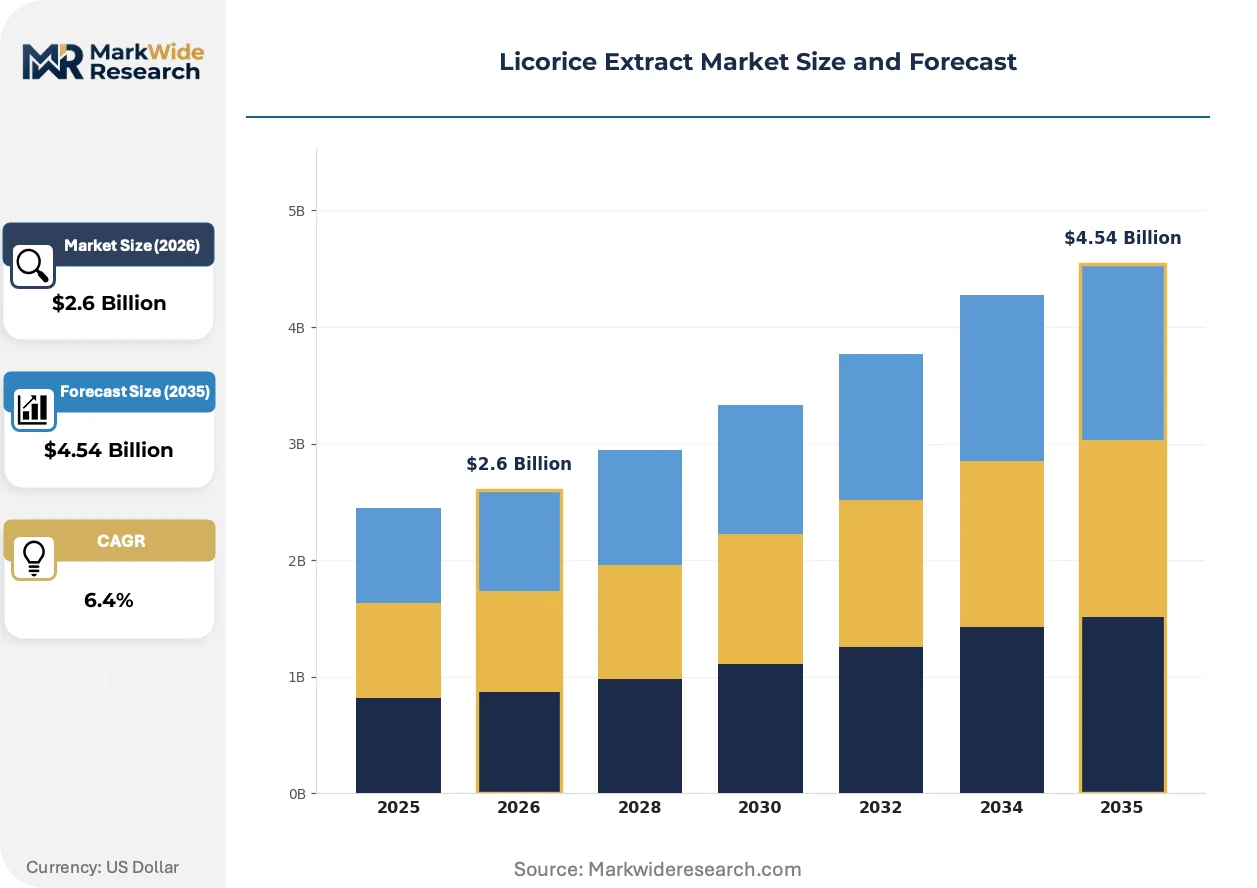
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $4.54 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Licorice Extract, Powdered Licorice, Liquid Licorice, Glycerin Licorice Application: Pharmaceuticals, Food & Beverage, Cosmetics, Nutraceuticals Form: Whole Root, Extracts, Concentrates, Infusions End User: Food Manufacturers, Cosmetic Companies, Pharmacies, Herbalists |
| Companies Covered | MAFCO Worldwide LLC, Norevo GmbH, FC Licorice, Sepidan Osareh Jonoob Co., Zagros Licorice Co., Maruzen Pharmaceuticals Co., Ltd., C.E. Roeper, VPL Chemicals, Aushadhi Herbal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Licorice Extract Market Strategic Shifts & Innovations
Extraction technology and regulatory traceability frameworks are reshaping competitive position in licorice processing, with purity verification and sustainable sourcing emerging as primary differentiation vectors.
Supercritical CO2 extraction is decomposing the traditional solvent-based processing hierarchy by eliminating residual solvent compliance risks entirely. Pharmaceutical formulators in Germany and Switzerland are adopting this method for high-margin API production despite higher capex requirements. The technology is decomposing cost structures for mid-tier processors who cannot amortize equipment upgrades against contract volumes.
REACH registration requirements for botanical substances are forcing European processors to submit full toxicological dossiers for glycyrrhizin concentrates previously traded under generic classifications. This regulatory burden is consolidating formulation supply relationships toward certified processors with dedicated regulatory affairs functions. Food and beverage applications face reduced compliance exposure compared to pharmaceutical segments, creating a two-tier market access structure.
Buyers are consolidating procurement relationships around processors offering integrated origin documentation and batch-level testing. Direct contracting with Fars Province harvest clusters is displacing multi-layered trader networks for European pharmaceutical manufacturers. This pattern is most visible in German API procurement, where EMA qualification timelines reward pre-qualified supplier relationships over spot-market sourcing.
Licorice Extract Market Segmentation
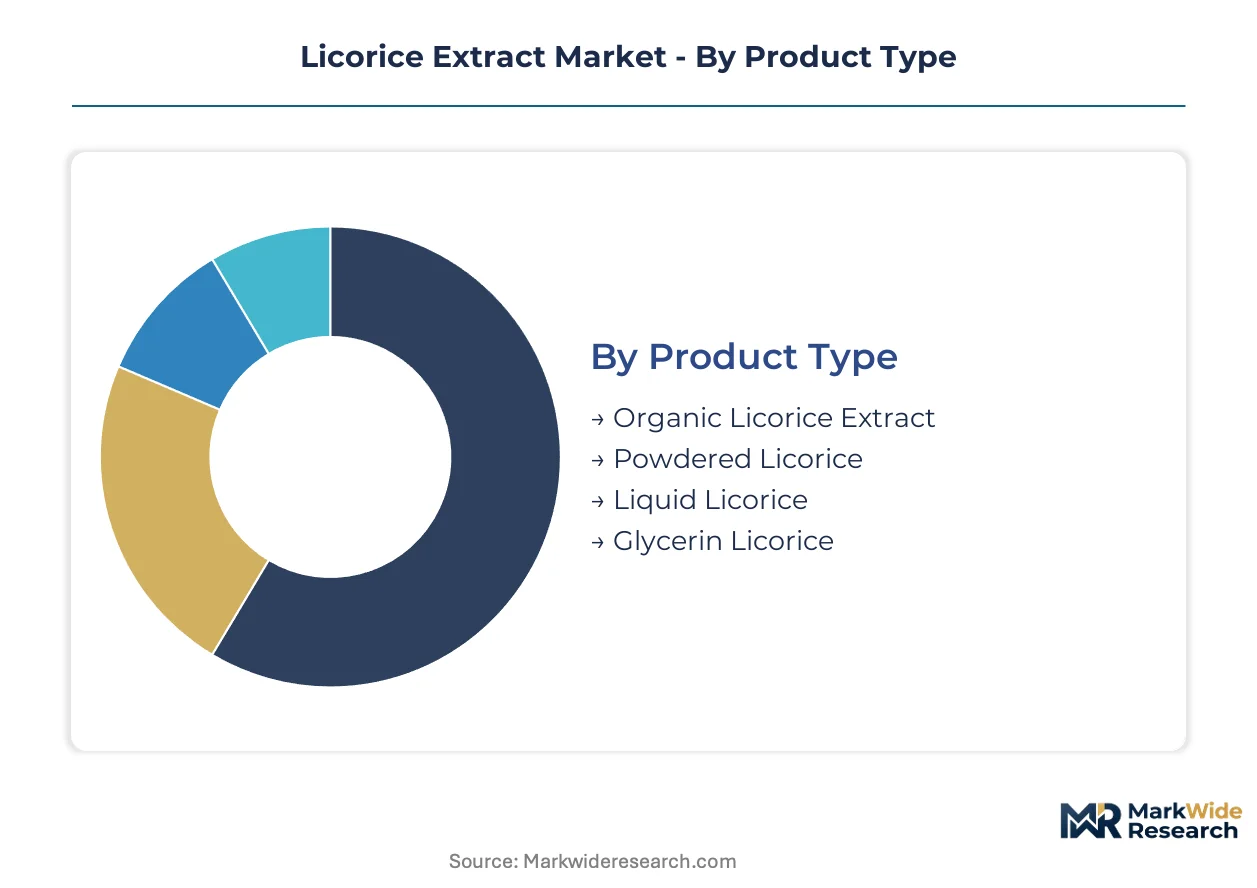
Licorice extract segmentation reveals divergent purity requirements and margin structures across pharmaceutical, food, and cosmetic channels. Each category carries distinct regulatory burdens that reshape competitive positioning among processors.
Product Type:
Substitution pressure from synthetic sweeteners and artificial flavorants weighs most heavily on commodity-grade formats, while certified organic and pharmaceutical-grade extracts maintain defensive moats through regulatory compliance.
- Powdered Licorice:Spray-dried aqueous extract standardized to glycyrrhizic acid content between 3% and 15%. Food and beverage manufacturers in Germany and Iran source this format for confectionery and beverage flavor masking where cost efficiency dominates procurement criteria.
- Liquid Licorice:Aqueous or ethanol-based solutions with adjustable viscosity for industrial dosing. Cosmetics formulators in Switzerland and France are scaling procurement for melanin-inhibiting skincare actives, though residual solvent thresholds under REACH registration impose qualification delays.
- Organic Licorice Extract:Certified organic aqueous extraction from Glycyrrhiza glabra root meeting EU organic regulation standards. Supply concentrates in Fars Province cultivation clusters with documented harvest batch traceability.
- Glycerin Licorice:Propylene glycol or glycerin-based extraction yielding humectant-compatible solutions for topical formulation. Cosmetic contract manufacturers favor this format for emulsion stability.
Powdered licorice anchors the volume base while liquid licorice gains share at the steepest rate.
Application:
Cost tier stratification separates pharmaceutical-grade extractors carrying pharmacopeial compliance burdens from food-grade processors competing on throughput efficiency.
- Pharmaceuticals:Glycyrrhizin concentrates meeting pharmacopeial monographs for API formulation and botanical drug submissions. EMA tightened guidelines are forcing German formulators to rebuild purification protocols and extend supplier qualification timelines.
- Cosmetics:Standardized extracts for anti-inflammatory and skin-brightening actives in premium skincare. Formulators in France and Switzerland are displacing synthetic alternatives with natural glycyrrhizin derivatives.
- Food & Beverage:Flavor masking and natural sweetening applications in confectionery and beverages. Clean-label substitution trends favor licorice over artificial alternatives in North American functional food channels.
- Nutraceuticals:Dietary supplement formulations targeting adrenal support and digestive health. This segment remains underpenetrated by pharmaceutical-certified suppliers in North American markets.
Pharmaceuticals command the highest margin tier while cosmetics demonstrates the steepest expansion trajectory.
Form:
Supply concentration in Iranian root harvesting clusters shapes availability across downstream processing formats.
- Extracts:Processed aqueous or ethanol solutions ready for industrial formulation. This format dominates pharmaceutical and cosmetic contract manufacturing where standardized potency simplifies quality control.
- Concentrates:High-potency glycyrrhizin preparations exceeding 20% purity for API production. German pharmaceutical formulators are scaling procurement as EMA elevates purity requirements.
- Whole Root:Dried Glycyrrhiza glabra or Glycyrrhiza uralensis root for traditional preparation and limited industrial use. Traditional medicine practitioners in Iran and China maintain stable offtake.
- Infusions:Pre-prepared aqueous solutions for immediate use in beverage and herbal applications. Limited industrial scale due to perishability constraints.
Extracts anchor the volume base while concentrates gain share at the steepest rate.
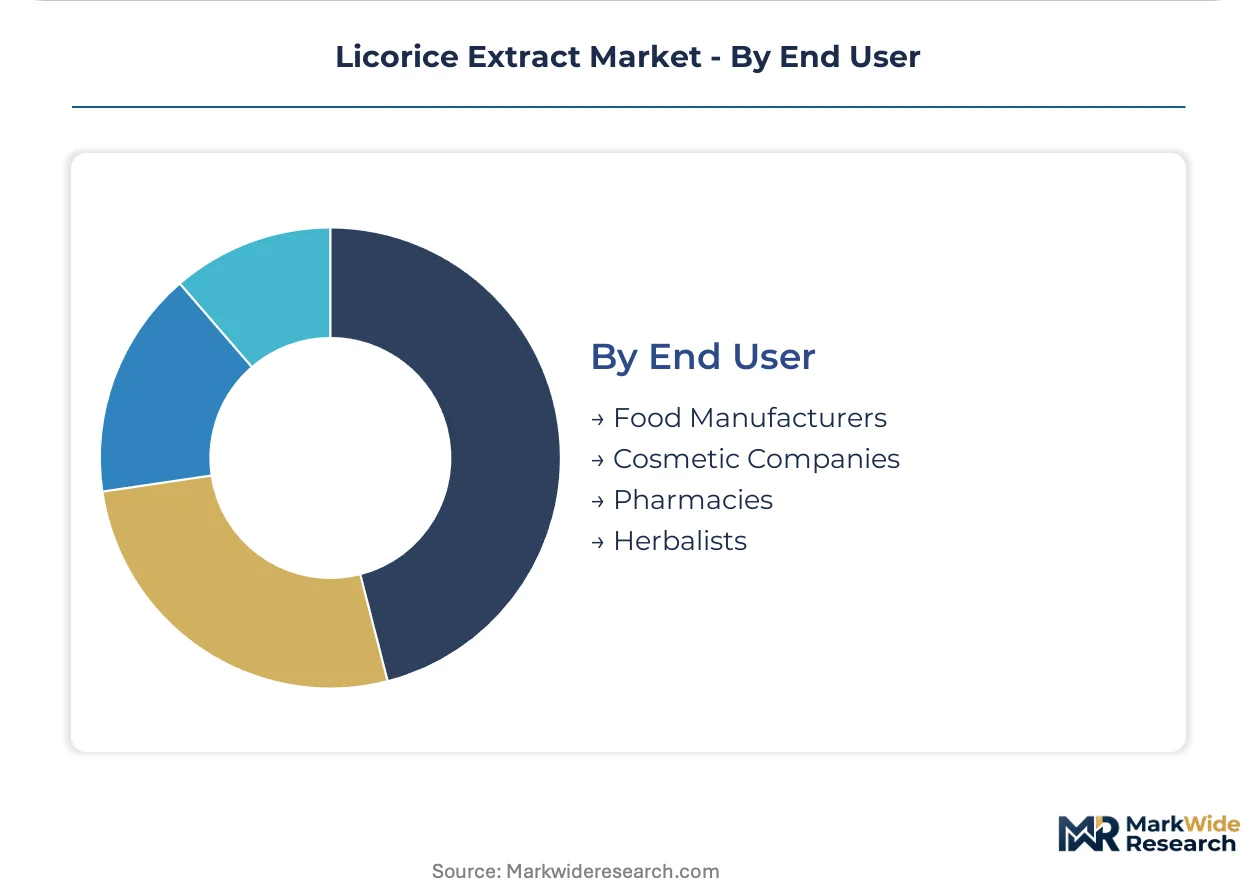
End User:
Customer type determines certification requirements, with pharmaceutical and cosmetic buyers demanding geographic origin documentation that trader networks cannot supply.
- Cosmetic Companies:Skincare and personal care manufacturers sourcing melanin-inhibiting and anti-inflammatory actives. Swiss and French formulators are consolidating procurement around processors with integrated Fars Province origin documentation.
- Food Manufacturers:Confectionery and beverage producers utilizing licorice for flavor masking and natural sweetening. This buyer segment faces reduced compliance exposure compared to pharmaceutical channels.
- Pharmacies:Compounding operations and botanical drug preparation requiring pharmacopeial-grade materials. EMA qualification timelines reward pre-certified supplier relationships.
- Herbalists:Traditional medicine practitioners sourcing whole root and basic extracts. Demand concentrates in Iran and China with limited export orientation.
Food manufacturers anchor the volume base while cosmetic companies gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across buyer segments. Food manufacturers in Germany accept premium pricing for certified extracts, while commodity traders in China face margin compression from synthetic sweetener substitution.
Germany
Pharmaceutical formulators in Hamburg and Frankfurt are scaling glycyrrhizin concentrate procurement as EMA's tightened botanical drug guidelines elevate purity requirements. The country's national pharmaceutical regulator enforces documentation burdens that disqualify spot-market sourcing. Processing clusters along the Elbe River concentrate pharmaceutical-grade extraction capacity serving European API manufacturers.
Iran
Traditional cultivation in Fars Province feeds contract manufacturing demand from Swiss and French cosmetic formulators seeking melanin-inhibiting actives. Iran's national standardization institute mandates harvest batch testing that processors must integrate into export documentation. Sepidan Osareh Jonoob Co. anchors vertical control of provincial harvest clusters, displacing multi-layered trader networks.
China
Cosmetics manufacturers in Shanghai and Guangzhou are expanding procurement of liquid glycerin extracts for skin-brightening formulations. NMPA's botanical substance registration requirements impose toxicological dossier burdens previously absent from generic trade classifications. Yangtze River Delta processing hubs concentrate mid-tier extraction capacity competing on throughput efficiency.
Switzerland
Swissmedic's pharmacopeial standards attract premium-tier glycyrrhizin concentrate imports from Iranian and Afghan farming partnerships. The country's pharmaceutical regulator maintains alignment with EMA herbal monograph standards that extend supplier qualification timelines. Basel-area formulators consolidate procurement around processors offering integrated Fars Province origin documentation.
United States
Functional food formulators in California and New Jersey remain underserved by pharmaceutical-certified suppliers holding glycyrrhizin concentrate capacity. FDA botanical drug guidance imposes residual solvent thresholds that disqualify legacy extraction equipment configurations. Pacific Coast beverage manufacturers are displacing artificial sweeteners with natural licorice flavor masking applications.
Licorice Extract Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with vertical control of root supply separating the two. Captive farming partnerships in Afghanistan and Azerbaijan distinguish the upper tier from traders dependent on spot-market sourcing. Three archetypes dominate: pharmaceutical-grade certifiers with regulatory affairs functions, solvent-extraction specialists optimizing throughput efficiency, and root-sourcing traders facing margin compression from purity documentation demands. Competitive moves center on backward integration into harvest clusters and capacity expansion of supercritical CO2 extraction lines.
Within the integrated-leader archetype, MAFCO Worldwide LLC and Sepidan Osareh Jonoob Co. exemplify upstream control strategies, with the former representing North American captive supply models and the latter anchoring Iranian vertical integration. Norevo GmbH occupies a position within the pharmaceutical-certifier tier, reflecting European regulatory compliance specialization. These three entities illustrate how geographic origin documentation and pharmacopeial batch testing capabilities are consolidating formulation supply relationships.
| Leading Market Players |
|---|
| MAFCO Worldwide LLC |
| Norevo GmbH |
| FC Licorice |
| Sepidan Osareh Jonoob Co. |
| Zagros Licorice Co. |
| Maruzen Pharmaceuticals Co., Ltd. |
| C.E. Roeper |
| VPL Chemicals |
| Aushadhi Herbal |
| Others |
Cost & Logistics Intelligence
Synthetic sweetener displacement in North American beverage formulation simultaneously shifts procurement geography toward Fars Province harvest clusters and compresses margin structures for traders lacking origin documentation capabilities. This substitution dynamic rewards processors with integrated supply chains while penalizing spot-market intermediaries.
Pricing Analysis
Certification-grade service bundling drives lifetime value for pharmaceutical extractors serving EMA-compliant formulators. Three-tier pricing structure across pharmaceutical, organic, and commodity grades separates EMA-registered suppliers from food-grade processors. Cost compression in commodity powdered formats intensifies because synthetic alternatives capture beverage sweetening contracts. Food manufacturers exhibit highest price sensitivity while German API formulators accept pharmacopeial premiums.
Supply Chain Analysis
Harvest-to-processor lead times elongate as EMA documentation requirements add batch-testing stages. Geographic concentration centers on Iran, Afghanistan, and Azerbaijan for root supply. Downstream processing draws from aqueous extraction equipment, ethanol recovery systems, and supercritical CO2 lines. Single-source vulnerability runs through Fars Province climate exposure. Distribution runs through direct contracts with Swiss and German pharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against synthetic sweetener and artificial flavorant incursions in food and beverage channels. Incumbents must navigate clean-label preference shifts that threaten commodity-grade extract positions.
For Market Incumbents: Shield pharmaceutical-grade margins by accelerating supercritical CO2 capacity additions in Hamburg and Basel processing clusters. Secure backward integration into Afghan farming partnerships before geopolitical disruption materializes. EMA qualification timeline extensions favor pre-certified supplier relationships over spot-market competition. For New Entrants and Emerging Players: FDA botanical drug certification fast-track opens white-space access in North American nutraceutical channels underserved by European pharmaceutical-certified suppliers. Target California functional food formulators with glycyrrhizin concentrate offerings. Lead with clean-label positioning against artificial sweetener incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with solvent-extraction specialists lacking supercritical CO2 upgrade capital. Five-to-ten year viability favors processors with captive root supply and dedicated regulatory affairs functions. Monitor EMA-REACH pharmacopeial alignment negotiations as certification cost inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Eliminates residual solvent compliance risks for German API manufacturers. |
| Backward Integration into Fars Province Harvest Clusters | Secures geographic origin documentation required by Swissmedic standards. |
| Pharmaceutical-Grade Certification Investment | Unlocks EMA botanical drug submission pathways for glycyrrhizin concentrates. |
| Clean-Label Sweetener Repositioning | Captures North American beverage formulation contracts from artificial alternatives. |
| Long-Term Supply Agreement with German Formulators | Locks in offtake volumes ahead of EMA qualification timeline extensions. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across extraction technology specialists, pharmaceutical regulatory affairs directors, cosmetic formulation chemists, and Fars Province agricultural cooperatives. Secondary validation drew from EMA herbal monograph databases, FDA botanical drug guidance filings, Iran's national standardization institute harvest records, and REACH registration dossiers. Bottom-up volume triangulation against top-down value estimates anchored forecast reliability.
Across the analysis window, projections modeled product type segmentation by purity grade, application tier by regulatory burden, and extraction technology by capex intensity. CAGRs derived from segment-level growth rate blending weighted by revenue contribution. Forecast inputs incorporated EMA guideline revision schedules and supercritical CO2 equipment adoption curves.
Underlying assumptions cover pharmacopeial alignment stability and Iranian harvest yield consistency, with deviation risk concentrated in climate volatility and geopolitical supply disruption. Revision becomes warranted when EMA-FDA regulatory divergence crosses implementation threshold delays.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Cholic Acid Market
Flavorings and Food Additives
Sour Flavor Ingredient Market
Flavorings and Food Additives
Tangerine Extract Market
Flavorings and Food Additives
United States Food Flavor Market
Flavorings and Food Additives
Coloring Foodstuffs Market
Flavorings and Food Additives
Global Floral Flavors Market
Flavorings and Food Additives
Global Artichoke Extract Market
Flavorings and Food Additives
Food Flavors & Flavor Enhancers Market
Flavorings and Food Additives
Africa Food Flavor Market
Flavorings and Food Additives
Taste Modulators Market
Flavorings and Food Additives
Soy Sauce Powder Market
Flavorings and Food Additives
Pine Bark Extract Market
Flavorings and Food Additives
Flavoring Agents Market
Flavorings and Food Additives
Flavored Salt Market
Flavorings and Food Additives
Chicory Products Market
Flavorings and Food Additives
Russia Food Colorants Market