
 Feed Flavors, Sweeteners and Natural Enhancers Market | 2026-2036
Feed Flavors, Sweeteners and Natural Enhancers Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Flavors, Sweeteners and Natural Enhancers Market Insights
FAMI-QS certification is rotating the competitive set as non-compliant suppliers lose access to major compound feed manufacturers. Cargill leverages its oilseed processing footprint to backward-integrate into natural flavor precursor supply. ADM sustains volume leadership through its global essential oils and extractives network. Kemin Industries differentiates via synthetic-free antioxidant-flavor combinations for heat-stressed livestock.
Feed flavors, sweeteners and natural enhancers comprise sensory-active and bioactive compounds—typically essential oils, oleoresins, glycosides, and fermentation-derived metabolites at inclusion rates of 0.01–0.5%—formulated to elevate feed intake, mask anti-nutritional bitterness, and stabilize rumen or gut microbiome function. Palatability enhancers command the widest volume base across ruminant and swine diets, while nutritional enhancers extract premium pricing from aquaculture and pet food channels where omega-3 masking and growth-promoting claims justify higher dosing costs. Powder and liquid forms split the market by climate: humid tropical zones favor dry carriers, while temperate zones with automated liquid dosing systems absorb higher-concentration suspensions.
The European Food Safety Authority (EFSA) and the U.S. Food and Drug Administration (FDA) jointly constrain novel additive approvals through divergent safety assessment timelines, forcing dual-track regulatory investment. China's Ministry of Agriculture and Rural Affairs (MARA) and the EU's Feed Hygiene Regulation (183/2005/EC) impose traceability mandates that favor integrated producers with captive analytical laboratories over trading-house intermediaries. Stakeholders must track evolving maximum residue limits for botanical actives in export-bound meat and dairy to avoid shipment detention at destination ports.
Market Dynamics
F-Gas Regulation compliance costs are compressing synthetic flavorant margins across European compound feed manufacturing, redirecting formulation investment toward botanical extraction and fermentation-derived alternatives.
Growth Catalysts
- EU F-Gas Regulation phase-down:Synthetic hydrofluorocarbon-based carriers face quota restrictions, accelerating botanical solvent adoption in flavor extraction processes. German and Dutch feed compounders now specify natural carrier systems in procurement tenders.
- Precision livestock farming uptake:Automated feeding systems in Brazilian and Vietnamese poultry houses require consistent palatability across variable humidity conditions. Sensor-driven intake monitoring validates enhancer ROI through feed conversion ratio documentation.
- Aquaculture feed mill consolidation:Large-scale shrimp and salmon feed producers in China and Norway are standardizing on high-dose nutritional enhancers to differentiate premium product lines and justify omega-3 masking premiums.
Market Restraints
- Essential oil input volatility:Climate-driven harvest variability in Indonesian clove and Indian turmeric regions creates 15-40% price swings for key oleoresin precursors, compressing blender margins.
- Dual-track regulatory investment:EFSA and FDA safety assessment timeline divergence forces additive developers to maintain parallel toxicology dossiers, extending approval cycles and freezing smaller entrants from novel molecule markets.
- Synthetic flavorant substitution threat:Cost-conscious Southeast Asian swine producers continue specifying artificial vanillin and ethyl maltol where regulatory enforcement remains fragmented.
Strategic Opportunities
- Heat-stressed livestock antioxidant-flavor convergence:Synthetic-free formulations combining polyphenol extracts with palatability enhancement capture premium positioning in Australian and Texan cattle feed markets where thermal stress reduces intake.
- EU Feed Hygiene Regulation traceability mandates:Integrated producers with captive analytical laboratories capture compounder contracts from trading-house intermediaries unable to document batch-level botanical provenance.
- Pet food humanization channel expansion:E-commerce direct-to-consumer brands in South Korea and Japan are sourcing custom flavor profiles previously reserved for pharmaceutical applications, opening volume tiers above commodity feed pricing.
Industry Challenges
- FAMI-QS certification timeline compression:Non-compliant suppliers lose access to major compound feed manufacturers within 18-month audit cycles, requiring immediate HACCP system overhauls.
- Maximum residue limit documentation:Export-bound meat and dairy producers must track evolving botanical active thresholds across destination markets to avoid port detention, demanding dedicated regulatory affairs staffing.
- Liquid dosing system integration:Temperate zone automated feed mills face retrofit complexity when shifting from dry carriers to high-concentration suspensions, requiring engineering coordination across equipment OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Flavors, Sweeteners and Natural Enhancers Market |
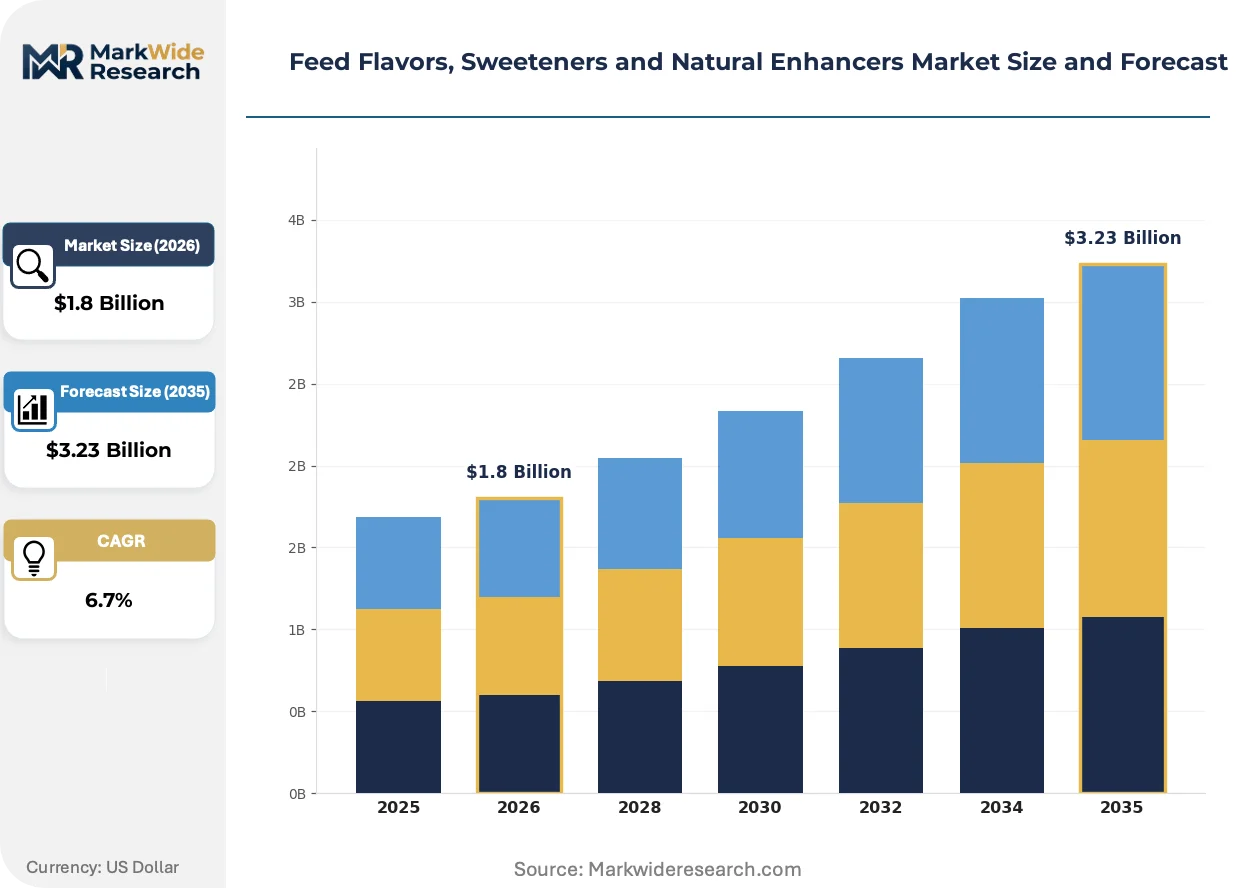
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavoring Agents, Sweetening Agents, Nutritional Enhancers, Palatability Enhancers Form: Liquid, Powder, Granular, Pellet Animal Type: Ruminants, Poultry, Swine, Aquaculture Application: Feed Composition, Animal Health, Nutritional Supplementation, Behavioral Conditioning |
| Companies Covered | Cargill, ADM (Archer Daniels Midland), Evonik Industries, Kemin Industries, DuPont, Givaudan, Symrise, Kerry Group, International Flavors & Fragrances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Flavors, Sweeteners and Natural Enhancers Market Trends and Innovations
Formulation science is converging with microbiome research, creating enhancer categories that modulate gut function while masking bitterness. This dual-functionality is redefining value capture away from pure sensory performance.
Microencapsulation of essential oils is decomposing the traditional trade-off between flavor stability and bioactive release. Poultry integrators in Brazil and Thailand are adopting spray-dried lipid matrix systems at commercial scale. The technology is decomposing commodity oleoresin markets into differentiated tiers based on rumen bypass efficiency and intestinal release kinetics.
REACH authorization requirements for synthetic flavor precursors are tightening substance volume thresholds across EU manufacturing. Chemical suppliers face registration cost escalation for legacy molecules, accelerating withdrawal of mid-tier artificial compounds. Aquaculture feed mills in Norway and Scotland are responding by locking multi-year contracts with botanical extract suppliers before 2026 sunset dates.
Compound feed procurement teams are consolidating supplier panels around integrated producers offering bundled sensory-nutritional solutions. Large swine operations in Denmark and Spain now specify single-source accountability for both palatability and gut health outcomes. This preference shift is most visible in northwestern European markets where feed mill consolidation has concentrated buying power among three-to-five national compounders.
Feed Flavors, Sweeteners and Natural Enhancers Market Segmentation
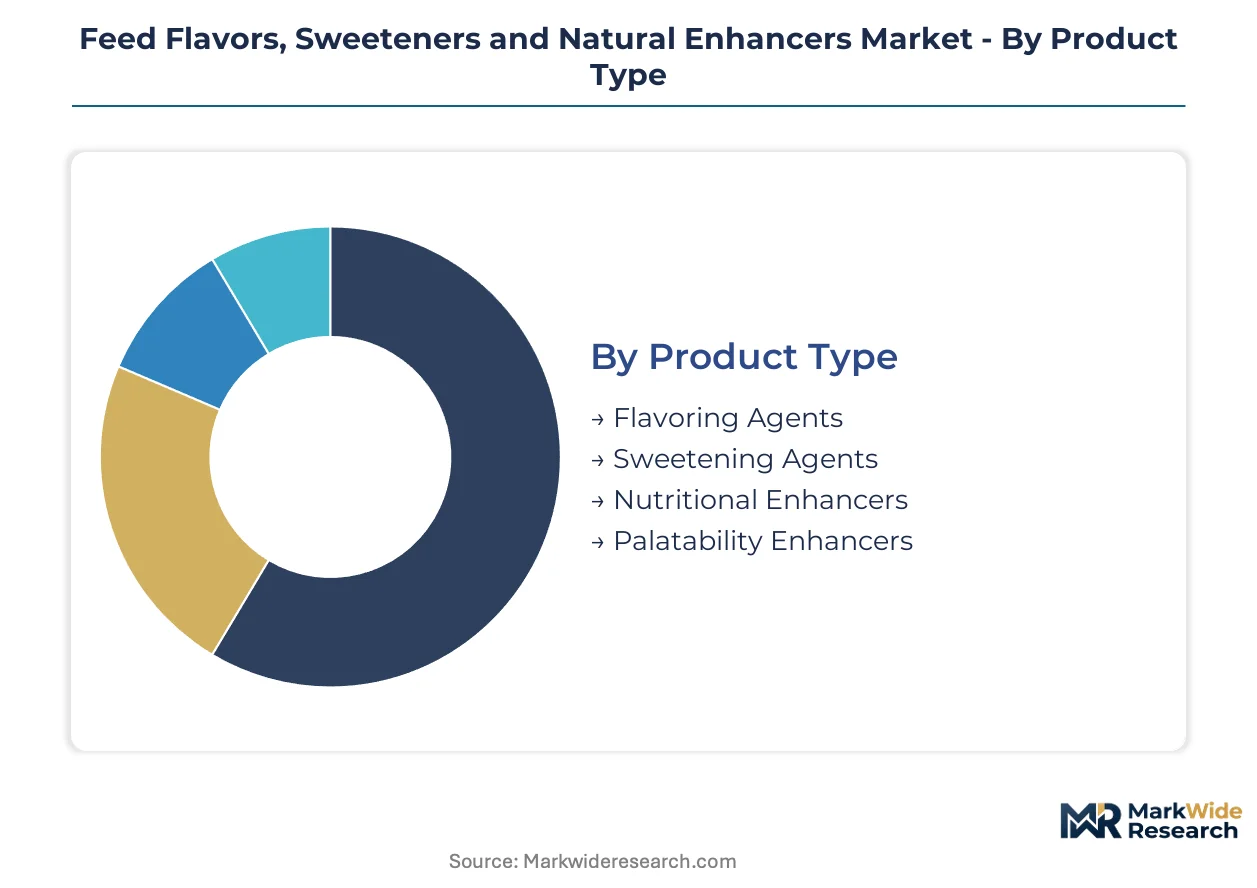
Segmentation in this market tracks divergent regulatory pathways across geographies while mapping how sensory and bioactive functions command distinct price tiers. Each dimension reveals where formulation investment concentrates and where margin compression threatens.
Product Type:
EFSA and FDA safety assessment timelines diverge sharply across these categories, forcing developers to maintain parallel toxicology dossiers for botanical actives versus synthetic molecules.
- Flavoring Agents:Essential oils and oleoresins at 0.01-0.5% inclusion rates mask anti-nutritional bitterness in compound feeds. German and Dutch compounders now specify natural carrier systems in procurement tenders following F-Gas Regulation phase-down quotas on synthetic hydrofluorocarbon carriers.
- Palatability Enhancers:Glycosides and fermentation-derived metabolites elevate feed intake across variable humidity conditions. Brazilian and Vietnamese poultry houses deploy these in automated feeding systems where sensor-driven intake monitoring validates ROI through feed conversion ratio documentation.
- Sweetening Agents:Natural glycoside extracts replace artificial alternatives where regulatory enforcement tightens.
- Nutritional Enhancers:Omega-3 masking and growth-promoting claims justify premium dosing costs in aquaculture channels.
Palatability enhancers handle the majority of throughput; nutritional enhancers are expanding most quickly on share as aquaculture feed mills consolidate.
Form:
Climate-driven infrastructure dictates form selection, with automated liquid dosing systems in temperate zones commanding different supply chain configurations than tropical dry carrier networks.
- Powder:Dry carriers dominate humid tropical zones where moisture stability determines shelf life. Indonesian and Thai feed mills specify powder forms for clove and turmeric oleoresin precursors despite climate-driven harvest volatility creating 15-40% input price swings.
- Liquid:High-concentration suspensions integrate with automated dosing systems in temperate European and North American feed mills. Retrofit complexity when shifting from dry carriers creates engineering coordination demands across equipment OEMs.
- Granular:Intermediate flow properties suit manual dosing in smaller compound feed operations.
- Pellet:Co-extruded forms target rumen bypass efficiency in ruminant applications.
Powder maintains volume leadership across tropical production belts; liquid forms gain share fastest where precision livestock farming automates.
Animal Type:
Species-specific metabolism drives divergent inclusion rates and regulatory residue limits that reshape supplier qualification requirements.
- Poultry:Heat-stressed broiler operations in Australia and Texas drive demand for synthetic-free antioxidant-flavor combinations. Thermal stress reduces intake, creating premium positioning for polyphenol extract formulations that stabilize rumen function while masking bitterness.
- Aquaculture:Shrimp and salmon feed producers in China and Norway standardize on high-dose nutritional enhancers to differentiate premium product lines. MARA traceability mandates favor integrated producers with captive analytical laboratories over trading-house intermediaries.
- Ruminants:Microbiome modulation claims attract investment from dairy-dense regions.
- Swine:Cost-conscious Southeast Asian producers continue artificial vanillin specification where enforcement fragments.
Poultry handles the majority of volume throughput; aquaculture climbs the fastest on value share.
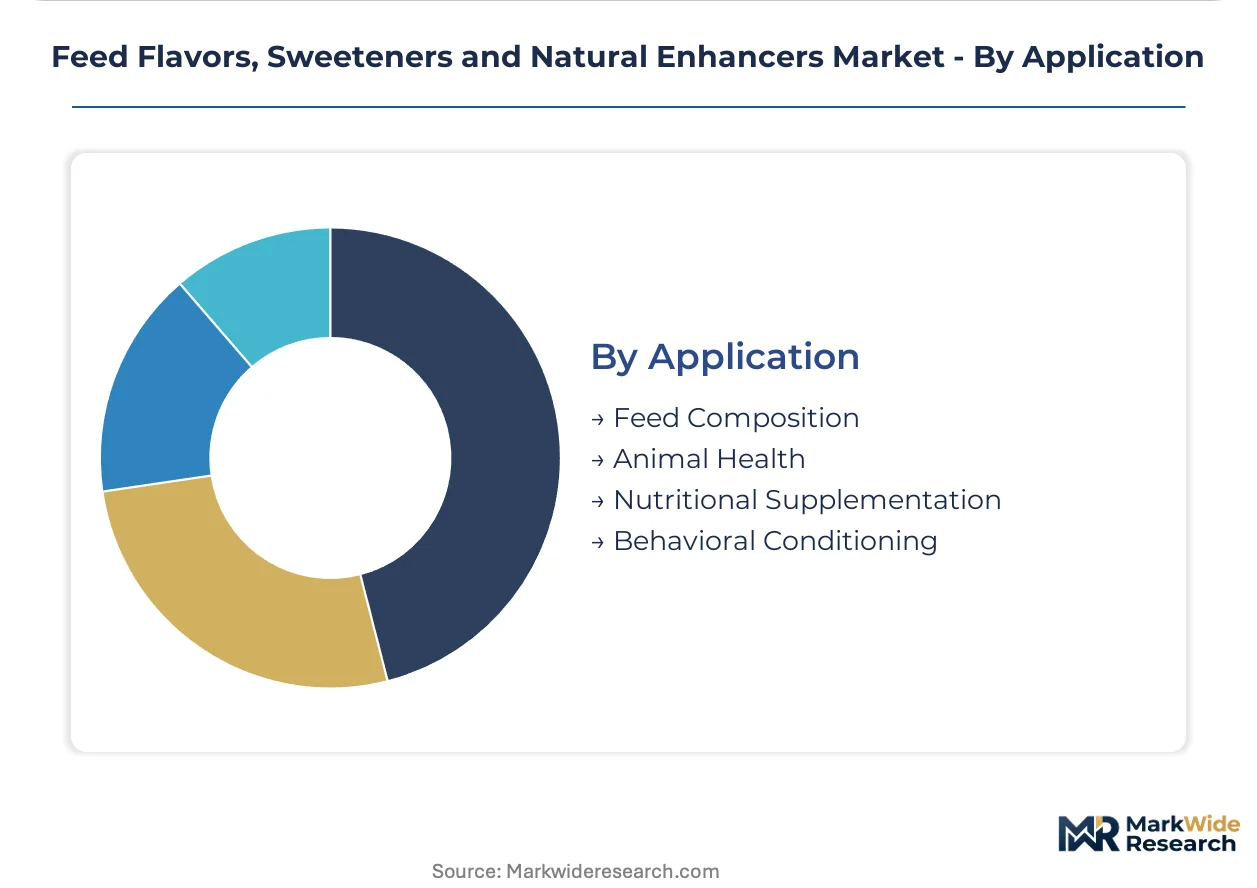
Application:
Outcome-based contracting is consolidating procurement around bundled sensory-nutritional solutions rather than single-function additives.
- Feed Composition:Base formulation integration captures the widest volume base across ruminant and swine diets. Large swine operations in Denmark and Spain now specify single-source accountability for both palatability and gut health outcomes.
- Nutritional Supplementation:Top-dressing and premix channels extract premium pricing where omega-3 masking and growth-promoting claims justify higher dosing costs. Pet food humanization in South Korea and Japan sources custom flavor profiles previously reserved for pharmaceutical applications.
- Animal Health:Veterinary-directed therapeutic nutrition expands in regulated markets.
- Behavioral Conditioning:Precision feeding systems validate enhancer performance through documented intake patterns.
Feed composition handles the majority of throughput; nutritional supplementation is gaining share fastest as pet food and aquaculture premiumize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compound feed manufacturers in Germany, China, Brazil, Norway, and the United States concentrate procurement authority, driving formulation standardization across distinct regulatory and climate zones.
Germany
F-Gas Regulation phase-down quotas redirect procurement toward botanical solvent systems. EFSA traceability mandates under Feed Hygiene Regulation 183/2005/EC favor integrated producers with captive laboratories over intermediaries. The Lower Saxony feed milling corridor now specifies natural carrier systems in compounder tenders.
China
Domestic aquaculture feed mills scale additive procurement for shrimp and salmon operations. MARA imposes batch-level botanical provenance documentation that disadvantages trading-house suppliers. The Yangtze River Delta concentration of feed manufacturers drives standardization on high-dose nutritional enhancers.
Brazil
Poultry integrators expand palatability enhancer deployment to improve feed conversion ratios in automated houses. ANVISA enforcement on residue limits remains fragmented compared to export destination standards. The São Paulo state cluster validates enhancer ROI through sensor-driven intake monitoring systems.
Norway
Aquaculture feed producers lock multi-year contracts with botanical extract suppliers ahead of 2026 REACH authorization deadlines. The country's national pharmaceutical regulator aligns with EFSA timelines on novel additive safety assessments. The Bergen-Stavanger processing corridor differentiates premium product lines through omega-3 masking formulations.
United States
Heat-stressed cattle operations in Texas drive demand for synthetic-free antioxidant-flavor combinations. FDA safety assessment timelines diverge from EFSA, forcing dual-track regulatory investment on developers. The Texas Panhandle feedlot concentration documents thermal stress intake reduction through polyphenol extract formulations.
Feed Flavors, Sweeteners and Natural Enhancers Market Competitive Landscape
Player mix skews toward diversified agricultural processors with oilseed and extractives footprints. Three tiers structure competitive positioning: integrated agribusiness conglomerates with backward integration into natural precursors, specialty chemical houses with fermentation-derived metabolite capabilities, and flavor-science specialists with pharmaceutical-grade formulation expertise. Dominant competitive moves include captive supply chain development for botanical oleoresins and multi-year contract locking ahead of regulatory sunset dates.
Within the integrated agribusiness tier, Cargill and ADM represent archetypes of oilseed-processing footprint leverage into flavor precursor supply. Kemin Industries exemplifies the specialty chemical house model, occupying a position defined by synthetic-free antioxidant-flavor convergence for heat-stressed livestock applications. These three anchors illustrate how procurement consolidation around FAMI-QS-compliant, traceability-documented suppliers rewards scale and captive analytical capability over trading-house intermediaries.
| Leading Market Players |
|---|
| Cargill |
| ADM (Archer Daniels Midland) |
| Evonik Industries |
| Kemin Industries |
| DuPont |
| Givaudan |
| Symrise |
| Kerry Group |
| International Flavors & Fragrances |
| Others |
Pricing and Supply Chain Analysis
Ninety-day clove oleoresin inventory cycles in Indonesian processing hubs concentrate pricing power among integrated extractive houses serving European compound feed manufacturers. This lead-time compression binds botanical harvest volatility directly to contract renegotiation windows, forcing procurement teams to index pricing against spot oleoresin markets while building buffer stocks ahead of monsoon disruptions.
Pricing Analysis
Cost-plus contracts with oleoresin indexation dominate procurement between Indonesian clove processors and German compound feed manufacturers. Price differentiation hinges on FAMI-QS certification tier and captive laboratory traceability documentation. Margins are tightening due to climate-driven harvest variability in Indian turmeric regions. Southeast Asian swine producers exhibit highest price sensitivity, while Norwegian aquaculture feed mills absorb premium pricing for omega-3 masking formulations.
Supply Chain Analysis
Container availability constraints on the Jakarta-Rotterdam trade lane inflate inbound logistics costs for Indonesian oleoresin shipments. Supply concentrates in Indonesia, India, and Vietnam for essential oil precursors, with Brazilian fermentation-derived metabolite capacity expanding. The chain draws from clove bud, turmeric rhizome, and citrus peel feedstocks. Single-source vulnerability persists for heat-stressed livestock polyphenol extracts. Distribution runs through integrated agribusiness conglomerates with backward integration into natural precursor supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized toxicology dossier capabilities for dual-track EFSA-FDA submissions represent the scarcest asset in this market, locking smaller developers out of novel molecule commercialization. Firms possessing captive analytical laboratories and botanical provenance documentation systems command disproportionate procurement access under tightening EU Feed Hygiene Regulation mandates.
For Market Incumbents: Shield market position by accelerating multi-year botanical extract contracts ahead of REACH authorization deadlines, and expand captive supply of clove and turmeric oleoresins through direct plantation partnerships in Indonesia and India. Synthetic flavorant substitution threats from cost-conscious Southeast Asian producers demand certification-tier differentiation through FAMI-QS compliance investments. For New Entrants and Emerging Players: Custom flavor profile development for pet food humanization channels in South Korea and Japan represents the most penetrable service-layer gap, as incumbents under-serve e-commerce direct-to-consumer brands seeking pharmaceutical-grade formulation expertise. Target nutritional supplementation applications where omega-3 masking premiums justify higher dosing costs. Establish go-to-market partnerships with aquaculture feed mill engineering teams in China and Norway. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because divergent EFSA-FDA safety assessment timelines create durable moats for integrated producers with parallel toxicology capabilities. Acquisition targets should exhibit captive analytical laboratory infrastructure and established botanical provenance documentation systems. Watch for F-Gas Regulation enforcement intensity in German procurement tenders as inflection indicator for natural carrier system adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleoresin Supply | Cargill's plantation partnerships in Indonesia secure clove precursor access ahead of quota restrictions. |
| Multi-Year Contract Locking | Norwegian aquaculture feed producers pre-position botanical extract supply before REACH sunset deadlines. |
| FAMI-QS Certification Investment | Non-compliant suppliers lose compounder access within 18-month audit cycles, concentrating procurement panels. |
| Microencapsulation Technology Scale-Up | Spray-dried lipid matrix systems decompose commodity oleoresin markets into rumen-bypass efficiency tiers. |
| Synthetic-Free Formulation Development | Polyphenol extract combinations capture premium positioning in Australian and Texan heat-stressed cattle feed markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA additive safety opinions, FDA Generally Recognized As Safe notifications, and EU Feed Hygiene Regulation compliance databases. Interviews with compound feed procurement directors, botanical extraction plant managers, regulatory affairs specialists at flavor houses, and aquaculture feed mill technical directors inform demand-side validation. Customs trade data for oleoresin imports, FAMI-QS certification registries, and REACH authorization timelines provide supply-side triangulation against bottom-up volume modeling.
Segmentation dimensions modeled include product type, physical form, animal species, and application channel across the analysis window. CAGRs derive from regression analysis of historical inclusion rate trends, feed production forecasts by species, and regulatory-driven substitution elasticities for synthetic versus natural carriers. Industry-specific inputs incorporate climate-driven harvest variability coefficients for Indonesian clove and Indian turmeric regions, and precision livestock farming adoption rates in Brazilian and Vietnamese poultry operations.
Forecasts assume regulatory continuity in EU F-Gas Regulation phase-down schedules and MARA traceability enforcement intensity; material policy shifts would require re-modeling. Essential oil input price volatility, dual-track regulatory timeline divergence, and synthetic flavorant enforcement fragmentation in Southeast Asia represent specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Quillaia Extracts Market
Flavorings and Food Additives
Ylang Ylang Extract Market
Flavorings and Food Additives
Hops Essential Oil Market
Flavorings and Food Additives
Europe Food Flavor Market
Flavorings and Food Additives
Asia-Pacific Flavor and Fragrance Market
Flavorings and Food Additives
Global Natural Food Flavors Market
Flavorings and Food Additives
Lemon Extract Market
Flavorings and Food Additives
United States Food Colorants Market
Flavorings and Food Additives
American Spikenard Extract Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Water Flavoring Drop Market
Flavorings and Food Additives
US Essential Oil Market
Flavorings and Food Additives
Brazil Food Flavor and Enhancer Market
Flavorings and Food Additives
Cheese Flavor Market
Flavorings and Food Additives
Caralluma Extract Market
Flavorings and Food Additives
Oleoresin Market