
 Barley Malt Extract Market | 2026-2036
Barley Malt Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Barley Malt Extract Market Analytics
Brewery demand is decoupling from traditional whole-grain malting as craft and regional brewers seek consistent flavor profiles with lower capital equipment. Malteurop Group leverages its integrated malting network across six continents to supply standardized extracts at scale. Muntons PLC anchors the United Kingdom market through specialized brewing concentrates and food-grade syrups. Rahr Corporation competes in North America with technical support services tied to its extract portfolio.
Barley malt extract is a concentrated sweetener and flavoring agent produced by controlled germination of barley grain followed by mashing, enzymatic conversion, and evaporation, typically containing 65-80% fermentable sugars by dry weight. The product serves brewing, baking, and nutritional applications where standardized enzymatic activity and color development replace variable whole-malt processing. Powder extract commands premium positioning in health food manufacturing due to extended shelf stability and clean-label compatibility. Liquid extract dominates brewery procurement where solubility and batch consistency outweigh logistics costs. Organic and non-GMO quality grades are gaining fastest in European nutraceutical channels as ingredient traceability requirements tighten.
FDA food additive regulations and USDA organic certification standards govern product safety and label claims in the United States, while the EU Green Deal and REACH chemical registration frameworks shape agricultural input sustainability across European supply chains. These regulatory layers elevate compliance costs for smaller processors but create market access barriers that favor established suppliers with dedicated quality infrastructure. Stakeholders must monitor evolving carbon accounting rules for agricultural commodities and assess whether backward integration into barley sourcing or partnership with certified organic growers offers more defensible positioning.
Market Dynamics
The EU Green Deal's Farm to Fork Strategy is compressing sourcing windows for agricultural processors while craft brewers in Germany and the United States accelerate extract adoption to bypass capital-intensive malting infrastructure. This regulatory-demand intersection is restructuring procurement relationships across the value chain.
Growth Catalysts
- EU Farm to Fork Strategy:Sustainability mandates for agricultural inputs are redirecting brewery procurement toward certified organic malt extracts with traceable carbon footprints.
- Specialty brewing concentrates:Craft and regional brewers are deploying liquid extracts to achieve batch-to-batch consistency without investing in traditional malting equipment.
- German brewing heritage clusters:Traditional beer-producing regions are modernizing through extract-based innovation, creating concentrated demand for premium grades.
Market Restraints
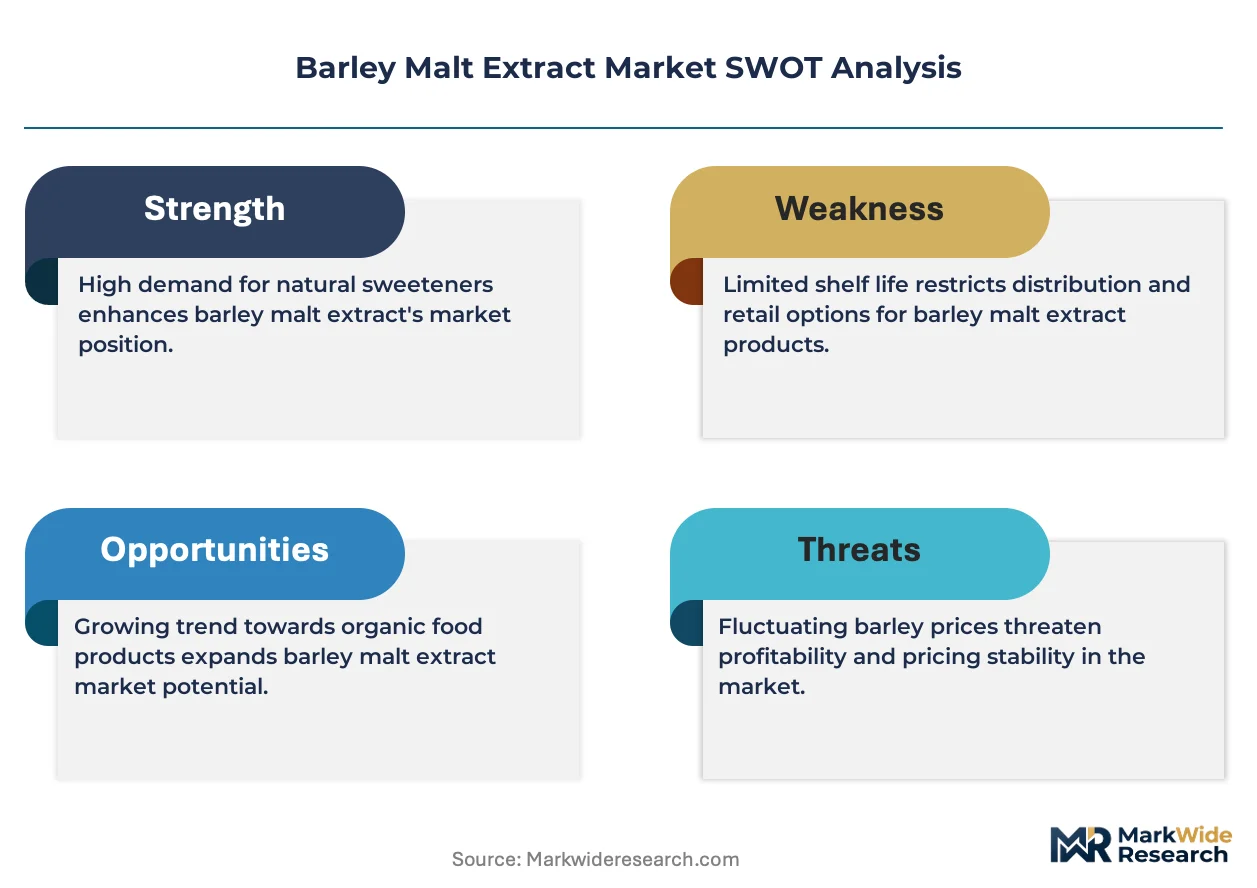
- Barley price volatility:Input cost swings for the underlying grain compress margins for extract processors without long-term supply contracts.
- REACH registration burdens:Chemical compliance frameworks in Europe elevate fixed costs for smaller malt extract producers seeking market access.
- Whole-grain malting substitution:Large-scale industrial brewers with captive malting facilities limit addressable market for extract suppliers in volume segments.
Strategic Opportunities
- India nutraceutical channels:FSSAI-regulated health food manufacturing is opening import demand for powder extracts with extended shelf stability.
- Organic certification tailwinds:USDA organic standards and EU organic regulations are creating premium price tiers for certified extract grades.
- Baking and confectionery convergence:Enzymatic malt syrups are crossing over from brewing into clean-label sweetener applications for industrial bakeries.
Industry Challenges
- Carbon accounting expertise gaps:Agricultural processors lack in-house capability to document Scope 3 emissions for EU Green Deal compliance.
- Legacy equipment integration:Breweries with existing mash tuns face technical friction when retrofitting workflows for extract-based production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barley Malt Extract Market |
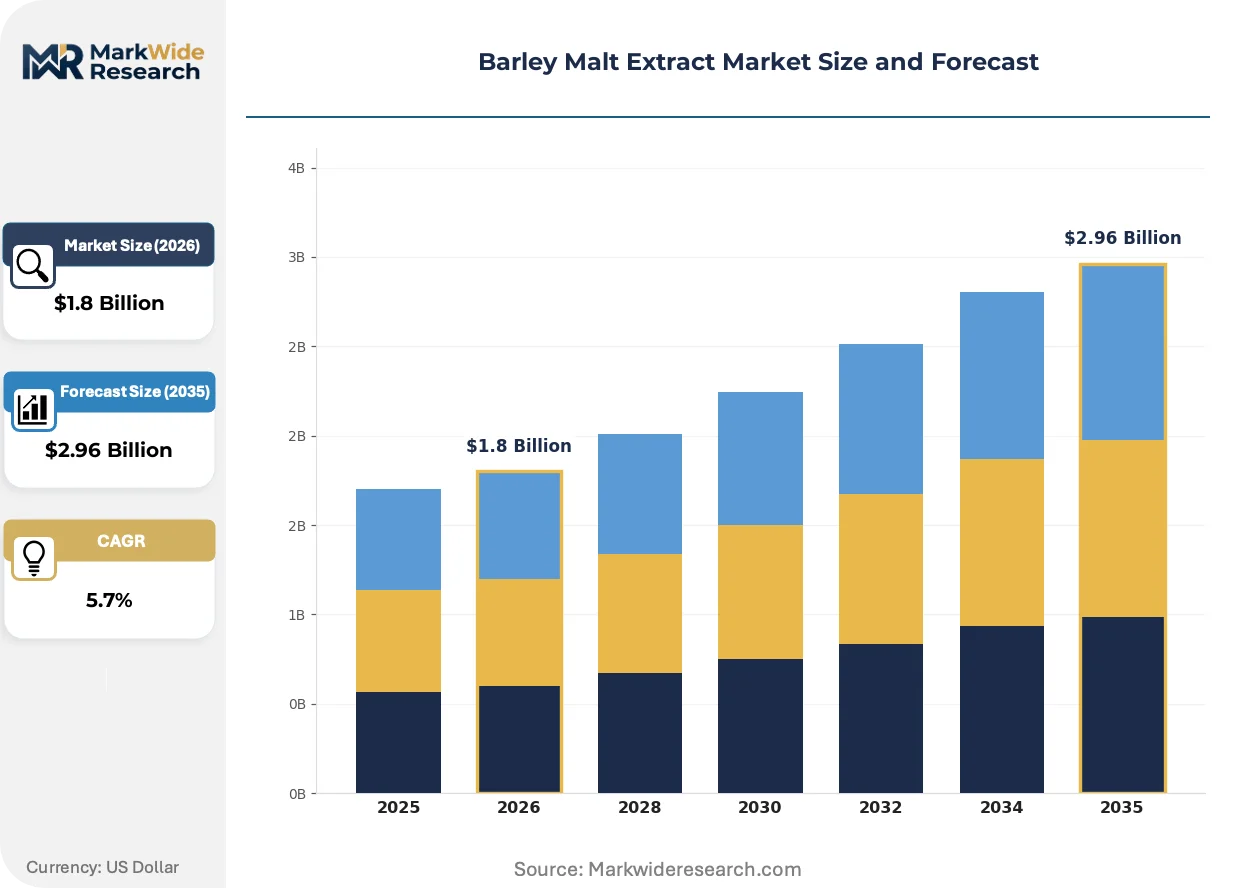
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Powder Extract, Syrup, Concentrate Application: Food & Beverage, Brewery, Pharmaceuticals, Nutraceuticals End User: Bakers, Breweries, Confectioneries, Health Food Manufacturers Quality Grade: Standard, Organic, Non-GMO, Specialty |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Malteurop Group, Groupe Soufflet, Muntons PLC, GrainCorp Limited, Boortmalt, Rahr Corporation, Viking Malt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barley Malt Extract Market Evolving Landscape
Enzymatic processing advances and regulatory traceability mandates are converging to reshape how malt extract is manufactured, certified, and procured across brewing and adjacent food sectors.
Spray-dried malt powder technology is expanding into health food manufacturing as a shelf-stable alternative to liquid syrups. Nutraceutical formulators in Germany and Switzerland are adopting these powders for protein bar and supplement applications where moisture control is critical. The technology is expanding into previously inaccessible retail channels that lacked cold-chain infrastructure for liquid concentrates.
REACH chemical registration frameworks are forcing agricultural processors to document substance safety across extended supply chains. Malt extract producers serving European brewers must now register enzymatic conversion byproducts and verify downstream chemical compliance. Small and mid-sized suppliers without dedicated regulatory affairs functions are outsourcing compliance to specialized consultants or exiting the European market entirely.
Direct procurement relationships between craft brewers and specialty extract suppliers are displacing traditional distributor intermediaries in North America and Western Europe. Regional breweries in Colorado and Bavaria are negotiating volume contracts directly with malting groups to secure consistent flavor profiles and technical support. This channel compression is most visible among breweries producing fewer than fifty thousand barrels annually, where distributor markups previously consumed disproportionate margin.
Barley Malt Extract Market Segmentation
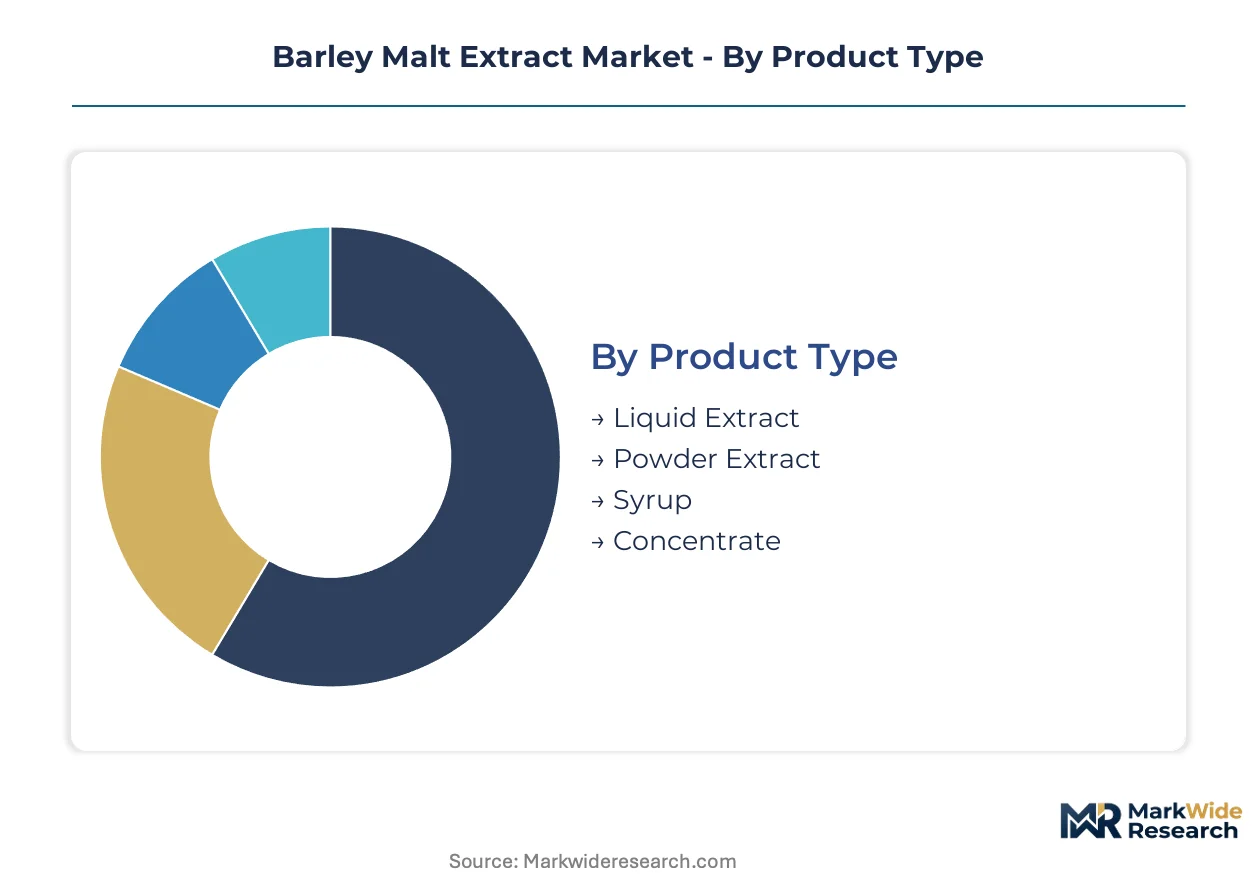
Segmentation in barley malt extract reveals how technical specifications, application requirements, and certification tiers create distinct procurement ecosystems. Each axis governs different margin structures, regulatory exposure, and customer loyalty dynamics across brewing, food manufacturing, and nutraceutical channels.
Product Type:
Moisture content and enzymatic stability separate the four product formats, with each commanding distinct logistics infrastructure and shelf-life economics.
- Liquid Extract:Aqueous solution containing 65-80% fermentable sugars by dry weight, requiring temperature-controlled transport but offering immediate solubility for brewery mash tuns. Demand concentrates in Germany and the United States where craft brewers bypass capital-intensive malting equipment to achieve batch consistency.
- Powder Extract:Spray-dried granules with sub-5% moisture content, extending shelf stability to 24+ months under ambient storage. Health food manufacturers in Switzerland and Germany are adopting this format for protein bar applications where moisture control prevents texture degradation.
- Syrup:Viscous intermediate with higher maltose concentration, serving confectionery applications requiring controlled browning and viscosity.
- Concentrate:Ultra-filtered reduced-water format for industrial-scale bakery procurement where dilution flexibility reduces shipping costs.
Liquid extract leads on scale; powder extract leads on momentum.
Application:
End-use specifications diverge sharply on enzymatic activity requirements, color development targets, and regulatory scrutiny intensity.
- Brewery:Dominant volume channel where diastatic power and fermentable sugar profiles determine extract selection. German traditional brewing clusters are modernizing through extract-based innovation, creating concentrated demand for premium grades with documented provenance.
- Food & Beverage:Cross-category demand spanning industrial bakeries seeking clean-label sweeteners and beverage formulators requiring standardized flavor contribution. FDA food additive regulations and USDA organic certification standards govern label claims and safety documentation.
- Nutraceuticals:Fastest-expanding segment as EU organic regulations and traceability mandates drive premium pricing for certified grades. Powder formats are gaining share in protein supplement manufacturing.
- Pharmaceuticals:Highest specification tier requiring batch-level documentation of enzymatic conversion byproducts under REACH frameworks.
Brewery applications anchor volume; nutraceuticals are climbing the fastest.
End User:
Procurement sophistication varies from artisanal scale to industrial contract structures, reshaping supplier relationship economics.
- Breweries:Direct contracting with malting groups is displacing distributor intermediaries in Colorado and Bavaria, compressing channel margins for volume commitments below fifty thousand barrels annually.
- Bakers:Industrial-scale procurement of enzymatic malt syrups for clean-label sweetener substitution, with FSSAI-regulated manufacturers in India opening import demand.
- Health Food Manufacturers:Organic certification tailwinds from USDA and EU standards create premium price tiers; shelf stability requirements favor powder formats.
- Confectioneries:Viscosity and browning control specifications drive syrup procurement for caramel and coating applications.
Breweries dominate procurement scale; health food manufacturers show steepest expansion trajectory.
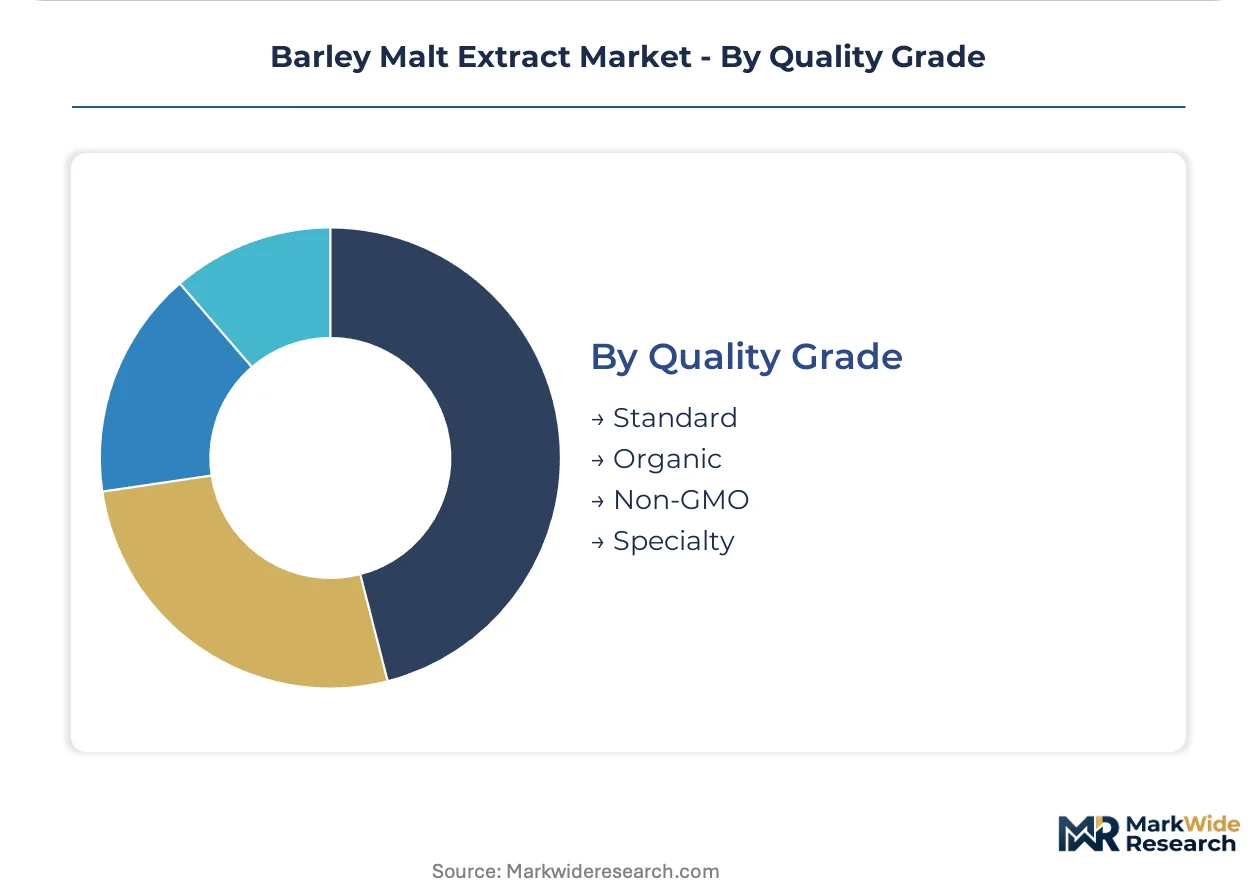
Quality Grade:
Certification tiers stratify pricing and market access, with regulatory compliance costs favoring established suppliers over smaller processors.
- Organic:Requires certified barley sourcing and documented carbon accounting for EU Green Deal compliance. The Farm to Fork Strategy is redirecting brewery procurement toward these grades with traceable footprints.
- Non-GMO:Identity-preserved supply chains with segregation protocols; European nutraceutical channels are tightening traceability requirements.
- Specialty:Custom enzymatic profiles and color specifications for craft brewing innovation; technical support services differentiate supplier relationships.
- Standard:Commodity grades serving volume industrial applications where certification premiums are not recovered in end-product pricing.
Standard grade leads on volume; organic certification commands the fastest premium expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting malt extract procurement toward jurisdictions with established carbon-accounting infrastructure, as EU Green Deal compliance costs widen the gap between certified and conventional supply origins. Processors in Germany and Switzerland capture premium positioning through documented traceability, while North American craft brewers exploit lower certification barriers to scale extract-based production.
Germany
Traditional brewing heritage clusters in Bavaria and Baden-Württemberg are modernizing through extract-based innovation, creating concentrated demand for premium grades. ECHA REACH registration requirements for enzymatic conversion byproducts elevate fixed costs for smaller processors. The Munich-Upper Bavaria metropolitan region anchors procurement relationships between craft breweries and specialty extract suppliers.
United States
Craft brewers in Colorado and the Pacific Northwest accelerate extract adoption to bypass capital-intensive malting infrastructure. FDA food additive regulations and USDA organic certification standards govern label claims and safety documentation. The Front Range urban corridor from Denver to Fort Collins hosts direct contracting relationships displacing traditional distributor intermediaries.
United Kingdom
Specialized brewing concentrates and food-grade syrups anchor domestic demand through industrial bakery and confectionery channels. EU organic regulations post-Brexit create parallel certification tracks with diverging carbon-accounting requirements. The East Anglia malting belt maintains integrated supply relationships between barley growers and extract processors.
Switzerland
Nutraceutical formulators in Zurich and Basel adopt spray-dried malt powders for protein bar applications where moisture control prevents texture degradation. Swissmedic pharmaceutical-grade documentation standards create the highest specification tier for batch-level enzymatic conversion tracking. The Swiss Mittelland corridor concentrates health-food manufacturing demand for certified organic grades.
India
FSSAI-regulated health food manufacturing is opening import demand for powder extracts with extended shelf stability. The country's national food safety regulator tightens traceability requirements for enzymatic ingredients in supplement formulations. Maharashtra and Gujarat industrial corridors host emerging procurement relationships with European extract suppliers seeking volume diversification.
Barley Malt Extract Market Competitive Landscape
Backward integration into barley sourcing dominates the current landscape as processors seek to defend margin positions against input cost volatility. The vendor base stratifies across three tiers: integrated malting groups with captive grain supply, specialized extract processors with technical service capabilities, and regional commodity suppliers serving price-sensitive industrial accounts. Two competitive moves define positioning: M&A activity consolidating malting assets under multi-continent networks, and portfolio diversification into organic-certified grades capturing Farm to Fork Strategy procurement.
Among integrated malting specialists, Malteurop Group and Muntons PLC exemplify contrasting geographic anchoring strategies. Malteurop occupies a position spanning six-continent supply networks with standardized extract production. Muntons sits within the United Kingdom market through specialized brewing concentrates and food-grade syrup formulations. Rahr Corporation represents the North American technical-service archetype, where extract portfolios tie to customer support infrastructure. These three anchors illustrate how procurement relationships compress toward direct contracting as craft brewers bypass distributor intermediaries.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Malteurop Group |
| Groupe Soufflet |
| Muntons PLC |
| GrainCorp Limited |
| Boortmalt |
| Rahr Corporation |
| Viking Malt |
| Others |
Value Network & Pricing Analysis
EU Farm to Fork Strategy procurement mandates for certified organic malt extracts with traceable carbon footprints are forcing processors to restructure sourcing relationships and absorb compliance premiums into contract structures. This regulatory-driven specification shift compresses margins for smaller suppliers while rewarding integrated malting groups with captive certified barley supply.
Pricing Analysis
Distributor markups in the craft brewery channel are compressing as regional brewers in Colorado and Bavaria negotiate direct volume contracts below fifty thousand barrels annually. Three-tier pricing structure across organic-certified, specialty-grade, and standard commodity levels separates procurement tiers, with EU organic regulations commanding the steepest premium expansion. Cost compression in standard grades is intensifying because barley price volatility feeds through to spot-market liquid extract without long-term supply contracts. Industrial-scale bakers show highest price sensitivity, while Swiss nutraceutical formulators demonstrate lowest sensitivity due to Swissmedic documentation requirements.
Supply Chain Analysis
Refurbishment flows for malting equipment and extract processing infrastructure concentrate maintenance value recovery in Germany, the United States, and the United Kingdom. Raw material dependencies rest on spring barley varieties, enzymatic conversion catalysts, and spray-drying energy inputs. Single-source vulnerability runs through concentrated malting belt clusters in East Anglia and the Munich-Upper Bavaria metropolitan region. Distribution runs through direct contracting relationships displacing traditional intermediaries, with temperature-controlled logistics for liquid extract and ambient storage networks for powder formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barley malt extract offers margin-expansion pathways through organic certification tier shifts, as EU Green Deal compliance costs filter non-certified competitors from premium procurement channels.
For Market Incumbents: Cement market position by deepening backward integration into certified organic barley sourcing in Germany and Switzerland, and by acquiring dedicated regulatory affairs capabilities to navigate ECHA REACH registration burdens. This defends against emerging specialty extract processors offering technical support services without captive grain supply. For New Entrants and Emerging Players: Artisanal-scale craft brewers in India's Maharashtra and Gujarat industrial corridors represent an underserved buyer archetype seeking powder extracts with extended shelf stability for FSSAI-regulated health food manufacturing. Target this penetration point through import partnerships with European extract suppliers seeking volume diversification, leveraging direct technical support as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-sized specialty extract processors possessing organic certification infrastructure and established technical service teams. Long-term viability hinges on carbon accounting capability buildout across the projection horizon. Watch for EU carbon border adjustment mechanism implementation signals as the inflection indicator for certified-grade procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Barley Sourcing | Secures EU Farm to Fork Strategy compliance and defends margin against input volatility. |
| Spray-Dried Powder Capacity Expansion | Captures Swiss and German nutraceutical demand where moisture control prevents texture degradation. |
| Direct-to-Brewer Technical Service Partnerships | Displaces distributor intermediaries in Colorado and Bavaria craft brewing clusters. |
| Organic Certification Investment | Creates premium price tier access under USDA and EU organic regulations. |
| Carbon Accounting Infrastructure Buildout | Documents Scope 3 emissions for EU Green Deal procurement eligibility. |
Research Methodology
Multiple input streams — structured interviews with malting group procurement directors, craft brewery operations managers, and Swiss nutraceutical formulators; secondary validation through customs trade data, SEC filings of integrated grain processors, and ECHA REACH registration databases; plus bottom-up and top-down triangulation — were reconciled to construct market estimates. Primary fieldwork captured direct contracting relationship dynamics between specialty extract suppliers and regional breweries, while secondary sources anchored volume assumptions in documented malt production and trade flows.
Data-stream reconciliation across product format segmentation, application channel splits, and quality grade tiers generated volume and value outputs over the projection horizon. CAGRs were derived from modeled adoption curves for extract-based brewing innovation and organic certification penetration. Forecast inputs incorporated EU Green Deal implementation timelines, craft brewery formation rates in Germany and the United States, and FSSAI regulatory evolution in Indian health food manufacturing.
Inputs from malting industry associations and national food safety regulators were available through the study window; gaps in proprietary contract pricing between direct-procurement craft brewers and specialty suppliers introduce uncertainty bands around channel-margin estimates. Forecasts reflect documented assumptions regarding regulatory compliance cost pass-through and organic barley supply expansion. Practitioners should monitor EU carbon border adjustment mechanism proposals and FSSAI traceability rulemakings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Protein Hydrolysate Ingredients Market
Ingredients
Red Orange Anthocyanin Extract Ingredients Market
Ingredients
Middle-East and Africa Vegetable Oil Market
Ingredients
South America Phytosterols Market
Ingredients
Rooster Comb Extract Market
Ingredients
Tapioca Market
Ingredients
Tryptose Market
Ingredients
Omega 6 Market
Ingredients
Caramel Malt Market
Ingredients
Feed Ingredients Market
Ingredients
Cold Water Swelling Starch Market
Ingredients
Fruit Concentrate Market
Ingredients
Icing Shortening Market
Ingredients
Soy Hydrolysates Market
Ingredients
Gum Arabic Market
Ingredients
Sweet Almond Oil Market