
 Natural Acerola Cherry Extract Market | 2026-2036
Natural Acerola Cherry Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Acerola Cherry Extract Market Insights
Modular dosing formats is recalibrating buyer choice across the Natural Acerola Cherry Extract Market, as manufacturers unbundle bulk powder from turnkey premix solutions to serve mid-sized nutraceutical clients. Givaudan leverages its flavor-science infrastructure to integrate acerola extracts into beverage systems with masking technologies. DSM anchors its position through backward integration into sustainable Brazilian cherry sourcing. Nexira specializes in clean-label positioning for organic-certified powder grades.
Natural acerola cherry extract is a botanical concentrate derived from Malpighia emarginata fruit, standardized to 17-25% vitamin C content by weight through cold-pressing or gentle dehydration processes that preserve heat-labile bioflavonoids and anthocyanins. The extract functions primarily as a natural antioxidant, color stabilizer, and nutrient fortificant across food, cosmetic, and pharmaceutical matrices. Powder formats dominate volume throughput due to superior shelf stability and blending compatibility in dry-mix applications, while liquid extracts command premium positioning in functional beverage and cosmetic serum segments. Nutraceutical applications represent the fastest-growing demand pool, driven by capsule and tablet formulations targeting immune-support positioning.
FDA GRAS self-affirmation pathways and EFSA Novel Food authorizations govern market access for new acerola extract entrants in the United States and European Union, with Brazil's ANVISA providing reference standards for raw material quality benchmarks. These regulatory frameworks elevate documentation burdens for synthetic-to-natural switchover claims while rewarding suppliers with validated traceability systems. Stakeholders must monitor evolving maximum vitamin C fortification thresholds and organic certification reciprocity agreements between source and destination markets.
Market Dynamics
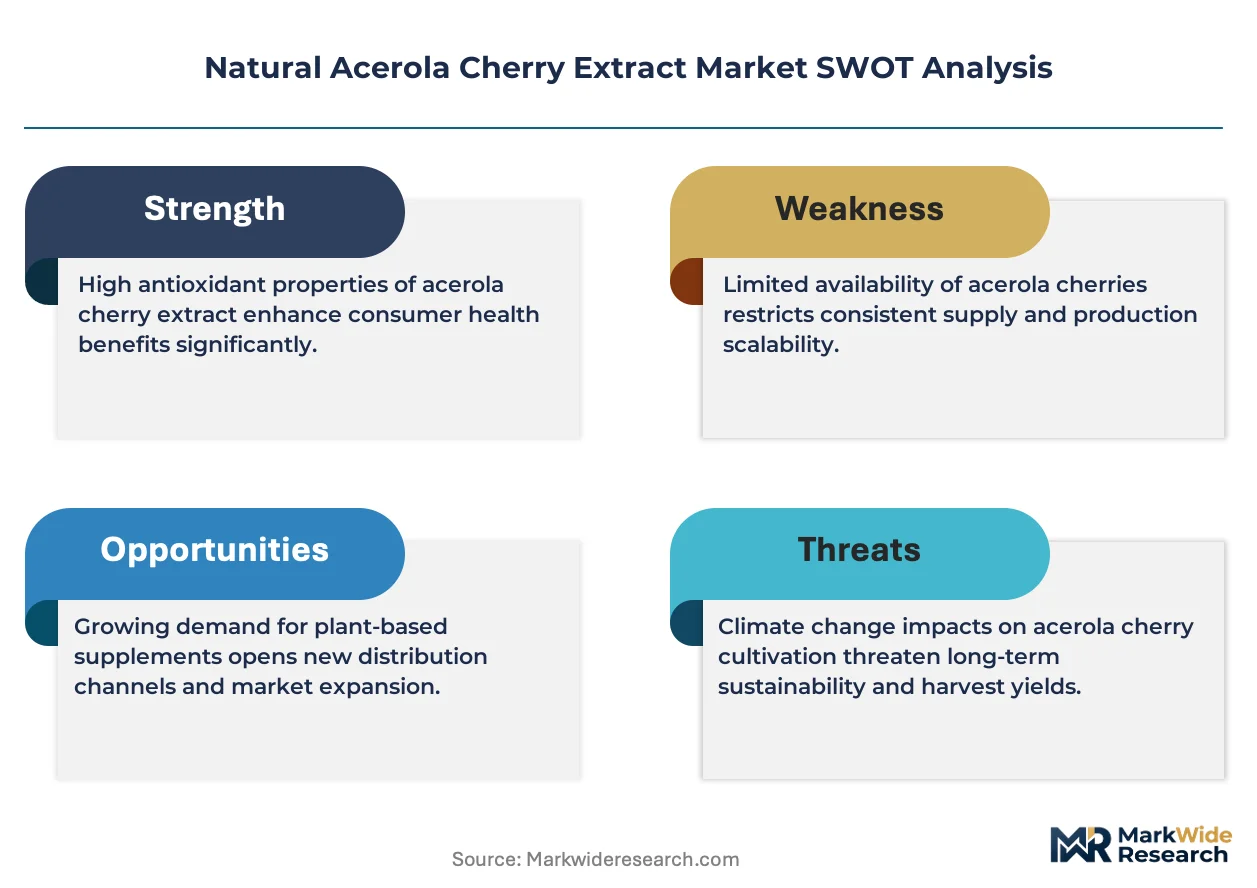
Clean-label vitamin C sourcing is compressing synthetic ascorbic acid margins while Brazilian cultivation expansion and EU Novel Food compliance costs are redrawing supplier tier boundaries. The structural pivot hinges on traceability-validated supply chains displacing commodity spot markets.
Growth Catalysts
- EU Novel Food Regulation:EFSA authorization pathways reward suppliers with validated traceability systems, creating competitive moats against unverified entrants. Brazilian exporters with ANVISA-certified raw material benchmarks capture preferential access.
- Functional beverage fortification:North American manufacturers accelerate procurement of acerola-derived vitamin C as synthetic ascorbic acid faces consumer skepticism. Cold-pressed extraction preserves heat-labile bioflavonoids that synthetic alternatives cannot replicate.
- Dehydration process innovation:Gentle low-temperature drying technologies reduce vitamin C degradation from 40% to under 12% during processing. This yield improvement tightens unit economics for mid-scale processors.
Market Restraints
- Brazilian supply concentration:Over 70% of global acerola cultivation clusters in northeastern Brazil, exposing buyers to climate volatility and port logistics bottlenecks. Drought frequency in Ceará and Pernambuco states disrupts harvest cycles.
- EU Novel Food compliance costs:EFSA safety dossier preparation exceeds €300,000 per novel food application, freezing out smaller suppliers. Authorization timelines stretch 18-24 months even for established botanical extracts.
- Synthetic ascorbic acid price floor:Fermentation-derived vitamin C from Chinese manufacturers maintains 60-70% cost advantage over natural extracts. Price-sensitive fortification applications resist switching despite clean-label preferences.
Strategic Opportunities
- Indian nutraceutical manufacturing:CDSCO's streamlined botanical extract approvals and FSSAI's functional food category expansion create entry pathways. Domestic capsule and tablet production capacity is scaling rapidly.
- Cosmetic serum formulations:Anthocyanin-rich liquid extracts command 3-4x powder pricing in premium skincare. K-beauty and J-beauty brands are validating antioxidant stability claims through clinical testing.
- Organic certification reciprocity:USDA-NOP and EU organic equivalence agreements reduce dual-certification burdens for Brazilian cooperatives. This regulatory alignment opens premium pricing tiers for verified organic powder grades.
Industry Challenges
- Phytochemical standardization expertise:Vitamin C potency varies 15-30% between harvest batches, requiring skilled analytical chemists and HPLC calibration protocols. Talent scarcity in northeastern Brazil constrains processor expansion.
- Cold-chain infrastructure gaps:Fresh cherry transport from farm to processing facility demands refrigerated logistics that rural Brazilian roads lack. Capital deployment for on-farm gentle dehydration units runs $2-4 million per installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Acerola Cherry Extract Market |
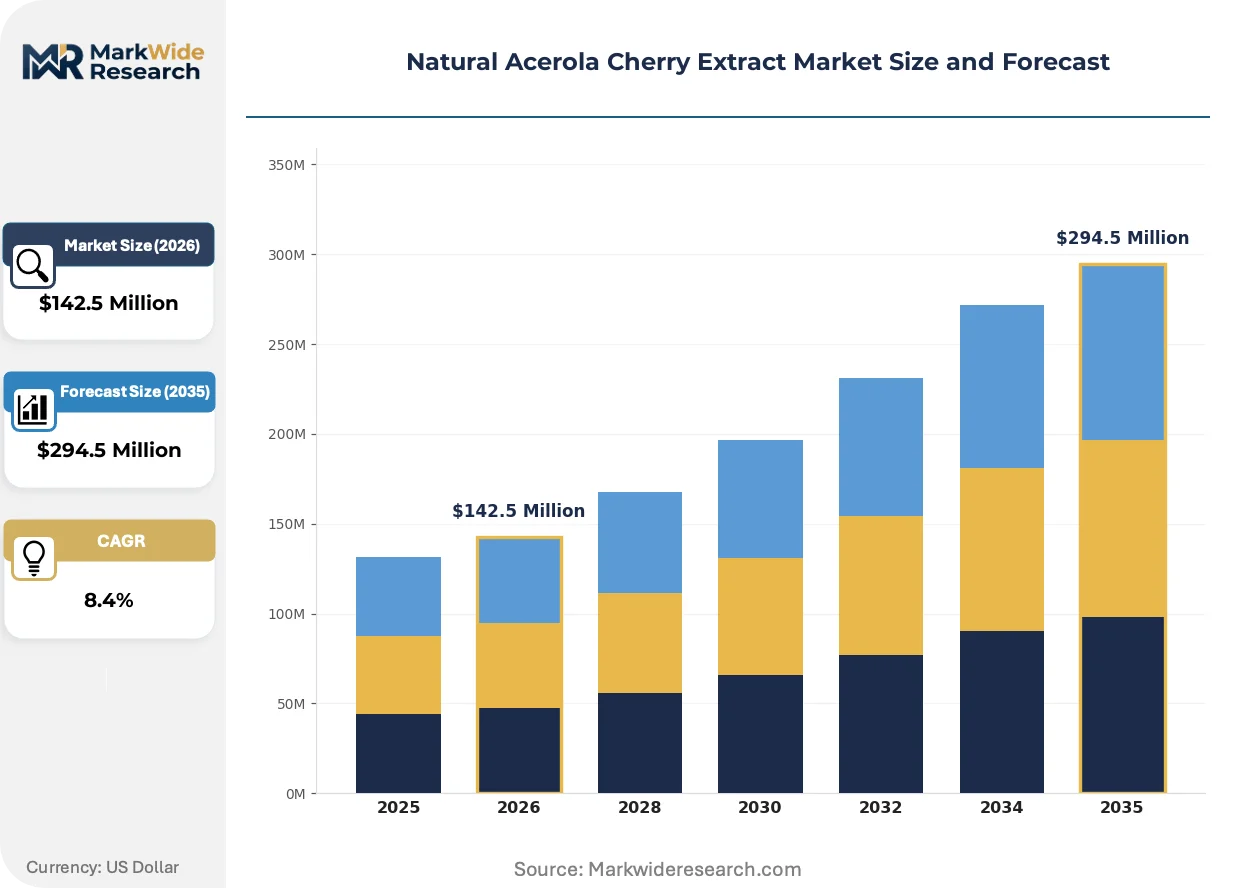
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $294.5 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsules, Tablets Application: Food & Beverage, Cosmetics, Nutraceuticals, Pharmaceuticals Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales End User: Manufacturers, Health Enthusiasts, Retailers, Consumers |
| Companies Covered | Givaudan, Symrise, Döhler GmbH, Nexira, Kemin Industries, DSM, DR Flavors & Ingredients, The Green Labs LLC, Duas Rodas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Acerola Cherry Extract Market Trends and Innovations
Extraction technology convergence and regulatory documentation automation are compressing time-to-market for new entrants while reshaping buyer-supplier power dynamics. Three forces dominate this transition.
Low-temperature vacuum dehydration is overtaking traditional spray-drying as the preferred processing method for premium nutraceutical applications. This technology preserves anthocyanin and bioflavonoid matrices that spray-drying degrades by 35-50%. European organic-certified brands and North American functional beverage manufacturers are specifying vacuum-dehydrated grades in procurement contracts, forcing mid-tier suppliers to retool or accept commodity pricing.
EFSA's evolving Novel Food guidance on botanical concentrates is tightening safety dossier requirements for heat-treated extracts. The regulation now mandates stability data across 24-month shelf-life projections and full toxicological profiles for non-traditional food uses. Powder-format suppliers targeting EU pharmaceutical and cosmetic applications face the steepest compliance ramps, with several Brazilian processors establishing dedicated regulatory affairs functions in Brussels to manage direct EFSA engagement.
Direct-contract sourcing is displacing spot-market purchasing among mid-sized nutraceutical manufacturers. Buyers are locking 12-18 month supply agreements with traceability-validated Brazilian cooperatives, bypassing traditional trading houses. This pattern is most visible in German and Dutch capsule manufacturers, where procurement teams now require blockchain-traceable farm-to-facility documentation as a standard tender qualification.
Natural Acerola Cherry Extract Market Segmentation
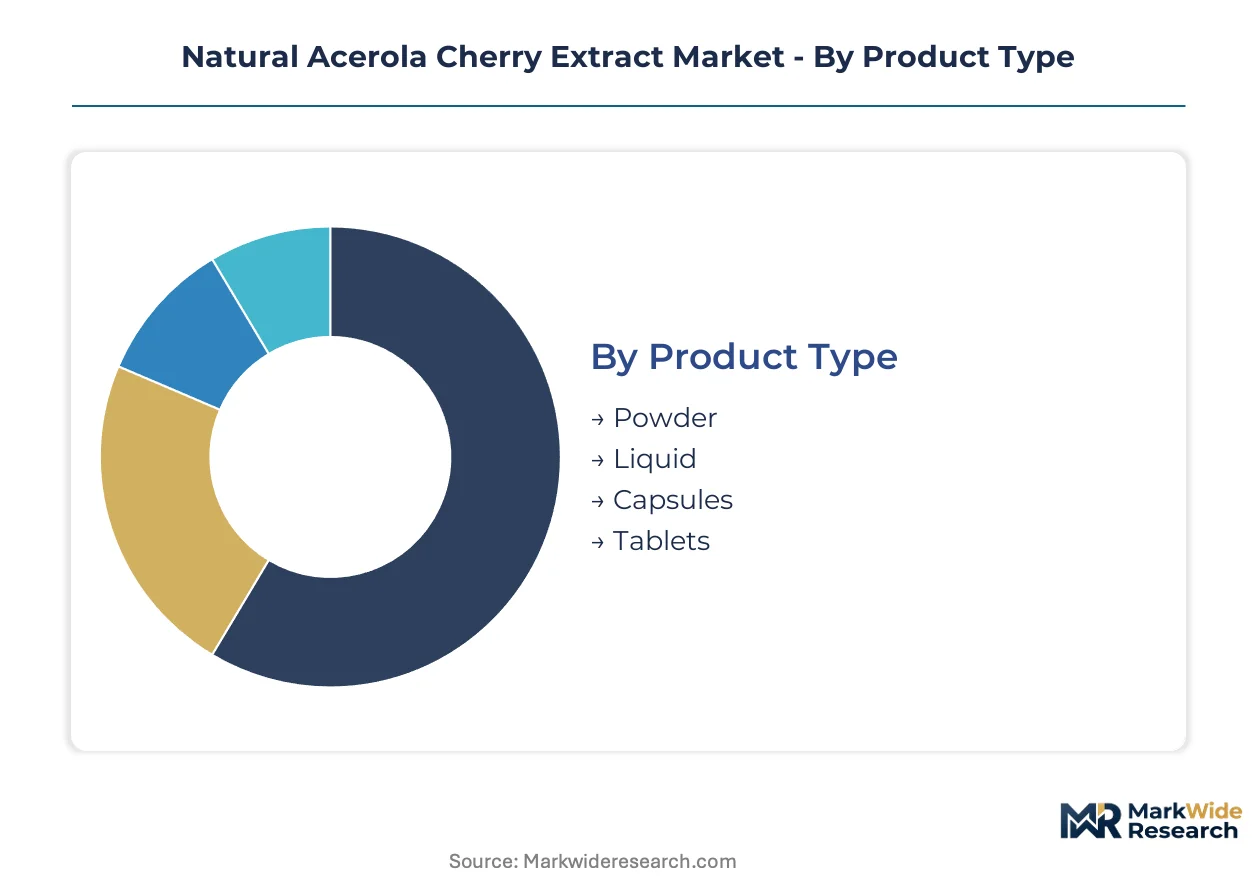
Segmentation in the Natural Acerola Cherry Extract Market reveals how supply chain configuration, extraction technology, and end-use specifications fragment buyer requirements. Each dimension carries distinct margin profiles and regulatory compliance burdens that reshape supplier positioning.
Product Type:
Brazilian cultivation concentration drives format specialization, with processors near Ceará and Pernambuco optimizing equipment for specific vitamin C stability targets.
- Powder:Spray-dried or vacuum-dehydrated concentrates standardized to 17-25% ascorbic acid content. Dry-mix compatibility and 24-month shelf stability anchor demand from German and Dutch capsule manufacturers seeking blockchain-traceable supply agreements.
- Liquid:Cold-pressed extracts retaining heat-labile anthocyanins and bioflavonoids. Premium functional beverage manufacturers in the United States specify liquid grades for immune-support positioning that synthetic ascorbic acid cannot replicate.
- Capsules:Pre-measured dosing units targeting health enthusiasts. Indian CDSCO streamlined approvals and FSSAI functional food expansion accelerate domestic manufacturing uptake.
- Tablets:Compressed formats for mass-market nutraceutical distribution. Cost-sensitive applications resist switching from synthetic alternatives despite clean-label preferences.
Today's leader: Powder. Tomorrow's challenger: Liquid.
Application:
Margin stratification across end-uses separates premium cosmetic serums from commodity food fortification.
- Nutraceuticals:Immune-support capsules and tablets represent the steepest expansion trajectory, with North American manufacturers accelerating procurement of acerola-derived vitamin C as synthetic alternatives face consumer skepticism.
- Cosmetics:Anthocyanin-rich liquid extracts command 3-4x powder pricing in premium skincare. K-beauty and J-beauty brands validate antioxidant stability through clinical testing protocols.
- Food & Beverage:Natural color stabilization and fortification across juice, dairy, and confectionery matrices. EFSA Novel Food compliance costs freeze out smaller suppliers seeking EU market access.
- Pharmaceuticals:Excipient-grade extracts meeting USP or EP monograph specifications. FDA GRAS self-affirmation pathways govern US market entry documentation requirements.
Cosmetics extracts capture peak margins. Nutraceuticals scale fastest.
Distribution Channel:
Channel selection reflects buyer sophistication and volume scale, with direct contracting displacing traditional trading intermediaries.
- Direct Sales:Long-term supply agreements between Brazilian cooperatives and mid-sized nutraceutical manufacturers. Blockchain-traceable farm-to-facility documentation now qualifies as standard tender requirement.
- Online Retail:E-commerce platforms serving health enthusiasts and small-scale manufacturers. Organic-certified powder grades with USDA-NOP validation command premium positioning.
- Health Stores:Specialty retail targeting consumer-direct supplement purchases. Shelf-stable powder formats dominate inventory turnover.
- Supermarkets:Mass-market food and beverage fortification ingredients. Price-sensitive procurement favors synthetic ascorbic acid where label claims permit.
Direct sales lock in supply security. Online retail expands geographic reach.
End User:
User type determines specification stringency, from pharmaceutical-grade documentation to consumer-facing label claims.
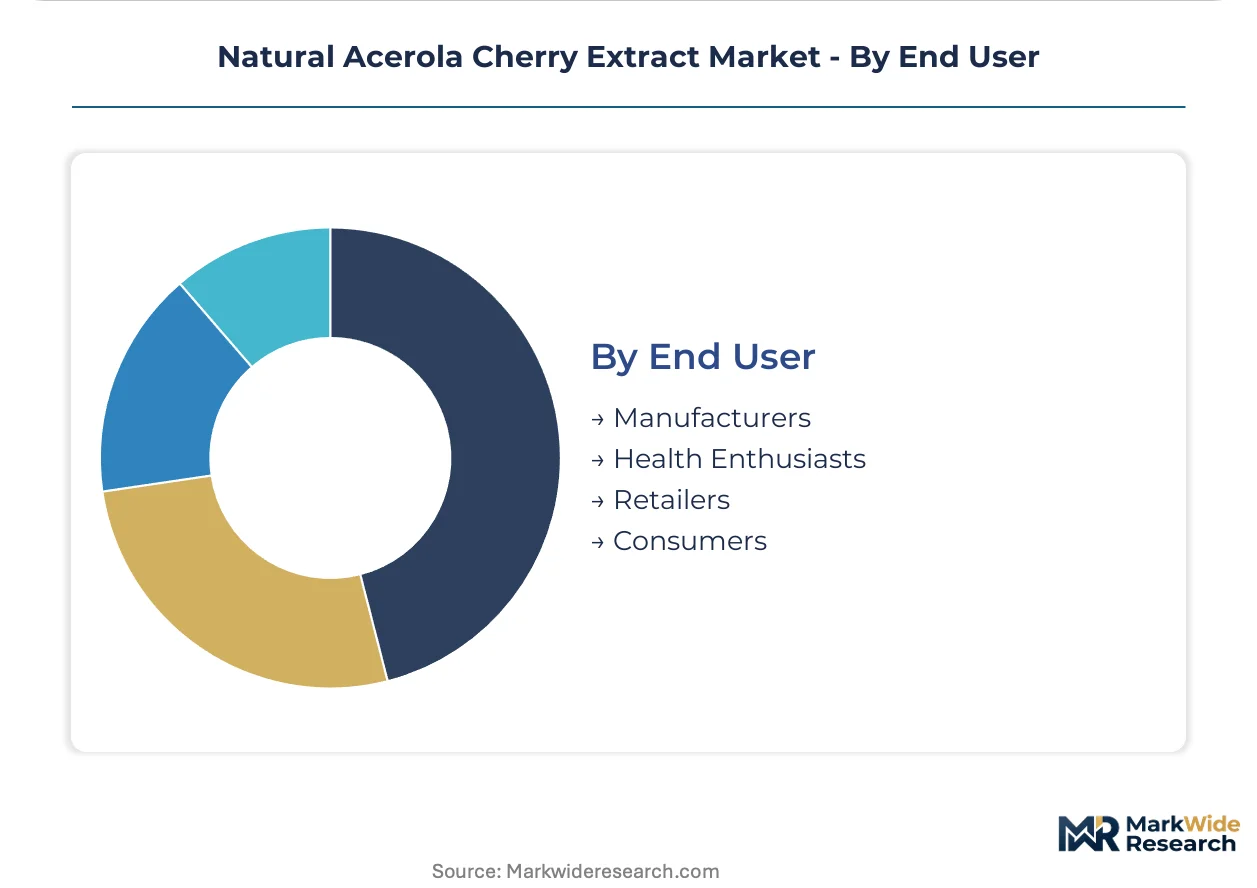
- Manufacturers:Functional beverage and nutraceutical producers requiring validated traceability systems. EFSA Novel Food authorization rewards suppliers with 18-24 month dossier preparation capabilities.
- Retailers:Private-label supplement brands and health store chains. Clean-label positioning drives substitution away from synthetic vitamin C.
- Health Enthusiasts:Individual consumers prioritizing organic certification and cold-pressed extraction methods. Premium pricing tolerance supports small-batch liquid extract demand.
- Consumers:Mass-market purchasers of fortified foods and basic supplements. Price elasticity constrains natural extract penetration in this tier.
Manufacturers dictate specification standards. Health enthusiasts amplify premium tier expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil pioneered commercial acerola cultivation in the 1950s, establishing northeastern states as the genetic and processing epicenter for global supply. This historical foundation shapes contemporary trade flows, with regulatory frameworks in consuming markets now filtering access to Brazilian-origin extracts.
Brazil
Northeastern cooperatives in Ceará and Pernambuco supply over 70% of global raw material, with ANVISA certification serving as the reference standard for quality benchmarks. The country's national pharmaceutical regulator validates traceability protocols that EFSA recognizes in Novel Food dossiers. Fortaleza-based processors are deploying on-farm gentle dehydration units to bypass rural cold-chain gaps.
United States
Functional beverage manufacturers accelerate procurement of acerola-derived vitamin C as synthetic ascorbic acid faces consumer skepticism. FDA GRAS self-affirmation pathways govern market entry, with documentation burdens elevating preference for suppliers with validated Brazilian partnerships. California and New Jersey host the largest concentration of finished goods formulation facilities.
Germany
Capsule and tablet manufacturers in Bavaria and North Rhine-Westphalia now require blockchain-traceable farm-to-facility documentation as standard tender qualification. EFSA Novel Food authorization timelines of 18-24 months reward suppliers with dedicated regulatory affairs functions. Frankfurt serves as the primary import hub for vacuum-dehydrated premium grades.
India
Domestic nutraceutical manufacturing scales rapidly as CDSCO streamlines botanical extract approvals and FSSAI expands functional food categories. Maharashtra and Gujarat host contract manufacturing organizations targeting export markets. Local capsule production capacity absorbs mid-tier powder grades previously routed through European traders.
Japan
K-beauty and J-beauty brands validate antioxidant stability claims through clinical testing, commanding 3-4x powder pricing for anthocyanin-rich liquid extracts. METI guidelines on functional food labeling shape import specifications. Osaka and Tokyo cosmetic formulators specify cold-pressed extraction methods for premium serum applications.
Natural Acerola Cherry Extract Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and traceability tiers, with organic-certified, blockchain-validated supply chains capturing 40-50% price premiums over conventional grades. The vendor base clusters around three strategic archetypes: flavor-science integrators leveraging masking technologies, backward-integrated agricultural processors controlling Brazilian sourcing, and clean-label specialists commanding organic positioning. Dominant competitive moves include 12-18 month direct-contract sourcing agreements displacing spot-market purchasing, and dedicated regulatory affairs functions established in Brussels to manage EFSA engagement.
Within the flavor-science integrator tier, Givaudan and Symrise exemplify positioning that bridges extraction expertise with beverage system formulation. Among agricultural processors with Brazilian roots, Duas Rodas occupies a position reflecting historical cultivation proximity. DSM anchors the backward-integrated archetype through captive supply arrangements in northeastern Brazil. Nexira represents the clean-label specialist tier with organic-certified powder grade focus. These players collectively illustrate how competitive advantage converges on traceability validation and regulatory dossier capabilities rather than scale alone.
| Leading Market Players |
|---|
| Givaudan |
| Symrise |
| Döhler GmbH |
| Nexira |
| Kemin Industries |
| DSM |
| DR Flavors & Ingredients |
| The Green Labs LLC |
| Duas Rodas |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap processors in northeastern Brazil anchor supply discipline through cooperative ownership structures that resist spot-market volatility while enforcing organic certification premiums. This ownership pattern concentrates pricing power among ANVISA-validated exporters capable of absorbing EFSA Novel Food dossier costs, compressing margins for unverified trading intermediaries.
Pricing Analysis
Three-tier pricing structure across organic-certified, conventional food-grade, and commodity feed-grade levels separates premium liquid extracts from standard powders. Price differentiation rests on blockchain traceability validation and cold-pressed extraction method, with vacuum-dehydrated grades commanding 40-50% premiums over spray-dried alternatives. Cost compression in conventional powder tiers is intensifying because Chinese synthetic ascorbic acid maintains 60-70% cost advantage. Mass-market food fortification buyers exhibit highest price sensitivity; cosmetic serum manufacturers demonstrate lowest.
Supply Chain Analysis
EFSA Novel Food authorization and USDA-NOP organic equivalence agreements gate market access, filtering supplier tiers by documentation capability. Geographic concentration centers on Brazil, India, and Germany as processing hubs. Raw material dependencies include fresh acerola fruit harvests, gentle dehydration equipment, and HPLC analytical calibration standards. Single-source vulnerability runs through northeastern Brazilian cultivation clusters exposed to Ceará drought cycles. Distribution runs through direct-contract agreements between cooperatives and finished goods manufacturers, displacing traditional trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where immune-support positioning in functional beverages shifts procurement specifications toward cold-pressed, anthocyanin-retaining grades that synthetic alternatives cannot replicate.
For Market Incumbents: Hedge Brazilian supply concentration by deploying on-farm gentle dehydration units in Pernambuco satellite regions, reducing cold-chain dependency. Deepen backward integration into organic-certified cooperatives before USDA-NOP reciprocity agreements expire. ANVISA certification moats erode as Indian CDSCO streamlines rival botanical approvals.
For New Entrants and Emerging Players: E-commerce direct-to-manufacturer platforms offer lowest customer acquisition cost for mid-sized nutraceutical buyers seeking smaller minimum order quantities. White-space availability concentrates in Indian contract manufacturing organizations scaling capsule production capacity. Target cosmetic serum formulations for K-beauty private label brands through clinical antioxidant stability validation.
For Investors and Strategic Acquirers: Valuations sit cheapest among conventional spray-dried powder specialists lacking organic certification or EFSA dossier capabilities. Long-term viability favors backward-integrated processors with captive Brazilian supply and Brussels regulatory affairs functions. Watch for inflection when EFSA publishes revised stability data requirements for heat-treated extracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brazilian Cooperatives | Captive supply secures ANVISA-validated raw material amid climate volatility in Ceará. |
| EFSA Novel Food Dossier Investment | Authorization unlocks premium pharmaceutical and cosmetic tier access in Germany. |
| Vacuum Dehydration Technology Deployment | Preserves anthocyanin matrices that spray-drying degrades by 35-50%. |
| Blockchain Traceability Implementation | German capsule manufacturers now require farm-to-facility documentation as standard tender qualification. |
| Cosmetic Serum Clinical Validation | K-beauty brands command 3-4x powder pricing for antioxidant stability claims. |
Research Methodology
Coverage spans Brazil, the United States, Germany, India, and Japan, with primary inputs from each market validating cross-regional patterns. The approach combines interviews with extraction technology specialists, regulatory affairs directors at nutraceutical manufacturers, procurement leads at functional beverage companies, and cooperative managers in Ceará and Pernambuco with secondary validation from ANVISA quality bulletins, EFSA Novel Food register entries, FDA GRAS notifications, and customs trade data. Bottom-up volume estimates triangulate against top-down category spending analysis.
Granularity-level modeling disaggregates volume and value across powder, liquid, capsule, and tablet formats; nutraceutical, cosmetic, food and beverage, and pharmaceutical applications; and direct sales versus online retail versus health store versus supermarket channels. CAGRs derive from segment-level growth drivers rather than single-point extrapolation. Forecast inputs include Brazilian cultivation yield projections, EFSA authorization timeline probabilities, and synthetic ascorbic acid price elasticity assumptions.
The model assumes a particular technology adoption path where vacuum dehydration overtakes spray-drying for premium grades; alternative pathways for cold-pressed liquid extraction scaling would alter the outlook. Forecasts reflect documented assumptions regarding EU Novel Food compliance cost trajectories and organic certification reciprocity stability. A model refresh is warranted upon material change in EFSA guidance on botanical concentrate stability data requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Ginkgo Biloba Extract Market
Flavorings and Food Additives
Chocolate Flavoring Compounds Market
Flavorings and Food Additives
D-Limonene Market
Flavorings and Food Additives
Valencene Market
Flavorings and Food Additives
Natural Extracts Market
Flavorings and Food Additives
Orange Extract Market
Flavorings and Food Additives
Brazil Food Colorants Market
Flavorings and Food Additives
Lemon Essential Oil Market
Flavorings and Food Additives
China Food Flavor and Enhancer Market
Flavorings and Food Additives
Oleoresin Market
Flavorings and Food Additives
Global Flavors Market
Flavorings and Food Additives
Asia-Pacific Food Flavor Market
Flavorings and Food Additives
Orange Peel Extract Market
Flavorings and Food Additives
Vanilla Bean Market
Flavorings and Food Additives
Global Syrup Market
Flavorings and Food Additives
Food Colorants Market