
 Edible Food Paints Market | 2026-2036
Edible Food Paints Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Food Paints Market Foresight
Buyer concentration in the edible food paints sector is decoupling as artisan micro-bakeries fragment demand while industrial food manufacturers consolidate procurement volumes. Wilton Brands LLC leverages its specialty store distribution network to sustain brand visibility among home bakers. AmeriColor Corp. competes through gel paint specialization that anchors professional pastry chef loyalty. Sensient Technologies Corporation dominates natural colorant R&D pipelines, positioning its portfolio for regulatory transitions in Europe and North America.
Edible food paints comprise FDA-certified and EFSA-compliant colorant suspensions in water, glycerin, or ethanol carriers, formulated for direct food contact with controlled viscosity between 500 and 5000 centipoise for brush, airbrush, or spray application. These formulations enable precise aesthetic customization on fondant, royal icing, and chocolate surfaces without compromising flavor profiles or shelf stability. Liquid paints lead volume sales through versatility across home and professional settings, while gel paints command margin premiums in confectionery applications where saturation control determines visual outcome quality. Powder paints represent the fastest-growing format as food manufacturers seek reduced-moisture formulations for extended ambient storage.
FDA color additive regulations under 21 CFR 73 and 74 govern batch certification requirements for synthetic dyes, while EFSA re-evaluations of titanium dioxide and azo compounds drive reformulation mandates across EU-exporting suppliers. The EU Green Deal chemical sustainability targets further pressure manufacturers to document carbon intensity across natural pigment supply chains. Stakeholders must monitor divergence between FDA and EFSA approved substance lists when configuring regional product portfolios.
Market Dynamics
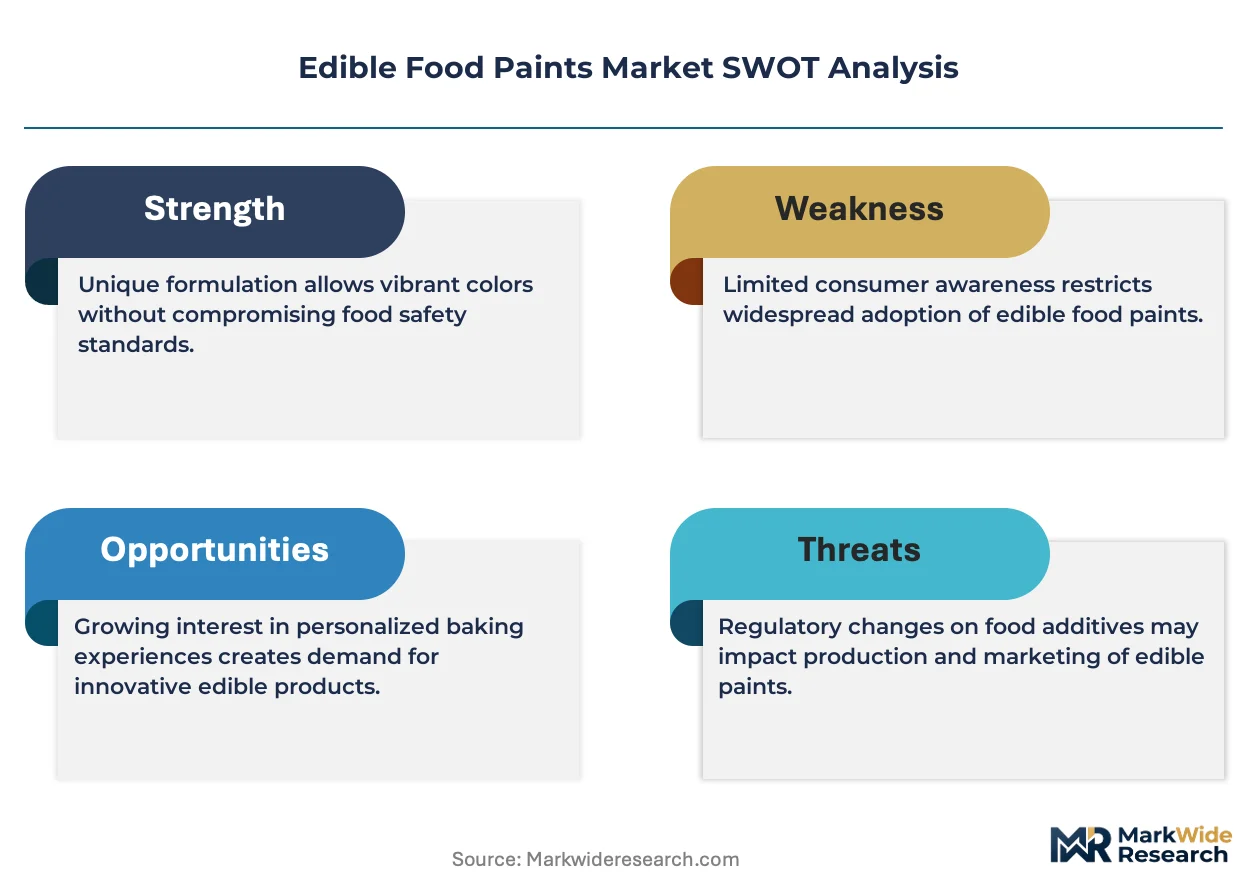
Regulatory divergence between FDA and EFSA purity standards is fragmenting formulation portfolios and forcing suppliers to maintain parallel product lines with divergent ingredient specifications.
Growth Catalysts
- EU Green Deal chemical sustainability targets:Carbon intensity documentation mandates for natural pigment supply chains are accelerating investment in vertically controlled botanical sourcing from seed to extraction.
- Artisan bakery segment expansion:Micro-bakeries and custom cake studios in Germany are absorbing premium-priced gel paint formats at volumes that offset declining industrial procurement.
- Airbrush application technology:Precision viscosity formulations between 500 and 1500 centipoise are displacing hand-brush methods in commercial confectionery operations seeking throughput gains.
Market Restraints
- Carmine and cochineal supply concentration:Peru and Canary Islands control over 90 percent of global insect-derived red pigment harvests, exposing formulators to climate-driven harvest volatility.
- Titanium dioxide substitution costs:EFSA's 2022 re-evaluation and subsequent withdrawal of E171 authorization forces costly reformulation using calcium carbonate or starch-based opacifiers with inferior coverage performance.
- Ethanol carrier price sensitivity:Biofuel policy competition for fermentation-derived alcohol is compressing margins on spray-format edible paints in North American markets.
Strategic Opportunities
- India FSSAI natural colorant approvals:Regulatory streamlining for plant-based pigments creates entry pathways for suppliers targeting domestic confectionery manufacturers and export-oriented processing hubs.
- Powder paint ambient stability:Reduced-moisture formats enable 18-month shelf life extension, opening mass-market retail distribution through grocery and club channels previously inaccessible to liquid formats.
- Carbon accounting integration:Blockchain-tracked supply chain documentation aligns with EU Green Deal Scope 3 reporting requirements, differentiating premium portfolios for ESG-mandated procurement.
Industry Challenges
- FDA batch certification timelines:21 CFR 74 synthetic dye lot approvals average 45-90 days, constraining just-in-time production scheduling for seasonal demand spikes.
- Cross-regulatory portfolio complexity:Maintaining separate FDA-certified and EFSA-compliant SKUs doubles inventory carrying costs and complicates demand forecasting for multi-market distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Food Paints Market |
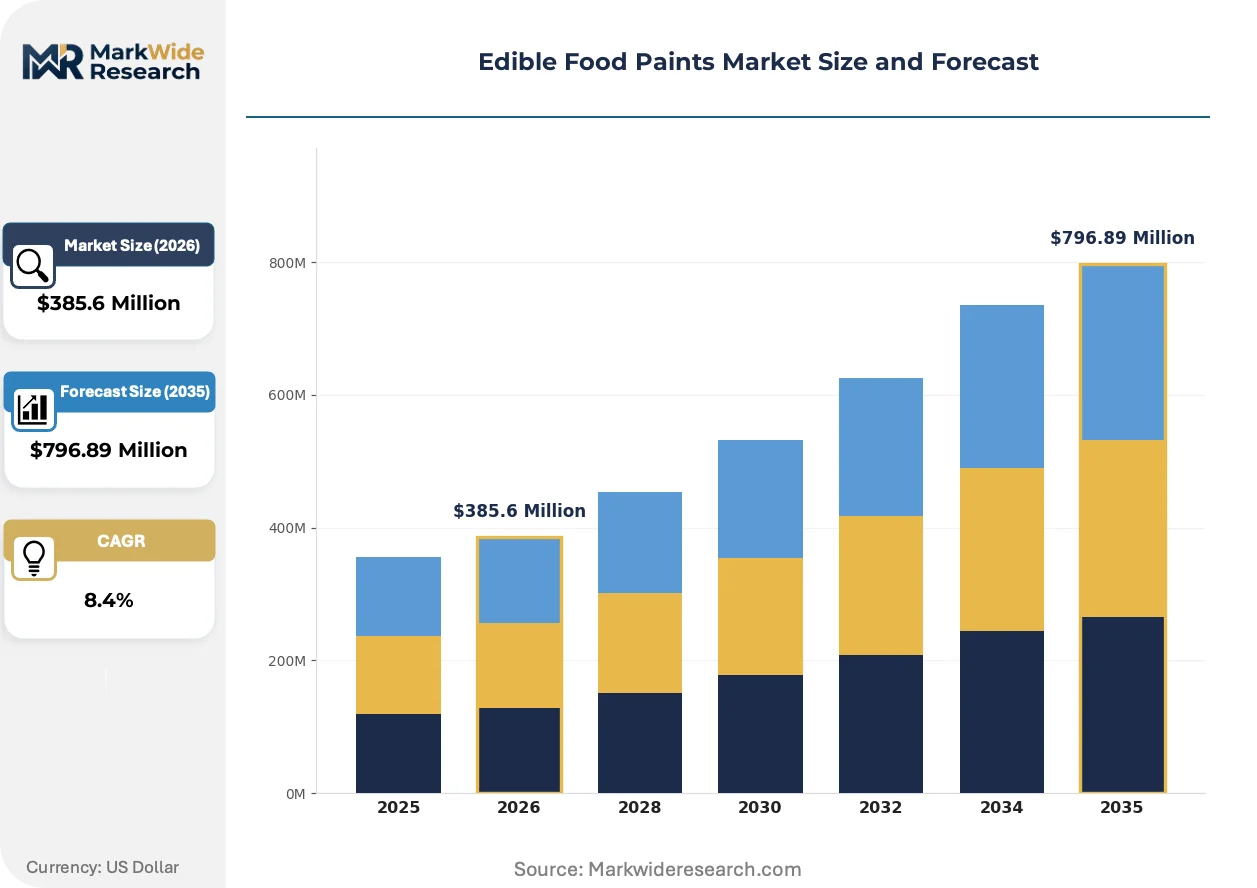
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Paints, Gel Paints, Powder Paints, Spray Paints Application: Baking, Decorating, Crafting, Confectionery End User: Home Bakers, Professional Pastry Chefs, Culinary Schools, Food Manufacturers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesalers |
| Companies Covered | Wilton Brands LLC, Chefmaster, AmeriColor Corp., Sensient Technologies Corporation, Dohler GmbH, Koninklijke DSM N.V., Cargill, Incorporated, Tate & Lyle PLC, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Food Paints Market Shifts & Advancements
Formulation science and application hardware are converging to compress the skill barrier between amateur and professional decorative outcomes.
Microencapsulated natural pigments are consolidating performance parity with synthetic alternatives. Anthocyanin and curcumin carriers now achieve light stability exceeding 12 months under LED display conditions. Artisan producers in Bavaria and Baden-Württemberg are adopting these formats for wedding cake commissions requiring outdoor display tolerance. The technology is consolidating premium pricing power around patent-protected encapsulation chemistries.
EFSA's 2023 updated guidance on enzymatic processing of plant extracts is tightening specification windows for chlorophyll and carotenoid concentrates. Manufacturers must now document residual protein content below 0.5 percent to maintain food-grade classification. German exporters to EU member states are reformulating extraction protocols to meet these thresholds, while US suppliers serving EU markets face dual validation requirements.
Direct-to-baker digital platforms are shortening replenishment cycles from monthly to weekly for high-velocity SKUs. Specialty distributors in Stuttgart and Munich now offer 48-hour delivery guarantees on custom-matched color lots. Professional pastry chefs are abandoning quarterly bulk procurement in favor of smaller, color-trend-responsive orders. This pattern is most visible in German urban centers where Instagram-driven cake aesthetics compress design-to-execution timelines.
Edible Food Paints Market Segmentation
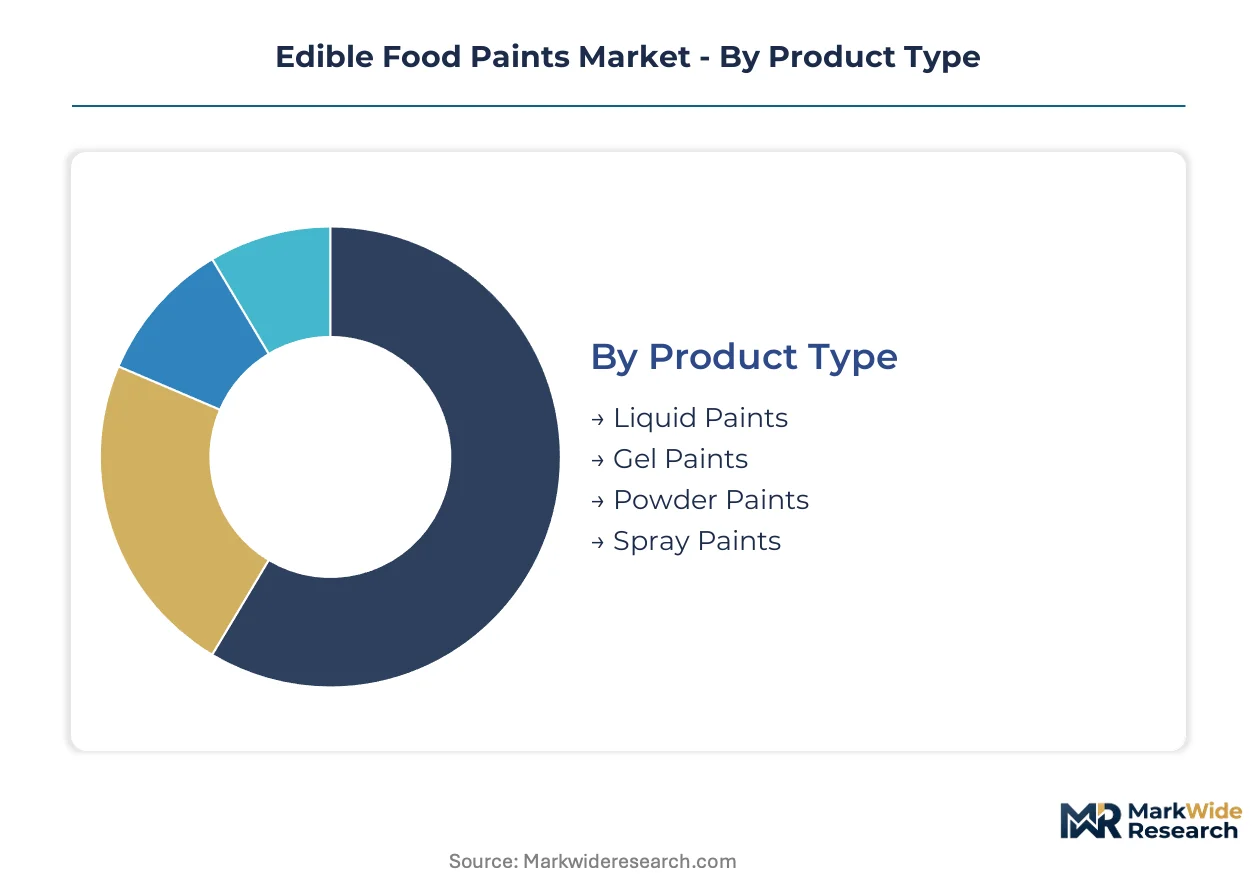
Edible food paints segment along formulation physics, application technique, and procurement behavior. Each dimension carries distinct margin profiles and regulatory exposure that reshape supplier portfolio priorities.
Product Type:
Supply concentration in carrier chemistry and moisture content splits manufacturing infrastructure between liquid-dominant facilities and emerging powder-capable lines.
- Liquid Paints:Water or glycerin suspensions with viscosity tunable between 500 and 5000 centipoise for brush or airbrush deployment. Home bakers in Germany absorb volume through specialty retail, though ethanol carrier cost volatility compresses North American margins.
- Gel Paints:Concentrated pigment pastes with thixotropic flow control for precise saturation layering on fondant surfaces. Professional pastry chefs in Bavaria and Baden-Württemberg drive premium absorption for wedding cake commissions requiring outdoor display tolerance.
- Powder Paints:Reduced-moisture formats enabling 18-month ambient shelf life extension. Food manufacturers seeking mass retail distribution favor these for grocery and club channel penetration.
- Spray Paints:Aerosolized or pump-dispensed formulations with ethanol carriers for uniform surface coverage. Biofuel policy competition for fermentation-derived alcohol constrains margin sustainability in US markets.
Today's leader: Liquid Paints. Tomorrow's challenger: Powder Paints.
Application:
End-use technique determines viscosity specification windows and colorant load requirements across professional versus amateur execution contexts.
- Baking:Heat-stable formulations resisting thermal degradation up to 200°C for direct incorporation into batters and doughs. Artisan micro-bakeries in Stuttgart source custom-matched lots with 48-hour replenishment cycles.
- Decorating:Surface application on cooled substrates including fondant, royal icing, and modeling chocolate. Instagram-driven aesthetics in German urban centers compress design-to-execution timelines.
- Crafting:Non-food-contact decorative use on display pieces and competition entries. Culinary schools generate training-volume demand for student practice kits.
- Confectionery:Precision color matching for molded chocolates and panned coatings. EFSA titanium dioxide withdrawal forces calcium carbonate opacifier substitution with inferior coverage performance.
Decorating commands current volume. Confectionery faces steepest reformulation headwinds.
End User:
Skill-based segmentation fragments procurement scale from individual hobbyist purchases to consolidated industrial tenders with divergent price elasticity.
- Home Bakers:Individual consumers purchasing through specialty stores and online platforms for occasional celebration baking. Wilton Brands LLC sustains visibility through dedicated retail channel presence.
- Professional Pastry Chefs:Commercial operators requiring batch consistency and custom color matching for commissioned work. Direct-to-baker digital platforms now enable weekly rather than monthly replenishment cycles.
- Culinary Schools:Institutional training programs consuming standardized kits for curriculum delivery. Volume procurement concentrates in urban centers with established hospitality education infrastructure.
- Food Manufacturers:Industrial scale users with consolidated procurement and ESG-mandated carbon accounting requirements. Blockchain-tracked supply chain documentation differentiates premium portfolio positioning.
Professional Pastry Chefs anchor premium pricing. Food Manufacturers consolidate procurement leverage.
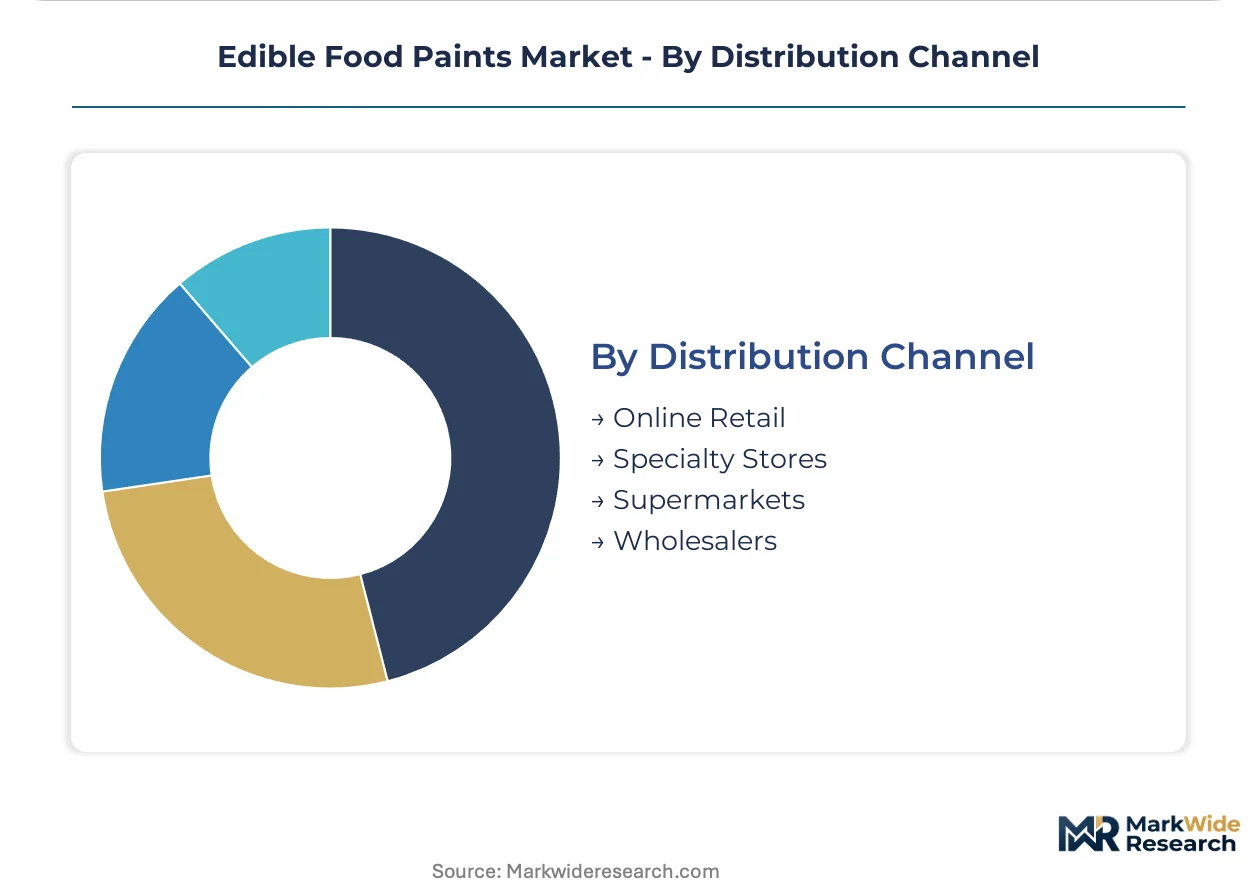
Distribution Channel:
Channel selection determines shelf life requirements, packaging format, and margin capture through intermediation layers.
- Online Retail:Direct-to-consumer and direct-to-baker platforms with trend-responsive inventory and 48-hour delivery guarantees. Specialty distributors in Munich leverage this channel for custom-matched color lots.
- Specialty Stores:Dedicated baking supply retailers with trained staff and color matching services. Wilton Brands LLC maintains dominant presence through this channel for home baker access.
- Supermarkets:Mass retail placement requiring powder format stability for extended ambient storage. Reduced-moisture formulations unlock grocery and club channel penetration previously inaccessible to liquid formats.
- Wholesalers:Industrial and institutional volume distribution with consolidated logistics. Food manufacturers and culinary schools procure through this channel for cost efficiency at scale.
Specialty Stores defend margin. Online Retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium positioning through craft baking culture and strict food-grade certification standards, while the United States absorbs volume through home baker retail channels despite ethanol carrier cost pressures.
Germany
Artisan micro-bakeries in Bavaria and Baden-Württemberg drive gel paint absorption for wedding cake commissions requiring outdoor display tolerance. EFSA purity thresholds for carmine alternatives force reformulation investments. Stuttgart and Munich specialty distributors now offer 48-hour delivery guarantees on custom-matched color lots.
United States
Home bakers sustain liquid paint volumes through specialty store networks, though biofuel policy competition for fermentation-derived alcohol compresses spray-format margins. FDA batch certification timelines under 21 CFR 74 constrain just-in-time production scheduling for seasonal demand spikes. Wilton Brands LLC leverages its dedicated retail channel presence to maintain visibility among occasional celebration bakers.
France
Confectionery manufacturers face steep reformulation headwinds from EFSA's titanium dioxide withdrawal, forcing calcium carbonate opacifier substitution with inferior coverage performance. ANSM enforces residual protein content thresholds below 0.5 percent for chlorophyll and carotenoid concentrates. Paris and Lyon anchor professional pastry chef demand for precision color matching in molded chocolate applications.
India
FSSAI regulatory streamlining for plant-based pigments creates entry pathways for suppliers targeting domestic confectionery manufacturers and export-oriented processing hubs. Powder paint formats unlock mass retail distribution through grocery channels previously inaccessible to liquid formulations. Maharashtra and Gujarat house emerging food processing clusters adopting reduced-moisture formulations for extended ambient storage.
United Kingdom
Instagram-driven cake aesthetics in London and Manchester compress design-to-execution timelines, accelerating weekly replenishment cycles among professional pastry chefs. Post-Brexit divergence from EU color additive approvals forces parallel inventory management for suppliers serving both markets. Direct-to-baker digital platforms gain share fastest in urban centers with established hospitality education infrastructure.
Edible Food Paints Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation physics and distribution channel access. The vendor base separates into three strategic archetypes: specialty baking supply brands with dedicated retail networks, natural colorant technology developers with R&D pipelines, and industrial ingredient conglomerates with consolidated procurement relationships. Dominant competitive moves include portfolio diversification into powder formats and geographic expansion through direct-to-baker digital platforms.
Within the specialty supply tier, Wilton Brands LLC and AmeriColor Corp. exemplify divergent channel strategies—Wilton sustaining home baker visibility through physical retail presence, AmeriColor anchoring professional loyalty through gel paint specialization. Sensient Technologies Corporation occupies a position at the technology-driven end, representing natural colorant R&D investment patterns visible across the sector.
| Leading Market Players |
|---|
| Wilton Brands LLC |
| Chefmaster |
| AmeriColor Corp. |
| Sensient Technologies Corporation |
| Dohler GmbH |
| Koninklijke DSM N.V. |
| Cargill, Incorporated |
| Tate & Lyle PLC |
| Ingredion Incorporated |
| Others |
Supply & Pricing Matrix
Fermentation-derived ethanol price indices cascade through edible food paint supply chains, compressing spray-format margins in North American markets while gel paint premiums hold firm in German artisan channels. This divergence between carrier chemistry cost pressures and professional-grade pricing power stratifies the market across moisture-content tiers and certification levels.
Pricing Analysis
Capacity additions in India are reshaping price floors for powder paint formats targeting mass retail distribution. Three-tier pricing structure across premium gel, standard liquid, and economy powder levels separates professional pastry chef demand from home baker volume. Certification tier differentiation—FDA batch-certified versus EFSA-compliant SKUs—drives margin premiums for dual-market suppliers. Cost compression in ethanol-dependent spray formats is intensifying because biofuel policy competition tightens fermentation alcohol supply. Food manufacturers exhibit highest price sensitivity through consolidated procurement tenders, while German artisan bakeries absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Return flows for expired liquid inventory and reformulated titanium dioxide stock create reverse-logistics complexity for EU-exporting suppliers. Peru, the Canary Islands, and India anchor global supply for carmine, botanical pigments, and FSSAI-approved plant extracts respectively. Formulation draws from insect-derived reds, curcumin carriers, and microencapsulated anthocyanins as primary inputs. Single-source vulnerability in cochineal harvests exposes formulators to climate-driven volatility. Distribution runs through specialty retail networks for home bakers and direct-to-baker digital platforms for professional segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between FDA and EFSA purity thresholds creates geographic-arbitrage value for suppliers configuring parallel product lines, with EFSA-compliant certification investments in Germany yielding premium positioning against US ethanol-cost-compressed margins.
For Market Incumbents: Acquire microencapsulation technology patents to defend against natural pigment stability substitutes threatening synthetic dye portfolios. Consolidate backward integration into Peruvian carmine harvesting cooperatives to mitigate climate-driven supply volatility. Expand powder-capable manufacturing lines in Maharashtra to capture FSSAI-streamlined export growth. For New Entrants and Emerging Players: Capture direct-to-baker digital platform share in Stuttgart and Munich where 48-hour delivery guarantees disrupt quarterly bulk procurement patterns. Target India's powder paint segment for mass retail grocery penetration. Lead with blockchain-tracked carbon accounting documentation to differentiate for ESG-mandated food manufacturer procurement. For Investors and Strategic Acquirers: Asymmetric upside sits with natural colorant R&D specialists holding encapsulation chemistry patent portfolios. Five-to-ten-year viability hinges on regulatory transition completion in Europe and North America. Monitor EFSA batch certification timeline compression and FDA-EFSA substance list convergence as inflection indicators for portfolio consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Sourcing | EU Green Deal Scope 3 reporting requirements favor vertically controlled seed-to-extraction supply chains. |
| Powder Format Manufacturing Scale-Up | Eighteen-month ambient shelf life unlocks grocery and club channel penetration previously inaccessible to liquid formats. |
| Direct-to-Baker Digital Platform Launch | Weekly replenishment cycles in German urban centers compress design-to-execution timelines for Instagram-driven aesthetics. |
| Dual Certification Portfolio Investment | Parallel FDA and EFSA compliance captures premium positioning in fragmented regulatory environments. |
| Carbon Accounting Integration Partnership | Blockchain-tracked documentation differentiates supply chains for ESG-mandated food manufacturer procurement. |
Research Methodology
Direct dialogue with formulation chemists, specialty distributor procurement leads, artisan bakery owners, and regulatory affairs directors at colorant suppliers grounded qualitative insights. Secondary validation drew from FDA 21 CFR filings, EFSA re-evaluation reports, FSSAI approval databases, and EU Green Deal implementation guidance. Bottom-up demand modeling across product type, application technique, and end-user skill segments triangulated against top-down market sizing from trade flow analysis.
Segment-level value and volume trajectories across the analysis window reflect elasticity-adjusted adoption curves for powder, liquid, gel, and spray formats. Modeled dimensions span formulation physics, carrier chemistry, viscosity specification, and regional regulatory cluster. CAGRs derive from regression against historical volume patterns and projected regulatory transition impacts. Forecast inputs include ethanol price index volatility and EFSA certification timeline compression.
EFSA substance list amendments, FDA batch certification delays, and climate-driven carmine harvest volatility are the dominant revision risks to projection assumptions. Practitioners should monitor regulatory divergence indicators, fermentation alcohol supply competition, and Peruvian agricultural output reports for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Coloring Foodstuffs Market
Flavorings and Food Additives
Global Flavors Market
Flavorings and Food Additives
France Food Colorants Market
Flavorings and Food Additives
Middle East and Africa Flavors and Fragrances Market
Flavorings and Food Additives
Flavoring Agents Market
Flavorings and Food Additives
Basil Oil Market
Flavorings and Food Additives
Oleoresin Market
Flavorings and Food Additives
Poria Cocos Extract Market
Flavorings and Food Additives
Botanical Flavors Market
Flavorings and Food Additives
Blueberry Extract Market
Flavorings and Food Additives
Beverage Flavoring Market
Flavorings and Food Additives
Fractionated Lecithin Market
Flavorings and Food Additives
Vanilla Oleoresin Market
Flavorings and Food Additives
Global Floral Flavors Market
Flavorings and Food Additives
United States Food Flavor and Enhancer Market
Flavorings and Food Additives
Food Grade Menthol Crystal Market